
 Boom Cranes Market | 2026-2036
Boom Cranes Market Size, Share, and Industry Trends Forecast 2026-2036
Boom Cranes Market Analytics
The capital-intensity divergence between integrated manufacturers and assembly-focused competitors is reorganizing competitive tiers in boom cranes. Manitowoc Company leverages its foundry-to-assembly vertical control across lattice boom crawler lines. Tadano Ltd. anchors its position through hydraulic precision engineering developed for all-terrain deployment. Palfinger AG differentiates via knuckle-boom specialization that dominates European utility and tree-care channels.
Boom cranes are load-lifting machines employing articulated or telescopic booms with hydraulic cylinder extension, typically achieving lift capacities from one ton to over one thousand tons depending on configuration and counterweight. These systems serve primary industrial purposes in vertical material placement, heavy component erection, and precision positioning across infrastructure, energy, and extractive operations. Hydraulic product types command the largest installed base due to power density and field-proven reliability, though electric drivetrains attract fastest-growing interest where emissions restrictions tighten. Telescopic configurations concentrate margin pools in rental fleet specifications, while heavy-duty feature variants sustain premium pricing in mining and offshore oil & gas end-user segments.
OSHA crane operator certification requirements and the EU Machinery Directive with CE marking obligations shape product design, training ecosystems, and market access documentation across manufacturing and deployment jurisdictions. The EU F-Gas Regulation and emerging EPA standards for non-road mobile machinery emissions are forcing hydraulic system redesigns and electrification roadmaps. Stakeholders must monitor regulatory calibration between diesel displacement timelines and the charging infrastructure readiness of construction job sites.
Market Dynamics
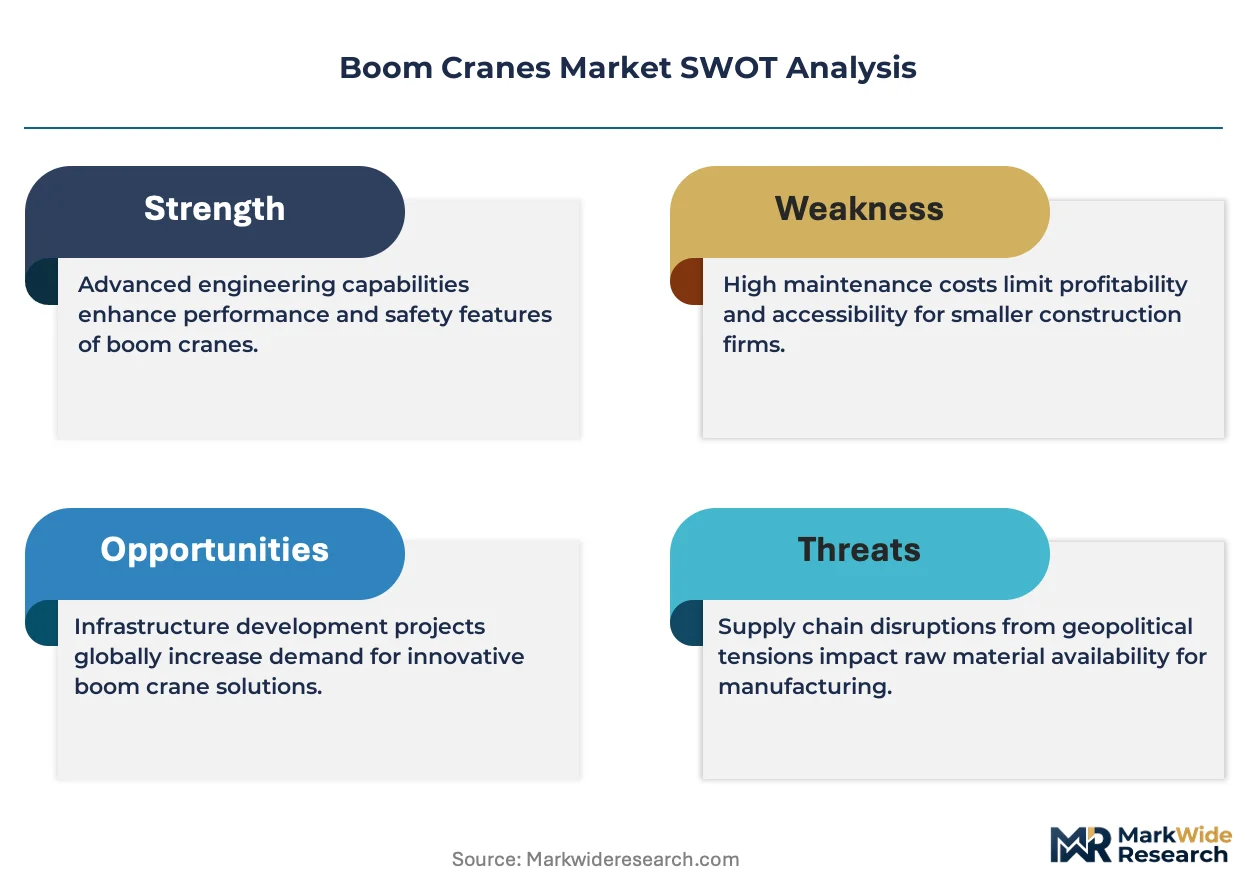
The EU F-Gas Regulation and parallel EPA non-road emissions standards are forcing hydraulic system redesigns while electrification roadmaps collide with construction site charging infrastructure gaps, creating a product development tension between compliance deadlines and field readiness.
Growth Catalysts
- Offshore wind farm construction:Germany's North Sea port clusters anchor turbine installation demand, requiring heavy-lift lattice boom configurations with precision positioning capabilities for monopile and jacket foundation placement.
- EU Machinery Directive CE marking:Harmonized safety standards accelerate cross-border equipment circulation, reducing certification duplication costs for manufacturers serving multiple European construction markets.
- Telescopic boom electrification:Battery-hybrid drivetrains penetrate urban rental fleets where municipal emissions zones restrict diesel operation during daylight hours.
Market Restraints
- High-strength steel plate concentration:Japanese and South Korean mill supply dominates ultra-heavy plate grades for lattice boom chord fabrication, exposing manufacturers to ocean freight volatility and alloy surcharge pass-through.
- Hydraulic component lead times:Precision cylinder and valve sourcing from specialized German and Italian suppliers extends delivery schedules 14-20 weeks beyond historical norms.
- OSHA crane operator certification scarcity:Licensed operator pipeline constraints in US infrastructure corridors limit fleet utilization rates regardless of equipment availability.
Strategic Opportunities
- India port modernization:Jawaharlal Nehru Port Trust and Mundra Port expansion programs specify all-terrain boom cranes for container handling and ship-to-shore logistics integration.
- EU Green Deal construction incentives:National recovery funds prioritize zero-emission machinery procurement, creating first-mover advantage for manufacturers with certified electric product lines.
- Telematics-ERP convergence:Real-time load monitoring and predictive maintenance data streams integrate with contractor enterprise systems, enabling usage-based rental pricing models.
Industry Challenges
- Mechatronics technician shortage:Hydraulic-electric hybrid systems require cross-trained service personnel scarce in established crane maintenance networks.
- CE-MDR transition documentation:Updated EU conformity assessment procedures demand revised technical files and notified body engagement, compressing product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boom Cranes Market |
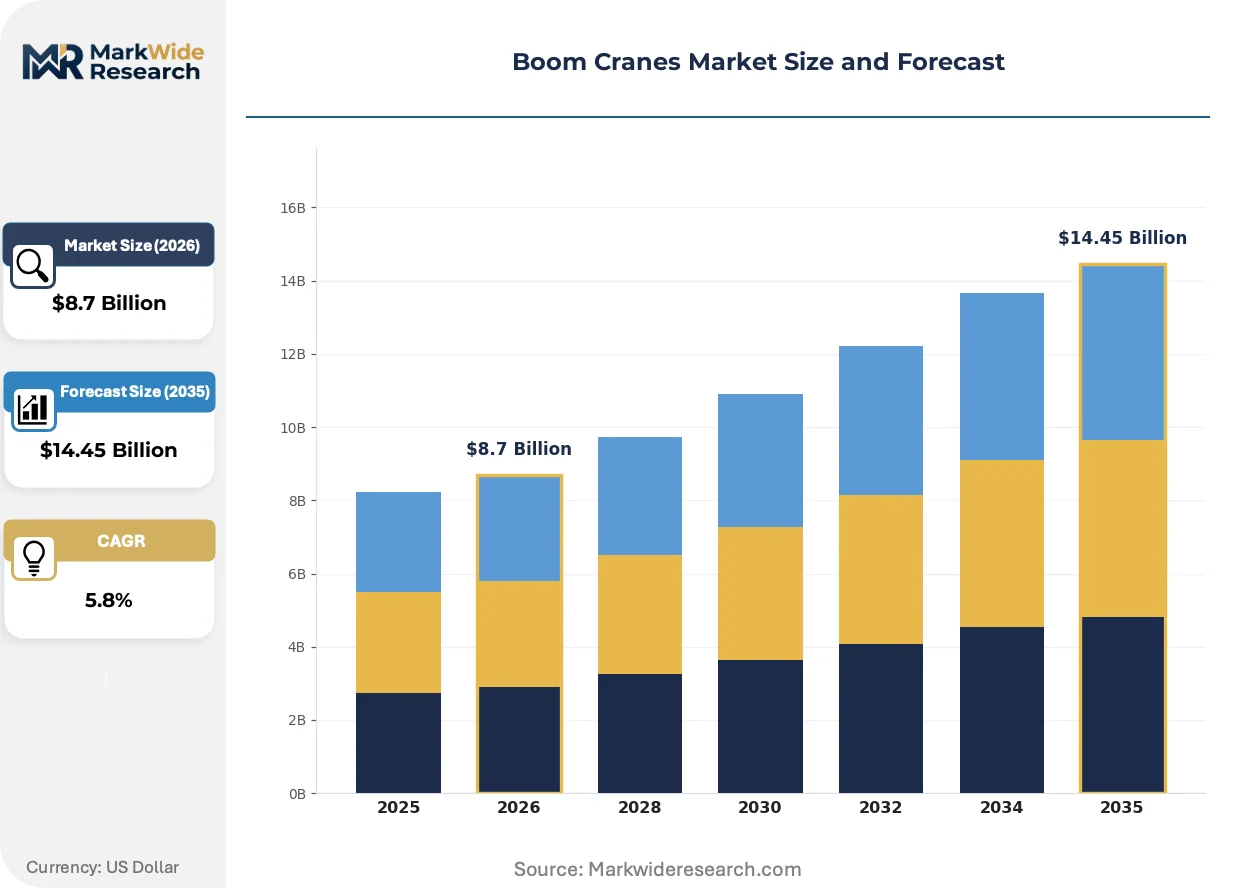
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Electric, Manual, Telescopic End User: Construction, Mining, Oil & Gas, Maritime Feature: Portable, Heavy Duty, Compact, Multi-Function Distribution Channel: Direct Sales, Distributors, Online Retail, Rentals |
| Companies Covered | Manitowoc Company, Tadano Ltd., Terex Corporation, Altec Industries, Elliott Equipment Company, Manitex International, Fassi Gru, Palfinger AG, Load King, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boom Cranes Market Evolving Landscape
Electrification architectures and digital load management systems are redefining boom crane performance specifications while regulatory emissions windows narrow, forcing simultaneous hardware and software innovation cycles.
Variable frequency drive electric winch systems are displacing traditional hydraulic hoist packages in 50-200 ton capacity classes. Urban rental fleet operators in German and Dutch metropolitan zones specify these configurations to comply with municipal diesel restrictions. The technology compresses maintenance intervals and fluid handling costs while expanding indoor and tunnel construction applicability.
EPA Tier 4 Final and emerging Stage V compliance pathways mandate selective catalytic reduction and diesel particulate filter integration for remaining hydraulic drivetrain products. Engine OEMs have consolidated exhaust after-treatment architectures, forcing crane manufacturers to redesign engine compartments and cooling packages. Mining and offshore oil & gas segments absorb premium pricing for compliant configurations given project scale and regulatory enforcement exposure.
Usage-based rental contracts with embedded telematics monitoring displace fixed-term dry hire arrangements in European equipment rental markets. Major contractors in France and the United Kingdom now specify guaranteed availability clauses with penalty structures, transferring operational risk to fleet owners. This compression demands predictive maintenance investment and remote diagnostics capability as competitive prerequisites rather than differentiators.
Boom Cranes Market Segmentation
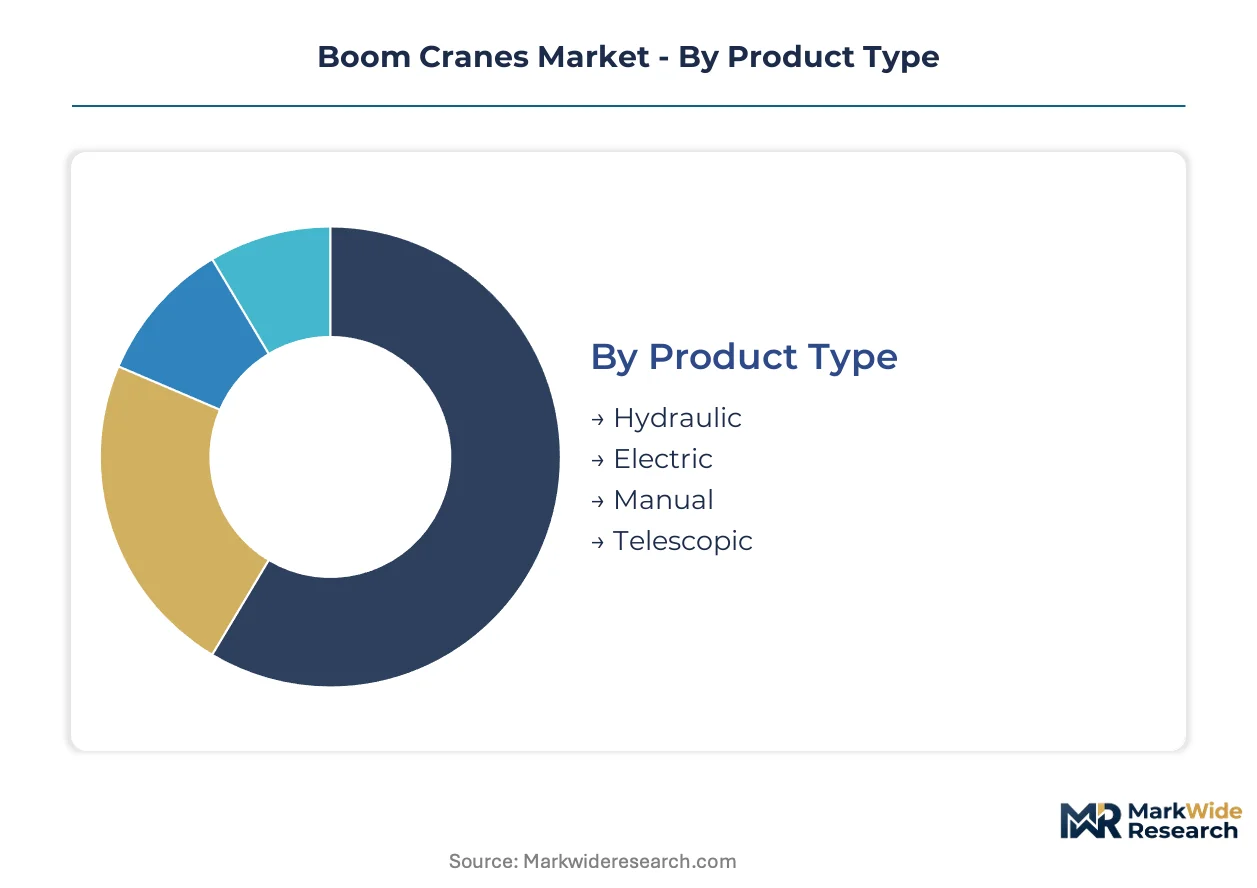
Boom crane segmentation reveals how hydraulic dominance, construction concentration, and rental channel expansion create distinct margin architectures across product configurations. Understanding these partitions exposes where electrification roadmaps and fleet modernization investments will reshape competitive positioning.
Product Type:
Hydraulic systems capture the deepest margin pools through aftermarket parts density and field-proven reliability premiums in heavy-lift applications.
- Hydraulic:Power-dense cylinder architectures achieve lift capacities exceeding one thousand tons with counterweight optimization. Demand concentrates in German North Sea port clusters for offshore wind monopile placement, where precision positioning under load justifies premium specifications despite EPA Tier 4 Final compliance costs.
- Electric:Battery-hybrid drivetrains with variable frequency drive winch systems eliminate hydraulic fluid handling in 50-200 ton classes. Municipal emissions zones in Dutch and German metropolitan areas now mandate these configurations for daylight urban operations, compressing maintenance intervals while expanding tunnel construction applicability.
- Manual:Hand-crank and mechanical leverage systems serve low-capacity maintenance and confined-space retrieval tasks where power infrastructure is absent.
- Telescopic:Multi-stage boom extension mechanisms dominate European rental fleet specifications, with OEMs optimizing transport dimensions and rapid deployment sequences for contractor productivity metrics.
The dominant share belongs to Hydraulic, while Electric is closing the gap fastest.
End User:
Application-driven cost structures separate project-scale procurement from fleet-based rental economics across vertical markets.
- Construction:Infrastructure contractors specify all-terrain and crawler configurations for vertical material placement and heavy component erection. India's Jawaharlal Nehru Port Trust and Mundra Port expansion programs anchor demand for ship-to-shore logistics integration.
- Mining:Ultra-heavy lattice boom systems with specialized counterweight carriage serve extractive operations requiring continuous duty cycles in abrasive environments. Japanese and South Korean mill supply concentration for ultra-heavy plate grades exposes procurement to ocean freight volatility.
- Oil & Gas:Offshore platform maintenance and subsea equipment deployment demand explosion-proof specifications and marine-grade corrosion resistance.
- Maritime:Port cargo handling and vessel-mounted lifting operations prioritize compact stowage dimensions and rapid cycle times for throughput optimization.
Construction commands the largest installed base, though Mining sustains the highest average transaction values.
Feature:
Physical configuration determines transport logistics, site access constraints, and operator certification requirements across deployment scenarios.
- Heavy Duty:Reinforced chord fabrication and enhanced counterweight systems support mining and offshore oil & gas segments absorbing premium pricing for regulatory compliance exposure. EPA and EU F-Gas Regulation mandates force engine compartment redesigns and cooling package integration.
- Portable:Modular assembly and reduced ground bearing pressure enable rapid relocation across dispersed construction sites without specialized transport permits.
- Compact:Confined-space maneuverability serves urban utility corridors and indoor industrial maintenance where dimensional constraints dominate specification decisions.
- Multi-Function:Attachment interchangeability and auxiliary power take-offs extend utilization rates across diverse task sequences for fleet owners.
Heavy Duty configurations generate the steepest margin premiums, while Portable designs are gaining share fastest in infrastructure corridors.
Distribution Channel:
Channel economics diverge between capital ownership models and operational risk transfer through availability-based contracting.
- Rentals:Usage-based contracts with embedded telematics monitoring displace fixed-term dry hire arrangements in French and UK markets. Guaranteed availability clauses with penalty structures transfer operational risk to fleet owners, demanding predictive maintenance investment as competitive prerequisites.
- Direct Sales:OEM relationship programs serve mining and offshore oil & gas operators with project-scale procurement and dedicated technical support.
- Distributors:Regional inventory positioning and localized service networks support construction contractor fleet replenishment across fragmented geographic markets.
- Online Retail:Digital quotation platforms and specification comparison tools penetrate small-capacity accessory and replacement component procurement.
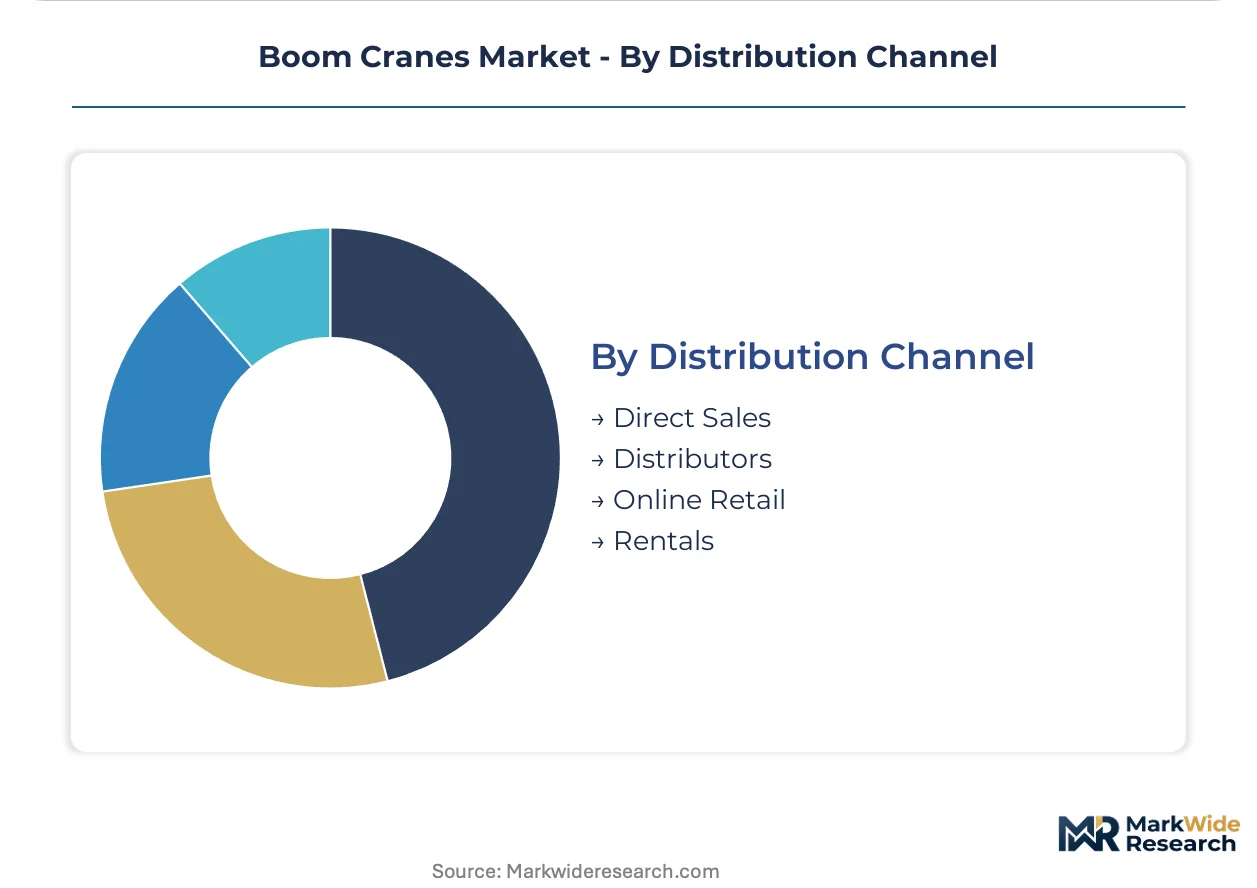
Rentals control the dominant transaction volume, with Direct Sales expanding most quickly in energy project development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German port clusters command premium pricing for heavy-lift lattice configurations, while Indian infrastructure corridors absorb cost-optimized all-terrain specifications. This asymmetry reflects divergent regulatory enforcement depth and project-scale economics across deployment zones.
Germany
North Sea offshore wind monopile installation drives demand for thousand-ton-capacity lattice boom systems with precision positioning. The EU F-Gas Regulation forces hydraulic system redesigns and electrification roadmaps for port-based fleet operators. Bremerhaven and Cuxhaven anchor turbine component staging and installation vessel provisioning.
United States
Infrastructure corridors from Texas to California absorb telescopic boom cranes for bridge construction and utility expansion. OSHA crane operator certification requirements constrain fleet utilization regardless of equipment availability. Houston-Galveston petrochemical complexes sustain demand for explosion-proof configurations in refinery maintenance cycles.
India
Jawaharlal Nehru Port Trust and Mundra Port expansion programs specify all-terrain cranes for container handling and ship-to-shore logistics. The PLI scheme for construction equipment manufacturing incentivizes domestic assembly partnerships. Gujarat port clusters concentrate procurement authority for maritime infrastructure modernization.
Japan
Ultra-heavy plate grade dependence from domestic mills supports lattice boom fabrication for mining and offshore applications. METI industrial standards govern precision engineering specifications for all-terrain deployment. Nagoya industrial corridor maintains foundry-to-assembly integration for export-oriented crawler crane production.
Netherlands
Rotterdam port logistics and urban construction zones mandate battery-hybrid drivetrains under municipal emissions restrictions. CE marking obligations under the EU Machinery Directive accelerate cross-border equipment circulation. Randstad metropolitan rental fleets specify rapid-deployment telescopic configurations for contractor productivity metrics.
Boom Cranes Market Competitive Landscape
Concentration sits with integrated manufacturers controlling foundry-to-assembly vertical chains alongside assembly-focused competitors sourcing specialized components. The vendor base stratifies across three tiers: premium specialists commanding reliability premiums, mid-scale regional fabricators optimizing transport economics, and emerging entrants targeting electrification niches. Dominant competitive moves include strategic partnerships for battery-drivetrain sourcing and geographic expansion into Indian port modernization corridors.
Among established manufacturers, Manitowoc Company exemplifies integrated production architecture spanning lattice boom crawler lines. Tadano Ltd. occupies a position within precision-engineered all-terrain deployment specialists. Palfinger AG represents knuckle-boom configuration leadership serving European utility and tree-care channels.
| Leading Market Players |
|---|
| Manitowoc Company |
| Tadano Ltd. |
| Terex Corporation |
| Altec Industries |
| Elliott Equipment Company |
| Manitex International |
| Fassi Gru |
| Palfinger AG |
| Load King |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation agreements with Japanese and South Korean ultra-heavy plate mills lock in both lattice boom chord fabrication access and alloy surcharge visibility for integrated manufacturers serving German North Sea wind installation fleets.
Pricing Analysis
Configured-to-order pricing for thousand-ton lattice boom crawler systems commands spreads exceeding standard telescopic rental fleet specifications by margins reflecting EPA Tier 4 Final after-treatment integration and precision positioning engineering. Three-tier pricing structure across premium, standard, and economy levels separates mining-grade heavy-duty configurations with explosion-proof specifications from urban battery-hybrid units and baseline hydraulic models. Cost compression in mid-capacity all-terrain segments is intensifying because Indian port modernization programs prioritize procurement scale over feature density. Mining and offshore oil & gas operators exhibit lowest price sensitivity given project-scale economics and regulatory enforcement exposure, while European rental fleet managers negotiate hardest on availability-guarantee terms.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose ultra-heavy plate shipments from Japanese mills to Bremerhaven turbine component staging yards, amplifying ocean freight volatility for lattice boom manufacturers. German hydraulic cylinder and Italian precision valve suppliers anchor component sourcing for European OEMs, while Chinese foundry capacity feeds cost-optimized all-terrain crane fabrication for Indian port expansion programs. Single-source vulnerability concentrates in South Korean mill supply for chord-grade steel grades above yield thresholds. Distribution runs through OEM-direct channels for mining project procurement and telematics-integrated rental platforms for European contractor markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Offshore wind farm construction enters an early-cycle expansion phase as monopile foundation deployment accelerates across German North Sea lease areas, creating durable demand visibility for heavy-lift lattice configurations.
For Market Incumbents: Secure captive supply relationships with Japanese ultra-heavy plate mills before alloy surcharge volatility compresses crawler crane margins. Deepen backward integration into foundry operations for counterweight casting to defend against emerging Chinese all-terrain entrants targeting Indian port procurement. Prioritize CE-MDR technical file preparation ahead of notified body queue congestion. For New Entrants and Emerging Players: Lead with battery-hybrid drivetrain configurations in Dutch and German municipal emissions zones where daylight diesel restrictions create specification gaps incumbent hydraulic portfolios cannot fill. Target Indian Jawaharlal Nehru Port Trust and Mundra Port expansion corridors through PLI scheme partnership structures. Deploy telematics-embedded rental contracts as the primary go-to-market mechanism to bypass capital ownership barriers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale European rental fleet operators with guaranteed availability contract infrastructure and predictive maintenance data streams already integrated. Long-term viability favors asset-light platform models over manufacturing-heavy positions given electrification capex requirements. Watch for OSHA crane operator certification pipeline expansion as the inflection signal for US infrastructure corridor utilization recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ultra-Heavy Plate Supply | Japanese mill capacity reservations secure lattice boom chord fabrication priority for German offshore wind demand. |
| Battery-Hybrid Drivetrain Certification | EU Green Deal procurement incentives reward first-movers with zero-emission machinery qualification for national recovery funds. |
| Telematics-ERP Platform Convergence | Real-time load monitoring enables usage-based rental pricing models displacing fixed-term dry hire in French markets. |
| Indian Port Expansion Partnership | PLI scheme domestic assembly incentives align OEM positioning with Jawaharlal Nehru Port Trust modernization timelines. |
| Predictive Maintenance Capability Buildout | Guaranteed availability penalty structures in UK rental contracts demand remote diagnostics as competitive prerequisite. |
Research Methodology
A spread of perspectives from crane fleet operations directors, OEM procurement managers, hydraulic component engineering leads, and port authority infrastructure planners converged on the working assumptions driving segmentation splits. Primary interview insights combined with secondary validation from EU Machinery Directive implementation guidance, EPA non-road emissions compliance databases, Indian PLI scheme construction equipment notifications, and customs trade data for ultra-heavy steel plate movements. Bottom-up unit economics for rental fleet utilization and top-down infrastructure investment pipelines were triangulated against manufacturer order backlogs.
Segmentation dimensions modeled span hydraulic, electric, and manual product types; construction, mining, oil & gas, and maritime end users; heavy duty, portable, compact, and multi-function feature configurations; and rentals, direct sales, distributors, and online retail channels. Geographic clusters incorporated German North Sea port zones, US infrastructure corridors, Indian maritime expansion programs, and Japanese export-oriented production bases. CAGRs were derived from equipment replacement cycles, regulatory compliance deadlines, and project-scale procurement pipelines across the analysis window. Forecast inputs included offshore wind installation vessel provisioning schedules and municipal emissions zone expansion trajectories.
Underlying assumptions cover EPA Tier 4 Final enforcement continuity and EU F-Gas Regulation implementation timelines, with deviation risk concentrated in construction site charging infrastructure deployment rates for battery-hybrid adoption. Forecasts reflect these assumptions without scenario weighting for technology substitution or trade policy disruption. Revision becomes warranted when OSHA crane operator certification throughput crosses thresholds sufficient to relieve US fleet utilization constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Commercial Laundry Machines Market
Construction Equipment
Construction Site Preparation Equipment Market
Construction Equipment
Log Splitters Rental Market
Construction Equipment
Latin America Heavy Construction Equipment Market
Construction Equipment
Escalator Cleaning Machine Market
Construction Equipment
Welding Equipment and Consumables Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
Trash Rack Cleaning Machine Market
Construction Equipment
Rotary Hammers Market
Construction Equipment
Dozer Blade Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
Global Portable Sawmills Market
Construction Equipment
United States Completion Equipment and Services Market
Construction Equipment
Rockbreakers Market
Construction Equipment
Japan Heavy Construction Equipment Rental Market
Construction Equipment
Utility Locator Market