
 Marine Manifolds and Risers Market | 2026-2036
Marine Manifolds and Risers Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Manifolds and Risers Market Outlook
Modular riser-manifold bundling is realigning procurement patterns among offshore operators. TechnipFMC dominates integrated subsea production system contracts through its control over umbilical-to-wellhead architecture. Volvo Penta leverages its marine propulsion heritage to anchor aftermarket manifold replacement demand across Nordic vessel fleets. Mercury Marine differentiates through high-performance aluminum casting expertise serving recreational and commercial boatbuilders.
Marine manifolds and risers constitute pressure-boundary components engineered to channel hydrocarbons or cooling media between subsea wells, surface platforms, and vessel engines, typically rated for operating pressures exceeding 10,000 psi in deepwater applications. Steel high-pressure manifolds lead capital expenditure in fixed platform installations, while titanium and composite riser segments gain share in ultra-deepwater floating platforms where weight reduction directly lowers topside structural load. Oil and gas companies concentrate procurement on integrated manifold-riser packages, whereas marine contractors unbundle installation-type contracts to optimize vessel-day economics across shallow and deepwater project tiers.
The American Petroleum Institute, ISO, and Brazil's national petroleum regulator shape material specifications and welding qualification protocols for subsea pressure-containing equipment. API 6A and ISO 13628-7 compliance gates market access for riser connectors and manifold valve assemblies in federally leased offshore blocks. Stakeholders must monitor evolving methane-emission detection mandates and their downstream effect on flange-sealing technology selection across both brownfield retrofit and greenfield development portfolios.
Market Dynamics
Deepwater pre-salt development off Brazil is compressing procurement cycles and forcing integrated manifold-riser package standardization across offshore operators, reshaping how engineering contractors bid for installation contracts.
Growth Catalysts
- API 6A and ISO 13628-7 harmonization:Unified welding qualification protocols are reducing certification duplication for subsea valve assemblies, accelerating vendor qualification timelines for Gulf of Mexico leaseholders.
- Titanium riser adoption:Weight reduction in ultra-deepwater floating platforms is lowering topside structural load requirements, cutting platform steel tonnage and installation vessel-day costs.
- Brazil pre-salt field maturation:Petrobras-led development of the Buzios and Mero complexes is sustaining procurement of high-pressure riser systems rated above 15,000 psi operating pressure.
Market Restraints
- Specialized alloy supply concentration:Premium-grade duplex stainless steel for manifold forging is concentrated among Scandinavian and Japanese metallurgical suppliers, creating single-source vulnerability for North Sea project timelines.
- Extended API 6A PSL 3G certification cycles:Enhanced material traceability requirements for sour service applications are stretching qualification periods to 18-24 months, gating market entry for new forging entrants.
- Composite riser thermal limitation:Polymer matrix composites face temperature ceilings near 120°C that exclude them from high-temperature high-pressure (HTHP) reservoirs in the Gulf of Mexico and West Africa.
Strategic Opportunities
- Angola ultra-deepwater:Block 15/06 and 17 development plans are creating demand for subsea production systems with integrated steel catenary riser configurations, opening new installation contract pools.
- EU Green Deal methane monitoring mandates:Leak detection requirements for subsea flange assemblies are creating aftermarket retrofit demand for sensor-integrated sealing systems across North Sea brownfield infrastructure.
- Digital twin convergence with predictive maintenance:Real-time riser fatigue monitoring combined with AI-driven anomaly detection is enabling condition-based replacement scheduling, shifting revenue from equipment sales to performance contracts.
Industry Challenges
- Subsea welding inspector scarcity:Qualified hyperbaric welding inspectors for deepwater riser installation are concentrated among Norwegian and Brazilian certification pools, constraining project ramp rates.
- Legacy platform integration complexity:Brownfield manifold replacement requires hydraulic interface matching with 1980s-vintage control systems, forcing custom engineering on each North Sea retrofit.
- Capex intensity of full-field development:Integrated subsea production systems require front-loaded investment in installation vessels and subsea trees before first oil, stretching operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Manifolds and Risers Market |
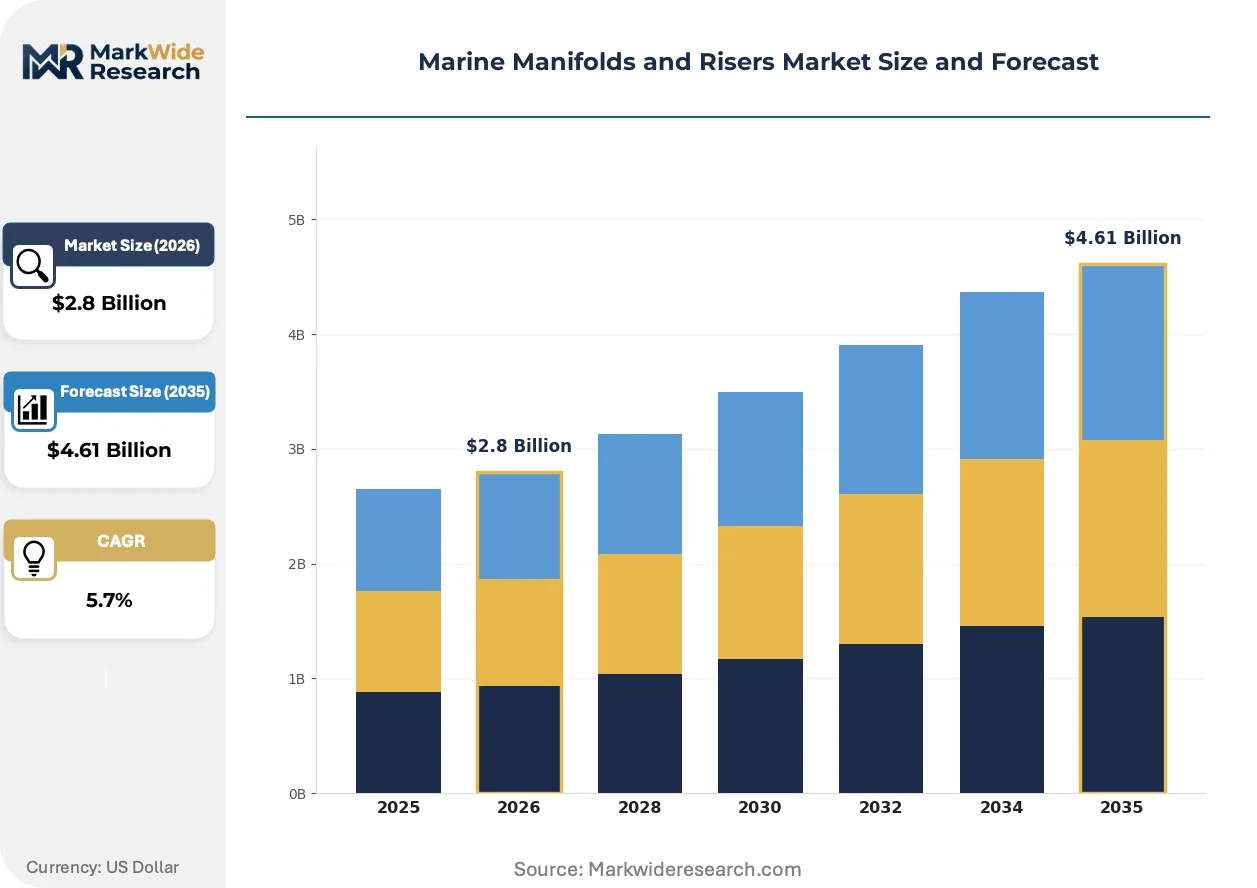
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Pressure Manifolds, Low-Pressure Manifolds, Risers, Other Components Material: Steel, Aluminum, Composite, Titanium End User: Oil & Gas Companies, Marine Contractors, Infrastructure Developers, Others Installation Type: Onshore Installations, Offshore Installations, Floating Platforms, Fixed Platforms |
| Companies Covered | Volvo Penta, Mercury Marine, BARR Marine, Mercruiser, Indmar, Blue Jacket Marine Products, EMP-Engineered Marine Products, Stainless Marine, TechnipFMC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Manifolds and Risers Market Strategic Shifts
Material science advances and regulatory tightening around methane containment are forcing concurrent evolution in riser architecture, flange sealing technology, and procurement contracting structures across deepwater provinces.
Composite-titanium hybrid riser joints are unifying the fatigue resistance of titanium stress joints with the weight advantages of carbon fiber-reinforced polymer in the upper riser sections. Petrobras and independent operators in Brazil are piloting these configurations in 2,000-meter water depths. This unifying architecture is compressing the traditional steel riser supply chain by displacing forged connector forgings with bonded titanium-composite transitions.
EPA methane emission detection rules for offshore facilities are mandating continuous monitoring at subsea wellhead and manifold flange interfaces. The regulation requires optical gas imaging or equivalent sensor deployment on all new deepwater installations in US federal waters. Subsea engineering contractors are responding by integrating fiber-optic leak detection into API 6A flange designs, with Gulf of Mexico operators leading adoption to preempt enforcement action.
Integrated service contracts are displacing equipment-only procurement for manifold-riser packages, with operators bundling installation, commissioning, and life-of-field maintenance into single-vendor agreements. This restructuring favors engineering firms with captive installation vessel fleets and is visible most acutely in Brazil, where Petrobras has consolidated subsea production system awards with contractors offering full-scope project delivery.
Marine Manifolds and Risers Market Segmentation
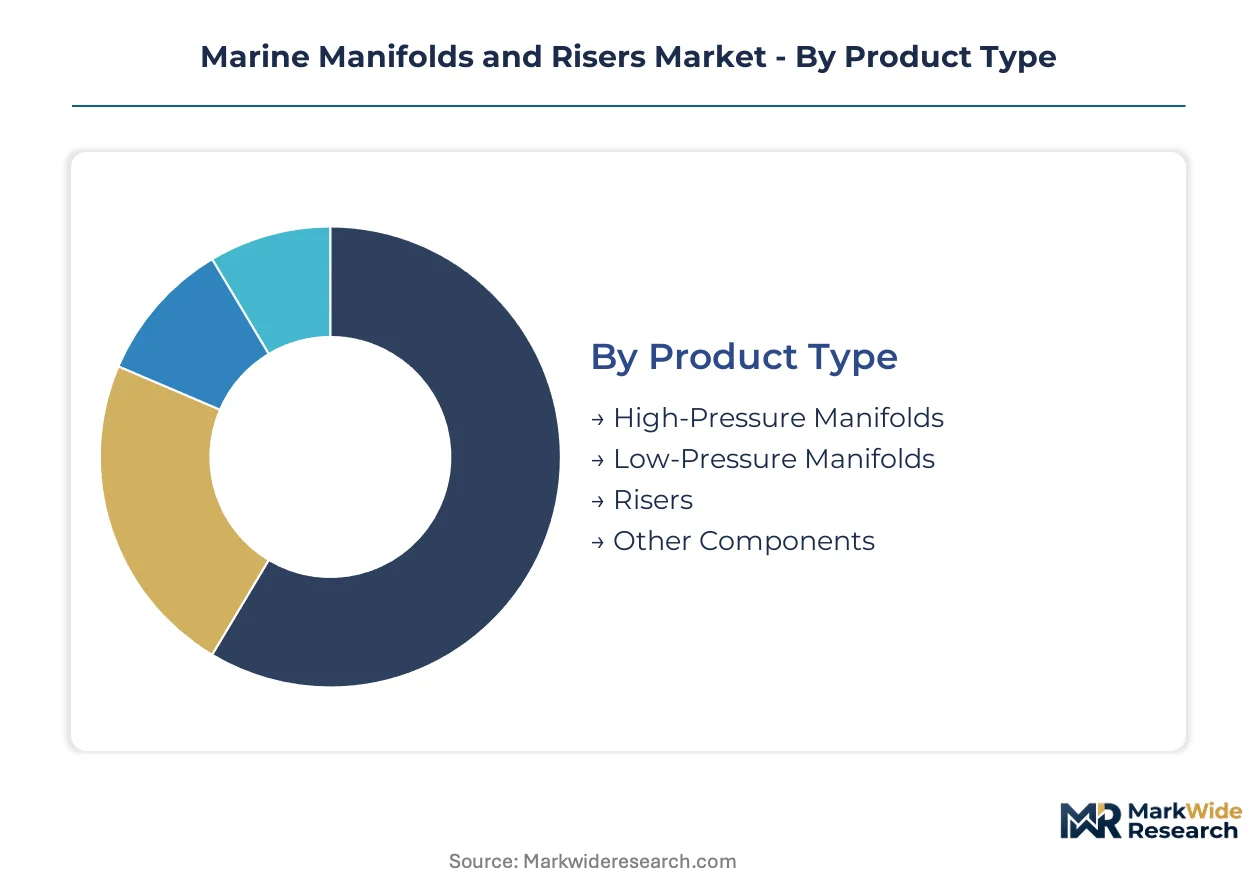
Marine manifolds and risers segment along pressure ratings, metallurgical grades, and installation architectures that dictate procurement bundling strategies. Each dimension carries distinct certification requirements and vessel-day economics that reshape how operators structure field development contracts.
Product Type:
Supply concentration in forged high-pressure connectors tilts procurement power toward integrated subsea production system vendors with captive metallurgical supply chains.
- High-Pressure Manifolds:Forged steel assemblies rated above 10,000 psi channel hydrocarbons from subsea wellheads to production risers. Demand concentrates in Brazil's pre-salt developments where Petrobras mandates 15,000 psi ratings for Buzios and Mero complex tiebacks.
- Risers:Steel catenary, titanium, and hybrid composite-titanium configurations bridge subsea infrastructure to surface platforms. Floating platform operators in ultra-deepwater Gulf of Mexico and West Africa specify titanium stress joints to cut topside structural tonnage.
- Low-Pressure Manifolds:Distribution headers rated below 5,000 psi handle processed fluids and cooling media on platform decks.
- Other Components:Flange assemblies, valve actuators, and control pod interfaces complete pressure-boundary systems.
High-pressure manifolds absorb the bulk of installed capacity; risers are expanding most quickly as floating platform deployment accelerates.
Material:
Cost tier differentiation separates premium alloy grades from standard carbon steel based on sour service resistance and weight-critical applications.
- Steel:API 6A PSL 2 and PSL 3G carbon and low-alloy grades dominate fixed platform manifold forging. North Sea brownfield replacement programs specify enhanced sour service grades to handle hydrogen sulfide exposure in mature reservoirs.
- Titanium:Grade 5 and Grade 23 titanium alloys deliver fatigue resistance at half the density of steel. Deepwater operators in Brazil and Angola specify titanium for upper riser joints and stress joints on tension-leg platforms.
- Composite:Carbon fiber-reinforced polymer with titanium end fittings targets weight-sensitive floating production applications.
- Aluminum:Cast and forged marine engine manifolds serve vessel cooling systems and recreational boatbuilders.
Steel retains the deepest installed base; titanium commands the steepest expansion trajectory as water depths exceed 1,500 meters.
End User:
Customer type determines contract structure, with integrated operators bundling procurement and marine contractors unbundling installation scope.
- Oil & Gas Companies:Supermajors and national oil companies specify integrated manifold-riser packages with life-of-field service contracts. Petrobras consolidated Brazilian subsea awards with contractors offering full-scope project delivery.
- Marine Contractors:Installation specialists bid vessel-day rates for riser lay and manifold hookup, unbundling equipment from execution to optimize fleet utilization across shallow and deepwater tiers.
- Infrastructure Developers:Port authorities and coastal energy terminals procure cooling manifolds for LNG regasification and power generation facilities.
- Others:Defense and research vessel operators specify custom manifold configurations for specialized mission profiles.
Oil and gas operators control the largest procurement volume; marine contractors are gaining share fastest as installation-only contracting expands.
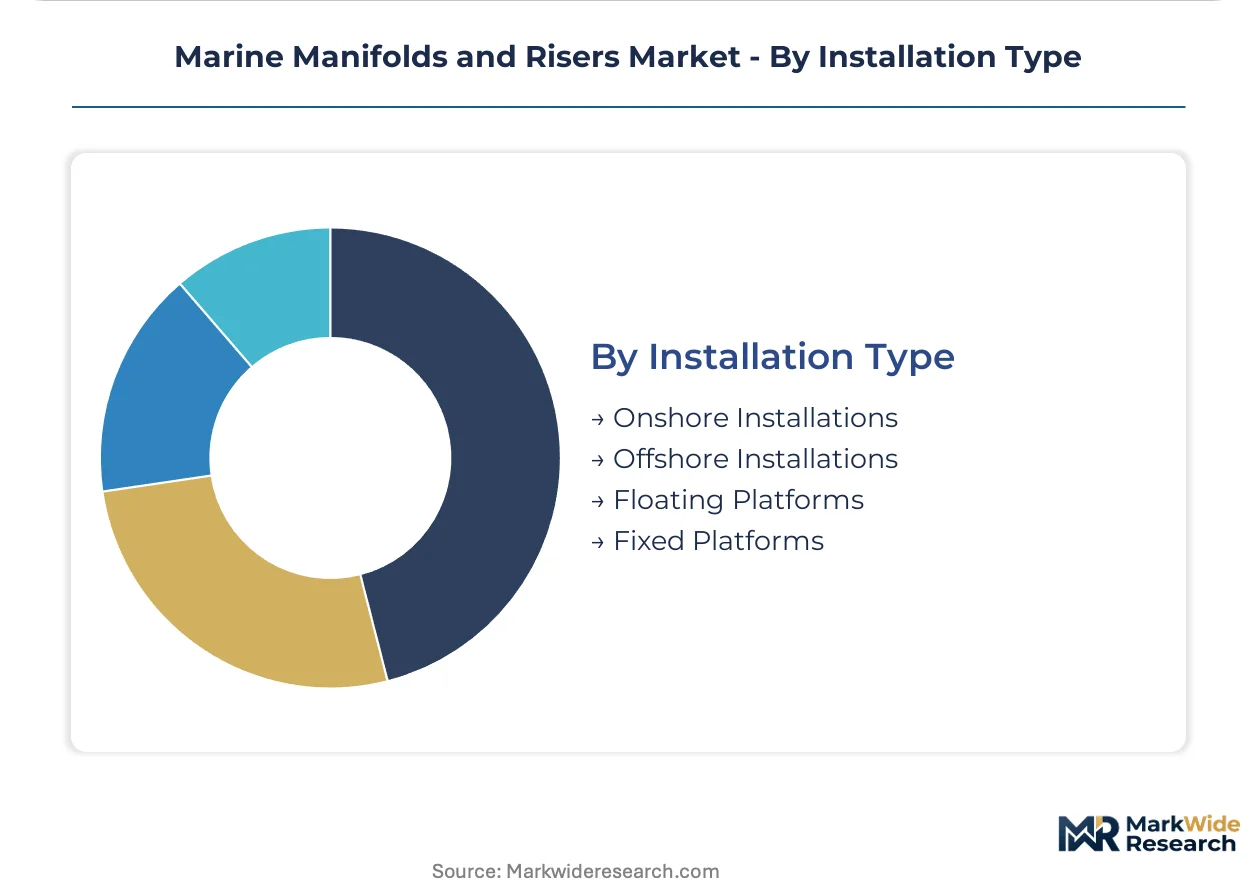
Installation Type:
Application environment dictates metallurgical specification, welding protocol, and regulatory compliance jurisdiction.
- Offshore Installations:Subsea manifold and riser systems in federal waters face API, ISO, and national regulator certification gates. Gulf of Mexico leaseholders navigate EPA methane monitoring mandates alongside BSEE safety requirements.
- Floating Platforms:Tension-leg platforms and FPSOs in Brazil, Angola, and Nigeria specify titanium and composite riser segments to reduce hull steel tonnage and mooring system loads.
- Fixed Platforms:Steel jacket structures in shallower North Sea and Gulf of Mexico waters use conventional steel riser and manifold configurations with established installation methodologies.
- Onshore Installations:Coastal processing facilities and LNG terminals handle lower-pressure manifold assemblies with reduced corrosion protection requirements.
Offshore installations represent the dominant deployment mode; floating platforms are climbing the fastest as pre-salt and ultra-deepwater fields mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of high-pressure manifold forgings concentrates in Scandinavian and Japanese metallurgical centers, while consumption tilts toward deepwater development provinces off Brazil, West Africa, and the Gulf of Mexico where operators deploy subsea production systems.
Brazil
Petrobras-led pre-salt development at Buzios and Mero complexes drives procurement of 15,000 psi riser systems. ANVISA and Brazil's national petroleum regulator enforce material traceability protocols that gate vendor qualification. Rio de Janeiro anchors the country's subsea engineering cluster where integrated service contractors bundle installation and life-of-field maintenance.
United States
Gulf of Mexico ultra-deepwater operators specify titanium stress joints to reduce floating platform topside loads. EPA methane detection mandates for federal waters require continuous monitoring at subsea flange interfaces. Houston hosts the primary procurement decision-making for integrated manifold-riser packages serving Lower Tertiary developments.
Norway
North Sea brownfield replacement programs specify enhanced sour service grades for hydrogen sulfide exposure in mature reservoirs. The Norwegian Petroleum Directorate enforces welding qualification standards that constrain hyperbaric inspector availability. Stavanger and Bergen concentrate subsea engineering capabilities serving North Sea and Barents Sea infrastructure.
Angola
Block 15/06 and 17 development plans create demand for steel catenary riser configurations in ultra-deepwater. The national petroleum regulator aligns with ISO 13628-7 for subsea equipment certification. Luanda serves as the coordination hub for installation contractors bidding vessel-day rates across West African deepwater tiers.
United Kingdom
North Sea decommissioning and life-extension projects drive aftermarket manifold replacement demand. The Health and Safety Executive enforces pressure equipment directives for subsea systems. Aberdeen maintains Europe's densest concentration of subsea engineering contractors and hyperbaric welding certification pools.
Marine Manifolds and Risers Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, creating a bifurcated structure where integrated system vendors capture bundled contracts while component fabricators serve unbundled installation scopes. The market organizes around three strategic archetypes: captive metallurgy-to-installation conglomerates, specialized forging houses, and marine propulsion heritage brands serving aftermarket replacement. Dominant competitive moves include backward integration into alloy supply chains and geographic clustering near deepwater development provinces to compress logistics cycles.
Among marine propulsion heritage brands, Volvo Penta and Mercury Marine occupy positions spanning OEM supply and aftermarket manifold replacement across Nordic and North American vessel fleets. TechnipFMC anchors the integrated subsea production system tier, representing the conglomerate archetype that bundles umbilical-to-wellhead architecture with captive installation vessel access. These three exemplify how competitive positioning splits between vessel-engine aftermarket density and deepwater project-scale integration capability.
| Leading Market Players |
|---|
| Volvo Penta |
| Mercury Marine |
| BARR Marine |
| Mercruiser |
| Indmar |
| Blue Jacket Marine Products |
| EMP-Engineered Marine Products |
| Stainless Marine |
| TechnipFMC |
| Others |
Value Chain & Pricing Dynamics
Captive metallurgical supply chains anchor both procurement positioning and pricing power for integrated subsea production system vendors serving deepwater oil and gas developments. TechnipFMC's control over umbilical-to-wellhead architecture compresses vendor qualification timelines while insulating margin structures from raw material volatility in duplex stainless steel markets.
Pricing Analysis
Margin tightening in forged high-pressure manifold assemblies reflects extended API 6A PSL 3G certification cycles stretching to 18-24 months. Project-based long-term offtake contracts dominate, with price differentiation tracking sour service certification grade and volume scale for Petrobras pre-salt packages. Cost compression accelerates in standard carbon steel tiers as Chinese fabrication capacity expands, while titanium stress joints retain pricing resilience due to Scandinavian and Japanese metallurgical supply concentration. Marine contractors exhibit highest price sensitivity, unbundling installation scope to optimize vessel-day economics, whereas integrated operators accept premium pricing for life-of-field service bundling.
Supply Chain Analysis
Refurbishment flows for North Sea brownfield manifold replacement create secondary supply channels alongside primary forging capacity. Production concentrates in Norway, Japan, and Sweden for premium-grade duplex stainless steel and titanium alloy inputs. The supply chain rests on forged connector forgings, API-qualified welding consumables, and hyperbaric installation equipment. Single-source vulnerability in hyperbaric welding inspector certification pools constrains project ramp rates. Distribution runs through Rio de Janeiro, Houston, and Stavanger engineering clusters co-located with deepwater operator procurement decision-making.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite-titanium hybrid riser technology is displacing conventional steel configurations in Brazil's 2,000-meter pre-salt developments, forcing concurrent evolution in procurement contracting and supplier capability investment.
For Market Incumbents: Lock in captive metallurgical supply through backward integration into Scandinavian and Japanese forging capacity, or through long-term offtake agreements with duplex stainless steel suppliers. Invest in hyperbaric welding inspector certification programs to defend project ramp rate capabilities against emerging installation contractors. Prioritize API 6A and ISO 13628-7 compliance automation to compress 18-24 month qualification timelines.
For New Entrants and Emerging Players: Fiber-optic leak detection integration into API 6A flange designs offers technology-first entry into EPA methane monitoring retrofit demand across Gulf of Mexico brownfield infrastructure. Target aftermarket sensor-integrated sealing systems for North Sea decommissioning and life-extension projects, where legacy platform hydraulic interface complexity favors specialized engineering over integrated system bundling.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated subsea production system vendors seeking captive installation vessel access and regional engineering clustering. Long-term viability favors pure-play specialists with demonstrated qualification status under ANVISA, BSEE, and Norwegian Petroleum Directorate protocols. Monitor titanium alloy adoption rates in Angola Block 15/06 and 17 developments as inflection indicator for composite-titanium hybrid architecture displacement of steel riser supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging Capacity | Captive duplex stainless steel supply insulates margin structures from Scandinavian supplier concentration. |
| Hyperbaric Welding Certification Expansion | Qualified inspector pools in Rio de Janeiro and Stavanger compress project ramp timelines for deepwater installation. |
| Composite-Titanium Hybrid Riser Development | Petrobras pilot programs at 2,000-meter depths validate bonded transition architecture for pre-salt standardization. |
| Fiber-Optic Leak Detection Integration | EPA methane monitoring mandates drive retrofit demand across Gulf of Mexico subsea flange interfaces. |
| Regional Engineering Cluster Establishment | Luanda and Luanda-adjacent capabilities capture Angola ultra-deepwater installation contract pools. |
Study Parameters
Document review covered API standards filings, ANVISA regulatory protocols, and subsea project development databases, complemented by interviews with subsea engineering directors, hyperbaric welding certification authorities, Petrobras procurement leads, and installation contractor fleet managers. Secondary validation drew from American Petroleum Institute technical reports, ISO 13628-7 documentation, and national petroleum regulator disclosure filings. Bottom-up equipment procurement tracking and top-down field development capex analysis were triangulated to reconcile volume estimates.
Historical deployment patterns for steel catenary and titanium riser configurations were cross-referenced against panel input from subsea system vendors and floating platform operators across the projection horizon. Segmentation modeling incorporated pressure rating tiers, metallurgical grade specifications, installation architecture types, and end-user contract structures. CAGRs were derived from water depth progression curves and pre-salt field maturation schedules, with sensitivity analysis around titanium alloy cost trajectories and composite thermal limitation thresholds.
Several conditions sit outside the modeled scope, including abrupt regulatory shifts in methane emission detection enforcement, geopolitical disruption to Scandinavian metallurgical supply, and unanticipated breakthroughs in polymer matrix composite temperature resistance. Forecasts reflect documented assumptions regarding Petrobras capital allocation continuity and Gulf of Mexico leaseholder development timelines. Practitioners should monitor ANP licensing rounds, BSEE safety directive revisions, and titanium sponge price indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Wind Turbine Installation Vessel Market
Marine and Coastal Engineering
Marine Cranes Market
Marine and Coastal Engineering
Submersible Dredge Pump Market
Marine and Coastal Engineering
Mooring Bollards Market
Marine and Coastal Engineering
Marine Heat Exchanger Market
Marine and Coastal Engineering
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market
Marine and Coastal Engineering
Middle East Offshore Crane Market
Marine and Coastal Engineering
Asia-Pacific Offshore Crane Market
Marine and Coastal Engineering
Offshore Pipeline Market
Marine and Coastal Engineering
Global Marine and Dock Gangways Market
Marine and Coastal Engineering
Global Pipe Laying Vessel Market
Marine and Coastal Engineering
STS (Ship-To-Shore) Cranes Market
Marine and Coastal Engineering
Cable Laying Vessel Market
Marine and Coastal Engineering
Global Marine Ventilation Systems Market
Marine and Coastal Engineering
Dredging Market
Marine and Coastal Engineering
Ship-To-Shore Cranes Market