
 Hydraulic Shearing Machine Market | 2026-2036
Hydraulic Shearing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Shearing Machine Market Analytics
Aftermarket service revenue is reshaping margin distribution across the hydraulic shearing machine value chain, pulling profitability away from unit sales toward lifecycle support contracts. Amada leverages its installed base in Japan and Southeast Asia to sustain recurring parts revenue streams. LVD anchors European demand through localized refurbishment centers in Belgium and the Netherlands. Durma competes on manufacturing scale from its Turkish production hub, offering shorter lead times for Middle Eastern and African buyers.
A hydraulic shearing machine applies force through a fluid-driven ram to cut sheet metal and plate material, typically operating at pressures between 20 and 60 tons with blade lengths spanning 1.5 to 6 meters for industrial throughput. Its primary purpose centers on producing clean, distortion-free edges in steel, aluminum, and alloy processing for downstream fabrication. CNC technology commands the premium tier as programmable backgauges and angle adjustments reduce setup waste in high-mix metal fabrication environments. Hydraulic product types retain volume leadership across steel industries handling thick plate above 12 millimeters, where mechanical alternatives lack cutting force. Servo-electric variants capture fastest growth in automotive manufacturing lines prioritizing energy recovery and positional repeatability within 0.01 millimeters.
OSHA machine guarding standards in the United States mandate two-hand controls and light curtain integration on new installations, elevating retrofit demand among workshops with pre-2010 equipment. CE marking under the EU Machinery Directive enforces documented risk assessments for hydraulic systems sold across Europe, creating compliance barriers for non-certified imports. China's GB standards and SAMR enforcement actions on industrial safety are accelerating domestic replacement cycles. Stakeholders must monitor how regional certification divergence affects cross-border equipment trade and service portability.
Market Dynamics
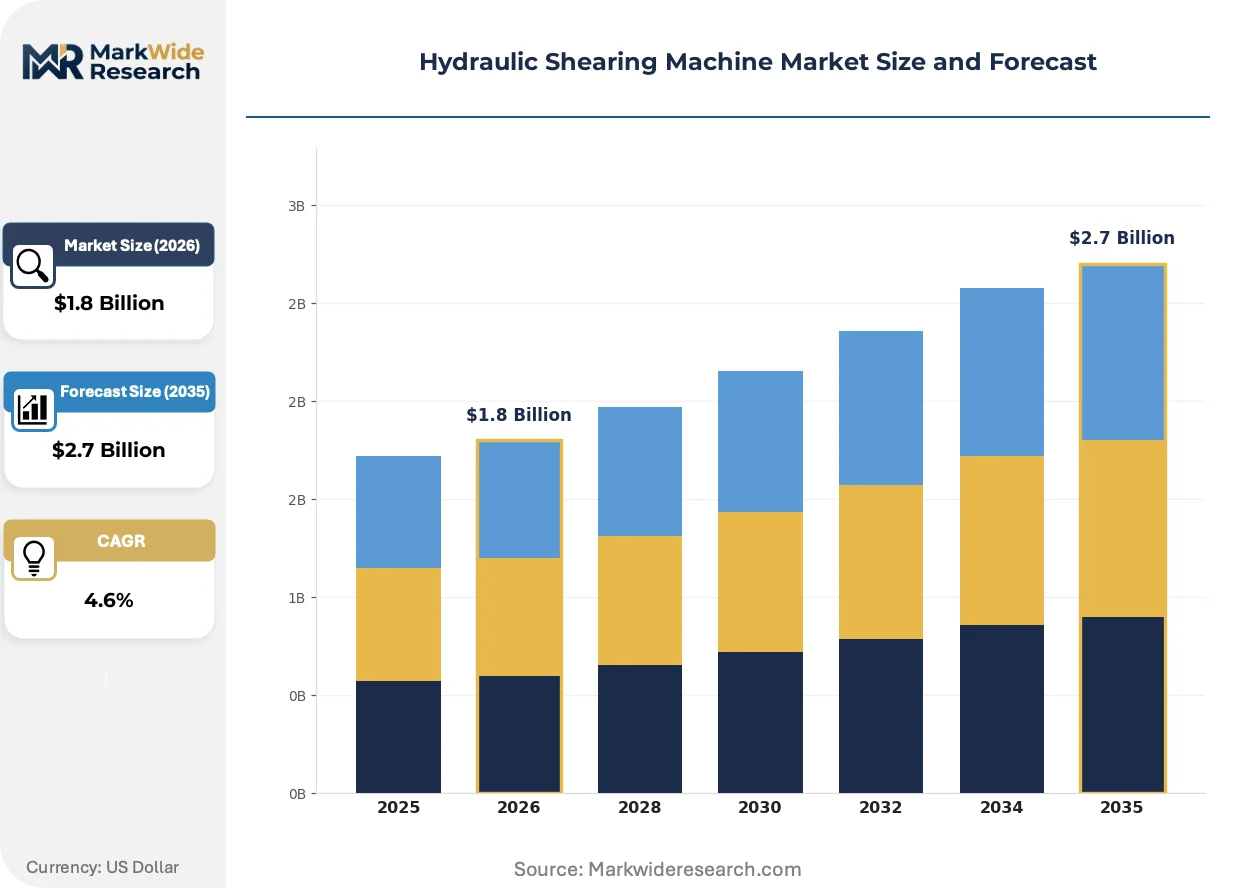
Aftermarket service revenue is pulling profitability away from unit sales toward lifecycle support contracts, while China's NMPA safety directives and dual carbon goals tighten energy-efficiency standards for industrial machinery.
Growth Catalysts
- Automotive precision stamping:OEMs across Germany, Japan, and the United States deploy CNC-hydraulic platforms for high-volume steel and aluminum processing with distortion-free edge quality.
- CE marking enforcement:The EU Machinery Directive mandates documented risk assessments for hydraulic systems, accelerating replacement cycles among European fabricators with pre-certified equipment preferences.
- China's dual carbon policy:MEE and SAMR enforcement actions on industrial energy consumption are forcing domestic workshops to retire mechanical shears for servo-hydraulic alternatives.
Market Restraints
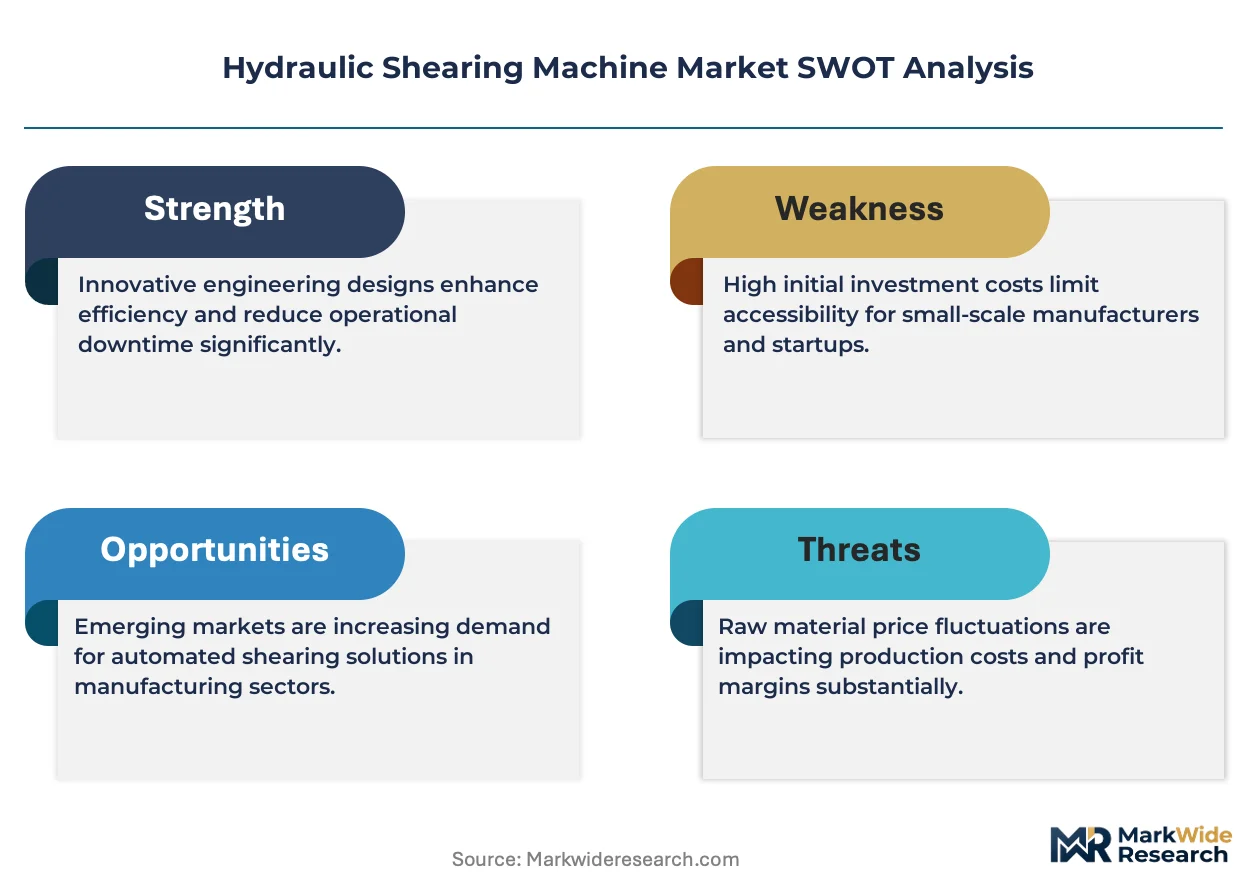
- Specialized steel input costs:Tool-grade blade alloys and high-pressure hydraulic fluid formulations expose margins to commodity volatility in specialty metals.
- Component supply concentration:Precision servo valves and linear encoders concentrate among German and Japanese component specialists, creating single-source vulnerability.
- Servo-electric substitution:Automotive lines handling thin-gauge material below 6 millimeters increasingly favor servo-electric shears for energy recovery and positional repeatability.
Strategic Opportunities
- India's PLI scheme for manufacturing:Steel fabrication clusters in Gujarat and Tamil Nadu lack modern shearing capacity, creating first-mover advantage for CNC-hydraulic system providers.
- Refurbishment services:Belgium and the Netherlands host underdeveloped refurbishment infrastructure for legacy mechanical-to-hydraulic conversions across Benelux metal workshops.
- Light curtain retrofit mandates:OSHA two-hand control requirements for pre-2010 equipment create compliance-driven upgrade revenue streams in United States job shops.
Industry Challenges
- CNC programming skill scarcity:Metal fabrication workshops struggle to hire operators capable of G-code backgauge programming and angle adjustment calibration.
- CE certification timeline compression:Third-party notified body queues for hydraulic system risk documentation extend equipment delivery windows by 8-14 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Shearing Machine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Hydraulic, Pneumatic, Servo Technology: Electric, Manual, CNC, Hybrid Application: Metal Fabrication, Automotive Manufacturing, Construction, Aerospace End User: OEMs, Workshops, Steel Industries, Repair Service Providers |
| Companies Covered | JMT, LVD, Durma, Amada, HARSLE, ADH Machine Tool, JEAN PERROT, Accurpress, Yangli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Shearing Machine Market Evolving Landscape
Digital twin technology is virtualizing commissioning workflows and compressing setup waste in high-mix fabrication environments. Three convergent forces are reshaping equipment specification, regulatory compliance, and buyer-supplier relationships.
Digital twin software is virtualizing machine commissioning and operator training for hydraulic shearing systems before physical installation. Tier-one automotive stampers in Germany and Japan deploy these virtual environments to reduce first-article inspection cycles. The technology is virtualizing traditional on-site调试 (debugging) processes, compressing deployment timelines and reducing scrap during production ramp-up.
REACH substance restrictions on hydraulic fluids are forcing reformulation of mineral oil-based pressure media across European installations. The ECHA authorization list now covers several anti-wear additives common in legacy systems, elevating bio-based synthetic alternatives. Metal fabricators in Italy and Poland face accelerated fluid replacement schedules and disposal compliance costs.
Buyer preference is consolidating around unbundled after-sales service contracts separate from equipment procurement. Japanese and Southeast Asian fabricators now source spare parts and preventive maintenance from third-party specialists rather than captive OEM service divisions. This pattern is most visible in automotive supply chains where total cost of ownership modeling dominates capital expenditure committees.
Hydraulic Shearing Machine Market Segmentation
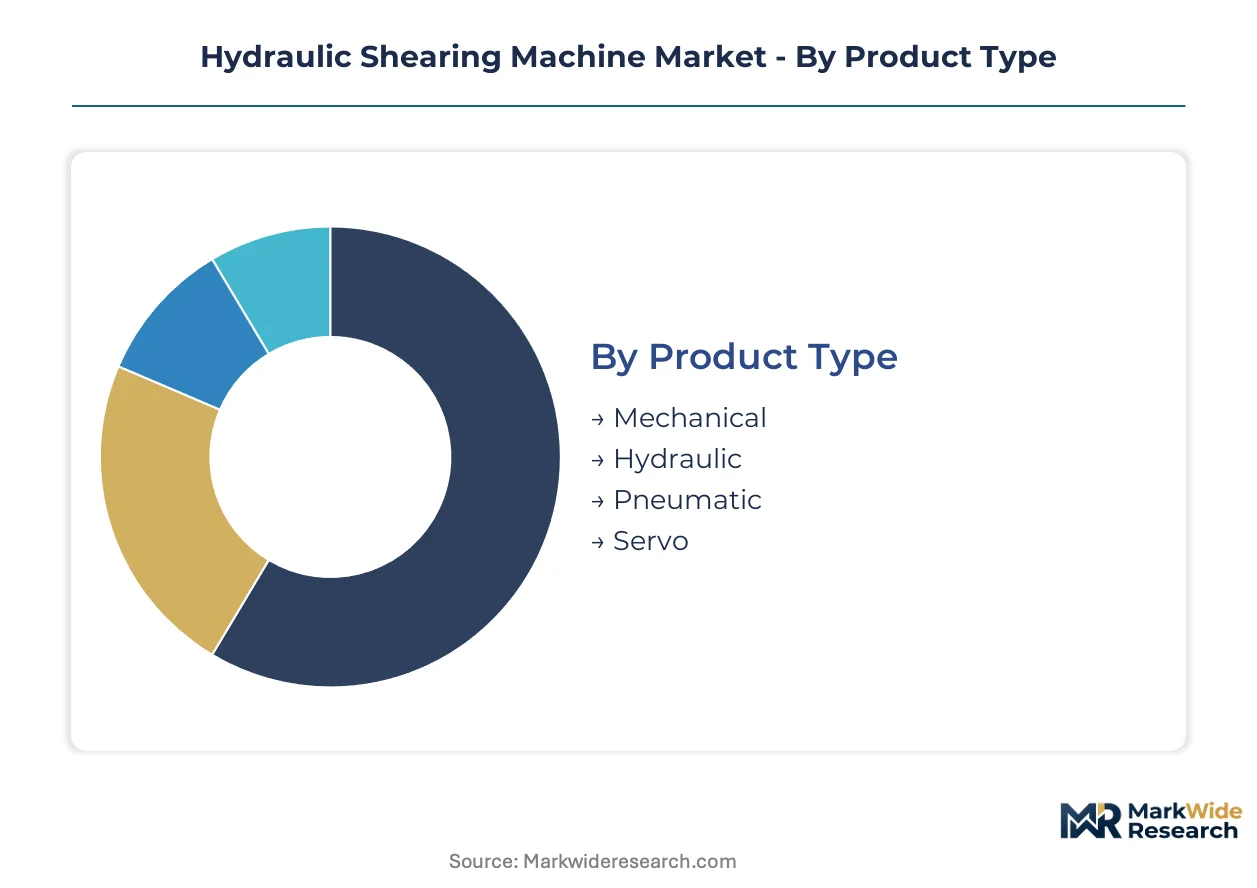
Segmentation in hydraulic shearing machines separates volume-driven commodity procurement from precision-specified capital investments. Buyers in automotive stamping and steel fabrication operate under fundamentally different technical requirements, forcing suppliers to maintain parallel product architectures.
Product Type:
Cost tier determines blade force economics and maintenance cadence across workshop capital budgets.
- Hydraulic:Fluid-driven rams generate 20-60 tons of cutting force with blade lengths spanning 1.5-6 meters, handling plate thickness above 12 millimeters where mechanical alternatives fail. Steel industries in Germany's Ruhr cluster and China's Hebei province specify these systems for distortion-free edge quality in structural steel processing.
- Servo:Electric servo motors with ball-screw drives achieve positional repeatability within 0.01 millimeters while recovering energy during deceleration cycles. Automotive OEMs in Japan and the United States favor these units for thin-gauge aluminum and high-strength steel below 6 millimeters.
- Mechanical:Flywheel-powered crank mechanisms dominate legacy installations in Eastern European job shops with limited capital replacement budgets.
- Pneumatic:Compressed-air systems serve light-duty sheet metal operations in HVAC duct fabrication and signage production.
Hydraulic systems hold installed capacity across heavy fabrication. Servo is rotating up the share rankings in automotive powertrain stamping.
Technology:
Automation depth separates price-competitive commodity supply from premium-specified programmable platforms.
- CNC:Programmable backgauges with G-code compatibility reduce setup waste through automated angle adjustment and stroke optimization. Metal fabrication workshops in Belgium and the Netherlands specify these for high-mix, low-volume production environments where changeover frequency exceeds 15 cycles per shift.
- Electric:All-electric architectures eliminate hydraulic fluid maintenance and REACH compliance costs for European fabricators facing ECHA substance restrictions on mineral oil formulations.
- Manual:Hand-cranked backgauges persist in developing market job shops where CNC programming skill scarcity limits technology absorption.
- Hybrid:Combined hydraulic power with electric backgauge control offers intermediate automation for mid-capacity steel service centers.
CNC platforms hold installed capacity across precision fabrication. Electric is rotating up the share rankings in regulatory-constrained European markets.
Application:
End-use geometry and material specification dictate blade alloy selection and ram force calibration.
- Metal Fabrication:General-purpose steel and aluminum processing for structural components, architectural metalwork, and industrial equipment housings. Demand concentrates in India's Gujarat and Tamil Nadu clusters where PLI scheme incentives are accelerating domestic capacity expansion.
- Automotive Manufacturing:High-volume stamping of body-in-white panels, chassis rails, and powertrain brackets requiring distortion-free edges for downstream welding operations. OEMs across Germany, Japan, and the United States deploy these systems in 24/7 production cycles.
- Construction:Heavy plate shearing for bridge girders, building frames, and infrastructure rebar processing.
- Aerospace:Titanium and aluminum alloy cutting for airframe stringers and wing ribs with tight tolerances on edge squareness.
Metal fabrication holds installed capacity across general industrial supply. Automotive manufacturing is rotating up the share rankings in electric vehicle platform investments.
End User:
Customer scale determines procurement modality and aftermarket service contract structure.
- OEMs:Integrated automotive and appliance manufacturers with captive metal stamping operations negotiate total cost of ownership contracts spanning 10-15 year equipment lifecycles. These buyers specify predictive maintenance integration and digital twin commissioning support.
- Steel Industries:Primary metal producers and service centers handling raw coil and plate distribution require maximum throughput with minimal operator intervention.
- Workshops:Independent job shops with 5-50 employee headcount prioritize equipment financing flexibility and third-party spare parts availability over OEM captive service divisions.
- Repair Service Providers:Specialized refurbishment contractors in Belgium and the Netherlands converting legacy mechanical systems to CNC-hydraulic platforms.
OEMs hold installed capacity across integrated manufacturing. Workshops are rotating up the share rankings as unbundled aftermarket procurement patterns spread from Southeast Asia into European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr cluster demands CNC-hydraulic platforms for thick-plate structural steel, while Japan's automotive stampers prioritize servo-electric units for thin-gauge aluminum. China's Hebei province and India's Gujarat cluster represent divergent procurement patterns—state-mandated energy retrofits versus PLI-scheme capacity buildouts.
United States
Automotive OEMs in Detroit and stamping suppliers across the Midwest specify CNC-hydraulic systems for high-volume steel processing. OSHA machine guarding standards mandate two-hand controls and light curtain integration on new installations, elevating retrofit demand among pre-2010 equipment owners. Pittsburgh-area steel service centers upgrade legacy mechanical shears to hydraulic platforms for distortion-free edge quality.
Germany
Automotive body-in-white stamping operations in Bavaria and Baden-Württemberg deploy precision shearing equipment for 24/7 production cycles. CE marking under the EU Machinery Directive enforces documented risk assessments for hydraulic systems, creating compliance barriers for non-certified imports. The Ruhr industrial cluster concentrates steel fabrication workshops converting mechanical systems to CNC-hydraulic platforms.
China
Hebei province's steel mills and fabrication workshops face forced equipment turnover under MEE enforcement actions on industrial energy consumption. NMPA safety directives and dual carbon goals tighten energy-efficiency standards, compelling retirement of mechanical shears for servo-hydraulic alternatives. Yangtze River Delta automotive suppliers specify programmable backgauges for high-mix aluminum processing.
Japan
Automotive powertrain stampers in Aichi Prefecture and Kanto-region OEMs favor servo-electric variants for thin-gauge high-strength steel below 6 millimeters. METI industrial efficiency guidelines accelerate replacement of legacy hydraulic systems in metal fabrication workshops. Osaka-area job shops source unbundled aftermarket services from third-party specialists rather than captive OEM divisions.
India
Steel fabrication clusters in Gujarat and Tamil Nadu lack modern shearing capacity despite PLI scheme incentives for domestic manufacturing expansion. BIS certification requirements and DGFT import regulations shape equipment procurement timelines for workshop buyers. Mumbai-Pune industrial corridor job shops prioritize equipment financing flexibility over OEM captive service contracts.
Hydraulic Shearing Machine Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated structure where precision engineering specialists and high-volume fabricators occupy distinct competitive spaces. Japanese and European vendors anchor premium CNC-hydraulic segments through localized refurbishment networks, while Turkish and Chinese producers compete on manufacturing scale and lead-time compression. Two strategic archetypes dominate: integrated technology providers with captive aftermarket ecosystems, and scale-focused fabricators serving price-sensitive emerging markets. Competitive moves center on geographic expansion into India's PLI-driven clusters and portfolio diversification toward servo-electric architectures.
Among Japanese-anchored specialists, Amada exemplifies the integrated-service archetype through recurring parts revenue streams sustained across Southeast Asian installed bases. LVD occupies a position within European premium-tier supply, anchoring demand through Belgium and Netherlands refurbishment centers. Durma represents scale-driven competition from its Turkish production hub, offering shorter lead times for Middle Eastern and African buyers. These three patterns—captive aftermarket integration, regional refurbishment density, and manufacturing-scale proximity—define the competitive landscape's structural segmentation.
| Leading Market Players |
|---|
| JMT |
| LVD |
| Durma |
| Amada |
| HARSLE |
| ADH Machine Tool |
| JEAN PERROT |
| Accurpress |
| Yangli |
| Others |
Value Network & Pricing Analysis
Single-source dependency on German and Japanese precision servo valves determines both pricing tier spreads and supply chain shape across hydraulic shearing machine procurement. Buyers face extended delivery windows and elevated premiums for CNC-hydraulic platforms when component specialists throttle output, while workshops in price-sensitive segments retreat to mechanical alternatives or Turkish-manufactured standard-tier equipment.
Pricing Analysis
Long-term lifecycle support contracts dominate OEM procurement, bundling predictive maintenance and spare parts availability into ten-to-fifteen-year total cost of ownership agreements. Three-tier pricing structure across premium CNC-hydraulic, standard hydraulic, and economy mechanical levels reflects certification grade differentiation and after-sales service bundling. Cost compression in the standard tier is intensifying because Turkish and Chinese manufacturers compress lead times for Middle Eastern and African buyers. Workshop segments with limited capital replacement budgets exhibit highest price sensitivity, while integrated automotive OEMs prioritize performance guarantees over unit economics.
Supply Chain Analysis
Export-control regimes limiting precision linear encoder and servo valve flows from Germany and Japan concentrate supply vulnerability among European and North American CNC-hydraulic assemblers. Manufacturing gravity centers on Turkey, China, and Germany, with component sourcing drawing from Japanese motion-control specialists and Italian hydraulic fluid formulators. Single-source vulnerability in ball-screw drives and high-pressure seals creates chokepoint exposure when regional trade restrictions activate. Distribution runs through captive OEM service divisions in developed markets and third-party aftermarket specialists in Southeast Asia and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as automotive electrification and construction infrastructure cycles create divergent equipment specifications, opening niches for specialized servo-electric and heavy-plate hydraulic providers respectively.
For Market Incumbents: Entrench installed base loyalty through captive refurbishment networks and predictive maintenance integration, countering servo-electric substitution in automotive thin-gauge applications. Expand certification investment for CE marking and China's GB standards compliance to erect import barriers against Turkish scale competitors. Vertical integration into blade alloy recycling and hydraulic fluid reformulation defends margin position against REACH-driven input cost volatility.
For New Entrants and Emerging Players: India's Gujarat and Tamil Nadu steel fabrication clusters offer the most penetrable geography, where PLI scheme incentives outpace domestic CNC-hydraulic supply capacity. Target workshop segments with unbundled aftermarket procurement patterns spreading from Southeast Asia, positioning third-party spare parts and preventive maintenance as alternatives to captive OEM service divisions. Pursue equipment financing flexibility as the primary go-to-market angle for Mumbai-Pune corridor job shops.
For Investors and Strategic Acquirers: China's dual carbon policy enforcement reshapes the acquisition landscape, accelerating replacement demand for servo-hydraulic alternatives and devaluing mechanical shear portfolios. Target refurbishment specialists with Belgium and Netherlands infrastructure access and documented risk assessment capabilities under EU Machinery Directive. Watch NMPA safety directive implementation velocity as the inflection signal for domestic Chinese equipment turnover rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Refurbishment Center Expansion | Belgium and Netherlands infrastructure captures legacy mechanical-to-hydraulic conversion demand across Benelux metal workshops. |
| Servo-Electric Architecture Diversification | Automotive OEMs in Japan and Germany specify thin-gauge aluminum processing with 0.01 millimeter positional repeatability. |
| Third-Party Aftermarket Platform | Osaka-area job shops and Southeast Asian fabricators source spare parts outside captive OEM service divisions. |
| REACH-Compliant Fluid Reformulation | ECHA authorization list coverage forces bio-based synthetic alternatives for Italian and Polish metal fabricators. |
| Digital Twin Commissioning Integration | Tier-one automotive stampers in Bavaria reduce first-article inspection cycles through virtual environment deployment. |
Research Methodology
Desk research of trade customs data, EU Machinery Directive filing databases, and SEC equipment manufacturer disclosures preceded structured interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads across Germany, Japan, China, and the United States. Primary fieldwork with metal fabrication workshop owners and automotive stamping operations directors validated secondary estimates of installed base age and replacement intent. Bottom-up equipment shipment analysis triangulated against top-down steel processing capacity expansion figures.
Assumption sets held regional regulatory enforcement timelines and commodity alloy price corridors within observed ranges while varying automotive platform electrification penetration and construction infrastructure investment intensity across the projection horizon. Segmentation modeling incorporated product type, technology depth, application geometry, and end-user scale dimensions. CAGRs derived from regression analysis of historical equipment procurement cycles against steel production and automotive stamping output indices, with hydraulic fluid formulation cost trajectories and servo valve lead time volatility as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Turkish manufacturers or accelerated REACH substance restrictions would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Wood Milling Machine Market
Construction Equipment
Stamping Machines Market
Construction Equipment
Asia-Pacific Mobile Light Tower Market
Construction Equipment
Turkey Construction Equipment Market
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
Saudi Arabia Completion Equipment and Services Market
Construction Equipment
Grinding Machinery Market
Construction Equipment
Gear Grinding Machine Market
Construction Equipment
Construction Pump Market
Construction Equipment
Saudi Arabia Construction Equipment Market
Construction Equipment
Used Construction Equipment Market
Construction Equipment
Industrial Nailers Market
Construction Equipment
GCC Crane Market
Construction Equipment
Global Portable Light Towers Market
Construction Equipment
Europe Used Construction Machinery Market
Construction Equipment
Rockbreakers Market