
 Floating Docks Market | 2026-2036
Floating Docks Market Size, Share, and Industry Trends Forecast 2026-2036
Floating Docks Market Analysis
The EU Green Deal is expanding requirements for marine construction materials, pushing dock manufacturers toward lower-carbon aluminum and recycled plastic formulations. Bellingham Marine leverages its West Coast manufacturing scale to supply high-volume marina projects with certified sustainable timber-aluminum hybrids. Marinetek anchors its competitive position through integrated design-build capabilities across Nordic and Baltic waterfront developments. EZ Dock differentiates via rotational-molded polyethylene systems that eliminate chemical treatments and reduce lifecycle maintenance costs for recreational users.
A floating dock is a buoyant platform structure, typically constructed from aluminum extrusions, reinforced concrete pontoons, or high-density polyethylene modules, designed to provide stable water-level access for vessels, equipment, or pedestrian traffic regardless of tidal fluctuation. These systems incorporate foam-filled flotation chambers or concrete displacement hulls achieving specific buoyancy ratios, with load ratings spanning residential jet-ski berths to industrial cargo transfer facilities. Modular plastic docks lead the product type landscape due to rapid installation and reconfiguration flexibility, though concrete docks command premium positioning in permanent commercial and government installations where fifty-year service life justifies higher capital outlay. Aluminum docks represent the fastest-expanding segment as marina operators balance durability against weight constraints for deep-water pile-supported configurations.
The US Army Corps of Engineers and EPA jointly govern dock permitting through Clean Water Act Section 404 and Rivers and Harbors Act provisions, creating compliance complexity that favors established manufacturers with dedicated regulatory affairs capacity. CE marking under the EU Construction Products Regulation and national maritime authority type-approval processes in France, Germany, and Italy determine market access across European coastal zones. Stakeholders must monitor evolving shoreline protection mandates and flood-resilience building codes as climate adaptation spending redirects public procurement toward elevated and relocatable dock configurations.
Market Dynamics
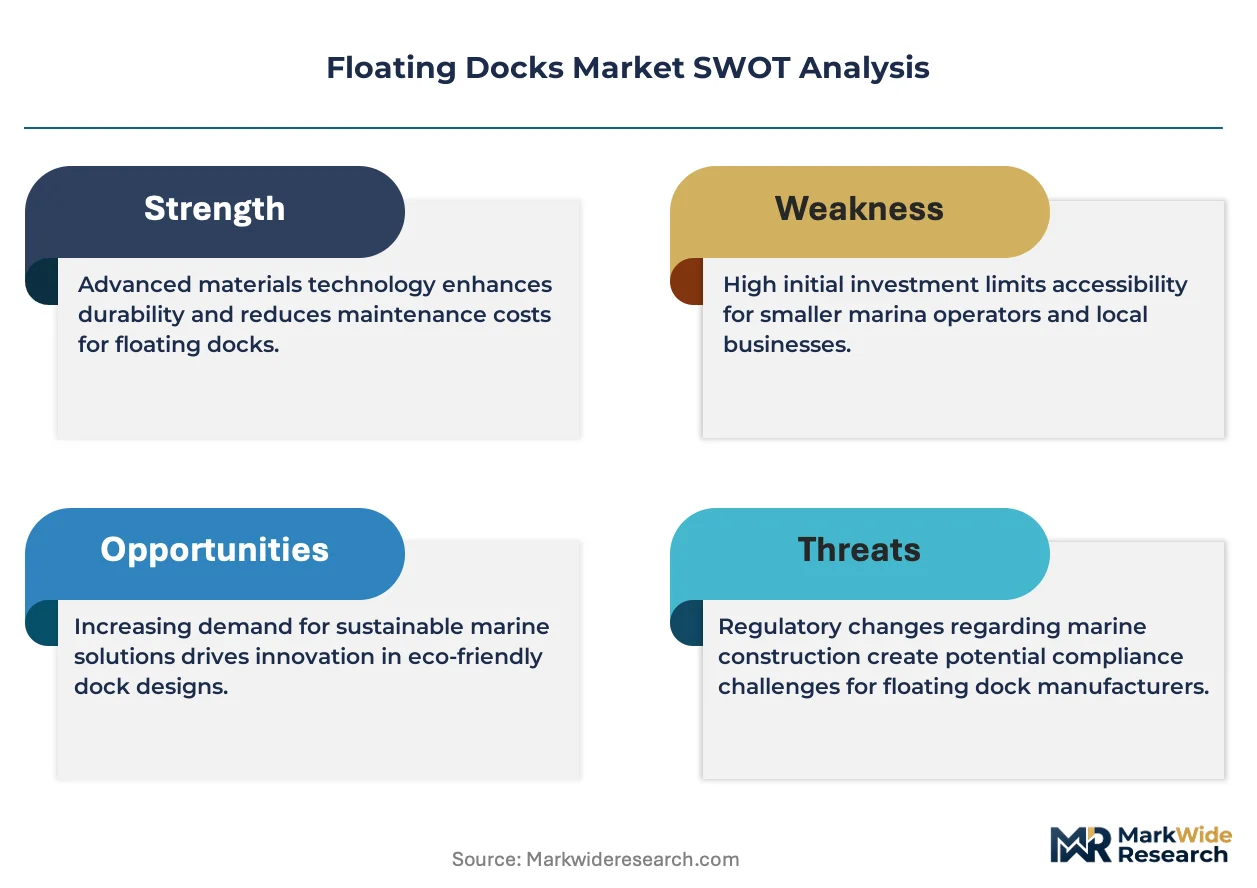
The EU Green Deal's marine infrastructure sustainability criteria are forcing dock manufacturers to reformulate material specifications and recertify product lines for European coastal installations. This regulatory pressure cascades through supply chains, reshaping competitive positioning between aluminum extrusion suppliers, recycled polymer compounders, and certified timber processors.
Growth Catalysts
- Modular aluminum systems:Marina operators in Spain, Italy, and Greece are specifying lightweight, corrosion-resistant aluminum extrusions for deep-water pile-supported configurations to reduce installation labor and extend service intervals.
- CE marking harmonization:The EU Construction Products Regulation streamlines type-approval processes across France, Germany, and Italy, reducing time-to-market for certified dock manufacturers.
- Rotational-molded polyethylene:Recreational waterfront developers are specifying foam-filled HDPE modules that eliminate chemical treatments and enable rapid seasonal reconfiguration.
Market Restraints
- Aluminum price volatility:Primary aluminum ingot costs fluctuate with energy-intensive smelting economics, compressing margins for extrusion-dependent dock fabricators.
- Concrete pontoon supply concentration:Reinforced concrete displacement hull production clusters in Mediterranean precast facilities, creating geographic supply risk for northern European projects.
- Clean Water Act permitting friction:US Army Corps of Engineers Section 404 review timelines extend project development cycles, favoring established manufacturers with dedicated regulatory affairs capacity.
Strategic Opportunities
- Flood-resilience procurement:US coastal municipalities are redirecting climate adaptation spending toward elevated and relocatable dock configurations that exceed base flood elevation requirements.
- Integrated design-build contracting:Nordic waterfront developers are bundling engineering, fabrication, and installation to compress project timelines and transfer liability.
- Recycled polymer feedstocks:Post-consumer HDPE sourcing from European packaging waste streams enables circular economy positioning under EU Green Deal circularity metrics.
Industry Challenges
- Marine engineering talent scarcity:Specialized hydrodynamic modeling and coastal structural design expertise concentrates in legacy port engineering firms, constraining independent dock manufacturers.
- Multi-jurisdiction certification timelines:CE marking, national maritime authority type-approval, and local shoreline protection permits create sequential bottlenecks for pan-European product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floating Docks Market |
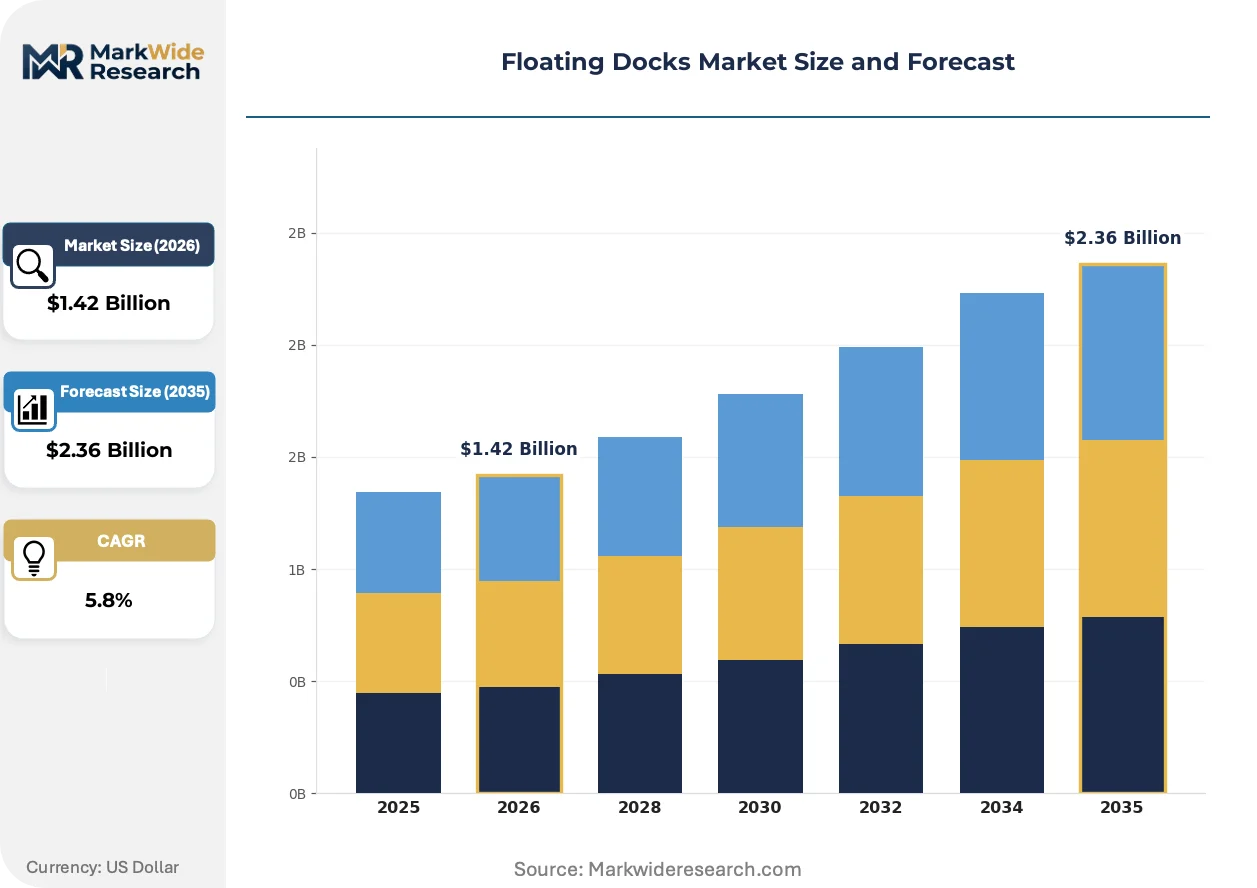
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Docks, Concrete Docks, Aluminum Docks, Plastic Docks Application: Marinas, Residential, Commercial, Industrial End User: Government, Private Sector, Recreational Users, Businesses Installation Type: Permanent, Semi-Permanent, Temporary, Mobile |
| Companies Covered | Bellingham Marine, Marinetek, EZ Dock, Meeco Sullivan, Candock, AccuDock, Jet Dock Systems, SF Marina Systems, Brunswick Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floating Docks Market Emerging Trajectories
Material science advances and regulatory stringency are converging to redefine dock system architecture. Electrification of marina operations and circular economy mandates are accelerating specification shifts across recreational and commercial waterfront developments.
Aluminum-lithium alloy extrusions are electrifying competitive dynamics in deep-water marina construction. Norwegian and Swedish developers are specifying these reduced-weight profiles for pile-supported configurations in fjord environments. The technology is compressing installation equipment requirements and extending viable water depth ranges for modular systems.
REACH restrictions on chromate conversion coatings are eliminating traditional aluminum pretreatment processes across EU dock manufacturing. Manufacturers are migrating to trivalent chromium and cerium-based alternatives that satisfy corrosion resistance standards without hazardous hexavalent chromium. French and Italian regulatory authorities are enforcing accelerated compliance timelines for marine-grade metal finishing.
Seasonal rental and lease-to-own arrangements are displacing outright purchase models in North American recreational dock markets. Independent marina operators and waterfront property managers are unbundling capital expenditure from operational budgets. This pattern concentrates in Great Lakes and Northeast coastal markets where seasonal usage patterns reduce utilization-based ROI calculations.
Floating Docks Market Segmentation
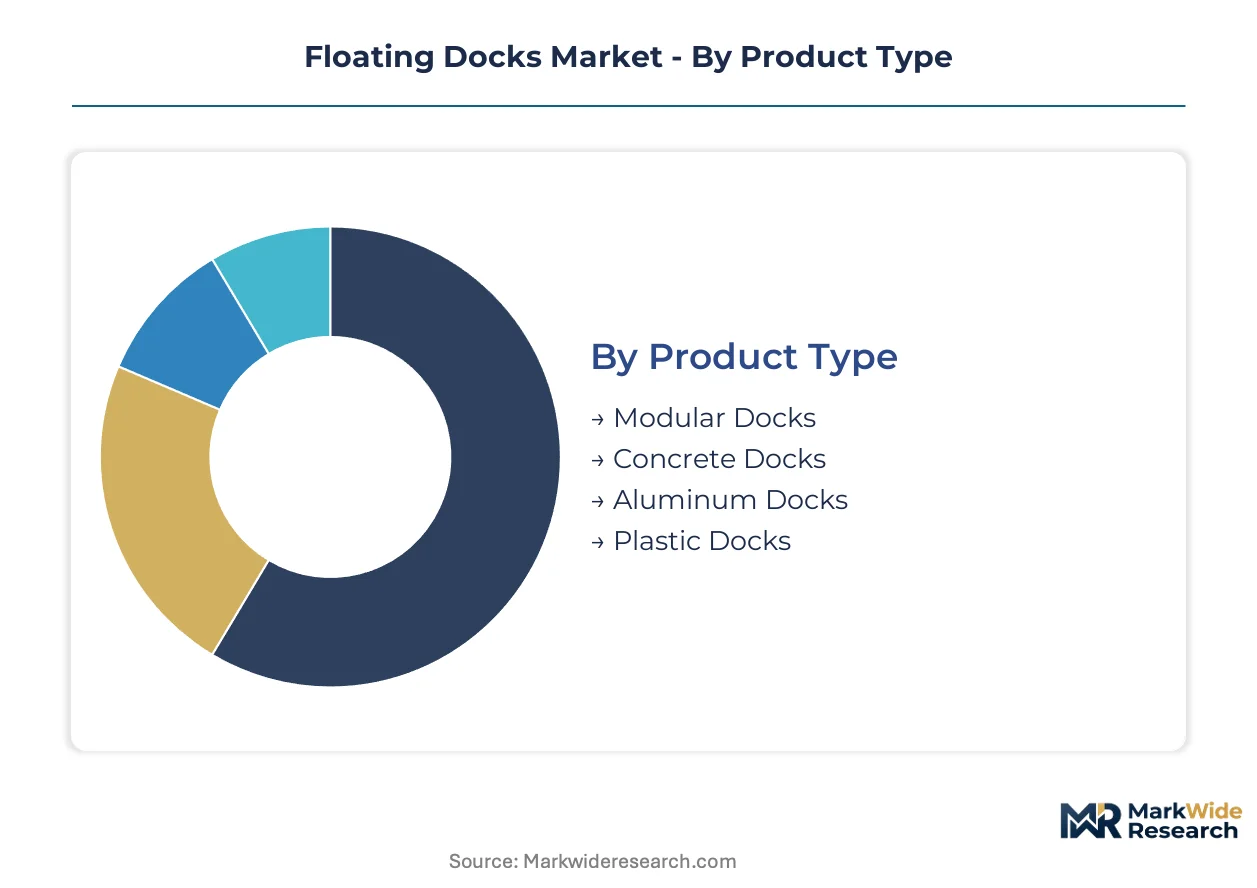
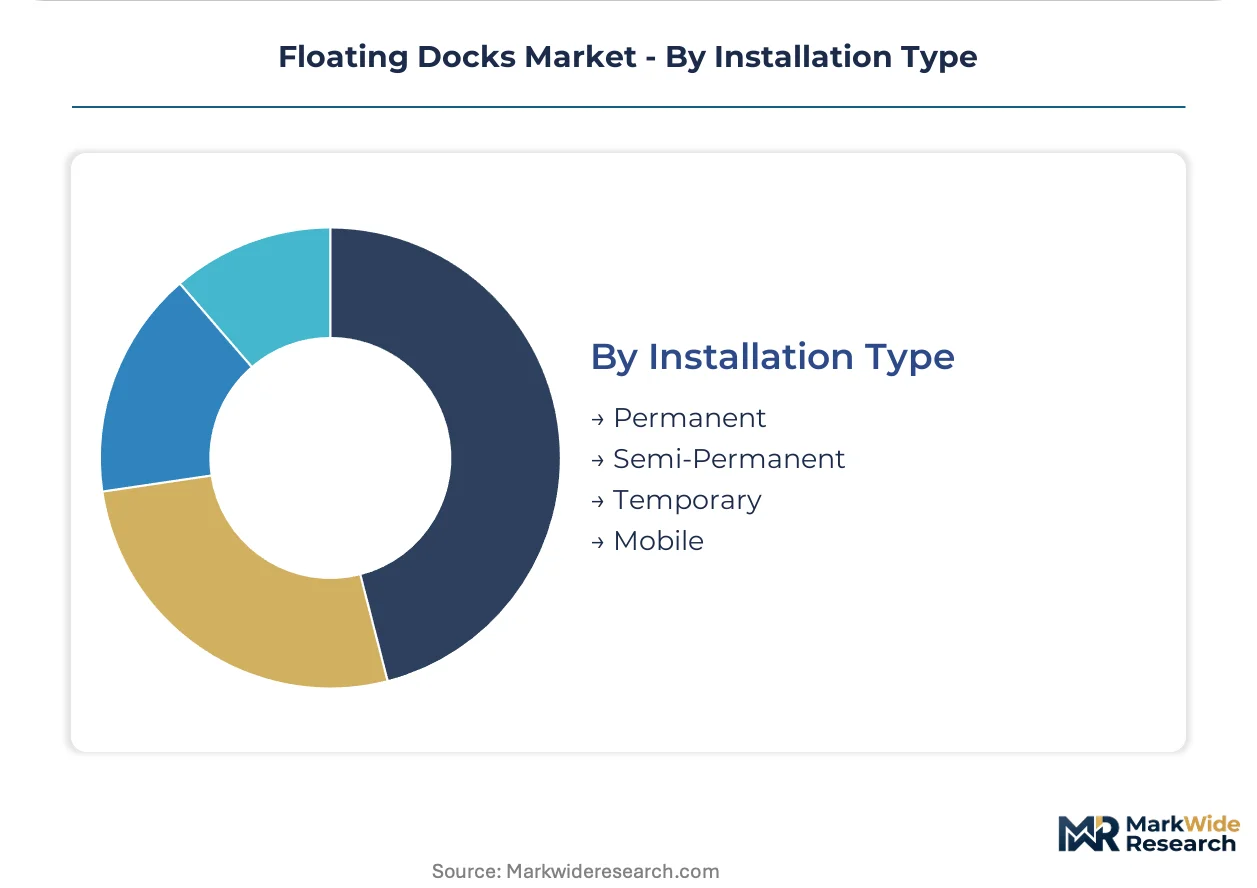
Material composition and installation permanence drive specification divergence across floating dock procurement. Procurement patterns split between capital-intensive permanent installations and flexible seasonal configurations.
Product Type:
Supply concentration in aluminum extrusion and rotational molding capacity shapes competitive dynamics across dock material categories.
- Modular Docks:Interconnecting HDPE or aluminum sections enable rapid reconfiguration for seasonal marinas and event-based waterfronts. Mediterranean marina operators in Spain and Italy specify these systems to compress installation windows during off-peak tourism months.
- Concrete Docks:Reinforced displacement hulls deliver fifty-year service life for permanent commercial and government installations. Precast production clusters in Italian and Greek facilities create geographic supply constraints for northern European projects requiring heavy-lift transport.
- Aluminum Docks:Lightweight extruded profiles reduce pile foundation requirements in deep-water configurations.
- Plastic Docks:Foam-filled polyethylene modules eliminate chemical treatments and enable tool-free assembly by recreational users.
Concrete docks absorb the bulk of installed capacity in permanent commercial installations; aluminum docks are expanding most quickly in deep-water marina configurations.
Application:
End-use economics separate high-frequency commercial operations from intermittent residential deployment.
- Marinas:Multi-berth commercial facilities demand load-rated systems with integrated utilities infrastructure. Greek and Croatian coastal developments are specifying aluminum-lithium alloy configurations to extend viable water depth ranges without heavy pile-driving equipment.
- Residential:Single-dock installations prioritize low-maintenance materials and seasonal removal capability. Great Lakes property managers are unbundling capital expenditure through lease-to-own arrangements that align payments with seasonal usage patterns.
- Commercial:Waterfront retail and hospitality operators require pedestrian-rated loadings with aesthetic finishing.
- Industrial:Cargo transfer facilities specify reinforced concrete or steel-composite systems for heavy equipment loading.
Marina applications command premium pricing through integrated service requirements; residential deployment shows steepest expansion trajectory in seasonal rental markets.
End User:
Procurement authority and budget structure determine specification tier and financing mechanism.
- Government:Public port authorities and military facilities mandate certified durability with multi-decade asset life. US Army Corps of Engineers permitting requirements favor established manufacturers with dedicated regulatory compliance capacity.
- Private Sector:Independent marina operators balance upfront capital constraints against operational uptime requirements.
- Recreational Users:Individual waterfront property owners prioritize tool-free installation and seasonal portability.
- Businesses:Corporate campus and hospitality developers integrate dock systems into broader amenity packages.
Government end users anchor demand for permanent concrete installations; private sector procurement is climbing the fastest as marina operators modernize aging infrastructure.
Installation Type:
Permanence expectations and climate adaptation requirements are redirecting specification toward relocatable configurations.
- Permanent:Pile-supported or anchored systems designed for twenty-plus year service life without major reconstruction. French and Italian regulatory authorities are enforcing elevated base flood elevation requirements that increase foundation costs.
- Semi-Permanent:Seasonally installed systems with annual removal and redeployment cycles. Nordic waterfront developers are bundling engineering and installation to compress project timelines.
- Temporary:Event-based configurations for regattas, concerts, and seasonal commercial activation.
- Mobile:Self-propelled or towable platforms for industrial logistics and emergency response.
Permanent installations retain the largest share of capital expenditure; semi-permanent systems are gaining share fastest as climate adaptation spending elevates flood-resilience requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Adriatic port cluster spanning Trieste to Dubrovnik anchors European floating dock procurement, where Croatian marina developments and Italian coastal infrastructure projects concentrate aluminum and concrete system demand.
United States
Great Lakes recreational waterfronts and Florida marina expansions drive seasonal dock installations. EPA Clean Water Act Section 404 permitting creates compliance complexity that favors established manufacturers with dedicated regulatory capacity. The Pacific Northwest timber-aluminum hybrid cluster supplies high-volume marina projects with certified sustainable materials.
Italy
Mediterranean marina operators in Liguria and Campania specify lightweight aluminum extrusions for deep-water pile-supported configurations. CE marking under the EU Construction Products Regulation streamlines type-approval alongside national maritime authority processes. Precast concrete displacement hull production concentrates in Apulian facilities serving permanent government installations.
Greece
Aegean and Ionian island developments accelerate adoption of modular dock systems for seasonal tourism infrastructure. EU Green Deal marine sustainability criteria reshape material specifications toward lower-carbon aluminum formulations. Athens-based engineering consultancies bundle design-build contracting for integrated waterfront projects.
Spain
Catalan and Valencian coastal municipalities redirect climate adaptation spending toward elevated dock configurations exceeding base flood elevation requirements. REACH restrictions on chromate conversion coatings eliminate traditional aluminum pretreatment processes. Barcelona-area fabricators migrate to trivalent chromium alternatives for marine-grade metal finishing.
Sweden
Fjord marina operators specify aluminum-lithium alloy extrusions to extend viable water depth ranges without heavy pile-driving equipment. Nordic waterfront developers bundle engineering, fabrication, and installation to compress project timelines. Gothenburg-based suppliers anchor integrated service capabilities across Baltic Sea developments.
Floating Docks Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material certification and regulatory compliance capabilities, with sustainable timber-aluminum hybrids and rotational-molded polyethylene systems commanding price premiums over untreated wood or standard concrete. The vendor base organizes into three strategic archetypes: integrated design-build contractors, modular system fabricators with rapid-installation IP, and commodity concrete pontoon producers. Dominant competitive moves include geographic expansion into Mediterranean marina developments and backward integration into recycled polymer feedstock sourcing.
Among North American fabricators, Bellingham Marine and EZ Dock exemplify divergent material strategies, with the former representing timber-aluminum hybrid specialists and the latter anchoring rotational-molded polyethylene modular systems. Marinetek occupies a position within the integrated design-build tier, bundling engineering and installation capabilities across Nordic and Baltic waterfronts. These three entities illustrate how competitive positioning fragments across material science specialization, regulatory compliance scale, and service integration depth rather than consolidating around uniform product architectures.
| Leading Market Players |
|---|
| Bellingham Marine |
| Marinetek |
| EZ Dock |
| Meeco Sullivan |
| Candock |
| AccuDock |
| Jet Dock Systems |
| SF Marina Systems |
| Brunswick Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between CE-marked aluminum extrusions and uncertified timber alternatives splits procurement budgets across European marina developments. This tier separation manifests in supply chain configurations where Italian and Greek precast facilities anchor premium concrete pontoon production while Nordic extrusion houses feed mid-market aluminum demand.
Pricing Analysis
Throughput-based value anchoring dominates marina operator procurement, with dock systems priced against berthing capacity and seasonal revenue potential. Three-tier pricing structure across premium certified, standard compliant, and economy ungraded levels tracks CE marking status and aluminum alloy grade. Cost compression in economy timber segments intensifies because untreated wood faces REACH chemical restriction phase-outs. Residential recreational buyers exhibit highest price sensitivity, while government port authorities absorb premium positioning for fifty-year service life specifications.
Supply Chain Analysis
End-of-life aluminum recovery and seasonal dock refurbishment flows are formalizing across Mediterranean rental fleets, creating secondary material circuits. Primary supply draws from Italian precast concrete facilities, Spanish aluminum extrusion plants, and Chinese rotational-molding equipment. Raw material dependencies center on primary aluminum ingot, high-density polyethylene resin, and marine-grade timber certified under FSC chain-of-custody. Single-source vulnerability concentrates in Mediterranean concrete hull production for northern European projects. Distribution runs through integrated design-build contractors in Nordic markets and independent marina distributors in North American recreational segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance narrative where EU Green Deal marine sustainability criteria erect regulatory moats favoring certified manufacturers with dedicated type-approval capacity.
For Market Incumbents: Anticipate REACH chemical restriction enforcement accelerating aluminum pretreatment process migrations. Defensive positioning demands backward integration into recycled polymer feedstock sourcing and captive aluminum-lithium alloy extrusion capacity. Threat vectors include modular polyethylene entrants from rotational-molding specialists and flood-resilience procurement shifts elevating relocatable system demand. For New Entrants and Emerging Players: Direct-to-marina digital specification platforms offer route-to-market entry points bypassing established distributor relationships. White-space targets concentrate in seasonal rental arrangements for Great Lakes recreational waterfronts and Adriatic marina service expansions. Most penetrable segment sits in semi-permanent HDPE configurations for climate adaptation spending in Spanish and Catalan coastal municipalities. For Investors and Strategic Acquirers: Re-rating potential sits with integrated design-build contractors given EU Green Deal circularity metrics favoring bundled engineering-fabrication-installation liability structures. Long-term viability over a multi-year horizon favors targets with CE marking capacity and national maritime authority relationships across France, Italy, and Germany. Signal to monitor: flood-resilience building code adoptions redirecting public procurement toward elevated dock configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Polymer Feedstocks | EU Green Deal circularity metrics reward post-consumer HDPE sourcing from European packaging waste streams. |
| Aluminum-Lithium Alloy Extrusion Capacity Addition | Norwegian fjord developers specify reduced-weight profiles to extend viable water depth ranges without heavy pile-driving equipment. |
| Integrated Design-Build Contracting Expansion | Nordic waterfront developers bundle engineering, fabrication, and installation to compress project timelines and transfer liability. |
| CE Marking and National Type-Approval Investment | French, German, and Italian maritime authority processes determine market access across European coastal zones. |
| Seasonal Rental and Lease-to-Own Model Development | Great Lakes and Northeast US markets unbundle capital expenditure from operational budgets for intermittent recreational users. |
Methodological Framework
Multi-period observation of marina construction permits, aluminum extrusion capacity utilization, and rotational-molding equipment shipments anchored the trend analysis, supplemented by interviews with dock system procurement managers at Mediterranean port authorities, Nordic waterfront engineering consultancies, and North American recreational marina operators. Secondary validation drew from EU Construction Products Regulation certification databases, US Army Corps of Engineers Section 404 permitting records, and customs trade data on aluminum alloy and HDPE resin imports. Bottom-up project pipeline tracking and top-down material consumption estimates were triangulated against manufacturer production disclosures.
Input-output matrix framing connected raw material throughput to installed dock capacity across product type, application, and installation permanence dimensions over the projection horizon. Segmentation modeling captured material composition splits, end-use economics, and procurement authority structures. CAGRs were derived from fitted growth curves applied to verified base-year volumes and value estimates, incorporating aluminum price elasticity parameters and climate adaptation spending trajectories as industry-specific forecast inputs.
The model holds under stable regulatory enforcement timelines for EU Green Deal marine infrastructure criteria; deviation in REACH restriction acceleration or flood-resilience code adoption would shift material specification trajectories and regional demand concentration. Practitioners should monitor national maritime authority type-approval backlog durations and primary aluminum smelting energy cost volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Crane Barge Market
Marine and Coastal Engineering
Work Barges Market
Marine and Coastal Engineering
Ship-To-Shore Cranes Market
Marine and Coastal Engineering
Marine Manifolds and Risers Market
Marine and Coastal Engineering
Mooring Compensators Market
Marine and Coastal Engineering
Marine Watertight Door Market
Marine and Coastal Engineering
STS (Ship-To-Shore) Cranes Market
Marine and Coastal Engineering
Ship Gangways Market
Marine and Coastal Engineering
Global Marine Ventilation Systems Market
Marine and Coastal Engineering
Saudi Arabia Mobile Sea Water Reverse Osmosis (SWRO) Treatment Plants Market
Marine and Coastal Engineering
Offshore Inspection, Repair, and Maintenance Market
Marine and Coastal Engineering
Dredging Market
Marine and Coastal Engineering
Seismic Support Vessels Market
Marine and Coastal Engineering
Global Pipe Laying Vessel Market
Marine and Coastal Engineering
Offshore Crane Market
Marine and Coastal Engineering
Offshore Pipeline Market