
 STS (Ship-To-Shore) Cranes Market | 2026-2036
STS (Ship-To-Shore) Cranes Market Size, Share, and Industry Trends Forecast 2026-2036
STS (Ship-To-Shore) Cranes Market Analytics
Super-post-Panamax lifting specifications is unwinding legacy fleet replacement cycles across major port authorities. ZPMC leverages integrated steel fabrication and quayside assembly to dominate newbuild deliveries for terminals in Asia and Europe. Liebherr-International AG sustains premium positioning through custom engineering for high-wind North Sea installations. Konecranes differentiates via software-integrated crane management platforms that reduce vessel turnaround times.
STS cranes are rail-mounted gantry systems designed to lift shipping containers between vessels and dockside transport, typically achieving outreach spans exceeding 70 meters and lift heights above 50 meters to service the largest container ships. Electromechanical drive systems now lead technology preferences due to energy recovery capabilities and reduced maintenance intervals versus hydraulic alternatives. Container terminals represent the dominant end-user category, with automation-ready semi-automated configurations capturing expanding capital allocation as labor costs rise and throughput guarantees tighten. Hybrid technology segments are gaining share where ports face carbon intensity mandates and grid reliability constraints.
FERC guidelines on port electrification infrastructure and the EU Green Deal emissions benchmarks shape North American and European procurement specifications, while China's MEE enforces domestic manufacturing environmental compliance that filters into export equipment standards. ISO 4301-1 crane classification and CE marking requirements create tiered market access barriers that favor established builders with certification depth. Stakeholders must monitor regulatory divergence between carbon-border mechanisms and local content rules when sizing regional manufacturing footprints.
Market Dynamics
Ultra-large container vessel deployment is compressing crane replacement cycles as port authorities race to match quayside lifting specifications. Terminal operators face simultaneous pressure from carbon intensity mandates and throughput guarantees that favor automated, electromechanical systems over legacy hydraulic fleets.
Growth Catalysts
- EU F-Gas Regulation:Terminal operators across Rotterdam and Hamburg accelerate hybrid crane procurement to meet phasedown timelines for high-global-warming-potential refrigerants in onboard HVAC systems.
- Container vessel upsizing:24,000 TEU newbuilds entering service on Asia-Europe routes force berth-depth and outreach upgrades at Singapore, Busan, and Colombo terminals.
- Electromechanical drive recovery:Regenerative braking systems cut energy consumption by capturing hoist-descent kinetic energy, shortening payback periods for automation investments.
Market Restraints
- Steel price volatility:High-strength quenched and tempered plate for boom fabrication exposes builders to input cost swings that compress tender margins.
- Supply concentration in East Asia:ZPMC and three domestic competitors control over 80% of structural steel fabrication capacity, creating single-source risk for European and Middle Eastern buyers.
- Grid reliability constraints:Ports in Southeast Asia and Sub-Saharan Africa lack shore-power infrastructure to support full electrification, forcing continued diesel-hybrid dependence.
Strategic Opportunities
- India port privatization:Adani Ports and JSW Infrastructure are expanding container terminals at Mundra, Hazira, and Ennore, creating demand for 16+ new STS units annually through 2030.
- Remote operator stations:5G-enabled crane management platforms allow centralized control of multiple berths, reducing labor costs and enabling 24-hour operations in high-wage markets.
- EU Green Deal carbon border adjustments:Import tariffs on carbon-intensive steel incentivize European terminal operators to source cranes from builders with verified low-carbon fabrication processes.
Industry Challenges
- Automation systems integration:Terminal operating systems from Navis and TBA must interface with crane PLC architectures, creating commissioning delays and interoperability failures.
- Certification timeline compression:ISO 4301-1 classification and CE marking for modified crane configurations add 8-14 months to delivery schedules, misaligning with vessel deployment windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | STS (Ship-To-Shore) Cranes Market |
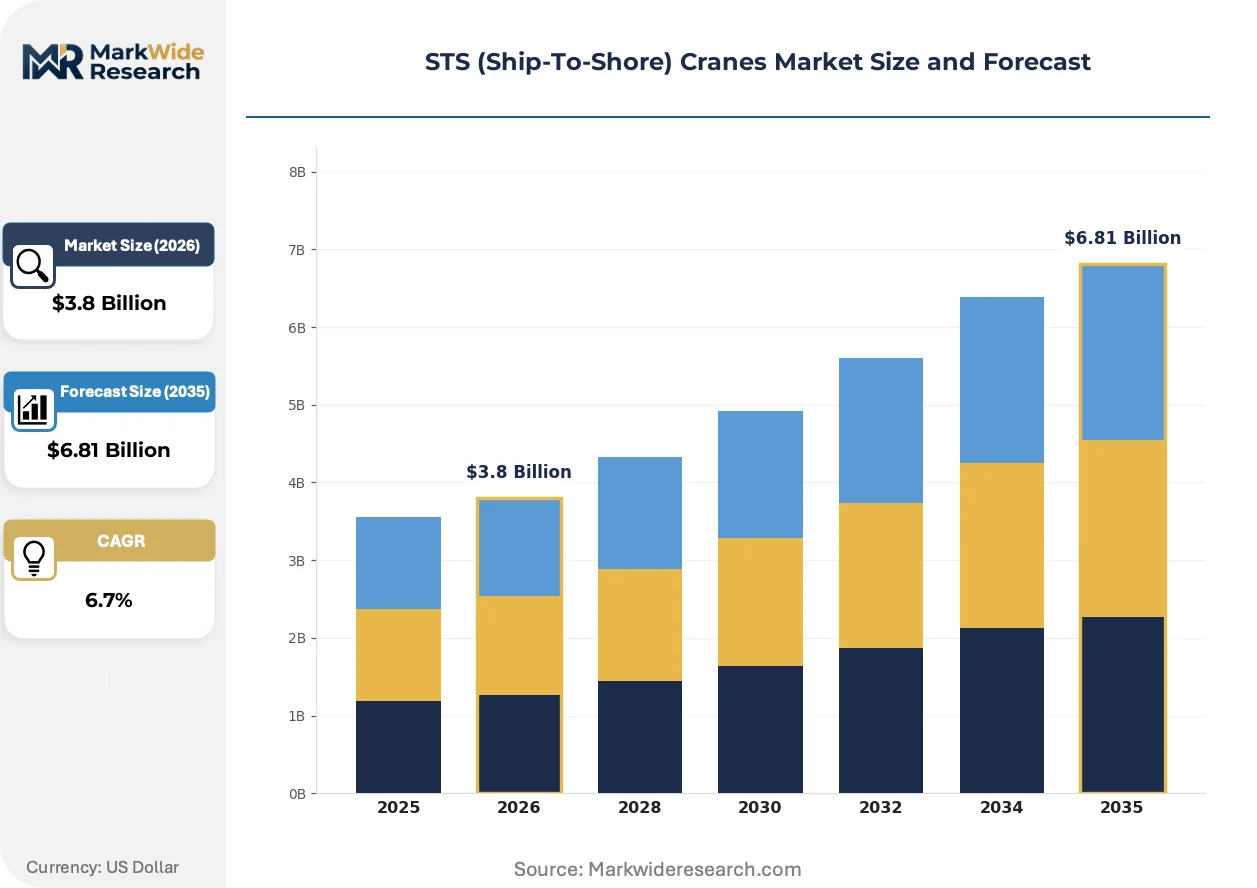
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Mobile, Fixed, Semi-automated Deployment Type: Onshore, Offshore, Compact, Standard End User: Container Terminals, Shipping Lines, Logistics Providers, Freight Forwarders Technology: Electromechanical, Hydraulic, Pneumatic, Hybrid |
| Companies Covered | Shanghai Zhenhua Heavy Industries Co., Ltd. (ZPMC), Liebherr-International AG, Sany Group, Cargotec (Kalmar), Konecranes, PACECO CORP., Doosan Corporation, ANUPAM-MHI Industries Limited, HD Hyundai Samho Heavy Industries Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
STS (Ship-To-Shore) Cranes Market Evolving Landscape
Quayside automation is splitting crane procurement into two distinct performance tiers as terminal operators weigh throughput guarantees against capital constraints. Technology choices now hinge on labor cost differentials and grid reliability rather than vessel size alone.
Electromechanical hoist machinery is bifurcating the installed base. Regenerative AC drive systems recover descent energy while cutting maintenance intervals versus wound-rotor motor alternatives. Automated terminals in Rotterdam and Qingdao specify full electromechanical configurations, while hybrid ports in Jakarta and Lagos retain hydraulic auxiliaries for grid-independent operations. This split is compressing the addressable market for pure hydraulic crane builders.
The EU Green Deal emissions benchmarks and F-Gas Regulation are forcing terminal operators to document lifecycle carbon intensity. Builders must now provide environmental product declarations covering steel sourcing, fabrication energy, and shipping emissions. European port authorities in Antwerp and Barcelona have embedded these requirements into tender evaluation criteria, disadvantaging suppliers without certified supply chain traceability.
Long-term service contracts are displacing traditional spare-parts procurement. Terminal operators at Singapore PSA and Dubai DP World now purchase availability guarantees rather than component inventories. Crane builders retain ownership of critical spares and charge per lift or per vessel call. This shift concentrates aftermarket revenue with OEMs while reducing working capital burdens for port operators in high-throughput environments.
STS (Ship-To-Shore) Cranes Market Segmentation
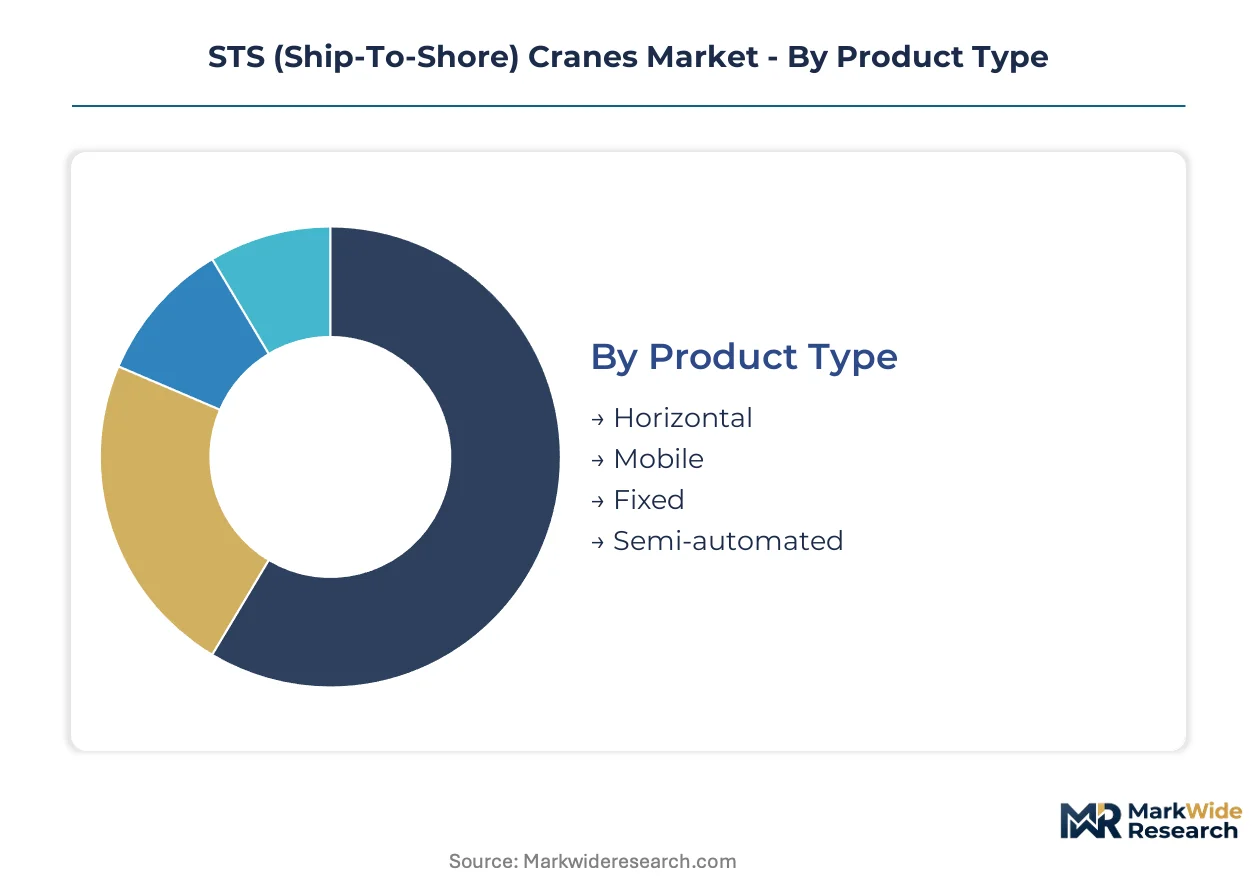
STS crane procurement splits sharply across automation readiness and powertrain architecture. Terminal operators weigh capital efficiency against throughput guarantees when selecting configurations. Each segmentation axis reveals distinct margin pools and vendor positioning strategies.
Product Type:
Margin pools concentrate in automation-capable configurations where software integration commands pricing premiums over structural steel commodity value.
- Semi-automated:Combines manual oversight with PLC-controlled hoisting and trolley positioning. Container terminals at Rotterdam and Singapore specify these units to reduce labor costs while retaining human intervention for exception handling. Demand is climbing fastest as mid-tier ports balance automation investment against operational risk.
- Fixed:Rail-mounted gantry systems with permanent foundation anchoring dominate greenfield terminal builds. Chinese port modernization programs at Ningbo and Xiamen anchor procurement volume for this segment.
- Horizontal:Specialized cantilever designs for narrow berth constraints at legacy European ports.
- Mobile:Rubber-tired variants for multi-berth flexibility at smaller container facilities.
Fixed holds installed capacity. Semi-automated is rotating up the share rankings.
Deployment Type:
Volume concentrates in standard quayside configurations, though compact designs are gaining traction at space-constrained Asian hub terminals.
- Standard:Full-specification rail-mounted systems with 70+ meter outreach and 50+ meter lift height. Busan and Colombo terminal expansions specify these units to handle 24,000 TEU vessel classes. Procurement is expanding most quickly where berth-depth upgrades accompany crane replacement cycles.
- Onshore:Conventional dockside installations at established container terminals. Adani Ports at Mundra and Hazira in India drive regional demand for this configuration.
- Offshore:Heavy-lift variants for floating cargo handling at remote logistics hubs.
- Compact:Reduced-footprint units for secondary ports with limited quay length.
Standard dominates current order books. Compact is climbing the fastest as Asian port densification accelerates.
End User:
Customer type dictates financing structures and service contract terms, with container terminal operators capturing the deepest vendor relationships.
- Container Terminals:Dedicated quayside operators at PSA Singapore and DP World Dubai purchase availability-based service contracts rather than component spares. These buyers specify electromechanical systems with regenerative braking to meet carbon intensity benchmarks under EU Green Deal frameworks.
- Shipping Lines:Maersk and MSC operate captive terminal facilities requiring fleet-standardized crane specifications.
- Logistics Providers:DHL Supply Chain and Kuehne+Nagel contract for dedicated berth capacity at multi-user terminals.
- Freight Forwarders:Smaller volume purchasers relying on terminal operator crane access rather than direct procurement.
Container Terminals command vendor attention. Logistics Providers are expanding their direct procurement footprint.
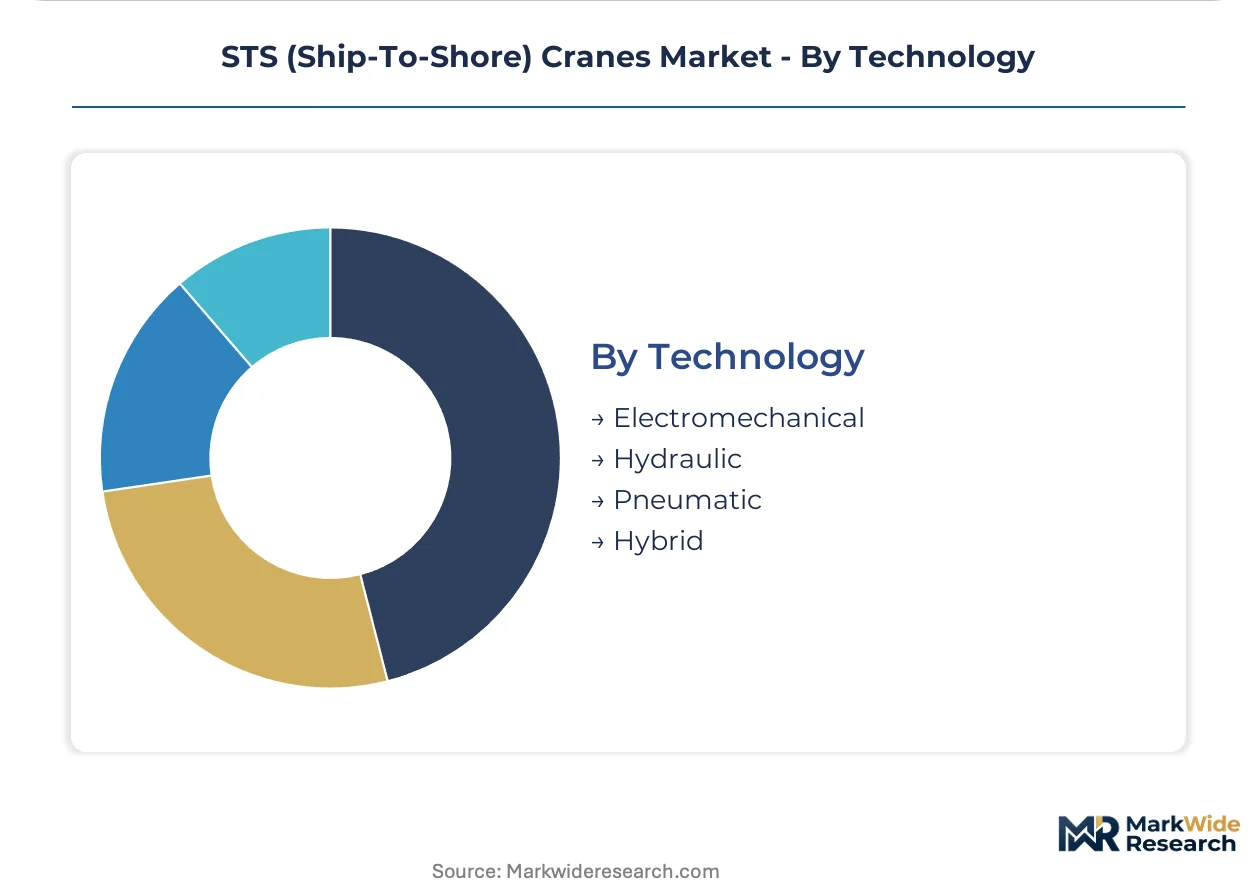
Technology:
Powertrain selection now hinges on grid reliability and carbon accounting rather than lift capacity alone.
- Electromechanical:AC regenerative drive systems capture hoist-descent kinetic energy, cutting energy consumption and maintenance intervals versus hydraulic alternatives. Rotterdam and Qingdao terminals specify full electromechanical configurations to satisfy EU F-Gas Regulation and China's MEE compliance requirements.
- Hybrid:Diesel-electric systems with battery buffering for grid-independent operations. Jakarta and Lagos ports retain these configurations where shore-power infrastructure remains underdeveloped.
- Hydraulic:Legacy wound-rotor motor systems facing replacement pressure from energy recovery mandates.
- Pneumatic:Niche auxiliary power for specific lifting applications in hazardous cargo handling.
Electromechanical holds technology leadership. Hybrid is gaining share fastest where grid constraints persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Structural steel fabrication capacity concentrates heavily in East Asia, with Chinese builders supplying over four-fifths of newbuild deliveries to terminals worldwide. This geographic clustering shapes procurement risk profiles and carbon accounting methodologies across import-dependent regions.
China
Shanghai Zhenhua Heavy Industries anchors domestic manufacturing through integrated steel fabrication and quayside assembly operations. The Ministry of Ecology and Environment enforces environmental compliance standards that filter into export equipment specifications. Ningbo and Xiamen container terminals drive procurement volume through port modernization programs handling ultra-large vessel classes.
Germany
Terminal operators at Hamburg and Bremerhaven accelerate hybrid crane procurement to meet EU F-Gas Regulation phasedown timelines for high-global-warming-potential refrigerants. The EU Green Deal carbon border adjustment mechanism incentivizes sourcing from verified low-carbon fabrication processes. North Sea installations demand custom engineering for high-wind conditions, sustaining premium-tier vendor relationships.
India
Adani Ports and JSW Infrastructure expand container terminals at Mundra, Hazira, and Ennore, creating demand for sixteen-plus new STS units annually through 2030. The Central Electricity Authority guidelines on port electrification infrastructure shape procurement specifications for grid-connected systems. Gujarat and Tamil Nadu industrial corridors concentrate greenfield terminal development with dedicated berth capacity.
Singapore
PSA Singapore purchases availability-based service contracts rather than component spares, concentrating aftermarket revenue with original equipment manufacturers. The Maritime and Port Authority enforces emissions benchmarks aligned with EU Green Deal frameworks. Tuas Mega Port automation programs specify electromechanical systems with regenerative braking to meet carbon intensity mandates.
United States
FERC guidelines on port electrification infrastructure shape procurement specifications for North American terminal operators. Long Beach and Los Angeles port complexes face simultaneous pressure from California Air Resources Board emissions rules and vessel deployment windows. Pacific Southwest terminals balance automation investment against grid reliability constraints and shore-power infrastructure gaps.
STS (Ship-To-Shore) Cranes Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure with limited overlap between premium engineering and scale fabrication. The vendor base separates into three strategic groupings: integrated steel fabricators with captive supply chains, electromechanical specialists with software-integrated platforms, and regional builders serving protected domestic markets. Competitive moves concentrate on vertical integration into high-strength steel plate sourcing and long-term service contract structures that displace traditional spare-parts procurement.
Among Asian fabricators, Shanghai Zhenhua Heavy Industries Co., Ltd. occupies a position exemplifying scale-driven manufacturing archetypes. Liebherr-International AG represents the premium engineering tier focused on custom configurations. Konecranes sits within the technology-integrated segment, anchoring software-centric competitive positioning.
| Leading Market Players |
|---|
| Shanghai Zhenhua Heavy Industries Co., Ltd. (ZPMC) |
| Liebherr-International AG |
| Sany Group |
| Cargotec (Kalmar) |
| Konecranes |
| PACECO CORP. |
| Doosan Corporation |
| ANUPAM-MHI Industries Limited |
| HD Hyundai Samho Heavy Industries Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Integrated steel fabrication at ZPMC's Shanghai facilities generates capacity-utilization advantages that compress price floors for standard rail-mounted configurations while elevating entry barriers for European and Middle Eastern buyers lacking captive quayside assembly operations.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across European procurement, with hybrid electromechanical systems commanding premiums over legacy hydraulic fleets due to compliance-driven specification shifts. Price differentiation rests on ISO 4301-1 certification grade and after-sales service bundling, with Rotterdam and Hamburg terminal operators least sensitive to upfront capital outlays. Cost compression in standard fixed configurations is intensifying because ZPMC's integrated steel sourcing undercuts tender margins for regional builders. Small freight forwarders and secondary port operators in Southeast Asia exhibit highest price sensitivity, deferring replacement cycles where grid reliability constraints already favor lower-cost hybrid units.
Supply Chain Analysis
China and South Korea anchor structural steel fabrication for boom assemblies and quayside gantry systems, with high-strength quenched and tempered plate drawing from integrated mills at Ningbo and Pohang. Raw material dependencies center on specialized steel grades, copper windings for AC regenerative drives, and precision bearings for trolley positioning systems. Single-source vulnerability concentrates in East Asian plate rolling capacity, where four producers control over four-fifths of export-grade supply. Distribution runs through direct terminal operator contracts with extended commissioning and availability-based service attachments displacing traditional component spare parts procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
STS crane procurement is shifting toward platform-economics dynamics where terminal operating systems from Navis and TBA must interoperate with crane PLC architectures, creating winner-take-most positioning for builders with certified software integration capabilities.
For Market Incumbents: Consolidate backward integration into high-strength steel plate sourcing to defend margins against ZPMC's captive supply advantages. Deepen certification depth for EU Green Deal carbon border adjustments, as Antwerp and Barcelona authorities now embed environmental product declarations into tender evaluation criteria. Prioritize long-term service contract structures that displace traditional spare-parts procurement, mirroring PSA Singapore's availability-guarantee purchasing model.
For New Entrants and Emerging Players: CE marking fast-track programs for modified crane configurations offer penetration pathways where ISO 4301-1 classification timelines currently disadvantage unestablished builders. Target India's port privatization wave at Mundra, Hazira, and Ennore, where Adani Ports and JSW Infrastructure demand sixteen-plus units annually and procurement specifications remain less prescriptive than European frameworks. Lead with 5G-enabled remote operator stations as a differentiated go-to-market angle for high-wage markets seeking labor cost reduction.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electromechanical specialists with software-integrated crane management platforms over pure structural fabricators facing commodity steel price volatility. Long-term viability over a five-to-ten year window rests on automation systems integration capabilities and verified low-carbon supply chain traceability. Acquisition targets should exhibit certified environmental product declarations and established relationships with terminal operators at Rotterdam, Singapore, or Qingdao. The signal to watch is FERC guideline expansion on port electrification infrastructure, which would accelerate grid-connected system deployment and disadvantage hybrid-dependent builders.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Plate Sourcing | ZPMC's captive supply of quenched and tempered plate compresses competitor tender margins at Ningbo and Xiamen terminals. |
| Software Platform Certification Investment | Navis and TBA interoperability testing reduces commissioning delays that currently misalign with vessel deployment windows. |
| Long-term Service Contract Structures | Availability guarantees at PSA Singapore and DP World Dubai concentrate aftermarket revenue with OEMs while reducing operator working capital. |
| CE Marking Fast-track Programs | Accelerated certification timelines address the 8-14 month delivery schedule compression that disadvantages modified crane configurations. |
| 5G Remote Operator Station Deployment | Centralized multi-berth control enables 24-hour operations at Rotterdam and Hamburg where labor costs drive automation investment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, port authority procurement disclosures, and builder SEC filings. Terminal operations directors, crane maintenance heads at PSA Singapore and DP World Dubai, OEM procurement teams at ZPMC and Liebherr, and aftermarket service managers contributed structured interviews. Secondary validation drew from EU F-Gas Regulation implementation reports, China MEE environmental compliance filings, and ISO 4301-1 classification documentation. Bottom-up unit demand estimates from terminal expansion projects were triangulated against top-down market value assessments across the analysis window.
Segmentation dimensions modeled span automation readiness, powertrain architecture, deployment type, and end-user category with regional regulatory cluster overlays. Volume and value outputs were derived through installed base replacement cycle analysis, berth-depth upgrade pipelines, and carbon intensity mandate compliance trajectories over the projection horizon. CAGRs reflect convergence of historical procurement patterns, vessel upsizing timelines, and electrification infrastructure buildout schedules. Industry-specific forecast inputs include 24,000 TEU vessel deployment routes and shore-power grid reliability indices for Southeast Asian and Sub-Saharan African ports.
Decision-makers should treat outputs as directional under base assumptions of continued EU Green Deal enforcement and China MEE export standard alignment; material deviation in regulatory divergence or steel price volatility would warrant model refresh. Specific risks include automation systems integration failures, certification timeline compression beyond current 8-14 month baselines, and grid infrastructure gaps that perpetuate diesel-hybrid dependence. Recalibration cycles align with material shifts in FERC guideline expansion, carbon border adjustment mechanism implementation, and ultra-large container vessel orderbook deliveries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Asia-Pacific Offshore Crane Market
Marine and Coastal Engineering
Seismic Support Vessels Market
Marine and Coastal Engineering
Offshore Inspection, Repair, and Maintenance Market
Marine and Coastal Engineering
Mooring Bollards Market
Marine and Coastal Engineering
Work Barges Market
Marine and Coastal Engineering
Marine Cranes Market
Marine and Coastal Engineering
Global Seismic Vessels Market
Marine and Coastal Engineering
Global Pipe Laying Vessel Market
Marine and Coastal Engineering
Marine Hawser Market
Marine and Coastal Engineering
Middle East Offshore Crane Market
Marine and Coastal Engineering
Marine Manifolds and Risers Market
Marine and Coastal Engineering
Underwater Concrete Market
Marine and Coastal Engineering
Floating Docks Market
Marine and Coastal Engineering
Bilge Pump Market
Marine and Coastal Engineering
Global Marine and Dock Gangways Market
Marine and Coastal Engineering
Offshore Crane Market