
 Marine Watertight Door Market | 2026-2036
Marine Watertight Door Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Watertight Door Market Analytics
Shipyard-direct procurement channels is reconfiguring as naval and commercial vessel builders consolidate supplier lists around certified manufacturers. Speed-Horse Marine leverages its coastal China manufacturing base to dominate regional supply for standard steel door variants. ACIR Marine differentiates through specialized aluminum and composite door systems for yacht and patrol craft segments. Deansteel Manufacturing Company anchors North American demand with heavy-duty steel doors engineered for military and ice-class commercial specifications.
Marine watertight doors are pressure-rated closures engineered to prevent progressive flooding between compartments, typically constructed from steel or aluminum with rubber gasket seals and dogging mechanisms tested to SOLAS and classification society standards. These assemblies maintain vessel subdivision integrity during hull breach events, directly preserving buoyancy margins and crew safety. Single leaf configurations occupy the largest installed base across commercial fleets due to simpler maintenance and lower weight penalties, while composite material doors represent the fastest-expanding segment as ship operators pursue fuel efficiency through topside weight reduction. Military ships and submarines concentrate the highest-margin procurement pools, where electromagnetic signature control and blast resistance specifications command premium engineering.
The International Maritime Organization's SOLAS Convention, enforced by flag-state administrations and classification societies including Lloyd's Register and DNV, mandates watertight door testing protocols and maintenance logging that shape product design cycles and aftermarket service revenue. The EU's MDR and CE marking frameworks apply to door control and monitoring systems integrated into passenger vessel automation architectures. Stakeholders must monitor classification society rule harmonization around remote monitoring and predictive maintenance capabilities as regulatory pressure shifts from prescriptive testing toward continuous operational assurance models.
Market Dynamics
Naval modernization programs and SOLAS subdivision amendments are compressing supplier qualification timelines while concentrating procurement around certified manufacturers with integrated testing capabilities.
Growth Catalysts
- IMO SOLAS Chapter II-1 amendments:Tightened damage stability requirements for passenger vessels mandate upgraded watertight door assemblies with enhanced remote monitoring capabilities.
- East Asian shipyard clustering:Ulsan and Geoje in South Korea generate concentrated demand for certified door systems through naval frigate and LNG carrier construction programs.
- Composite material substitution:Aluminum and fiber-reinforced polymer doors reduce topside weight by 40-60% versus steel equivalents, directly improving vessel fuel efficiency metrics.
Market Restraints
- Specialized steel alloy volatility:Marine-grade AH36 and DH36 plate prices fluctuate with scrap metal and nickel markets, compressing margins for steel door fabricators.
- Korean classification society concentration:Korean Register and DNV Korea dominate certification pathways, creating bottleneck risk for non-Korean suppliers seeking naval contracts.
- Hydraulic actuator lead times:Precision-machined dogging mechanisms require 16-20 week procurement cycles from European and Japanese specialty component houses.
Strategic Opportunities
- Indonesian archipelago ferry replacement:Domestic short-sea passenger fleet renewal creates demand for cost-optimized single-leaf doors meeting simplified SOLAS compliance tiers.
- EU MDR convergence with maritime automation:Medical device regulation alignment for integrated door monitoring systems opens service contract bundling for European passenger vessel operators.
- Predictive maintenance sensor integration:IoT-enabled gasket wear detection and dogging force analytics enable shift from periodic inspection to condition-based service models.
Industry Challenges
- Welding certification scarcity:Qualified aluminum TIG welders for marine pressure-boundary applications command 35-50% wage premiums in shipyard clusters.
- Legacy vessel retrofit compatibility:Pre-2000 hulls with non-standard frame spacing require custom door fabrication rather than catalog standard products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Watertight Door Market |
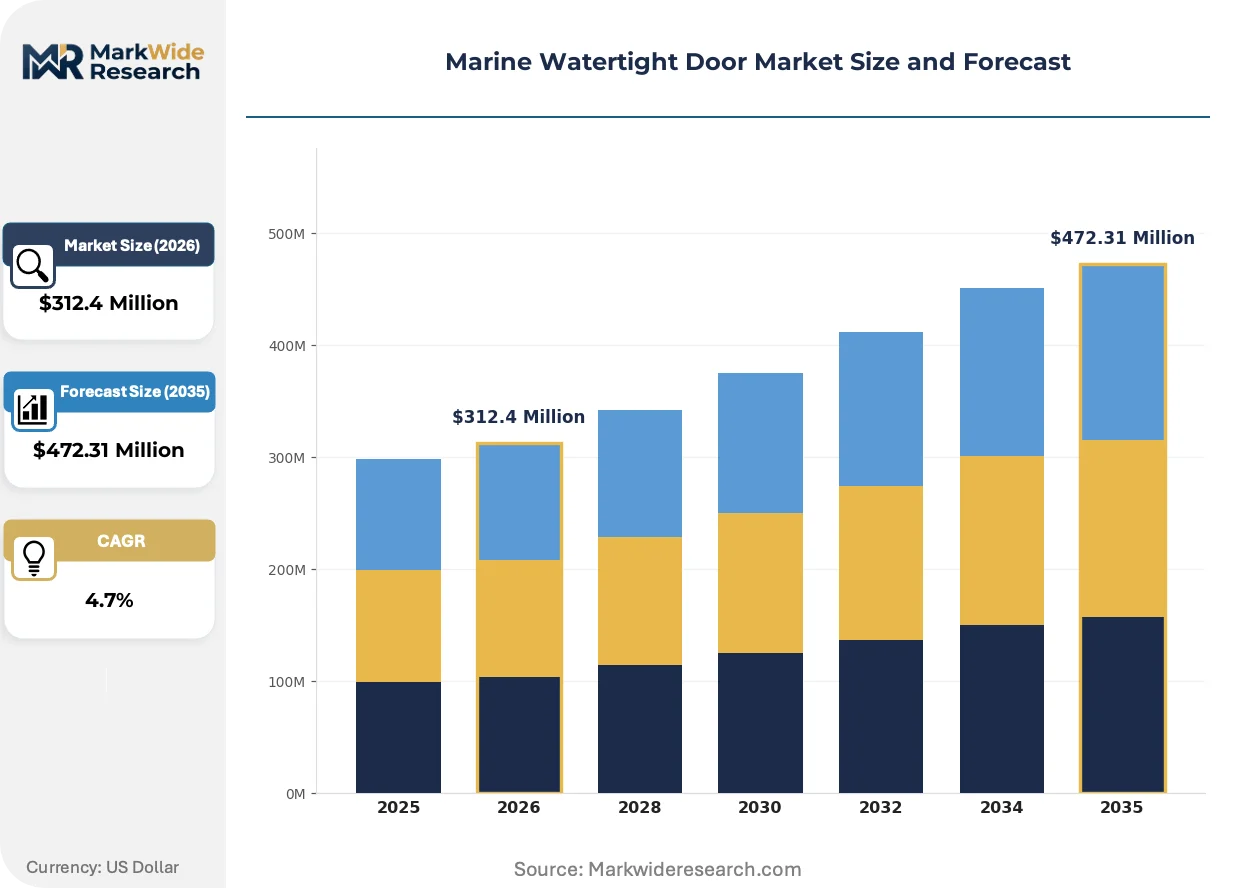
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Leaf, Double Leaf, Folding, Sliding Material: Aluminum, Steel, Composite, Fiberglass Installation Type: Onboard, Offshore, Modular, Custom Application: Commercial Vessels, Military Ships, Yachts, Submarines |
| Companies Covered | Railway Specialties Corporation, Speed-Horse Marine, OUCO Industry, Jinbo Marine, Deansteel Manufacturing Company, Hi-Sea Group, ACIR Marine, AdvanTec Marine, IMS Groups, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Watertight Door Market Evolving Landscape
Remote monitoring capabilities and lightweight material substitution are restructuring competitive advantage around integrated system suppliers rather than component fabricators.
Electro-hydraulic door control systems is migrating from centralized machinery spaces to distributed local actuator networks. Offshore supply vessel operators and ice-class cargo fleets are adopting decentralized architectures to reduce piping weight and failure points. This migration from centralized to edge-computing control topologies compresses installation labor hours by 25-30% while enabling faster fault isolation.
Classification society harmonization around IACS UR Z17 service supplier requirements is tightening third-party maintenance provider qualification standards. Lloyd's Register and DNV now mandate annual witness testing for firms performing watertight door seal replacements. Commercial ferry operators in the Mediterranean and Baltic routes are consolidating service contracts with fewer, fully certified providers to reduce audit burden.
Shipyard-direct specification authority is consolidating procurement decisions at the vessel design stage rather than through owner-furnished equipment channels. Naval architects at Hyundai Heavy Industries and Daewoo Shipbuilding are embedding door performance specifications into hull structural drawings before contract award. This shift compresses supplier negotiation windows while favoring manufacturers with early-stage engineering collaboration capabilities.
Marine Watertight Door Market Segmentation
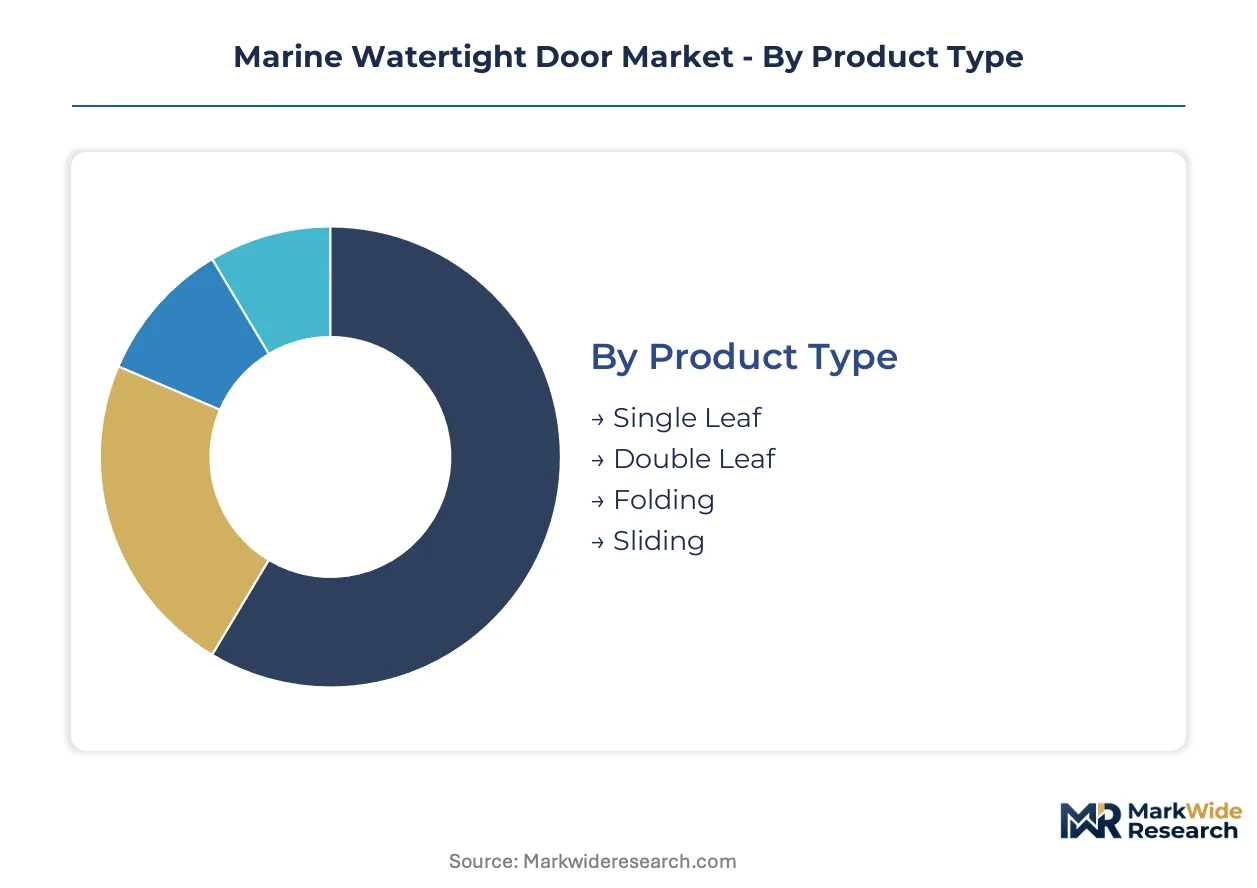
Watertight door procurement patterns diverge sharply across vessel architectures and operational profiles. Material selection and installation approach directly determine compliance pathways, lifecycle costs, and supplier qualification requirements for shipyard procurement teams.
Product Type:
Cost tier differentiation separates standardized catalog offerings from engineered-to-order pressure boundary systems.
- Single Leaf:These unidirectional hinged closures with single-point dogging mechanisms dominate commercial fleet specifications due to reduced maintenance complexity and lower weight penalties. Container ships and bulk carriers operating out of Ulsan and Geoje shipyards specify these for machinery space boundaries where access frequency remains moderate.
- Double Leaf:Bi-parting configurations with centerline sealing interfaces accommodate wider compartment openings in cruise vessels and naval auxiliaries. Mediterranean ferry operators favor these for passenger embarkation zones where corridor widths exceed 1.2 meters and SOLAS crowd flow requirements apply.
- Folding:Accordion-style multi-panel systems retract against bulkhead surfaces to maximize clear opening width in constrained machinery spaces.
- Sliding:Horizontal or vertical translation mechanisms serve submarine pressure hull applications where swing radius constraints eliminate hinged alternatives.
Single Leaf commands the established base. The steepest expansion runs through Double Leaf configurations.
Material:
Application severity and topside weight budgets drive material selection trade-offs between structural integrity and fuel efficiency gains.
- Steel:Marine-grade AH36 and DH36 plate constructions deliver blast resistance and electromagnetic signature control for naval combatants. Korean naval frigate programs specify these for damage stability-critical boundaries where projectile penetration resistance outweighs mass penalties.
- Composite:Fiber-reinforced polymer and aluminum hybrid assemblies reduce topside weight by 40-60% versus steel equivalents. Offshore supply vessel operators in the North Sea specify these for superstructure watertight boundaries to improve seakeeping stability and reduce fuel consumption.
- Aluminum:Extruded and welded 5083-H116 configurations serve patrol craft and fast ferry segments where corrosion resistance and moderate strength-to-weight ratios balance procurement cost against performance.
- Fiberglass:Glass-reinforced plastic molded doors address yacht and small commercial craft applications where aesthetic finish requirements and magnetic signature minimization take priority over pressure rating.
Steel retains the dominant installed base across military and ice-class commercial fleets. Composite materials are gaining share fastest in fuel-efficiency-focused segments.
Installation Type:
Customer capability and vessel construction phase determine whether doors ship as finished assemblies or field-integrated components.
- Onboard:Final installation at outfitting piers accommodates last-minute specification changes and hull tolerance adjustments. This approach dominates repair and conversion markets where existing frame openings require dimensional verification before door fabrication.
- Modular:Pre-assembled door and frame units with integrated sealing systems reduce shipyard labor hours and improve quality consistency. Hyundai Heavy Industries and Daewoo Shipbuilding specify these for series-built LNG carriers where production line efficiency demands minimize pier-side work content.
- Offshore:Floating production platform and subsea habitat applications require pressure-rated doors installed at quayside or in sheltered waters rather than drydock environments.
- Custom:Non-standard frame spacing and unusual opening geometries in legacy vessel retrofits demand bespoke fabrication against measured hull dimensions.
Onboard installation commands the established base. The steepest expansion runs through Modular approaches.
Application:
End-use operational profiles create divergent specification hierarchies around pressure rating, cycle frequency, and regulatory scrutiny intensity.
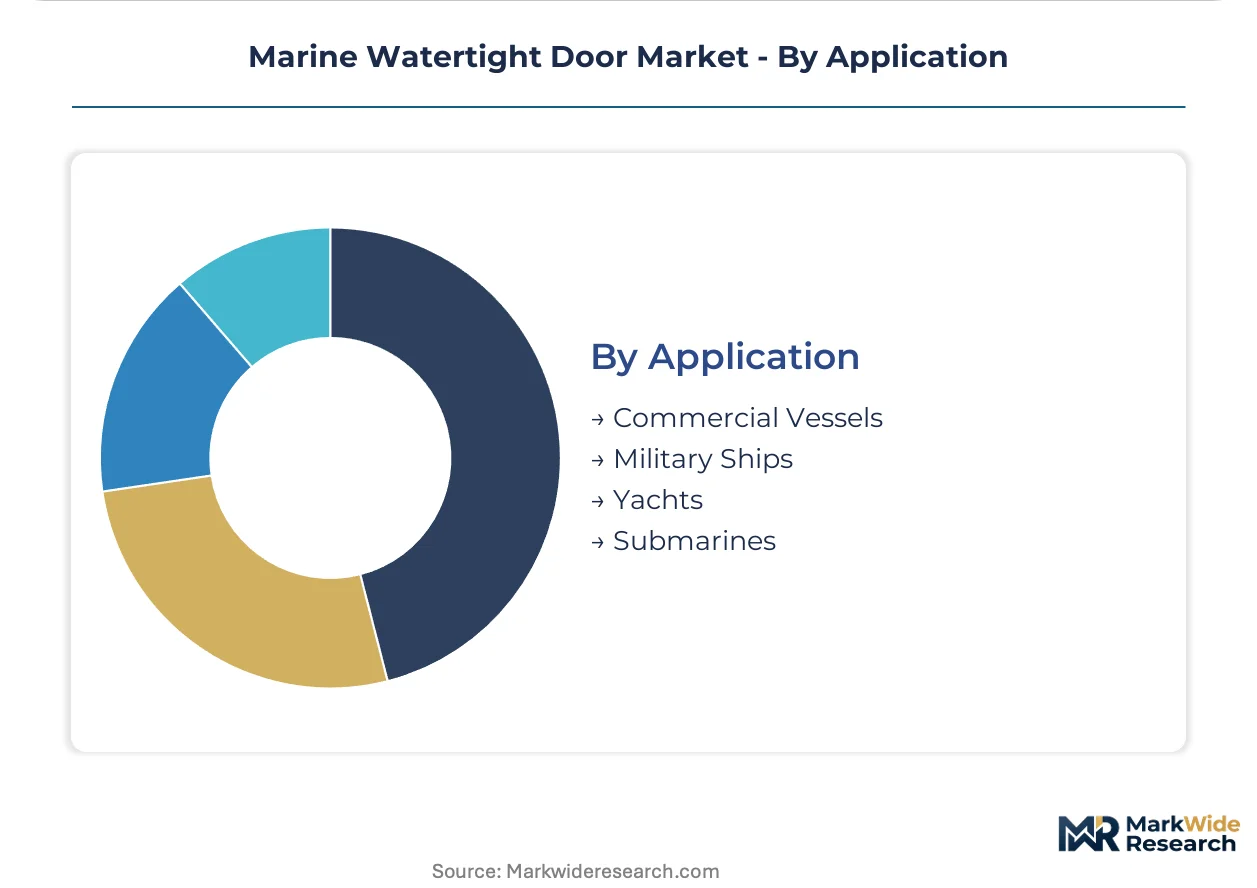
- Commercial Vessels:Container ships, bulk carriers, and tankers drive volume procurement of SOLAS-compliant single-leaf steel doors with standardized 0.25 N/mm² pressure ratings. Classification society type approval and mass production economies dominate supplier selection criteria for this segment.
- Military Ships:Naval surface combatants concentrate premium engineering requirements around blast resistance, electromagnetic compatibility, and shock qualification. These specifications command extended development cycles and captive supply relationships with defense-prime system integrators.
- Yachts:Superyacht newbuild programs in Northern Italy and the Netherlands specify aluminum and composite doors where interior design integration and quiet operation outweigh cost minimization priorities.
- Submarines:Pressure hull boundary applications demand circular or elliptical steel doors tested to depths exceeding 300 meters, with specialized locking mechanisms and materials traceability documentation exceeding commercial maritime standards.
Commercial Vessels commands the established base. The steepest expansion runs through Military Ships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SOLAS subdivision amendments and naval shipbuilding incentives are redistributing procurement volumes toward East Asian manufacturing clusters and North American defense yards. Shipyard certification requirements now favor suppliers with integrated testing capabilities located within 500 kilometers of major construction sites.
South Korea
Naval frigate and LNG carrier programs at DSME and Hyundai Heavy Industries drive concentrated demand for certified steel door systems. Korean Register mandates annual witness testing for seal replacement contractors, tightening supplier qualification standards. Ulsan and Geoje shipyards account for the majority of regional procurement volume through consolidated supplier lists.
China
Coastal manufacturing bases supply standardized steel door variants to domestic and export shipyards under GB standards alignment with SOLAS. MIIT shipbuilding subsidies support yard modernization programs requiring upgraded watertight boundary systems. Qingdao and Shanghai clusters host fabricators serving both commercial vessel newbuilds and conversion markets.
United States
Navy LPD and FFG programs sustain demand for blast-resistant steel doors with electromagnetic signature control specifications. OSHA maritime safety enforcement and USCG flag-state administration shape maintenance logging requirements for commercial fleets. Gulf Coast shipyards in Louisiana and Mississippi concentrate military and offshore supply vessel procurement.
Japan
METI maritime industry support programs fund development of lightweight aluminum door systems for coastal ferry fleets. JIS standards harmonization with IACS rules simplifies export certification for domestic manufacturers. Nagoya and Kobe industrial corridors maintain specialized fabricators serving patrol craft and fast ferry segments.
Germany
EU MDR convergence with maritime automation standards creates service contract opportunities for integrated door monitoring systems. CE marking requirements for passenger vessel control systems elevate engineering documentation burdens. Northern shipyards in Mecklenburg-Vorpommern specialize in ice-class commercial specifications requiring heavy-duty steel constructions.
Marine Watertight Door Market Competitive Landscape
On the supply side, the industry is consolidating around certified manufacturers with captive testing capabilities and early-stage shipyard engineering relationships. Two strategic archetypes dominate: coastal Asian fabricators leveraging proximity to construction clusters, and Western specialists commanding premium positions in military and yacht segments. Competitive moves center on backward integration into precision-machined actuator production and geographic expansion through Korean Register certification acquisition.
Among China-based fabricators, Speed-Horse Marine, Jinbo Marine, and Hi-Sea Group exemplify the scale-driven archetype serving commercial fleet procurement through standardized catalog offerings. These entities occupy positions within regional supply chains anchored to Yangtze River Delta and Bohai Rim shipyard clusters. ACIR Marine and Deansteel Manufacturing Company represent specialization-focused alternatives, with the former sitting within aluminum and composite system tiers and the latter anchoring North American military-grade steel door procurement.
| Leading Market Players |
|---|
| Railway Specialties Corporation |
| Speed-Horse Marine |
| OUCO Industry |
| Jinbo Marine |
| Deansteel Manufacturing Company |
| Hi-Sea Group |
| ACIR Marine |
| AdvanTec Marine |
| IMS Groups |
| Others |
Value Network & Pricing Analysis
Ulsan and Geoje shipyard clusters concentrate procurement authority for certified watertight door systems, compressing supplier margins through consolidated supplier lists while amplifying pricing power for manufacturers with Korean Register certification and integrated testing capabilities.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with SOLAS Chapter II-1 compliant assemblies commanding substantial premiums over basic commercial variants. Three-tier pricing structure separates naval-grade blast-resistant specifications from standard commercial single-leaf doors and economy retrofit alternatives. Price differentiation reflects after-sales service bundling and predictive maintenance sensor integration rather than hardware alone. Commercial ferry operators in Indonesia and Southeast Asia exhibit highest price sensitivity due to fleet renewal budget constraints, while naval programs prioritize electromagnetic signature control over unit cost.
Supply Chain Analysis
Marine-grade AH36 and DH36 steel plate feeds from Chinese and South Korean mills, while precision-machined hydraulic actuators draw from Japanese and European specialty component houses. Rubber gasket compounds and seal materials rest on petrochemical supply chains concentrated in Northeast Asia. Single-source vulnerability around certified TIG welding labor creates bottleneck risk in Ulsan and Geoje clusters. Distribution runs through shipyard-direct channels with early-stage engineering collaboration, displacing traditional owner-furnished equipment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance service contracts and IoT-enabled condition monitoring represent the fastest-expanding revenue layer, expanding faster than hardware sales as classification societies shift from periodic inspection toward continuous operational assurance models.
For Market Incumbents: Insulate market position through backward integration into precision-machined actuator production and captive welding certification programs. Secure Korean Register witness testing accreditation to defend against emerging Chinese competitors. Expand early-stage engineering collaboration with Hyundai Heavy Industries and Daewoo Shipbuilding to compress competitor negotiation windows.
For New Entrants and Emerging Players: Pursue Indonesian archipelago ferry replacement demand with cost-optimized single-leaf doors meeting simplified SOLAS compliance tiers. Target EU MDR convergence opportunities for integrated door monitoring systems in Mediterranean passenger fleets. Establish service contract bundling partnerships with regional maintenance providers to bypass shipyard-direct procurement barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with predictive maintenance sensor integration and classification society harmonization capabilities. Long-term viability hinges on shift from component fabrication toward integrated system supplier archetypes. Watch for IACS UR Z17 service supplier requirement tightening as inflection indicator for consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Korean Register Certification Acquisition | Unlocks naval frigate and LNG carrier procurement at DSME and Hyundai Heavy Industries. |
| Backward Integration into Actuator Production | Reduces 16-20 week procurement cycles from European and Japanese specialty houses. |
| Predictive Maintenance Sensor Integration | Enables shift from periodic inspection to condition-based service revenue models. |
| Early-Stage Shipyard Engineering Collaboration | Embeds door specifications into hull structural drawings before contract award. |
| Indonesian Ferry Market Entry | Captures archipelago fleet renewal demand for cost-optimized SOLAS-compliant doors. |
Research Methodology
Operator-level perspectives from shipyard procurement managers, naval architect specification leads, classification society surveyors, and aftermarket service contractors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against Lloyd's Register and DNV technical rule filings, Korean Register certification databases, and IMO SOLAS amendment documentation. Bottom-up vessel newbuild projections triangulated against top-down shipyard capacity utilization data from Ulsan, Geoje, Qingdao, and Shanghai clusters.
Scenario-bracketing around steel alloy price volatility and hydraulic actuator lead time disruption shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade, installation approach, and application severity tier. CAGRs derived from shipyard orderbook analysis and naval program budget trajectories, with cross-checking against IACS member society type approval records and flag-state administration enforcement patterns.
Macroeconomic conditions sit as an overlay; deviation in marine steel scrap prices, Korean Won exchange rates, or naval defense budget allocations would shift the trajectory. Forecasts reflect assumptions around SOLAS amendment implementation timelines and classification society rule harmonization. Cross-checking against Lloyd's Register and DNV annual review publications is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Flood Control Sandbags Market
Marine and Coastal Engineering
Global Pipe Laying Vessel Market
Marine and Coastal Engineering
Global Marine Ventilation Systems Market
Marine and Coastal Engineering
Mooring Bollards Market
Marine and Coastal Engineering
Marine Hawser Market
Marine and Coastal Engineering
Middle East Offshore Crane Market
Marine and Coastal Engineering
Offshore Crane Market
Marine and Coastal Engineering
Global Seismic Vessels Market
Marine and Coastal Engineering
Marine Manifolds and Risers Market
Marine and Coastal Engineering
Marine Heat Exchanger Market
Marine and Coastal Engineering
Mooring Compensators Market
Marine and Coastal Engineering
Submersible Dredge Pump Market
Marine and Coastal Engineering
Wind Turbine Installation Vessel Market
Marine and Coastal Engineering
Floating Docks Market
Marine and Coastal Engineering
Offshore Pipeline Market
Marine and Coastal Engineering
Ship Gangways Market