
 Indonesia Anchors and Grouts Market | 2026-2036
Indonesia Anchors and Grouts Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Anchors and Grouts Market Insights
High-performance epoxy grout specifications are redrawing competitive benchmarks across Indonesia's construction chemicals sector. Sika AG leverages its regional manufacturing footprint to sustain consistent supply to Java-based contractors. MAPEI S.p.A. anchors its position through specialized distribution networks serving Jakarta's high-rise developments. MBCC Group differentiates via technical service capabilities that support complex ground stabilization projects.
Anchors and grouts comprise bonded or mechanical fastening systems and flowable fill materials designed to transfer loads between structural elements and substrates, typically achieving compressive strengths exceeding 50 MPa for critical infrastructure applications. These systems secure machinery, reinforce concrete connections, and stabilize rock formations in Indonesia's geologically active terrain. Epoxy grouts command premium positioning in seismic retrofitting applications where flexural performance governs specification decisions. Cement grouts dominate volume in standard construction end uses across the archipelago, though margin pools concentrate in chemical grout formulations for mining and marine environments.
Indonesia's Ministry of Public Works and Housing (PUPR) enforces building codes that mandate anchor performance under seismic loading, while BIS standards govern imported product quality certification. The country's national standardization body (BSN) aligns SNI markings with international test protocols, creating compliance barriers for uncertified imports. Stakeholders must monitor evolving SNI requirements for injection-grade resins and evaluate local blending capacity as import substitution policies gain traction.
Market Dynamics
Seismic retrofitting mandates across Java's commercial corridor are compressing specification cycles and elevating performance thresholds for anchoring systems. Contractors now face simultaneous pressure from PUPR enforcement timelines and BSN certification requirements.
Growth Catalysts
- High-rise commercial construction:Jakarta's vertical development boom demands epoxy-based anchoring systems rated for dynamic loading. Building permits in the capital region increasingly specify post-installed anchors with seismic qualification.
- SNI alignment with international test protocols:BSN's harmonization of injection-grade resin standards is streamlining import pathways for certified European and Asian suppliers. This regulatory convergence reduces technical barriers for compliant products.
- Mining sector ground stabilization:Indonesia's mineral extraction operations in Papua and Sulawesi require chemical grout formulations for tunnel support and rock bolt anchoring. Underground projects specify ultra-fine cement and silicate-based systems.
Market Restraints
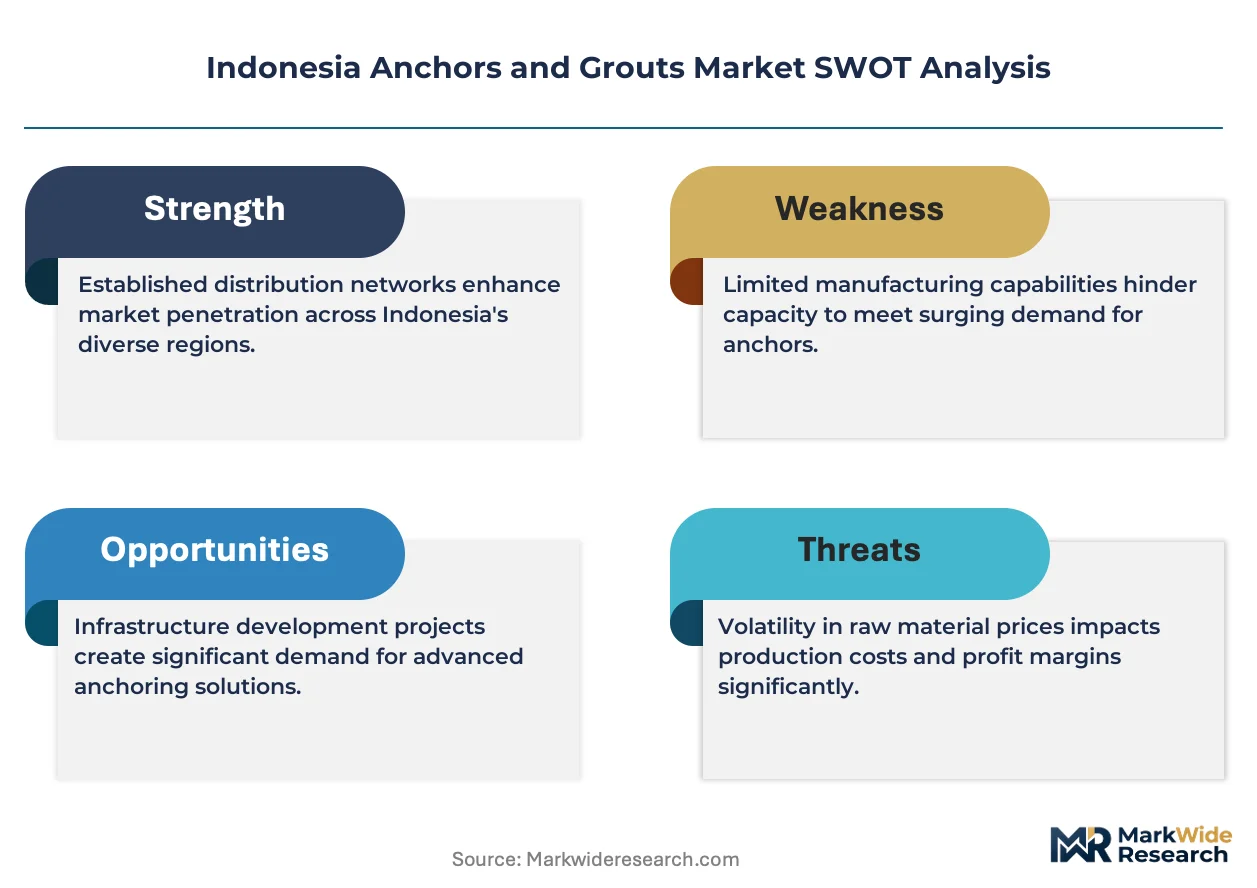
- Epoxy resin cost volatility:Petrochemical feedstock fluctuations compress margins for high-performance grout manufacturers. Formulators struggle to pass through raw material swings in competitive bidding environments.
- Import dependency for specialty additives:Domestic blending capacity remains concentrated in basic cementitious systems. Advanced curing agents and flexibilizers arrive through Singapore and Malaysia distribution nodes.
- Cement grout substitution pressure:Standard construction applications favor lower-cost cementitious fills over chemical alternatives. Price-sensitive contractors in residential and light commercial segments resist specification upgrades.
Strategic Opportunities
- Eastern Indonesia infrastructure gap:Sulawesi and Maluku provinces lack established supply chains for construction chemicals. First-mover distributors can capture specification influence in nascent port and industrial zone developments.
- Digital procurement platforms:Contractor purchasing through B2B marketplaces is reducing traditional distributor markups. Direct manufacturer relationships with tier-one builders are displacing multi-layer channel structures.
- PLI scheme localization incentives:Indonesia's production-linked incentive framework rewards domestic manufacturing of construction chemicals. Qualifying investments in Java-based blending facilities gain tax and import duty advantages.
Industry Challenges
- Specialized applicator certification:Epoxy grout installation requires trained technicians for surface preparation and mixing ratios. The shortage of certified crews delays project schedules and compromises warranty coverage.
- SNI testing backlog:BSN laboratory capacity constraints extend product approval timelines. Importers face inventory carrying costs while awaiting certification for new formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Anchors and Grouts Market |
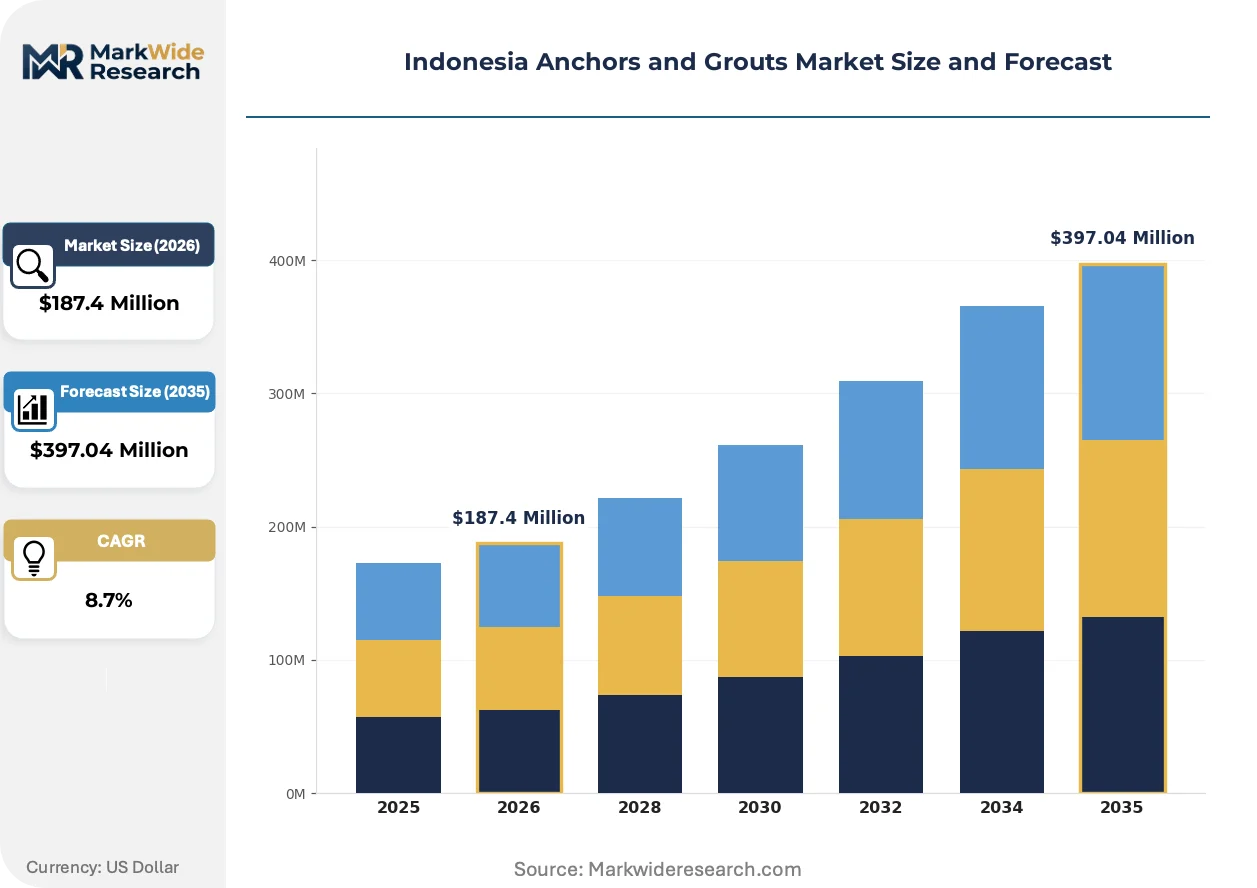
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Grouts, Epoxy Grouts, Cement Grouts, Resin Grouts End User: Construction, Marine, Mining, Civil Engineering Installation Method: Injection, Pre-packing, Manual Mixing, Automated Dispensing Application: Structural Repairs, Ground Stabilization, Waterproofing, Seismic Retrofitting |
| Companies Covered | Sika AG, MAPEI S.p.A., Fosroc, Inc., MBCC Group, Saint-Gobain, LATICRETE International Inc, Arkema, Deltacretindo, Normet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Anchors and Grouts Market Trends and Innovations
Material science advances and procurement digitization are restructuring how anchoring systems reach Indonesian construction sites. Technical specifications now travel faster through digital channels than traditional distribution relationships can adapt.
Hybrid epoxy-cement grout formulations are fragmenting the traditional product category boundaries that separated chemical and cementitious systems. Mining contractors in Kalimantan are specifying these intermediate-performance materials for ground support applications where pure epoxy exceeds cost constraints. The resulting specification diversity is fragmenting manufacturer product portfolios and forcing regional formulators to maintain broader formulation libraries.
PUPR's updated seismic design codes are mandating anchor performance verification under cyclic loading conditions. Building permit approvals now require third-party test reports for post-installed anchoring in high-rise structures. Jakarta-based engineering consultants are restructuring specification documents to incorporate these verification requirements, shifting liability toward product manufacturers.
Contractor buying committees are consolidating supplier relationships around technical service capabilities rather than price alone. Large infrastructure developers in Surabaya now require on-site mixing support and cure monitoring from grout vendors. This service bundling is compressing the addressable market for commodity distributors who lack application engineering resources.
Indonesia Anchors and Grouts Market Segmentation
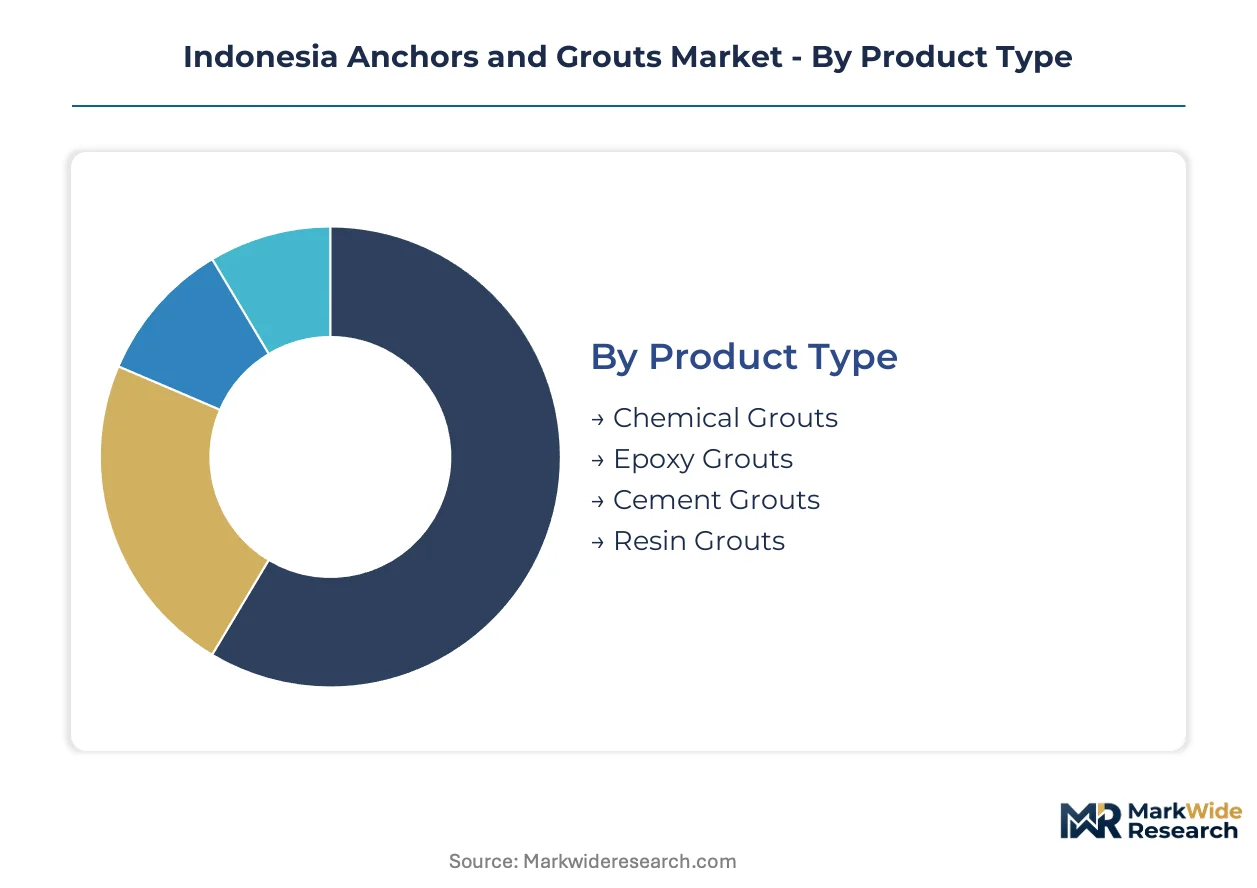
Segmentation reveals how BSN certification requirements and PUPR seismic mandates reshape procurement patterns across Indonesia's construction chemicals sector. Product specifications diverge sharply between Java's high-rise corridor and resource extraction zones in Eastern Indonesia.
Product Type:
BSN's SNI alignment with international test protocols creates tiered compliance barriers that segment manufacturers by formulation complexity and import certification status.
- Epoxy Grouts:Two-component systems achieve compressive strengths exceeding 80 MPa with superior chemical resistance. Jakarta's commercial tower projects specify these for post-installed anchoring under cyclic seismic loading per PUPR mandates. Contractors face extended procurement cycles due to specialized applicator certification requirements.
- Chemical Grouts:Polyurethane and silicate-based formulations penetrate micro-fractures for ground stabilization. Mining operations in Papua and Kalimantan drive specification of ultra-fine particle systems for rock bolt anchoring in water-bearing formations.
- Cement Grouts:Portland cement-based fills dominate volume in standard construction across Java's residential sector. Basic SNI certification requirements allow domestic blending facilities to capture price-sensitive segments.
- Resin Grouts:Acrylic and vinylester systems serve marine environments requiring rapid cure times. Port infrastructure projects in Surabaya specify these for underwater pile repair applications.
Cement Grouts handles the majority of throughput; Epoxy Grouts is climbing the fastest on specification influence in commercial construction.
End User:
Customer concentration varies by project scale and technical service intensity, with tier-one contractors consolidating supplier relationships around application engineering support.
- Construction:Vertical development in Jakarta and Surabaya demands epoxy-based anchoring systems with seismic qualification documentation. Building permit approvals now require third-party test reports for post-installed anchors.
- Civil Engineering:Bridge and highway projects across Java specify cementitious systems for bearing pad grouting. PUPR infrastructure budgets favor cost-optimized formulations over performance premiums.
- Mining:Underground operations in Sulawesi and Papua require chemical grout formulations for tunnel support. Groundwater conditions dictate silicate-based or micro-cement system selection.
- Marine:Port expansion in Eastern Indonesia drives demand for corrosion-resistant anchoring. Saltwater exposure mandates specialized resin formulations with extended warranty coverage.
Construction commands the largest addressable base; Mining is expanding most quickly on project pipeline growth in mineral extraction zones.
Installation Method:
Application technique determines labor skill requirements and warranty eligibility, creating segmentation between certified contractor networks and generalist crews.
- Injection:Pressure-injected resins and cementitious slurries achieve deep substrate penetration for crack repair and soil stabilization. BSN certification requirements for injection-grade resins elevate technical barriers for applicator qualification.
- Automated Dispensing:Metered mixing systems ensure precise ratio control for epoxy grout installations in high-rise structural connections. Large developers in Surabaya now mandate on-site cure monitoring from vendors.
- Pre-packing:Factory-blended dry mixes reduce field variability for standard grouting applications. Domestic blending facilities in Java capture volume through simplified logistics.
- Manual Mixing:Site-proportioned cementitious fills serve remote projects lacking specialized equipment. Quality variability limits specification to non-structural applications.
Manual Mixing retains the widest deployment footprint; Automated Dispensing is gaining share fastest on technical service bundling requirements.
Application:
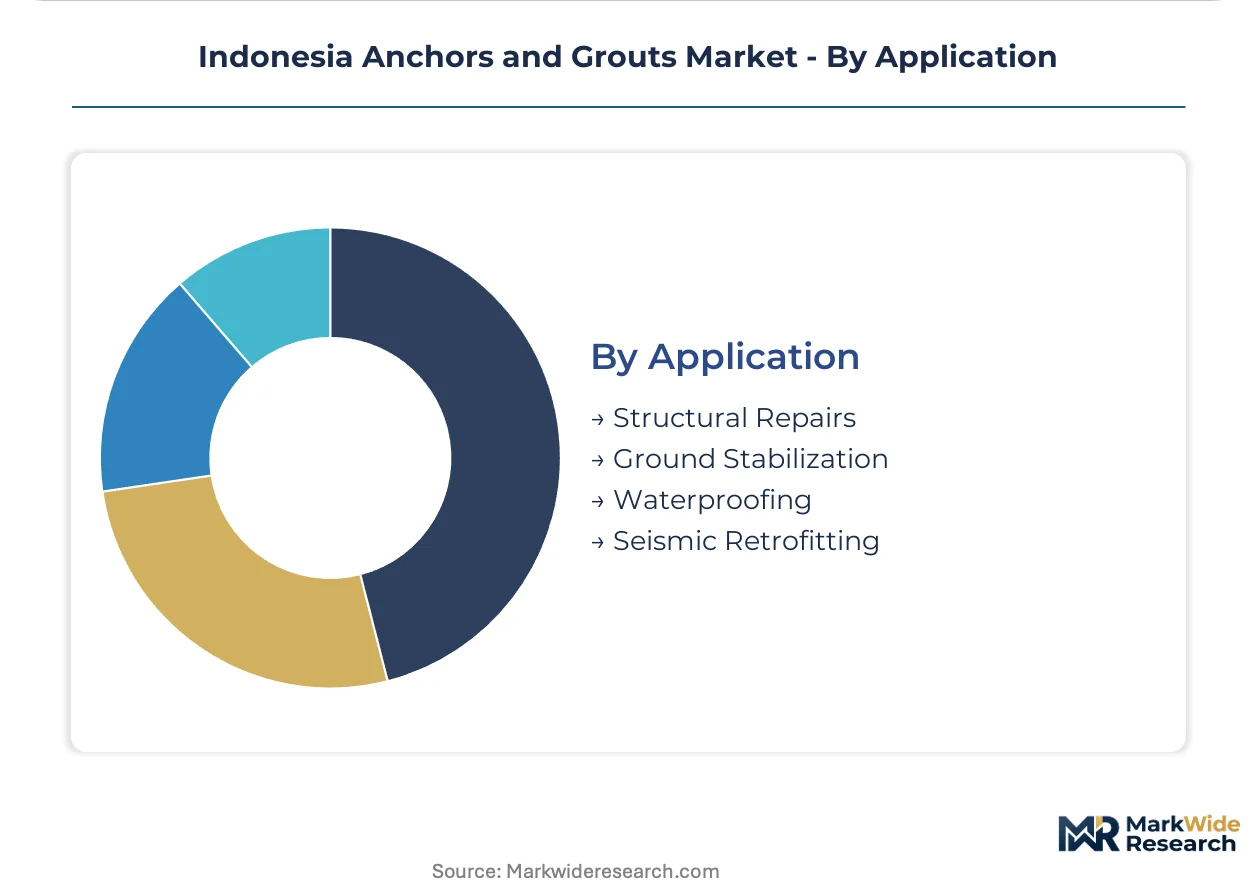
Performance thresholds diverge by structural criticality, with seismic retrofitting mandates compressing specification cycles for qualified anchoring systems.
- Seismic Retrofitting:Post-installed anchor qualification under cyclic loading governs material selection for Java's commercial building upgrades. PUPR enforcement timelines accelerate procurement of certified epoxy systems.
- Ground Stabilization:Rock bolt anchoring and void filling in mining and tunneling applications specify chemical grout penetration characteristics. Sulawesi infrastructure projects drive demand for ultra-fine cement systems.
- Structural Repairs:Concrete restoration and load transfer applications span epoxy and cementitious solutions based on exposure conditions. Warranty terms differentiate qualified from commodity suppliers.
- Waterproofing:Membrane-compatible grouts serve below-grade construction in Jakarta's high water table conditions. Hydrostatic pressure ratings govern specification decisions.
Structural Repairs absorbs the greatest volume; Seismic Retrofitting shows the steepest expansion trajectory on regulatory mandate acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Indonesia's outer islands exhibit acute price sensitivity to cementitious grouts, while Jakarta's commercial developers absorb substantial premiums for seismic-qualified epoxy systems without demand elasticity.
Java
Jakarta's vertical construction boom drives procurement of post-installed anchors with cyclic loading certification per PUPR mandates. BSN's SNI alignment with international test protocols streamlines import pathways for certified European suppliers. Surabaya's engineering consultants now require third-party test reports for high-rise structural connections.
Sumatra
Palm oil processing facilities and port expansions in Medan generate steady demand for machinery anchoring and bearing pad grouting. The Ministry of Public Works and Housing directs infrastructure budgets toward cost-optimized cementitious formulations. Batam's industrial zone attracts distributors serving Singapore-linked supply chains for specialty additives.
Sulawesi
Nickel mining operations in Morowali and Konawe specify chemical grout formulations for tunnel support and rock bolt anchoring. Groundwater conditions dictate silicate-based or micro-cement system selection for underground projects. Local blending capacity remains underdeveloped, forcing reliance on Makassar distribution nodes.
Kalimantan
Coal and bauxite extraction in East Kalimantan drives consumption of ultra-fine cement systems for ground stabilization. The PLI scheme's localization incentives have yet to attract qualifying investments in regional blending facilities. Samarinda contractors face extended lead times for injection-grade resins.
Papua
Copper and gold mining in Grasberg and Wabu generate isolated demand for chemical anchoring in geologically challenging terrain. Import dependency for specialty curing agents amplifies logistics costs through Jayapura and Timika ports. Remote project sites tolerate manual mixing methods despite quality variability.
Indonesia Anchors and Grouts Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Indonesia's construction chemicals sector. The market exhibits tiered concentration with multinational formulators commanding premium segments while domestic blenders capture volume in standard applications. Three archetypes dominate: integrated construction chemical specialists with regional manufacturing footprints, import-dependent distributors with technical service capabilities, and localized blending operations serving price-sensitive residential construction. Capacity expansion and strategic partnerships represent the dominant competitive vectors as stakeholders respond to PLI scheme incentives and procurement digitization.
Among European-anchored construction chemical groups, Sika AG and MAPEI S.p.A. occupy positions exemplifying integrated regional manufacturing archetypes. MBCC Group represents the technical service-intensive model that supports complex ground stabilization projects across Indonesia's mining and infrastructure sectors. These three entities anchor the competitive structure through differentiated supply chain configurations rather than overlapping segment contestation.
| Leading Market Players |
|---|
| Sika AG |
| MAPEI S.p.A. |
| Fosroc, Inc. |
| MBCC Group |
| Saint-Gobain |
| LATICRETE International Inc |
| Arkema |
| Deltacretindo |
| Normet |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Java-based blending facilities creates pronounced scale economies that compress unit costs for domestic cementitious producers while elevating price floors for imported epoxy formulations. This concentration of manufacturing scale in Indonesia's western corridor simultaneously shapes procurement patterns across the archipelago and establishes tiered entry barriers for specialty chemical suppliers.
Pricing Analysis
BSN's SNI certification requirements dictate the pricing tier structure across Indonesia's construction chemicals sector. Three-tier pricing structure across premium, standard, and economy levels separates seismic-qualified epoxy systems from basic cement grouts and uncertified commodity fills. Price differentiation centers on certification grade and technical service bundling, with Jakarta's commercial developers absorbing substantial premiums for PUPR-compliant anchoring systems. Cost compression in standard cementitious tiers is intensifying because domestic blenders compete aggressively on volume contracts. Residential contractors in outer island provinces exhibit acute price sensitivity, while mining operators in Papua and Sulawesi prioritize performance specifications over unit economics.
Supply Chain Analysis
Container availability through Singapore and Port of Tanjung Priok shapes inbound logistics costs for specialty curing agents and flexibilizers arriving from European and Northeast Asian manufacturing hubs. Geographic supply concentration centers on Germany, Switzerland, and Japan for advanced epoxy resin formulations, while China and South Korea feed basic cementitious additives. Raw material dependencies rest on petrochemical-derived bisphenol-A, amine hardeners, and ultra-fine Portland cement clinker. Single-source vulnerability for injection-grade resin formulations creates exposure to BSN laboratory approval delays. Distribution runs through Makassar and Surabaya distribution nodes serving Eastern Indonesia mining corridors, with direct manufacturer relationships displacing traditional multi-layer channel structures in Jakarta's high-rise segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's anchors and grouts sector is accelerating through a regulatory inflection as PUPR seismic retrofitting mandates compress specification cycles and elevate performance thresholds for qualified anchoring systems. This disruption creates asymmetric opportunities across incumbent defense, entrant positioning, and investment targeting.
For Market Incumbents: Fortify technical service capabilities through on-site cure monitoring and applicator certification programs that lock in Surabaya and Jakarta infrastructure developers. Deepen backward integration into specialty additive blending within Java-based facilities to capture PLI scheme incentives and reduce Singapore distribution node dependency. Channel control through direct contractor relationships displaces commodity distributors who lack application engineering resources. For New Entrants and Emerging Players: BSN's accelerated SNI fast-track for injection-grade resins creates entry pathways for certified Asian suppliers seeking to bypass traditional European import channels. Target Sulawesi and Maluku provinces where established supply chains for construction chemicals remain underdeveloped and first-mover distributors can capture specification influence in nascent port developments. Digital procurement platform partnerships with tier-one builders enable direct manufacturer relationships that circumvent legacy distributor markups. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors technical service-intensive formulators with regional manufacturing footprints over import-dependent distributors lacking application engineering depth. Long-term viability across the projection horizon rests on domestic blending capacity expansion aligned with import substitution policy trajectories. Acquisition target archetype: Java-based facilities with existing SNI certification infrastructure and established relationships with PUPR-contracted infrastructure developers. The signal to monitor is BSN laboratory capacity expansion timelines, which would indicate regulatory bottlenecks easing and certification throughput accelerating for new market entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Blending Facility Expansion | PLI scheme tax advantages reduce import duty exposure for Java-based epoxy formulators serving PUPR projects. |
| Technical Service Capability Buildout | On-site cure monitoring and applicator training differentiate qualified suppliers from commodity distributors in Surabaya. |
| BSN Certification Fast-Track Investment | Accelerated SNI approval timelines compress market entry barriers for injection-grade resin suppliers. |
| Eastern Indonesia Distribution Partnership | Makassar and Jayapura logistics nodes capture mining sector demand in Sulawesi and Papua extraction zones. |
| Digital Procurement Platform Integration | Direct manufacturer relationships with Jakarta tier-one builders displace traditional multi-layer channel structures. |
Research Methodology
Desk research of BSN regulatory filings, PUPR infrastructure procurement databases, and customs trade records preceded structured interviews with plant managers at domestic blending facilities, procurement leads at Jakarta-based commercial developers, distribution channel partners serving Eastern Indonesia mining corridors, and technical R&D directors at regional construction chemical formulators. Primary fieldwork combined with secondary validation through SEC 10-K disclosures of multinational suppliers and Indonesian Ministry of Trade import statistics enabled bottom-up and top-down triangulation across volume and value estimates.
Variance decomposition across product type, end-use industry, installation method complexity, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled included formulation chemistry tier, project scale category, certification status, and geographic infrastructure development phase. CAGRs were derived through slope analysis of historical trajectory and forward-looking intensity indicators without reliance on single-source extrapolation. Industry-specific forecast inputs incorporated PUPR budget allocation patterns and mining sector project pipeline disclosures from mineral extraction operators in Papua and Sulawesi.
Decision-makers should treat outputs as directional under assumptions of sustained PUPR enforcement timelines and stable BSN certification throughput; material deviation in regulatory implementation pace or laboratory capacity expansion would warrant model refresh. Specific risk factors that could revise forecasts include abrupt epoxy resin feedstock price volatility, accelerated import substitution policy shifts, and seismic code enforcement variability across provincial PUPR offices. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
ASEAN Waterproofing Market
Specialty Construction
Concrete and Cement Dissolver Market
Specialty Construction
Shotcrete Accelerators Market
Specialty Construction
Welded Metal Bellows Market
Specialty Construction
Europe Anchors and Grouts Market
Specialty Construction
Global Fencing Market
Specialty Construction
Slab Repair Products Market
Specialty Construction
Expandable Shelter Market
Specialty Construction
Fire Hydrants Market
Specialty Construction
Asia-Pacific Waterproofing Solutions Market
Specialty Construction
Portable Walls Market
Specialty Construction
Construction Repaint Market
Specialty Construction
Composite Repair Market
Specialty Construction
Asia-Pacific Anchors and Grouts Market
Specialty Construction
Indonesia Waterproofing Solutions Market
Specialty Construction
South America Anchors and Grouts Market