
 Marine Boiler Burner Market | 2026-2036
Marine Boiler Burner Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Boiler Burner Market Intelligence
South Korea's expansion of its LNG-fueled shipbuilding capacity is reconfiguring the competitive landscape for dual-fuel burner systems. SAACKE Group leverages its extensive portfolio of multi-fuel burners to secure contracts for new tanker and container ship constructions. Meanwhile, Volcano Co., Ltd. specializes in compact, efficient burner designs suited for smaller general cargo vessels and passenger ships.
A marine boiler burner is an engineered device that atomizes liquid or gaseous fuel, mixes it with combustion air, and ignites it to generate heat within a ship's boiler. Its primary purpose is to produce steam for propulsion, auxiliary power generation, and heating services aboard vessels. The shift towards Liquefied Natural Gas (LNG) and biofuels is creating new opportunities within the fuel type segment, moving away from traditional Heavy Fuel Oil. Demand from tanker and container ship applications continues to dominate, driven by fleet renewals and environmental retrofitting mandates.
Regulations from the International Maritime Organization (IMO) on NOx and SOx emissions set the baseline for burner performance standards. Regional policies like the EU's FuelEU Maritime initiative and directives from China's Ministry of Ecology and Environment (MEE) accelerate the transition to alternative fuels. Burner manufacturers must now balance the engineering challenge of accommodating diverse fuel types with the commercial need to maintain cost-competitiveness.
Market Dynamics
The imperative to comply with stringent maritime emissions regulations serves as the central structural force shaping the marine boiler burner market. Mandates from the International Maritime Organization (IMO) are compelling a technological pivot away from traditional fuel oil systems towards more complex, multi-fuel capable burners.
Growth Catalysts
- Emissions Regulations:Stricter limits on SOx and NOx emissions under the IMO's MARPOL Annex VI mandate the adoption of cleaner fuels and more efficient combustion technologies, directly stimulating demand for new and retrofitted burners.
- Fleet Modernization:The ongoing renewal cycle for the global tanker, bulk carrier, and container ship fleets provides a consistent demand driver, as newbuilds increasingly specify dual-fuel or alternative fuel-ready boiler systems.
- Alternative Fuel Availability:Expanding port infrastructure for Liquefied Natural Gas (LNG) bunkering is making LNG-fueled vessels a more viable option, which in turn creates a direct pull for compatible dual-fuel burner installations.
Market Restraints
- High Retrofit Costs:The significant capital investment required to retrofit an existing vessel with a new dual-fuel burner system, including fuel storage and supply infrastructure, deters many smaller and mid-sized vessel operators.
- Fuel Handling Complexity:Alternative fuels like LNG and methanol introduce significant engineering challenges related to cryogenic storage, fuel conditioning, and safe handling, complicating burner system design and onboard integration.
- Limited Bunkering Infrastructure:Outside of major global trade routes, the lack of widespread availability of alternative fuels like LNG or biofuels acts as a structural barrier to the adoption of burners designed for these specific energy sources.
Strategic Opportunities
- Ammonia and Hydrogen-Ready Burners:Developing burner systems capable of handling future zero-carbon fuels like ammonia and hydrogen positions manufacturers to capture long-term value as the industry progresses toward full decarbonization.
- Digital Twin and Simulation Services:Offering advanced digital services, including simulation of burner performance with various fuel blends and predictive maintenance analytics, creates a new, high-margin revenue stream beyond hardware sales.
- Modular Retrofit Kits:Designing standardized, modular burner retrofit kits for popular vessel classes can reduce installation time and cost, opening a larger addressable market among budget-conscious shipowners.
Industry Challenges
- Multi-Fuel Operational Consistency:Manufacturers face the challenge of designing burners that deliver stable, efficient, and compliant combustion across a wide spectrum of fuels with varying properties, from traditional oils to LNG and biofuels.
- Legacy System Integration:Integrating modern, digitally controlled burner management systems with older, analog ship automation and control platforms on existing vessels is a significant technical and operational hurdle during retrofits.
- Crew Competency and Training:A shortage of marine engineers with the skills to operate, maintain, and troubleshoot complex multi-fuel burner systems poses an operational risk for vessel operators and a barrier to technology adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Boiler Burner Market |
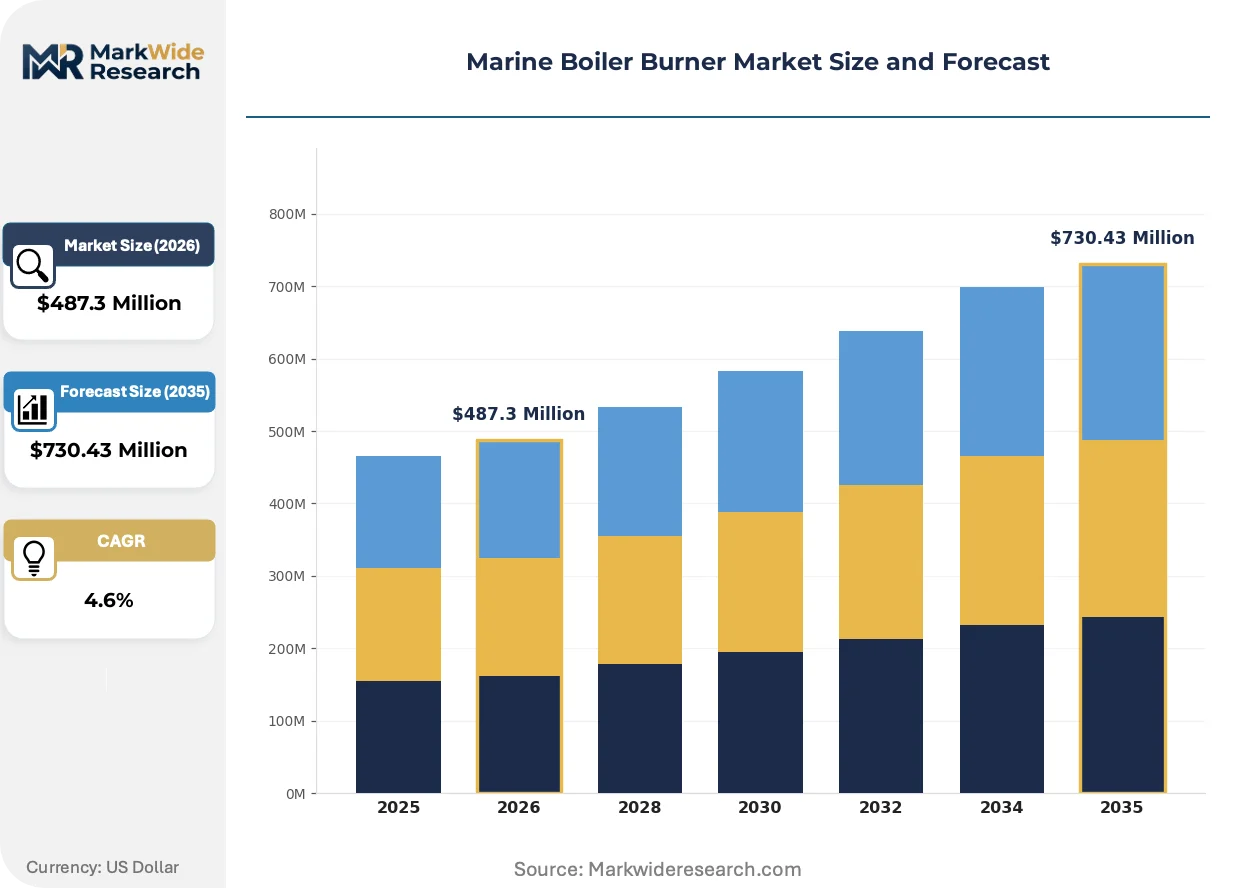
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Jet Burner, Rotary Cup Atomizer, Air-Suspension Burner, Duplex Burner, Premix Burner Fuel Type: Heavy Fuel Oil, Marine Diesel Oil, Liquefied Natural Gas, Biofuel, Bunker C Oil Application: Container Ships, Bulk Carriers, Tankers, General Cargo Vessels, Passenger Ships End User: Shipyards, Shipping Companies, Vessel Operators, Offshore Platforms |
| Companies Covered | Weishaupt Group, SAACKE Group, Volcano Co., Ltd., Oilon Group Oy, Burner Automation Rotterdam, Filter AS, Zeeco, Inc., Osaka Boiler Mfg. Co., Ltd., Sunflame Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Boiler Burner Market Strategic Shifts & Innovations
A fundamental re-evaluation of fuel flexibility and operational efficiency defines the current innovation cycle. Manufacturers are developing systems that can seamlessly switch between conventional and alternative fuels while integrating digital oversight to ensure performance and compliance under evolving maritime regulations.
Dual-Fuel Combustion Systems
A dual-fuel burner is an integrated system designed to combust both gaseous fuels like LNG and conventional liquid marine fuels. These systems are seeing rapid adoption by operators of newbuild container ships and tankers seeking to meet emissions targets. The core engineering focus is migrating from perfecting single-fuel efficiency to mastering the control logic for seamless fuel changeovers and stable combustion across different operating loads.
Impact of Regional Green Shipping Mandates
The EU's FuelEU Maritime initiative is establishing new benchmarks for the industry. This regulation imposes penalties on vessels based on the lifecycle greenhouse gas intensity of the energy they use, creating a powerful incentive for fuels beyond LNG, such as green methanol and biofuels. Consequently, burner manufacturers servicing the European trade routes are accelerating development of multi-fuel systems optimized for these next-generation liquid fuels.
Shift to Lifecycle Service Agreements
Vessel operators are moving away from transactional hardware procurement toward demanding comprehensive lifecycle support. This trend disrupts the traditional break-fix and spare parts model, as fleet managers now seek long-term service agreements that bundle remote monitoring, performance analytics, and compliance reporting. This demand is most pronounced among large, technically sophisticated container and LNG carrier fleets operating on global routes.
Marine Boiler Burner Market Segmentation
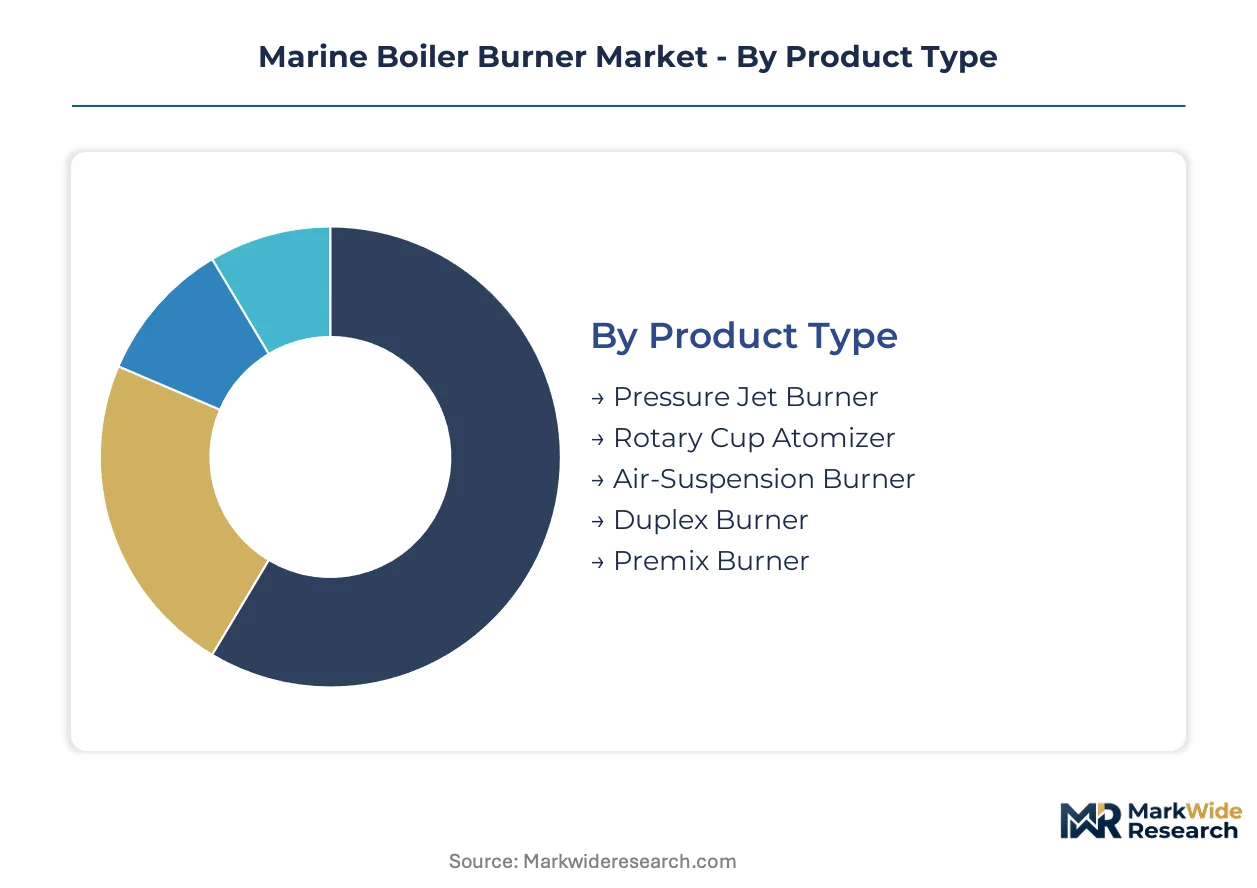
The marine boiler burner market is intricately segmented, reflecting the diverse operational demands, fuel preferences, and regulatory environments across the global shipping industry. Understanding these segments is crucial for manufacturers to tailor product development and for stakeholders to identify areas of concentrated demand and technological evolution.
Product Type:
The operational mechanism for marine boiler burners defines distinct product types, each optimized for specific combustion characteristics and vessel requirements.
- Pressure Jet Burner:This type atomizes liquid fuel by forcing it through a nozzle under high pressure, creating a fine mist for efficient combustion. Demand concentrates in smaller general cargo vessels and older tanker fleets seeking cost-effective retrofit solutions for traditional liquid fuels.
- Duplex Burner:Featuring two separate fuel lines and atomizers, this system allows for rapid switching between different fuels or provides critical redundancy for continuous operation. This design sees strong demand from newbuild container ships and LNG carriers prioritizing operational flexibility and uptime in compliance with emission zones.
- Rotary Cup Atomizer:A rotary cup atomizer uses a spinning cup to atomize viscous fuels, often found in older heavy fuel oil systems requiring robust handling of challenging fuel properties.
- Air-Suspension Burner:This burner type mixes fuel with a primary air stream before combustion, making it suitable for various liquid fuels and offering good flame stability.
- Premix Burner:A premix burner pre-mixes fuel and air before ignition, providing very low NOx emissions for specific applications where stringent air quality standards are paramount.
Pressure Jet Burners command the established base. The steepest expansion runs through Duplex Burners.
Fuel Type:
Burner designs are fundamentally shaped by the specific fuel characteristics they are engineered to combust, driving innovation in multi-fuel capabilities and emission reduction.
- Liquefied Natural Gas:These burners require specialized systems designed for gaseous fuel combustion, often incorporating pilot ignition and advanced safety features for cryogenic fuels. Demand is accelerating within new container ship and tanker constructions, driven by stringent IMO emission standards for SOx and NOx.
- Heavy Fuel Oil:Traditionally combusted in marine boilers, HFO burners require preheating and robust atomization systems due to the fuel's high viscosity and impurities. This fuel type continues to dominate retrofit projects for older bulk carriers and general cargo vessels operating outside current emission control areas.
- Marine Diesel Oil:Offering cleaner combustion than HFO, MDO burners require less preheating and generally simpler burner configurations, suitable for vessels operating in Emission Control Areas (ECAs).
- Biofuel:Emerging as a sustainable alternative, these fuels necessitate burners adaptable to varying viscosities, calorific values, and combustion properties for future decarbonization pathways.
- Bunker C Oil:Similar to HFO, Bunker C oil is a residual fuel oil, requiring robust burners capable of handling high viscosity and impurities for reliable operation.
Traditional Heavy Fuel Oil systems maintain a significant installed base. Liquefied Natural Gas burners are expanding most quickly.
Application:
The operational profile and scale of a vessel dictate the specific boiler burner requirements, influencing capacity, fuel flexibility, and emission control features.
- Container Ships:These large vessels demand high-capacity, multi-fuel burners to generate steam for propulsion and extensive auxiliary power needs, especially for reefer containers. Newbuild orders in South Korea and China are increasingly specifying LNG-capable burner systems for environmental compliance on global trade routes.
- Tankers:Tankers require robust boiler burners for cargo heating, inert gas generation, and propulsion, often handling diverse fuel types to maintain operational flexibility. Fleet renewal programs and retrofits for SOx compliance drive significant burner upgrades in this segment, particularly for crude oil and chemical carriers.
- Bulk Carriers:Bulk carriers utilize boiler burners primarily for auxiliary power and heating services, with a focus on reliability and fuel efficiency for long voyages.
- General Cargo Vessels:Often smaller, these vessels employ compact and efficient burner designs for general steam requirements, balancing performance with space constraints.
- Passenger Ships:Passenger ships prioritize low emissions, quiet operation, and high reliability from boiler burners to ensure passenger comfort and adherence to strict environmental regulations in sensitive areas.
Container Ships and Tankers represent the largest consumers of marine boiler burners. General Cargo Vessels are undergoing consistent modernization.
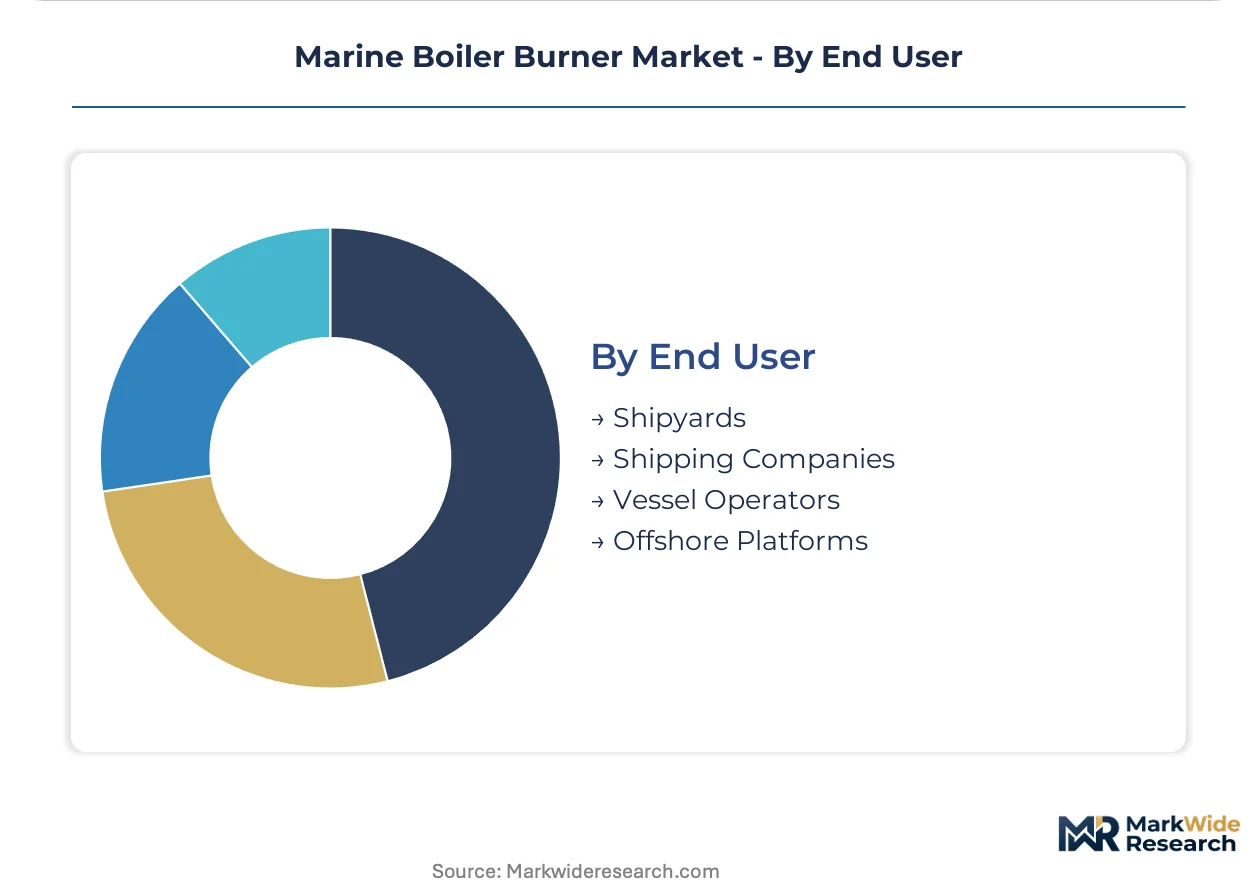
End User:
The procurement and integration of marine boiler burners are managed by distinct stakeholder groups within the maritime ecosystem, each with unique purchasing drivers and technical requirements.
- Shipping Companies:These entities own and operate fleets, making strategic decisions on burner selection for both newbuilds and existing vessel retrofits. Their focus on long-term operational costs, fuel flexibility, and regulatory compliance drives demand for efficient multi-fuel systems.
- Shipyards:Shipyards integrate boiler burner systems into new vessel constructions, often working closely with specific burner manufacturers to meet design specifications and delivery schedules. Major shipbuilding centers in South Korea and China are critical for new burner installations in global fleets.
- Vessel Operators:Vessel operators manage the day-to-day operation and maintenance of boiler burners, influencing decisions related to spare parts, service contracts, and minor upgrades.
- Offshore Platforms:Offshore platforms employ specialized boiler burners for power generation, heating, and process steam in demanding marine environments, prioritizing robustness and continuous operation.
Shipyards are central to new installations. Shipping Companies are increasingly driving retrofit decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global marine boiler burner supply heavily concentrates in established shipbuilding hubs. These regions drive demand for advanced burner systems, responding to stringent emissions regulations and continuous fleet modernization efforts. The shift towards alternative fuels significantly impacts regional market dynamics.
South Korea
South Korea's robust shipbuilding industry generates substantial demand for dual-fuel burner systems. The country's Ministry of Oceans and Fisheries supports green shipping initiatives, encouraging LNG-fueled vessel construction. Major shipyards in Ulsan and Geoje are at the forefront of integrating complex multi-fuel boiler technologies into newbuilds.
China
China’s expansive shipbuilding capacity and growing domestic fleet renewal programs fuel significant burner market activity. The Ministry of Ecology and Environment (MEE) implements strict air pollution controls, accelerating the adoption of cleaner combustion solutions. Shipyards across the Yangtze River Delta, particularly in Shanghai, are key centers for new burner installations.
Germany
European environmental mandates drive demand for efficient and low-emission marine boiler burners in Germany. The EU's FuelEU Maritime initiative creates incentives for vessels operating in European waters to adopt alternative fuels. Major port cities like Hamburg and Bremen are seeing increased retrofitting activities and new orders for advanced burner technologies.
United States
Vessel operators in the United States increasingly seek burners compliant with domestic and international emission zones. The EPA's Vessel General Permit (VGP) regulations influence the adoption of cleaner marine technologies. Shipyards and maintenance facilities along the Gulf Coast and East Coast are upgrading boiler systems for both commercial and government fleets.
Japan
Japanese shipbuilders and fleet owners prioritize high-efficiency and reliable marine boiler burners for their technologically advanced vessels. Japan's Ministry of Land, Infrastructure, Transport and Tourism (MLIT) promotes decarbonization through research into ammonia and hydrogen fuels. Shipbuilding clusters in Imabari and Nagasaki are actively developing and integrating next-generation burner solutions.
Marine Boiler Burner Market Key Industry Players
Technology specialists and diversified industrial conglomerates split the market for marine boiler burners. The industry structure reflects a balance between highly specialized engineering firms and larger entities leveraging broad manufacturing capabilities across various industrial sectors. Dominant competitive moves include strategic partnerships for multi-fuel system development, continuous portfolio diversification into alternative fuel solutions, and geographic expansion into emerging shipbuilding markets.
Specialists in multi-fuel burner systems, such as SAACKE Group, exemplify companies leveraging extensive engineering portfolios to secure contracts for new tanker and container ship constructions. This German-based group positions itself as a provider of comprehensive combustion solutions. Meanwhile, Volcano Co., Ltd., a Japanese firm, represents companies focusing on compact, efficient burner designs specifically suited for smaller general cargo vessels and passenger ships. These companies anchor innovation in fuel flexibility and emission reduction, addressing diverse vessel requirements across the global fleet.
| Leading Market Players |
|---|
| Weishaupt Group |
| SAACKE Group |
| Volcano Co., Ltd. |
| Oilon Group Oy |
| Burner Automation Rotterdam |
| Filter AS |
| Zeeco, Inc. |
| Osaka Boiler Mfg. Co., Ltd. |
| Sunflame Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Commodity price volatility for alternative fuels like LNG significantly influences pricing tiers and the global supply chain for marine boiler burners. This volatility shapes investment in multi-fuel burner research and development and manufacturing capacity.
Pricing Analysis
IMO's MARPOL Annex VI dictates the pricing tier structure for marine boiler burners, emphasizing compliance and advanced technology. The dominant pricing model is project-based, tailored for newbuilds and complex retrofits, with price differentiation driven by customization for multi-fuel systems and comprehensive after-sales service. Pricing pressure trends upward due to extensive research and development for new fuel compatibility and stringent emission standards. Smaller general cargo vessel operators exhibit high price sensitivity, while large container and LNG carrier fleets prioritize performance and long-term operational savings.
Supply Chain Analysis
Upstream sourcing of specialized control electronics and high-grade steel alloys forms a critical dependency for marine boiler burner manufacturers. Geographic supply concentrates in South Korea, China, and Germany, reflecting established shipbuilding and industrial manufacturing hubs. Logistics chokepoints, particularly for global shipping routes, pose a structural risk to component delivery schedules. Distribution runs through direct sales channels to major shipyards and shipping companies, alongside specialized marine equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine boiler burner market represents an early-cycle expansion story, driven by the pervasive impact of stricter IMO emission standards. This regulatory tailwind accelerates technology adoption and market penetration for advanced multi-fuel systems.
For Market Incumbents: Entrench existing market share by investing heavily in research and development for ammonia and hydrogen-ready burner technologies. Incumbents should acquire specialized software firms to offer digital twin and predictive maintenance services, mitigating margin pressure from new entrants. Expanding global service networks in emerging alternative fuel bunkering hubs will reinforce customer loyalty and operational support. Certification investment for new fuel types provides a critical competitive lever.
For New Entrants and Emerging Players: Modular retrofit kits for smaller general cargo vessels on regional trade routes represent a penetrable entry point, addressing budget-conscious shipowners. Specialized solutions for biofuel combustion, adaptable to varying viscosities, offer another white-space opportunity. Partnerships with regional ship repair yards provide an effective go-to-market angle for installation and service. Focusing on these underserved segments avoids direct competition with established multi-fuel specialists.
For Investors and Strategic Acquirers: The market sits at an early-growth phase that favors technology-agnostic innovators within the marine combustion space. Strong long-term viability is evident across the next 5-10 years, driven by global decarbonization mandates. Acquisition targets should include specialized firms in advanced fuel atomization or digital combustion control systems. Accelerated development of hydrogen and ammonia bunkering infrastructure is a critical signal to watch for future inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Ammonia and Hydrogen-Ready Burners | Positions manufacturers for future zero-carbon shipping, capturing long-term value from decarbonization pathways. |
| Form Partnerships with Green Fuel Suppliers | Ensures compatibility and early market access for next-generation fuels like green methanol and biofuels. |
| Acquire Digital Twin Software Specialists | Enhances service offerings with predictive maintenance and performance analytics for vessel operators. |
| Expand Manufacturing in South Korea and China | Capitalizes on high demand from major shipbuilding centers for new installations and retrofits. |
| Implement Modular Retrofit Kit Production | Reduces installation time and cost for shipowners, opening a larger addressable market among mid-sized fleets. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and robust secondary research. Primary insights came from marine engineers, shipyard procurement managers, shipping company fleet managers, and regulatory compliance officers. Secondary validation drew from IMO reports, national maritime authority publications, and shipbuilding association statistics. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and forecast consistency.
Forecast inputs considered vessel fleet renewal cycles, alternative fuel infrastructure development, and evolving emission mandates across the analysis window. The analytical framework modeled segmentation dimensions including product type, fuel type, application, end-user, and regional regulatory frameworks. Compound Annual Growth Rates were derived via a weighted average of market drivers and historical growth trends.
Macroeconomic conditions sit as an overlay; deviation in global trade volumes or rapid shifts in energy prices would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement and technological adoption rates. Cross-checking against international maritime organization projections is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Micro Combined Heat and Power (CHP) Market
Boilers
Brazil Combined Heat and Power Market
Boilers
Industrial Boiler MRO Market
Boilers
Fire Tube Industrial Boiler Market
Boilers
Combi Boiler Market
Boilers
Global Marine Boilers Market
Boilers
Europe Combined Heat and Power Market
Boilers
Water Tube Industrial Boiler Market
Boilers
Global Boiler Market
Boilers
US Combined Heat and Power (CHP) Market
Boilers
Boiler Control Solutions Market
Boilers
Space Heating Boilers Market
Boilers
Superheater Tubes Market
Boilers
Gas Fired Boilers Market
Boilers
Global Domestic Boilers Market
Boilers
Electric Boiler Market