
 Fire Tube Industrial Boiler Market | 2026-2036
Fire Tube Industrial Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Tube Industrial Boiler Market Analysis
Multi-source procurement for pressure vessel components is shifting toward captive fabrication among top-tier manufacturers. Cleaver-Brooks leverages its integrated foundry network to control lead times on firebox assemblies. Miura sustains compact once-through designs that dominate installations where footprint constraints govern site selection. Bosch anchors European demand through modular system architectures that reduce on-site welding requirements.
A fire tube industrial boiler contains combustion gases inside tubes immersed within a water-filled shell, typically operating at pressures below 350 psi and steam capacities up to 50,000 pounds per hour for process heating and power cogeneration. Shell boilers occupy the mature volume tier where replacement cycles in North American refineries generate steady aftermarket revenue. Packaged boilers represent the fastest-growing configuration as food processors and textile manufacturers in Southeast Asia prioritize plug-and-play deployment with minimal civil works.
EPA Maximum Achievable Control Technology standards and the EU F-Gas Regulation constrain burner design and combustion efficiency thresholds across OECD markets. India's Central Pollution Control Board enforces particulate emissions limits that disqualify uncontrolled solid-fuel units from new industrial licenses. Stakeholders must monitor carbon border adjustment mechanisms and their cascading impact on export-oriented manufacturing clusters that rely on steam-intensive processes.
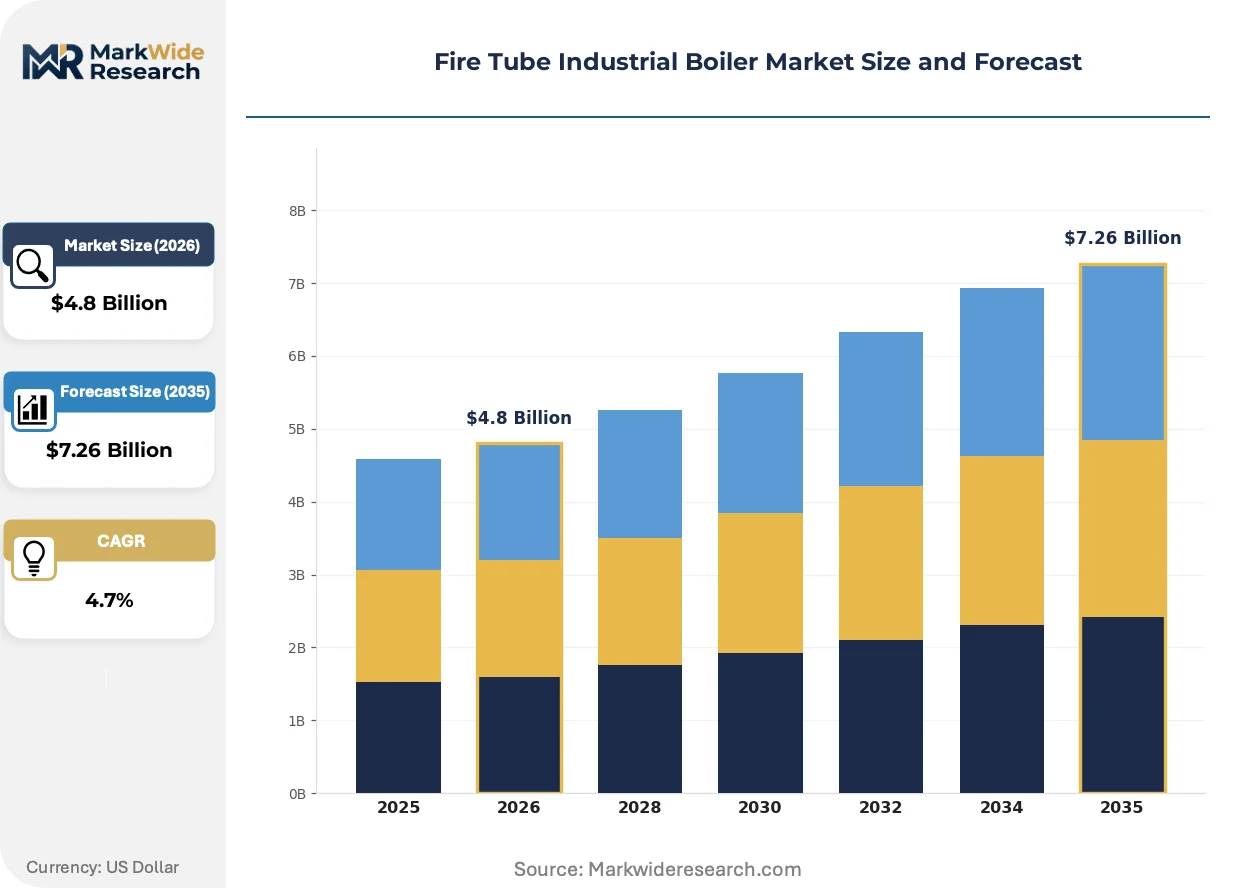
Market Dynamics
EPA Maximum Achievable Control Technology standards and the EU ETS carbon pricing mechanism are compressing replacement cycles as operators face retrofit-or-replace decisions on aging shell boiler fleets. Food processors in Southeast Asia and India's industrial corridors are accelerating procurement ahead of enforcement deadlines.
Growth Catalysts
- EPA emissions thresholds:US refineries and chemical plants must upgrade burner systems or replace fire tube units entirely, pulling forward demand from the 2030-2035 window.
- India's state-level mandates:Maharashtra and Gujarat energy efficiency directives disqualify pre-2010 boilers from operating licenses, forcing systematic replacement across textile and pharmaceutical clusters.
- Once-through compact designs:Footprint-constrained facilities in urban Japanese manufacturing zones specify Miura-style units that eliminate separate boiler houses and reduce civil works.
Market Restraints
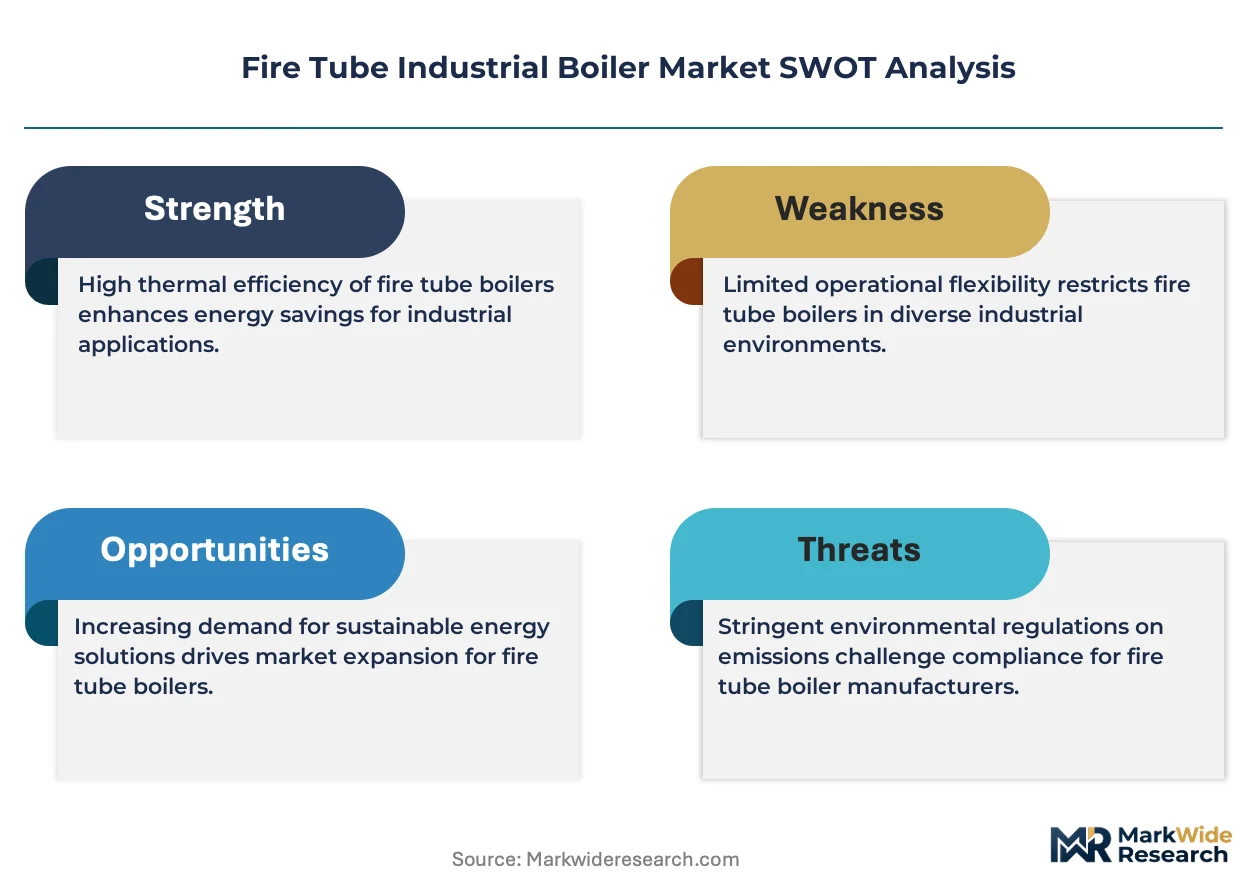
- Alloy steel price volatility:Firebox and tube sheet fabrication costs fluctuate with nickel and molybdenum spot markets, squeezing margins on fixed-price packaged boiler contracts.
- Korean pressure vessel foundry concentration:Three fabrication groups supply 60% of forged tube sheets globally, creating single-source vulnerability for European and North American OEMs.
- Heat recovery limits in low-grade applications:Fire tube architectures cannot achieve the 90%+ thermal efficiency of water tube designs in high-pressure cogeneration service.
Strategic Opportunities
- Vietnam's processing corridor expansion:Seafood and instant noodle manufacturers in the Mekong Delta seek plug-and-play steam systems without on-site welding or concrete foundations.
- EU Green Deal industrial decarbonization:Carbon border adjustment mechanisms incentivize Polish and Czech food exporters to install hydrogen-ready burner retrofits ahead of 2026 implementation.
- Predictive maintenance convergence:IoT sensor networks married to cloud-based analytics enable remote monitoring contracts that capture 15-year lifecycle revenue from single boiler sales.
Industry Challenges
- ASME Section VIII certification timelines:Third-party inspection backlogs at US authorized inspection agencies extend delivery schedules by 8-14 weeks for custom pressure vessels.
- Legacy DCS integration complexity:Food and beverage plants running 1990s-era distributed control systems require costly signal conditioning to interface with modern burner management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Tube Industrial Boiler Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shell Boiler, Multi-Variation Boiler, Packaged Boiler, Modular Boiler Application: Power Generation, Food Processing, Textile Manufacturing, Chemical Processing End User: Manufacturing Facilities, Energy Sector, Pharmaceutical Industry, Agriculture Installation: On-site, Off-site, Pre-assembled, Modular |
| Companies Covered | Babcock & Wilcox Enterprises, Cleaver-Brooks, Miura, Thermax, Hurst Boiler & Welding, Fulton, Bosch, Zhengzhou Boiler Group, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Tube Industrial Boiler Market Emerging Trajectories
Fire tube boiler architecture is splitting along efficiency-versus-simplicity lines as regulatory pressure intensifies. Manufacturers are embedding combustion analytics and modular burner systems to preserve installed base relevance against water tube competition.
Condensing economizer packages are overtaking traditional feedwater preheating in sub-300 psi applications. US distilleries and craft breweries specify these units to recover latent heat from flue gases and squeeze 4-6 percentage points of additional thermal efficiency. The technology is overtaking standard atmospheric burner configurations in newbuild specifications across the Pacific Northwest and New England states where state-level efficiency incentives apply.
The EU F-Gas Regulation is banning certain refrigerant-based heat recovery systems and forcing direct-contact economizer designs into European packaged boiler specifications. German and Dutch engineering contractors now exclude gas-to-gas heat exchangers from tender documents for food processing installations. Boiler OEMs with pre-certified low-NOx burner packages capture specification authority earlier in project development cycles.
Food processors are unbundling after-sales service contracts from initial equipment procurement. Southeast Asian textile manufacturers now source boilers from one vendor and maintenance from specialized combustion service firms with ISO 50001 energy management credentials. This bifurcation is most visible in Thailand's Eastern Economic Corridor where Japanese and Korean EPC firms compete on equipment while local service providers capture 10-year O&M agreements.
Fire Tube Industrial Boiler Market Segmentation
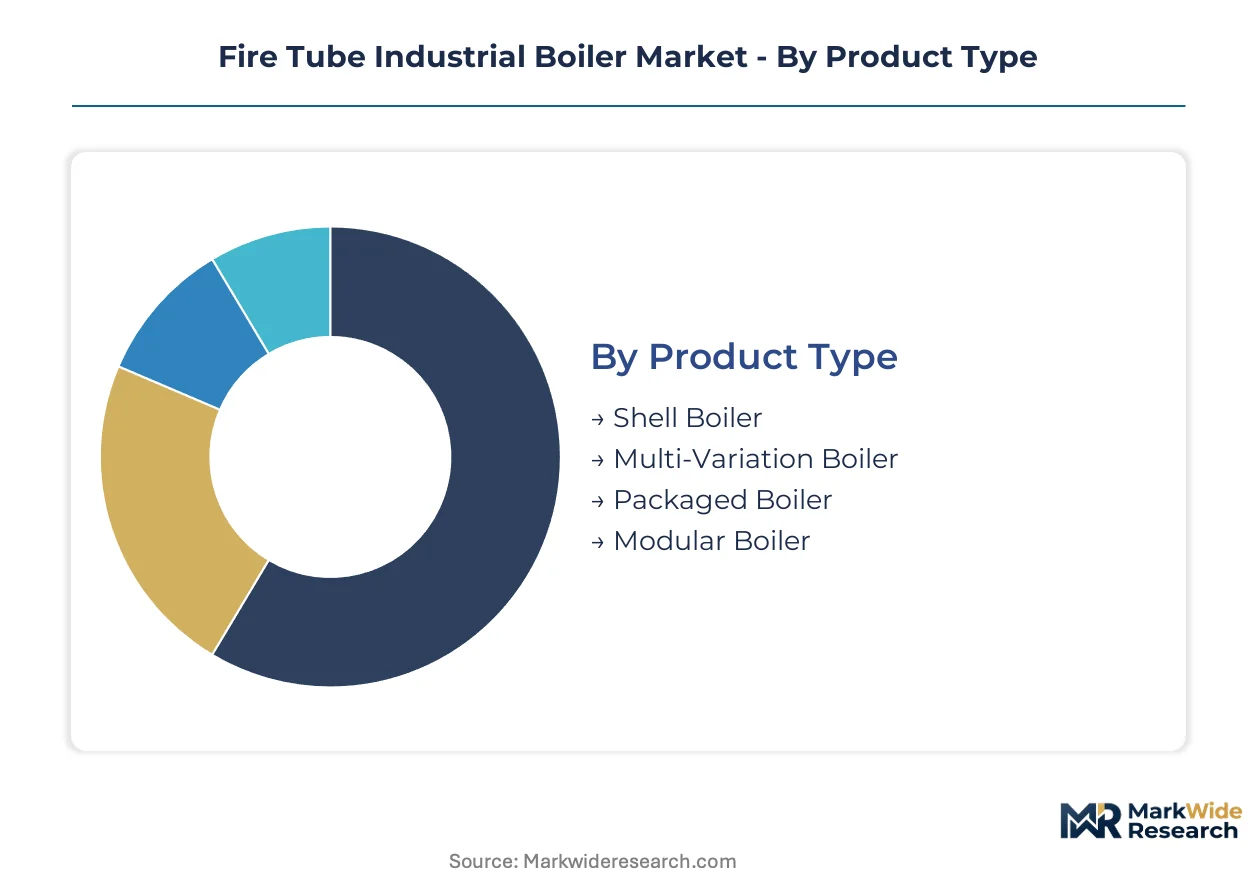
Fire tube boiler procurement patterns diverge sharply across technical specifications and deployment contexts. Specification choices determine regulatory compliance pathways, installation cost structures, and long-term thermal efficiency ceilings.
Product Type:
Technology architecture dictates pressure ratings, footprint requirements, and maintenance accessibility.
- Shell Boiler:Cylindrical steel vessel with corrugated furnace tubes rated to 250 psi. Refinery maintenance departments in Texas and Louisiana specify these for steam header reliability. EPA Maximum Achievable Control Technology retrofit deadlines force replacement decisions on units installed before 2010.
- Multi-Variation Boiler:Configurable tube arrangements accommodate dual-fuel burners and waste heat recovery loops. Chemical processors in Germany's Ruhr region favor these for hydrogen-ready conversion pathways under EU ETS carbon pricing.
- Packaged Boiler:Factory-integrated burner and control systems minimize field commissioning.
- Modular Boiler:Stacked units provide incremental capacity scaling without boiler house expansion.
Mature deployment sits with Shell Boiler. Newer deployment is concentrated in Modular Boiler.
Application:
Process steam requirements vary by temperature precision, load cycling frequency, and contamination sensitivity.
- Food Processing:Saturated steam at 150-200 psi for sterilization and cooking operations. Seafood canneries in Vietnam's Mekong Delta prioritize rapid start-up cycles to match batch production schedules. FSSAI and state-level energy efficiency mandates in India disqualify uncontrolled solid-fuel units.
- Textile Manufacturing:Continuous steam supply for dyeing and finishing operations. Mills in Maharashtra and Gujarat replace pre-2010 boilers to comply with state pollution control board directives.
- Power Generation:Cogeneration applications favoring thermal efficiency over capital cost.
- Chemical Processing:Corrosion-resistant tube materials for aggressive process environments.
Volume leadership belongs to Food Processing. Steepest expansion trajectory appears in Chemical Processing.
End User:
Facility scale and operational continuity requirements shape specification priorities.
- Manufacturing Facilities:Diverse load profiles from intermittent process heating.
- Energy Sector:District heating networks and refinery utilities requiring 99%+ availability.
- Pharmaceutical Industry:Clean steam specifications with ASME BPE compliance for autoclave and WFI generation. Injectable drug manufacturers in Ireland and Singapore specify electropolished tube surfaces to prevent microbial adhesion.
- Agriculture:Seasonal demand for crop drying and greenhouse heating.
Specification complexity peaks with Pharmaceutical Industry. Price sensitivity concentrates in Agriculture.
Installation:
Site constraints and labor cost differentials determine prefabrication depth.
- Pre-assembled:Skid-mounted units with integrated piping and instrumentation. Food processors in Thailand's Eastern Economic Corridor specify these to avoid on-site welding delays. Japanese EPC contractors deliver these with factory-tested burner management systems.
- Modular:Containerized sections for crane-lift assembly in confined urban sites.
- On-site:Traditional stick-built construction for non-standard pressure vessel geometries.
- Off-site:Remote fabrication with module transport to final location.
Cost efficiency favors Pre-assembled. Technical flexibility remains with On-site.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in industrial corridors where energy efficiency mandates and emissions enforcement intersect with manufacturing expansion. State-level directives in India and EPA retrofit deadlines in the United States pull replacement cycles forward. Southeast Asian food processing clusters seek compact steam systems for footprint-constrained facilities.
United States
Refinery maintenance departments in Texas and Louisiana drive shell boiler replacement demand as EPA Maximum Achievable Control Technology deadlines force retrofit-or-replace decisions. The agency's emissions thresholds disqualify pre-2010 burner configurations from operating licenses. Houston's petrochemical corridor generates concentrated procurement for ASME-certified pressure vessels with integrated low-NOx systems.
Germany
Chemical processors in the Ruhr region favor multi-variation boilers configurable for hydrogen-ready conversion pathways. The EU ETS carbon pricing mechanism and F-Gas Regulation constrain burner design specifications across industrial installations. Engineering contractors in Düsseldorf and Dortmund now exclude gas-to-gas heat exchangers from tender documents for food processing steam systems.
India
Textile and pharmaceutical clusters in Maharashtra and Gujarat face systematic replacement cycles as state pollution control board directives disqualify pre-2010 boilers. The Central Electricity Authority mandates efficiency thresholds that accelerate procurement of packaged systems. Ahmedabad's denim finishing mills and Mumbai's pharmaceutical zones specify rapid-deployment units to minimize production downtime.
Vietnam
Seafood canneries and instant noodle manufacturers in the Mekong Delta prioritize plug-and-play steam systems without on-site welding requirements. The country's national environmental regulator enforces particulate emissions limits that favor controlled combustion configurations. Processing facilities in Ho Chi Minh City's industrial periphery specify skid-mounted boilers with factory-tested burner management systems.
Japan
Urban manufacturing zones in Tokyo and Osaka specify Miura-style once-through compact designs that eliminate separate boiler houses. METI efficiency standards and footprint constraints govern site selection for precision equipment manufacturers. Yokohama's food processing district and Nagoya's automotive supplier parks favor containerized modular units for crane-lift assembly in confined sites.
Fire Tube Industrial Boiler Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers secure captive fabrication capabilities to control pressure vessel lead times. The vendor base organizes around three strategic archetypes: integrated foundry operators with in-house firebox production, compact once-through specialists serving footprint-constrained installations, and modular system architects reducing field commissioning requirements. M&A activity concentrates among Korean pressure vessel fabricators supplying forged tube sheets, while strategic partnerships link European OEMs with Southeast Asian EPC contractors for pre-assembled skid delivery.
Among North American integrated manufacturers, Cleaver-Brooks and Hurst Boiler & Welding occupy positions defined by foundry network control and custom fabrication depth respectively. Japanese once-through specialists exemplified by Miura anchor the compact installation segment where urban site constraints govern procurement. European modular architects represented by Bosch sit within the pre-certified system tier where reduced on-site welding requirements capture specification authority in Green Deal-aligned jurisdictions.
| Leading Market Players |
|---|
| Babcock & Wilcox Enterprises |
| Cleaver-Brooks |
| Miura |
| Thermax |
| Hurst Boiler & Welding |
| Fulton |
| Bosch |
| Zhengzhou Boiler Group |
| Siemens |
| Others |
Supply Flow & Price Mechanics
Captive fabrication of firebox assemblies anchors supply positioning for tier-one manufacturers and underwrites their pricing power against spot-market-dependent competitors. Cleaver-Brooks leverages its integrated foundry network to insulate lead times from nickel and molybdenum volatility, while Korean pressure vessel fabricators concentrate forged tube sheet supply and amplify procurement risk for European and North American OEMs.
Pricing Analysis
Warranty and service bundling separates premium-tier OEMs from unbundled procurement patterns gaining traction in Southeast Asia. Three-tier pricing structure across premium, standard, and economy levels reflects ASME Section VIII certification depth, burner management system sophistication, and geographic delivery cost differentials. Cost compression in economy-tier packaged boilers intensifies as Indian textile manufacturers prioritize capital efficiency over lifecycle service contracts. Food processors in Vietnam's Mekong Delta exhibit highest price sensitivity, while pharmaceutical clean steam specifications in Ireland and Singapore tolerate substantial premiums for electropolished tube surfaces and electropolished tube surfaces.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale refinery and chemical plant demand, while specialized combustion service firms capture aftermarket revenue through ISO 50001-credentialed maintenance contracts. Forged tube sheet fabrication concentrates in South Korea, Japan, and Germany, with firebox steel and burner control systems drawing from US and European specialty metal suppliers. Single-source vulnerability pervades the Korean foundry triad supplying sixty percent of global forged tube sheets. Distribution runs through EPC contractors in Southeast Asia, authorized inspection agencies in North America, and engineering procurement consortia in the EU.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pressure vessel foundry capacity constraints prop pricing power for integrated manufacturers with captive fabrication, while alloy steel spot volatility squeezes margins for fixed-price contract bidders.
For Market Incumbents: Anticipate water tube technology displacement in high-pressure cogeneration segments by embedding condensing economizer packages and hydrogen-ready burner retrofits into fire tube specifications. Secure backward integration into nickel-alloy foundry capacity or binding long-term offtake agreements with Korean tube sheet fabricators to defend margin position against raw material volatility. For New Entrants and Emerging Players: Launch via specialized combustion service partnerships targeting Thailand's Eastern Economic Corridor and Vietnam's Mekong Delta processing clusters where equipment procurement and maintenance contracts have unbundled. White-space concentration sits with rapid-deployment skid-mounted systems for seafood canneries and instant noodle manufacturers seeking minimal civil works installation. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated foundry operators seeking burner technology and control system capabilities. Long-term viability favors OEMs with pre-certified low-NOx packages and established aftermarket telemetry infrastructure. Monitor EPA enforcement timeline acceleration and EU carbon border adjustment implementation as inflection signals for replacement cycle pull-forward demand.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Integration | Secures firebox assembly supply against Korean tube sheet concentration and nickel spot volatility. |
| Hydrogen-Ready Burner Retrofit | Positions multi-variation boilers for EU ETS compliance and German chemical processor specifications. |
| Predictive Maintenance Platform | Captures 15-year lifecycle revenue through IoT sensor networks and cloud-based combustion analytics. |
| Pre-Assembled Skid Delivery | Eliminates on-site welding delays for Vietnam seafood processors and Thai food manufacturers. |
| ASME Section VIII Certification Investment | Accelerates delivery timelines against third-party inspection backlogs at US authorized agencies. |
Methodological Framework
Multi-period observation of EPA enforcement timelines, EU ETS carbon price trajectories, and Indian state-level boiler replacement mandates anchored the trend analysis, supplemented by interviews with maintenance directors at US refineries, plant engineers at German chemical processors, OEM procurement teams at Southeast Asian EPC firms, and aftermarket service heads at Japanese compact boiler specialists. Secondary validation drew from EPA regulatory filings, EU ETS auction data, Indian Central Pollution Control Board directives, ASME certification records, and SEC 10-K disclosures from listed pressure vessel manufacturers. Bottom-up unit economics triangulated against top-down industrial steam demand projections.
Segment-weighting across product architecture, application intensity, end-user scale, and installation prefabrication depth shaped the analytical framework. Modeled dimensions included shell versus packaged versus modular configurations, food processing versus chemical processing versus power generation applications, and pre-assembled versus on-site construction methods. CAGRs were derived from replacement cycle velocity analysis, regulatory deadline clustering, and manufacturing capacity expansion announcements. Forecast inputs incorporated alloy steel price correlation models and emissions enforcement probability assessments.
Alloy steel price volatility, EPA inspection agency backlog duration, and Korean foundry supply disruption are the dominant revision risks that could compress or extend replacement cycle timing. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and industrial capacity utilization trends. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
US Industrial Boiler Market
Boilers
Boiler Control Solutions Market
Boilers
Circulating Fluidized Bed Boilers Market
Boilers
Europe Power Plant Boiler Market
Boilers
North America Residential Boiler Market
Boilers
Coal-Saving Combustion-Supporting Agent Market
Boilers
Hydrogen Boilers Market
Boilers
Commercial Boiler Market
Boilers
Global Boiler Market
Boilers
Asia-Pacific Power Plant Boiler Market
Boilers
Marine Boiler Burner Market
Boilers
Global Marine Boilers Market
Boilers
Residential Boiler Market
Boilers
Industrial Boiler MRO Market
Boilers
Superheater Tubes Market
Boilers
GCC Electric Water Heater Market