
 Global Boiler Market | 2026-2036
Global Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Global Boiler Market Analysis
Remote monitoring and predictive maintenance subscriptions is repositioning how boiler vendors capture lifetime value from installed bases. Bosch Thermotechnology leverages its cloud-connected control platforms to sustain recurring revenue streams alongside hardware sales. Viessmann Climate Solutions anchors its European position through specialized heat pump-hybrid integration services. Babcock & Wilcox Enterprises dominates the utility-scale segment with engineering-led retrofit and upgrade contracts.
A boiler is a closed vessel in which water or other fluid is heated under pressure to produce steam or hot water for industrial processes, space heating, or power generation, with operating pressures typically ranging from low-pressure residential systems at 30 psi to supercritical utility boilers exceeding 3,200 psi. Fire-tube designs occupy the mature commercial and light industrial tier where replacement cycles drive steady aftermarket revenue, while water-tube configurations lead in power generation applications demanding higher pressures and throughput. Modular electric boilers represent the fastest-expanding product category as electrification mandates reshape new construction specifications across multiple end-use verticals.
The EPA enforces emissions limits under the National Emission Standards for Hazardous Air Pollutants that compel coal and oil-fired boiler operators toward natural gas conversion or shutdown. The EU Ecodesign Directive and F-Gas Regulation collectively mandate minimum efficiency thresholds and refrigerant containment standards that reshape product development priorities for manufacturers serving European markets. China's Ministry of Ecology and Environment enforces dual carbon goals that restrict new coal-fired boiler permits in urban clusters. Stakeholders must monitor the divergence between electrification mandates in advanced economies and continued fossil fuel reliance in industrializing markets when allocating R&D and manufacturing capacity.
Market Dynamics
The boiler market faces structural pressure from electrification mandates that are compressing replacement cycles for fossil fuel systems while simultaneously fragmenting demand across hybrid, hydrogen-ready, and fully electric architectures.
Growth Catalysts
- EU Ecodesign Directive:Minimum efficiency thresholds are phasing out non-condensing gas units across Germany, France, and Italy. Replacement demand concentrates in residential retrofit segments.
- Industrial process steam:Food processing and pharmaceutical manufacturing in China and India require reliable high-pressure systems. Boiler operators secure long-term service contracts alongside equipment sales.
- Hydrogen blending infrastructure:Pilot programs in the Netherlands and United Kingdom validate 20-30% hydrogen co-firing. OEMs are engineering burner retrofits for existing installed bases.
Market Restraints
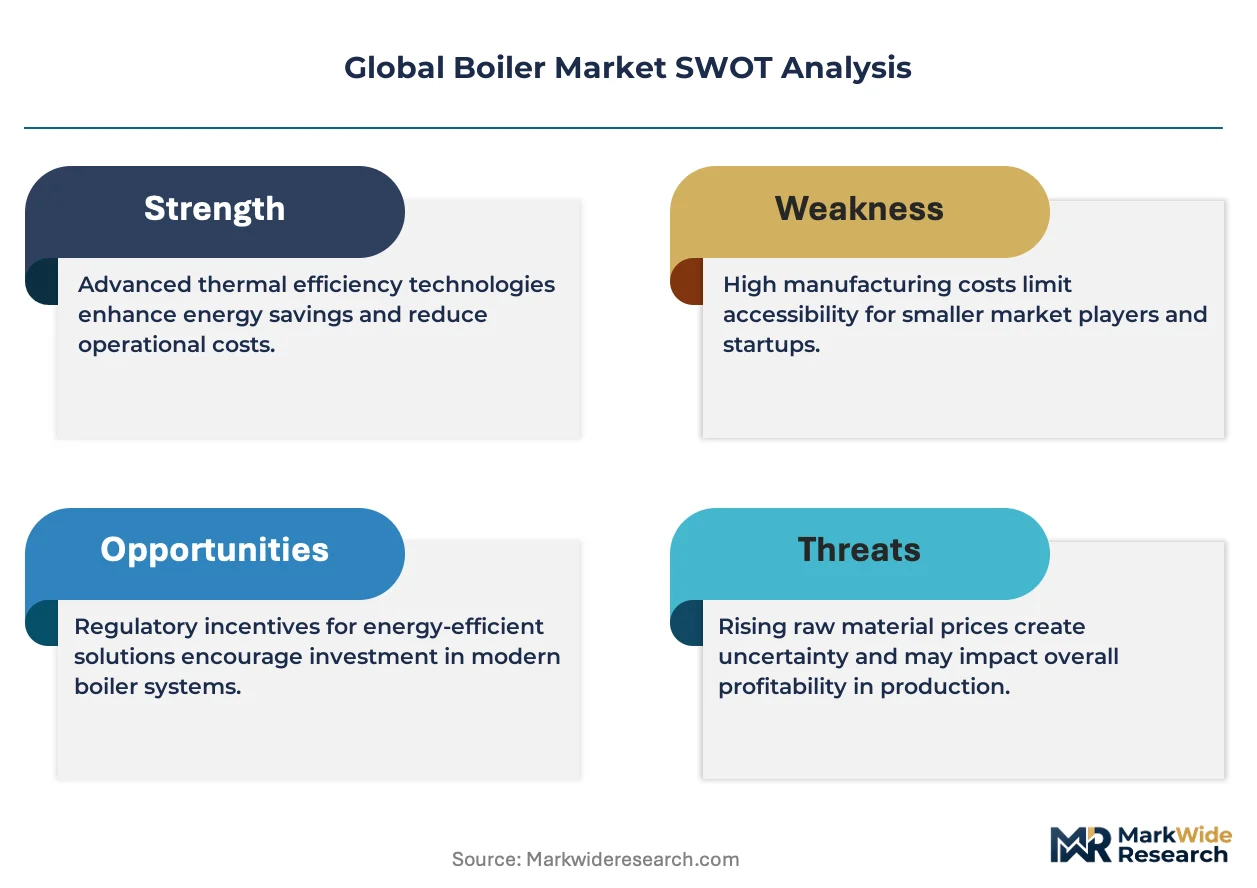
- Copper and steel input volatility:Heat exchanger fabrication depends on commodity metals with price swings exceeding 40% annually. Procurement teams struggle to hedge exposure across multi-year project timelines.
- Refractory material concentration:High-alumina brick and ceramic fiber supply concentrates in Henan province, China. Utility boiler operators face extended lead times for critical rebuild components.
- Electrification infrastructure gaps:Grid capacity constraints in Poland and Romania limit electric boiler deployment despite regulatory push. Industrial sites require substation upgrades that extend project timelines.
Strategic Opportunities
- India urban district heating:Smart city initiatives in Delhi and Mumbai create first-mover advantage for European and Korean OEMs with packaged plant expertise. Local manufacturing partnerships reduce import duty exposure.
- Heat pump-boiler hybrid systems:Convergence of vapor compression and combustion technologies enables bivalent operation. German and Swedish utilities are bundling these configurations into building renovation subsidies.
- Remote monitoring platforms:Cloud-based combustion optimization and predictive tube failure detection unlock recurring revenue. North American multi-site facility operators are standardizing on connected fleet management.
Industry Challenges
- Weld inspection certification backlog:ASME Section IX and ISO 9606 qualification delays extend manufacturing schedules. Pressure vessel fabricators in Italy and South Korea report six-month examiner availability gaps.
- Legacy control system integration:Brownfield sites in the United States and Japan require protocol translation between proprietary burner management systems and modern building automation. Middleware development consumes engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Boiler Market |
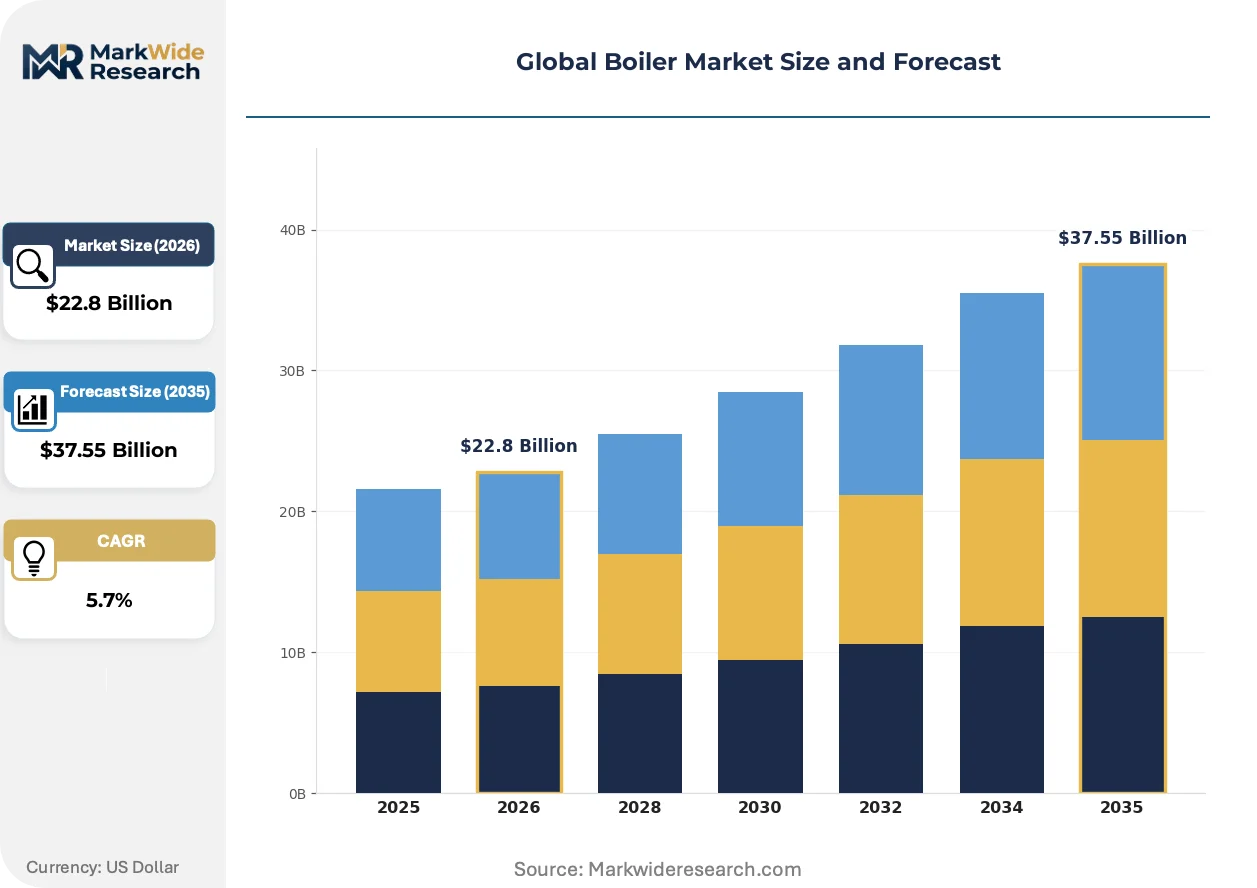
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $37.55 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire-Tube, Water-Tube, Electric, Modular End User: Manufacturing, Power Generation, Residential, Commercial Fuel Type: Natural Gas, Oil, Biomass, Coal Installation Type: Onshore, Offshore, Prefabricated, Site-Built |
| Companies Covered | Bosch Thermotechnology, Viessmann Climate Solutions, A.O. Smith Corporation, Babcock & Wilcox Enterprises, Vaillant Group, Mitsubishi Heavy Industries, Siemens, Cleaver-Brooks, Thermax Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Boiler Market Emerging Trajectories
Digital combustion management and alternative fuel compatibility are redefining product architectures. Vendors are repositioning around lifecycle service monetization rather than equipment-only transactions.
Artificial neural networks for flame pattern recognition and excess air optimization are integrating into commercial boiler control systems. Hospital and university campus operators in Germany and the Netherlands deploy these systems to maintain sub-3% oxygen trim without continuous manual tuning. The technology is integrating real-time emissions compliance verification into standard operating protocols.
The EPA National Emission Standards for Hazardous Air Pollutants and parallel EU Industrial Emissions Directive are tightening particulate and NOx limits for solid fuel combustion. Coal and biomass boiler operators in Poland and the United States face retrofit or shutdown decisions. Utility-scale plants are responding with selective catalytic reduction upgrades and fuel switching to natural gas.
Facility managers are unbundling aftermarket service from original equipment procurement. Multi-site operators in the United Kingdom and Australia now contract combustion tuning and tube inspection through third-party specialists rather than OEM service arms. This shift is most visible in food and beverage processing, where production continuity priorities override brand loyalty in maintenance sourcing.
Global Boiler Market Segmentation
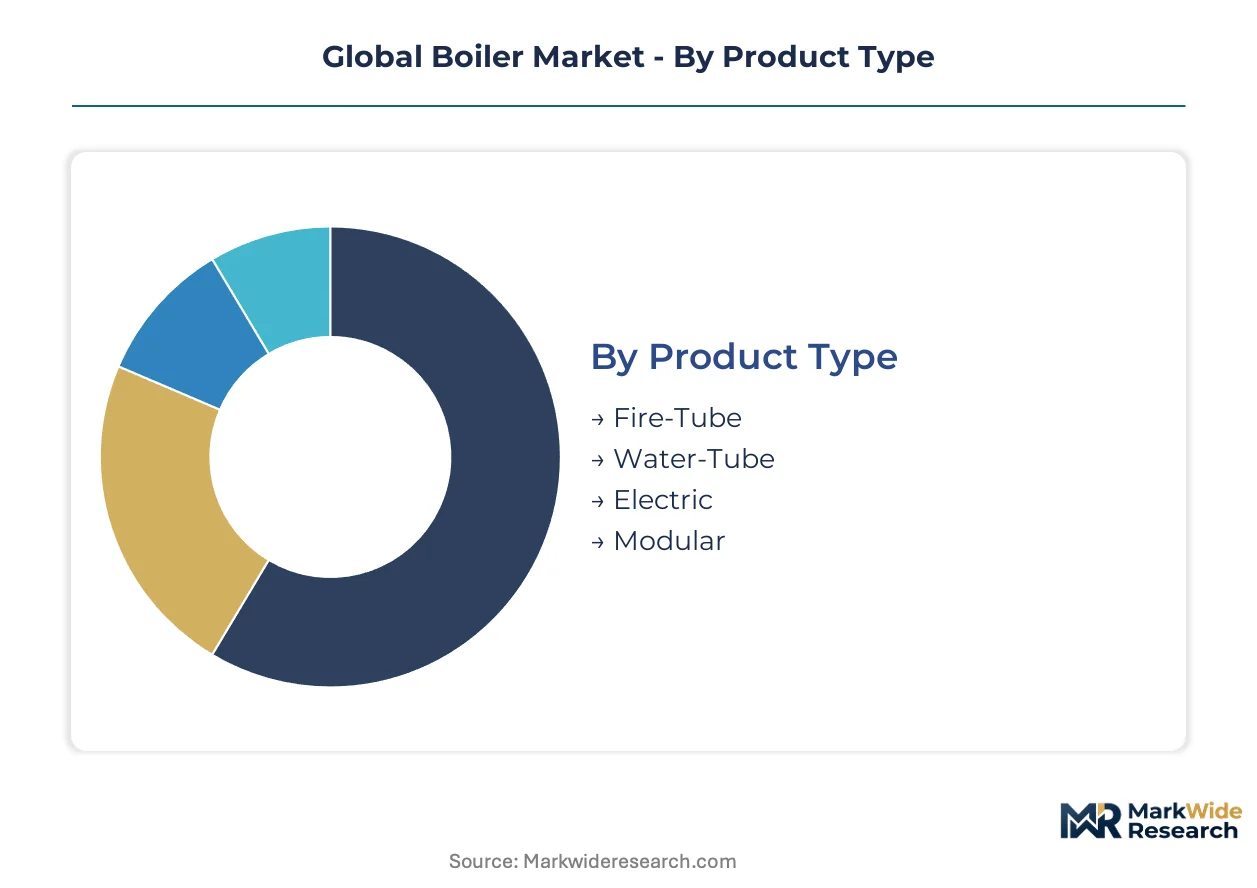
Boiler procurement decisions split sharply between standalone replacement cycles and integrated plant engineering. Vendors must calibrate R&D and service architectures to these divergent deployment modes.
Product Type:
Standalone units dominate residential and light commercial retrofits, while embedded configurations anchor industrial process and power generation installations.
- Fire-Tube:Hot gases pass through tubes immersed in a water-filled shell, producing steam or hot water at pressures below 300 psi. Demand clusters in North American commercial buildings and European district heating retrofits where the EU Ecodesign Directive accelerates non-condensing unit replacement.
- Water-Tube:Water circulates through tubes exposed to combustion gases, enabling supercritical pressures above 3,200 psi for utility-scale power generation. Chinese and Indian thermal power operators specify these configurations for baseload capacity additions.
- Electric:Resistance or electrode elements deliver steam without combustion emissions. German and Dutch new construction mandates are expanding this category fastest.
- Modular:Skid-mounted, factory-tested units reduce field installation complexity. Hospital and university campus operators in the United States favor these for phased capacity expansion.
Volume placements concentrate in Fire-Tube; the faster expansion belongs to Modular.
End User:
Capital intensity and operating pressure requirements separate heavy industrial buyers from building services procurement.
- Manufacturing:Food processing, pharmaceutical, and chemical plants require saturated steam for sterilization, drying, and reaction heating. German and Japanese automotive suppliers specify high-purity steam systems with predictive maintenance contracts.
- Power Generation:Utility and independent power producers operate supercritical boilers for baseload electricity. Chinese state-owned utilities dominate new capacity additions while US operators focus on emissions retrofit.
- Residential:Single-family and multi-family buildings specify compact wall-hung or floor-standing units. Italian and Polish markets drive condensing gas boiler replacement cycles.
- Commercial:Office buildings, hotels, and hospitals prioritize redundancy and part-load efficiency. UK facility managers are bundling heat pump-boiler hybrids into renovation tenders.
Manufacturing commands the largest installed base; Power Generation absorbs the highest per-unit engineering value.
Fuel Type:
Regulatory phase-out timelines and infrastructure availability determine fuel switching economics across geographies.
- Natural Gas:Cleanest fossil option with established pipeline networks. US EPA NESHAP compliance is accelerating coal-to-gas conversions in industrial boiler fleets.
- Oil:Residual and distillate fuels serve remote or peak-load applications. Northeast US heating oil markets are contracting as electrification mandates advance.
- Biomass:Wood chip and pellet combustion qualifies for renewable energy incentives. Finnish and Swedish district heating operators anchor demand through carbon pricing advantages.
- Coal:Bituminous and sub-bituminous firing persists in emerging market power generation. China's MEE restrictions on new urban permits are compressing this segment fastest.
Natural Gas retains volume leadership; Biomass is climbing the fastest on decarbonization policy support.
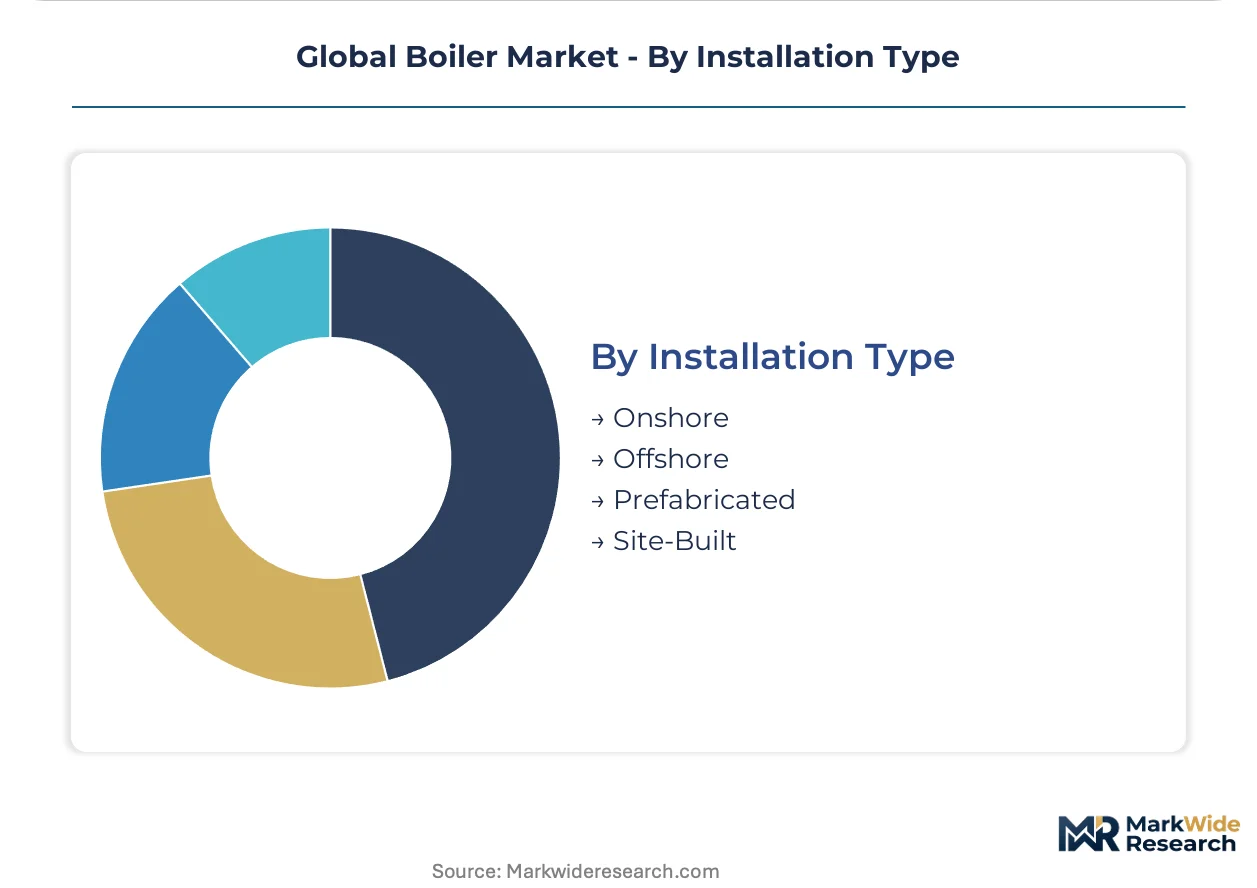
Installation Type:
Project delivery method shapes margin structure and vendor-customer relationship intensity.
- Onshore:Land-based installation within continental infrastructure networks. German and US industrial sites specify these for accessible maintenance and regulatory inspection.
- Offshore:Platform-mounted units for oil and gas production and marine power. North Sea operators demand compact, corrosion-resistant designs with remote monitoring integration.
- Prefabricated:Factory-assembled modules minimize field labor and schedule risk. Indian smart city initiatives are importing European packaged plant expertise under local manufacturing partnerships.
- Site-Built:Custom field erection for unique capacity or footprint constraints. Utility-scale projects in Poland and Romania require this approach for grid integration timelines.
Prefabricated solutions are gaining share fastest; Site-Built retains dominance in utility-scale applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of utility-scale boiler pressure vessels while Germany and the United States absorb the highest-value retrofit engineering. This production-consumption divide shapes trade flows and service revenue capture across the industry.
Germany
District heating network expansions in Berlin and Hamburg drive condensing boiler replacement cycles. The EU Ecodesign Directive enforces minimum efficiency thresholds that phase out non-condensing gas units nationwide. Bavarian industrial clusters around Munich anchor demand for high-purity steam systems in automotive supplier plants.
China
State-owned utilities dominate supercritical coal-fired capacity additions for baseload power generation. The Ministry of Ecology and Environment enforces dual carbon goals that restrict new coal boiler permits in urban clusters. Yangtze River Delta manufacturing hubs around Shanghai concentrate heat exchanger fabrication for export markets.
United States
Industrial boiler operators face EPA National Emission Standards for Hazardous Air Pollutants compliance deadlines that accelerate coal-to-natural-gas conversions. Food processing facilities in the Midwest secure long-term service contracts for saturated steam reliability. Texas petrochemical corridors anchor demand for high-pressure process steam systems.
India
Smart city initiatives in Delhi and Mumbai create first-mover openings for packaged district heating plant suppliers. The Bureau of Indian Standards enforces pressure vessel certification that shapes import specifications for European OEMs. Gujarat pharmaceutical manufacturing clusters require high-purity steam systems with predictive maintenance integration.
Poland
Coal-dependent district heating operators face EU Industrial Emissions Directive retrofit deadlines that drive selective catalytic reduction upgrades. Grid capacity constraints limit electric boiler deployment despite national electrification targets. Silesian industrial basins concentrate biomass co-firing pilot programs for carbon pricing compliance.
Global Boiler Market Vendor Landscape
Top-tier vendors anchor premium engineering-led segments, while mid-tier fabricators compete on modular standardization and local service density. The vendor base stratifies across three tiers: multinational OEMs with integrated control platforms, regional specialists with heat pump-hybrid expertise, and commodity fabricators serving price-sensitive replacement cycles. Strategic archetypes include lifecycle service monetizers, hydrogen-ready technology licensors, and prefabricated plant packagers. Competitive moves concentrate on M&A for control system capabilities and geographic expansion through local manufacturing partnerships.
Within the multinational OEM tier, Bosch Thermotechnology and Viessmann Climate Solutions exemplify platform-integrated service models. Babcock & Wilcox Enterprises occupies a position among engineering-led retrofit specialists serving utility-scale operators. These three names represent divergent archetypes: cloud-connected lifecycle monetization, European heat pump-hybrid integration, and supercritical pressure vessel engineering.
| Leading Market Players |
|---|
| Bosch Thermotechnology |
| Viessmann Climate Solutions |
| A.O. Smith Corporation |
| Babcock & Wilcox Enterprises |
| Vaillant Group |
| Mitsubishi Heavy Industries |
| Siemens |
| Cleaver-Brooks |
| Thermax Limited |
| Others |
Supply Flow & Price Mechanics
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating refrigerant containment certification that only ASME-authorized fabricators can satisfy. German and Italian OEMs command 15-20% price premiums for Ecodesign-compliant condensing units while Chinese commodity producers serve price-sensitive replacement cycles in Eastern Europe.
Pricing Analysis
Margin tightening in the standard equipment tier reflects copper and steel input volatility exceeding 40% annually. Project-based pricing dominates utility-scale water-tube contracts while modular electric boilers command subscription-tied service bundles. Price differentiation separates CE-marked condensing systems from uncertified economy units. Manufacturing buyers in food processing show lowest price sensitivity due to production continuity requirements; residential retrofit segments exhibit highest sensitivity to upfront capital outlay.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale utility demand while distributor networks serve fragmented commercial replacement markets. Heat exchanger fabrication concentrates in China, Germany, and South Korea. High-alumina refractory supply draws from Henan province, China. Copper and steel sourcing rests on commodity exchange pricing with limited hedge coverage. Tariff exposure on Chinese pressure vessel imports creates procurement risk for European project developers. Distribution runs through authorized service partners for warranty-integrated installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Boiler Market operates as a cost-of-compliance story where EPA NESHAP and EU Ecodesign Directive enforcement creates barrier-to-entry moats for certified fabricators. Players lacking ASME Section IX qualification face exclusion from premium utility and industrial segments.
For Market Incumbents: Cement control over hydrogen-ready burner technology through captive R&D investment in Dutch and UK pilot programs. Acquire specialized refractory suppliers to secure rebuild component availability against Henan province concentration risk. Defensive consolidation around predictive maintenance platforms protects recurring revenue from third-party service unbundling.
For New Entrants and Emerging Players: Polish district heating operators facing EU Industrial Emissions Directive retrofit deadlines represent an underserved buyer archetype with urgent compliance-driven procurement. Indian smart city packaged plant tenders offer white-space entry through local manufacturing partnerships. Target remote monitoring platform licensing as the go-to-market angle for multi-site facility operators in Australia and the United Kingdom.
For Investors and Strategic Acquirers: First commercial hydrogen co-firing contracts exceeding 20% blend rates are the leading indicator that burner retrofit technology will command acquisition premiums. Five-to-ten year viability favors engineering-led service monetizers over pure equipment fabricators. Target acquisition archetype: cloud-connected control platform specialists with installed base access. Watch ASME Section IX examiner availability gaps as the signal for manufacturing capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump-Boiler Hybrid Integration | German and Swedish utilities bundle bivalent configurations into building renovation subsidies. |
| Predictive Maintenance Platform Launch | Bosch Thermotechnology leverages cloud-connected controls to sustain recurring revenue streams. |
| Hydrogen-Ready Burner Retrofit | Dutch and UK pilot programs validate 20-30% hydrogen co-firing for existing installed bases. |
| Local Manufacturing Partnership | Indian smart city initiatives reduce import duty exposure for European packaged plant suppliers. |
| Selective Catalytic Reduction Upgrade | Polish coal-dependent operators face EU Industrial Emissions Directive compliance deadlines. |
Methodological Framework
Document review covered trade association filings, customs data, and regulatory dockets from EPA and EU ECHA, complemented by interviews with plant engineering directors, OEM procurement managers, aftermarket service heads, and district heating network operators. Secondary validation drew from ASME certification records, Ecodesign compliance databases, and utility capex disclosures. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Installed base projections and replacement cycle modeling produced volume and value trajectories segmented by product architecture, fuel compatibility, end-use vertical, and regional regulatory cluster. CAGRs derived from historical replacement patterns and mandate-driven phase-out timelines. Industry-specific forecast inputs included hydrogen infrastructure deployment schedules and ASME examiner capacity constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electrification mandate acceleration and grid capacity expansion timelines. Base assumptions reflect current enforcement trajectories for EPA NESHAP and EU Ecodesign Directive compliance. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Industrial Boiler MRO Market
Boilers
Germany Combined Heat and Power Market
Boilers
Power Plant Boiler Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
North America and Europe Electric Boilers Market
Boilers
Biomass Boiler Market
Boilers
US Commercial Boiler Market
Boilers
Residential Boiler Market
Boilers
Micro Combined Heat and Power (CHP) Market
Boilers
Superheater Tubes Market
Boilers
Fuel Operated Heaters Market
Boilers
Power Boiler Market
Boilers
Industrial Biomass Boiler Market
Boilers
Utility Boiler Market
Boilers
Boiler Combustion Chamber Market
Boilers
Coal-Saving Combustion-Supporting Agent Market