
 Marine Seismic Equipment and Acquisition Market | 2026-2036
Marine Seismic Equipment and Acquisition Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Seismic Equipment and Acquisition Market Outlook
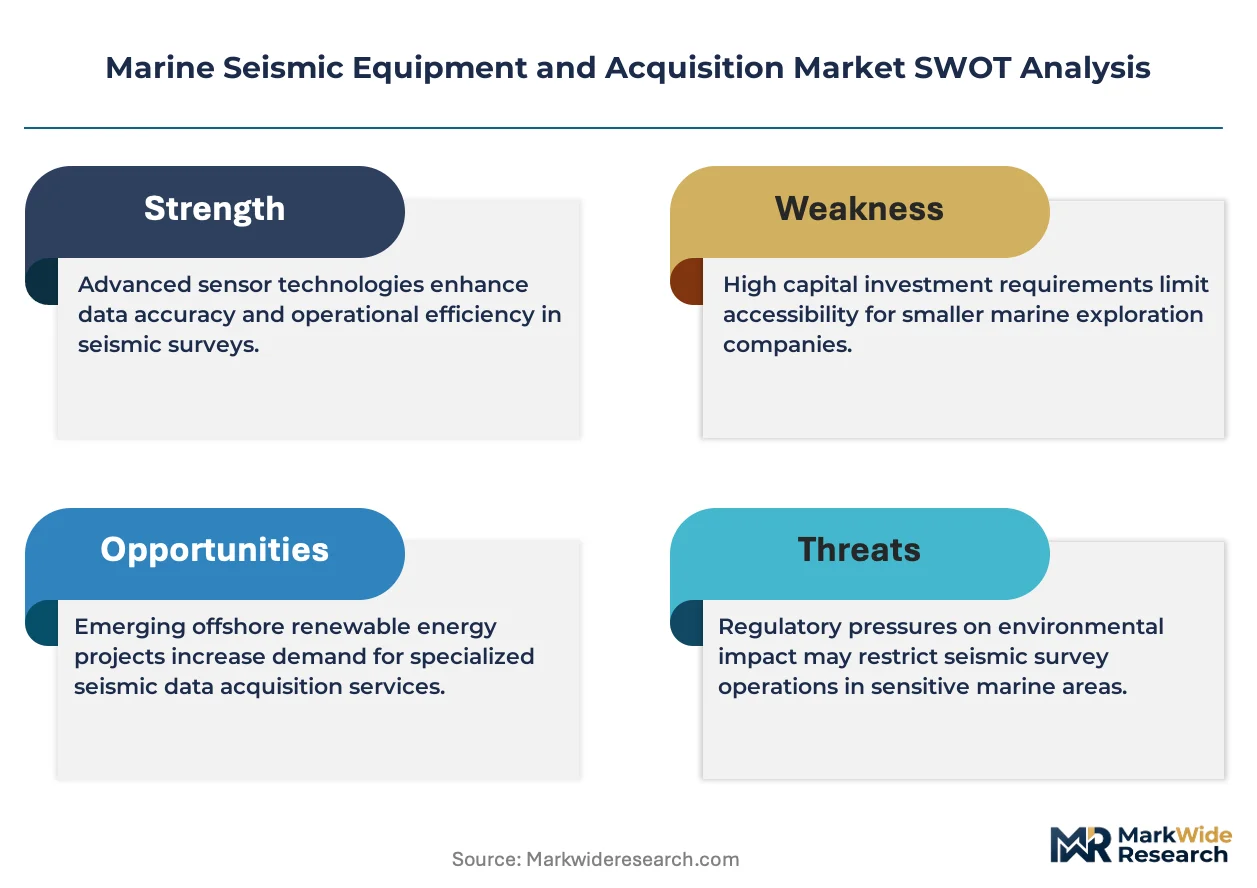
High-resolution 4D time-lapse specification tiers is collapsing the gap between exploration-grade and reservoir-monitoring contracts, forcing fleet operators to upgrade sensor density and source repeatability. PGS ASA leverages its Ramform vessel architecture to sustain wide-azimuth acquisition economics in mature basins. Schlumberger Limited anchors integrated processing-to-interpretation workflows that compete on cycle-time reduction rather than day-rate alone. Shearwater GeoServices differentiates through proprietary source technology and lean-crewed vessel operations.
Marine seismic equipment and acquisition encompasses the integrated systems of towed streamer arrays, controlled acoustic sources, hydrophone receivers, and data recording platforms used to map sub-seafloor geological structures through reflected sound-wave analysis, typically operating at frequencies between 5 Hz and 200 Hz depending on target depth and resolution requirements. The primary commercial purpose is to de-risk hydrocarbon exploration and optimize field development by generating subsurface images spanning tens of kilometers in width and several kilometers in depth. Streamer-based equipment categories still dominate contract value, though 4D seismic technology commands premium pricing where reservoir management demands repeatability standards below three meters source-position deviation. Deep-water deployment methods represent the fastest-growing structural segment as pre-salt and subsalt plays in ultradeath environments require longer offset spreads and higher channel counts.
Offshore regulatory frameworks from the US Bureau of Ocean Energy Management, Brazil's National Petroleum Agency, and Norway's Petroleum Safety Authority shape vessel permitting timelines, environmental mitigation requirements, and data ownership structures that directly influence acquisition scheduling and contract terms. The International Maritime Organization's greenhouse gas strategy is forcing vessel operators to document fuel consumption and emissions profiles as pre-qualification criteria in national licensing rounds. Stakeholders must monitor how carbon accounting rules reshape fleet renewal decisions and whether national oil companies begin bundling emissions thresholds into seismic tender specifications.
Market Dynamics
The International Maritime Organization's carbon intensity regulations are compressing vessel utilization rates and forcing fleet operators to retire older tonnage ahead of schedule, reshaping contract economics across the acquisition services layer.
Growth Catalysts
- Pre-salt licensing rounds:Brazil's National Petroleum Agency has accelerated concession auctions in the Santos Basin, triggering multi-year 3D and 4D seismic commitments from international operators.
- Wide-azimuth specification:Reservoir imaging requirements now demand azimuthal coverage exceeding 60 degrees, expanding channel-count per streamer and equipment refresh cycles.
- IMO 2023 GHG Strategy:The maritime emissions framework is disqualifying fuel-inefficient vessels from national oil company tender pre-qualification, advantaging modernized fleets.
Market Restraints
- High-specification streamer manufacturing:Solid-state hydrophone arrays and advanced telemetry electronics concentrate among a limited supplier base, creating lead-time vulnerability.
- Deep-water operational complexity:Ultradeath deployments beyond 3,000 meters require specialized handling systems and extended offset spreads that constrain vessel productivity per day.
- Substitution from permanent reservoir monitoring:Seabed-emplaced ocean-bottom cable systems are capturing repeatability-sensitive 4D contracts that previously defaulted to towed streamer acquisition.
Strategic Opportunities
- Guyana-Suriname basin expansion:ExxonMobil and consortium partners are licensing contiguous blocks requiring systematic 3D coverage in a frontier province with minimal legacy data.
- Electrification of source arrays:Battery-powered seismic source vessels are converging with offshore wind installation fleets, enabling dual-use asset strategies and harbor infrastructure sharing.
- Carbon credit stacking:Emissions-reduction documentation from fuel-efficient acquisition programs may qualify for voluntary carbon market monetization, creating ancillary revenue streams.
Industry Challenges
- Geophysicist specialization gap:4D time-lapse processing and quantitative interpretation expertise remains concentrated among retiring cohorts, constraining quality-assured crew scaling.
- Multi-client data library amortization:Pre-funded speculative surveys require extended sales cycles to recover acquisition costs, pressuring working capital during licensing round droughts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Seismic Equipment and Acquisition Market |
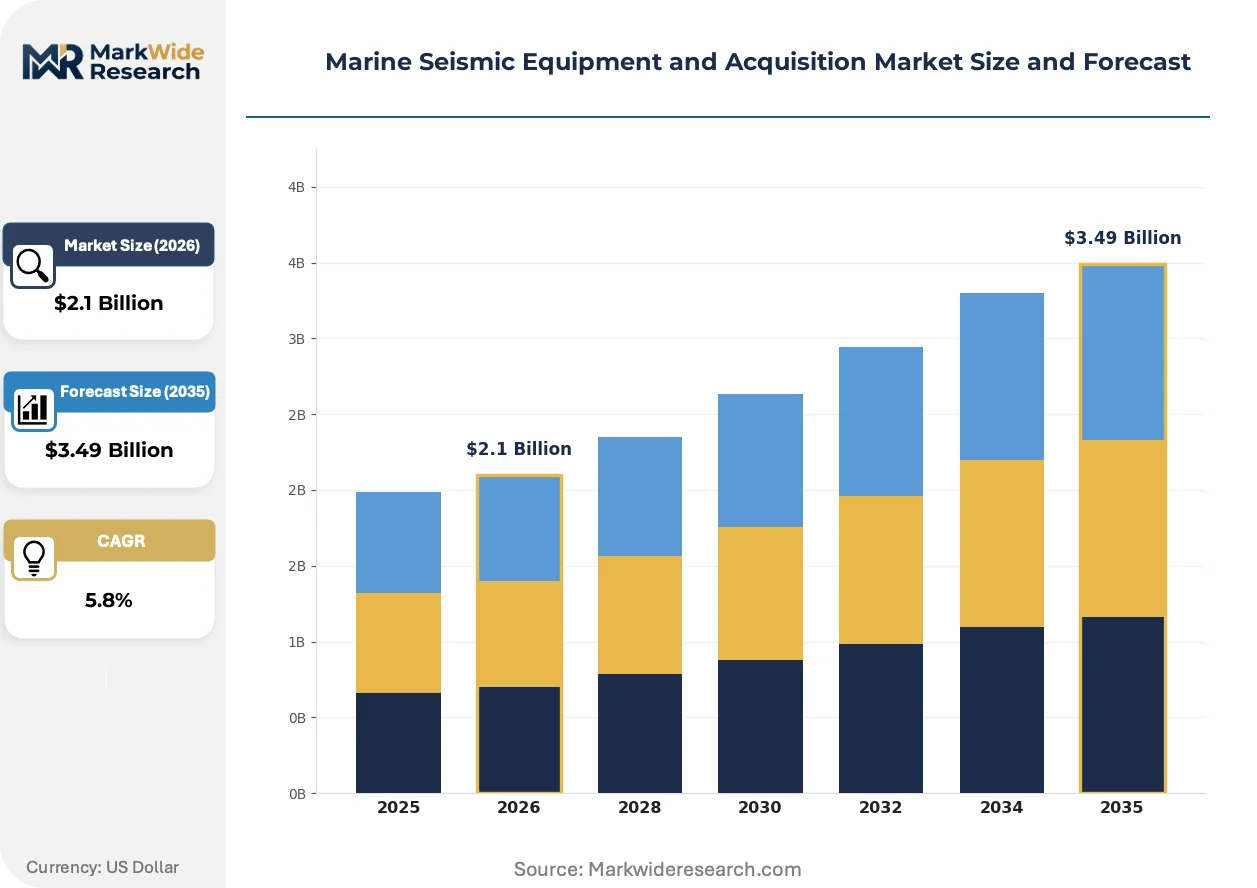
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Streamers, Hydrophones, Acoustic Sources, Recording Systems Technology: 2D Seismic, 3D Seismic, 4D Seismic, Non-linear Signal Processing End User: Oil & Gas Companies, Marine Survey Providers, Military Applications, Research Institutes Deployment Method: Offshore, Nearshore, Shallow Water, Deep Water |
| Companies Covered | CGG, Schlumberger Limited, PGS ASA, Shearwater GeoServices, Fugro N.V., TGS-NOPEC Geophysical Company ASA, ION Geophysical Corporation, Seabird Exploration Group, Sercel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Seismic Equipment and Acquisition Market Strategic Shifts
Seismic acquisition technology is bifurcating between ultra-high-density reservoir monitoring specifications and cost-optimized exploration-grade systems, compressing the viable middle tier of equipment offerings.
Multi-sensor streamer technology combining hydrophone, geophone, and accelerometer measurements is displacing conventional pressure-only arrays in pre-salt and subsalt imaging contracts. Petrobras and international partners operating Brazil's Santos Basin now mandate full-wavefield acquisition for new licensing commitments. The technology is displacing single-sensor streamer inventories and forcing equipment lessors into accelerated capital refresh cycles.
The International Maritime Organization's carbon intensity indicator framework is imposing documented emissions reporting as a contractual precondition in Norwegian and UK North Sea licensing rounds. Vessel operators must submit verified fuel consumption profiles to national petroleum regulators before bid qualification. Deep-water contractors with older diesel-electric propulsion face exclusion from state-backed exploration programs.
Integrated acquisition-to-processing service bundling is compressing the traditional vendor separation between field operations and data imaging. National oil companies in Brazil and Norway now specify single-accountability contracts covering source-to-migration workflows. This consolidation is most visible in Petrobras tender structures, where cycle-time guarantees outweigh day-rate competition in award criteria.
Marine Seismic Equipment and Acquisition Market Segmentation
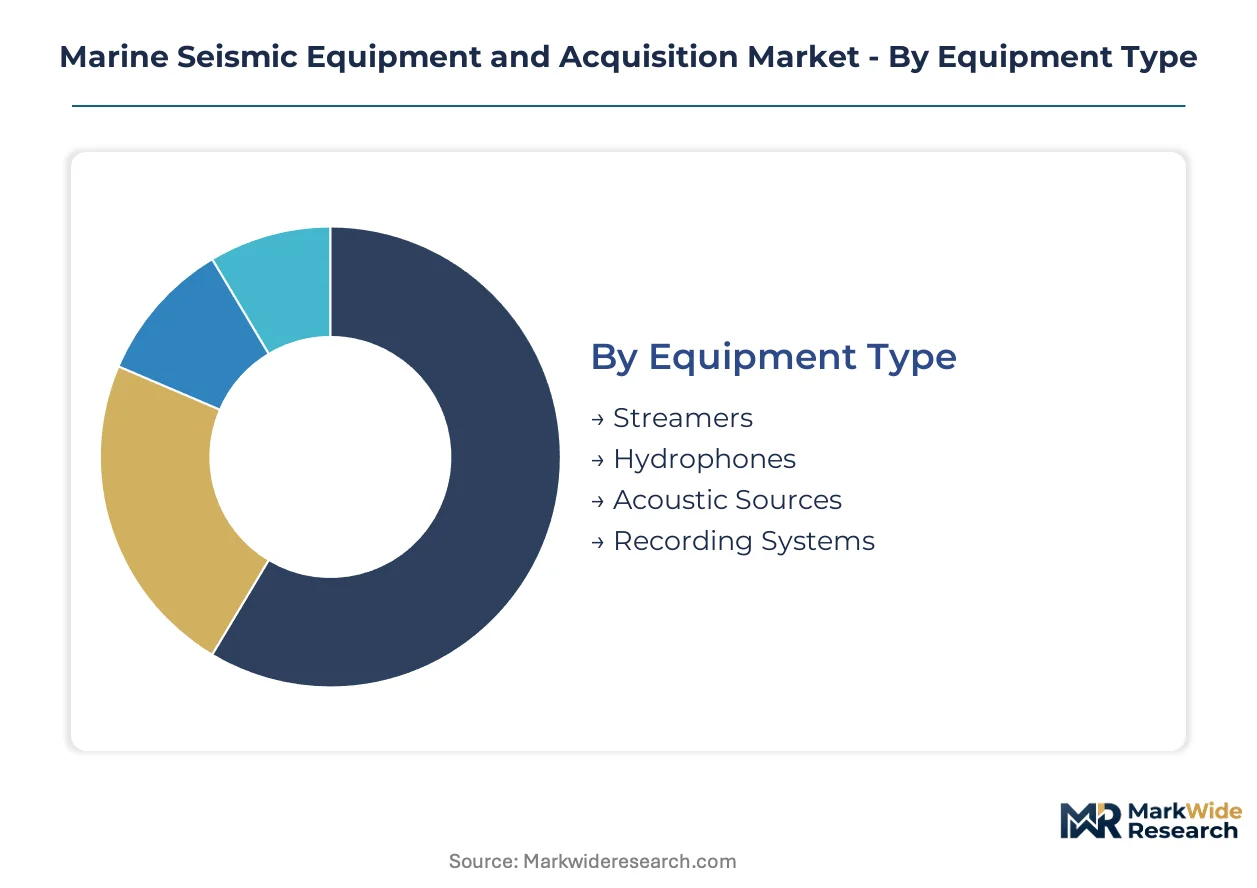
Segmentation in marine seismic equipment reveals distinct procurement patterns across exploration versus reservoir monitoring workflows. Equipment type and technology tiers channel through fundamentally different contract structures, with 4D specifications commanding multi-year service agreements while 2D/3D systems rotate through shorter exploration campaigns.
Equipment Type:
Streamers and hydrophones flow through integrated vessel charter contracts, while acoustic sources and recording systems often separate into specialized supplier relationships with distinct margin profiles.
- Streamers:Towed hydrophone arrays with channel counts ranging from 6,000 to over 12,000 per vessel, now incorporating solid-state sensor technology for improved reliability. Demand concentrates in Brazil's Santos Basin, where Petrobras mandates wide-azimuth spreads exceeding 10 kilometer streamer lengths for pre-salt imaging. The shift toward multi-sensor streamers combining pressure and particle motion measurements is accelerating replacement cycles.
- Hydrophones:Piezoelectric and MEMS-based pressure sensors forming the detection layer within streamer arrays, with calibration stability specifications tightening for 4D repeatability contracts. Norway's Petroleum Safety Authority now requires traceable calibration documentation for all seabed-emplaced sensors, tightening qualification barriers for non-integrated suppliers.
- Acoustic Sources:Air-gun arrays and emerging marine vibroseis systems generating controlled seismic energy, with source signature repeatability becoming the critical specification for time-lapse surveys.
- Recording Systems:High-capacity data acquisition platforms managing telemetry from distributed sensor networks, with real-time quality control capabilities now standard for deep-water operations.
By volume, streamers lead equipment procurement. By growth pace, acoustic sources incorporating electrification and signature control are expanding most quickly.
Technology:
Technology selection maps directly to project economics, with 2D and 3D systems competing on cost-per-kilometer while 4D and advanced processing command value-based pricing tied to reservoir outcomes.
- 2D Seismic:Single-vessel reconnaissance surveys providing regional structural mapping at lowest acquisition cost per line-kilometer. Frontier basin licensing in Guyana-Suriname is sustaining contract flow for 2D programs ahead of detailed 3D commitments.
- 3D Seismic:Multi-vessel wide-azimuth acquisition generating volumetric subsurface images, now standard for field development planning in all major offshore provinces. Brazil's pre-salt province anchors global 3D demand, with Petrobras and international partners committing to systematic coverage across contiguous blocks.
- 4D Seismic:Time-lapse repeat surveys monitoring reservoir fluid movement, with source-position repeatability specifications below three meters commanding premium pricing. The North Sea and Gulf of Mexico concentrate 4D activity where mature fields require production optimization.
- Non-linear Signal Processing:Advanced algorithms extracting signal from complex geologies including subsalt and basalt-covered sequences, increasingly bundled with acquisition contracts rather than sold as separate processing services.
3D seismic dominates current contract value. 4D seismic shows the steepest expansion trajectory as reservoir management displaces pure exploration in capital allocation.
End User:
End-user segmentation reflects divergent procurement sophistication, with supermajors internalizing technical specifications while survey providers compete on fleet utilization and research institutes prioritize equipment access over ownership.
- Oil & Gas Companies:Integrated operators and independents specifying acquisition parameters, with national oil companies in Brazil and Norway increasingly mandating integrated source-to-migration accountability. ExxonMobil's Guyana-Suriname program exemplifies the shift toward multi-year, basin-scale seismic commitments.
- Marine Survey Providers:Specialized contractors including PGS ASA, Shearwater GeoServices, and WesternGeco competing on vessel efficiency, sensor density, and cycle-time guarantees. The International Maritime Organization's carbon intensity regulations are reshaping fleet qualification criteria in tender processes.
- Military Applications:Naval seabed mapping and submarine detection programs, with procurement classified and specifications emphasizing low-frequency penetration and covert operational signatures.
- Research Institutes:Academic and governmental oceanographic programs, with equipment access typically through shared-use facilities rather than dedicated acquisition.
Oil and gas companies generate the largest contract flow. Marine survey providers are gaining share fastest as integrated service bundling displaces direct operator procurement.
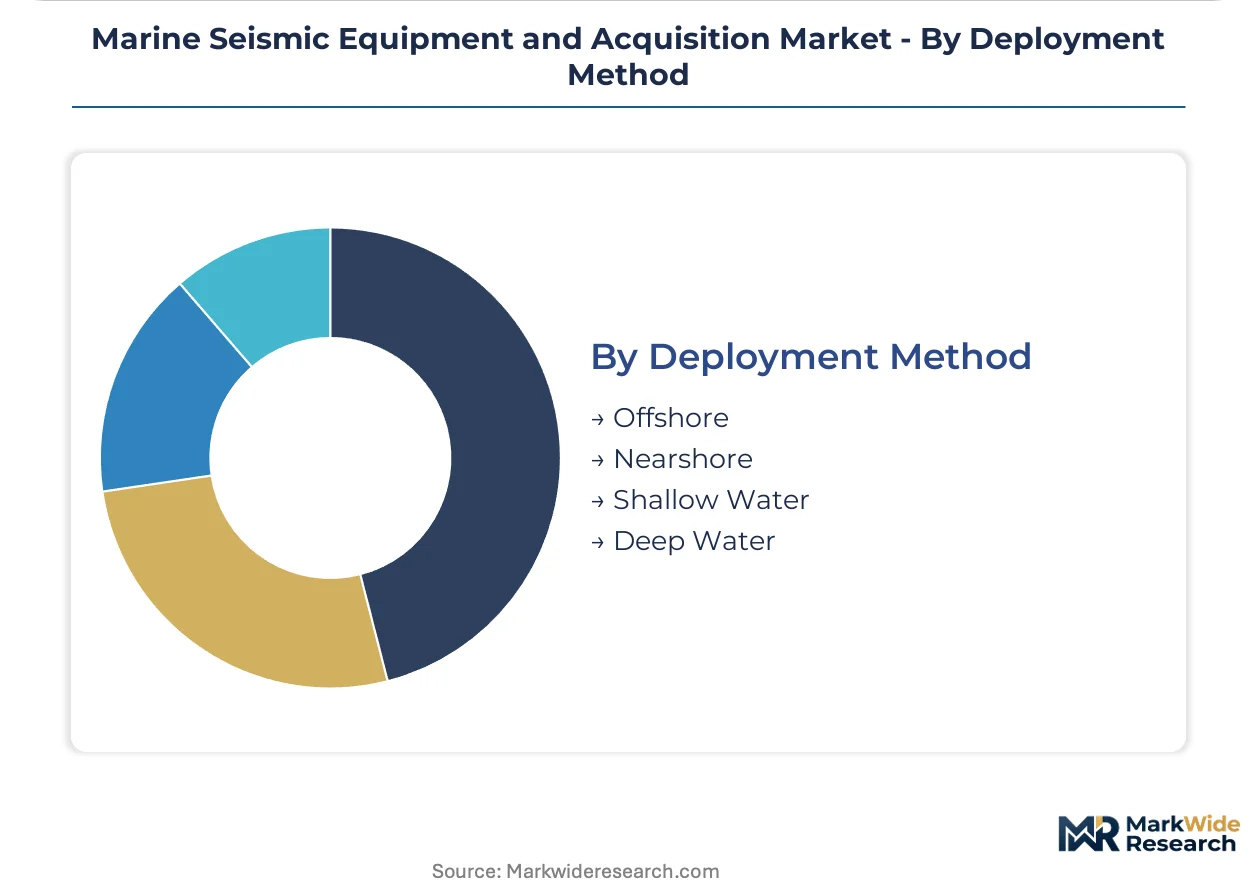
Deployment Method:
Deployment depth tiers separate equipment specifications dramatically, with deep-water systems requiring specialized handling infrastructure and environmental mitigation protocols that shallow-water programs avoid.
- Offshore:Open-ocean operations beyond territorial waters, representing the core revenue base for major acquisition contractors. Regulatory frameworks from the US Bureau of Ocean Energy Management and Brazil's National Petroleum Agency shape permitting timelines and environmental mitigation requirements.
- Nearshore:Coastal transition zones with mixed regulatory oversight, where vessel traffic coordination and fisheries interaction protocols constrain operational windows.
- Shallow Water:Continental shelf environments generally above 200 meters depth, where conventional streamer systems operate without specialized deep-water handling equipment.
- Deep Water:Ultradeath deployments beyond 3,000 meters, requiring extended offset spreads, higher channel counts, and dynamic positioning systems capable of maintaining station in challenging current regimes. Brazil's pre-salt province anchors global deep-water demand.
Offshore deployment handles the greatest survey kilometerage. Deep water is climbing the fastest as pre-salt and subsalt plays push technical boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment export flows concentrate in Norway and France, while Brazil and the United States anchor import demand for deep-water acquisition services. Trade balances tilt toward vessel-operating jurisdictions with integrated manufacturing bases. Regional procurement patterns diverge sharply between state-backed exploration programs and speculative multi-client data licensing.
Norway
Stavanger and Bergen host the world's densest cluster of seismic vessel operators and streamer manufacturers. The Petroleum Safety Authority mandates emissions documentation as a pre-qualification criterion for North Sea licensing rounds. Kongsberg Maritime supplies dynamic positioning systems to acquisition fleets operating across the Barents Sea and Norwegian Sea.
Brazil
Petrobras commits to systematic 3D and 4D coverage across the Santos Basin pre-salt province, driving equipment import demand. The National Petroleum Agency accelerates concession auctions with multi-year seismic work commitments. Rio de Janeiro anchors service provider headquarters for deep-water operations in ultradeath environments exceeding 3,000 meters.
United States
Gulf of Mexico lease sales sustain demand for wide-azimuth acquisition and time-lapse reservoir monitoring. The Bureau of Ocean Energy Management extends permitting timelines for seismic surveys in frontier Alaskan waters. Houston concentrates corporate headquarters for integrated acquisition-to-processing service providers bidding on federal acreage.
United Kingdom
North Sea decommissioning schedules compress remaining 4D seismic windows for mature field optimization. The North Sea Transition Authority bundles emissions thresholds into tender specifications for seismic contractors. Aberdeen maintains its position as the primary service hub for UK continental shelf operations despite declining exploration drilling.
France
Paris-based equipment manufacturers export solid-state streamer technology to Brazilian and Norwegian acquisition programs. The General Directorate for Energy and Climate oversees carbon intensity reporting requirements for French-flagged survey vessels. Toulon hosts specialized facilities for acoustic source array calibration and maintenance serving Mediterranean and West African contracts.
Marine Seismic Equipment and Acquisition Market Competitive Environment
Listed leaders compete with private specialists across vessel ownership and technology licensing dimensions. The vendor base organizes around three archetypes: integrated energy service conglomerates with processing-to-interpretation workflows, pure-play seismic contractors competing on fleet utilization, and equipment specialists manufacturing streamer arrays and source systems. Consolidation pressure operates through vessel fleet renewal cycles and multi-client data library amortization requirements. Strategic moves concentrate on emissions-compliant fleet modernization and integrated service bundling for national oil company tenders.
Within the listed-company tier, PGS ASA and Shearwater GeoServices occupy positions as pure-play seismic contractors with differentiated vessel architectures. Schlumberger Limited exemplifies the integrated service model anchoring processing capabilities to acquisition operations. These three entities represent distinct competitive vectors: wide-azimuth vessel economics, proprietary source technology, and cycle-time guarantees respectively.
| Leading Market Players |
|---|
| CGG |
| Schlumberger Limited |
| PGS ASA |
| Shearwater GeoServices |
| Fugro N.V. |
| TGS-NOPEC Geophysical Company ASA |
| ION Geophysical Corporation |
| Seabird Exploration Group |
| Sercel |
| Others |
Value Chain & Pricing Dynamics
Multi-year service agreements with national oil companies lock in both streamer fleet utilization and day-rate visibility across Brazil's Santos Basin and Norway's North Sea licensing rounds. These contract structures insulate vessel operators from spot-market volatility while committing buyers to equipment refresh cycles tied to carbon intensity regulations.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures that stratify across exploration-grade, wide-azimuth, and 4D reservoir-monitoring tiers. Price differentiation hinges on channel-count density and source-position repeatability specifications below three meters, with IMO-compliant vessel certification commanding measurable premiums. Cost compression in legacy 2D/3D tiers is intensifying as older diesel-electric fleets face tender disqualification. National oil companies exhibit lowest price sensitivity due to integrated source-to-migration accountability requirements, while independent operators prioritize cost-per-kilometer metrics.
Supply Chain Analysis
Solid-state hydrophone inventory lead times now stretch eighteen to twenty-four months, constraining fleet expansion timelines for contractors bidding on Petrobras deep-water programs. Manufacturing concentrates in Norway, France, and the United States, with piezoelectric sensor fabrication drawing from specialized semiconductor foundries and advanced telemetry electronics resting on single-source suppliers. Tariff exposure on Chinese-manufactured dynamic positioning components creates procurement vulnerability. Distribution runs through integrated vessel charter contracts rather than discrete equipment sales, with acoustic sources and recording systems separating into specialized supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine seismic equipment and acquisition market is recovering from cyclical lows as offshore exploration budgets rebound and pre-salt licensing rounds accelerate in frontier basins. Vessel fleet renewal cycles and carbon intensity regulations are compressing supply availability faster than demand normalization.
For Market Incumbents: Consolidate fleet ownership around emissions-compliant tonnage while retiring older diesel-electric vessels ahead of IMO disqualification timelines. Secure backward integration into solid-state hydrophone manufacturing to reduce lead-time vulnerability from Norwegian and French sensor suppliers. Lock in multi-year offtake agreements with Petrobras and Equinor before speculative multi-client data libraries flood the market. For New Entrants and Emerging Players: Differentiate on electrified source array technology that converges with offshore wind installation fleets, enabling dual-use asset strategies and harbor infrastructure sharing. Target Guyana-Suriname frontier basin contracts where legacy data scarcity justifies premium pricing for systematic 3D coverage. Pursue carbon credit stacking documentation as a go-to-market wedge, qualifying emissions-reduction programs for voluntary carbon market monetization. For Investors and Strategic Acquirers: Pure-play seismic contractors with proprietary vessel architectures and integrated processing capabilities represent the most defensible acquisition targets in a consolidating vendor landscape. Monitor IMO carbon intensity indicator enforcement as the critical inflection signal—disqualification thresholds will accelerate fleet retirement and concentrate contract flow among modernized operators. Long-term viability rests on exposure to national oil company tender structures rather than speculative multi-client data exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Program | Battery-powered source vessels qualify for IMO carbon intensity thresholds and offshore wind dual-use contracts. |
| Multi-sensor Streamer Refresh | Full-wavefield acquisition mandates from Petrobras displace single-sensor inventories and accelerate capital cycles. |
| Integrated Service Bundling | Single-accountability source-to-migration contracts displace day-rate competition in Brazilian and Norwegian tenders. |
| Carbon Credit Documentation | Emissions-reduction verification creates ancillary revenue streams qualifying for voluntary carbon markets. |
| Deep-water Handling Systems | Specialized deployment infrastructure for ultradeath environments beyond 3,000 meters captures pre-salt contract premiums. |
Study Parameters
Operator-level perspectives from vessel fleet managers, seismic acquisition project directors, Petrobras procurement officers, and IMO regulatory compliance leads anchored the qualitative base. Primary interview insights triangulated against secondary validation from Bureau of Ocean Energy Management permitting databases, ANP concession auction records, Petroleum Safety Authority emissions documentation requirements, and SEC filings from listed seismic contractors. Bottom-up equipment procurement flows and top-down contract value estimates converged through iterative reconciliation.
Sensitivity analysis around channel-count adoption curves and carbon intensity enforcement timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include equipment type, technology tier, deployment depth, and end-user procurement sophistication, with vessel utilization rates and licensing round cadence as industry-specific forecast inputs. CAGRs derived from regression against historical contract awards and stated national oil company seismic work commitments.
The analysis sits within stated boundaries; outcomes outside sustained pre-salt exploration activity or accelerated IMO enforcement would require recalibration. Forecasts reflect assumptions regarding Petrobras capital allocation continuity and frontier basin licensing momentum. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Jack-Up Rigs Market
Offshore Oil and Gas
Asia-Pacific Floating Production Systems Market
Offshore Oil and Gas
Deepwater and Ultra-Deepwater Drilling Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market
Offshore Oil and Gas
Gulf of Mexico Oil & Gas Decommissioning Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
Brazil Oil and Gas Downstream Market
Offshore Oil and Gas
Oman Oil and Gas Downstream Market
Offshore Oil and Gas
Ecuador Oil and Gas Downstream Market
Offshore Oil and Gas
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market
Offshore Oil and Gas
East Africa Oil and Gas Midstream Market
Offshore Oil and Gas
Europe Jackup Rig Market
Offshore Oil and Gas
Offshore Oilfield Services Market
Offshore Oil and Gas
Norway Oil and Gas EPC Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market