
 Space Heating Boilers Market | 2026-2036
Space Heating Boilers Market Size, Share, and Industry Trends Forecast 2026-2036
Space Heating Boilers Market Analytics
Commercial district heating is expanding its share of total boiler procurement as municipalities decarbonize centralized thermal networks. Viessmann Group leverages its German manufacturing base to dominate condensing boiler exports across Central Europe. Bosch Thermotechnology competes through integrated heat pump-boiler hybrid systems that anchor its position in renovation-driven markets. Rheem Manufacturing sustains North American channel control through extensive distributor relationships in the institutional segment.
Space heating boilers are closed-vessel thermal generators designed to heat water or produce steam for distribution through hydronic circuits, typically operating at pressures up to 30 bar and thermal outputs ranging from residential-scale units to industrial megawatt-class systems. Their primary purpose is to provide controllable, efficient space conditioning for buildings and process heat for industrial applications. Gas boilers occupy the largest installed base across European and North American retrofit markets, though electric boilers are gaining structural share where grid decarbonization outpaces building-level fuel switching. Floor-standing installations retain margin concentration in commercial and industrial settings due to higher output requirements and longer replacement cycles.
The EU Green Deal and F-Gas Regulation in Europe, alongside EPA emissions standards in the United States, are tightening minimum efficiency requirements and phasing out high-GWP refrigerants in hybrid systems. These frameworks reshape product portfolios by penalizing conventional atmospheric boilers and rewarding condensing technology with low-NOx burners. Stakeholders must monitor how national transposition timelines for the EU AI Act's building automation mandates will alter control system integration requirements and aftermarket service models.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing replacement cycles for atmospheric boilers while accelerating condensing technology deployment across European building stock renovation programs.
Growth Catalysts
- Retrofit mandates:Germany's municipal building codes now require minimum seasonal efficiency thresholds for new installations, forcing system replacements in the Rhine-Ruhr corridor.
- Heat pump convergence:Hybrid boiler-heat pump systems are capturing renovation-driven demand as households seek decarbonization pathways without full fuel switching.
- District heating expansion:Municipal decarbonization of centralized thermal networks is lifting procurement volumes for high-output commercial boiler systems.
Market Restraints
- Copper and stainless steel volatility:Heat exchanger material costs fluctuate with commodity markets, compressing margins for boiler manufacturers.
- Component concentration:Burner and control module supply concentrates in German and Italian specialist suppliers, creating single-source vulnerabilities.
- Refrigerant phase-down:The F-Gas Regulation's hydrofluorocarbon quotas restrict hybrid system production capacity and extend lead times.
Strategic Opportunities
- Polish residential penetration:Aging coal boiler stock and EU cohesion funding create replacement demand in Silesian and Greater Poland voivodeships.
- Building automation integration:The EU AI Act's transposition timelines will mandate smart control interfaces, opening aftermarket service revenue streams.
- Electrification corridors:Grid-decarbonized zones in France and Nordic markets favor electric boiler deployment where gas infrastructure is sparse.
Industry Challenges
- Combustion engineering talent:Low-NOx burner design expertise concentrates in aging specialist workforces across Central European manufacturing bases.
- Certification lag:CE marking under the MDR and updated efficiency testing protocols extend product approval timelines for condensing variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Heating Boilers Market |
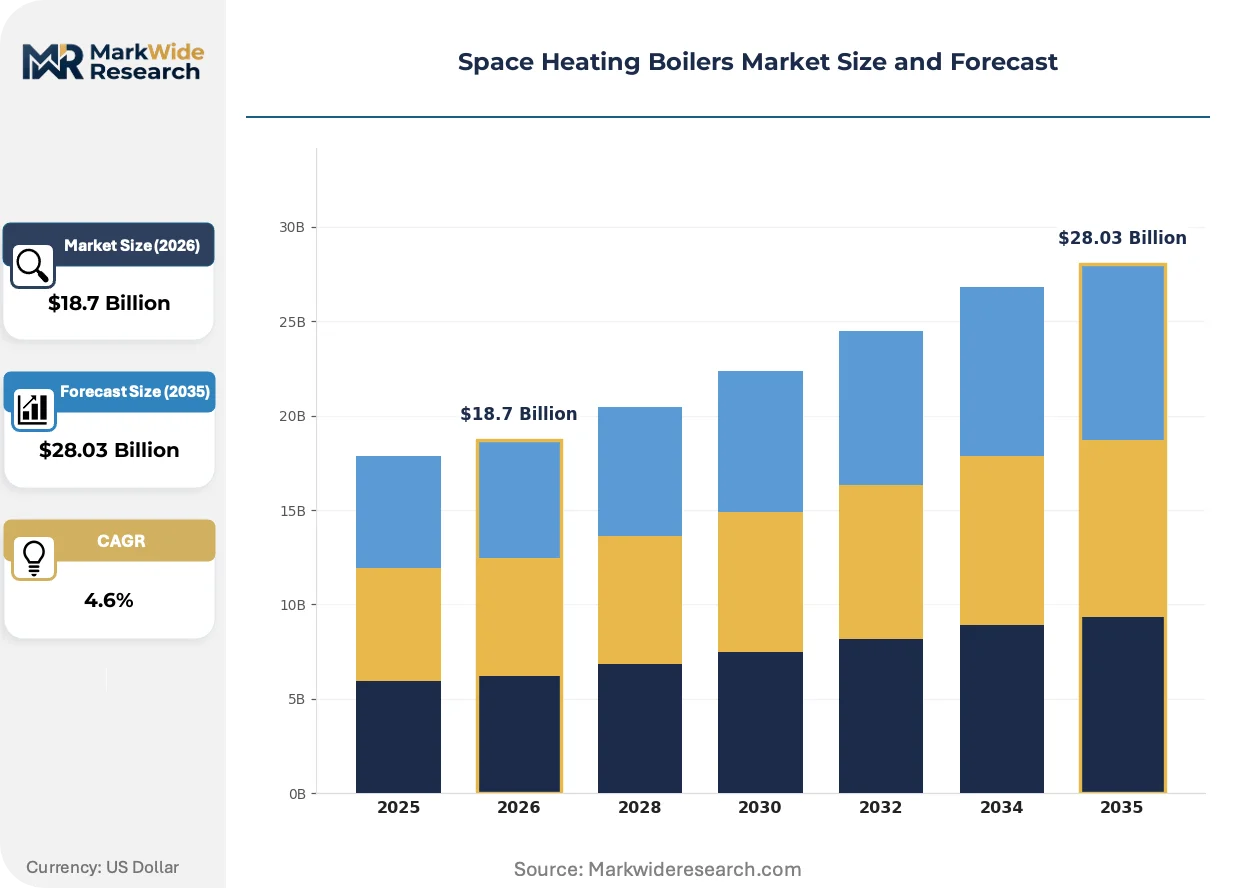
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Boilers, Oil Boilers, Electric Boilers, Biomass Boilers End User: Residential, Commercial, Industrial, Institutional Fuel Type: Natural Gas, Propane, Electricity, Wood Installation Type: Wall-Mounted, Floor-Standing, Modular, Others |
| Companies Covered | Viessmann Group, Lennox International, Daikin Industries, Ltd., Rheem Manufacturing, Vaillant Group, Bosch Thermotechnology, Carrier Global, Johnson Controls, Ingersoll-Rand Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Heating Boilers Market Evolving Landscape
Product architecture is converging around hybrid thermal systems, regulatory pressure is hardening efficiency minimums, and buyer procurement is fragmenting across direct OEM, distributor, and energy-service channels.
Condensing boiler technology is unifying heat generation and heat pump compatibility within single hydronic systems. Residential renovators in Germany and Italy are specifying these units at accelerating rates. This convergence is compressing the addressable market for standalone atmospheric boilers while expanding service contract attach rates.
The F-Gas Regulation's hydrofluorocarbon phase-down is restricting refrigerant choice in hybrid heat pump-boiler combinations. Manufacturers must redesign working fluid circuits and retest efficiency certifications. Commercial segment procurement in France and Benelux markets is delaying hybrid purchases pending regulatory clarity on alternative refrigerants.
Building owners are fragmenting procurement across multiple channels, unbundling equipment purchase from installation and maintenance. Distributor relationships in North American institutional segments face disintermediation from direct OEM engagement and energy-service contracting. Germany's municipal housing associations are piloting this unbundled model for district heating boiler replacements.
Space Heating Boilers Market Segmentation
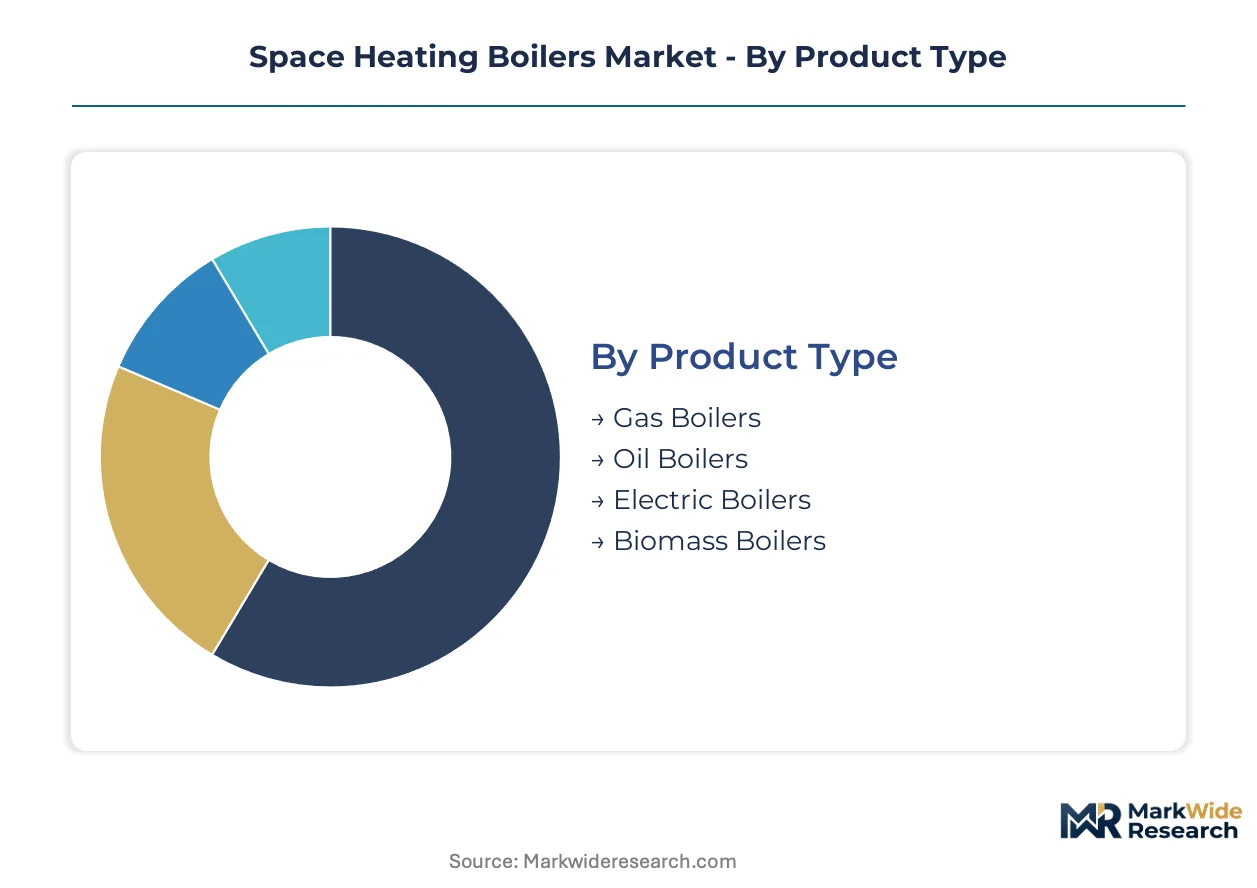
Boiler procurement patterns diverge sharply across building types, fuel infrastructures, and regulatory environments. Segmentation reveals how technology choices cluster around retrofit economics, carbon intensity targets, and installation constraints in distinct end-use contexts.
Product Type:
Buyers in this category separate by fuel access, efficiency mandates, and capital recovery timelines rather than thermal output alone.
- Gas Boilers:Condensing variants with low-NOx burners dominate European retrofit programs. Germany's municipal building codes in the Rhine-Ruhr corridor mandate minimum seasonal efficiency thresholds that only condensing technology satisfies, compressing atmospheric boiler replacement cycles.
- Electric Boilers:Resistance and electrode designs gain traction where grid decarbonization outpaces building-level fuel switching. France and Nordic markets favor deployment in zones with sparse gas infrastructure, though operating cost premiums constrain penetration in wholesale electricity markets.
- Oil Boilers:Declining share in EU markets under Green Deal pressure; residual demand concentrates in rural German and Polish properties lacking grid connectivity.
- Biomass Boilers:Pellet and chip systems serve agricultural and forestry-adjacent installations; feedstock logistics limit scaling beyond district heating anchor loads.
Volume sits with gas condensing units; growth tilts toward electric variants in grid-decarbonized corridors.
End User:
Procurement scale and replacement frequency create four distinct customer archetypes with diverging technical specifications.
- Residential:Single-family and multi-family dwellings drive replacement demand through renovation subsidies. Italian and Polish households specify hybrid boiler-heat pump systems to retain hydronic distribution while meeting efficiency thresholds.
- Commercial:Hotels, offices, and retail spaces prioritize modularity and part-load efficiency. District heating network operators in Benelux markets procure high-output units with extended maintenance intervals.
- Industrial:Process heat applications require pressure-rated vessels and steam capability; longer replacement cycles concentrate margin in aftermarket service contracts.
- Institutional:Schools, hospitals, and government buildings favor floor-standing installations with redundant capacity; North American procurement runs through established distributor relationships with OEM service backing.
Commercial district heating anchors current procurement volumes; residential retrofit programs deliver the steepest expansion trajectory.
Fuel Type:
Energy transition timelines and infrastructure availability lock buyers into distinct fuel pathways with limited switching flexibility.
- Natural Gas:Pipeline connectivity determines addressable market geography. Central European networks support condensing boiler deployment at scale, though hydrogen-readiness specifications are emerging as a procurement filter.
- Propane:Bottled supply serves rural properties beyond grid reach; higher per-unit costs constrain market to backup and off-grid applications.
- Electricity:Grid carbon intensity and time-of-use tariffs shape operating economics. Nordic markets with high renewable penetration favor heat pump-compatible electric boilers as primary heat sources.
- Wood:Localized supply chains and combustion emissions regulations restrict growth to regions with established pellet distribution and particulate control waivers.
Natural gas retains the largest installed base; electricity is climbing the fastest as building codes harden carbon intensity limits.
Installation Type:
Spatial constraints and output requirements divide procurement between compact wall units and engineered floor-standing systems.
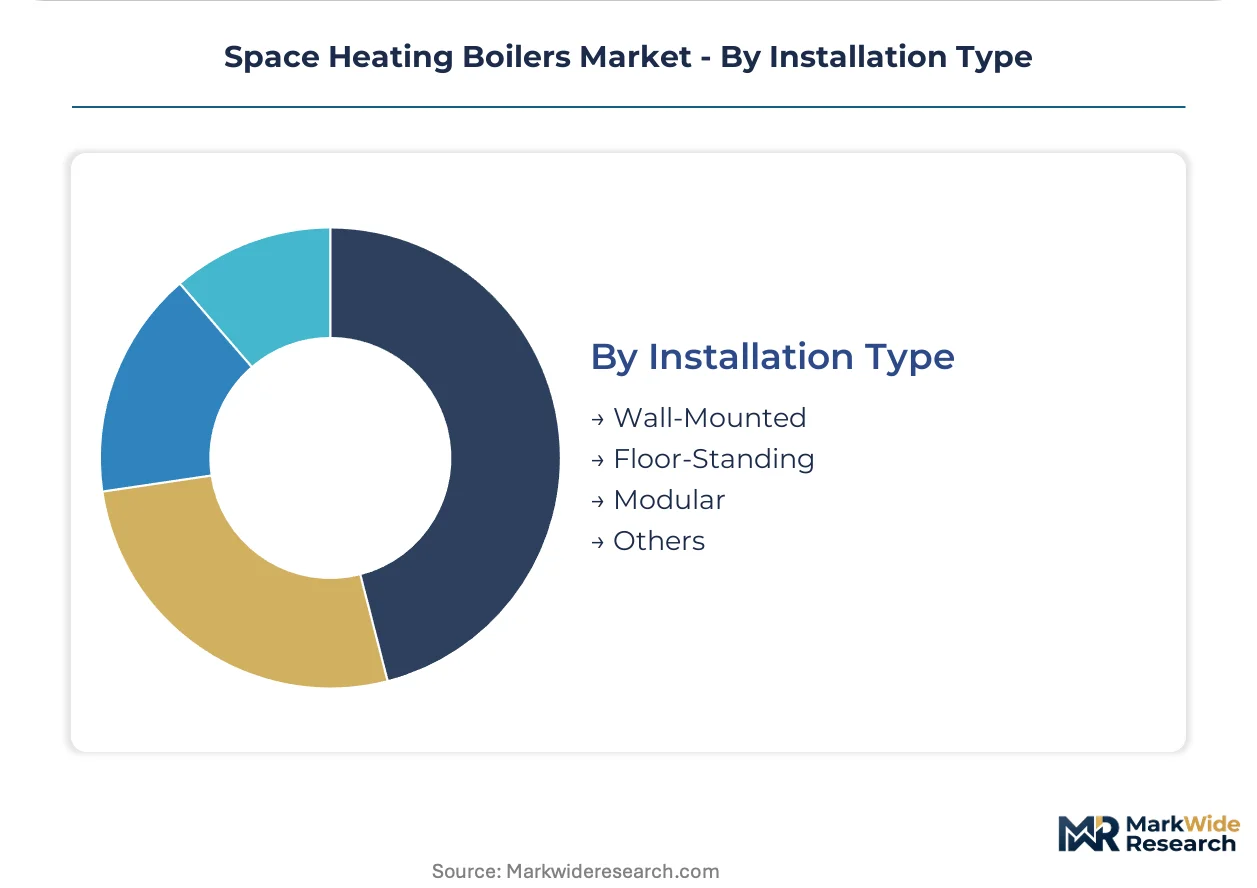
- Wall-Mounted:Compact condensing units dominate residential renovations where utility space is constrained. German and Italian installers favor these for apartment building retrofits with limited plant room access.
- Floor-Standing:Higher thermal outputs and service accessibility anchor commercial and industrial specifications. Margin concentration persists due to longer replacement cycles and custom engineering requirements.
- Modular:Cascaded small-output units offer redundancy and part-load optimization for variable-demand commercial buildings; controls integration determines competitive positioning.
- Others:Specialized configurations including outdoor-rated enclosures and seismic-rated frames serve niche climatic and regulatory environments.
Wall-mounted units capture residential volume; floor-standing configurations defend margin in commercial and industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers supply condensing boiler technology across Central Europe, while residential retrofit demand concentrates in Italy, Poland, and France. Production capacity clusters along the Rhine-Ruhr corridor, but consumption patterns diverge sharply between gas-connected urban cores and rural electrification zones.
Germany
The Rhine-Ruhr corridor drives replacement demand as municipal building codes mandate seasonal efficiency thresholds for new installations. The EU Green Deal and F-Gas Regulation accelerate heat pump-compatible boiler specifications. Manufacturing clusters in North Rhine-Westphalia export condensing systems across Central European retrofit markets.
Italy
Household renovation subsidies propel hybrid boiler-heat pump system specifications in northern industrial cities. The EU AI Act's building automation mandates will reshape control system integration requirements. Installers in Lombardy and Veneto favor compact wall-mounted condensing units for apartment building retrofits with constrained utility space.
Poland
Aging coal boiler stock in Silesian and Greater Poland voivodeships creates replacement demand supported by EU cohesion funding. The F-Gas Regulation's hydrofluorocarbon quotas restrict hybrid system production capacity and extend lead times. Rural properties lacking grid connectivity retain residual oil boiler demand under Green Deal pressure.
France
Grid-decarbonized zones favor electric boiler deployment where gas infrastructure remains sparse, particularly in rural western departments. The EU Green Deal hardens carbon intensity limits for building stock renovation programs. District heating network operators in the Paris Basin procure high-output commercial units with extended maintenance intervals.
United States
EPA emissions standards tighten minimum efficiency requirements for atmospheric boiler replacements across northeastern and midwestern states. Institutional procurement runs through established distributor relationships with OEM service backing. Floor-standing installations dominate commercial and educational building specifications due to redundant capacity requirements.
Space Heating Boilers Market Competitive Landscape
Top-tier vendors anchor premium condensing technology, while mid-scale fabricators compete on retrofit installation speed and regional distributor density. The vendor base stratifies across German engineering specialists, diversified HVAC conglomerates, and North American channel players. Two strategic archetypes dominate: integrated heat pump-boiler hybrid specialists and pure-play condensing boiler exporters. Competitive moves concentrate on backward integration into burner and control module supply, plus geographic expansion through distributor acquisition in renovation-driven markets.
Within the German engineering tier, Viessmann Group and Bosch Thermotechnology exemplify manufacturing-base dominance in condensing technology exports. Rheem Manufacturing occupies a position in North American institutional channel control. These three anchors represent distinct competitive vectors: European export specialization, integrated hybrid system development, and distributor relationship depth across federal and state procurement channels.
| Leading Market Players |
|---|
| Viessmann Group |
| Lennox International |
| Daikin Industries, Ltd. |
| Rheem Manufacturing |
| Vaillant Group |
| Bosch Thermotechnology |
| Carrier Global |
| Johnson Controls |
| Ingersoll-Rand Plc |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation's hydrofluorocarbon quotas are forcing manufacturers to redesign hybrid heat pump-boiler refrigerant circuits and retest efficiency certifications, compressing margins and extending quoted lead times for condensing variants across German and Italian procurement channels.
Pricing Analysis
Premium pricing for sub-eight-week lead times now separates urgent renovation contracts from standard delivery schedules in the Rhine-Ruhr corridor. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking tier, burner technology grade, and bundled service contract scope. Cost compression in economy-tier atmospheric boilers is intensifying because Polish and rural German buyers face fuel-switching uncertainty. Residential renovators in Italy and Poland exhibit highest price sensitivity; institutional buyers in North American federal procurement channels demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with German and Italian burner and control module specialists concentrated in North Rhine-Westphalia and Lombardy manufacturing clusters. Heat exchanger fabrication draws from German, Chinese, and Turkish steel and copper processing hubs. Commodity price volatility in stainless steel and copper feedstock presents persistent margin risk. Distribution runs through multi-tier wholesaler networks in European retrofit markets and direct OEM-distributor partnerships dominating North American institutional segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around engineering-capable incumbents as F-Gas compliance costs and certification lag eliminate marginal atmospheric boiler fabricators across Central Europe.
For Market Incumbents: Acquire burner technology specialists and control module engineering teams to secure captive supply of low-NOx combustion systems. Expand condensing boiler capacity in Poland's Silesian corridor to capture EU cohesion-funded coal replacement demand. Defend against heat pump pure-play entrants by anchoring hybrid system service contracts to municipal housing association procurement.
For New Entrants and Emerging Players: Rural French properties beyond gas grid connectivity represent an underserved buyer archetype with unmet electric boiler demand and limited incumbent coverage. Polish voivodeships with aging coal stock and EU funding access offer the most penetrable geography for modular electric-resistance boiler deployment. Partner with regional electrical distributors rather than plumbing wholesalers to bypass established hydronic channel control.
For Investors and Strategic Acquirers: The window for entry favors mid-scale fabricators with certified condensing platforms and existing CE marking under updated MDR protocols. Long-term viability rests on regulatory compliance capability rather than scale economics alone. Watch F-Gas Regulation transposition timelines in Benelux markets as the signal for hybrid system demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Burner Supply | Secures low-NOx combustion engineering talent concentrated in aging German specialist workforces. |
| Hybrid System Certification Investment | Accelerates CE marking pathways for heat pump-boiler combinations under tightening F-Gas quotas. |
| Polish Manufacturing Footprint Expansion | Positions production capacity adjacent to Silesian and Greater Poland coal replacement demand zones. |
| Building Automation Control Integration | Captures EU AI Act-mandated smart interface aftermarket service revenue in German municipal housing. |
| Distributor Relationship Deepening | Reinforces channel control against disintermediation from direct OEM engagement in North American institutional procurement. |
Research Methodology
Multi-period observation of municipal building code adoptions, F-Gas quota utilization rates, and hybrid system certification timelines anchored the trend analysis, supplemented by interviews with boiler manufacturing executives, district heating network operators, municipal procurement officers, and HVAC installation contractors. Secondary validation drew from EU ECHA regulatory filings, German KfW renovation subsidy disbursement data, EPA emissions compliance databases, and trade customs records for heat exchanger material flows. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates.
Input-output matrices mapped fuel type, installation configuration, end-user segment, and regional regulatory cluster against thermal output demand and replacement cycle timing across the projection horizon. CAGRs were derived from segment-level growth trajectory aggregation and macroeconomic elasticity modeling. Forecast inputs incorporated EU Green Deal building stock renovation targets, national transposition timelines for efficiency mandates, and grid decarbonization curves in Nordic and French markets.
Revisions become necessary when F-Gas Regulation quota allocations shift, CE marking protocols under MDR extend unexpectedly, or copper and stainless steel commodity volatility disrupts heat exchanger supply economics. Forecasts reflect documented assumptions about regulatory enforcement intensity and subsidy program continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Advanced Utility Boilers Market
Boilers
Circulating Fluidized Bed Boilers Market
Boilers
Watertube Boilers Market
Boilers
Gas Fired Boilers Market
Boilers
Marine Boiler Burner Market
Boilers
Electric Boiler Market
Boilers
Global Domestic Boilers Market
Boilers
Superheater Market
Boilers
North America and Europe Electric Boilers Market
Boilers
Reformer Unit Market
Boilers
Brazil Combined Heat and Power Market
Boilers
Commercial Boiler Market
Boilers
Boiler Combustion Chamber Market
Boilers
Global Boiler Market
Boilers
Steam Boiler for Thermal Power Plant and Oil Refinery Market
Boilers
Boiler Control Market