

Superheater Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Superheater Tubes Market Insights
Grade 91 and Grade 92 creep-strength enhanced ferritic steel specification tiers is unwinding legacy carbon steel positions across utility procurement programs. Sandvik leverages its precision cold-drawing capabilities to dominate niche high-alloy segments for advanced ultra-supercritical plants. JFE Steel anchors Asian supply through integrated mill control from steelmaking to finished tube. Vallourec differentiates via proprietary thermomechanical processing that extends service life in corrosive high-temperature steam environments.
Superheater tubes are thick-walled, high-alloy steel conduits engineered to convey saturated steam through furnace radiation and convection zones, elevating temperatures beyond 540°C before turbine admission; they typically specify chromium-molybdenum compositions with controlled vanadium and niobium microadditions to resist thermal fatigue and creep deformation under sustained pressure loading. Alloy steel material types command the deepest margin pools owing to metallurgical complexity and limited qualified supplier bases, while stainless steel grades represent the fastest-expanding category as operators confront aggressive flue gas chemistries from low-rank coal and biomass co-firing. Seamless tubes retain structural preference in supercritical pressure regimes where weld integrity risks exclude welded alternatives, though electric resistance welded tubes occupy growing share in subcritical industrial boiler retrofits where cost sensitivity outweighs peak performance requirements.
EPA Mercury and Air Toxics Standards and the EU F-Gas Regulation shape product specifications by mandating higher thermal efficiency that only advanced alloy tubing can deliver, while China's GB standards and MEE emission enforcement drive domestic upgrading of boiler tube inventories. ASME Section II and ISO 9329 certification frameworks control market access by defining mandatory testing protocols for elevated-temperature service. Stakeholders must monitor evolving alloy qualification timelines against utility procurement cycles, as certification lag risks stranding capacity commitments before demand materializes.
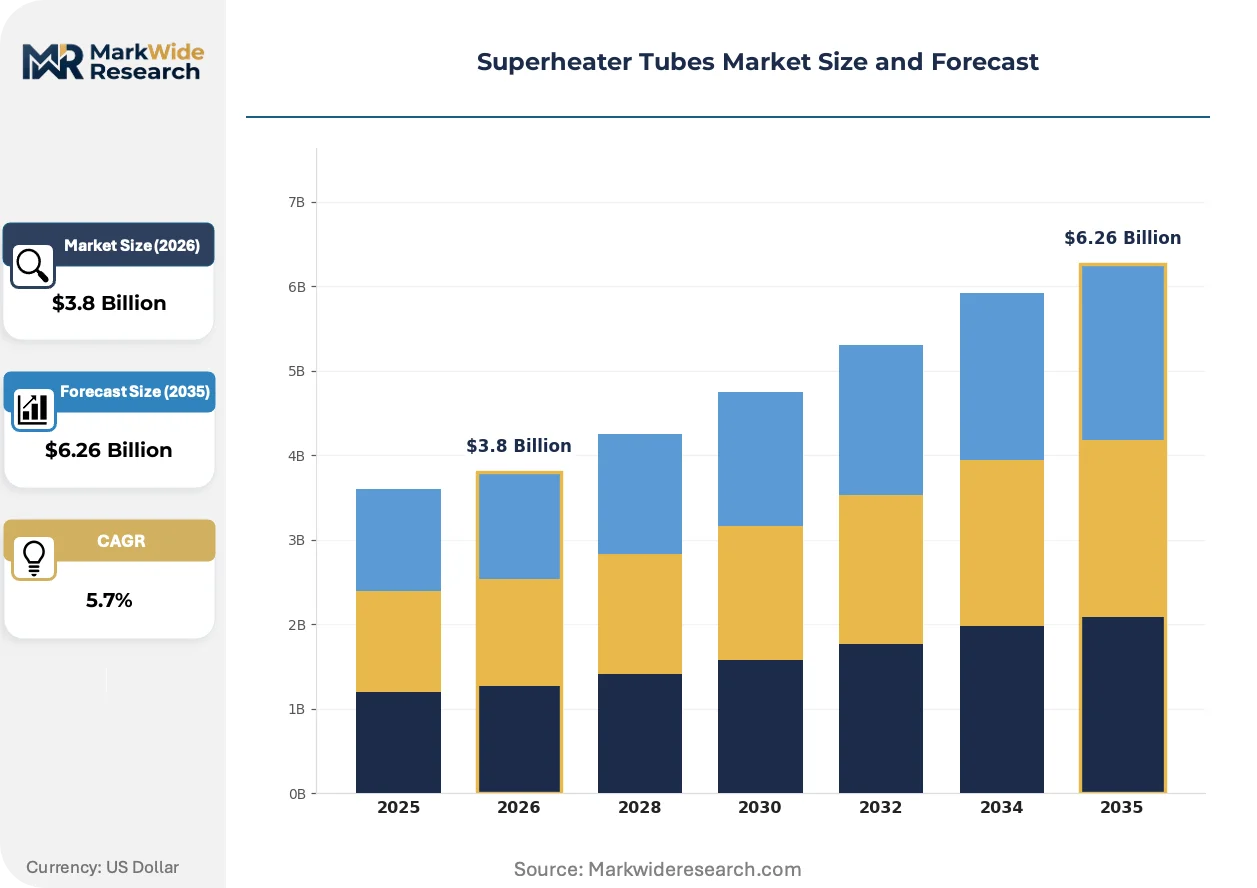
Market Dynamics
Ultra-supercritical boiler deployment is compressing qualification timelines for advanced ferritic alloys, forcing mills to synchronize metallurgical R&D with utility procurement cycles before ASME Section II certifications expire.
Growth Catalysts
- EPA Mercury and Air Toxics Standards:US utilities must retrofit subcritical boilers with superheater arrays capable of 600°C steam conditions, mandating Grade 91 alloy procurement.
- China's dual carbon goals:State-backed ultra-supercritical coal plant construction in Shandong and Inner Mongolia sustains demand for seamless high-chromium tubing.
- Biomass co-firing chemistry:Aggressive flue gases from agricultural waste combustion accelerate stainless steel superheater adoption in European district heating networks.
Market Restraints
- Nickel and molybdenum price volatility:Alloy surcharge fluctuations compress mill margins on long-delivery utility contracts indexed to LME spot prices.
- Qualified supplier concentration:Seamless tube capacity for ASME Grade 92 concentrates among three integrated European and Japanese producers.
- Weld integrity limitations:Supercritical pressure regimes exclude electric resistance welded alternatives regardless of cost advantage.
Strategic Opportunities
- India's PLI scheme for advanced manufacturing:Domestic stainless steel superheater production incentives attract technology licensing from qualified foreign mills.
- Carbon capture retrofits:Amine-based post-combustion capture systems impose corrosive operating conditions favoring duplex stainless specifications.
- Digital twin integration:Real-time creep monitoring via embedded sensors creates aftermarket service contracts tied to tube replacement forecasting.
Industry Challenges
- ASME Section II qualification timelines:New alloy grades require 100,000-hour creep rupture testing that outlasts utility procurement windows.
- Skilled non-destructive examination workforce:Phased-array ultrasonic inspection technicians for thick-wall ferritic tubing remain scarce in emerging manufacturing clusters.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superheater Tubes Market Trends and Innovations
Additive manufacturing of nickel superalloy repair inserts is disrupting conventional weld-overlay maintenance protocols for superheater headers in aging plants.
Directed energy deposition of Inconel 625 is miniaturizing repair geometries for cracked superheater headers, enabling utilities to defer full tube-bundle replacement. Power plant maintenance contractors in Germany and Japan are piloting these inserts during scheduled outages. The technology is compressing outage durations from weeks to days while extending asset life beyond original design limits.
EU F-Gas Regulation phase-down mandates are tightening thermal efficiency requirements that only advanced alloy tubing can satisfy. Boiler OEMs must now specify Grade 92 or austenitic stainless grades for newbuild projects to meet minimum performance thresholds. This regulatory compression is eliminating carbon steel and lower-grade ferritic options from European utility procurement lists entirely.
Long-term service agreements are displacing spot procurement for superheater tube replacement campaigns. Original equipment manufacturers in China and South Korea now bundle tubing supply with predictive maintenance analytics, capturing recurring revenue streams. This model is most visible in state-owned utility fleets where capital budgeting constraints favor operational expenditure structures.
Superheater Tubes Market Segmentation
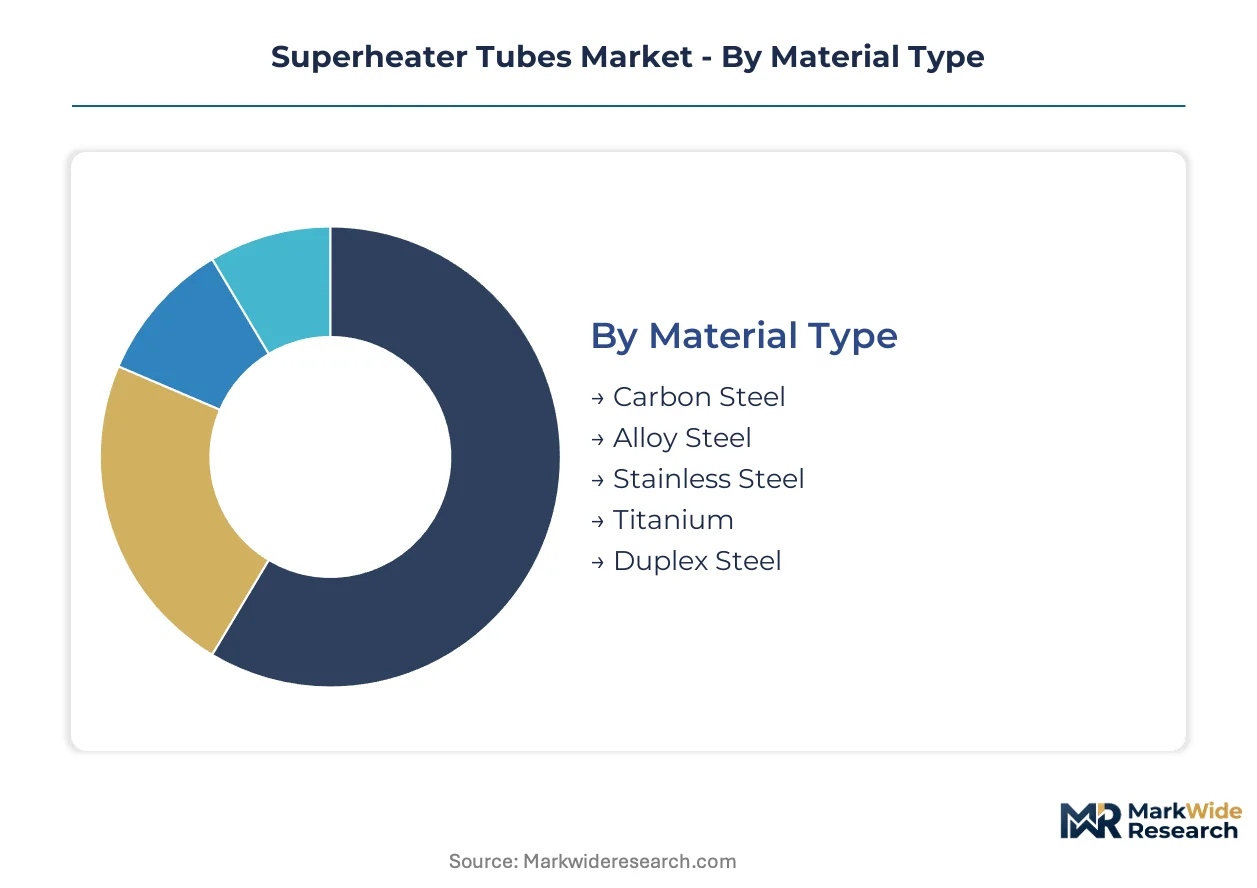
Superheater tube procurement varies sharply by operating environment and metallurgical specification. Material selection and product form decisions cascade through certification requirements, lead times, and maintenance economics.
Material Type:
Domestic production dominates carbon and standard alloy grades across China, India, and the United States, while high-performance alloys remain concentrated in European and Japanese export channels.
- Carbon Steel:Legacy boiler installations in developing markets specify this grade for subcritical pressure regimes below 200 bar. Procurement concentrates in India and Southeast Asia where cost sensitivity outweighs efficiency mandates.
- Alloy Steel:Chromium-molybdenum compositions with vanadium microadditions define the commercial core for 540-600°C steam conditions. Demand clusters in Chinese ultra-supercritical builds and US EPA-driven retrofits.
- Stainless Steel:Expanding most quickly as biomass co-firing and low-rank coal combustion spread aggressive flue gas chemistries across European district heating networks.
- Titanium:Niche seawater-cooled condenser applications in coastal Middle Eastern and Southeast Asian plants.
- Duplex Steel:Emerging specification for carbon capture retrofits where amine-based post-combustion systems impose severe corrosive loading.
Alloy steel commands the established base. The steepest expansion runs through stainless steel.
End User Industry:
Volume scale separates utility-scale procurement from industrial boiler operators, with divergent contracting structures and technical specifications.
- Power Plants:Centralized procurement by state-backed utilities in China and regulated investor-owned utilities in the United States drives seamless high-alloy specifications. China's dual carbon goals sustain concentrated demand for Grade 91 and Grade 92 tubing in Shandong and Inner Mongolia installations.
- Bulk Chemicals:Process steam requirements at 400-500°C favor welded tube alternatives where pressure cycling tolerance permits cost reduction.
- Metallurgy:Coke oven gas recovery boilers in integrated steel mills specify corrosion-resistant grades for hydrogen sulfide exposure.
- Paper Manufacturing:Recovery boiler rebuilds in Nordic and North American mills drive periodic replacement demand for composite tube assemblies.
- Textile Production:Saturated steam requirements at moderate pressures sustain carbon steel procurement in South Asian manufacturing clusters.
Power plants anchor volume procurement. Chemical processing offers the most flexible entry for secondary suppliers.
Application:
Temperature-pressure profiles and corrosion exposure dictate material grade selection across installation types.
- Steam Boilers:Radiant and convection superheater zones impose the most severe thermal fatigue and creep conditions, mandating seamless construction and advanced ferritic or austenitic grades.
- Heat Exchangers:Feedwater preheater applications operate below critical thresholds, permitting wider substitution between seamless and welded alternatives.
- Petrochemical Refineries:Hydrogen and hydrogen sulfide service at 450-550°C requires chrome-molybdenum specifications with precise hardness control.
- Waste Incineration:Chlorine and heavy metal vapor corrosion accelerates stainless steel adoption in European municipal energy recovery facilities.
- Cement Kilns:Preheater tower waste heat boilers encounter alkaline dust accumulation favoring specific alloy compositions.
Steam boilers concentrate premium-grade demand. Waste incineration is climbing fastest on emissions compliance timelines.
Product Form:
Manufacturing method determines structural integrity margins and cost positioning across pressure regimes.
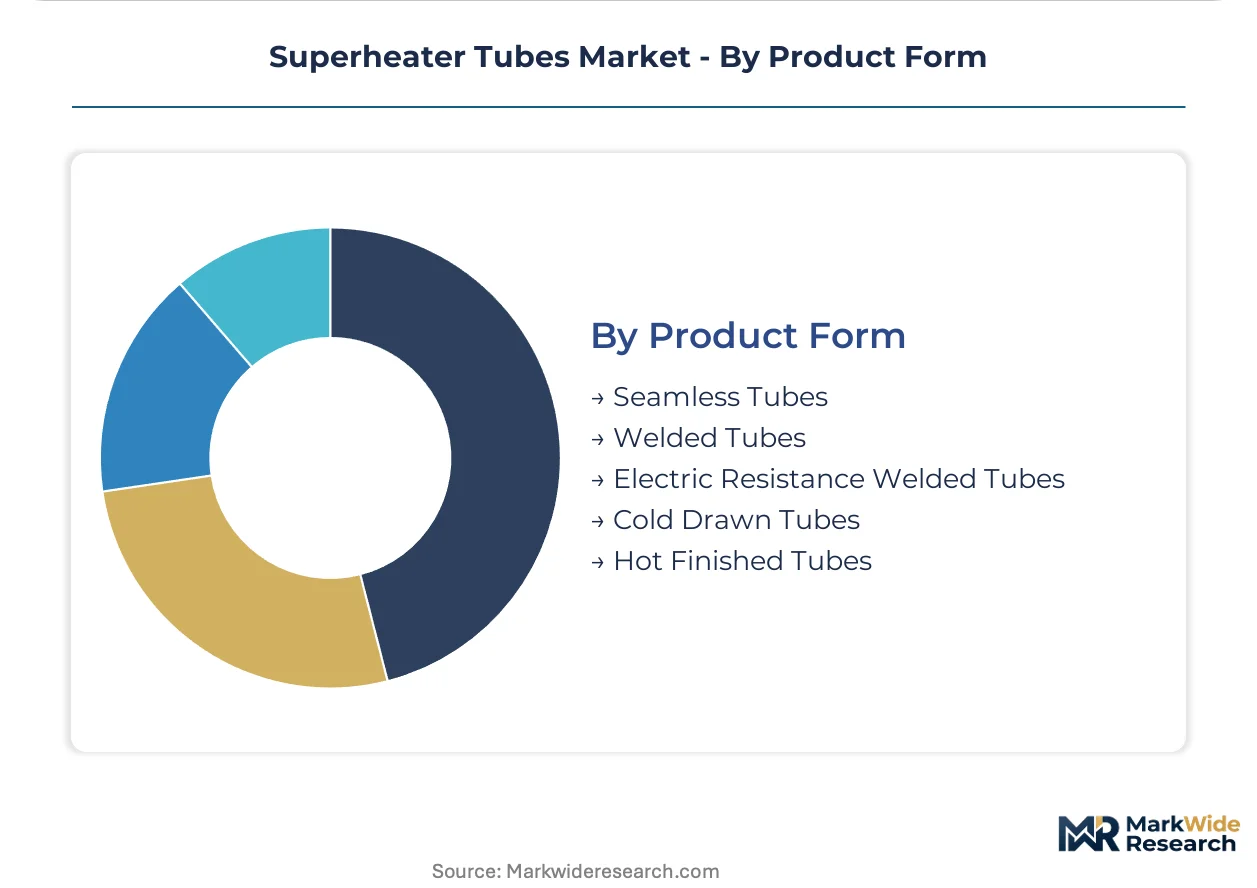
- Seamless Tubes:Hot-rolled or cold-drawn from solid billets, these retain mandatory preference for supercritical pressures where weld integrity risks exclude alternatives. ASME Section II certification requirements limit qualified supply bases.
- Welded Tubes:Longitudinal seam construction serves subcritical industrial boilers where cost sensitivity dominates performance requirements.
- Electric Resistance Welded Tubes:High-frequency induction welding offers intermediate cost positioning for 150-200 bar applications in chemical and paper sectors.
- Cold Drawn Tubes:Precision dimensional control supports superheater header assemblies requiring tight tolerance stacking.
- Hot Finished Tubes:As-rolled surfaces and broader tolerances serve lower-stress convection pass applications with shorter design lives.
Seamless tubes hold the premium position. Electric resistance welded variants are gaining share fastest in industrial retrofit markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in superheater tubes tilt heavily toward Asian manufacturing dominance, with European and Japanese mills capturing premium alloy segments while Chinese producers supply volume markets across developing economies.
China
State-backed ultra-supercritical coal plant construction in Shandong and Inner Mongolia sustains concentrated procurement of seamless high-chromium tubing. GB standards and MEE emission enforcement accelerate domestic boiler upgrades. Zhengzhou and Jiangsu manufacturing clusters anchor integrated production from steelmaking to finished tube.
United States
EPA Mercury and Air Toxics Standards compel utilities to retrofit subcritical boilers with Grade 91 alloy superheater arrays capable of 600°C steam conditions. FERC-regulated grid reliability requirements shape procurement timelines. Texas and Ohio utility corridors concentrate replacement demand from aging coal fleets.
Germany
EU F-Gas Regulation phase-down mandates eliminate carbon steel options from utility procurement lists, forcing specification of Grade 92 or austenitic stainless grades. REACH compliance adds material traceability burdens. Ruhr industrial district heating networks pilot stainless steel adoption for biomass co-firing applications.
Japan
METI-supported advanced ultra-supercritical R&D programs maintain domestic demand for creep-strength enhanced ferritic tubing. JIS certification frameworks control supplier qualification. Chubu and Kansai manufacturing regions retain precision cold-drawing capabilities for niche high-alloy segments.
India
CEA-mandated emission norms and PLI scheme incentives for advanced manufacturing attract technology licensing for domestic stainless steel superheater production. BIS standards govern import substitution timelines. Maharashtra and Gujarat industrial corridors concentrate process steam boiler installations favoring welded tube alternatives.
Superheater Tubes Market Competitive Landscape
Concentration sits with integrated steelmakers possessing captive metallurgical R&D and ASME Section II certification capabilities. Three to five European and Japanese producers control seamless tube capacity for Grade 92 specifications. Strategic archetypes divide between precision alloy specialists, integrated mill operators, and regional fabricators serving cost-sensitive industrial segments. Capacity expansion and strategic technology licensing represent the dominant competitive moves as mills synchronize alloy qualification timelines with utility procurement cycles.
Among Swedish and French integrated producers, Sandvik and Vallourec exemplify the precision alloy specialist archetype through proprietary thermomechanical processing and cold-drawing capabilities. Japanese steelmakers including JFE Steel occupy positions anchored by integrated mill control from steelmaking to finished tube. These three names represent the qualified supplier base that utility procurement programs must access for supercritical pressure regime applications.
| Leading Market Players |
|---|
| Sandvik |
| JFE Steel |
| Nippon Steel |
| Mannesmann Stainless Tubes |
| Tenaris |
| Vallourec |
| ISMT Limited |
| Jiangsu Sheye Metal Group |
| Tata Steel |
| Others |
Pricing and Supply Chain Analysis
Twenty-four to thirty-six month lead times for ASME Section II Grade 92 certification compress procurement flexibility and amplify pricing power for qualified European and Japanese mills serving utility buyers. This elongated qualification window concentrates supply-side leverage among integrated producers with captive metallurgical R&D, forcing buyers into long-delivery contracts indexed to volatile nickel and molybdenum alloy surcharges.
Pricing Analysis
Industrial OEM buyers anchor a bifurcated pricing structure where seamless high-alloy specifications command premium positioning against welded alternatives. Three-tier pricing stratification across ASME-certified premium grades, standard ferritic alloys, and carbon steel economy tiers reflects divergence in certification investment and thermal performance thresholds. Cost compression in the carbon steel tier is intensifying because Indian and Southeast Asian fabricators compete on mill-direct volume procurement. State-backed Chinese utilities exhibit lowest price sensitivity due to capital budget insulation, while European district heating operators face acute pressure from EU F-Gas Regulation compliance deadlines.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for specialty alloy feedstock deliveries to non-integrated tube mills. Primary supply concentrates in China, Japan, and Germany, with Zhengzhou and Jiangsu clusters controlling carbon and standard alloy output while Chubu and Ruhr regions retain high-performance seamless capacity. Raw material dependencies rest on Indonesian nickel matte, Chilean molybdenum concentrate, and ferrochrome from South African producers. Single-source vulnerability concentrates in ASME-qualified seamless finishing capacity, where only three integrated mills hold active certification. Distribution runs through mill-direct long-term offtake contracts for utility procurement, with spot channel serving industrial boiler retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified ASME Section II certification capacity for advanced ferritic grades remains tethered to a handful of integrated producers with 100,000-hour creep rupture testing infrastructure, creating persistent scarcity rents for incumbent specialists.
For Market Incumbents: Fortify ASME Section II certification pipelines by synchronizing metallurgical R&D with utility procurement cycles before qualification windows expire. Expand precision cold-drawing capacity in captive facilities to defend margin position against emerging Chinese integrated mills. Prioritize backward integration into nickel and molybdenum alloy feedstock to buffer LME spot price volatility on long-delivery contracts. For New Entrants and Emerging Players: Anchor in India's PLI scheme for advanced manufacturing to access technology licensing pathways from qualified foreign mills. Target carbon capture retrofit applications where duplex stainless specifications face qualified supplier shortages and certification backlogs. Pursue joint venture structures with established European or Japanese producers to accelerate ASME qualification timelines. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because EPA Mercury and Air Toxics Standards and EU F-Gas Regulation phase-downs structurally eliminate lower-grade alternatives from utility procurement lists. Acquisition focus should center on integrated mills with active ASME Section II certifications and captive thermomechanical processing capabilities. Monitor ASME new-grade qualification announcements as inflection signals for capacity stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| ASME Section II Certification Investment | Grade 92 qualification unlocks utility procurement access in EPA-driven US retrofits. |
| Backward Integration into Alloy Feedstock | Captive nickel and molybdenum supply buffers LME volatility on long-delivery contracts. |
| Technology Licensing to Indian PLI Beneficiaries | Domestic stainless superheater production incentives attract JIS-certified process transfers. |
| Digital Twin Service Contract Bundling | Embedded sensor analytics create recurring revenue from predictive tube replacement forecasting. |
| Carbon Capture Retrofit Specification Development | Duplex stainless grades for amine corrosion exposure open white-space in European utility upgrades. |
Research Methodology
Operator-level perspectives from utility procurement officers, EPC contractor metallurgical engineers, power plant maintenance directors, and seamless tube mill technical sales managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through ASME Section II certification databases, EPA enforcement action records, EU ETS compliance filings, and customs trade data for alloy steel tube flows. Bottom-up demand modeling triangulated against top-down capacity assessments across integrated mill networks.
Sensitivity analysis tested forecast outputs against variable nickel price scenarios, ASME qualification timeline extensions, and utility capital budget freeze assumptions across the projection horizon. Segmentation dimensions spanned material grade tier, end-use industry, pressure regime specification, and regional regulatory framework cluster. CAGRs derived from installed base replacement cycles, newbuild project pipelines, and alloy substitution elasticity parameters. Industry-specific inputs incorporated creep rupture testing completion rates and MEE emission enforcement intensity indices.
Underlying assumptions cover sustained EPA and EU emission enforcement, continuation of China's dual carbon goals implementation, and stable ASME Section II certification protocols, with deviation risk concentrated in nickel price volatility spikes and utility procurement cycle delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.