
 Hydrogen Storage System Market | 2026-2036
Hydrogen Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Storage System Market Foresight
Long-term service contracts for storage vessel recertification and predictive maintenance are restructuring how hydrogen infrastructure providers monetize assets. Air Liquide leverages its global cryogenic expertise to anchor liquefied hydrogen storage networks across industrial zones. Worthington Industries specializes in high-pressure composite cylinder manufacturing for tube trailer and ground storage applications. Linde controls large-scale liquid hydrogen production and distribution, extending its reach into refueling station deployments.
A hydrogen storage system encompasses vessels, materials, and integrated containment architectures designed to hold hydrogen in compressed gas, liquid, or solid-state forms at pressures reaching 700 bar or cryogenic temperatures below minus 253 degrees Celsius, serving the fundamental purpose of bridging temporal and spatial gaps between hydrogen production and consumption points. Compressed hydrogen dominates current transportation and light-duty applications due to established infrastructure, while metal hydrides represent the fastest-growing storage type as material science advances improve gravimetric density for stationary and portable power systems. Pipeline distribution as a delivery mode remains concentrated in mature industrial corridors where dedicated hydrogen networks already exist, though storage tanks capture expanding margin pools in maritime and aviation fueling projects requiring massive stationary capacity.
The EPA regulates hydrogen fueling station safety under Clean Air Act provisions, while OSHA mandates specific handling protocols for high-pressure gaseous systems in industrial settings, and the Department of Transportation's PHMSA governs tube trailer and pipeline transport standards that directly shape equipment certification cycles and market access timelines. Stakeholders must monitor how evolving ISO 19880 and ISO 19881 standards for gaseous and liquid hydrogen fueling interfaces will force retrofit investments or create first-mover advantages for compliant system architectures.
Market Dynamics
Heavy-duty trucking fleets are scaling hydrogen adoption as fuel cell costs decline, forcing storage infrastructure providers to restructure asset monetization around long-term service contracts rather than equipment sales.
Growth Catalysts
- EU Hydrogen Strategy:The REPowerEU framework mandates storage infrastructure buildout across member states, with industrial clusters in Germany's Rhineland and Hamburg anchoring integrated import and distribution hubs.
- Metal hydride materials:Advances in gravimetric density for stationary and portable power systems position solid-state storage as the fastest-growing storage type for applications requiring compact footprint.
- Tube trailer logistics:Ground storage applications for high-pressure composite cylinders concentrate demand in maritime and aviation fueling projects requiring massive stationary capacity.
Market Restraints
- Cryogenic energy penalty:Liquefied hydrogen storage consumes 30-40% of stored energy content in boil-off and cooling, compressing margins for liquid distribution networks.
- Equipment certification cycles:The Department of Transportation's PHMSA governs tube trailer standards with multi-year recertification timelines that delay fleet expansion.
- Pipeline corridor concentration:Dedicated hydrogen networks exist only in mature industrial zones, limiting distribution options for new production sites.
Strategic Opportunities
- Aviation fueling infrastructure:Maritime and aviation sectors require massive stationary storage capacity at ports and airports, creating greenfield deployment opportunities outside existing industrial corridors.
- ISO 19880 compliance:Evolving standards for gaseous hydrogen fueling interfaces create first-mover advantages for system architectures designed to forthcoming certification requirements.
- Predictive maintenance contracts:Storage vessel recertification services enable infrastructure providers to capture recurring revenue streams from installed equipment bases.
Industry Challenges
- Cryogenic technician scarcity:Liquid hydrogen handling requires specialized training in minus 253 degrees Celsius containment protocols that outpaces current vocational pipeline output.
- Multi-standard interoperability:Divergent ISO 19880 and ISO 19881 interface specifications force engineering teams to design for incompatible regional certification regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Storage System Market |
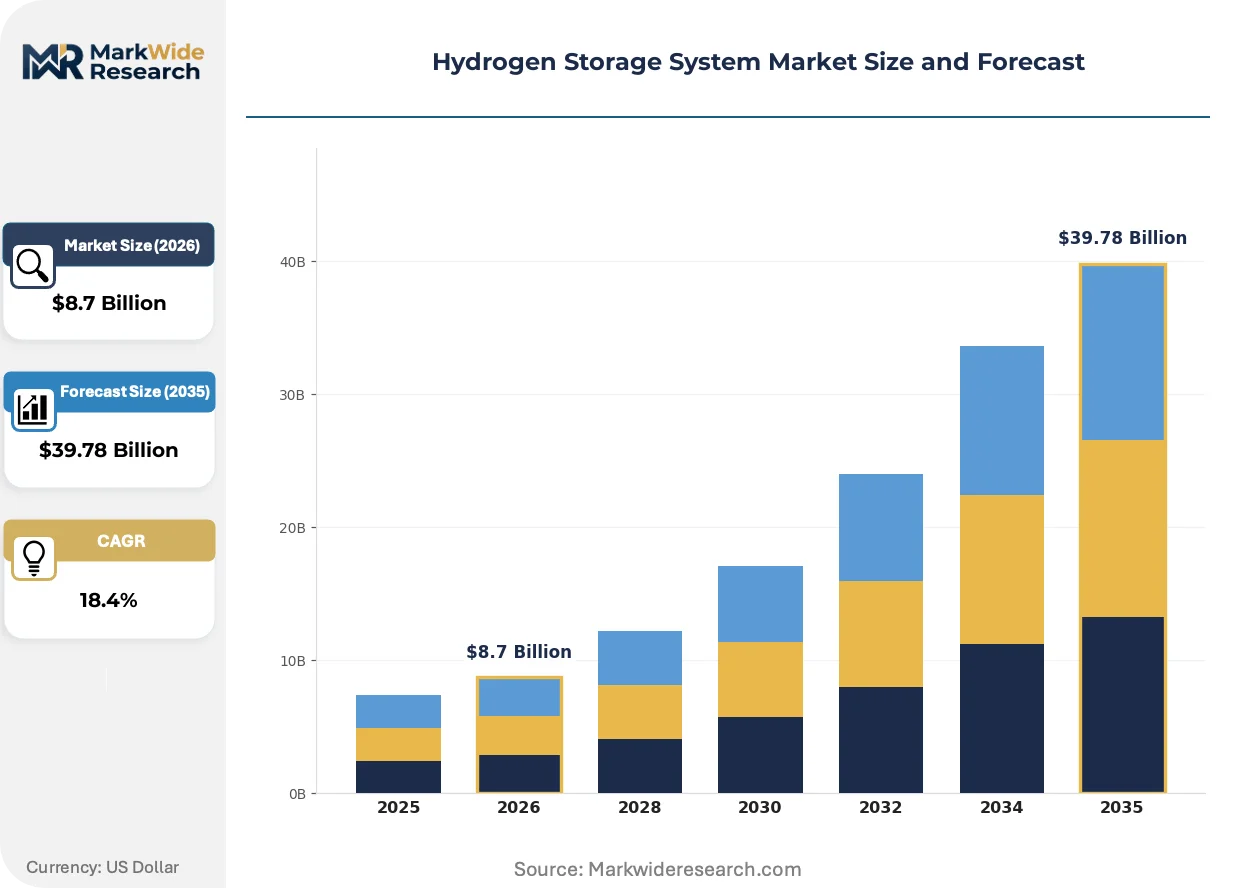
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Compressed Hydrogen, Liquefied Hydrogen, Metal Hydrides, Chemical Hydrogen Storage Delivery Mode: Tube Trailers, Storage Tanks, Pipeline Distribution, Refueling Stations Application: Fuel Cells, Industrial Processes, Power Generation, Transportation End User: Automotive, Aerospace, Energy, Manufacturing |
| Companies Covered | Air Liquide, Worthington Industries, Linde, Luxfer Holdings, Hexagon Composites, Chart Industries, McPhy Energy, VRV, Noble Gas Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Storage System Market Shifts & Advancements
Material science breakthroughs and regulatory harmonization efforts are compressing technology adoption cycles while reshaping how buyers evaluate storage system lifecycle costs.
Solid-state metal hydride storage is modularizing for portable and stationary power applications. Material advances improve gravimetric density above five weight percent hydrogen. Forklift fleets and backup power operators are piloting these systems for indoor deployment where compressed gas safety constraints limit alternatives. Modular cartridge designs enable rapid refueling without high-pressure infrastructure, compressing capital requirements for distributed hydrogen access.
OSHA mandates specific handling protocols for high-pressure gaseous systems in industrial settings. The EPA regulates hydrogen fueling station safety under Clean Air Act provisions with inspection frequencies tightening. Station operators in California and Texas are retrofitting containment architectures to preempt enforcement actions, accelerating replacement demand for non-compliant vessel designs.
Buyers are unbundling after-sales service from equipment procurement. Fleet operators now contract predictive maintenance and recertification separately from initial storage system purchase. This compresses vendor margins on hardware while expanding addressable market for specialized service providers. Germany's industrial clusters show the most advanced adoption of unbundled contracting structures.
Hydrogen Storage System Market Segmentation
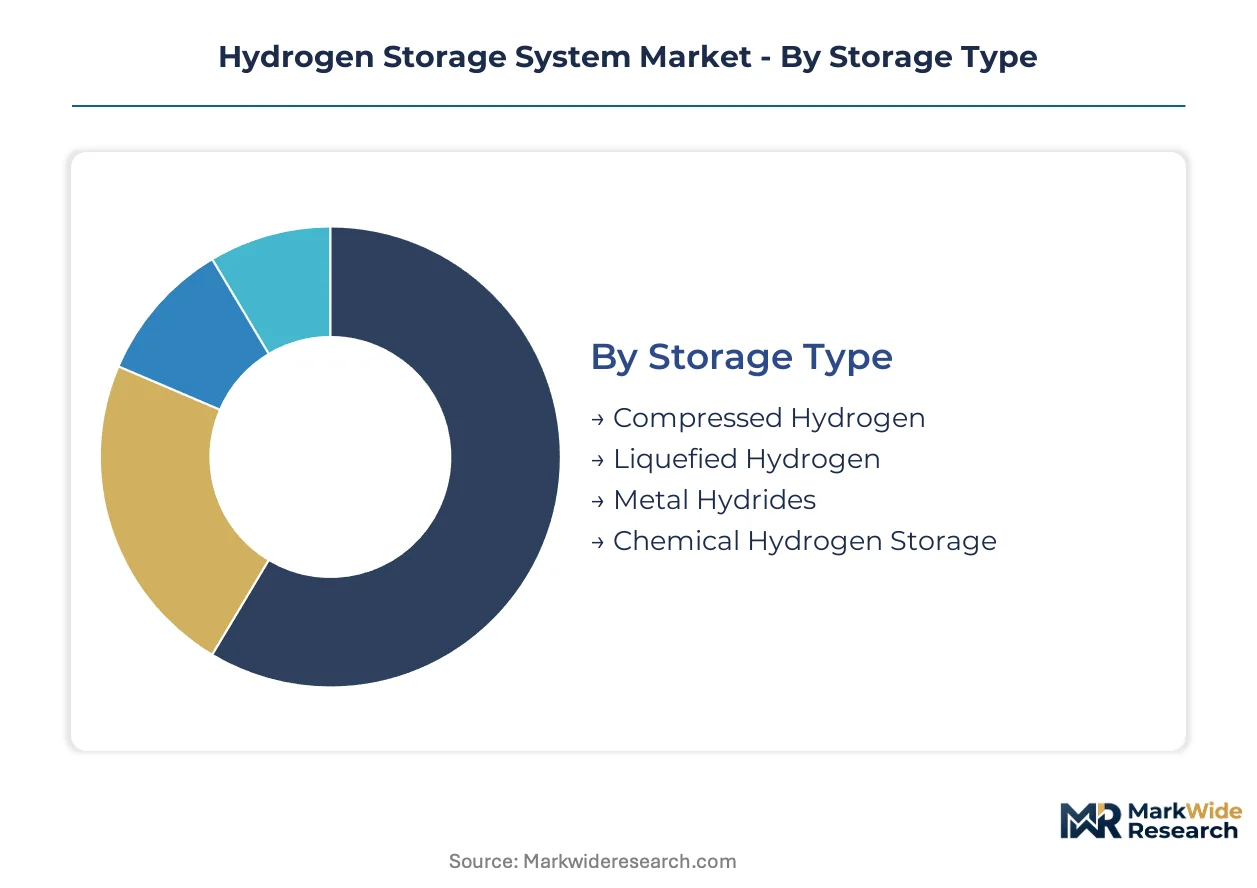
Storage architecture choices determine capital intensity, energy efficiency, and regulatory compliance pathways for hydrogen infrastructure investors. Segmentation reveals how technology maturity, application requirements, and geographic deployment patterns fragment procurement decisions across end-use sectors.
Storage Type:
Buyers differentiate primarily by energy density requirements and operating temperature tolerance for their specific deployment environment.
- Compressed Hydrogen:Gaseous storage at pressures reaching 700 bar dominates tube trailer logistics and light-duty vehicle refueling. German industrial clusters in the Rhineland anchor demand for high-pressure ground storage systems serving integrated import hubs.
- Liquefied Hydrogen:Cryogenic containment below minus 253 degrees Celsius enables maritime and aviation fueling projects requiring massive stationary capacity. The 30-40% energy penalty from boil-off and cooling compresses margins for liquid distribution networks.
- Metal Hydrides:Solid-state absorption systems improve gravimetric density above five weight percent for portable and stationary power. Forklift fleets pilot modular cartridge designs for indoor deployment where compressed gas safety constraints limit alternatives.
- Chemical Hydrogen Storage:Liquid organic hydrogen carriers and ammonia-based systems enable long-duration storage with ambient temperature handling. Maritime shipping corridors evaluate these formats for hydrogen-derived fuel supply chains.
Compressed hydrogen leads volumes today; metal hydrides are gaining share fastest.
Delivery Mode:
Procurement patterns track proximity to existing hydrogen production infrastructure and volume scale requirements.
- Tube Trailers:High-pressure composite cylinders transport compressed hydrogen from production sites to dispersed demand points. The Department of Transportation's PHMSA governs recertification timelines that delay fleet expansion.
- Storage Tanks:Stationary vessels capture expanding margin pools in maritime and aviation fueling projects requiring massive capacity at ports and airports. Hamburg's hydrogen import hub anchors ground storage deployment.
- Pipeline Distribution:Dedicated hydrogen networks concentrate in mature industrial corridors where infrastructure already exists. New production sites face limited distribution options outside these zones.
- Refueling Stations:Integrated compression, storage, and dispensing systems serve heavy-duty trucking fleets scaling hydrogen adoption. California and Texas operators retrofit containment architectures to preempt EPA enforcement actions under Clean Air Act provisions.
Tube trailers dominate mobile logistics; storage tanks show the steepest expansion trajectory for stationary applications.
Application:
End-use requirements dictate pressure specifications, purity standards, and cycling frequency for storage system design.
- Fuel Cells:High-purity hydrogen supply for proton exchange membrane systems drives demand for advanced filtration and contamination control. Heavy-duty trucking fleets scaling adoption force infrastructure providers toward long-term service contracts.
- Industrial Processes:Steel, ammonia, and refining applications consume bulk hydrogen with established safety protocols. Germany's industrial clusters anchor integrated production and consumption networks.
- Power Generation:Grid-scale storage and turbine blending applications require massive stationary capacity with rapid discharge capability. Backup power operators pilot metal hydride systems for indoor deployment.
- Transportation:Maritime and aviation sectors require fueling infrastructure at ports and airports outside existing industrial corridors. These greenfield deployments create equipment procurement opportunities independent of legacy hydrogen networks.
Industrial processes anchor current demand; transportation applications are climbing the fastest.
End User:
Customer sophistication and capital access determine contracting structures and service unbundling preferences.
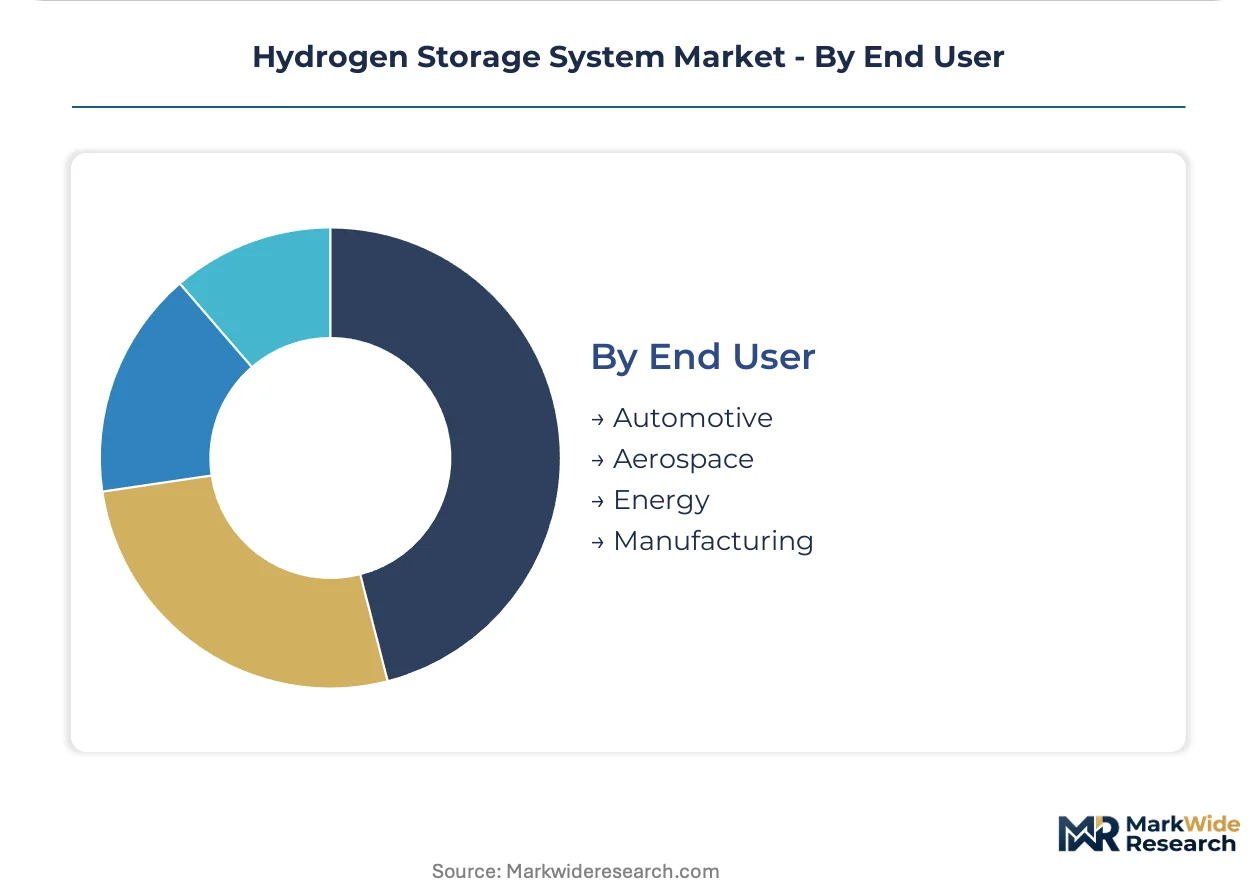
- Automotive:Light-duty and heavy-duty vehicle manufacturers drive standardization for gaseous hydrogen fueling interfaces. Fleet operators now contract predictive maintenance separately from initial storage system purchase.
- Aerospace:Aviation fueling infrastructure at airports requires cryogenic storage systems with specialized technician training. Liquid hydrogen handling protocols outpace current vocational pipeline output.
- Energy:Utility-scale storage and renewable integration projects evaluate metal hydrides and compressed gas formats. Grid operators prioritize modular systems for distributed hydrogen access.
- Manufacturing:Steel, chemicals, and electronics producers consume hydrogen as feedstock with established procurement relationships. These industrial buyers show the most advanced adoption of unbundled service contracting structures.
Manufacturing leads procurement volumes today; aerospace is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in hydrogen storage infrastructure deployment, while Japan and South Korea accelerate metal hydride commercialization. The United States concentrates demand in California and Texas refueling corridors. China scales liquefied hydrogen capacity for maritime applications.
United States
Heavy-duty trucking fleets in California and Texas drive tube trailer and refueling station procurement. The EPA regulates hydrogen fueling station safety under Clean Air Act provisions with tightening inspection frequencies. Station operators in both states retrofit containment architectures to preempt enforcement actions, accelerating replacement demand for compliant vessel designs.
Germany
Industrial clusters in the Rhineland and Hamburg anchor integrated hydrogen import and distribution hubs requiring massive ground storage systems. The EU Hydrogen Strategy and REPowerEU framework mandate storage infrastructure buildout across member states. Hamburg's hydrogen import hub specifically anchors ground storage deployment serving maritime and aviation fueling projects.
Japan
Fuel cell vehicle fleets and stationary power applications concentrate demand for compressed hydrogen and metal hydride systems. METI guides national hydrogen roadmap implementation with specific storage technology targets. Industrial zones around Tokyo and Osaka pilot solid-state storage for backup power operators requiring indoor deployment capabilities.
South Korea
Hyundai Motor Group's fuel cell ecosystem drives high-pressure composite cylinder demand for automotive and heavy-duty applications. The country's national hydrogen regulator enforces KGS certification standards for pressure equipment. The Ulsan industrial complex integrates hydrogen production with petrochemical and steel manufacturing, anchoring large-scale stationary storage deployment.
China
State-owned energy enterprises scale liquefied hydrogen production for maritime shipping corridors and aviation fueling infrastructure. MIIT coordinates hydrogen storage technology development under national dual carbon goals. The Yangtze River Delta and Pearl River Delta industrial zones concentrate cryogenic storage capacity serving export-oriented manufacturing hubs.
Hydrogen Storage System Market Competitive Landscape
Top-tier vendors anchor integrated liquid hydrogen production and distribution networks, while mid-tier specialists concentrate on high-pressure composite cylinders and modular metal hydride systems. The vendor base stratifies across three archetypes: cryogenic infrastructure integrators, composite pressure vessel fabricators, and solid-state storage material specialists. Competitive positioning hardens around long-term service contracts for vessel recertification and predictive maintenance. Capacity expansion into aviation and maritime fueling infrastructure represents the dominant geographic move, while backward integration into material production captures margin from metal hydride supply constraints.
Within the cryogenic infrastructure tier, Air Liquide and Linde occupy positions as integrated liquid hydrogen network operators. Among composite pressure vessel fabricators, Worthington Industries and Hexagon Composites exemplify high-pressure cylinder specialists serving tube trailer logistics. Chart Industries anchors the cryogenic equipment fabrication segment with liquefied hydrogen containment expertise. These three archetypes—integrated gas majors, composite cylinder specialists, and cryogenic fabricators—represent the structural poles around which competitive dynamics organize.
| Leading Market Players |
|---|
| Air Liquide |
| Worthington Industries |
| Linde |
| Luxfer Holdings |
| Hexagon Composites |
| Chart Industries |
| McPhy Energy |
| VRV |
| Noble Gas Systems |
| Others |
Supply & Pricing Matrix
Backward integration into metal hydride material production anchors supply positions for solid-state storage specialists while compressing input cost volatility that otherwise erodes pricing power. This captive sourcing strategy distinguishes vendors competing for long-term service contracts in Germany's industrial clusters from equipment sellers exposed to spot market rare earth fluctuations.
Pricing Analysis
Capacity additions in China are reshaping price floors for liquefied hydrogen containment systems as state-owned energy enterprises scale cryogenic production. Three-tier pricing structure across premium, standard, and economy levels separates ISO 19880-compliant architectures from legacy vessel designs facing retrofit mandates. Cost compression in standard-tier composite cylinders is intensifying because PHMSA recertification timelines extend fleet replacement cycles. Fleet operators show highest price sensitivity; aviation fueling infrastructure buyers absorb premium pricing for specialized cryogenic handling protocols.
Supply Chain Analysis
Cryogenic technician scarcity in Germany, Japan, and South Korea constrains manufacturing throughput for liquid hydrogen storage systems below minus 253 degrees Celsius. Production draws from rare earth deposits for metal hydride alloys, carbon fiber prepreg for composite cylinders, and nickel-based superalloys for high-pressure containment. Single-source vulnerability concentrates in carbon fiber supply from aerospace-qualified weavers. Distribution runs through tube trailer logistics networks for mobile hydrogen, with dedicated pipeline corridors serving only mature industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as industrial decarbonization mandates across the EU, Japan, and South Korea lock in hydrogen infrastructure procurement cycles. The regulatory anchor creates predictable demand visibility for storage system vendors.
For Market Incumbents: Acquire predictive maintenance service capabilities to capture recurring revenue from installed vessel bases. Consolidate metal hydride material supply through captive production or exclusive offtake agreements. Emerging solid-state specialists threaten margin compression in portable power segments; certification investment in ISO 19881 liquid hydrogen interfaces creates switching costs against retrofit competitors. For New Entrants and Emerging Players: Launch via modular metal hydride cartridge designs targeting forklift fleets and backup power operators requiring indoor deployment. Maritime and aviation fueling infrastructure at ports and airports outside existing industrial corridors offers the most penetrable greenfield deployment. Partner with cryogenic equipment fabricators to bypass technician scarcity constraints. For Investors and Strategic Acquirers: Roll-up economics work for regional service providers because vessel recertification contracts generate annuity-like cash flows with low customer churn. Five-to-ten year viability hinges on exposure to EU Hydrogen Strategy-funded projects versus speculative export markets. Watch for PHMSA acceleration of recertification timelines as signal for replacement cycle inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metal Hydride Production | Captures margin from rare earth supply constraints while securing input for solid-state storage systems. |
| Long-term Service Contract Expansion | Transforms equipment vendors into recurring revenue platforms through predictive maintenance and recertification services. |
| Aviation Fueling Infrastructure Deployment | Opens greenfield capacity outside legacy hydrogen corridors at airports requiring massive stationary cryogenic storage. |
| ISO 19880 Compliance Pre-positioning | Creates first-mover certification advantages as EPA and OSHA tighten inspection frequencies for gaseous systems. |
| Cryogenic Technician Training Pipeline Investment | Addresses vocational output gaps that constrain liquid hydrogen handling capacity below minus 253 degrees Celsius. |
Research Methodology
Coverage spans Germany, Japan, South Korea, the United States, and China, with primary inputs from each market informing demand segmentation. Interviews with hydrogen infrastructure planners, cryogenic equipment procurement leads at industrial clusters, tube trailer fleet operators, and metal hydride R&D directors combined with secondary validation from SEC filings, EIA hydrogen project databases, EU REPowerEU implementation reports, and METI hydrogen roadmap disclosures. Bottom-up vessel shipment data triangulated against top-down infrastructure investment announcements.
Granularity-level modeling disaggregated compressed, liquefied, metal hydride, and chemical hydrogen storage formats across tube trailer, storage tank, pipeline, and refueling station delivery modes. Projections incorporated fuel cell vehicle deployment trajectories, industrial process feedstock conversion timelines, and maritime aviation fueling project announcements across the analysis window. CAGRs derived from segment-level volume buildups validated against macro hydrogen demand scenarios.
Forecast precision tightens around the base case; tail outcomes carry wider variance under delays in EU Hydrogen Strategy funding disbursement or PHMSA recertification timeline acceleration. Assumptions reflect current regulatory enforcement postures and material science advancement rates for gravimetric density improvement. Material deviation in REPowerEU implementation pace or cryogenic technician training program scale warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Battery Energy Storage Market
Energy Storage
Compressed Air Energy Storage (CAES) Market
Energy Storage
Energy Storage Sodium Ion Battery Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Ultracapacitors Market
Energy Storage
Natural Gas Storage Market
Energy Storage
Super Capacitor Energy Storage System Market
Energy Storage
North America NMC Battery Energy Storage System (BESS) Market
Energy Storage
ASEAN Energy Storage Market
Energy Storage
Gravity Energy Storage Market
Energy Storage
Long-Duration Energy Storage Market
Energy Storage
Supercapacitor Market
Energy Storage
United Kingdom Energy Storage Systems Market
Energy Storage
South America Energy Storage Market
Energy Storage
Lead Acid Battery for Energy Storage Market
Energy Storage
ASEAN Energy Storage Devices Market