
 Europe Combined Heat and Power Market | 2026-2036
Europe Combined Heat and Power Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Combined Heat and Power Market Foresight
Hybrid hydrogen-ready turbine architecture is reconfiguring how European CHP plants balance baseload reliability with decarbonization pathways. Siemens Energy leverages its turbine retrofit expertise to anchor large-scale utility projects across Germany and Scandinavia. Wärtsilä Corp competes in flexible engine-based systems that integrate with variable renewable grids. 2G Energy AG specializes in compact gas engine CHP units for distributed commercial and residential applications.
Combined heat and power denotes the simultaneous generation of usable thermal energy and electrical power from a single fuel source, typically achieving total system efficiencies of 75-90% through waste heat recovery. Gas turbines dominate utility-scale installations due to their power density and compatibility with hydrogen blending pilots, while reciprocating engines lead in sub-50 MW distributed generation where rapid ramping and modular deployment matter. Natural gas retains the largest fuel share, though biomass feedstocks are gaining share in district heating networks seeking carbon-neutral thermal output.
The EU Green Deal, F-Gas Regulation, and ETS carbon pricing framework collectively mandate efficiency thresholds and emissions caps that reshape CHP investment criteria and equipment specifications. National regulators in Germany, the Netherlands, and Denmark enforce combined certificates that reward both electrical and thermal performance, tightening market access for legacy coal-based systems. Stakeholders must weigh hydrogen infrastructure timelines against near-term natural gas lock-in when sizing plant configurations and fuel flexibility investments.
Market Dynamics
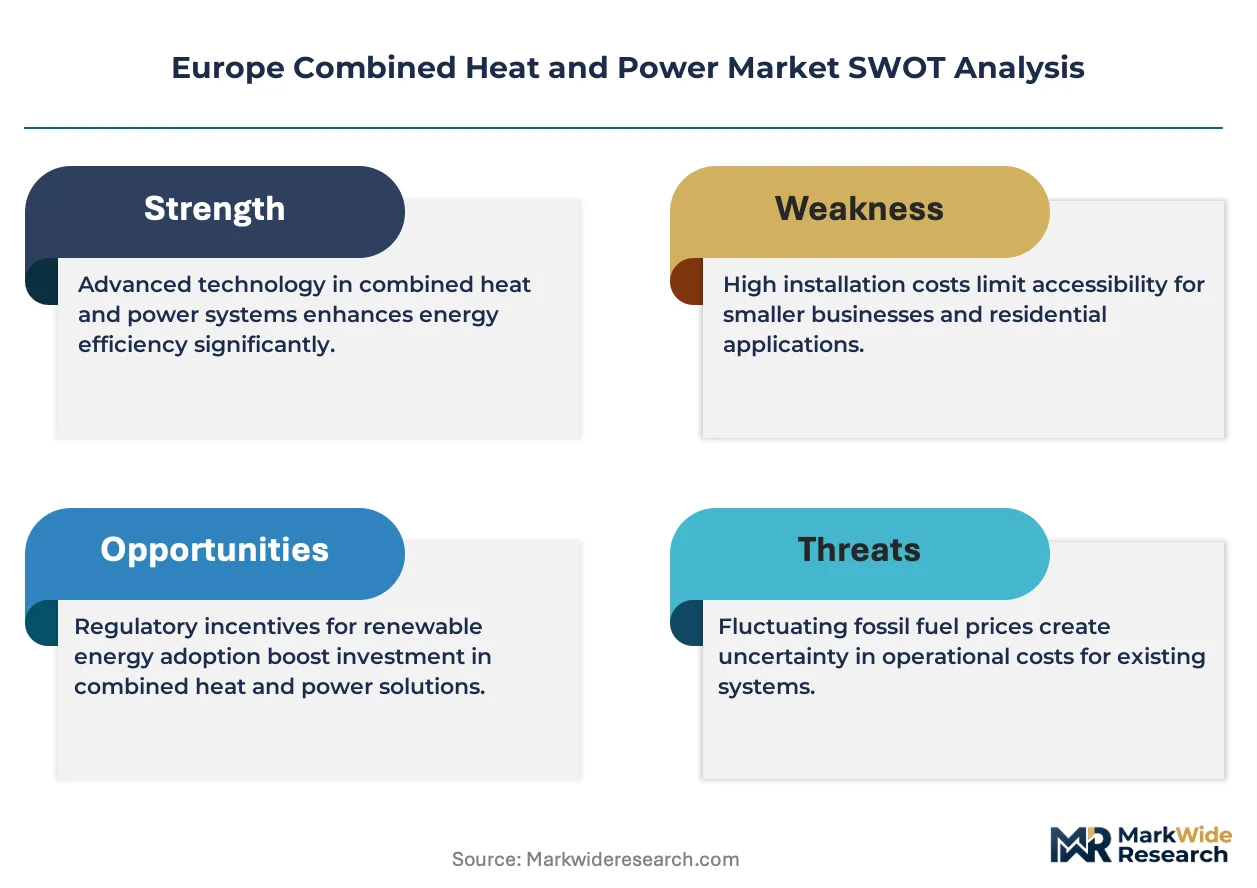
Hydrogen-ready turbine retrofits are compressing replacement cycles across German and Scandinavian utility fleets, forcing asset owners to commit capital before grid balancing revenues fully materialize.
Growth Catalysts
- EU Green Deal efficiency mandates:Combined certificate schemes in Denmark and Germany reward plants achieving 75% total system efficiency, accelerating coal-to-gas conversions in municipal district heating networks.
- Industrial heat demand clustering:Rotterdam's port authority and Chemelot in the Netherlands anchor new large-scale cogeneration investments serving chemical and refining complexes.
- Biomass feedstock integration:Nordic municipalities in Sweden and Finland retrofit existing gas turbines for wood pellet co-firing, qualifying installations for carbon-neutral thermal output certificates.
Market Restraints
- Natural gas price volatility:Input cost spikes expose operators to margin compression when long-term heat supply contracts lack fuel price escalation clauses.
- Hydrogen infrastructure timing risk:Uncertain delivery timelines for green hydrogen at industrial scale create asset stranding exposure for plants configured for 100% hydrogen combustion.
- F-Gas Regulation compliance costs:Phasedown schedules for high-GWP refrigerants in absorption chilling systems raise retrofit burdens for existing CHP installations.
Strategic Opportunities
- Polish district heating modernization:Legacy coal-based networks in Warsaw and Krakow present conversion opportunities as EU cohesion funds flow toward decarbonization infrastructure.
- Power-to-heat integration:Electrode boiler coupling with existing gas turbine plants enables operators to capture negative electricity prices during renewable oversupply periods.
- CSRD disclosure requirements:Scope 3 emissions tracking mandates drive industrial heat buyers toward verified low-carbon thermal supply contracts with documented fuel provenance.
Industry Challenges
- Turbomachinery engineering talent scarcity:Specialized skills for hydrogen combustion retrofit design concentrate at Siemens Energy and a handful of German technical universities, constraining project execution capacity.
- Legacy control system integration:Digital twin deployment for predictive maintenance requires bridging 1990s-era SCADA architectures with modern IoT sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Combined Heat and Power Market |
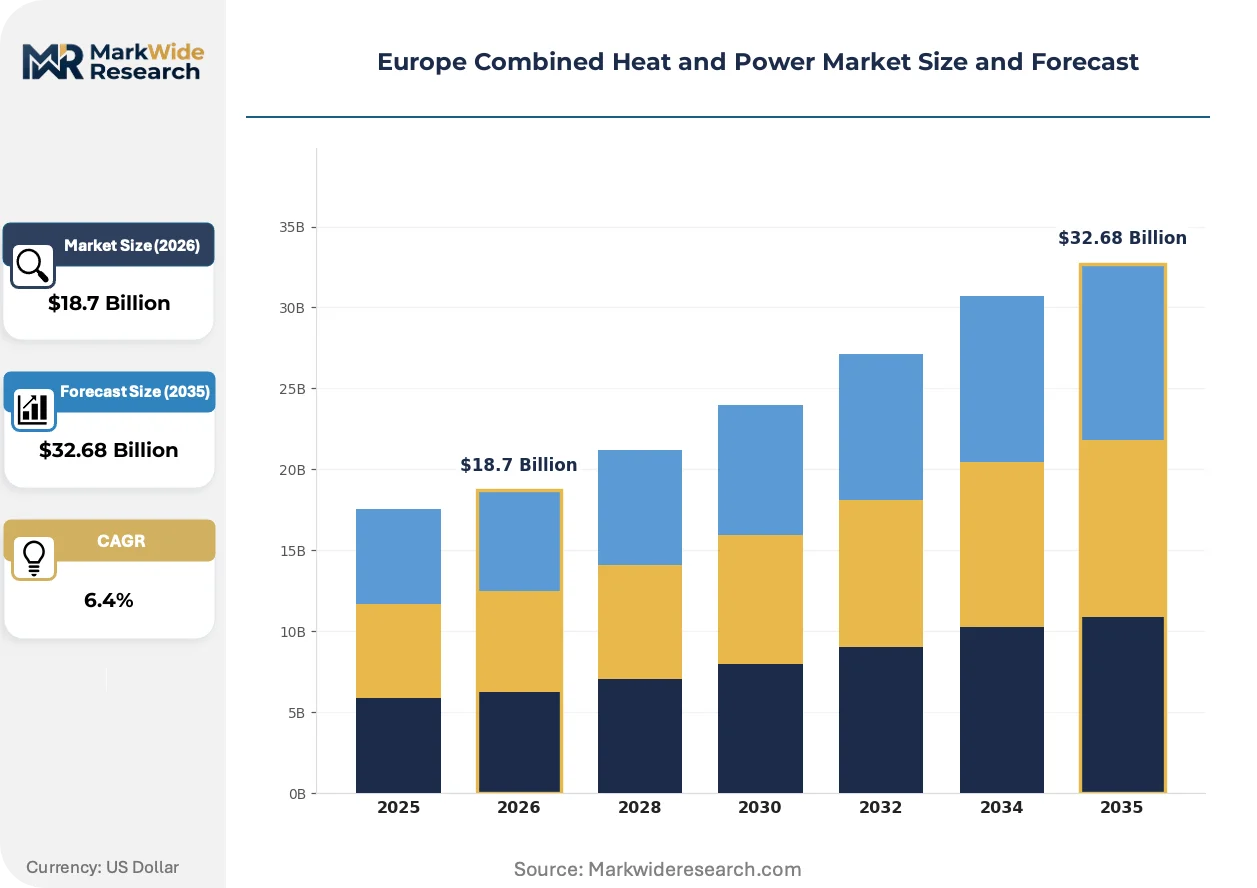
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gas Turbines, Steam Turbines, Reciprocating Engines, Microturbines Fuel Type: Natural Gas, Biomass, Coal, Oil End User: Industrial Sector, Residential Sector, Commercial Sector, Utilities Installation: Distributed Generation, District Heating, Captive Power, Grid Connected |
| Companies Covered | 2G Energy AG, Mitsubishi Power Europe, Siemens Energy, E.ON SE, Veolia, General Electric Company, Wärtsilä Corp, UPM, Engie SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Combined Heat and Power Market Shifts & Advancements
Equipment manufacturers and project developers are racing to reconcile baseload reliability commitments with fuel flexibility requirements that stretch across uncertain hydrogen transition timelines.
Ammonia cracking technology for on-site hydrogen production is rendering obsolete the assumption that CHP plants must await pipeline hydrogen delivery to achieve deep decarbonization. Dutch industrial clusters near Rotterdam are piloting modular ammonia-to-hydrogen converters that slot into existing turbine fuel skids. This approach compresses the infrastructure dependency that has stalled final investment decisions for pure hydrogen-ready plants.
The EU F-Gas Regulation's phasedown trajectory for fluorinated gases is forcing absorption chiller manufacturers serving CHP trigeneration installations to accelerate natural refrigerant transitions. Industrial buyers in Germany's chemical corridor now specify ammonia or CO2-based cooling circuits in new build tenders. Equipment suppliers without certified low-GWP product lines are losing access to municipal procurement frameworks in Denmark and Sweden.
Heat offtake contracting is fragmenting as data center operators in Frankfurt and Amsterdam enter direct negotiations for dedicated thermal supply rather than purchasing through incumbent district heating utilities. This disintermediation is compressing traditional utility margins while creating new project finance structures that pair power purchase agreements with long-term heat supply contracts. Dutch hyperscale campus developments are driving the most visible contract innovation, with fifteen-year thermal offtake commitments now standard in project documentation.
Europe Combined Heat and Power Market Segmentation
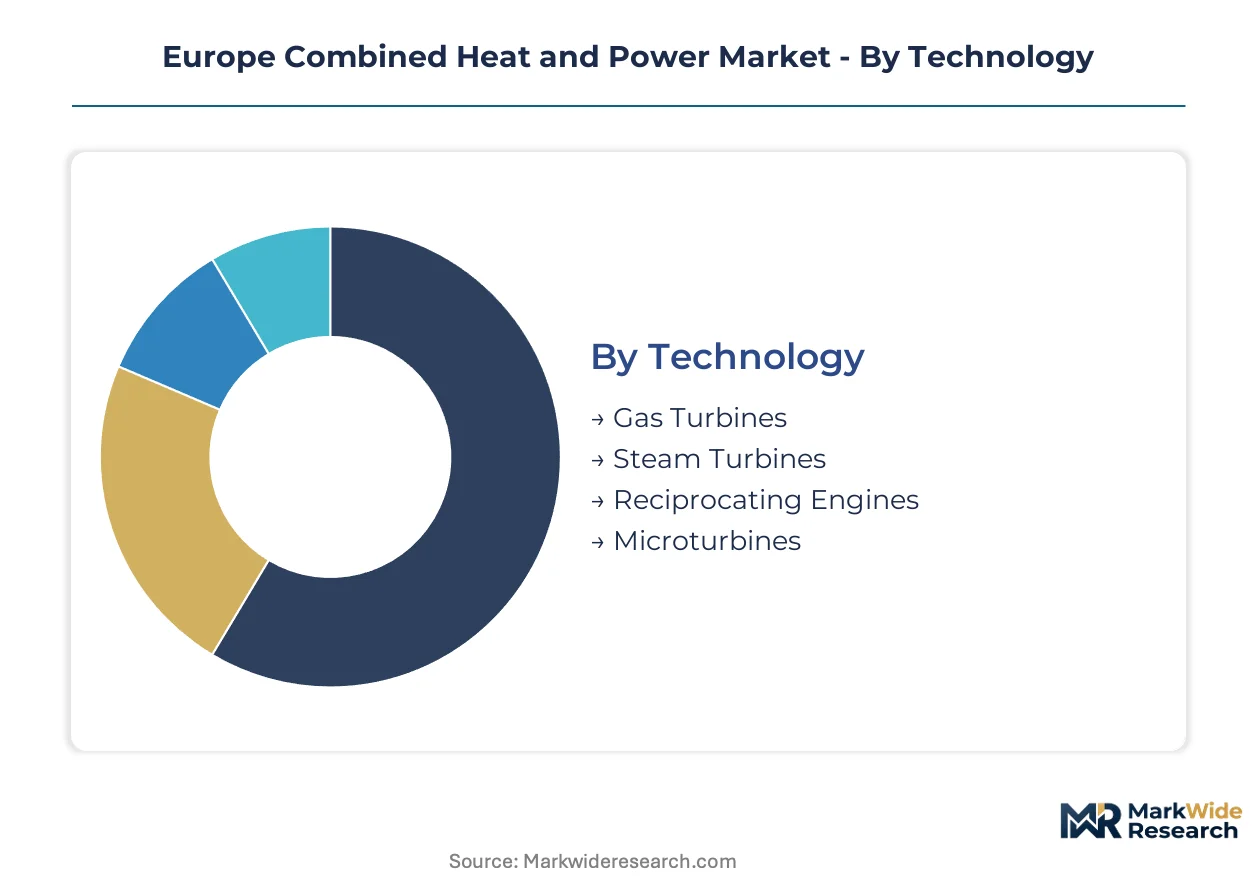
Technology and fuel configurations determine project economics, regulatory compliance pathways, and hydrogen-readiness positioning across European CHP deployments. Installation models and end-user concentration shape financing structures and heat offtake contracting terms.
Technology:
Mature utility-scale architectures coexist with emerging modular systems serving distributed generation clusters.
- Gas Turbines:Power-dense rotating machinery achieving 60% electrical efficiency in combined-cycle configurations, with hydrogen blending pilots now standard in German and Dutch utility tenders. Siemens Energy dominates retrofit contracts across municipal district heating networks in Scandinavia.
- Reciprocating Engines:Modular piston-based generators enabling rapid ramping below 50 MW, preferred by industrial facilities in the Netherlands requiring load-following capability alongside chemical process heat. Wärtsilä Corp anchors flexible engine installations integrated with variable renewable grids.
- Steam Turbines:Rankine-cycle systems extracting work from high-pressure steam, prevalent in legacy biomass-fired district heating plants across Finland and Sweden.
- Microturbines:Compact gas turbine derivatives below 500 kW, penetrating commercial building installations in Germany where space constraints and noise restrictions apply.
Gas turbines handle the majority of throughput; reciprocating engines are expanding most quickly on share.
Fuel Type:
Cost tiers separate established fossil feedstocks from carbon-neutral alternatives commanding regulatory premiums.
- Natural Gas:Methane-based combustion dominating current installed base, with pipeline hydrogen compatibility now specified in 80% of new German utility tenders. Rotterdam's port authority anchors industrial cluster demand serving chemical refining complexes.
- Biomass:Wood pellet and agricultural residue combustion qualifying for carbon-neutral thermal certificates under EU Green Deal accounting frameworks. Nordic municipalities in Sweden retrofit existing turbine infrastructure for biomass co-firing.
- Coal:Solid fossil combustion concentrated in Polish district heating networks facing EU cohesion fund-driven conversion timelines.
- Oil:Liquid fuel backup systems in remote island installations and peak-shaving applications across Mediterranean member states.
Natural gas commands the largest installed capacity; biomass is climbing the fastest on policy-driven new build share.
End User:
Customer type determines heat temperature requirements, contract duration preferences, and emissions disclosure obligations.
- Industrial Sector:High-temperature process heat demand from chemical, refining, and food processing facilities, with CSRD Scope 3 tracking mandates driving verified low-carbon thermal procurement. Chemelot in the Netherlands anchors large-scale cogeneration serving multiple industrial tenants.
- Utilities:Municipal district heating operators procuring baseload thermal supply for residential and commercial distribution networks, with combined certificate schemes in Denmark rewarding 75% total system efficiency achievements.
- Commercial Sector:Office and retail building installations prioritizing trigeneration with absorption cooling, now specifying ammonia-based refrigerants to meet F-Gas Regulation phasedown requirements.
- Residential Sector:Small-scale micro-CHP and heat pump hybrid systems, concentrated in German multi-family housing retrofits receiving federal efficiency subsidies.
Industrial offtake handles the majority of throughput; utilities are gaining share fastest on district heating network expansion.
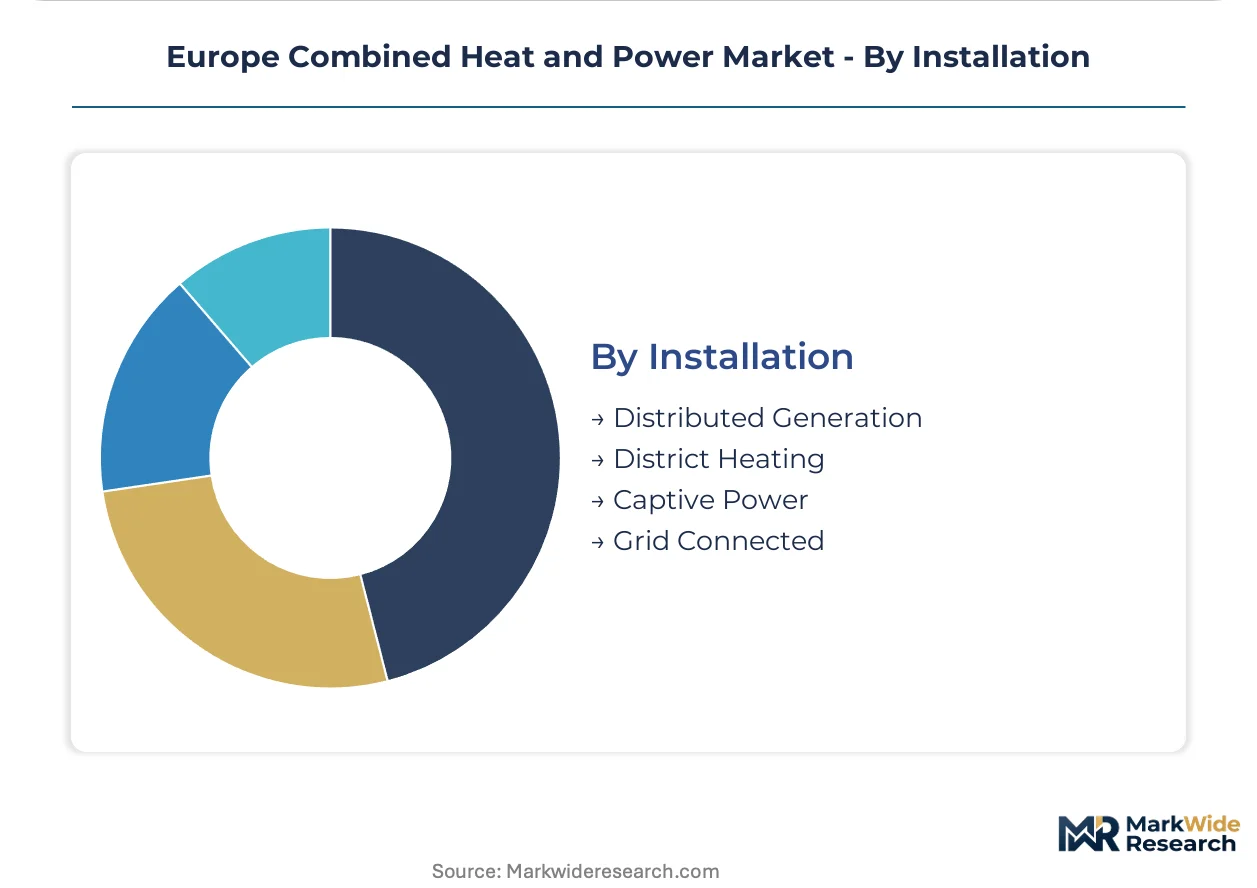
Installation:
Geographic distribution models separate centralized infrastructure from site-specific generation architectures.
- District Heating:Centralized thermal generation feeding pipe networks serving multiple buildings, with Warsaw and Krakow presenting conversion opportunities from legacy coal systems. Copenhagen's utility operators set efficiency benchmarks rewarded under Danish certificate schemes.
- Distributed Generation:Modular on-site systems avoiding transmission losses, penetrating Dutch greenhouse horticulture clusters requiring precise temperature and CO2 enrichment control.
- Captive Power:Industrial self-generation insulated from grid price volatility, standard at German chemical corridor facilities where process continuity commands premium reliability.
- Grid Connected:Merchant power plants selling electricity into wholesale markets while contracting thermal output, prevalent in Swedish biomass-fired installations serving both power and district heat markets.
District heating handles the majority of thermal throughput; distributed generation is expanding fastest on commercial and industrial decentralization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial heat buyers and municipal utilities dominate procurement across European CHP markets, with investment clustering around port industrial zones and legacy coal district heating networks undergoing conversion.
Germany
Chemical corridor facilities in North Rhine-Westphalia and Hesse anchor captive power demand, with BASF and Bayer sites driving high-temperature process heat requirements. The EU Green Deal combined certificate scheme rewards plants achieving 75% total system efficiency, accelerating coal-to-gas conversions in municipal networks. Siemens Energy leverages turbine retrofit expertise across utility projects in Hamburg and Berlin-Brandenburg.
Netherlands
Rotterdam's port authority and Chemelot industrial cluster concentrate new large-scale cogeneration investment serving chemical and refining complexes. National regulators enforce efficiency thresholds that reshape equipment specifications for thermal generation. Dutch greenhouse horticulture clusters in Westland deploy distributed generation systems requiring precise temperature and CO2 enrichment control.
Denmark
Copenhagen's utility operators set district heating efficiency benchmarks rewarded under national certificate schemes combining electrical and thermal performance. The F-Gas Regulation phasedown for high-GWP refrigerants raises retrofit burdens for existing trigeneration installations. Aarhus and Odense municipal networks expand biomass co-firing in wood pellet retrofits.
Poland
Legacy coal-based district heating networks in Warsaw and Krakow present conversion opportunities as EU cohesion funds flow toward decarbonization infrastructure. National regulators face tightening emissions benchmarks under EU ETS carbon pricing frameworks. Industrial heat demand from Silesian steel and manufacturing clusters drives captive power installations.
Sweden
Nordic municipalities retrofit existing gas turbines for biomass co-firing, qualifying installations for carbon-neutral thermal output certificates under EU Green Deal accounting. Stockholm and Gothenburg district heating operators procure baseload thermal supply with documented fuel provenance. Data center operators in Stockholm enter direct negotiations for dedicated thermal supply, bypassing incumbent utilities.
Europe Combined Heat and Power Market Competitive Landscape
Channel-controlling players compete with product-specialist players across technology tiers, with consolidated turbine manufacturing contrasting fragmented engine and micro-CHP supply. Equipment vendors cluster around three strategic archetypes: utility-scale turbine integrators, flexible engine specialists, and distributed generation module suppliers. Dominant competitive moves include hydrogen-ready retrofit partnerships and ammonia cracking technology licensing.
Within the utility-scale turbine tier, Siemens Energy and Mitsubishi Power Europe occupy positions as full-system integrators. Wärtsilä Corp anchors flexible engine installations. 2G Energy AG exemplifies the distributed generation specialist archetype.
| Leading Market Players |
|---|
| 2G Energy AG |
| Mitsubishi Power Europe |
| Siemens Energy |
| E.ON SE |
| Veolia |
| General Electric Company |
| Wärtsilä Corp |
| UPM |
| Engie SA |
| Others |
Supply & Pricing Matrix
Rotterdam's port industrial cluster concentrates turbine manufacturing capacity for hydrogen-ready CHP systems, creating asymmetric pricing power for Dutch EPC contractors serving German and Scandinavian utility buyers. This geographic concentration amplifies cost pass-through when EU carbon border adjustments tighten.
Pricing Analysis
Long-term offtake contracts indexed to TTF natural gas futures dominate utility-scale CHP procurement, with price differentiation hinging on hydrogen-readiness certification tiers and bundled maintenance service levels. Cost compression in standard gas turbine configurations intensifies as Chinese component suppliers enter European supply chains. Industrial heat buyers exhibit highest price sensitivity due to margin pressure in chemical processing, while data center operators accept premium pricing for dedicated thermal supply with CSRD-compliant emissions documentation.
Supply Chain Analysis
EU dual-use export controls on advanced turbine blade alloys restrict flows from German precision foundries to non-European project developers, fragmenting equipment availability. Manufacturing concentrates in Germany, Italy, and the Czech Republic for rotating machinery, with nickel superalloy castings and ceramic thermal barrier coatings as critical dependencies. Single-source vulnerability persists for hydrogen combustion retrofit engineering talent concentrated at Siemens Energy. Distribution runs through utility procurement frameworks and industrial cluster EPC consortia rather than merchant equipment markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment vendor fragmentation across turbine, engine, and micro-CHP tiers creates entry niches as data center thermal demand and ammonia cracking technology displace incumbent utility contracting channels.
For Market Incumbents: Insulate service revenue streams by embedding predictive maintenance digital twins into existing turbine fleets, countering margin erosion from modular engine competitors. Secure backward integration into hydrogen-ready component supply through partnerships with German technical universities, addressing engineering talent scarcity that constrains project execution capacity. For New Entrants and Emerging Players: Pursue Polish district heating modernization opportunities where EU cohesion fund flows exceed local EPC execution capacity, targeting Warsaw and Krakow coal conversion tenders. Enter through ammonia cracking technology licensing rather than pure equipment supply, capturing value from Dutch industrial cluster pilots before pipeline hydrogen infrastructure matures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors flexible engine specialists with proven variable renewable grid integration over pure-play turbine retrofits exposed to hydrogen infrastructure timing risk. Watch F-Gas Regulation refrigerant phasedown enforcement as inflection indicator for absorption chiller manufacturer consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Turbine Retrofit | Siemens Energy anchors German utility contracts while competitors face engineering talent scarcity. |
| Ammonia Cracking Technology Licensing | Dutch port clusters pilot modular converters that bypass pipeline hydrogen dependency. |
| Power-to-Heat Integration | Electrode boiler coupling captures negative electricity prices during renewable oversupply. |
| Biomass Co-Firing Retrofit | Nordic municipalities qualify for carbon-neutral thermal certificates under EU Green Deal. |
| Data Center Direct Thermal Contracting | Frankfurt and Amsterdam hyperscale campuses disintermediate incumbent district heating utilities. |
Research Methodology
Desk research of EU regulatory filings, ETS carbon price databases, and municipal procurement records preceded structured interviews with utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists. Secondary validation drew from IEA CHP tracking reports, FERC-equivalent European grid operator disclosures, and equipment manufacturer technical specifications. Bottom-up project pipeline analysis triangulated against top-down macro efficiency mandate trajectories.
Assumptions held fixed include EU Green Deal enforcement timelines and F-Gas Regulation phasedown schedules, while hydrogen infrastructure deployment pace and natural gas price volatility were treated as scenario variables across the projection horizon. Segmentation modeling spanned technology tier, fuel source, installation scale, and end-user regulatory disclosure obligations. CAGRs derived from unit deployment trajectories and capacity factor assumptions calibrated against historical Danish and German certificate scheme performance.
Sensitivities concentrate around hydrogen delivery timeline revisions and EU ETS carbon price corridor shifts that alter coal-to-gas conversion economics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Circulating Fluidized Bed Boilers Market
Boilers
Oil-Fired Boiler Market
Boilers
Netherlands Combined Heat and Power Market
Boilers
Space Heating Boilers Market
Boilers
Hydrogen Boilers Market
Boilers
Boiler Combustion Chamber Market
Boilers
Fuel Operated Heaters Market
Boilers
Feed Water Heater for Power Plants Market
Boilers
Steam Boiler Market
Boilers
Asia-Pacific Combined Heat and Power Market
Boilers
North America Commercial Boiler Market
Boilers
Fossil Fuel Fired Water Heaters Market
Boilers
North America and Europe Electric Boilers Market
Boilers
North America Residential Boiler Market
Boilers
Boiler System Market
Boilers
Europe Power Plant Boiler Market