
 Industrial Gas Turbine Ignition System Market | 2026-2036
Industrial Gas Turbine Ignition System Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Gas Turbine Ignition System Market Analysis
High-reliability ignition specifications for heavy-duty frame turbines is redrawing competitive priorities across the supply base. General Electric Company leverages its installed base of F-class and H-class turbines to sustain aftermarket ignition contracts across North American power plants. Siemens Energy AG anchors European demand through service agreements tied to its SGT turbine fleet. Woodward, Inc. specializes in electronic ignition controls and occupies a narrow but defensible position in precision timing systems for distributed generation units.
An industrial gas turbine ignition system generates controlled electrical discharge to ignite compressed fuel-air mixtures within combustion chambers, typically operating at excitation voltages between 5 kV and 20 kV and temperatures exceeding 1,200°C during spark events. Dry ignition systems dominate installed capacity due to lower maintenance burdens in baseload power applications, though hybrid configurations are gaining share in peaking plants where rapid cycling degrades conventional electrode life. Electronic ignition technology leads new procurement for grid-connected turbines, while plasma ignition retains niche positions in oil and gas facilities requiring ignition assurance across variable fuel compositions.
EPA emissions standards and the EU F-Gas Regulation shape product roadmaps by mandating lower NOx formation and restricting fluorinated greenhouse gases in cooling circuits adjacent to ignition hardware. FAA airworthiness directives for aviation turbine ignition systems create parallel compliance obligations for manufacturers serving aerospace end users. Stakeholders must monitor evolving EPA rules on methane intensity and EU carbon border adjustments, as these frameworks will determine which ignition architectures qualify for project finance and offtake contracts.
Market Dynamics
EPA methane intensity rules and EU F-Gas Regulation are compressing procurement timelines for ignition system upgrades, forcing power utilities to accelerate replacement cycles for electrode assemblies and exciter modules ahead of scheduled maintenance windows.
Growth Catalysts
- Peaking plant cycling intensity:Grid operators in Texas and California require ignition systems rated for 300+ annual starts, driving procurement of hybrid electrode configurations with extended thermal cycling tolerance.
- China's dual carbon goals:Provincial grid operators in Jiangsu and Guangdong are retrofitting coal-to-gas turbine conversions with electronic ignition architectures to meet MEE emissions benchmarks.
- Hydrogen fuel blending:Pilot programs at German combined-cycle facilities demand spark energy profiles calibrated for variable hydrogen-natgas mixtures, opening specification windows for adaptive ignition controls.
Market Restraints
- High-voltage ceramic supply concentration:Sourcing of alumina insulators for exciter housings concentrates among Japanese and German specialty ceramic producers, exposing OEMs to 18-24 week lead times.
- Plasma ignition substitution:Oil and gas facility operators in the Permian Basin retain plasma torch systems for heavy fuel oil applications, limiting electronic ignition penetration in upstream power generation.
- REACH substance restrictions:ECHA candidate list scrutiny of cobalt-containing electrode alloys is forcing reformulation of spark plug tip materials before full technical qualification.
Strategic Opportunities
- Saudi power sector expansion:SEC's planned 60 GW gas turbine additions through 2030 create demand for ignition system packages bundled with long-term service agreements.
- Digital twin integration:Convergence of ignition timing sensors with predictive maintenance platforms enables outcome-based service pricing for utility fleet operators.
- India PLI scheme alignment:Domestic manufacturing incentives for power generation equipment are drawing ignition system suppliers toward joint ventures with Bharat Heavy Electricals.
Industry Challenges
- High-voltage engineering talent scarcity:Design of 20 kV exciter transformers requires specialized dielectric engineering expertise concentrated among aging workforce cohorts in the US and Germany.
- FAA airworthiness certification overlap:Manufacturers serving both industrial and aviation turbine segments must maintain parallel quality systems, extending product development cycles for dual-use ignition hardware.
- Legacy control system integration:Brownfield power plants operating Woodward or Siemens legacy governor systems face protocol incompatibility when retrofitting modern electronic ignition modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Gas Turbine Ignition System Market |
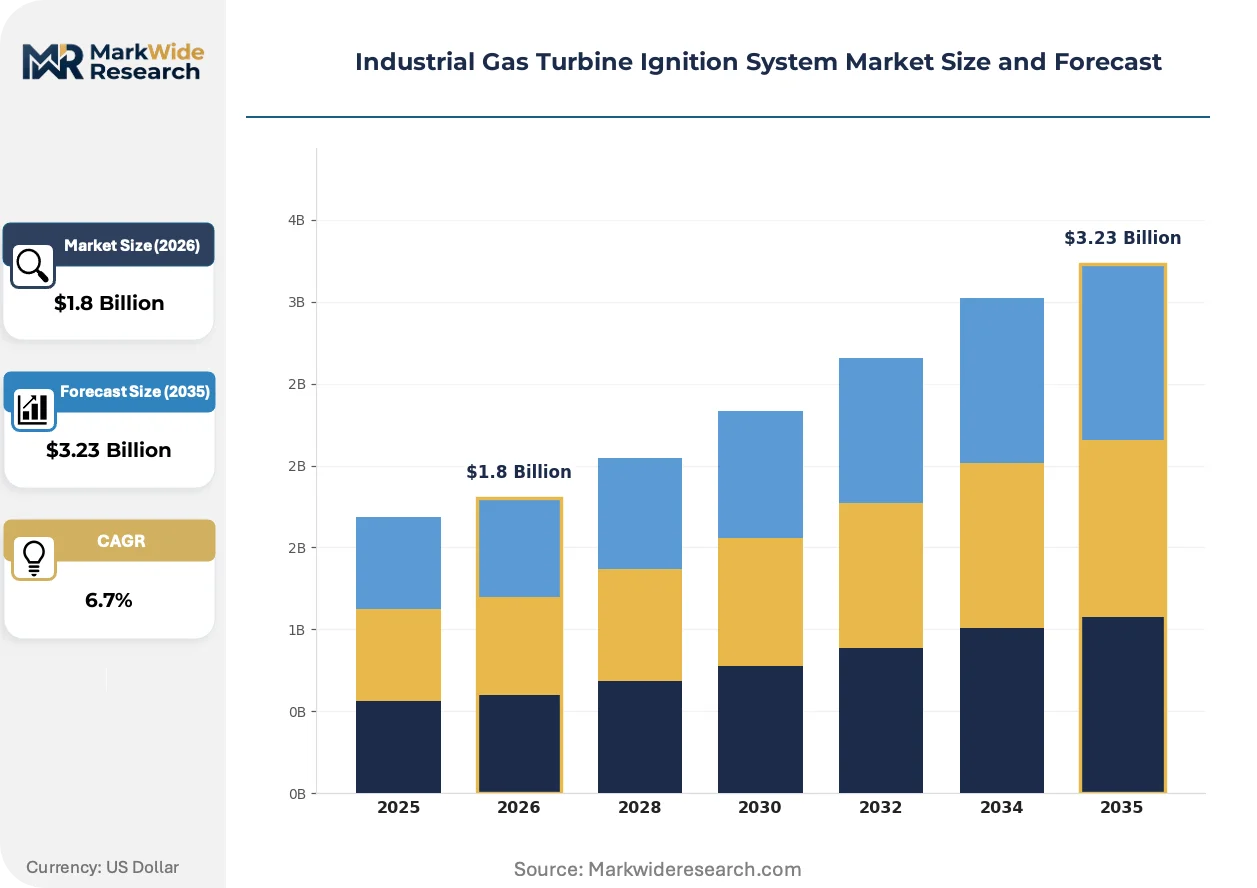
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Ignition System, Wet Ignition System, Hybrid Ignition System, Spark Ignition System Technology: Plasma Ignition, Electronic Ignition, Flame-Proof Ignition, Piezoelectric Ignition End User: Power Generation, Oil & Gas, Marine, Aerospace Application: Industrial Turbine, Aviation Turbine, Electric Generating Turbine, Cogeneration Turbine |
| Companies Covered | Solar Turbines Incorporated, MAN Energy Solutions SE, General Electric Company, Woodward, Inc., Kawasaki Heavy Industries, Ltd., Siemens Energy AG, Ansaldo Energia S.p.A., Champion Aerospace LLC, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Gas Turbine Ignition System Market Emerging Trajectories
Ignition system architecture is fragmenting across three vectors: solid-state exciter technology, emissions-driven specification tightening, and procurement model compression favoring integrated service contracts over component sales.
Solid-state exciter technology is decomposing the traditional transformer-rectifier-spark generator stack into modular semiconductor-based pulse circuits. Grid-connected utilities in Germany and Japan are piloting silicon carbide switching topologies that eliminate oil-filled transformers entirely. This topology shift is decomposing the aftermarket service model by reducing scheduled maintenance intervals from annual to biennial cycles.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant migration in cooling circuits adjacent to ignition exciter enclosures. Turbine OEMs serving European power utilities must now qualify alternative cooling fluids with lower global warming potential for exciter thermal management. Heavy-duty frame turbine segments face the steepest compliance cost escalation as exciter housing redesigns propagate through type certification timelines.
Power utility procurement departments are consolidating ignition system sourcing under fleet-level master service agreements. Independent power producers in Texas and Florida are displacing transactional component purchases with 10-year ignition maintenance contracts bundled with combustion inspection services. This purchasing consolidation is most visible among merchant gas plant operators seeking to lock in spark plug replacement costs against volatile natural gas price environments.
Industrial Gas Turbine Ignition System Market Segmentation
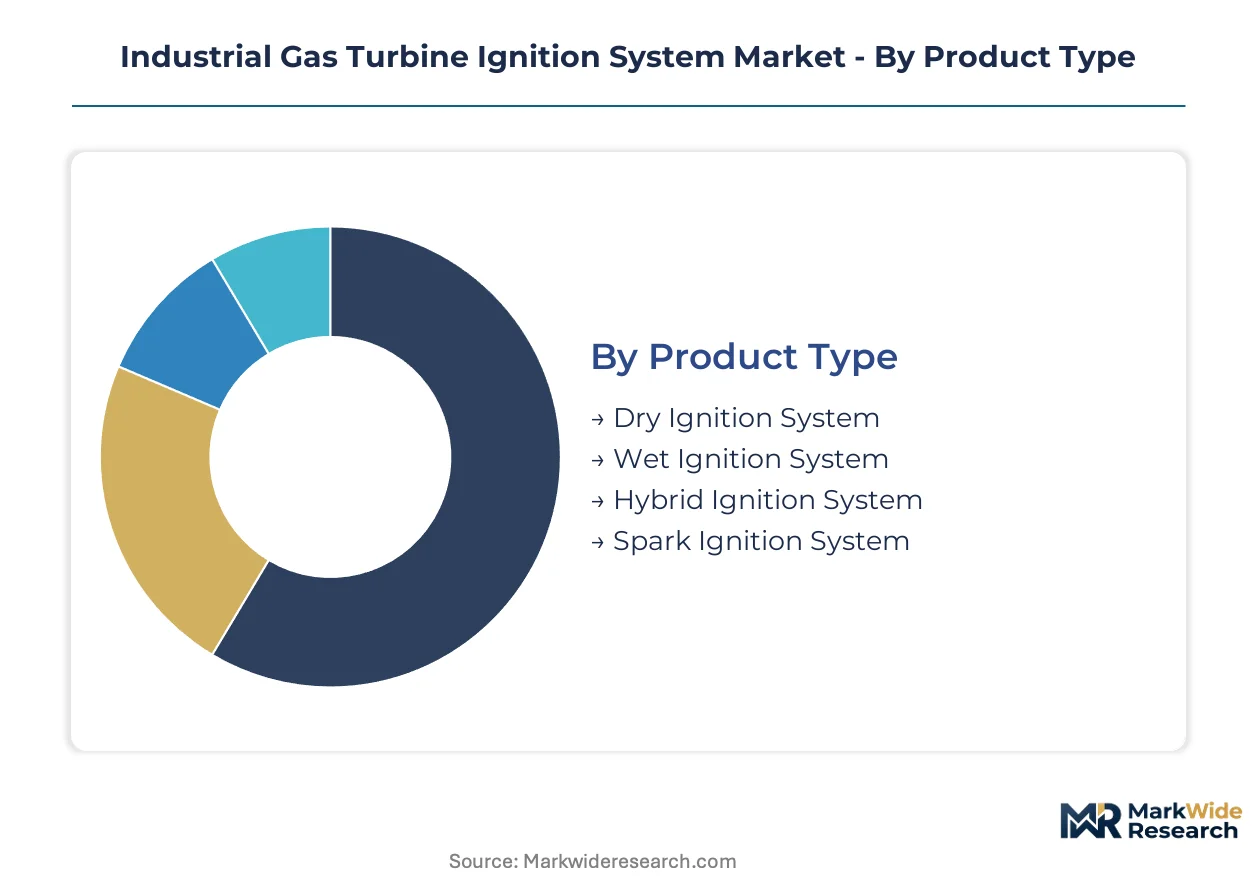
Ignition system procurement splits across four dimensions that determine specification intensity and service contract value. Product type and technology choices lock in maintenance cadences and exciter replacement cycles, while end-user verticals dictate certification requirements and operating environment tolerances.
Product Type:
Margin pools concentrate in configurations that minimize electrode degradation under thermal cycling stress.
- Dry Ignition System:Electrode assemblies operate without liquid cooling circuits, reducing auxiliary system complexity in baseload power plants. North American utilities favor these for combined-cycle facilities running continuous duty cycles, where electrode erosion proceeds predictably and scheduled replacement aligns with combustion inspection windows.
- Hybrid Ignition System:Combines dry electrode architecture with auxiliary cooling for peaking applications requiring 300+ annual starts. Texas and California grid operators specify these for fast-ramp gas turbines where thermal shock accelerates conventional spark plug degradation.
- Wet Ignition System:Liquid-cooled exciter housings serve aviation turbine applications where FAA airworthiness directives mandate thermal management redundancy.
- Spark Ignition System:Conventional transformer-rectifier configurations dominate legacy industrial turbine fleets awaiting electronic ignition retrofits.
Dry ignition systems hold installed capacity. Hybrid configurations are rotating up the share rankings.
Technology:
Technology selection tracks the voltage transformation topology and switching semiconductor material.
- Electronic Ignition:Solid-state pulse circuits using silicon carbide switching elements eliminate oil-filled exciter transformers. German and Japanese utilities pilot these for grid-connected heavy-duty turbines, cutting scheduled maintenance intervals from annual to biennial cycles.
- Plasma Ignition:High-energy torch systems sustain ignition across variable fuel compositions in upstream oil and gas facilities. Permian Basin operators retain these for heavy fuel oil applications where electronic spark energy proves insufficient.
- Flame-Proof Ignition:Explosion-hardened exciter enclosures serve hazardous area classifications in offshore platform power generation.
- Piezoelectric Ignition:Mechanical compression-based spark generation occupies niche positions in small-scale distributed generation units lacking electrical exciter infrastructure.
Electronic ignition is climbing the fastest as solid-state topologies displace transformer-based architectures.
End User:
End-user verticals segment by operating hour intensity and emissions compliance stringency.
- Power Generation:Grid-connected utilities drive specification tightening through fleet-level master service agreements bundling ignition maintenance with combustion inspections.
- Oil & Gas:Upstream and midstream facilities prioritize ignition assurance across variable fuel compositions, retaining plasma systems where fuel quality fluctuates.
- Marine:Classification society rules for redundant ignition channels shape procurement for LNG carrier propulsion turbines.
- Aerospace:FAA airworthiness directives create parallel compliance obligations for manufacturers serving aviation turbine segments.
Power generation holds installed capacity. Oil and gas is rotating up the share rankings.
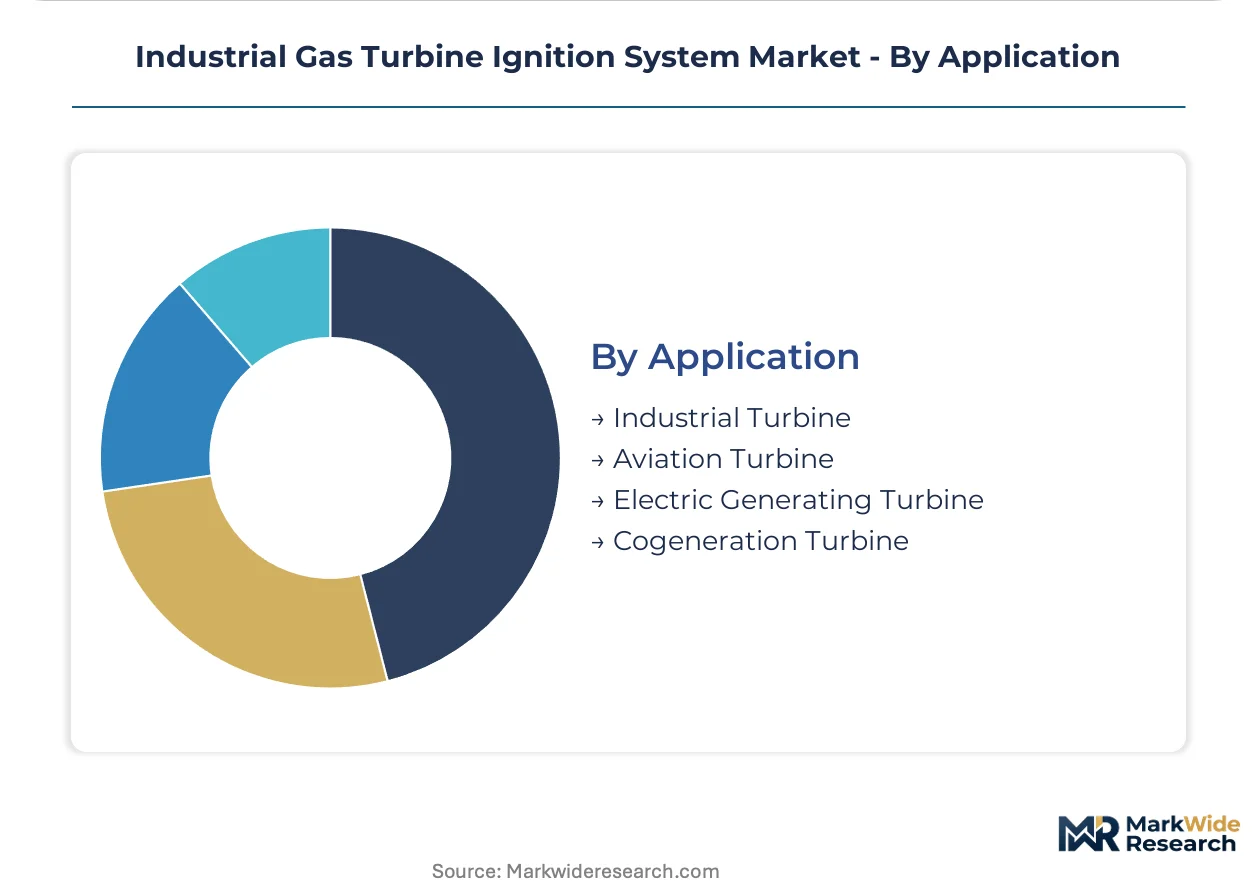
Application:
Application segmentation follows turbine frame size and duty cycle classification.
- Industrial Turbine:Heavy-duty frame units in process industries and manufacturing facilities specify ignition systems rated for continuous baseload operation.
- Electric Generating Turbine:Merchant power plants and utility fleets drive procurement volume through peaking and intermediate duty cycle requirements.
- Cogeneration Turbine:Combined heat and power facilities prioritize ignition reliability for simultaneous electricity and steam production.
- Aviation Turbine:Aero-derivative units for power generation and mechanical drive applications inherit aviation-grade ignition specifications.
Industrial turbines hold installed capacity. Electric generating turbines are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in industrial gas turbine ignition systems favor established manufacturing bases in Germany, Japan, and the United States, with import dependency rising in Saudi Arabia, India, and China as domestic fleet expansion outpaces local production capacity.
United States
ERCOT grid operators in Texas and CAISO-managed utilities in California drive specification intensity for rapid-cycling ignition hardware. EPA methane intensity rules compress procurement timelines for electrode assembly replacements. Houston hosts the densest concentration of gas turbine service providers, where ignition system retrofits align with combined-cycle plant upgrade cycles.
Germany
Combined-cycle facilities in North Rhine-Westphalia pilot hydrogen-natgas blending programs requiring adaptive spark energy calibration. EU F-Gas Regulation phase-down schedules force exciter housing redesigns for lower-GWP cooling fluids. Siemens Energy anchors aftermarket demand through service agreements tied to SGT turbine fleets across Bavarian and Baden-Württemberg industrial zones.
China
Provincial grid operators in Jiangsu and Guangdong retrofit coal-to-gas conversions with electronic ignition architectures. MEE emissions benchmarks mandate cleaner combustion initiation systems. Yangtze River Delta manufacturing clusters concentrate domestic ignition component production, though high-voltage ceramic insulators still import from Japanese suppliers.
Saudi Arabia
SEC's 60 GW gas turbine expansion through 2030 creates demand for ignition packages bundled with long-term service contracts. The country's national power regulator emphasizes grid stability standards that favor high-reliability ignition specifications. Eastern Province industrial cities host the primary installation base for heavy-duty frame turbines requiring upgraded exciter modules.
India
Domestic manufacturing incentives under the PLI scheme draw ignition system suppliers toward joint ventures with Bharat Heavy Electricals. CEA grid codes tighten reliability requirements for peaking plant ignition systems. Gujarat and Maharashtra industrial corridors concentrate new gas turbine installations, with import dependency persisting for solid-state exciter components.
Industrial Gas Turbine Ignition System Market Vendor Landscape
Concentration sits with diversified industrial conglomerates that leverage installed turbine bases to capture recurring aftermarket ignition contracts. The competitive structure tiers across three archetypes: turbine OEMs with captive ignition divisions, independent electronic controls specialists, and aerospace-derived component suppliers. Dominant competitive moves include bundling ignition maintenance into fleet-level service agreements and backward integration into high-voltage ceramic supply chains.
Among turbine OEMs, General Electric Company and Siemens Energy AG exemplify the installed-base leverage archetype, anchoring aftermarket demand through service contracts tied to F-class, H-class, and SGT turbine fleets. Woodward, Inc. occupies the independent controls specialist position, focusing on precision timing systems for distributed generation applications. Champion Aerospace LLC represents the aerospace crossover archetype, bringing FAA-certification-hardened ignition hardware to industrial turbine retrofits.
| Leading Market Players |
|---|
| Solar Turbines Incorporated |
| MAN Energy Solutions SE |
| General Electric Company |
| Woodward, Inc. |
| Kawasaki Heavy Industries, Ltd. |
| Siemens Energy AG |
| Ansaldo Energia S.p.A. |
| Champion Aerospace LLC |
| Mitsubishi Heavy Industries |
| Others |
Supply Flow & Price Mechanics
Fleet-level master service agreements lock in multi-year ignition maintenance contracts for North American power utilities, binding electrode replacement schedules to combustion inspection windows while fixing spark plug unit costs against volatile natural gas price environments. This contracting pattern concentrates pricing power with turbine OEMs holding installed base leverage, particularly as EPA methane intensity rules compress procurement timelines and eliminate spot-market purchasing flexibility.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels differentiated by certification grade and after-sales service bundling. Premium tiers capture FAA-certification-hardened hardware for aero-derivative applications, while economy tiers serve distributed generation units with reduced thermal cycling tolerance. Cost compression in standard-tier electronic ignition modules is intensifying because solid-state exciter technology cuts maintenance intervals and erodes recurring revenue pools. Merchant power producers in Texas exhibit highest price sensitivity due to merchant margin exposure, whereas Saudi Electric Company fleet operators show lowest sensitivity given sovereign-backed procurement budgets.
Supply Chain Analysis
Japan and Germany anchor high-voltage ceramic insulator production for exciter housings, with Japanese specialty ceramic producers feeding alumina components to Siemens Energy and General Electric captive manufacturing networks. Solid-state switching semiconductors draw from Taiwan wafer fabrication and German power electronics packaging facilities. Single-source vulnerability concentrates in 20 kV dielectric engineering talent pools concentrated among aging workforce cohorts in the United States and Germany. Distribution runs through turbine OEM service subsidiaries and independent combustion inspection contractors serving utility fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial gas turbine ignition system market functions as a defensive-moat arena where regulatory entrenchment protects incumbent positions. EPA emissions standards and EU F-Gas Regulation create certification barriers that lock out unqualified suppliers and cement existing aftermarket relationships.
For Market Incumbents: Shield installed base revenue by deepening backward integration into high-voltage ceramic supply chains, capturing Japanese and German specialty insulator producers before lead time exposures disrupt electrode assembly fulfillment. Accelerate solid-state exciter qualification timelines to outpace plasma ignition substitution threats in Permian Basin oil and gas facilities. Prioritize hydrogen-natgas blend calibration capabilities to capture German combined-cycle retrofit specifications. For New Entrants and Emerging Players: Aftermarket service gaps in legacy Woodward and Siemens governor protocol integration present entry points for protocol bridge technology suppliers targeting brownfield power plant retrofits. India's PLI scheme manufacturing incentives offer the most penetrable geography, particularly through joint venture structures with Bharat Heavy Electricals that satisfy domestic content requirements. Lead with digital twin integration capabilities to differentiate against incumbent combustion inspection bundling. For Investors and Strategic Acquirers: Independent electronic controls specialists with precision timing IP and established FAA certification pathways represent prime acquisition targets, offering aerospace-to-industrial crossover technology transfer potential. Long-term viability hinges on hydrogen fuel blending specification windows and solid-state exciter adoption curves across German and Japanese grid-connected utilities. Monitor ECHA candidate list decisions on cobalt-containing electrode alloys as inflection indicators for material reformulation cost exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Supply | Captures Japanese alumina insulator capacity to secure 20 kV exciter housing production. |
| Hydrogen Blend Calibration Investment | Positions suppliers for German combined-cycle pilot programs requiring adaptive spark energy. |
| Digital Twin Platform Development | Enables outcome-based service pricing for Texas and California peaking plant operators. |
| PLI Scheme Joint Venture Formation | Unlocks Indian domestic manufacturing incentives tied to Bharat Heavy Electricals partnerships. |
| Solid-State Exciter Qualification | Eliminates oil-filled transformers to cut maintenance intervals for Japanese utility pilots. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EIA power plant databases, FERC interconnection queues, EPA emissions compliance filings, and EU ETS installation records. Interviews with utility maintenance directors, OEM aftermarket service heads, EPC combustion engineers, and high-voltage ceramic procurement leads informed specification intensity and contract structure validation. Bottom-up triangulation across electrode assembly shipment records and top-down reconciliation against gas turbine installation databases anchored market sizing.
Segmentation dimensions modeled span product type, technology topology, end-user vertical, and application duty cycle across the projection horizon. CAGRs derive from regression against historical replacement cycle data and regulatory compliance timeline acceleration. Forecast inputs incorporate hydrogen blending pilot expansion rates and solid-state exciter adoption curves in grid-connected heavy-duty segments.
Underlying assumptions cover EPA methane rule implementation pacing and EU F-Gas phase-down adherence, with deviation risk concentrated in ECHA substance restriction timing and Japanese ceramic export license volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Steam Turbine Control System Market
Power Equipment
Power Recovery Winches Market
Power Equipment
Wind Turbine Components Market
Power Equipment
Global Power Rental Systems Market
Power Equipment
Portable Power Station Market
Power Equipment
Qatar Power EPC Market
Power Equipment
United Arab Emirates Power EPC Market
Power Equipment
France Power EPC Market
Power Equipment
Kazakhstan Power EPC Market
Power Equipment
Global Hydraulic Power Unit Market
Power Equipment
Australia Power EPC Market
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
Power Infrastructure Market
Power Equipment
Asia-Pacific Steam Turbine Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Variable Frequency Drive (VFD) Market