
 US Combined Heat and Power (CHP) Market | 2026-2036
US Combined Heat and Power (CHP) Market Size, Share, and Industry Trends Forecast 2026-2036
US Combined Heat and Power (CHP) Market Analytics
A shortage of certified turbine technicians and stationary engine specialists is reorganizing project timelines across the US CHP landscape. General Electric Company leverages its deep field-service network to sustain long-term maintenance contracts at utility-scale installations. Caterpillar Inc. anchors the commercial-industrial midrange with reciprocating engine packages that dominate hospital and campus deployments. Cummins Inc. competes on fast-start capability and modular packaging for distributed generation sites.
Combined Heat and Power captures waste thermal energy from electricity generation for productive heating, cooling, or industrial process applications, typically achieving total system efficiencies of sixty to eighty percent versus separate heat and power production. Gas turbine technology leads in large-scale industrial settings where high-pressure steam demand justifies capital intensity, while reciprocating engine systems occupy the fastest-expanding tier among commercial end users seeking sub-twenty-megawatt footprints. Natural gas retains primacy as the dominant fuel type, though biomass and waste heat recovery segments are gaining traction where carbon accounting and landfill gas access reshape project economics.
EPA Clean Air Act standards, FERC interconnection rules, and state-level renewable portfolio standards collectively shape equipment specifications, dispatch economics, and market access for CHP developers. NHTSA and OSHA workplace safety requirements further constrain installation practices and operational protocols at manufacturing and institutional sites. Stakeholders must monitor evolving carbon border adjustments and utility rate redesigns that could revalue on-site thermal-electric assets faster than equipment replacement cycles allow.
Market Dynamics
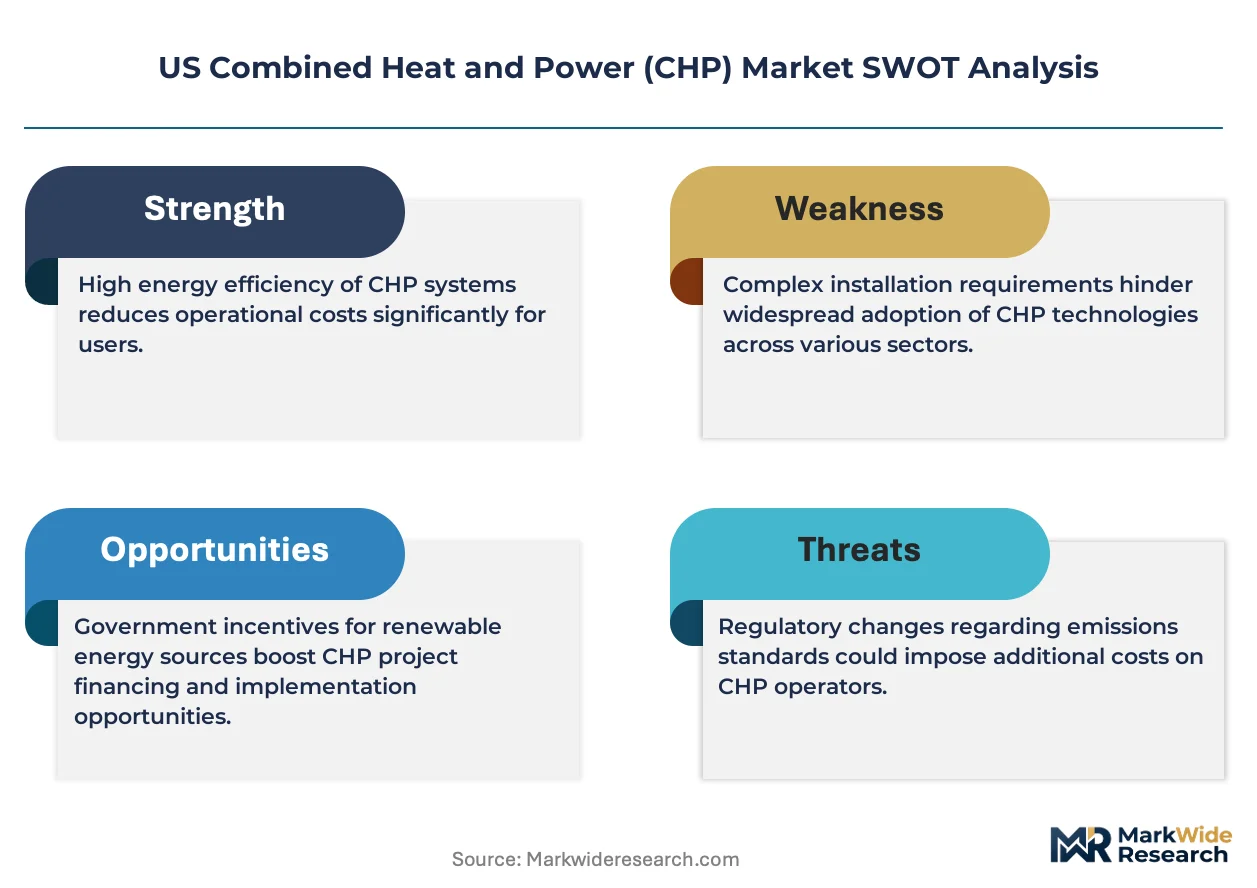
EPA emissions standards and state-level clean energy mandates are compressing project timelines while simultaneously expanding the addressable market for fuel-flexible CHP systems across industrial and institutional load centers.
Growth Catalysts
- Grid Instability Resilience:Hospitals across the Midwest and Northeast are expanding on-site generation to secure uninterrupted operations during extreme weather events and transmission failures.
- IRA Clean Energy Incentives:Federal tax credits for efficient thermal-electric systems are improving project economics for campus and manufacturing deployments.
- Reciprocating Engine Efficiency Gains:Fast-start modular packages are capturing sub-twenty-megawatt commercial sites previously served by separate heat and power infrastructure.
Market Restraints
- Certified Technician Scarcity:A shortage of turbine technicians and stationary engine specialists is extending commissioning timelines and inflating service contract premiums.
- Natural Gas Price Volatility:Fuel cost uncertainty undermines long-term dispatch economics for baseload CHP installations dependent on pipeline supply contracts.
- FERC Interconnection Delays:Utility queue backlogs and technical study requirements stretch project development cycles by eighteen to thirty-six months in high-demand territories.
Strategic Opportunities
- Texas Industrial Load Centers:Petrochemical and refining clusters along the Gulf Coast present untapped demand for high-pressure steam integration with electric generation.
- Biomass Fuel Convergence:Landfill gas and agricultural waste streams are enabling carbon-negative project economics where renewable thermal credits apply.
- Utility Rate Redesign Tailwinds:Demand charges and time-of-use structures in California and New York are revaluing on-site thermal-electric assets against grid-purchased alternatives.
Industry Challenges
- Turbine Specialist Pipeline Collapse:Aging field-service workforce and limited apprenticeship throughput constrain OEM capacity to honor long-term maintenance obligations.
- Stack Compliance Complexity:Navigating overlapping EPA Clean Air Act standards, state air quality regulations, and local permitting creates certification bottlenecks.
- Legacy Control System Integration:Retrofitting digital monitoring and dispatch optimization onto existing reciprocating engine installations demands specialized engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Combined Heat and Power (CHP) Market |
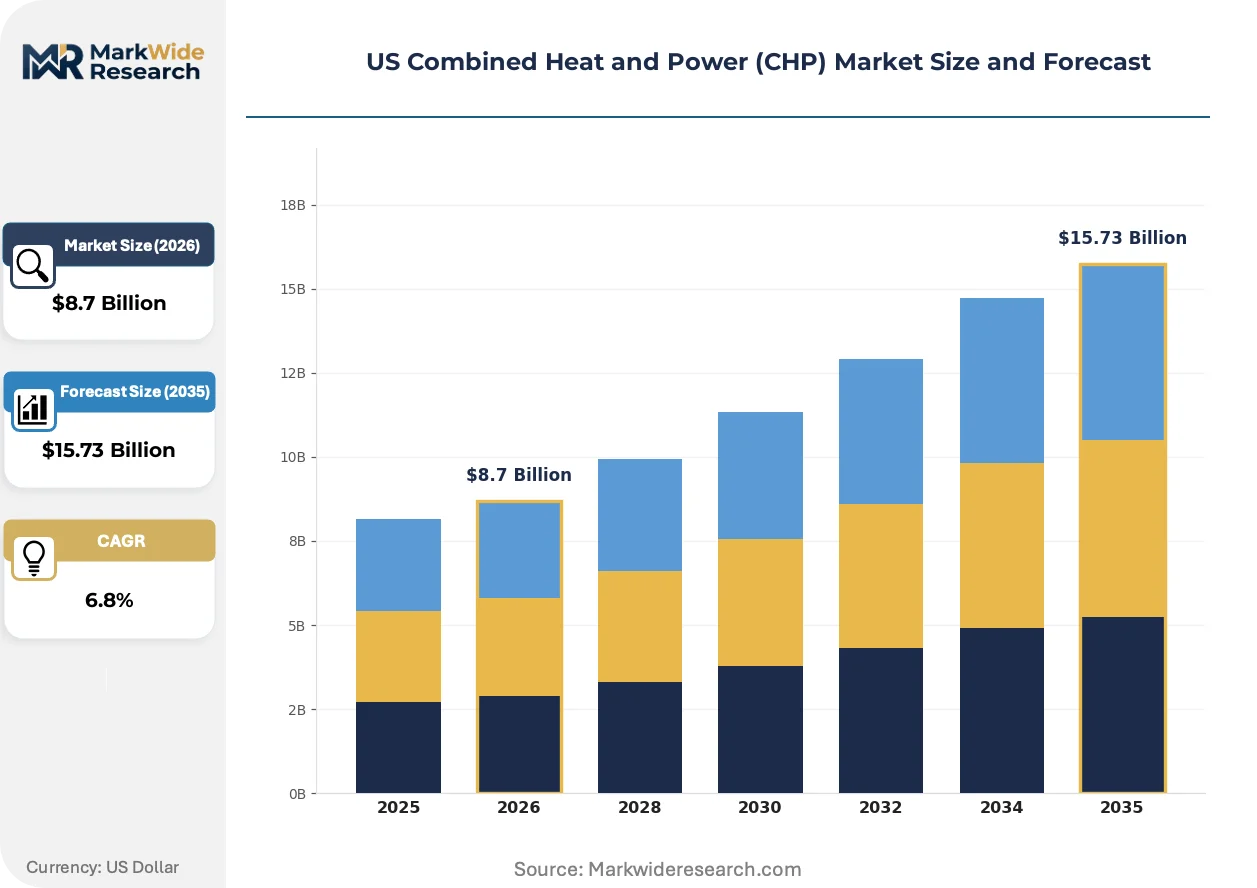
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Reciprocating Engine, Gas Turbine, Steam Turbine, Microturbine Application: Industrial, Commercial, Residential, District Energy Fuel Type: Natural Gas, Biomass, Coal, Waste Heat End User: Manufacturers, Hospitals, Educational Institutions, Hotels |
| Companies Covered | General Electric Company, 2G Energy Inc., Caterpillar Inc., Cummins Inc., Aegis Energy Services Inc., Curtis Engine & Equipment Co., Yanmar America Corp, Capstone Turbine Corporation, FuelCell Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Combined Heat and Power (CHP) Market Evolving Landscape
Technology trajectories in the US CHP landscape are diverging between large-scale turbine deployments and distributed reciprocating engine systems, with regulatory pressure and procurement innovation accelerating both paths simultaneously.
Gas turbine technology is bifurcating the industrial segment by separating high-pressure steam-dependent facilities from sites where thermal load profiles favor reciprocating alternatives. Petrochemical complexes along the Texas Gulf Coast are sustaining capital-intensive turbine investments for process steam integration. This technology split is compressing the mid-scale market where neither architecture delivers optimal economics.
EPA Clean Air Act standards are tightening stack emissions requirements for nitrogen oxides and particulate matter across existing and greenfield installations. Industrial operators are responding with selective catalytic reduction retrofits and fuel-flexible system designs. The Northeast corridor faces the most acute compliance pressure due to non-attainment zone designations and state-level carbon caps.
Hospital procurement patterns are migrating from capital purchase toward long-term energy service agreements with guaranteed thermal output and uptime commitments. Third-party developers are assuming construction risk and operational responsibility in exchange for fifteen-to-twenty-year offtake contracts. This shift is most pronounced in California and New York where utility rate structures amplify the value of predictable thermal-electric costs.
US Combined Heat and Power (CHP) Market Segmentation
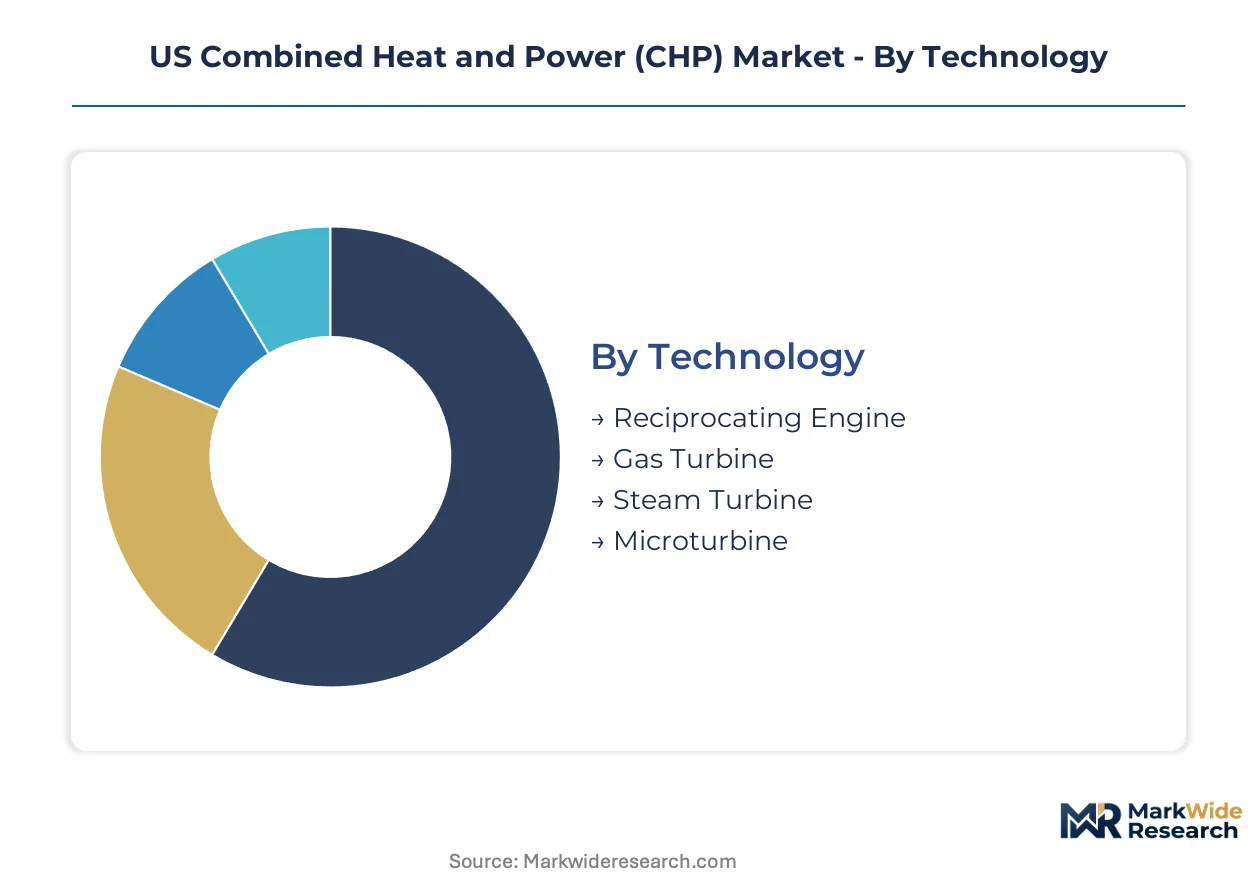
Technology selection in the US CHP market determines capital intensity, thermal output quality, and regulatory compliance pathways. Fuel flexibility and end-use thermal profiles drive substitution patterns across installation types.
Technology:
Reciprocating engine systems face mounting pressure from microturbine alternatives in sub-five-megawatt commercial sites where maintenance simplicity outweighs thermal efficiency premiums.
- Reciprocating Engine:Modular packages deliver fast-start capability and sub-twenty-megawatt footprints ideal for hospital and campus deployments. Midwest and Northeast healthcare facilities are standardizing on these systems to secure resilience against grid instability while meeting EPA emissions standards through selective catalytic reduction.
- Gas Turbine:High-pressure steam output serves petrochemical and refining clusters along the Texas Gulf Coast where process thermal demand justifies capital intensity. FERC interconnection delays compress project timelines but do not deter industrial operators seeking baseload thermal-electric integration.
- Steam Turbine:Legacy infrastructure in paper and chemical manufacturing leverages existing boiler assets for combined-cycle retrofits.
- Microturbine:Compact footprints target distributed generation sites with limited mechanical space and simplified maintenance requirements.
Reciprocating engine systems anchor the volume base while microturbine installations gain share at the steepest rate in commercial sub-utility applications.
Application:
Cost tier differentiation separates capital-intensive industrial deployments from operational-expense-focused commercial contracts.
- Industrial:Petrochemical, refining, and paper manufacturing operations require high-pressure steam integration with electric generation. Texas and California load centers concentrate demand where utility rate structures reward thermal-electric baseload operation.
- Commercial:Office complexes and retail centers prioritize fast-start modular systems under fifteen megawatts. Third-party energy service agreements are displacing capital purchases as hospital procurement patterns migrate toward guaranteed thermal output contracts.
- Residential:Limited deployment concentrates in multi-unit developments with centralized thermal distribution.
- District Energy:University campuses and urban heating networks leverage centralized CHP for thermal load aggregation.
Industrial applications dominate installed capacity while commercial deployments expand most quickly through energy-as-a-service contracting models.
Fuel Type:
Carbon accounting requirements and landfill gas access reshape project economics across fuel categories.
- Natural Gas:Pipeline supply contracts dominate baseload installations despite price volatility undermining long-term dispatch economics. EPA Clean Air Act standards tighten stack requirements for nitrogen oxides, driving selective catalytic reduction retrofits across existing turbine and engine fleets.
- Biomass:Landfill gas and agricultural waste streams enable carbon-negative economics where renewable thermal credits apply. Agricultural processing clusters in the Midwest are converging on biomass fuel convergence for waste-to-energy integration.
- Coal:Declining installation rate reflects state-level clean energy mandates and carbon border adjustment pressures.
- Waste Heat:Industrial process recovery systems capture exhaust thermal energy for secondary power generation.
Natural gas retains primacy in installed base while biomass fuel types climb the fastest under state renewable portfolio standards.
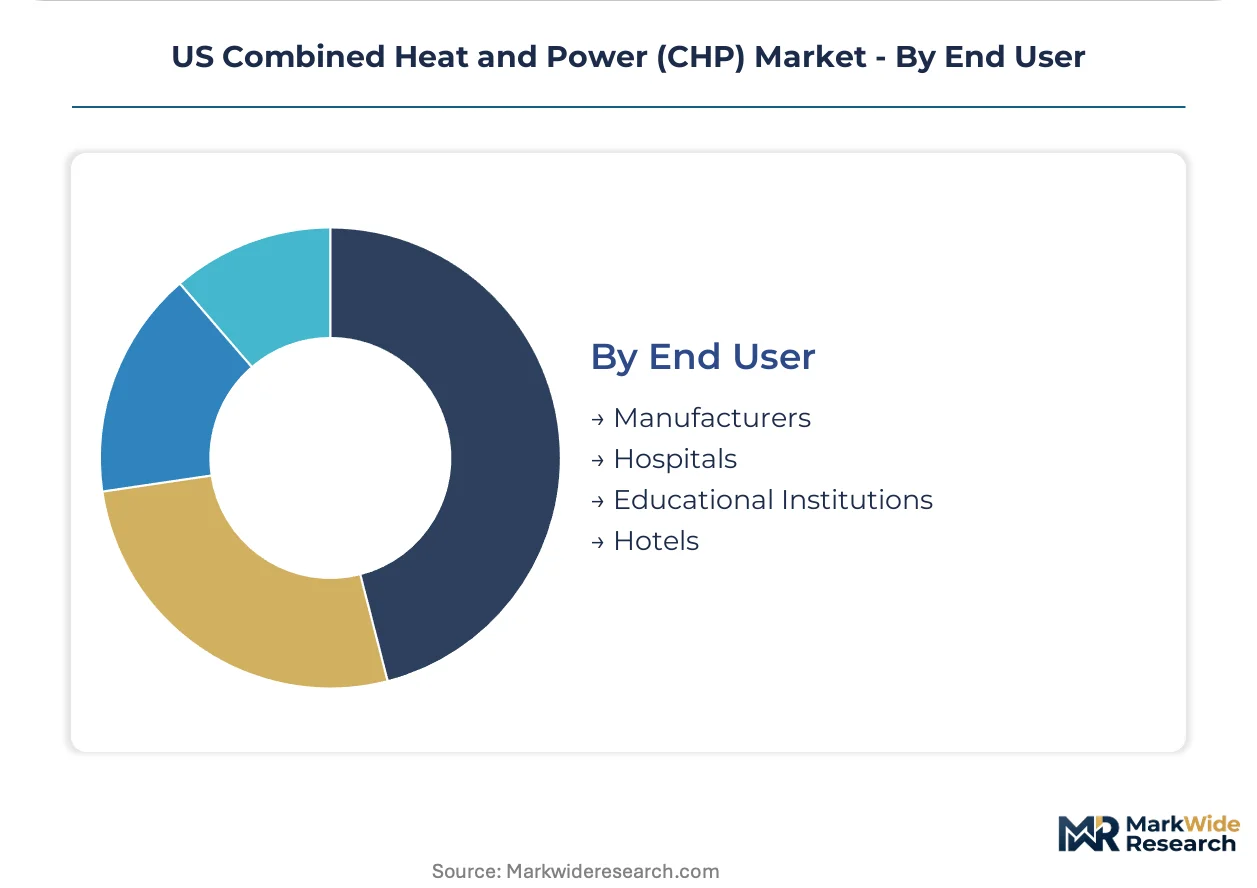
End User:
Customer type determines procurement structure, uptime requirements, and regulatory exposure.
- Manufacturers:Petrochemical and refining operations along the Texas Gulf Coast sustain demand for high-pressure steam integration. OSHA workplace safety requirements constrain installation practices while FERC interconnection rules shape dispatch economics.
- Hospitals:Critical facility status mandates uninterrupted thermal and electric supply during extreme weather events. Midwest and Northeast healthcare systems are expanding on-site generation to secure resilience against transmission failures.
- Educational Institutions:University campuses leverage district energy architectures for thermal load aggregation and carbon reduction commitments.
- Hotels:Hospitality operators prioritize operational expense predictability through third-party thermal service contracts.
Manufacturers anchor the volume base while hospitals gain share at the steepest rate driven by resilience mandates and IRA clean energy incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions standards anchor the US CHP landscape, with state-level mandates compressing timelines across industrial and institutional load centers. Texas, California, and New York concentrate demand where utility rate structures reward thermal-electric integration. Regional deployment patterns diverge between Gulf Coast process steam applications and Northeast resilience-driven hospital installations.
Texas
Petrochemical and refining clusters along the Gulf Coast sustain demand for high-pressure steam integration with electric generation. EPA Clean Air Act standards tighten stack requirements for nitrogen oxides, driving selective catalytic reduction retrofits across existing turbine fleets. Houston and Beaumont industrial corridors anchor capacity additions where process thermal demand justifies capital-intensive baseload configurations.
California
Hospital procurement patterns are migrating from capital purchase toward long-term energy service agreements with guaranteed thermal output commitments. State-level clean energy mandates and renewable portfolio standards accelerate fuel-flexible system deployments across campus and manufacturing sites. Los Angeles and San Francisco Bay Area load centers concentrate third-party developer activity where utility rate redesigns amplify on-site asset valuations.
New York
Critical facility status mandates uninterrupted thermal and electric supply for healthcare systems across the Northeast corridor. FERC interconnection delays compress project timelines but do not deter institutional operators seeking resilience against transmission failures. New York City and Albany metropolitan areas standardize on fast-start reciprocating engine packages for sub-twenty-megawatt footprints.
Illinois and Ohio
Agricultural processing clusters in the Midwest are converging on biomass fuel streams for waste-to-energy integration. State air quality regulations and local permitting create certification bottlenecks for landfill gas access projects. Chicago and Cleveland industrial zones leverage existing boiler assets for combined-cycle retrofits where carbon accounting reshapes project economics.
Pennsylvania
Paper and chemical manufacturing operations require high-pressure steam integration with legacy infrastructure for combined-cycle retrofits. OSHA workplace safety requirements constrain installation practices while EPA emissions standards tighten stack requirements across existing engine fleets. Pittsburgh and Philadelphia metropolitan areas anchor demand where district energy architectures enable thermal load aggregation.
US Combined Heat and Power (CHP) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the US CHP market, with OEMs fielding deep service networks to capture long-term maintenance obligations. The vendor base separates between utility-scale turbine fabricators and modular engine packagers serving commercial sub-twenty-megawatt sites. Strategic archetypes include full-lifecycle service integrators, fast-start modular specialists, and fuel-flexible technology licensors. Competitive moves concentrate on securing certified technician pipelines and locking in fifteen-to-twenty-year offtake contracts through energy-as-a-service structures.
Within the integrated service tier, General Electric Company and Caterpillar Inc. exemplify contrasting scale positions—one anchoring utility-scale field-service networks, the other dominating hospital and campus deployments with reciprocating engine packages. Cummins Inc. occupies a distinct position among fast-start modular specialists serving distributed generation sites. These three entities represent the competitive core around which smaller specialists and regional fabricators organize their market access strategies.
| Leading Market Players |
|---|
| General Electric Company |
| 2G Energy Inc. |
| Caterpillar Inc. |
| Cummins Inc. |
| Aegis Energy Services Inc. |
| Curtis Engine & Equipment Co. |
| Yanmar America Corp |
| Capstone Turbine Corporation |
| FuelCell Energy |
| Others |
Value Network & Pricing Analysis
EPA Clean Air Act certification tiers gate both supplier qualification and price differentiation simultaneously, with selective catalytic reduction compliance separating premium turbine packages from standard reciprocating engine configurations across hospital and industrial procurement channels.
Pricing Analysis
Long-term energy service agreements dominate hospital and campus deployments, with fifteen-to-twenty-year offtake contracts displacing capital purchases in California and New York. Price differentiation rests on fast-start capability guarantees and selective catalytic reduction certification tiers, with commercial buyers showing highest sensitivity to upfront capital outlay while industrial operators prioritize thermal output reliability. Pricing pressure intensifies in the sub-five-megawatt commercial tier as microturbine alternatives compete on maintenance simplicity.
Supply Chain Analysis
Strategic stockpiling of turbine components and reciprocating engine parts prevails over just-in-time approaches given eighteen-to-thirty-six-month FERC interconnection timelines and certified technician scarcity. Manufacturing concentrates in the United States, Germany, and Japan for precision turbine components and control systems. Raw material dependencies include nickel-based superalloys, high-grade steel forgings, and selective catalytic reduction catalyst substrates. Supply chain risk centers on single-source vulnerability for specialized turbine blade castings. Distribution runs through OEM-authorized service networks and third-party EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates acquisition opportunities as procurement patterns fragment between utility-scale turbine deployments and distributed commercial engine packages, with third-party energy-as-a-service developers capturing hospital and campus segments previously served by direct OEM sales.
For Market Incumbents: Consolidate field-service network coverage to honor long-term maintenance obligations amid certified technician scarcity. Acquire regional reciprocating engine specialists in Texas and California to secure fifteen-to-twenty-year offtake contract pipelines. Backward integration into selective catalytic reduction catalyst supply hedges EPA compliance cost volatility. For New Entrants and Emerging Players: Differentiate on fuel-flexible system designs enabling biomass and landfill gas convergence for carbon-negative project economics. Target agricultural processing clusters in the Midwest where renewable thermal credits apply and incumbent coverage remains thin. Pursue fast-start modular packaging for sub-twenty-megawatt hospital deployments in the Northeast corridor. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across microturbine and fuel-flexible technology tiers as manufacturing scale economies mature. Long-term viability favors developers with locked utility rate redesign exposure in California and New York. Acquisition targets should show contracted recurring revenue streams from energy service agreements. Watch FERC interconnection queue clearance rates as inflection indicator for development cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Field-Service Network Expansion | General Electric and Caterpillar leverage technician pipelines to capture long-term maintenance contracts at utility-scale installations. |
| Fuel-Flexible Technology Licensing | Biomass convergence capabilities unlock carbon-negative economics where EPA emissions standards and state renewable portfolio standards intersect. |
| Energy-as-a-Service Platform Buildout | Third-party developers assume construction risk for hospital deployments under guaranteed thermal output commitments in California and New York. |
| Selective Catalytic Reduction Retrofit Programs | Existing turbine and engine fleets require nitrogen oxides compliance upgrades across non-attainment zones in the Northeast corridor. |
| Fast-Start Modular Packaging Development | Reciprocating engine systems capture sub-twenty-megawatt commercial sites previously served by separate heat and power infrastructure. |
Research Methodology
The analysis maps gas turbine, reciprocating engine, steam turbine, and microturbine technology tiers, each validated through plant engineers at petrochemical facilities, maintenance directors at Midwest hospitals, EPC contractors, and utility interconnection planners. Primary interviews with OEM field-service managers and third-party energy service developers combined with secondary validation against EPA Clean Air Act filings, FERC interconnection queue databases, EIA generation statistics, and state renewable portfolio standard registries. Bottom-up installation capacity estimates triangulated against top-down market value projections.
Consistency checks validated volume and value outputs against EIA commercial and industrial CHP deployment benchmarks and state-level incentive program uptake data. Segmentation dimensions modeled include technology type, fuel source, application tier, and regional regulatory framework across the projection horizon. CAGRs derived from trend-line extrapolation of historical deployment rates adjusted for IRA clean energy incentive phase-in effects and utility rate redesign implementation timelines.
Decision-makers should treat outputs as directional under assumptions of continued EPA emissions standard tightening and natural gas price volatility within historical bands; material deviation would warrant model refresh. Revision becomes warranted when FERC interconnection queue clearance rates or certified technician apprenticeship throughput crosses thresholds that compress or extend project development cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Boilers
Biomass Boiler Market
Boilers
Residential Boiler Market
Boilers
Fossil Fuel Fired Water Heaters Market
Boilers
Europe Power Plant Boiler Market
Boilers
Industrial Boiler MRO Market
Boilers
US Boiler Market
Boilers
Boiler Combustion Chamber Market
Boilers
Power Boiler Market
Boilers
Hydrogen Boilers Market
Boilers
Power Plant Boiler Market
Boilers
Fire Tube Industrial Boiler Market
Boilers
Boiler Control Market
Boilers
Germany Combined Heat and Power Market
Boilers
Industrial and Residential Heating Market
Boilers
Gas Condensing Boiler Market
Boilers
Marine Boiler Burner Market