
 Marine Biotechnology Market | 2026-2036
Marine Biotechnology Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Biotechnology Market Intelligence
The EU Marine Strategy Framework Directive is broadening compliance requirements for sustainable marine biomass extraction across European waters. Corbion N.V. leverages its algae fermentation infrastructure to supply omega-3 alternatives for aquafeed and human nutrition. Aker BioMarine ASA anchors Antarctic krill harvesting operations with Marine Stewardship Council certification. DSM-Firmenich specializes in marine-derived nutritional lipids, competing on pharmaceutical-grade purity standards.
Marine biotechnology encompasses the application of molecular biology, fermentation science, and aquaculture techniques to cultivate, extract, and modify organisms from marine ecosystems for commercial use. Bioactive compounds extracted from deep-sea microorganisms require cold-chain bioprocessing and sterile fermentation at controlled salinity levels to preserve pharmacological activity. Enzymes from extremophile bacteria dominate current product-type revenue due to their catalytic stability in industrial processes, while bioplastics from algal polysaccharides represent the fastest-expanding category as packaging mandates tighten. Functional foods applications attract premium pricing from nutraceutical suppliers seeking clinically validated marine ingredients.
The European Medicines Agency evaluates marine-derived pharmaceuticals through centralized marketing authorization pathways, while the U.S. Food and Drug Administration maintains specific guidance for complex natural product submissions from aquatic sources. REACH compliance in Europe and evolving EPA discharge standards for U.S. coastal bioprocessing facilities both elevate capital requirements for new entrants. Stakeholders must monitor regulatory divergence between jurisdictions to optimize clinical trial placement and manufacturing location decisions.
Market Dynamics
Pharmaceutical pipelines are scaling marine-derived compound screening, while sustainable harvesting mandates from the EU Marine Strategy Framework Directive force bioprospecting operations into certified Antarctic corridors and Arctic zones with stricter biomass quotas.
Growth Catalysts
- Antarctic Bioprospecting Corridors:Marine Stewardship Council certification unlocks institutional investment for krill-derived omega-3 extraction, channeling capital into sterile cold-chain bioprocessing infrastructure.
- REACH Biomass Compliance:ECHA registration pathways for novel marine substances create first-mover advantages for European fermentation facilities with pre-validated extraction protocols.
- Algal Polysaccharide Bioplastics:Packaging mandates in food service and cosmetics are displacing petroleum-based films with seaweed-derived barrier materials.
Market Restraints
- Deep-Sea Access Costs:Manned submersible and ROV deployment for extremophile collection requires capital intensity that excludes mid-scale fermentation operators from novel compound pipelines.
- Krill Harvest Concentration:Antarctic biomass quotas consolidate extraction rights among MSC-certified operators, limiting feedstock diversification for omega-3 suppliers outside the certification perimeter.
- Cold-Chain Dependency:Bioactive compound degradation outside controlled salinity and temperature parameters forces redundant processing infrastructure at collection and fermentation sites.
Strategic Opportunities
- Indian Ocean Cyanobacteria:Underexplored photosynthetic microbial mats in Seychelles and Madagascar waters offer untapped alkaloid diversity for neuropharmacology screening programs.
- CSRD Supply Chain Disclosure:EU corporate sustainability reporting mandates create premium pricing corridors for marine ingredients with documented biomass provenance and carbon-negative cultivation claims.
- CRISPR-Assisted Cultivation:Gene-editing convergence with photobioreactor automation is compressing strain optimization cycles for high-value carotenoid production.
Industry Challenges
- Extremophile Cultivation Expertise:The talent pool for piezophilic and psychrophilic organism husbandry remains concentrated at fewer than twelve academic marine stations worldwide, constraining workforce scaling.
- Marine-Derived IND Timelines:FDA complex natural product guidance requires extended pharmacokinetic validation for polysaccharide-based therapeutics, stretching development timelines relative to synthetic analogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Biotechnology Market |
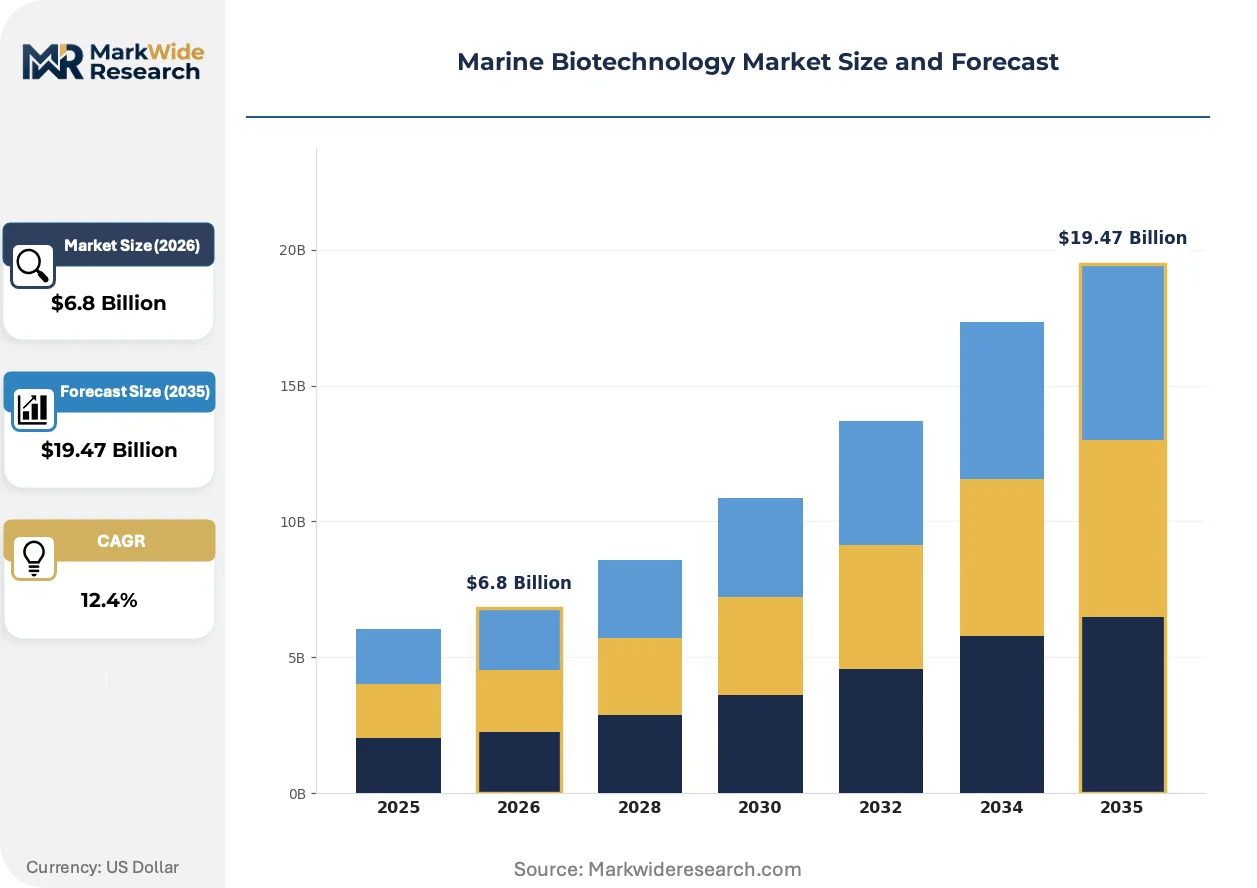
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $19.47 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Bioactive Compounds, Carbohydrates, Bioplastics Application: Aquaculture, Pharmaceuticals, Cosmetics, Functional Foods End User: Research Institutions, Biopharmaceutical Companies, Nutraceutical Suppliers, Cosmetic Manufacturers Technology: Genetic Engineering, Bioprocessing, Fermentation, Aquaculture Techniques |
| Companies Covered | Corbion N.V., Lonza Group Ltd, BASF SE, Qingdao Seawin Biotech, DSM-Firmenich, Aker BioMarine ASA, PharmaMar S.A., DuPont de Nemours, Inc., Cyanotech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Biotechnology Market Strategic Shifts & Innovations
Synthetic biology tools are compressing strain development timelines while regulatory disclosure mandates restructure procurement criteria around verified biomass provenance.
Metagenomic sequencing platforms are unifying taxonomic identification with biosynthetic gene cluster prediction, enabling pharmaceutical screening programs to bypass cultivation bottlenecks for unculturable deep-sea microorganisms. Contract research organizations in Norway and California are deploying these platforms at scale. The technology is unifying discovery-phase timelines that previously required years of axenic culture establishment into months of bioinformatic prioritization.
EU F-Gas Regulation phase-down schedules are accelerating adoption of natural refrigerants in cold-chain bioprocessing, forcing Antarctic and Arctic collection vessels to retrofit ammonia and CO2 systems. Marine-derived compound handlers face capital reallocation toward compliant infrastructure. Norwegian krill operators are responding with vessel modernization programs tied to MSC recertification cycles.
Pharmaceutical procurement departments are imposing origin-verification requirements that displace spot-market biomass purchasing with long-term offtake agreements tied to specific harvesting coordinates and seasonal windows. Nutraceutical formulators in Germany and Japan are restructuring supplier qualification around blockchain-tracked chain-of-custody documentation. This pattern is most visible in omega-3 and astaxanthin supply contracts.
Marine Biotechnology Market Segmentation
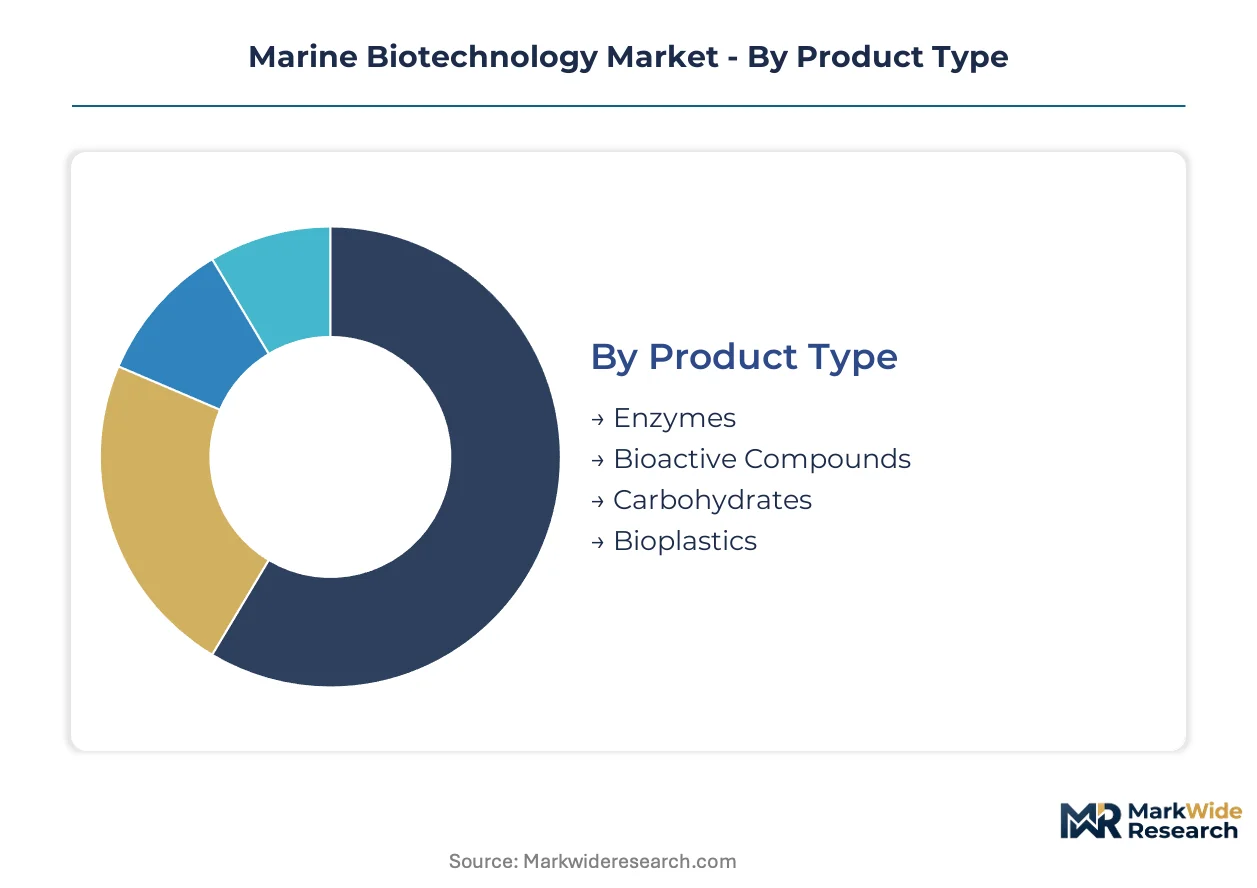
Segmentation in marine biotechnology exposes where capital allocation and regulatory compliance burdens diverge most sharply. Product-type boundaries increasingly blur as fermentation platforms pivot between enzymes, bioplastics, and bioactive compounds based on spot feedstock economics.
Product Type:
Upgrade cycles in cold-chain bioprocessing infrastructure are forcing product-type pivots every three to five years as sterile salinity controls improve.
- Enzymes:Extremophile-derived catalysts from psychrophilic and piezophilic bacteria tolerate pressure and temperature ranges that destroy terrestrial alternatives. Demand clusters in Norwegian Arctic bioprospecting corridors for industrial detergent and textile processing applications. The installed base of sterile fermentation vessels constrains supply elasticity.
- Bioplastics:Algal polysaccharide films from seaweed cultivation displace petroleum-derived barrier materials in EU food-service packaging mandates. Danish and French coastal processing facilities are scaling photobioreactor output to meet tightening single-use plastic restrictions. Cold-chain requirements are less severe than for pharmaceutical-grade extracts.
- Bioactive Compounds:Marine-derived alkaloids and polyphenols for neuropharmacology screening require sub-zero extraction protocols to preserve pharmacological activity.
- Carbohydrates:Sulfated polysaccharides from red algae supply cosmeceutical texturizers and nutraceutical prebiotics with documented biomass provenance.
Volume placements concentrate in Enzymes; the faster expansion belongs to Bioplastics.
Application:
Application mix tracks regulatory filing costs, with EMA centralized pathways and FDA complex natural product guidance creating divergent margin structures.
- Pharmaceuticals:Marine-derived IND candidates face extended pharmacokinetic validation timelines under FDA guidance for polysaccharide-based therapeutics. Deep-sea microorganism collections from Antarctic and Arctic zones feed centralized EMA marketing authorization pathways. Cold-chain bioprocessing redundancy at collection and fermentation sites inflates capital requirements.
- Functional Foods:Omega-3 and astaxanthin formulations command premium pricing from German and Japanese nutraceutical suppliers demanding blockchain-tracked chain-of-custody documentation. REACH biomass compliance and CSRD supply chain disclosure mandates restructure procurement toward long-term offtake agreements.
- Aquaculture:Algae fermentation infrastructure supplies omega-3 alternatives for fish feed as Antarctic krill harvesting faces MSC certification concentration.
- Cosmetics:Marine collagen and polysaccharide texturizers require documented sustainable harvesting coordinates under EU Green Deal procurement criteria.
Pharmaceuticals captures the dominant revenue share; Functional Foods is climbing the fastest.
End User:
End-user concentration reflects where cultivation expertise and capital access intersect most favorably.
- Biopharmaceutical Companies:Pipeline-stage marine-derived compounds require sterile fermentation at controlled salinity levels with redundant processing infrastructure. These firms dominate Antarctic bioprospecting corridor access through MSC-certified harvesting rights.
- Nutraceutical Suppliers:German and Japanese formulators impose origin-verification requirements that displace spot-market biomass purchasing with coordinate-specific seasonal offtake agreements.
- Research Institutions:Academic marine stations in Norway and California deploy metagenomic sequencing platforms to bypass cultivation bottlenecks for unculturable deep-sea microorganisms.
- Cosmetic Manufacturers:Procurement departments restructure supplier qualification around EU corporate sustainability reporting mandates for documented biomass provenance.
Biopharmaceutical Companies anchor the volume base; Nutraceutical Suppliers is gaining share fastest.
Technology:
Technology adoption curves compress as synthetic biology tools and photobioreactor automation converge.
- Fermentation:Sterile cold-chain bioprocessing at controlled salinity levels preserves pharmacological activity in bioactive compound extraction. Norwegian and Danish facilities lead in pre-validated ECHA registration pathways for novel marine substances.
- Genetic Engineering:CRISPR-assisted cultivation compresses strain optimization cycles for high-value carotenoid production in automated photobioreactors.
- Bioprocessing:EU F-Gas Regulation phase-down schedules force Antarctic and Arctic collection vessels toward ammonia and CO2 refrigeration retrofits.
- Aquaculture Techniques:Open-water seaweed farming and closed-system microbial mat cultivation supply feedstock for bioplastics and nutritional lipids respectively.
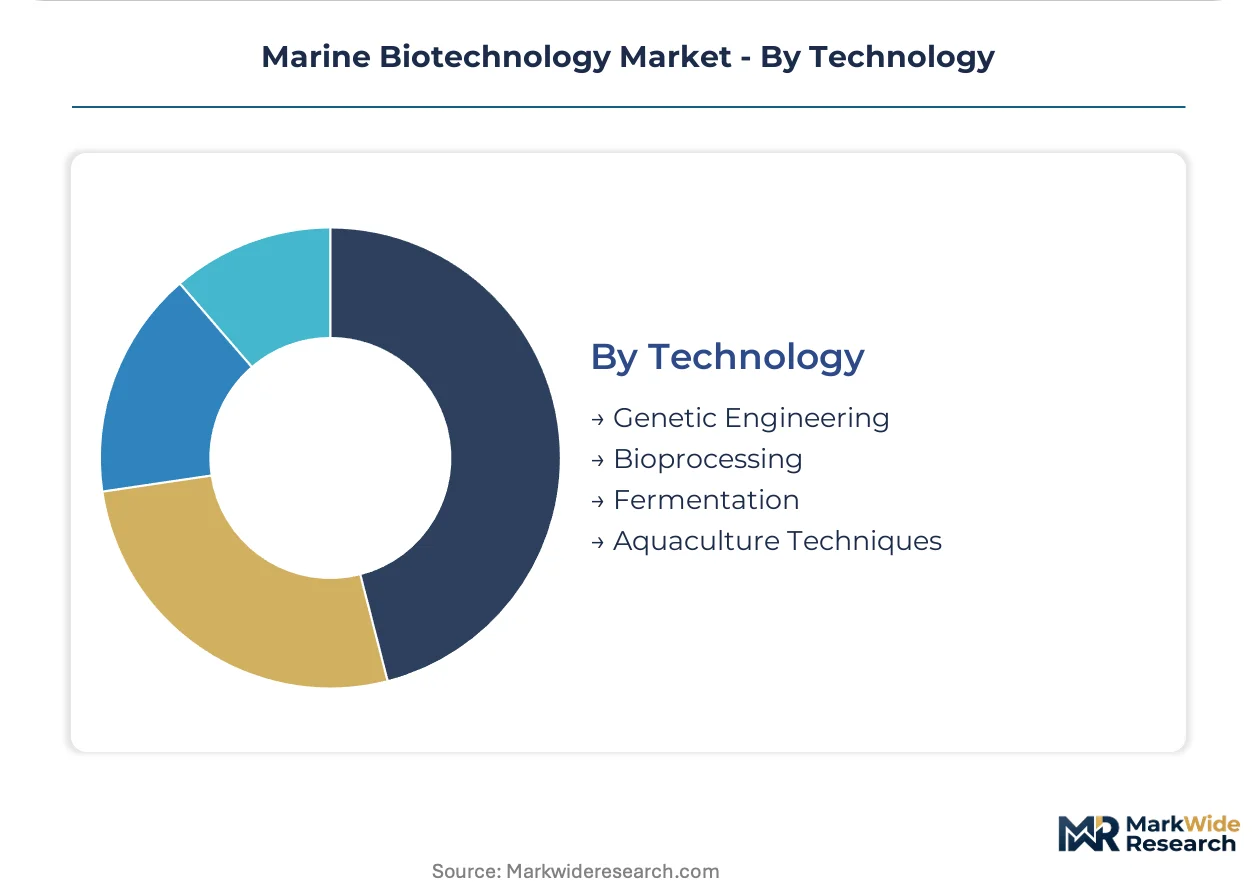
Fermentation retains the largest installed base; Genetic Engineering shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bergen anchors the European marine biotechnology corridor, with Norwegian Arctic bioprospecting operations feeding sterile cold-chain infrastructure that supplies pharmaceutical-grade extracts across Northern Europe.
Norway
Arctic krill harvesting and deep-sea microorganism collection drive capital allocation toward Bergen and Tromsø. The EU Marine Strategy Framework Directive tightens biomass quotas for MSC-certified operators. Marine Stewardship Council recertification cycles are forcing vessel modernization programs tied to ammonia refrigeration retrofits.
United States
FDA complex natural product guidance shapes clinical trial placement decisions for marine-derived IND candidates. California contract research organizations deploy metagenomic sequencing platforms to bypass cultivation bottlenecks. San Diego and Monterey Bay clusters concentrate talent for extremophile organism husbandry.
China
Algal polysaccharide production for bioplastics scales through coastal processing facilities in Shandong and Fujian provinces. National standards for marine-derived food additives tighten under SAMR oversight. Qingdao anchors seaweed cultivation research tied to single-use plastic replacement mandates.
Denmark
Photobioreactor automation for omega-3 alternatives attracts fermentation infrastructure investment. REACH biomass compliance creates first-mover advantages for facilities with pre-validated ECHA registration pathways. Copenhagen and Kalundborg clusters integrate algal cultivation with pharmaceutical-grade lipid extraction.
Japan
Metagenomic screening programs for neuropharmacology applications concentrate at academic marine stations in Okinawa and Kagoshima. PMDA evaluation pathways for marine-derived therapeutics require extended pharmacokinetic validation. Tokyo-based nutraceutical formulators impose blockchain-tracked chain-of-custody requirements on suppliers.
Marine Biotechnology Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification tiers, with Marine Stewardship Council status separating Antarctic krill extractors from open-ocean competitors. The vendor base stratifies into three archetypes: integrated bioprocessors controlling sterile fermentation infrastructure, specialized harvesters with exclusive biomass concessions, and platform technology licensors supplying strain optimization tools. Consolidation pressures concentrate extraction rights among MSC-certified operators while mid-scale fermentation specialists face capital barriers to deep-sea access. Dominant competitive moves include backward integration into captive algal cultivation and technology licensing agreements for CRISPR-assisted photobioreactor automation.
Within the integrated bioprocessor tier, DSM-Firmenich and BASF SE exemplify European fermentation infrastructure at pharmaceutical-grade purity standards. Aker BioMarine ASA anchors Norwegian Antarctic operations with MSC-certified harvesting rights. Corbion N.V. occupies a position in algae fermentation supply for aquafeed and human nutrition alternatives. These three entities represent contrasting geographic and technological positioning across the value chain.
| Leading Market Players |
|---|
| Corbion N.V. |
| Lonza Group Ltd |
| BASF SE |
| Qingdao Seawin Biotech |
| DSM-Firmenich |
| Aker BioMarine ASA |
| PharmaMar S.A. |
| DuPont de Nemours, Inc. |
| Cyanotech Corporation |
| Others |
Cost & Logistics Intelligence
Biopharmaceutical procurement departments concentrate demand for marine-derived compounds, imposing origin-verification requirements that restructure supplier relationships around long-term offtake agreements rather than spot-market transactions. This buyer concentration shifts pricing power toward MSC-certified harvesters with documented biomass provenance and sterile cold-chain infrastructure.
Pricing Analysis
Yield-based pricing anchors marine biotechnology contracts, with pharmaceutical-grade extracts commanding premiums tied to pharmacological potency preservation through controlled salinity processing. Three-tier pricing structure across MSC-certified premium, REACH-compliant standard, and uncertified economy levels separates Antarctic krill extractors from Arctic corridor operators and open-ocean competitors. Cost compression in omega-3 alternatives is intensifying because algae fermentation platforms displace wild-harvested feedstock. Nutraceutical suppliers in Germany and Japan exhibit least price sensitivity due to blockchain-tracked chain-of-custody mandates, while commodity aquafeed blenders face margin erosion from feedstock substitution.
Supply Chain Analysis
Direct-to-bioprocessor channels handle pharmaceutical-grade biomass demand, bypassing spot-market intermediaries that dominate commodity omega-3 trading. Supply concentrates in Norway, Denmark, and China, with Bergen and Tromsø anchoring Antarctic krill harvesting and Qingdao feeding algal polysaccharide production. Raw material dependencies include Antarctic krill biomass, Arctic deep-sea extremophile collections, and cultivated seaweed feedstock. Single-source vulnerability runs through MSC-certified Antarctic extraction rights consolidated among fewer than six operators. Distribution runs through sterile fermentation facilities with pre-validated ECHA registration pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Marine Strategy Framework Directive elevates compliance capital requirements, creating a durable barrier-to-entry moat for MSC-certified operators with existing sterile bioprocessing infrastructure.
For Market Incumbents: Anchor Antarctic harvesting rights through Marine Stewardship Council recertification cycles tied to ammonia refrigeration retrofits. Deepen backward integration into captive algal cultivation to offset krill biomass quota constraints. Threat substitution from CRISPR-assisted photobioreactor automation demands preemptive technology licensing agreements to preserve yield-based pricing power. For New Entrants and Emerging Players: Begin with Indian Ocean cyanobacteria bioprospecting in Seychelles and Madagascar waters, where alkaloid diversity for neuropharmacology remains underexplored. The most penetrable entry point sits in cosmeceutical texturizers, where EU Green Deal procurement criteria favor documented sustainable harvesting coordinates over pharmaceutical-grade purity standards. A go-to-market angle through Danish photobioreactor automation partnerships bypasses deep-sea access cost barriers. For Investors and Strategic Acquirers: The window for entry favors integrated bioprocessors with sterile fermentation infrastructure and REACH pre-validated extraction protocols. Long-term viability hinges on consolidation of extraction rights among MSC-certified operators as biomass quotas tighten. Watch EU F-Gas Regulation enforcement intensity as the inflection signal for capital reallocation toward natural refrigerant compliance.| Strategic Initiative | Industry Significance |
|---|---|
| MSC Recertification Investment | Antarctic krill operators secure institutional capital flows through certified biomass provenance. |
| Ammonia Refrigeration Retrofit | EU F-Gas Regulation phase-down schedules force cold-chain bioprocessing infrastructure modernization. |
| CRISPR-Assisted Cultivation Licensing | Gene-editing convergence compresses strain optimization cycles for high-value carotenoid production. |
| Backward Integration into Algal Cultivation | Fermentation platforms secure feedstock autonomy against Antarctic krill quota concentration. |
| Blockchain Chain-of-Custody Implementation | CSRD supply chain disclosure mandates create premium pricing corridors for verified biomass origin. |
Research Approach
Document review covered EMA centralized marketing authorization filings, FDA complex natural product guidance documents, and EU Marine Strategy Framework Directive implementation reports, complemented by interviews with sterile fermentation facility operators, Antarctic krill harvesting logistics coordinators, and pharmaceutical procurement managers. Secondary validation drew from Marine Stewardship Council certification databases, ECHA REACH registration records, and SEC filings of publicly traded bioprocessors. Bottom-up feedstock volume estimates triangulated against top-down pharmaceutical pipeline screening data.
Historical extraction volume trajectories cross-referenced against panel input from Norwegian and Danish facility operators informed the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application, end user, and technology platform, with regional regulatory cluster variations. CAGRs derived from compound growth assumptions tied to cold-chain infrastructure deployment rates and MSC certification expansion timelines. Industry-specific inputs incorporated EU F-Gas Regulation phase-down schedules and CSRD disclosure mandate compliance costs.
Underlying measurement precision varies by segment; pharmaceutical-grade bioactive compounds carry tighter precision than commodity bioplastics due to documented pharmacokinetic validation requirements. Forecasts reflect assumptions regarding Antarctic biomass quota stability and algae fermentation yield improvements. Periodic stress-testing of base assumptions is recommended against regulatory enforcement intensity and synthetic biology substitution rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Nannochloropsis Market
Bio-Agriculture
North America Biofertilizer Market
Bio-Agriculture
China Biocontrol Agents Market
Bio-Agriculture
United States Biofertilizer Market
Bio-Agriculture
Biofumigation Market
Bio-Agriculture
China Biostimulants Market
Bio-Agriculture
United Kingdom Biopesticides Market
Bio-Agriculture
Asia-Pacific Biostimulants Market
Bio-Agriculture
North America Biological Organic Fertilizer Market
Bio-Agriculture
Biochar Machine Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
Asia-Pacific Biofertilizers Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
Biofertilizers Market