
 Asia-Pacific Biostimulants Market | 2026-2036
Asia-Pacific Biostimulants Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Biostimulants Market Outlook
Australian seaweed extract producers is restructuring supply chains to serve drought-prone wheat belts across Queensland and New South Wales. Biostadt India Limited leverages its domestic fermentation infrastructure to dominate microbial product supply in South Asia. UPL Limited anchors its biostimulant portfolio through deep distributor relationships across Southeast Asian rice economies. Valagro competes on marine-sourced extraction technology leadership, particularly in Australian and Japanese specialty crop segments.
Asia-Pacific biostimulants comprise organic and biological formulations containing active compounds such as amino acids, humic acids, seaweed extracts, and beneficial microorganisms that enhance plant metabolic processes without direct nutrient provision. These inputs primarily function to improve stress tolerance, nutrient use efficiency, and crop quality parameters in intensive agricultural systems. Seaweed extracts command premium positioning in Australian and Japanese horticulture due to proven abiotic stress mitigation properties. Microbial products represent the fastest-expanding category as Indian and Chinese regulators broaden biofertilizer-biostimulant overlap approvals. Amino acid formulations sustain mature volume pools across Southeast Asian rice cultivation where cost sensitivity limits margin expansion.
India's FSSAI and CDSCO frameworks increasingly intersect with agri-input regulation as biostimulant-biopesticide boundary definitions tighten product classification requirements. Australia's APVMA and Japan's MAFF enforce distinct efficacy verification standards that fragment registration costs across the region. China's NMPA and MEE dual oversight of microbial strain safety and environmental release adds compliance layers for foreign entrants. Stakeholders must monitor evolving strain patentability rulings and organic equivalency agreements between national certification bodies to anticipate market access shifts.
Market Dynamics
India's PLI scheme for agrochemical manufacturing is compressing domestic production costs while simultaneously fragmenting import dependency across Southeast Asian supply chains.
Growth Catalysts
- Horticulture intensification:Specialty crop growers across Vietnam and Thailand deploy biostimulant cocktails to buffer yield volatility from monsoon disruption. Input distributors report accelerating offtake in Mekong Delta vegetable clusters.
- Japan's MAFF efficacy verification standards:Streamlined biofertilizer-biostimulant overlap approvals accelerate microbial product commercialization timelines. Domestic fermentation houses expand capacity to capture premium positioning.
- Seaweed extraction technology:Australian producers deploy cold-cell rupture methods to preserve bioactive compound integrity. Queensland processors supply drought-prone wheat belts with abiotic stress formulations.
Market Restraints
- Regulatory friction from China's NMPA-MEE dual oversight:Microbial strain safety assessments and environmental release permits layer compliance costs onto foreign entrants. Registration timelines extend 18-24 months.
- Input cost volatility in marine biomass:Tasman Sea harvest variability and fuel-linked extraction logistics compress margins for seaweed-derived product categories.
- Substitution threat from conventional NPK:Price-sensitive Southeast Asian rice growers revert to synthetic fertilizers when biostimulant premiums exceed 15%.
Strategic Opportunities
- Underpenetrated Philippines coconut sector:Cadang-cadang disease pressure and declining palm productivity create white space for trunk-injection biostimulant protocols. Local cooperatives seek yield recovery solutions.
- Technology convergence of CRISPR-edited strains and precision fermentation:Indian laboratories engineer hyper-efficient nitrogen-fixing consortia. Commercial scale-up partnerships with Gujarat agricultural universities accelerate.
- Direct-to-farm digital channels:Indonesian agritech platforms bypass layered distributor markups. Smartphone-based soil diagnostics bundle with customized microbial prescriptions.
Industry Challenges
- Strain patentability disputes:India's evolving biological material ownership frameworks create licensing uncertainty for microbial product developers. Court precedents remain unsettled.
- Certification timeline compression:Australia's APVMA organic equivalency agreements with multiple certification bodies require parallel documentation. Audit backlogs delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Biostimulants Market |
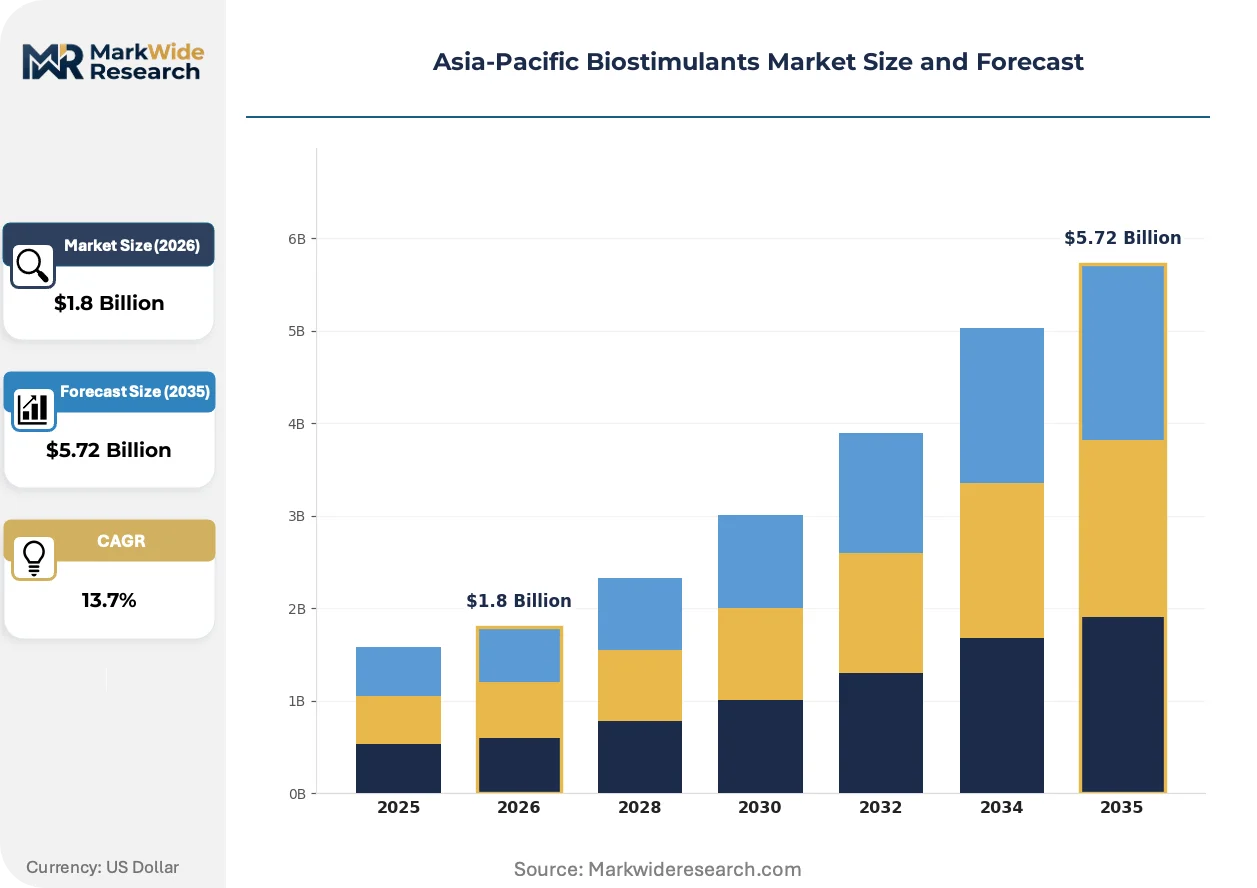
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Humic Acids, Seaweed Extracts, Microbial Products Application: Cereals, Fruits, Vegetables, Turf Formulation: Granular, Liquid, Powder, Gel Distribution Channel: Online Retail, Distributors, Warehouses, Agri-Stores |
| Companies Covered | Biostadt India Limited, T. Stanes and Company Limited, Biolchim SpA, Valagro, BASF SE, Syngenta, UPL Limited, Bayer AG, Gujarat State Fertilizers & Chemicals Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Biostimulants Market Strategic Shifts
Formulation science and regulatory data requirements are compressing product development cycles while elevating technical barriers to market entry across the region.
Nanostructured humic acid delivery systems is electrifying nutrient use efficiency benchmarks in intensive vegetable production. Japanese greenhouse operators adopt these formulations at accelerating rates to reduce synthetic fertilizer inputs by 30-40%. The technology is compressing competitive differentiation around particle size distribution and root-zone retention metrics.
Australia's APVMA is tightening efficacy substantiation requirements for biostimulant label claims. Field trial protocols now mandate multi-season, multi-site data packages that favor well-capitalized domestic producers. Specialty crop segments in Victoria and South Australia absorb compliance costs through premium pricing while broadacre wheat applications face registration delays.
Farmer buying collectives in India's Maharashtra-Gujarat belt are consolidating procurement volumes to negotiate direct manufacturer relationships. Traditional multi-tier distributor networks lose margin share as 500+ hectare horticulture operations demand technical service bundling. This concentration is most visible in grape and pomegranate export-oriented clusters where traceability requirements override price sensitivity.
Asia-Pacific Biostimulants Market Segmentation
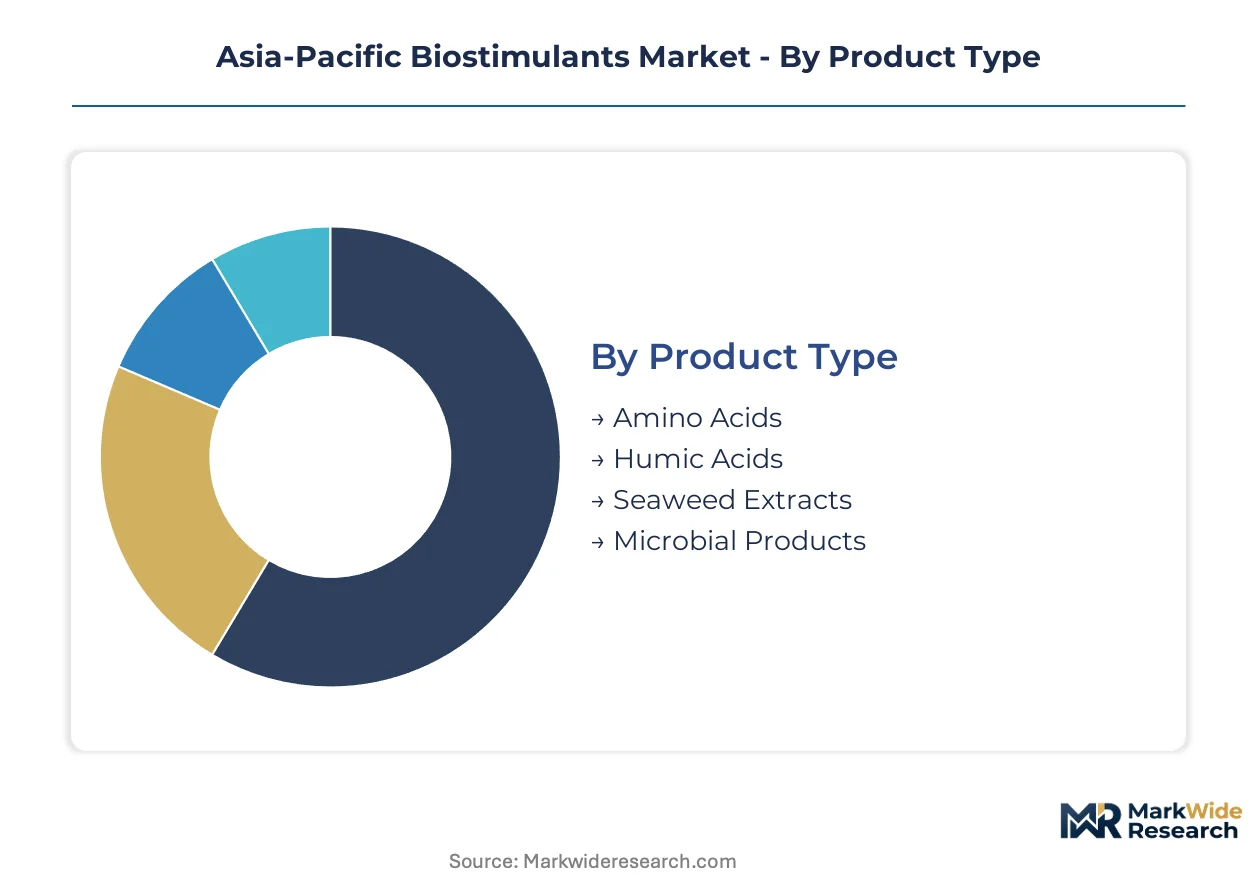
Segmentation in Asia-Pacific biostimulants reveals how regulatory pathways and crop-specific efficacy requirements fragment commercial strategies. Product registration costs, formulation stability under monsoon conditions, and channel access to smallholder cooperatives vary dramatically across these dimensions.
Product Type:
APVMA in Australia and MAFF in Japan impose distinct efficacy verification burdens on microbial strains versus seaweed extracts, while India's CDSCO-FSSAI intersection creates classification ambiguity for amino acid formulations.
- Seaweed Extracts:Cold-processed marine biomass concentrates containing cytokinins and betaines that enhance abiotic stress tolerance. Queensland processors supply drought-prone wheat belts across New South Wales where irrigation restrictions intensify. Tasman Sea harvest variability and fuel-linked extraction logistics compress margins.
- Microbial Products:Bacterial and fungal consortia engineered for nitrogen fixation or phosphate solubilization. Indian and Chinese regulators broaden biofertilizer-biostimulant overlap approvals, accelerating commercialization timelines for domestic fermentation houses. Patentability disputes around engineered strains create licensing uncertainty.
- Amino Acids:Protein hydrolysates and synthetic peptides that regulate plant metabolic pathways under stress conditions.
- Humic Acids:Humified organic matter complexes improving nutrient chelation and root-zone retention.
Leading the category by volume: Amino Acids. Growing fastest: Microbial Products.
Application:
Cost tiers diverge sharply between export-oriented horticulture with traceability premiums and price-sensitive domestic rice cultivation.
- Vegetables:Intensive greenhouse and open-field production in Vietnam's Mekong Delta and India's Gujarat-Maharashtra belt drives consistent offtake. Monsoon disruption volatility pushes growers toward biostimulant cocktails for yield resilience. Nanostructured humic delivery systems reduce synthetic fertilizer inputs by 30-40% in Japanese greenhouse operations.
- Fruits:Grape and pomegranate export clusters in Maharashtra demand technical service bundling and traceability documentation that overrides price sensitivity. Cadang-cadang disease pressure in Philippines coconut plantations creates white space for trunk-injection protocols.
- Cereals:Wheat cultivation across Australian drought-prone belts and Southeast Asian rice economies.
- Turf:Golf course and sports field maintenance applications in urban Australia and Japan.
Highest margin concentration: Fruits. Steepest expansion trajectory: Vegetables.
Formulation:
Application method determines supply chain configuration, with liquid formulations demanding cold-chain integrity and granular products suiting warehouse bulk distribution.
- Liquid:Concentrated suspensions and solutions enabling foliar spray and fertigation delivery. Cold-cell rupture methods preserve bioactive compound integrity in Australian seaweed processing. Shelf stability under tropical humidity challenges packaging specifications.
- Granular:Slow-release matrix formulations for soil incorporation in broadacre cereals. Compatible with existing fertilizer spreading equipment across Australian wheat belts and Indian rice economies.
- Powder:Dry concentrates requiring reconstitution prior to application.
- Gel:Viscous formulations for trunk-injection and precision placement in perennial crops.
Dominant by volume: Liquid. Gaining share fastest: Granular.
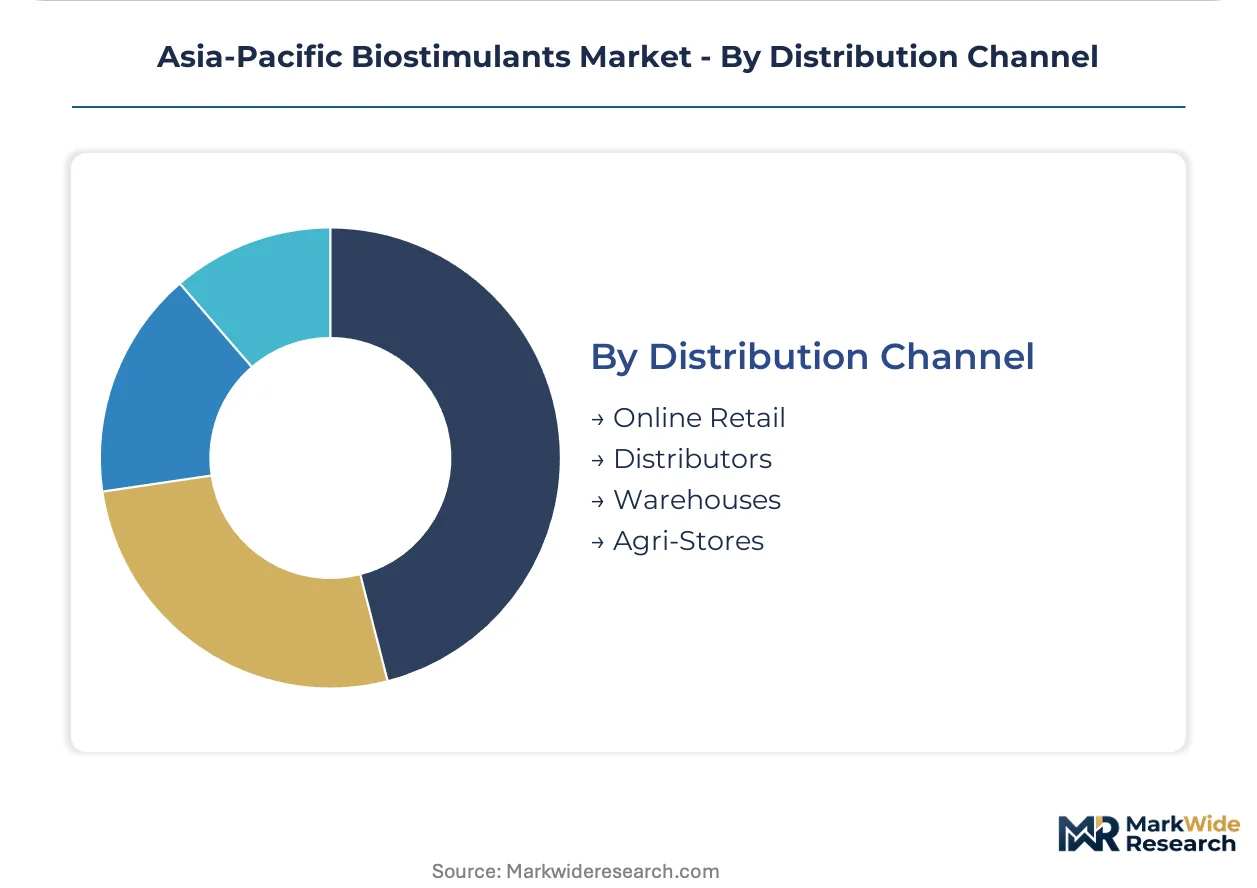
Distribution Channel:
Customer scale and technical support requirements are displacing traditional multi-tier networks in favor of direct relationships and digital intermediation.
- Distributors:Multi-tier networks with technical agronomists serving smallholder rice economies across Southeast Asia. UPL Limited anchors market presence through deep relationships in Vietnamese and Thai rice cultivation zones. Margin compression accelerates as farmer collectives consolidate procurement volumes.
- Agri-Stores:Rural retail points with credit extension and seasonal inventory financing. Gujarat and Maharashtra horticulture clusters drive premium product stocking for grape and pomegranate export operations.
- Online Retail:Smartphone-based platforms bundling soil diagnostics with customized microbial prescriptions in Indonesia.
- Warehouses:Bulk procurement hubs serving large-scale cooperatives and plantation operations.
Still commanding majority volume: Distributors. Expanding most quickly: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tasman Sea kelp beds and Queensland macroalgae harvests anchor raw material supply for Australian processors serving drought-prone wheat belts across New South Wales and Victoria.
India
Horticulture intensification in the Gujarat-Maharashtra belt drives microbial product demand for grape and pomegranate export clusters. The PLI scheme for agrochemical manufacturing compresses domestic production costs while fragmenting import dependency. Farmer buying collectives in Nashik and Sangli consolidate procurement volumes to negotiate direct manufacturer relationships.
Australia
Drought-prone wheat cultivation across Queensland and New South Wales absorbs abiotic stress formulations from cold-processed seaweed extracts. APVMA efficacy verification standards mandate multi-season field trial data that favors well-capitalized domestic producers. Specialty crop segments in Victoria absorb compliance costs through premium pricing.
Japan
Greenhouse vegetable operators adopt nanostructured humic acid delivery systems to reduce synthetic fertilizer inputs. MAFF streamlined biofertilizer-biostimulant overlap approvals accelerate microbial product commercialization timelines. Domestic fermentation houses in Kanto and Kansai regions expand capacity to capture premium positioning.
China
Precision fermentation laboratories engineer nitrogen-fixing consortia for intensive vegetable production systems. NMPA and MEE dual oversight of microbial strain safety and environmental release extends registration timelines to 18-24 months. Yangtze River Delta agricultural clusters face layered compliance costs for foreign biostimulant entrants.
Vietnam
Mekong Delta vegetable growers deploy biostimulant cocktails to buffer yield volatility from monsoon disruption. Input distributors report accelerating offtake in open-field and greenhouse clusters around Can Tho and An Giang. Rice cultivation cost sensitivity limits margin expansion for premium biostimulant categories.
Asia-Pacific Biostimulants Market Competitive Environment
Global majors compete with regional champions across formulation technology and distribution reach, producing a tiered structure where multinational agrochemical conglomerates anchor premium segments while domestic specialists capture cost-sensitive volume pools. The vendor base separates into three strategic archetypes: fermentation-integrated domestic producers, marine-extraction technology leaders, and distributor-anchored multinational platforms. Competitive moves concentrate on backward integration into raw material supply and direct-to-farm digital channel development.
Among India-based specialists, Biostadt India Limited and Gujarat State Fertilizers & Chemicals Ltd. occupy positions within the fermentation-integrated tier, leveraging domestic infrastructure to supply microbial consortia across South Asian rice and horticulture economies. Valagro represents the marine-sourced extraction archetype, while UPL Limited anchors distributor-dependent market presence across Southeast Asian cultivation zones.
| Leading Market Players |
|---|
| Biostadt India Limited |
| T. Stanes and Company Limited |
| Biolchim SpA |
| Valagro |
| BASF SE |
| Syngenta |
| UPL Limited |
| Bayer AG |
| Gujarat State Fertilizers & Chemicals Ltd. |
| Others |
Value Chain & Pricing Dynamics
Tasman Sea kelp harvest volatility cascades through Australian extraction facilities into three distinct pricing tiers for seaweed-derived biostimulants, with cold-processed premium formulations commanding substantial markups over commodity-grade alternatives while fuel-linked logistics compress margins across all categories.
Pricing Analysis
Technical service bundling separates premium-tier microbial consortia from unbundled economy-grade amino acid formulations across Indian horticulture procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence under APVMA and MAFF frameworks, with organic-equivalent products absorbing compliance premiums. Cost compression in standard-tier seaweed extracts is intensifying because Tasman Sea biomass availability fluctuates seasonally. Smallholder rice growers across Vietnam and Thailand exhibit highest price sensitivity, while Maharashtra grape export clusters override cost concerns with traceability requirements.
Supply Chain Analysis
Specialized fermentation technicians in Gujarat and Maharashtra command premium wages that concentrate microbial manufacturing capacity across India's western agricultural belt. Raw material supply draws from Queensland macroalgae harvests, Yangtze River Delta precision fermentation feedstocks, and Tasman Sea kelp beds. Single-source vulnerability pervades cold-processed seaweed extraction where Queensland processors dominate drought-prone wheat belt supply. Distribution runs through multi-tier agronomist networks in Southeast Asian rice economies and direct-to-farm digital platforms in Indonesian vegetable clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
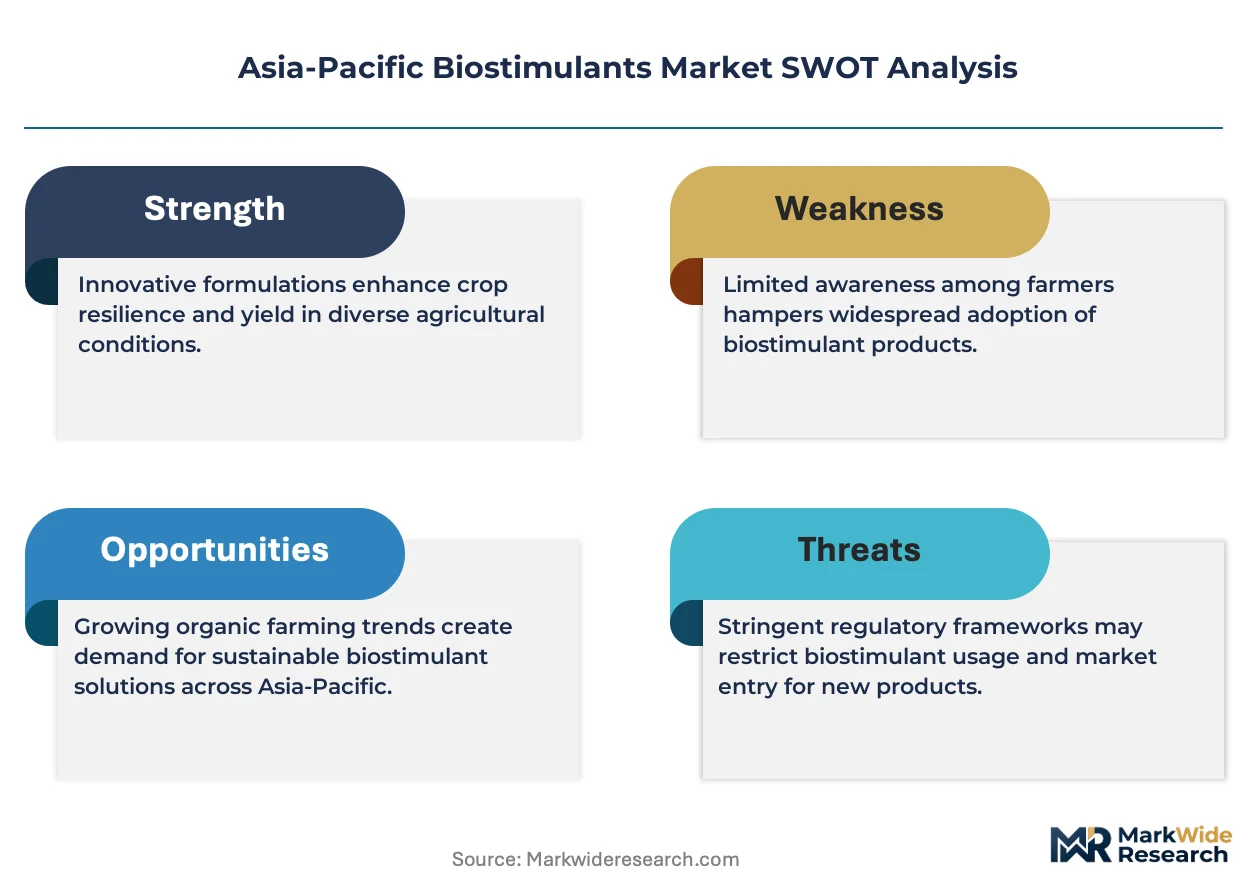
Asia-Pacific biostimulants represents a consolidation play where regulatory compliance burdens and multi-season efficacy data requirements are forcing sub-scale fermentation houses and extraction-dependent specialists toward exit or acquisition.
For Market Incumbents: Hedge against substitution threats from CRISPR-edited microbial strains by securing captive supply agreements with Gujarat agricultural universities for nitrogen-fixing consortia development. Anchor distributor relationships across Mekong Delta vegetable clusters through technical agronomist deployment that smaller competitors cannot replicate. Prioritize backward integration into Queensland kelp harvesting to insulate margin compression from marine biomass volatility.
For New Entrants and Emerging Players: Begin with trunk-injection biostimulant protocols for Philippines coconut plantations where cadang-cadang disease pressure has eliminated incumbent presence. Target Indonesian agritech platforms for smartphone-based soil diagnostic bundling that bypasses established distributor markups. Pursue direct-to-farm digital channels as the primary go-to-market angle, leveraging precision fermentation partnerships with domestic laboratories to compress product development timelines.
For Investors and Strategic Acquirers: The window for entry favors fermentation-integrated domestic producers with established CDSCO-FSSAI registration pathways and existing university research partnerships. Acquisition targets should demonstrate viable commercial scale-up for microbial consortia and defensive patent positions around engineered strains. Monitor APVMA efficacy verification standard tightening as the inflection indicator that will accelerate margin compression for non-compliant extraction-dependent players.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kelp Harvesting | Queensland processors secure drought-prone wheat belt supply against Tasman Sea variability. |
| Precision Fermentation Scale-Up | Gujarat laboratories accelerate nitrogen-fixing consortia commercialization timelines under PLI incentives. |
| Direct-to-Farm Digital Channel Development | Indonesian agritech platforms bypass distributor markups with smartphone-based microbial prescriptions. |
| Multi-Season Efficacy Data Investment | APVMA-compliant field trials favor well-capitalized domestic producers in Victoria specialty crops. |
| University Research Partnership Structuring | CDSCO-FSSAI intersection creates licensing certainty for engineered strain patentability. |
Study Parameters
Independent corroboration across fermentation facility operators, APVMA registration consultants, and Maharashtra horticulture cooperative procurement managers underwrites the qualitative findings. Primary interviews with microbial product development leads, seaweed extraction plant managers, and Vietnamese input distributors combined with secondary validation from CDSCO regulatory filings, MAFF biofertilizer approval databases, and Australian customs trade records. Bottom-up volume modeling across product type and application segments triangulates against top-down agricultural input expenditure analysis.
Rate-of-change decomposition isolates volume growth from price/mix effects across the projection horizon. Segmentation dimensions modeled include product category, crop application, formulation type, and regulatory approval pathway complexity. CAGRs derive from logistic diffusion curves fitted to adoption patterns in greenhouse vegetable operations and drought-prone cereal cultivation. Forecast inputs incorporate PLI scheme capacity addition timelines and evolving organic equivalency agreement coverage between certification bodies.
Underlying measurement precision varies by segment; microbial products with biofertilizer-biostimulant overlap approvals carry tighter precision than seaweed extracts subject to harvest variability. Forecasts reflect documented assumptions regarding regulatory timeline compression and strain patentability precedent establishment. Material deviation in APVMA efficacy substantiation requirements or NMPA-MEE dual oversight stringency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
Europe Feed Probiotics Market
Bio-Agriculture
Europe Biopesticides Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
Africa Biofertilizer Market
Bio-Agriculture
Brazil Biopesticides Market
Bio-Agriculture
Canada Biofertilizers Market
Bio-Agriculture
Biofumigation Market
Bio-Agriculture
North America Bio Succinic Acid Market
Bio-Agriculture
Brazil Biocontrol Agents Market
Bio-Agriculture
Middle East and Africa Biopesticides Market
Bio-Agriculture
Biosolids Market
Bio-Agriculture
Biological Control Market
Bio-Agriculture
Bio-Seeds Market
Bio-Agriculture
Biorational Pesticides Market