
 Biochar Machine Market | 2026-2036
Biochar Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Biochar Machine Market Insights
China's industrial park expansion around Zhengzhou and Xuzhou is reshaping global supply chains for mid-scale pyrolysis equipment. PYREG GmbH leverages German engineering standards to dominate European premium system sales. Beston Group anchors Southeast Asian project deployment through integrated fabrication and commissioning services. Kingtiger Shanghai Environmental Technology Co., Ltd. competes on price-performance ratios for municipal waste-to-biochar contracts.
A biochar machine thermochemically converts lignocellulosic biomass through controlled pyrolysis at 350–700°C in oxygen-limited conditions, yielding stable carbonaceous material for soil amendment, filtration media, or carbon credit generation. Pyrolysis systems occupy the dominant revenue share due to proven operational reliability across feedstock variabilities. Gasification configurations represent the fastest-growing installation category, driven by combined heat-and-power integration in Nordic district heating networks. Mobile installations command premium pricing from agricultural cooperatives seeking seasonal feedstock flexibility without permanent infrastructure commitments.
The EPA oversees biochar soil application under the Toxic Substances Control Act, while USDA conservation programs channel cost-share funding toward on-farm carbonization equipment. EU REACH compliance and the EU Green Deal's carbon farming initiative shape product certification pathways and cross-border equipment trade. Stakeholders must monitor evolving carbon credit eligibility criteria across voluntary registries and compliance markets to align machine specifications with future offtake agreements.
Market Dynamics
The EU Carbon Removal Certification Framework is tightening permanence verification standards, forcing equipment manufacturers to redesign pyrolysis control systems for auditable carbon sequestration. This regulatory compression is reshaping R&D priorities across the value chain.
Growth Catalysts
- EU Green Deal carbon farming incentives:Member states are deploying cost-share programs for on-farm pyrolysis equipment, channeling capital toward continuous-feed systems.
- Corn-belt agricultural cooperatives:North American grain producers are aggregating stover feedstocks for seasonal mobile carbonization, creating distributed demand clusters.
- Continuous pyrolysis automation:Advanced feedstock handling and temperature control systems are reducing labor intensity and improving biochar consistency for soil amendment markets.
Market Restraints
- Feedstock supply volatility:Agricultural residue availability fluctuates with harvest cycles and competing uses, compressing utilization rates for fixed installations.
- German engineering concentration:Premium system manufacturing clusters in Bavaria and Baden-Württemberg, creating supply bottleneck risks for European project pipelines.
- Verification cost burden:EU REACH compliance and third-party permanence certification add 15-25% to total project economics, slowing adoption among smallholder aggregators.
Strategic Opportunities
- Municipal waste-to-biochar contracts:Chinese cities are tendering integrated pyrolysis systems for diverted biomass streams, opening equipment export channels.
- Nordic district heating convergence:Gasification configurations paired with combined heat-and-power systems are penetrating Swedish and Finnish municipal energy networks.
- Mobile unit rental channels:Agricultural cooperatives are piloting seasonal equipment leasing models that eliminate permanent infrastructure commitments for variable feedstock access.
Industry Challenges
- Pyrolysis engineer scarcity:Qualified technicians for high-temperature reactor operation and maintenance are concentrated in Central European training programs, limiting deployment velocity.
- Permanence certification timelines:EU Carbon Removal Certification Framework validation cycles extend 18-24 months, delaying revenue recognition from carbon credit offtake agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biochar Machine Market |
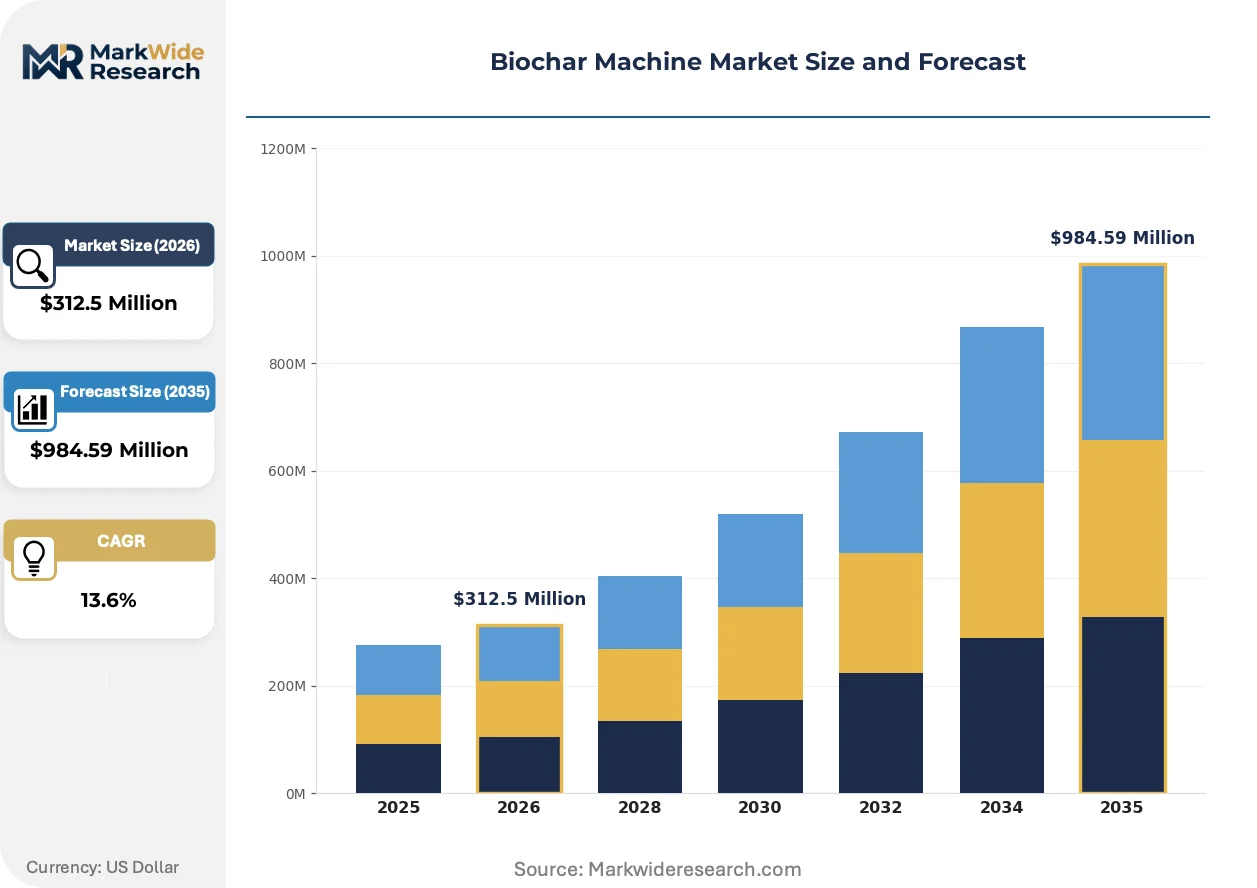
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $984.59 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pyrolysis, Gasification, Carbonization, Torrefaction Application: Agriculture, Soil Enhancement, Waste Management, Water Treatment End User: Farmers, Soil Scientists, Environmental Agencies, Waste Processors Installation: Onsite, Mobile, Permanent, Semi-Permanent |
| Companies Covered | PYREG GmbH, Beston Group, Klean Industries, FEECO International, Kingtiger Shanghai Environmental Technology Co., Ltd., GreenPower, AGICO Cement International Engineering Co., Ltd., Bioforcetech Corp., ARTi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biochar Machine Market Trends and Innovations
Equipment architecture is pivoting toward modular, containerized designs that slash commissioning timelines and enable feedstock-flexible deployment. This shift is compressing the traditional engineering-procurement-construction cycle.
Continuous-feed pyrolysis technology is migrating from batch-operated kiln systems toward automated screw-auger reactors with real-time temperature profiling. Agricultural cooperatives in the North American Great Plains are adopting these systems for corn stover processing. The technology is enabling higher throughput consistency while compressing labor requirements for seasonal operations.
REACH compliance pathways are tightening substance characterization requirements for biochar soil amendments, forcing equipment manufacturers to integrate inline quality monitoring. ECHA guidance documents now mandate full feedstock traceability. Nordic project developers are responding by specifying gasification configurations with integrated syngas analytics for dual-output certification.
Cooperative procurement collectives are aggregating demand across multiple farm operations to negotiate volume-based equipment pricing and shared technical service contracts. This channel is displacing direct manufacturer sales for mid-scale installations. The model is most visible in German agricultural soil amendment programs, where regional associations bundle pyrolysis system tenders.
Biochar Machine Market Segmentation
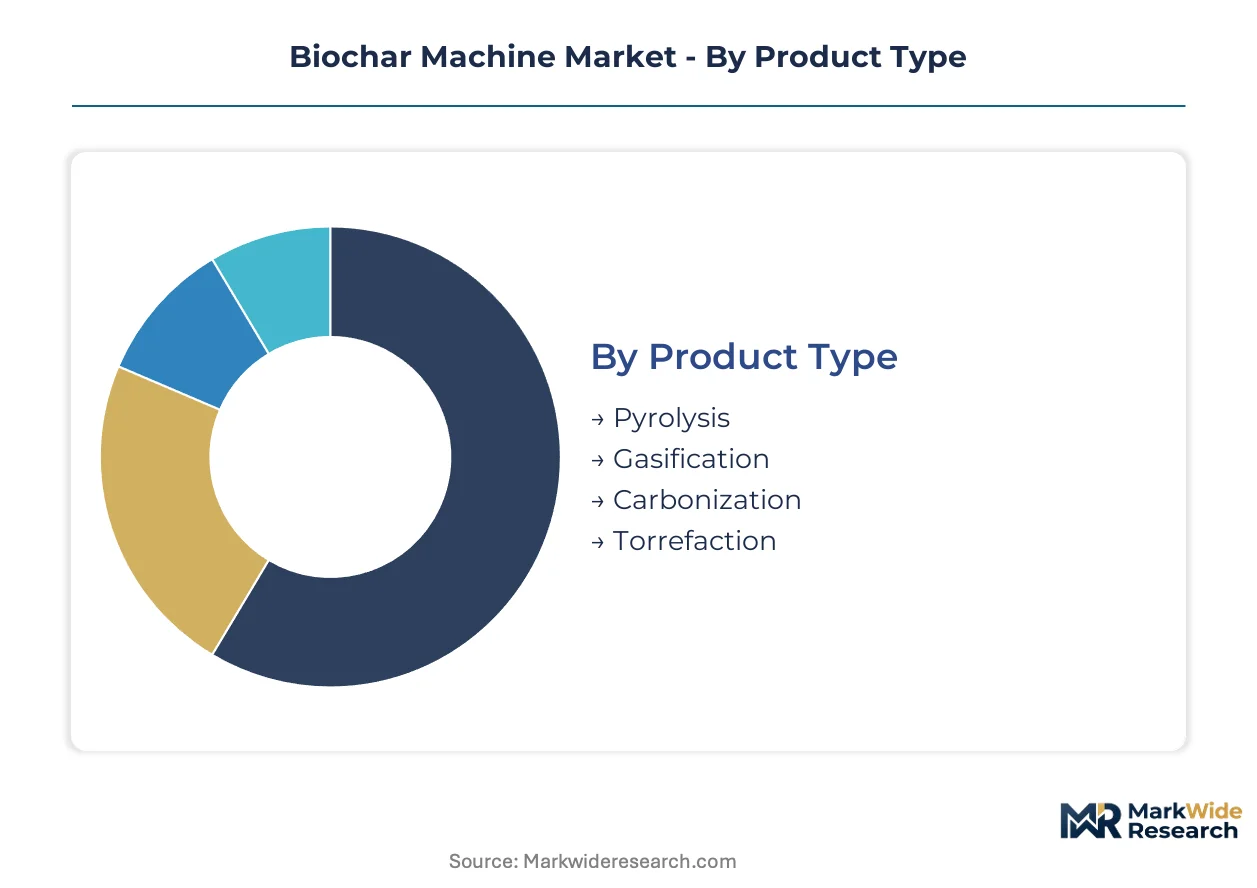
Equipment specification choices in the biochar machine market cascade through project economics, carbon credit eligibility, and operational flexibility. Segmentation reveals where capital concentrates and which configurations unlock new revenue streams.
Product Type:
Pyrolysis systems turn over on 7-10 year replacement cycles, while gasification units refresh faster due to syngas handling component wear. Carbonization and torrefaction equipment occupy intermediate positions based on feedstock abrasiveness.
- Pyrolysis:Continuous-feed screw-auger reactors dominate commercial installations for agricultural residue processing. German agricultural soil amendment programs drive procurement of automated systems with real-time temperature profiling for EU Carbon Removal Certification Framework compliance.
- Gasification:Dual-output configurations generate biochar alongside syngas for combined heat-and-power integration. Swedish and Finnish district heating networks anchor demand for these systems, with Nordic municipalities specifying integrated analytics for dual certification pathways.
- Carbonization:Batch-operated kiln systems serve smallholder aggregators with lower capital requirements and simpler maintenance protocols.
- Torrefaction:Mild thermal treatment systems produce hydrophobic solid fuels for co-firing applications, penetrating biomass power plant supply chains.
Pyrolysis anchors the volume base while gasification gains share at the steepest rate.
Application:
Cost tiers separate premium soil amendment systems from standard waste management configurations, with water treatment commanding specialized filtration-grade pricing.
- Agriculture:On-farm carbonization equipment processes corn stover and other crop residues for direct soil incorporation. North American Great Plains cooperatives aggregate demand through seasonal mobile unit deployment, bypassing permanent infrastructure investments.
- Soil Enhancement:High-consistent biochar for carbon credit markets requires inline quality monitoring and full feedstock traceability per ECHA guidance. Premium pricing reflects permanence verification readiness.
- Waste Management:Municipal tender specifications in Chinese cities prioritize integrated pyrolysis systems for diverted biomass streams, with volume-based equipment procurement compressing unit costs.
- Water Treatment:Activated biochar filtration media command specification-grade consistency, limiting viable equipment to continuous-feed systems with tight process control.
Agriculture absorbs the largest capital deployment while soil enhancement commands the highest margin premiums.
End User:
Customer type determines procurement modality, from individual farmer cost-share applications to institutional tender processes with extended validation timelines.
- Farmers:Individual and cooperative operators access USDA conservation program funding for on-farm carbonization equipment. Mobile unit rental channels eliminate permanent infrastructure commitments for variable feedstock access.
- Soil Scientists:Research institutions and carbon credit developers specify laboratory-grade systems for permanence verification studies, with EU Carbon Removal Certification Framework validation cycles extending 18-24 months.
- Environmental Agencies:Regulatory bodies procure demonstration systems for compliance pathway development, channeling specifications toward auditable carbon sequestration controls.
- Waste Processors:Municipal and industrial operators integrate pyrolysis into existing material recovery facilities, with throughput requirements favoring continuous-feed automation.
Farmers represent the broadest installed base while waste processors expand most quickly through municipal tender pipelines.
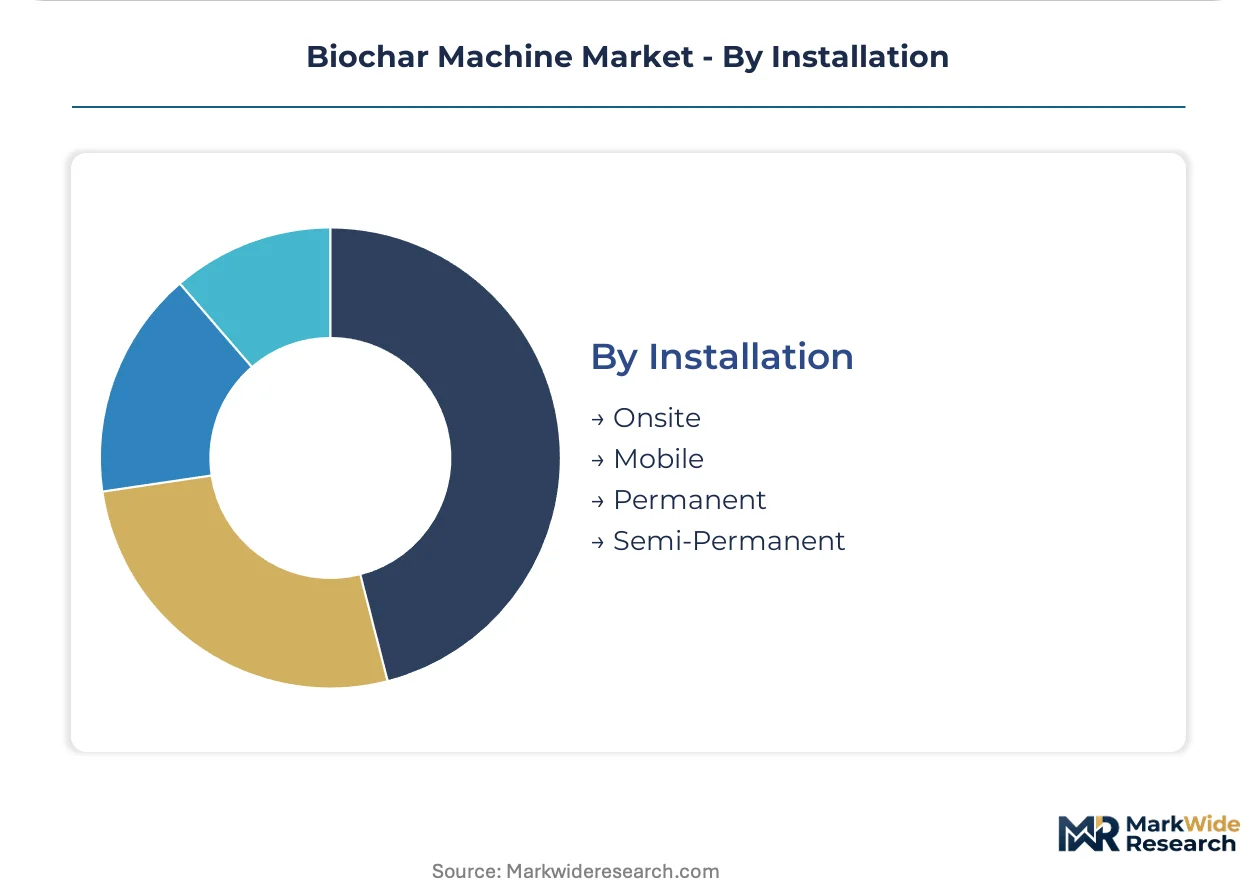
Installation:
Geographic mobility separates seasonal agricultural applications from permanent industrial configurations, with semi-permanent systems bridging project development phases.
- Onsite:Fixed installations at farms or waste facilities maximize utilization through dedicated feedstock supply agreements. EPA oversight under the Toxic Substances Control Act shapes soil application compliance protocols for US deployments.
- Mobile:Containerized and trailer-mounted units enable seasonal corn-belt stover processing without permanent infrastructure. Premium pricing reflects agricultural cooperative demand for feedstock flexibility across harvest cycles.
- Permanent:Industrial-scale installations with decades-long asset lifespans anchor municipal waste-to-biochar contracts and district heating convergence projects.
- Semi-Permanent:Modular skidded systems support project development phases, with containerized designs slashing commissioning timelines for feedstock-flexible deployment.
Permanent installations anchor the revenue base while mobile configurations climb the fastest on cooperative leasing model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. European buyers prioritize permanence verification readiness for carbon credit markets. North American demand clusters around seasonal agricultural flexibility. Asian procurement emphasizes integrated waste-to-energy configurations.
Germany
Bavarian engineering clusters manufacture continuous-feed pyrolysis systems for EU Carbon Removal Certification Framework compliance. The EU Green Deal channels cost-share funding toward on-farm carbonization equipment. Regional agricultural associations in Baden-Württemberg bundle tender specifications for automated temperature profiling systems.
United States
Corn-belt cooperatives aggregate corn stover for mobile carbonization units across Iowa and Illinois. EPA oversight under the Toxic Substances Control Act shapes soil application protocols. USDA conservation programs fund on-farm equipment deployment throughout the Great Plains.
China
Municipal tender pipelines in Zhengzhou and Xuzhou specify integrated pyrolysis systems for diverted biomass streams. National dual carbon goals accelerate waste-to-biochar project approvals. Industrial park expansion around Shanghai anchors mid-scale equipment fabrication clusters.
Sweden
Nordic district heating networks specify gasification configurations with combined heat-and-power integration. ECHA guidance mandates full feedstock traceability for biochar soil amendments. Municipal energy operators in Stockholm and Gothenburg pilot dual-output certification pathways.
India
Agricultural residue availability drives seasonal demand for batch-operated kiln systems across Punjab and Haryana. The central bank's priority sector lending guidelines influence rural equipment financing. State-level biomass power policies in Maharashtra and Karnataka create project development pipelines.
Biochar Machine Market Competitive Landscape
Capability concentration sits with German engineering specialists; scale advantage sits with Chinese integrated fabricators. The vendor base stratifies across three tiers: premium European system houses, mid-scale Asian project integrators, and regional batch-equipment suppliers. Dominant competitive moves include cooperative procurement collective formation and modular containerized system architecture development.
Among German GmbH-structured specialists, PYREG GmbH exemplifies premium-tier engineering concentration. Chinese fabricators including Kingtiger Shanghai Environmental Technology Co., Ltd. and Zhengzhou Shuli Machinery Co., Ltd. occupy positions within the integrated project deployment segment. These named entities represent archetypal positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| PYREG GmbH |
| Beston Group |
| Klean Industries |
| FEECO International |
| Kingtiger Shanghai Environmental Technology Co., Ltd. |
| GreenPower |
| AGICO Cement International Engineering Co., Ltd. |
| Bioforcetech Corp. |
| ARTi |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese mid-scale fabrication clusters around Zhengzhou and Xuzhou is compressing utilization rates below sustainable thresholds, forcing equipment suppliers into aggressive pricing postures while simultaneously driving consolidation toward integrated project deployment models that bundle fabrication with commissioning services.
Pricing Analysis
Long-term offtake contracts for carbon credit-linked biochar dominate pricing structures, with project-based procurement for municipal waste-to-biochar tenders in Chinese cities running at volume-discounted rates. Premium-mid-economy pricing differentiation separates EU Carbon Removal Certification Framework-compliant systems with inline quality monitoring from standard batch-operated units. Cost compression in the mid-scale segment is intensifying because Chinese fabricators compete on price-performance ratios for municipal contracts. Agricultural cooperatives in the North American Great Plains exhibit highest price sensitivity due to seasonal utilization uncertainty, while Nordic district heating operators demonstrate lowest sensitivity given dual-output revenue streams from combined heat-and-power integration.
Supply Chain Analysis
Export-control regimes limiting flows of high-temperature reactor control systems and precision temperature profiling equipment constrain technology transfer from German engineering clusters to emerging fabricators. Geographic supply concentrates in Germany for premium continuous-feed pyrolysis systems, China for integrated mid-scale fabrication, and India for batch-operated kiln components. Raw material dependencies draw from specialty steel alloys for reactor vessels, precision sensors for real-time temperature control, and automated screw-auger mechanisms. Single-source vulnerability sits with Bavarian engineering houses for EU compliance-ready control systems. Distribution runs through cooperative procurement collectives in German agricultural associations, direct municipal tender channels in Chinese cities, and equipment rental networks for North American mobile unit deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against direct air capture and mineralization technologies that compete for carbon credit offtake agreements and corporate net-zero procurement budgets.
For Market Incumbents: Insulate installed base relationships by embedding permanence verification services into equipment contracts, creating switching costs for agricultural cooperatives and municipal operators. Deepen backward integration into reactor control system manufacturing to reduce dependency on Bavarian engineering clusters. Counter emerging Chinese price competition by bundling EU REACH compliance consulting and carbon credit registration support with hardware sales. For New Entrants and Emerging Players: Pursue mobile unit rental channels serving North American corn-belt cooperatives, where seasonal feedstock flexibility creates demand for non-permanent infrastructure solutions. Target Indian agricultural residue processing with simplified batch-operated systems compatible with state-level biomass power policy frameworks. Lead with integrated financing partnerships that align equipment payments with carbon credit revenue recognition timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across containerized modular system architectures, compressing project development risk profiles and expanding addressable project sizes. Five-to-ten year viability favors manufacturers with demonstrated EU Carbon Removal Certification Framework compliance pathways and established cooperative procurement relationships. Acquisition target archetype: mid-scale Asian fabricators with municipal tender track records and nascent European certification capabilities. Signal to watch: permanence certification timeline compression from ECHA guidance refinement.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Containerized System Development | Containerized designs slash commissioning timelines for Zhengzhou and Xuzhou industrial park deployment. |
| EU Carbon Removal Certification Compliance Investment | Inline quality monitoring integration satisfies ECHA guidance for full feedstock traceability mandates. |
| Cooperative Procurement Collective Formation | German agricultural associations bundle tenders to negotiate volume pricing and shared technical service contracts. |
| Mobile Unit Rental Channel Establishment | Seasonal leasing models eliminate permanent infrastructure commitments for Iowa and Illinois corn-belt cooperatives. |
| Backward Integration into Control System Manufacturing | In-house production of temperature profiling components reduces Bavarian engineering cluster dependency risks. |
Research Methodology
Initial hypotheses were tested against primary input from pyrolysis plant engineers, agricultural cooperative procurement managers, municipal waste facility operators, and carbon credit developers, then refined through secondary validation against EU ECHA guidance documents, USDA conservation program funding disclosures, Chinese municipal tender specifications, and Nordic district heating network procurement records. Bottom-up equipment deployment counts triangulated with top-down carbon credit market sizing across the analysis window.
Demand-supply-balance framing anchored the forecast framework, modeling segmentation dimensions including pyrolysis versus gasification configuration, agriculture versus soil enhancement versus waste management application, farmer versus waste processor end user, and mobile versus permanent installation type. CAGRs derived from feedstock availability projections, carbon credit price trajectory assumptions, and regulatory compliance timeline evolution. Industry-specific inputs incorporated EU Carbon Removal Certification Framework implementation pace and USDA cost-share funding allocation patterns.
Macroeconomic conditions sit as an overlay; deviation in carbon credit market liquidity, agricultural commodity price volatility, or EU Green Deal funding continuity would shift the trajectory. Forecasts reflect documented assumptions regarding permanence verification standardization and cooperative procurement model adoption. Cross-checking against IEA bioenergy deployment databases and voluntary carbon market registry issuance data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Microphytes Market
Bio-Agriculture
South America Biological Organic Fertilizers Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
North America Feed Probiotics Market
Bio-Agriculture
Bacterial Biopesticides Market
Bio-Agriculture
North America Biocontrol Agents Market
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
Canada Biofertilizers Market
Bio-Agriculture
Bio-Seeds Market
Bio-Agriculture
Agriculture Biologicals Testing Market
Bio-Agriculture
Artificial Insemination Market
Bio-Agriculture
China Biofuels Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
Bovine High-Mountain Disease Market
Bio-Agriculture
China Biostimulants Market
Bio-Agriculture
Biostimulants Market