
 China Biostimulants Market | 2026-2036
China Biostimulants Market Size, Share, and Industry Trends Forecast 2026-2036
China Biostimulants Market Insights
GB 20287 microbial fertilizer standards certification is rotating market access toward domestic producers with proven strain libraries and fermentation capacity. Syngenta Group leverages its global germplasm partnerships to bundle biostimulants with crop protection packages across Sichuan and Hubei provinces. Qingdao Seawin Biotech Group Co., Ltd. anchors the seaweed extract segment through integrated kelp farming and extraction operations along the Shandong coast. Novonesis competes on microbial inoculant R&D intensity, sustaining multiple strain development pipelines for drought-stress applications.
Biostimulants comprise substances and microorganisms applied to plants or soil to stimulate natural processes that enhance nutrient uptake efficiency, tolerance to abiotic stress, and crop quality attributes without direct nutritive function; formulations typically contain active concentrations of humic acids at 8-15 percent, live microbial counts exceeding 10^8 CFU per gram, or oligosaccharide fractions from enzymatically hydrolyzed seaweed cell walls. Humic acids dominate product type value pools due to established supply chains from lignite and peat deposits in Inner Mongolia, while microbial inoculants represent the fastest-growing category as Chinese agronomists validate Bacillus and Trichoderma strains for saline-alkaline soil remediation. Agricultural crops absorb the majority of application volumes, though horticultural crops in protected cultivation generate premium pricing for liquid delivery modes tailored to fertigation systems.
China's Ministry of Agriculture and Rural Affairs enforces fertilizer registration under the Agricultural Inputs Regulation, requiring field efficacy trials that extend commercialization timelines for novel microbial strains. The National Health Commission through GB standards and provincial agricultural bureaus coordinate residue monitoring, shaping product safety thresholds that determine export eligibility for biostimulant-adjacent organic produce. Stakeholders must monitor evolving strain patent filings and provincial subsidy lists that signal which biological input categories will receive procurement preference in the next planning cycle.
Market Dynamics
China's biostimulant sector is reorienting around GB 20287 microbial fertilizer standards certification, which is filtering market access toward domestic producers with validated strain libraries and industrial fermentation capacity while marginalizing smaller formulators lacking compliance infrastructure.
Growth Catalysts
- Shandong greenhouse vegetable expansion:Specialty crop growers in this province are scaling biostimulant applications to build abiotic stress tolerance in protected cultivation environments, creating concentrated demand clusters for liquid humic acid and seaweed extract formulations.
- North China Plain nitrogen reduction trials:Large-scale wheat and corn operations across this grain belt are piloting humic acid-seaweed extract combinations to cut synthetic nitrogen application rates without yield penalty, validating biostimulant efficacy at commercial scale.
- Revised organic fertilizer standards:China's Ministry of Agriculture and Rural Affairs tightened registration protocols under updated organic fertilizer frameworks, redirecting domestic formulators toward compliant microbial inoculant production lines.
Market Restraints
- Inner Mongolia supply concentration:Humic acid feedstock dependence on lignite and peat deposits in this region creates geographic supply vulnerability and price volatility exposure for formulators lacking diversified sourcing.
- Field efficacy trial timelines:Agricultural Inputs Regulation mandates extended commercialization cycles for novel microbial strains, compressing innovation returns and favoring incumbents with established registration portfolios.
- Synthetic nitrogen pricing:Persistently low urea and ammonium phosphate costs in China's fertilizer market maintain substitution pressure on biostimulant adoption in price-sensitive commodity crop segments.
Strategic Opportunities
- Saline-alkaline soil remediation:Bacillus and Trichoderma strain validation for degraded soil restoration opens application white space across northern provinces with expanding saline intrusion, particularly in Hebei and Tianjin agricultural zones.
- Sichuan-Hubei crop protection bundling:Integrated biostimulant-pesticide distribution partnerships with germplasm providers create channel access advantages in high-value citrus and rice production corridors.
- Provincial subsidy list positioning:Agricultural bureaus in Shandong and Henan are signaling procurement preference for microbial inoculant categories through updated biological input subsidy frameworks, rewarding early compliance investments.
Industry Challenges
- Strain development talent scarcity:Industrial microbiology and fermentation engineering expertise concentrates in coastal biotech clusters, creating recruitment friction for inland formulators scaling production capacity.
- Residue monitoring alignment:National Health Commission GB standards coordination with provincial agricultural bureaus demands continuous product safety threshold recalibration to maintain organic produce export eligibility.
- Legacy synthetic fertilizer integration:Agronomist training and farmer practice patterns optimized for chemical input protocols create adoption friction for biological alternatives requiring modified application timing and equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Biostimulants Market |
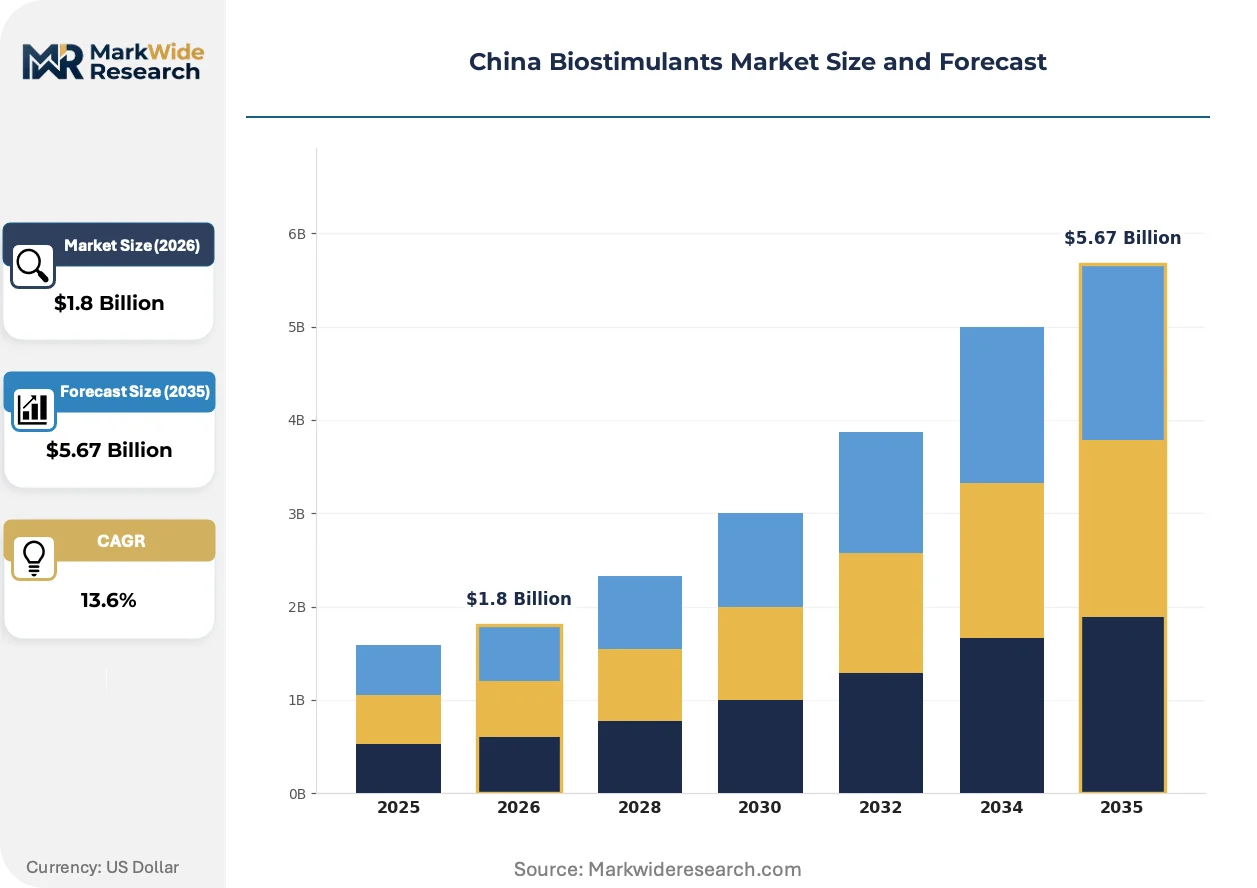
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.67 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Humic Acids, Seaweed Extracts, Microbial Inoculants, Protein Hydrolysates Application: Agricultural Crops, Horticultural Crops, Turf & Ornamentals, Others End User: Farmers, Distributors, Research Institutions, Agronomists Delivery Mode: Liquid, Granular, Powder, Suspensions |
| Companies Covered | Corteva Agriscience, Plant Response Biotech Inc, Syngenta Group, Trade Corporation International, Binzhou Jingyang Biological Fertilizer Co Ltd, Qingdao Seawin Biotech Group Co., Ltd., Haifa Group, Biolchim SpA, Novonesis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Biostimulants Market Trends and Innovations
Enzymatic hydrolysis protocols for seaweed cell wall extraction are reshaping active ingredient concentration capabilities, while provincial regulators accelerate strain patent filing surveillance to identify procurement priority categories.
Microbial consortia formulation technology is fragmenting the historical dominance of single-strain inoculants. Greenhouse operators in Shandong are adopting multi-species Bacillus-Trichoderma combinations at accelerating rates. This technology is fragmenting procurement patterns away from standalone products toward integrated soil health systems that bundle inoculation with organic substrate amendments.
GB standards enforcement through China's Ministry of Agriculture and Rural Affairs is tightening field efficacy documentation requirements for novel microbial strains. The regulation extends commercialization timelines by 18-24 months for unregistered biological entities. Domestic producers with existing compliant strain libraries are capturing shelf space from import-dependent competitors facing registration backlogs.
Buyer concentration among large-scale cooperatives in the North China Plain is compressing supplier negotiation cycles. These aggregators are displacing traditional village-level input retailers through direct procurement contracts with certified formulators. The shift concentrates volume allocation decisions within provincial agricultural technology extension stations that manage cooperative input sourcing.
China Biostimulants Market Segmentation
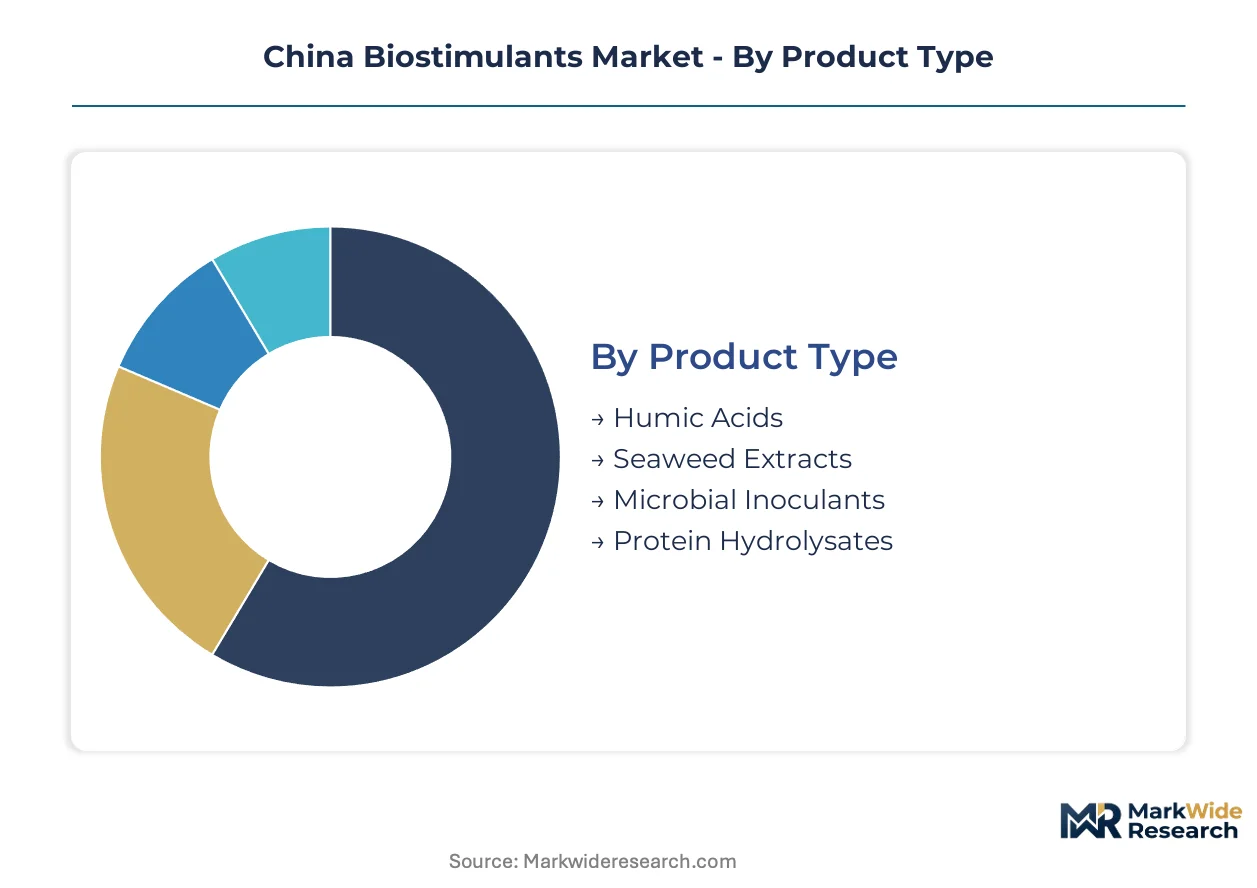
Segmentation in China's biostimulant market reflects divergent compliance pathways under GB standards and distinct agronomic requirements across cropping systems. Product registration categories and delivery mode specifications determine channel access and pricing power for formulators navigating provincial subsidy frameworks.
Product Type:
GB 20287 certification tiers separate microbial inoculants from extract-based categories, creating divergent registration timelines and capital requirements for domestic versus import-dependent producers.
- Humic Acids:Formulations contain 8-15 percent active humic and fulvic acid fractions derived from Inner Mongolia lignite and peat deposits. North China Plain wheat and corn operations consume bulk volumes for nitrogen use efficiency programs, though feedstock geographic concentration exposes supply chains to price volatility and transport cost spikes.
- Microbial Inoculants:Live microbial counts exceeding 10^8 CFU per gram define quality thresholds for Bacillus and Trichoderma strains. Shandong greenhouse vegetable growers are scaling multi-species consortia applications for abiotic stress tolerance, with provincial agricultural bureaus signaling procurement preference through updated biological input subsidy lists.
- Seaweed Extracts:Oligosaccharide fractions from enzymatically hydrolyzed kelp cell walls command premium positioning in protected cultivation fertigation systems.
- Protein Hydrolysates:Amino acid-based biostimulants from plant and animal protein sources serve specialty crop segments with organic certification requirements.
Humic acids handle the majority of throughput; microbial inoculants are climbing the fastest on share.
Application:
Application patterns track the divergence between commodity grain economies of scale and horticultural premium capture in protected cultivation.
- Agricultural Crops:Wheat, corn, and rice operations across the North China Plain absorb volume through cooperative procurement contracts managed by provincial agricultural technology extension stations. Large-scale trials validating humic acid-seaweed extract combinations for synthetic nitrogen reduction are consolidating demand among certified formulators with compliant strain libraries.
- Horticultural Crops:Greenhouse tomatoes, cucumbers, and peppers in Shandong Province generate premium pricing for liquid delivery modes tailored to fertigation infrastructure. Specialty crop growers prioritize abiotic stress tolerance formulations over yield maximization, shifting procurement toward microbial consortia and seaweed extract combinations.
- Turf & Ornamentals:Golf course and landscaping applications concentrate in coastal municipalities with stricter runoff regulations.
- Others:Forestry and nursery applications represent emerging demand pockets with limited formulation standardization.
Agricultural crops anchor volume allocation; horticultural crops command the steepest expansion trajectory.
End User:
Customer concentration is displacing traditional village-level retail channels through direct procurement relationships with large-scale cooperatives.
- Farmers:Individual operators in Hebei and Henan provinces access biostimulants through cooperative aggregation structures that consolidate volume decisions within provincial extension networks. Training gaps in biological input application timing create adoption friction relative to synthetic fertilizer protocols.
- Distributors:Certified formulators with GB 20287 compliance infrastructure are capturing shelf space from import-dependent competitors facing registration backlogs. Channel partners in Sichuan and Hubei provinces bundle biostimulants with crop protection packages through germplasm provider partnerships.
- Research Institutions:Agricultural universities and provincial academies of sciences conduct field efficacy trials required under Agricultural Inputs Regulation.
- Agronomists:Extension specialists influence cooperative procurement decisions through validation of strain performance in saline-alkaline soil remediation.
Farmers represent the dominant demand source; distributors are gaining share fastest as cooperative procurement consolidates.
Delivery Mode:
Equipment compatibility and labor cost structures determine mode selection across cropping systems with varying mechanization levels.
- Liquid:Fertigation-compatible formulations dominate protected cultivation in Shandong and premium horticultural segments. Enzymatic hydrolysis protocols for seaweed extraction are improving active ingredient solubility and concentration stability in aqueous systems.
- Granular:Mechanical spreader compatibility drives adoption in North China Plain grain operations with high mechanization coverage.
- Powder:Lower transport costs favor bulk commodity crop applications with price-sensitive procurement committees.
- Suspensions:Concentrated microbial formulations with extended shelf stability serve remote distribution networks with limited cold chain infrastructure.
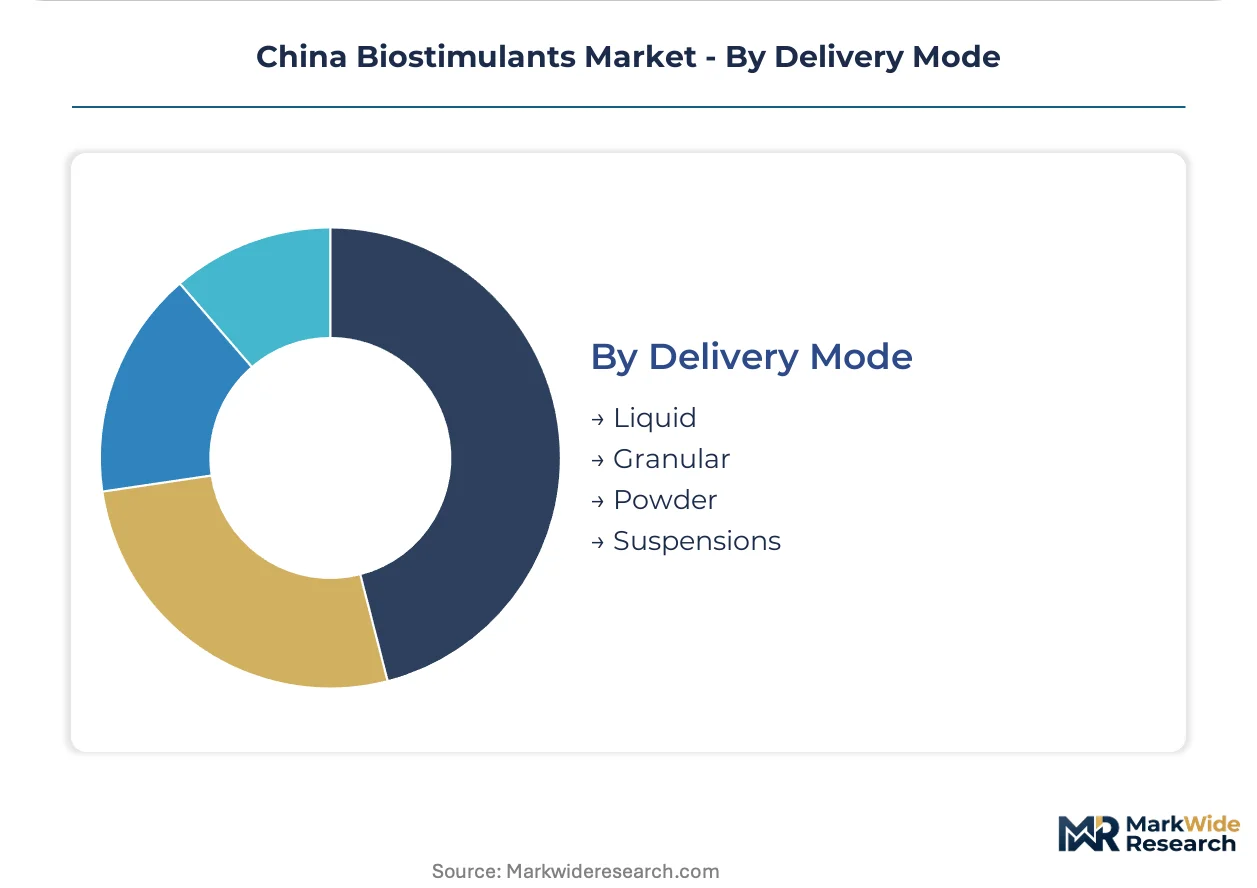
Liquid formulations capture premium positioning; granular modes retain volume leadership in grain belt applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao port infrastructure anchors Shandong Province's dominance in seaweed-derived biostimulant processing, with dedicated cold-chain terminals handling kelp biomass from coastal farming cooperatives.
Shandong Province
Greenhouse vegetable operations in Weifang and Qingdao municipalities drive concentrated demand for liquid humic acid and seaweed extract formulations. GB 20287 certification requirements under the Ministry of Agriculture and Rural Affairs filter market access toward domestic producers with validated strain libraries. Qingdao Seawin Biotech Group Co., Ltd. anchors the seaweed extract segment through integrated kelp farming and extraction operations along the Shandong coast.
North China Plain
Large-scale wheat and corn cooperatives in Hebei and Henan provinces pilot humic acid-seaweed extract combinations to reduce synthetic nitrogen application rates. Provincial agricultural technology extension stations manage cooperative procurement contracts, consolidating volume decisions among certified formulators. Lignite and peat deposits in Inner Mongolia supply feedstock for regional humic acid production, though geographic concentration creates supply vulnerability.
Sichuan Basin
High-value citrus and rice production corridors generate demand for bundled crop protection and biostimulant packages. Syngenta Group leverages global germplasm partnerships to distribute biological inputs across Sichuan and Hubei provinces. Chengdu-based agricultural technology stations validate strain performance in humid subtropical conditions, influencing cooperative procurement preferences.
Tianjin-Hebei Corridor
Saline-alkaline soil remediation applications expand across degraded agricultural zones in Tianjin and eastern Hebei. Bacillus and Trichoderma strain validation for soil restoration opens application white space as coastal saline intrusion intensifies. Novonesis competes on microbial inoculant R&D intensity, sustaining multiple strain development pipelines for drought-stress applications in these northern provinces.
China Biostimulants Market Competitive Landscape
Listed leaders compete with private specialists across registration compliance and fermentation capacity, creating a tiered structure where GB 20287 certification separates market tiers. The competitive field fragments between multinational agrichemical conglomerates with bundled distribution networks and domestic formulators with captive strain libraries and coastal kelp supply chains. Three archetypes dominate: integrated biostimulant-pesticide bundlers, seaweed extract specialists with backward kelp farming operations, and microbial inoculant R&D houses with validated strain pipelines. Capacity expansion in industrial fermentation facilities and strategic partnerships with provincial agricultural extension stations constitute the dominant competitive moves.
Within the microbial inoculant tier, Novonesis and Qingdao Seawin Biotech Group Co., Ltd. exemplify divergent sourcing strategies, with the former representing Northern European R&D-intensive fermentation science and the latter anchoring coastal Chinese kelp-to-extract vertical integration. Syngenta Group occupies a position as the bundled distribution archetype, leveraging germplasm partnerships to integrate biological inputs with crop protection portfolios across multiple provincial markets.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Plant Response Biotech Inc |
| Syngenta Group |
| Trade Corporation International |
| Binzhou Jingyang Biological Fertilizer Co Ltd |
| Qingdao Seawin Biotech Group Co., Ltd. |
| Haifa Group |
| Biolchim SpA |
| Novonesis |
| Others |
Pricing and Supply Chain Analysis
Industrial fermentation capacity utilization across Shandong and Jiangsu provinces shapes both supply concentration and price floors for microbial inoculants, with GB 20287-certified producers commanding 15-20 percent premiums over non-compliant formulators while marginal players face exit pressure from registration cost burdens.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts between North China Plain cooperatives and certified formulators, with agricultural crops absorbing bulk shipments at standard-grade humic acid pricing while horticultural segments pay premiums for liquid seaweed extract formulations with enhanced oligosaccharide concentrations. Price differentiation rests on certification grade under GB 20287 standards and geographic delivery cost from Inner Mongolia feedstock sources to coastal formulation facilities. Cost compression in standard-grade microbial inoculants is intensifying because synthetic nitrogen pricing remains depressed, forcing biostimulant suppliers to absorb margin pressure to maintain volume share. Commodity crop procurement committees exhibit highest price sensitivity, whereas Shandong greenhouse operators demonstrate lowest sensitivity due to abiotic stress tolerance premiums.
Supply Chain Analysis
Inner Mongolia lignite deposits and Shandong coastal kelp farming operations constitute the dominant chokepoints for humic acid and seaweed extract feedstock respectively, with Qingdao port cold-chain infrastructure handling enzymatic hydrolysis inputs. Raw material dependencies center on Bacillus and Trichoderma strain libraries, industrial fermentation equipment, and kelp biomass from coastal cooperatives. Single-source vulnerability pervades the Inner Mongolia humic acid supply base, where lignite extraction licenses concentrate among state-affiliated mining entities. Distribution runs through provincial agricultural technology extension stations that manage cooperative procurement contracts and consolidate volume allocation decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
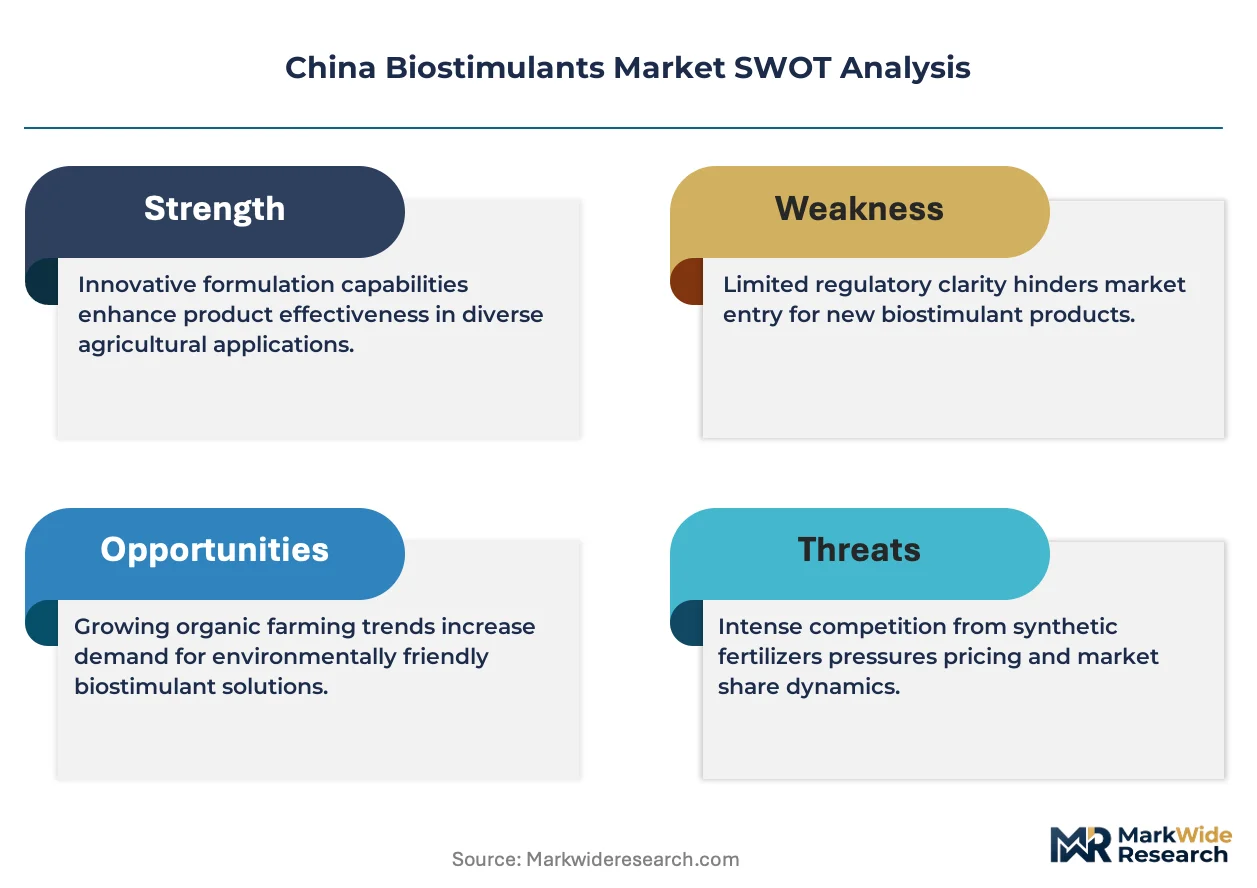
China's biostimulant sector is navigating a cyclical recovery as GB 20287 enforcement cycles through peak registration backlog clearance, with compliant domestic producers positioned to capture shelf space from import-dependent competitors facing extended commercialization timelines.
For Market Incumbents: Fortify strain library depth through targeted R&D investment in saline-alkaline soil remediation applications, particularly Bacillus consortia for Tianjin-Hebei corridor deployment. Secure backward integration into kelp farming operations along the Shandong coast to insulate seaweed extract margins from biomass price volatility. Channel control through provincial extension station partnerships remains critical as cooperative procurement displaces village-level retail.
For New Entrants and Emerging Players: Differentiate on microbial consortia formulation technology for greenhouse vegetable abiotic stress tolerance, where Shandong Province offers the most penetrable geography with established fertigation infrastructure and premium pricing tolerance. Pursue white-space positioning in protein hydrolysates for organic-certified specialty crops with limited incumbent saturation. Go-to-market execution should prioritize direct technical service relationships with agronomists at provincial agricultural academies.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic formulators with validated GB 20287 strain libraries and captive fermentation capacity over import-dependent competitors facing registration backlogs. Long-term viability across the next planning cycle hinges on provincial subsidy list positioning and saline-alkaline soil remediation application expansion. Monitor strain patent filing acceleration at provincial agricultural bureaus as the inflection indicator for procurement priority category shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| GB 20287 Certification Investment | Market access filtration under Ministry of Agriculture and Rural Affairs protocols rewards compliant domestic producers. |
| Microbial Consortia R&D Pipeline | Multi-species Bacillus-Trichoderma formulations capture greenhouse vegetable premium pricing in Shandong. |
| Backward Kelp Farming Integration | Coastal biomass supply control insulates seaweed extract margins from Qingdao port logistics volatility. |
| Provincial Extension Station Partnership | Direct cooperative procurement relationships displace traditional distributor channels in North China Plain. |
| Saline-Alkaline Strain Validation | Tianjin-Hebei soil remediation applications open degraded land restoration revenue streams. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation engineering directors, provincial agricultural extension specialists, greenhouse cooperative procurement managers, and GB standards compliance officers, then refined against secondary validation from customs trade records, Ministry of Agriculture and Rural Affairs registration databases, and provincial subsidy framework documentation. Bottom-up strain-level volume estimates and top-down agricultural input expenditure patterns were triangulated to constrain forecast variance.
Variance-decomposition framing separated product type, application crop category, and delivery mode specifications as the core segmentation dimensions modeled across the projection horizon. CAGRs were derived from installed fermentation capacity expansion trajectories and provincial biological input procurement growth curves, with nitrogen reduction trial adoption rates and saline-alkaline soil remediation penetration serving as industry-specific demand drivers.
Material uncertainties — regulatory timeline shifts for novel microbial strain approvals, synthetic nitrogen pricing volatility, and coastal kelp harvest yield fluctuations — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as GB standards enforcement intensity and provincial subsidy list revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
China Agricultural Biologicals Market
Bio-Agriculture
Biocontrol Agents Market
Bio-Agriculture
Biological Control Market
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
North America Bio Succinic Acid Market
Bio-Agriculture
Hydroponics Market
Bio-Agriculture
India Biopesticides Market
Bio-Agriculture
France Biopesticides Market
Bio-Agriculture
Asia-Pacific Biological Organic Fertilizers Market
Bio-Agriculture
North America Feed Probiotics Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
Italy Biopesticides Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
Africa Biological Organic Fertilizers Market
Bio-Agriculture
Asia-Pacific Agricultural Biologicals Market
Bio-Agriculture
Europe Biological Organic Fertilizer Market