
 United States Biofertilizer Market | 2026-2036
United States Biofertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
United States Biofertilizer Market Intelligence
Midwest fermentation capacity expansion is reconfiguring domestic microbial inoculant availability. Novonesis A/S leverages its Danish strain library to anchor North American biological supply. Kula Bio, Inc. specializes in nitrogen-fixing microbial platforms for broadacre crops. Lallemand Inc. dominates yeast and bacteria propagation through controlled manufacturing networks in the upper Midwest.
United States biofertilizers are living or latent microbial preparations containing nitrogen-fixing bacteria, phosphate-solubilizing fungi, or plant-growth-promoting rhizobacteria formulated at colony-forming unit counts exceeding industry thresholds, applied to seeds or soil to enhance nutrient cycling and reduce synthetic input dependency. Liquid biofertilizers lead volume share due to compatibility with existing planter application equipment, while granular formulations occupy premium positions in specialty crop systems where shelf stability and field longevity command higher price realization. Agricultural crops absorb the dominant share of end-user procurement, though commercial growers channel direct sales relationships to secure batch-consistent inoculant quality.
USDA EQIP cost-share structures and EPA biopesticide registration pathways under FIFRA shape product commercialization timelines and label claims for nitrogen-fixation efficacy. State-level fertilizer regulatory frameworks in Iowa, Illinois, and Nebraska impose additional quality verification requirements that filter smaller unvalidated suppliers from distribution channels. Stakeholders must monitor pending Farm Bill biological input provisions and evolving carbon credit qualification standards to align R&D portfolios with emerging revenue mechanisms.
Market Dynamics
USDA EQIP cost-share structures are accelerating biological input adoption across Corn Belt row-crop operations, compressing payback periods for microbial inoculant investments and reorienting supplier R&D priorities toward nitrogen-fixation efficacy validation.
Growth Catalysts
- USDA Environmental Quality Incentives Program:Cost-share payments reduce farmer out-of-pocket exposure for biological input trials, expanding addressable acreage beyond early adopters into mainstream corn-soy rotations.
- Corn Belt nitrogen management pressure:Row-crop farmers face escalating synthetic fertilizer cost volatility and watershed nutrient runoff restrictions, driving demand for microbial nitrogen fixation as a hedge input.
- Liquid formulation compatibility:Existing planter application equipment accommodates liquid biofertilizer delivery without capital retrofit, removing infrastructure friction from adoption decisions.
Market Restraints
- Strain propagation concentration:Domestic microbial manufacturing capacity clusters in upper Midwest fermentation facilities, creating geographic supply vulnerability and freight cost premiums for Western and Southern agricultural regions.
- EPA FIFRA registration timelines:Biopesticide pathway requirements extend product commercialization by 18-36 months, delaying revenue realization for novel nitrogen-fixing strain submissions.
- Synthetic fertilizer price cyclicality:Urea and anhydrous ammonia price collapses compress biofertilizer value propositions during downcycles, eroding farmer willingness to pay premium spreads.
Strategic Opportunities
- Carbon credit qualification standards:Emerging protocols for agricultural soil carbon sequestration create secondary revenue streams for verified biological input users, particularly in Midwestern corn-soy systems.
- Specialty crop penetration:Granular formulation shelf stability advantages position biofertilizers for expansion into high-value fruit and vegetable production where input precision commands price premiums.
- Pending Farm Bill biological provisions:Congressional reauthorization discussions include expanded biological input research funding and insurance integration mechanisms that would de-risk farmer adoption.
Industry Challenges
- CFU count standardization gaps:Inconsistent colony-forming unit measurement protocols across state fertilizer regulators create label claim disputes and interstate commerce friction.
- Microbiologist talent scarcity:Strain isolation, fermentation optimization, and field efficacy validation require specialized expertise that agricultural input employers compete for against pharmaceutical and food science sectors.
- Legacy synthetic input integration:Biofertilizer compatibility with existing fertility programs demands agronomic retraining and field trial investment that dealer networks absorb unevenly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Biofertilizer Market |
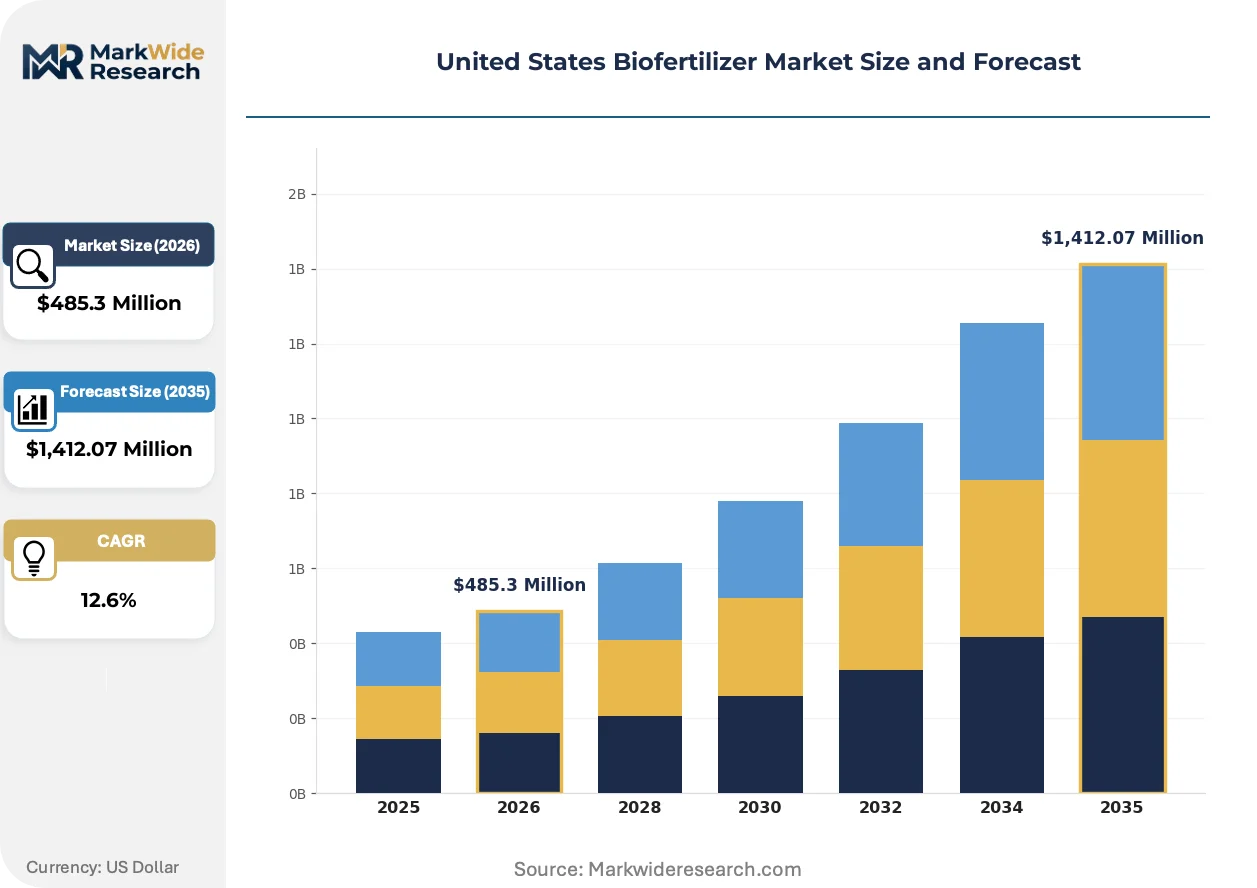
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,412.07 Million |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Biofertilizers, Granular Biofertilizers, Bioorganic Fertilizers, Bio-stimulants Application: Agricultural Crops, Horticultural Crops, Turf, Ornamentals Distribution Channel: Direct Sales, Retail, Online, Distributors End User: Farmers, Agrochemical Companies, Research Institutions, Commercial Growers |
| Companies Covered | Novonesis A/S, Rizobacter Argentina S.A., Symborg Inc., Kula Bio, Inc., Sustane Natural Fertilizer, Inc., Lallemand Inc., BioWorks, Inc., Nutramax Laboratories Inc., The Andersons Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Biofertilizer Market Strategic Shifts & Innovations
Microbial delivery systems and farmer decision-support tools are converging to transform biological input from experimental adjunct to core fertility planning, with data integration emerging as the critical differentiator between commodity inoculants and premium platforms.
Precision application hardware is migrating from blanket broadcast methods toward seed-coating and in-furrow placement technologies that improve microbial survival rates and colonization consistency. Large-scale corn and soybean operations in Iowa and Illinois are retrofitting planters with liquid injection systems at accelerated replacement cycles. This equipment migration is compressing demand for generic broadcast formulations while expanding margins for application-integrated product bundles.
The EPA's evolving biopesticide registration guidance under FIFRA is tightening efficacy substantiation requirements for nitrogen-fixation claims, forcing manufacturers to invest in multi-site field trial networks. Label claim restrictions are delaying product launches and narrowing permissible marketing language. Midwestern suppliers with established university research partnerships are securing faster pathway clearances than competitors reliant on third-party contract research.
Farmer purchasing patterns are consolidating around direct manufacturer relationships and cooperative buying groups that bypass traditional distribution markups. Commercial growers with acreage scale sufficient for batch-consistent annual contracts are negotiating quality verification protocols and dedicated supply allocations. This channel compression is most pronounced in Nebraska and Kansas where large operations command procurement leverage unavailable to smaller diversified farms.
United States Biofertilizer Market Segmentation
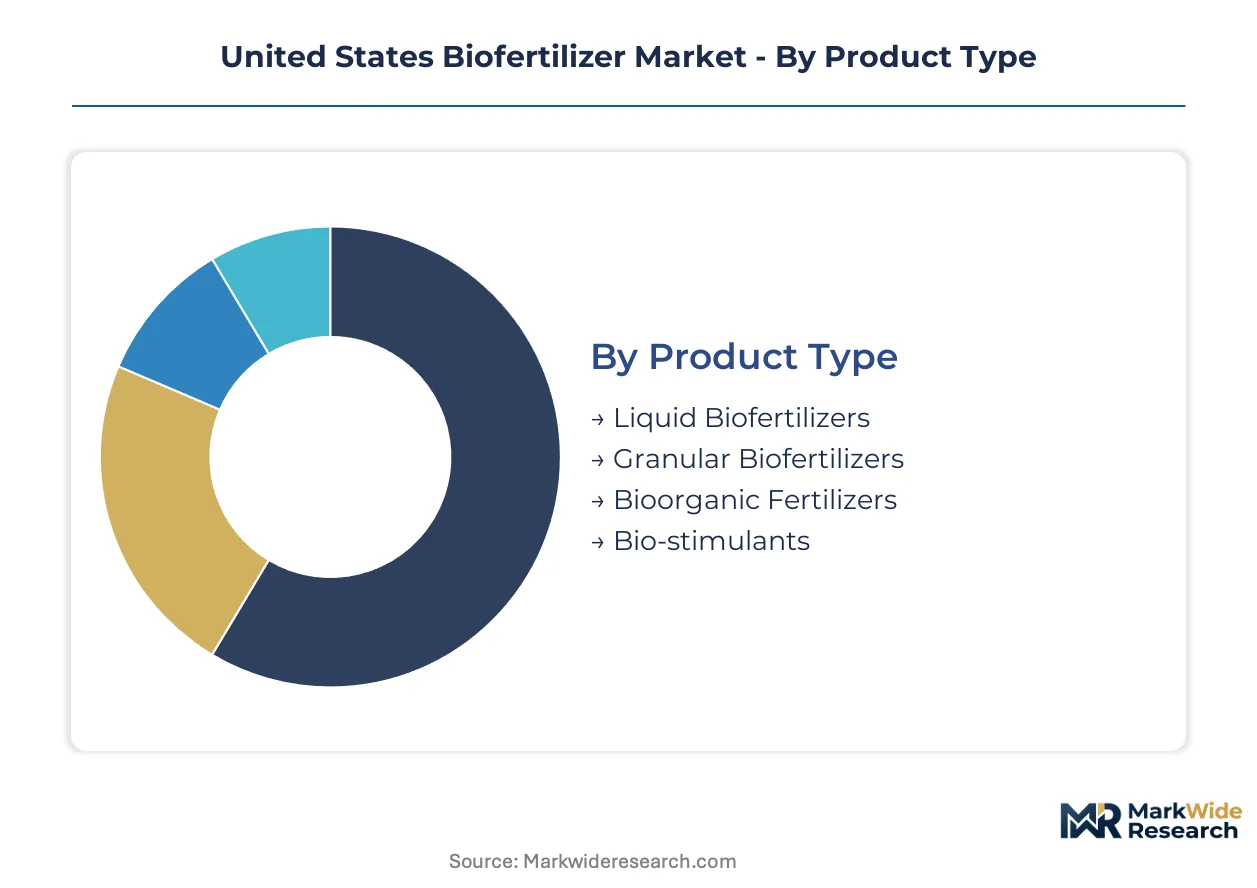
Biofertilizer segmentation reveals divergent commercial rhythms across formulation types, crop applications, and procurement channels. Understanding these cycle-time differentials enables suppliers to align inventory positioning with demand velocity and margin capture opportunities.
Product Type:
Formulation cycle times range from rapid-turn liquid blends to multi-year granular development pipelines, creating distinct working capital and R&D investment profiles across the category.
- Liquid Biofertilizers:Suspensions of nitrogen-fixing bacteria or phosphate-solubilizing fungi in aqueous carriers at colony-forming unit counts exceeding 10^8 CFU per milliliter. Corn Belt row-crop operations in Iowa and Illinois absorb dominant volumes through planter-mounted injection systems that eliminate field mixing labor. The USDA EQIP cost-share program accelerates farmer trials by compressing payback periods below two growing seasons.
- Granular Biofertilizers:Desiccated microbial preparations bound to clay or organic carriers with shelf stability extending 18-24 months under controlled storage. Specialty crop producers in California's Central Valley and Florida's vegetable districts pay premiums for field longevity that reduces application frequency in high-value production systems. Strain viability verification requirements under state fertilizer laws in Nebraska and Kansas filter smaller suppliers from premium distribution channels.
- Bioorganic Fertilizers:Composted organic matrices inoculated with functional microbial consortia combining nutrient provision with biological activity.
- Bio-stimulants:Microbial or botanical extracts enhancing plant metabolic processes without direct nutrient provision, regulated separately from biofertilizers under EPA guidance.
Liquid biofertilizers dominate installed base. Granular biofertilizers are where expansion concentrates.
Application:
End-use concentration varies sharply by crop value intensity and input substitution economics, with broadacre rotations exhibiting different adoption elasticities than protected cultivation systems.
- Agricultural Crops:Corn-soybean rotations across the Midwestern Corn Belt absorb the dominant volume share as farmers deploy microbial nitrogen fixation to hedge synthetic fertilizer price volatility. The EPA's FIFRA biopesticide registration pathway shapes commercialization timelines for novel strain introductions targeting these commodity systems.
- Horticultural Crops:Tree fruits, berries, and vegetables in Washington's Yakima Valley and Michigan's fruit belts command formulation precision that supports price premiums three to five times above broadacre equivalents. State-level quality verification frameworks in California and Florida impose additional testing burdens that consolidate supplier relationships around established manufacturers with dedicated analytical capabilities.
- Turf:Golf course and sports field maintenance programs in the Sun Belt states.
- Ornamentals:Nursery and greenhouse operations supplying landscape and retail garden markets.
Agricultural crops anchor volume throughput. Horticultural crops generate the steepest expansion trajectory.
Distribution Channel:
Channel economics reflect customer scale thresholds and quality assurance requirements that favor direct relationships for large operators while preserving intermediary roles for fragmented demand.
- Direct Sales:Manufacturer-to-grower contracts with batch-consistent quality protocols and dedicated supply allocations. Commercial operations exceeding 5,000 acres in Nebraska and Kansas leverage procurement scale to negotiate technical service packages and field trial support that dealer networks cannot replicate.
- Retail:Farm supply cooperatives and independent dealers serving diversified operations below direct-sale scale thresholds.
- Online:E-commerce platforms capturing small-scale horticultural and turf customers with standardized formulations and educational content.
- Distributors:Regional wholesalers consolidating fragmented demand and managing cold-chain logistics for temperature-sensitive liquid formulations.
Direct sales command the largest transaction values. Distributor networks retain critical mass in Western and Southern states beyond Midwestern manufacturing clusters.
End User:
User sophistication and procurement authority create distinct service intensity requirements that segment supplier resource allocation and technical support models.
- Farmers:Owner-operators and tenant producers making input decisions based on per-acre return calculations and equipment compatibility constraints.
- Agrochemical Companies:Integrated input manufacturers acquiring microbial platforms to complement synthetic portfolios or satisfy portfolio sustainability commitments.
- Research Institutions:University extension services and USDA Agricultural Research Service facilities conducting multi-site efficacy trials that underpin EPA registration submissions.
- Commercial Growers:Corporate farming operations and contract production entities with centralized procurement functions and standardized agronomic protocols across dispersed acreage.
Farmers represent the deepest installed base. Commercial growers are climbing the fastest as channel consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA EQIP cost-share structures anchor Midwestern adoption curves while state-level fertilizer quality laws filter supplier participation across Corn Belt jurisdictions.
Midwest Corn Belt
Iowa and Illinois absorb dominant liquid biofertilizer volumes through planter-mounted injection systems compatible with existing equipment. The USDA Environmental Quality Incentives Program compresses farmer payback periods below two growing seasons. Novonesis A/S leverages its Danish strain library to anchor North American biological supply from Midwestern fermentation clusters.
Great Plains
Nebraska and Kansas commercial growers exceeding 5,000 acres negotiate direct manufacturer contracts with batch-consistent quality protocols. State fertilizer regulatory frameworks impose additional CFU count verification requirements that filter smaller unvalidated suppliers. Lallemand Inc. dominates yeast and bacteria propagation through controlled manufacturing networks in the upper Midwest serving these large operations.
California Central Valley
Specialty crop producers in high-value fruit and vegetable districts pay premiums for granular formulations with 18-24 month shelf stability. The state's quality verification frameworks impose testing burdens that consolidate supplier relationships around established manufacturers. Kula Bio, Inc. positions nitrogen-fixing microbial platforms for broadacre crops while adjacent specialty applications command price premiums three to five times above commodity equivalents.
Pacific Northwest
Washington's Yakima Valley tree fruit and berry operations demand formulation precision supporting premium positioning. Geographic distance from Midwestern fermentation capacity creates freight cost premiums and supply vulnerability. Distributor networks retain critical mass in this region beyond manufacturing clusters, managing cold-chain logistics for temperature-sensitive liquid formulations.
Southeast
Florida's vegetable districts and turf maintenance programs in Sun Belt states absorb standardized formulations through cooperative buying groups. EPA FIFRA biopesticide registration pathways extend product commercialization timelines for novel strain introductions targeting these markets. Direct sales relationships remain less consolidated here than in Midwestern corn-soy systems.
United States Biofertilizer Market Key Industry Players
Capability concentration sits with strain library specialists and fermentation optimization experts; scale advantage sits with propagation networks and distribution infrastructure owners. The market structures around three tiers: multinational biological input platforms with global strain collections, domestic mid-cap specialists with regional manufacturing presence, and niche formulation providers serving specialty crop segments. Consolidation pressure operates through strategic partnerships between synthetic input manufacturers and microbial platform developers, plus capacity expansion in upper Midwest fermentation facilities.
Within the multinational platform tier, Novonesis A/S represents integrated strain-to-distribution capability, while Lallemand Inc. exemplifies controlled manufacturing network dominance. Among domestic specialists, Kula Bio, Inc. occupies a position focused on nitrogen-fixing microbial platforms for broadacre crop systems. These three anchors illustrate divergent competitive vectors: global strain library leverage, manufacturing scale economies, and targeted platform specialization.
| Leading Market Players |
|---|
| Novonesis A/S |
| Rizobacter Argentina S.A. |
| Symborg Inc. |
| Kula Bio, Inc. |
| Sustane Natural Fertilizer, Inc. |
| Lallemand Inc. |
| BioWorks, Inc. |
| Nutramax Laboratories Inc. |
| The Andersons Inc. |
| Others |
Cost & Logistics Intelligence
Midwest-to-California freight corridors transmit cost differentials that widen price spreads between Corn Belt liquid formulations and Pacific Coast granular premiums, while concentration of fermentation capacity in Iowa and Illinois grants incumbent suppliers asymmetric leverage over both input sourcing and downstream tiering.
Pricing Analysis
Geographic price spreads stretch widest between Midwestern liquid biofertilizers delivered through planter injection systems and California Central Valley granular formulations with extended shelf stability. Three-tier pricing structure across premium, standard, and economy levels reflects strain certification grade and batch consistency verification under state fertilizer laws. Cost compression in economy-tier liquid products is intensifying because freight cost premiums erode margins for distant delivery. Smaller diversified farms in the Southeast exhibit highest price sensitivity, while Nebraska commercial growers exceeding 5,000 acres absorb premium spreads for dedicated supply allocations.
Supply Chain Analysis
Upstream feedstock for microbial propagation draws from Danish strain libraries, domestic yeast and bacteria cultures, and organic carrier substrates sourced from Midwestern composting operations. Manufacturing concentrates in the United States upper Midwest, with secondary propagation nodes in Canada and limited import dependency on European specialty strains. Single-source vulnerability sits with Novonesis A/S strain library access for novel nitrogen-fixing platforms. Distribution runs through farm supply cooperatives and direct manufacturer contracts, with cold-chain logistics for temperature-sensitive liquid formulations adding cost layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in technical agronomy support and field efficacy validation are expanding faster than hardware formulation sales, creating recurring revenue layers that justify premium positioning beyond commodity inoculant pricing.
For Market Incumbents: Build regulatory data moats through multi-site field trial networks that accelerate EPA FIFRA registration clearances. Invest in backward integration into proprietary strain isolation capabilities to reduce dependency on third-party microbial libraries. Consolidate channel control by acquiring regional distributors in Western states beyond Midwestern manufacturing clusters. For New Entrants and Emerging Players: Establish a beachhead in Florida vegetable districts where direct sales relationships remain less consolidated than Midwestern corn-soy systems. Target specialty crop segments in Washington's Yakima Valley where formulation precision commands three-to-five-fold price premiums over commodity equivalents. Pursue cooperative buying group partnerships as the primary go-to-market angle for initial volume traction. For Investors and Strategic Acquirers: Fermentation optimization specialists with captive manufacturing networks in the upper Midwest represent the most defensible acquisition archetype for biological input portfolios. Long-term viability hinges on alignment with pending Farm Bill biological provisions and carbon credit qualification standards. Watch EPA biopesticide registration timeline compression as the critical inflection signal for revenue realization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Site Field Trial Network Expansion | Accelerates EPA FIFRA clearance timelines for novel nitrogen-fixing strain submissions. |
| Backward Integration into Strain Libraries | Reduces licensing costs and secures proprietary microbial platforms against supply interruption. |
| Direct Sales Channel Development | Bypasses cooperative markups and captures margin from large Nebraska and Kansas commercial growers. |
| Granular Formulation R&D Investment | Opens California Central Valley specialty crop penetration with 18-24 month shelf stability advantages. |
| Carbon Credit Protocol Alignment | Positions biological inputs for secondary revenue streams from agricultural soil sequestration verification. |
Research Approach
Operator-level perspectives from fermentation facility managers, agronomists at commercial growing operations, EPA registration consultants, and farm supply cooperative procurement directors anchored the qualitative base. Secondary validation drew from USDA EQIP program disbursement records, state fertilizer regulatory filings in Iowa and Illinois, EPA biopesticide registration databases, and university extension trial publications. Bottom-up volume estimates triangulated against top-down addressable acreage calculations across the Corn Belt.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning formulation type, crop application intensity, and procurement channel structure. CAGRs were derived from trend extrapolation of biological input adoption elasticities relative to synthetic fertilizer price cyclicality. Modeled inputs included USDA cost-share participation rates and planter equipment retrofit penetration curves in Iowa and Illinois.
Stress conditions across synthetic fertilizer price collapse scenarios, EPA registration timeline extensions, and freight cost volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about strain viability persistence and farmer willingness-to-pay threshold stability. Cross-checking against USDA NASS acreage reports and state-level fertilizer tonnage disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Bovine High-Mountain Disease Market
Bio-Agriculture
Red Algae Market
Bio-Agriculture
North America Biological Organic Fertilizer Market
Bio-Agriculture
China Feed Probiotics Market
Bio-Agriculture
Vietnam Biopesticides Market
Bio-Agriculture
India Biostimulants Market
Bio-Agriculture
Plant-Based Biologics Market
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
United States Biopesticides Market
Bio-Agriculture
Africa Biological Organic Fertilizers Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
West Africa Biostimulants Market
Bio-Agriculture
Cytokinins Market
Bio-Agriculture
India Agricultural Biologicals Market
Bio-Agriculture
Plant Based Biosurfactants Market
Bio-Agriculture
North America Bio-Ethanol Market