
 Biofertilizers Market | 2026-2036
Biofertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Biofertilizers Market Intelligence
The expansion of direct-to-farmer sales channels, including digital platforms, is reconfiguring traditional agricultural distribution networks. This shift allows for more targeted marketing and technical support. Novozymes A/S leverages its extensive R&D to develop specialized microbial strains for different crops and climates. Lallemand Inc. differentiates through its focus on yeast and bacteria-based solutions, while UPL sustains a broad portfolio integrating biofertilizers with conventional crop protection.
Biofertilizers are formulations containing living microorganisms that enhance plant nutrient uptake through natural processes. These products function by mechanisms such as atmospheric nitrogen fixation or phosphate solubilization, directly improving soil fertility. Nitrogen-fixing products like Rhizobium and Azotobacter hold a significant share, particularly for application in cereal and pulse crops. Formulations based on Mycorrhizal Fungi are expanding rapidly, valued for improving water and nutrient absorption in high-value horticulture.
Regulatory frameworks are critical in shaping market access and validating product efficacy claims. In the United States, the EPA oversees registrations, while in Europe, products must comply with standards under REACH and the EU Fertilising Products Regulation. Government bodies in India and Brazil also set quality standards, influencing farmer trust and adoption. Success hinges on navigating these diverse regional approval processes while investing in formulation technology to improve product shelf life and field performance.
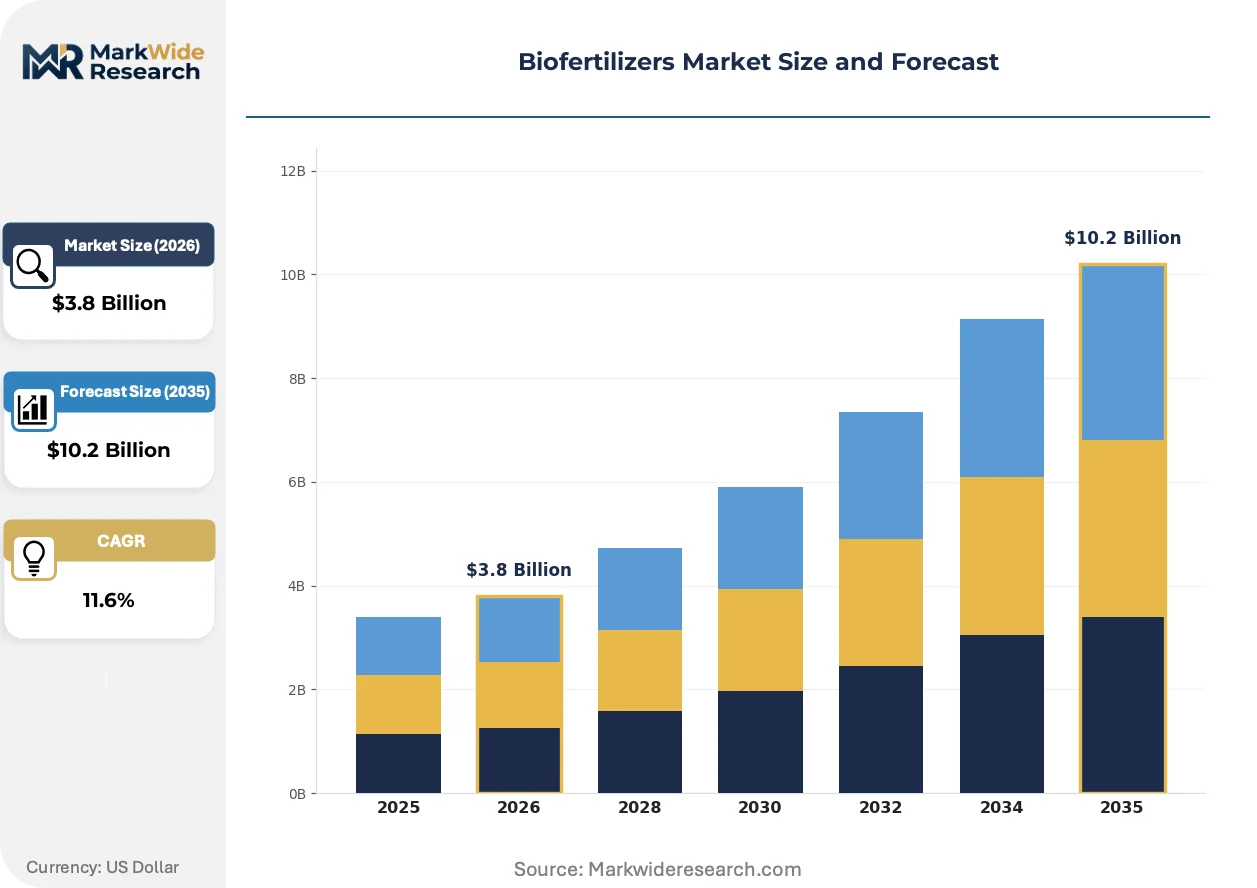
Market Dynamics
The biofertilizers market is defined by a structural shift away from chemical inputs, driven by national sustainable farming initiatives and regulations like the EU Green Deal. This transition elevates microbial science from a niche to a core agricultural technology.
Growth Catalysts
- Supportive Policies:Favorable government frameworks, including the EU Green Deal and national programs in India, provide subsidies and mandates that accelerate the replacement of synthetic fertilizers with biological alternatives in mainstream agriculture.
- Cereal Crop Adoption:Demand from large-scale cultivation of cereal and pulse crops for nitrogen-fixing products, such as those based on Rhizobium and Azotobacter, provides a significant volume-driven growth foundation for the market.
- Formulation Advances:Innovations in carrier materials and encapsulation are improving the shelf life and field efficacy of live microbial products, overcoming key historical barriers to farmer adoption and building trust in product performance.
Market Restraints
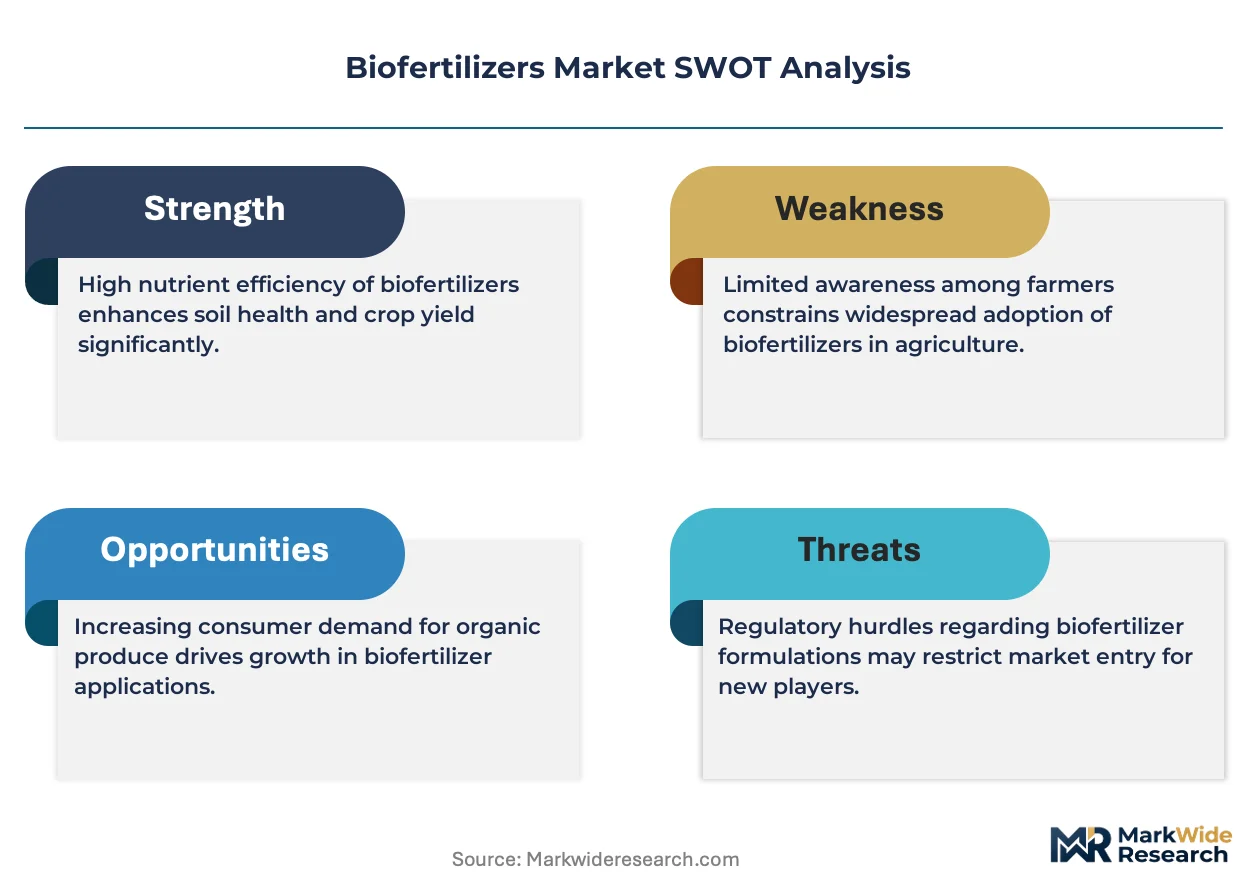
- Limited Shelf Life:The viability of living microorganisms in biofertilizer formulations is sensitive to temperature and storage conditions, creating significant logistical hurdles and limiting product shelf life compared to stable chemical alternatives.
- Regulatory Fragmentation:Navigating disparate and lengthy approval processes, such as those managed by the EPA in the United States and under REACH in Europe, increases costs and time-to-market for manufacturers seeking access.
- Competition from Conventional Inputs:The deeply entrenched infrastructure, distribution networks, and established farmer practices associated with chemical fertilizers present a substantial barrier to rapid market penetration, particularly in less-regulated regions.
Strategic Opportunities
- High-Value Horticulture:Formulations based on Mycorrhizal fungi offer significant performance benefits for nutrient and water uptake in high-value fruit and vegetable crops, representing a key expansion area beyond traditional row crops.
- Digital D2F Channels:The development of direct-to-farmer (D2F) digital platforms allows manufacturers to bypass traditional distributors, offering targeted technical support and capturing valuable field performance data to refine product offerings.
- Geographic Expansion:Agricultural economies in Southeast Asia and Africa remain significantly underpenetrated, presenting substantial growth opportunities for products tailored to local soil types, climate conditions, and dominant crop cycles.
Industry Challenges
- Quality Control Consistency:Maintaining consistent quality and microbial efficacy across large-scale production batches presents a significant operational challenge, requiring stringent process controls and investment in sophisticated fermentation and testing equipment.
- Farmer Education and Training:Effective use of biofertilizers requires different application knowledge than chemical inputs. A primary challenge is delivering scalable, practical training to a fragmented global farmer base to ensure correct usage and maximize field results.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biofertilizers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rhizobium, Azotobacter, Azospirillum, Phosphate Solubilizing Bacteria, Cyanobacteria, Mycorrhizal Fungi Application: Cereal Crops, Pulse Crops, Oilseed Crops, Horticulture, Plantation Crops, Vegetables Form: Liquid, Carrier-based, Granular, Powder, Emulsifiable Concentrate End User: Agri Input Companies, Farmers, Research Institutes, Government Agencies |
| Companies Covered | Novozymes A/S, Lallemand Inc., Rizobacter Argentina SA, UPL, Syngenta, Biomax, AgriLife, Symborg S.L, BioWorks Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biofertilizers Market Strategic Shifts & Innovations
The industrialization of microbial science is transforming biofertilizers from a supplementary product into a primary input for sustainable agriculture. This evolution is driven by precision biology, harmonizing regulations, and the reconfiguration of agricultural supply chains.
Advanced genomic and bioinformatic tools enable the rapid screening and development of specialized microbial strains. These technologies allow for the creation of products tailored to specific crops, soil types, and climatic stressors. Large-scale agricultural producers are adopting these customized solutions to optimize nutrient efficiency and improve crop resilience, moving beyond generic formulations.
Regulatory harmonization under frameworks like the EU Fertilising Products Regulation (FPR) is creating standardized pathways for market access. The FPR establishes common rules for safety, quality, and labeling, allowing products with a CE marking to be sold across the European Union. This affects manufacturers of microbial biostimulants most directly, compelling investment in rigorous efficacy data to gain market approval.
A shift toward direct-to-farmer sales models is disrupting traditional agricultural distribution. Digital platforms and manufacturer-led agronomy services are creating new channels for product delivery and technical support. This trend is most prominent in large agricultural markets like Brazil and India, where high mobile penetration enables scalable engagement and data gathering directly from end-users.
Biofertilizers Market Segmentation
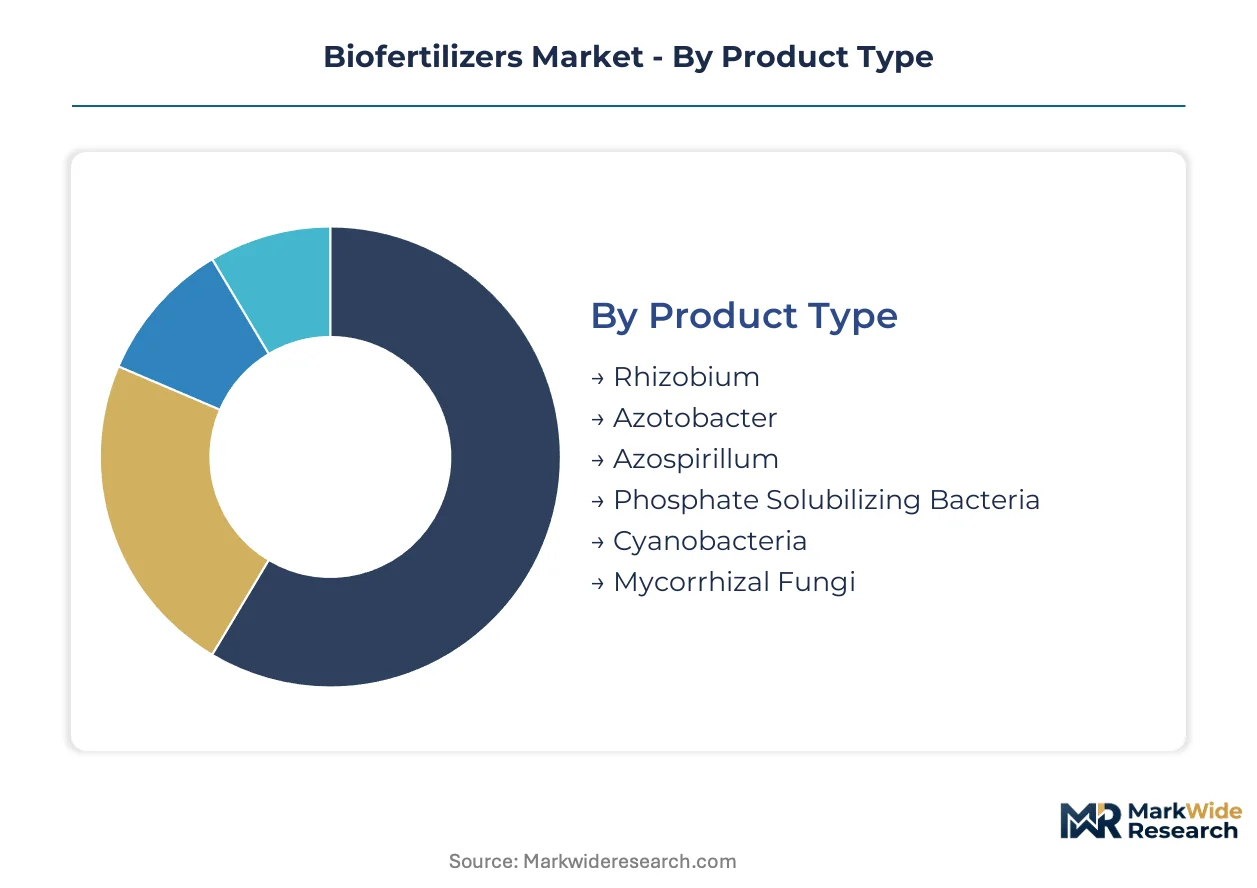
The biofertilizers market segmentation provides a granular view of product types, application areas, delivery forms, and end-user engagement. Understanding these distinct segments is essential for manufacturers to tailor solutions and for agricultural stakeholders to optimize adoption strategies across diverse farming contexts.
Product Type:
The product type segmentation reveals the diverse biological mechanisms employed to enhance soil fertility and crop nutrition across various agricultural applications.
- Rhizobium:These nitrogen-fixing bacteria form symbiotic relationships with legume roots, converting atmospheric nitrogen into a usable form for the plant, with significant demand from pulse crop cultivation in India and Brazil.
- Mycorrhizal Fungi:These fungi establish symbiotic associations with plant roots, extending the root system's reach for enhanced water and nutrient uptake, finding increasing adoption in high-value horticulture and specialty crops.
- Azotobacter:Free-living nitrogen-fixing bacteria commonly applied to cereal crops, improving soil nitrogen content without host plant dependency.
- Azospirillum:Nitrogen-fixing bacteria that colonize grass roots, enhancing nutrient absorption and promoting plant growth in cereal and forage crops.
- Phosphate Solubilizing Bacteria:Microorganisms that convert insoluble soil phosphates into forms accessible to plants, crucial for improving phosphorus availability in nutrient-deficient soils.
- Cyanobacteria:Photosynthetic nitrogen-fixing microorganisms, also known as blue-green algae, utilized in flooded rice paddies for sustainable nitrogen supply.
Established volume favors Rhizobium; emerging adoption favors Mycorrhizal Fungi.
Application:
The application segments delineate where biofertilizer formulations deliver targeted benefits for specific crop types and farming systems.
- Cereal Crops:Large-scale cultivation of crops like wheat, rice, and maize drives significant demand for nitrogen-fixing biofertilizers, supporting sustainable practices across vast agricultural lands.
- Horticulture:High-value fruit, vegetable, and ornamental crop production increasingly utilizes specialized biofertilizers for improved yield quality and enhanced nutrient efficiency, particularly in controlled environments.
- Pulse Crops:Leguminous crops such as lentils and chickpeas are major beneficiaries of Rhizobium-based biofertilizers, which directly enhance their nitrogen fixation capabilities.
- Oilseed Crops:Biofertilizers support the growth of crops like soybeans and mustard, contributing to better oil yield and plant health through improved nutrient absorption.
- Plantation Crops:Perennial crops including coffee, tea, and rubber benefit from biofertilizers that improve soil health over long growth cycles and reduce reliance on chemical inputs.
- Vegetables:Biofertilizers enhance the growth and productivity of various vegetable crops, promoting healthier produce and increased resistance to environmental stressors.
Cereal crops represent the largest cultivation area for biofertilizer use, while horticulture applications demonstrate the steepest expansion trajectory.
Form:
Biofertilizer forms reflect diverse delivery mechanisms designed to optimize microbial viability and field performance under varying environmental conditions.
- Liquid:These formulations offer ease of application through irrigation systems or seed treatment, providing uniform distribution of active microorganisms and gaining preference among large-scale growers.
- Carrier-based:Microorganisms are mixed with inert carriers like peat or lignite, offering a cost-effective and stable delivery method, particularly in regions with established traditional farming practices.
- Granular:Biofertilizers formulated into granules allow for precise application during planting or side-dressing, ensuring targeted delivery to the root zone.
- Powder:Dry powder formulations are often used for seed treatment or soil application, providing a concentrated microbial product with extended shelf life under proper storage.
- Emulsifiable Concentrate:This form allows for easy mixing with water and provides good coverage, suitable for spray applications on foliage or soil.
Liquid formulations are gaining market preference due to application convenience, while carrier-based products maintain a significant installed base.
End User:
The end-user segmentation identifies key stakeholders driving demand, adoption, and policy development within the biofertilizers ecosystem.
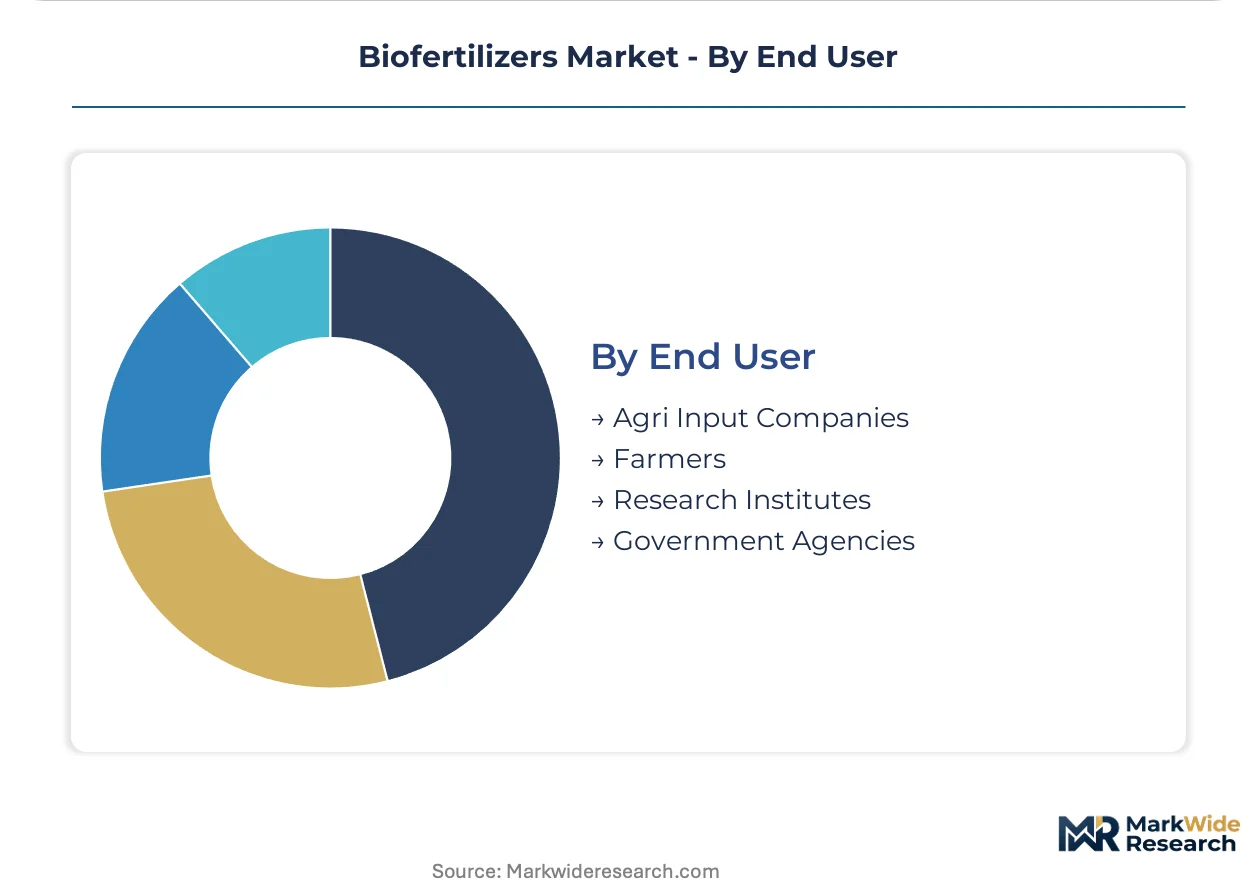
- Farmers:Direct consumers of biofertilizers, ranging from smallholder farmers to large commercial operations, seeking to improve crop yields and soil health sustainably.
- Agri Input Companies:These entities are involved in the manufacturing, distribution, and commercialization of biofertilizer products, leveraging their networks to reach agricultural markets.
- Research Institutes:Academic and private research bodies focus on developing new microbial strains, improving formulation technologies, and validating product efficacy.
- Government Agencies:Public sector bodies implement policies, provide subsidies, and establish regulatory frameworks to promote the adoption of biofertilizers for sustainable agriculture goals.
Farmers constitute the largest direct consumer base, with agri input companies playing a crucial role in product commercialization and market reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extensive agricultural infrastructure, including vast arable lands and established distribution networks, underwrites the significant role of key geographies in the biofertilizers market. These regions exhibit strong demand for sustainable agricultural inputs, supported by national policies and research initiatives.
India
Demand for biofertilizers in India is primarily driven by large-scale cultivation of cereal and pulse crops. The Indian government's National Mission for Sustainable Agriculture actively promotes the adoption of biological inputs through subsidies and awareness programs. Agricultural research centers in states like Maharashtra and Punjab focus on developing region-specific microbial strains for enhanced crop productivity.
Brazil
Brazil's expansive agricultural sector, particularly for soybean and corn production, underpins its high demand for biofertilizers. Government initiatives, such as the Low Carbon Agriculture Program (ABC+ Plan), incentivize farmers to reduce chemical fertilizer use. The agricultural hub in Mato Grosso is seeing increased farmer education and uptake of liquid biofertilizer formulations.
United States
The United States market is characterized by a strong focus on high-value horticulture and specialty crops, alongside large-scale row crop farming. The Environmental Protection Agency (EPA) oversees the registration of biofertilizer products, ensuring efficacy and safety standards. Research institutions in California and the Midwest are pioneering advanced microbial solutions tailored for specific soil types.
Germany
Germany's commitment to the EU Green Deal significantly shapes its biofertilizer market, with a strong regulatory push to reduce synthetic inputs. Products must comply with standards under REACH and the EU Fertilising Products Regulation for market access. Specialized agricultural technology clusters in Bavaria and North Rhine-Westphalia are developing innovative carrier materials and application methods.
Biofertilizers Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, focusing on microbial strain development. The biofertilizers market exhibits a tiered structure, with established agricultural input giants alongside specialized biotech firms. Archetypes include broad-portfolio providers, niche microbial specialists, and regional players. Dominant competitive moves include strategic partnerships to expand distribution and continuous investment in formulation technology to improve product stability.
Among the broad-portfolio providers, UPL and Syngenta exemplify companies integrating biofertilizers into their wider crop protection offerings. Novozymes A/S occupies a position as a leading microbial specialist, leveraging extensive R&D capabilities for strain development. Lallemand Inc. further represents a focused approach, specializing in yeast and bacteria-based solutions for diverse agricultural applications.
| Leading Market Players |
|---|
| Novozymes A/S |
| Lallemand Inc. |
| Rizobacter Argentina SA |
| UPL |
| Syngenta |
| Biomax |
| AgriLife |
| Symborg S.L |
| BioWorks Inc. |
| Others |
Cost & Logistics Intelligence
Major agricultural trade routes' cost dynamics directly influence the pricing power of concentrated microbial strain suppliers and differentiate downstream biofertilizer prices across diverse agricultural economies. This market’s logistics are particularly sensitive to product shelf life, impacting regional supply strategies.
Pricing Analysis
Volume-discounted pricing structures are prevalent, rewarding large commercial operations with more favorable rates. Price differentiation stems from formulation complexity and after-sales technical support bundled with products. Pricing pressure across the market stems from intense competition with established, lower-cost chemical fertilizer alternatives. Smallholder farmers typically exhibit the highest price sensitivity, while high-value horticulture growers prioritize efficacy and are less price-averse.
Supply Chain Analysis
Extended payment terms for critical raw materials support the upstream supply chain for carrier materials like peat and lignite. Supply concentration for advanced microbial strains primarily centers on research hubs in Europe and North America. Raw material dependencies include live microbial cultures, fermentation inputs, and specialized packaging for viable delivery. Shelf-life sensitivity creates a significant logistical chokepoint, particularly for export-oriented products. Distribution increasingly operates through a hybrid model, combining traditional agri-input networks with manufacturer-led direct-to-farmer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biofertilizers market is experiencing a significant shift in buyer power, driven by the increasing fragmentation of purchasing channels through direct-to-farmer digital platforms. This trend empowers individual farmers with more direct access to product information and technical support.
For Market Incumbents:
Harden core R&D capabilities to continuously develop specialized microbial strains and improve product stability against emerging threats from novel chemical alternatives. Invest strategically in advanced formulation technologies that extend product shelf life and enhance field efficacy. Expand direct-to-farmer digital platforms, leveraging them for targeted marketing and collecting valuable field performance data. This approach helps defend market share against both chemical inputs and agile new entrants.
For New Entrants and Emerging Players:
Build out localized distribution networks and technical support channels in underpenetrated agricultural economies like Southeast Asia and Africa. Focus on high-value horticulture applications, where Mycorrhizal fungi formulations offer significant performance benefits and command premium pricing. Develop product portfolios tailored to specific local soil types and crop cycles. A digital direct-to-farmer go-to-market strategy can bypass entrenched traditional distributors, offering a scalable entry point.
For Investors and Strategic Acquirers:
Niche microbial technology developers focusing on advanced genomic screening for crop-specific solutions represent attractive acquisition targets. These firms often possess proprietary strains and formulation expertise critical for long-term market leadership. The market's long-term viability remains strong, driven by global sustainable agriculture mandates. A key signal to watch is the successful regulatory harmonization across major agricultural regions, which could unlock significant market access and adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Formulation Technology | Improves product shelf life and field performance, overcoming key historical barriers to adoption. |
| Expand Direct-to-Farmer Platforms | Reconfigures distribution, enabling targeted marketing and capturing valuable end-user data. |
| Target High-Value Horticulture | Unlocks premium segments with specialized Mycorrhizal fungi applications for enhanced crop quality. |
| Geographic Expansion into Emerging Markets | Accesses underpenetrated regions like Southeast Asia and Africa, tapping into new growth opportunities. |
| Enhance Regulatory Compliance Capabilities | Navigates diverse regional approval processes, ensuring market access and validating product efficacy claims. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to gather granular insights into biofertilizer adoption patterns and market dynamics. Primary interviews included large commercial farmers, agri input company R&D heads, research institute scientists, and government agricultural officials. Secondary validation drew from EPA registration data, EU Fertilising Products Regulation guidelines, national sustainable farming initiative reports from India and Brazil, and academic journals on microbial science.
Market sizing calibration involved iterative refinement against historical data sets and expert consensus to ensure robust projections. The analytical framework modeled segmentation across product type, application, form, end user, and regional regulatory frameworks. Compound annual growth rates were derived from projected market growth drivers and identified restraints across the modeling period. Key industry-specific forecast inputs included biofertilizer adoption rates in major agricultural economies and regulatory approval timelines for new formulations.
Stress conditions across commodity crop prices, climate variability, and regulatory policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope for this study. Forecasts reflect assumptions regarding technological advancements and policy support for sustainable agriculture. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Poultry Manure Biofertilizers Market
Bio-Agriculture
Agricultural Biologicals Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
North America Biostimulants Market
Bio-Agriculture
Middle East and Africa Biopesticides Market
Bio-Agriculture
Biosolids Market
Bio-Agriculture
Bioherbicides Market
Bio-Agriculture
Europe Biocontrol Agents Market
Bio-Agriculture
Europe Biofertilizer Market
Bio-Agriculture
North America Bio Succinic Acid Market
Bio-Agriculture
India Biostimulants Market
Bio-Agriculture
Middle East and Africa Biofertilizers Market
Bio-Agriculture
France Biopesticides Market
Bio-Agriculture
North America Biological Organic Fertilizer Market