
 North America Biofertilizer Market | 2026-2036
North America Biofertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biofertilizer Market Intelligence
Project finance and operating lease structures for microbial fermentation capacity is fragmenting competitive entry barriers across the North America biofertilizer landscape. Novonesis leverages its integrated enzyme-manufacturing footprint to anchor strain development pipelines. Lallemand Inc competes through yeast and bacteria specialization spanning multiple inoculant categories. Suståne Natural Fertilizer Inc. differentiates via controlled composting processes that standardize organic matter content.
Biofertilizers contain living microorganisms—primarily nitrogen-fixing bacteria, phosphate-solubilizing fungi, or plant-growth-promoting rhizobacteria—formulated in liquid suspensions, granular carriers, or powder concentrates with colony-forming unit counts typically exceeding 10^8 CFU per gram; these formulations colonize the rhizosphere to enhance nutrient availability without synthetic chemical inputs. Liquid formulations lead volume share due to ease of tank-mixing with existing farm equipment, while granular products command premium positioning in organic row-crop systems where mechanical application dominates. Seed treatment applications attract fastest growth as farmers seek placement precision that reduces microbial mortality relative to broadcast soil methods.
The USDA National Organic Program and EPA biopesticide registration pathways shape product commercialization timelines and label claims across the United States, while Health Canada/PMRA oversight governs microbial strain approvals in the Canadian market. State-level fertilizer regulatory frameworks in Iowa, Illinois, and California impose additional testing protocols that filter smaller strain developers from multi-state distribution. Stakeholders must monitor evolving carbon credit methodologies for soil carbon sequestration, as these could restructure economic returns for microbial inoculant adoption beyond yield effects alone.
Market Dynamics
USDA Organic certification mandates and state-level nutrient management frameworks are compressing synthetic fertilizer dependency across Midwest row-crop operations and California specialty agriculture, forcing microbial inoculant integration into standard farm input procurement cycles.
Growth Catalysts
- USDA National Organic Program:Mandatory synthetic input restrictions for certified operations create guaranteed demand pull across corn, soybean, and vegetable production systems.
- Midwest row-crop concentration:Iowa and Illinois nutrient management plans require documented nitrogen reduction strategies, positioning biofertilizers as compliance pathways.
- Carbon credit methodologies:Emerging soil carbon sequestration protocols attach monetary value to microbial inoculant adoption beyond yield optimization alone.
Market Restraints
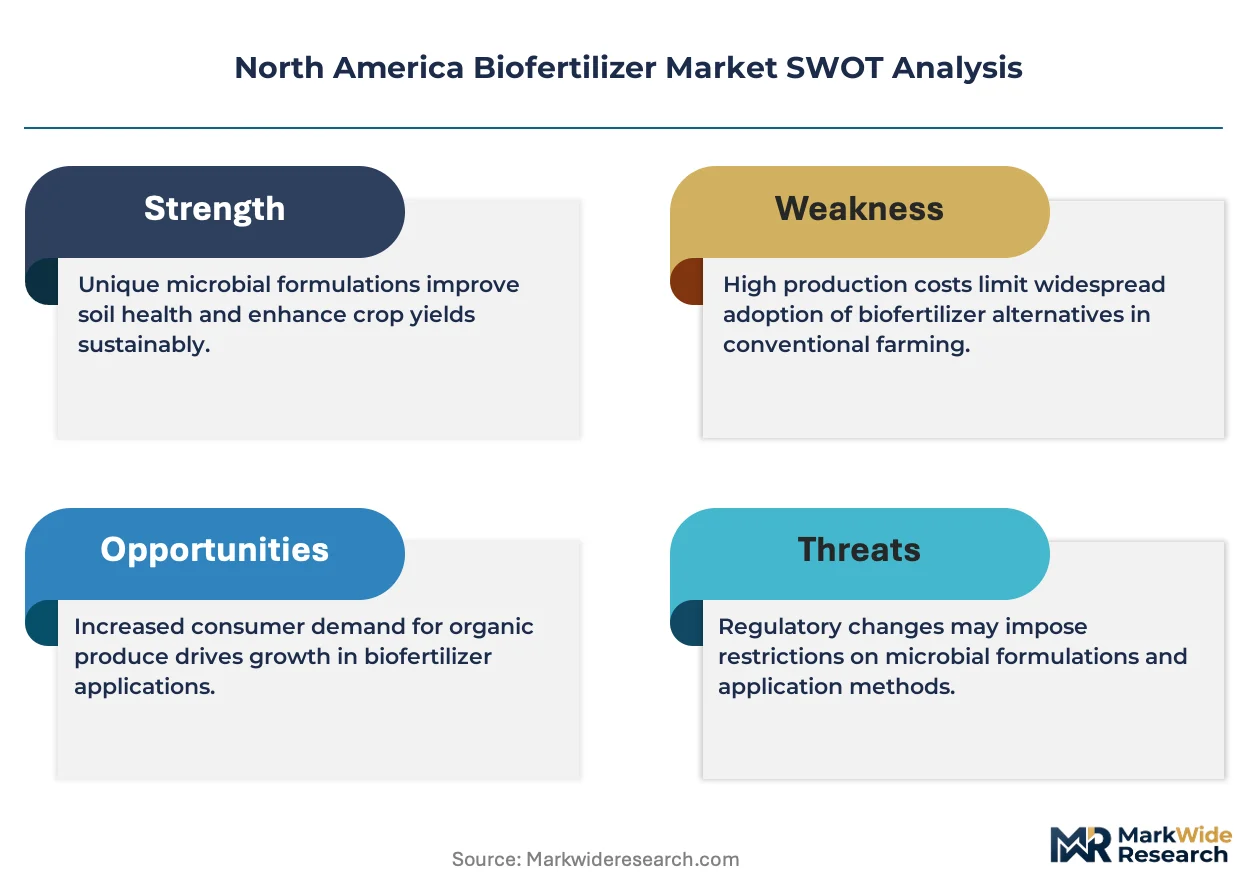
- Strain viability volatility:Temperature sensitivity during storage and application limits shelf stability and field performance consistency.
- Fermentation capacity concentration:Commercial-scale microbial production clusters in limited geographies create supply bottlenecks for new market entrants.
- Synthetic nitrogen price cycles:Low-cost urea and anhydrous ammonia during commodity downturns compress biofertilizer price competitiveness.
Strategic Opportunities
- Seed treatment integration:Precision placement technologies reduce microbial mortality versus broadcast soil application, opening premium formulation segments.
- Canada prairie expansion:Saskatchewan and Manitoba canola-wheat rotations remain underpenetrated relative to US Corn Belt saturation.
- EPA biopesticide registration streamlining:Expedited microbial strain approval pathways compress commercialization timelines for novel rhizobacteria formulations.
Industry Challenges
- Multi-state regulatory fragmentation:Iowa, Illinois, and California impose divergent testing protocols that strain distribution logistics for mid-size strain developers.
- Microbiome compatibility validation:Site-specific soil biology variability complicates standardized efficacy claims and farmer adoption confidence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biofertilizer Market |
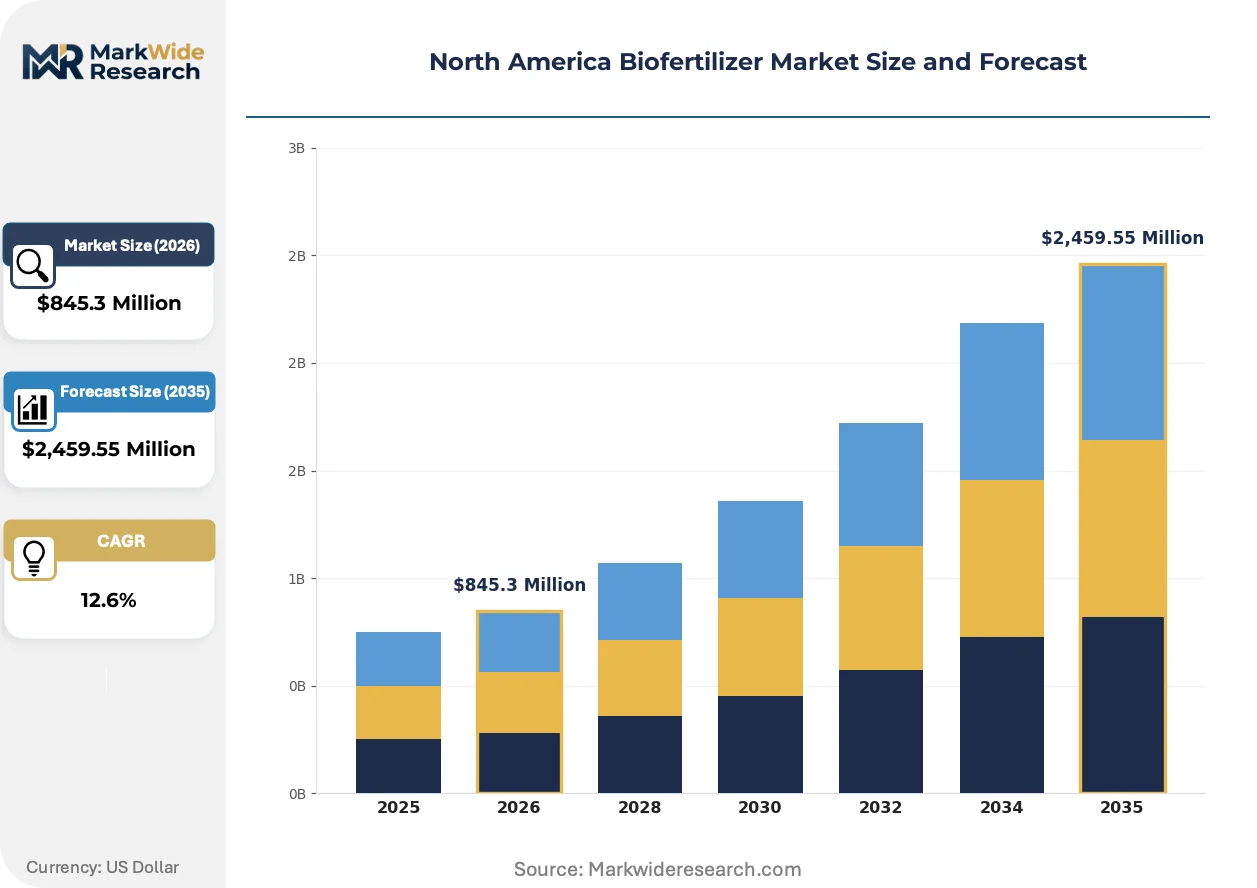
| Market Size in 2026 | $845.3 Million |
| Market Size in 2035 | $2,459.55 Million |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Granular, Powder, Tablet End User: Agriculture, Horticulture, Landscaping, Organic Farming Application: Soil Enhancement, Plant Growth, Seed Treatment, Foliar Application Distribution Channel: Online Retail, Specialty Stores, Agricultural Supply, Wholesale |
| Companies Covered | Novonesis, Lallemand Inc, Rizobacter, Suståne Natural Fertilizer Inc., Corteva Agriscience, The Andersons Inc., Koppert Biological Systems Inc., Kiwa Bio-Tech Products Group Corporation, Nutrien Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biofertilizer Market Strategic Shifts & Innovations
Digital agriculture platforms and precision microbiome management tools are compressing the gap between laboratory strain development and field-scale application optimization across North American commercial farming operations.
Microbiome sequencing and metagenomic analysis tools are virtualizing strain selection protocols. Large-scale row-crop operations in Nebraska and Kansas deploy soil DNA profiling to match specific rhizobacteria formulations to field-level microbial deficits. This capability is virtualizing the traditional one-size-fits-all inoculant model into prescription-based microbial services.
California's Department of Food and Agriculture fertilizer regulations now mandate heavy metal screening and pathogen detection for all organic input materials entering specialty crop valleys. Compliance costs filter smaller international suppliers from distribution networks. Central Valley vegetable growers increasingly demand third-party organic certification documentation as a procurement prerequisite.
Direct-to-farm microbial subscription services bypass traditional agricultural retail cooperatives. Midwest corn-soybean operations source liquid inoculants through season-long delivery contracts with fermentation specialists. Iowa and Minnesota display the fastest channel migration as farm consolidation reduces the relevance of local input dealer relationships.
North America Biofertilizer Market Segmentation
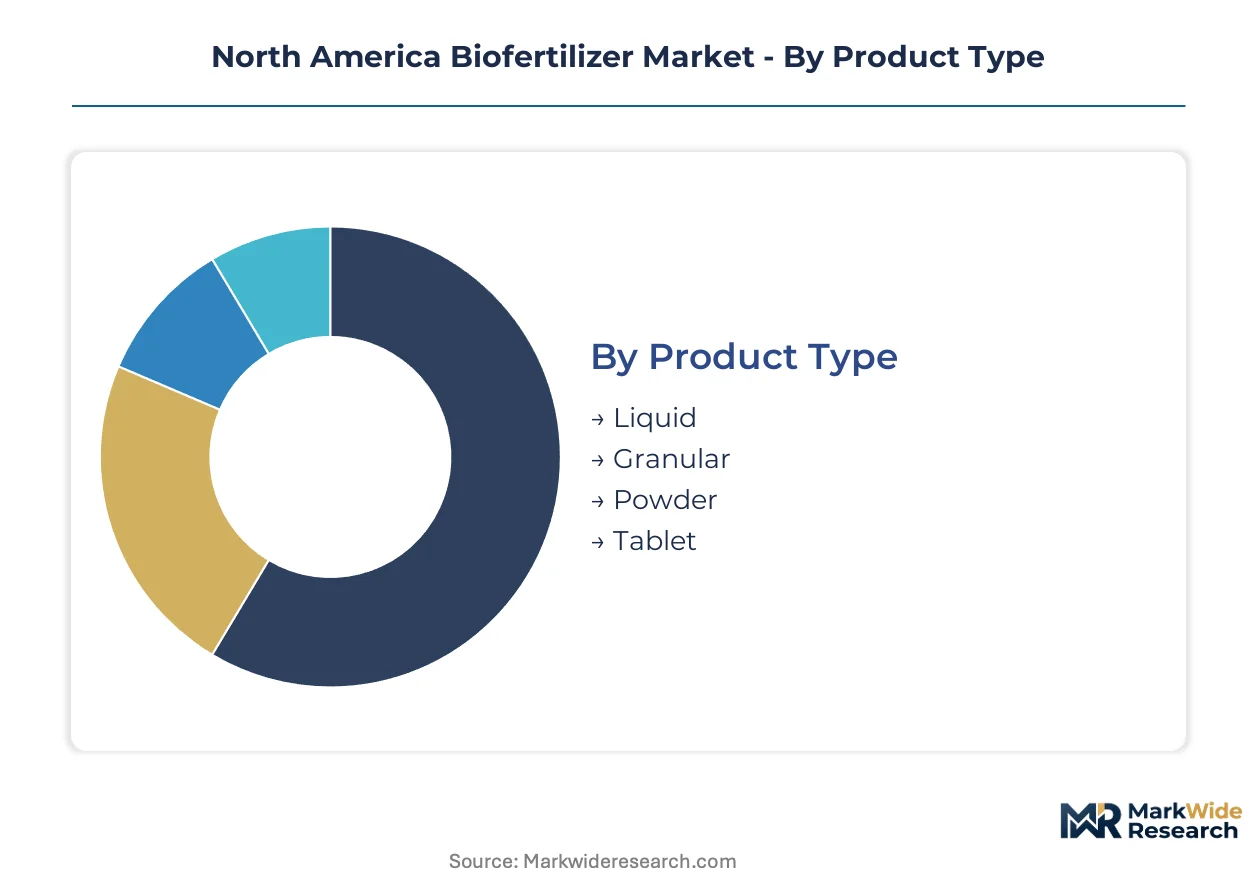
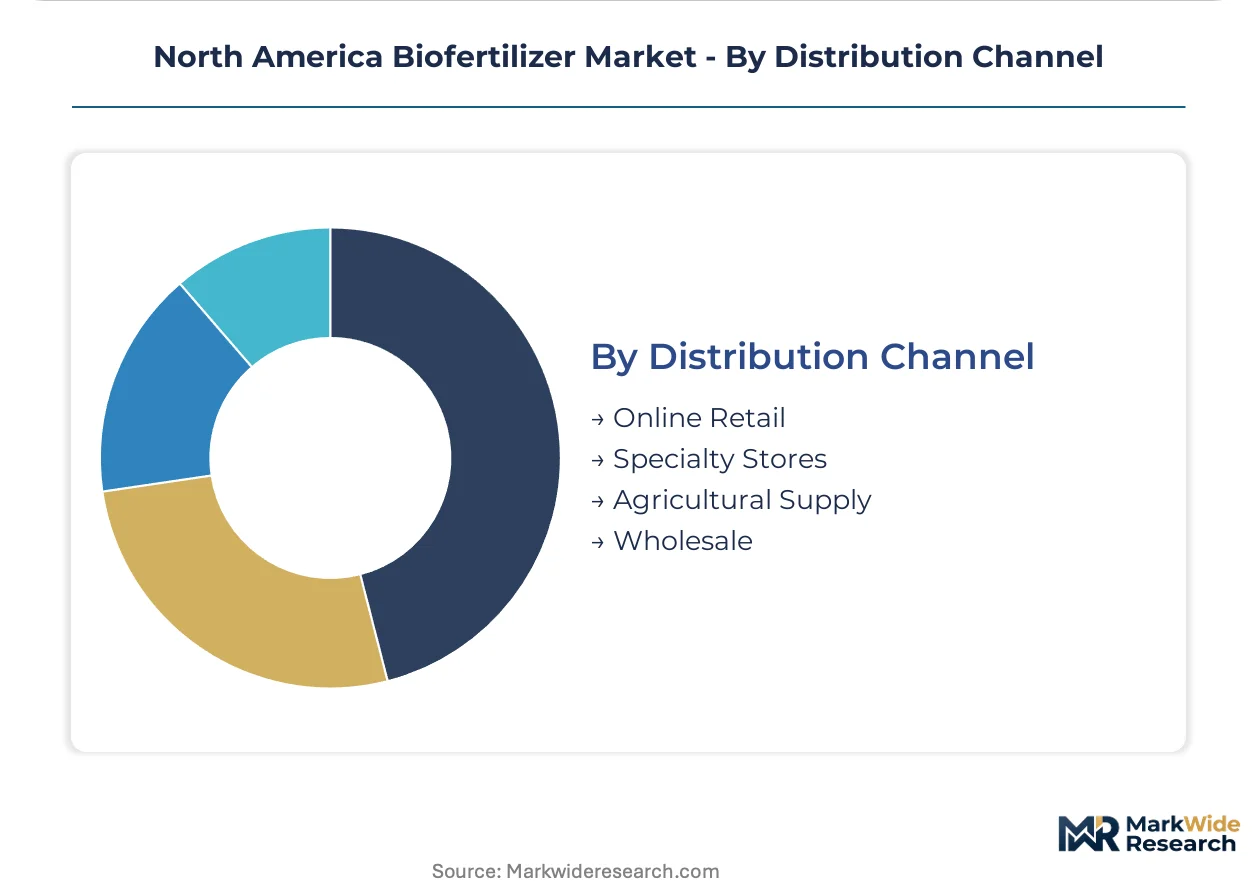
Segmentation in the North America biofertilizer market reveals how formulation chemistry, application precision, and procurement channel preferences fragment demand across distinct farmer operational profiles. Understanding these divides enables suppliers to match microbial viability requirements with specific cropping system constraints.
Product Type:
Cost tier differentiation separates premium-positioned formulations from commodity-grade alternatives based on shelf stability and application infrastructure requirements.
- Liquid:Suspensions of nitrogen-fixing bacteria or phosphate-solubilizing fungi in aqueous carriers with CFU counts exceeding 10^8 per milliliter. Midwest corn-soybean operations in Iowa and Illinois dominate procurement due to compatibility with existing sprayer fleets and tank-mix flexibility with herbicide programs.
- Granular:Microbial cultures immobilized on peat, clay, or compost-based carriers sized for mechanical spreader application. Organic row-crop systems across the Corn Belt absorb volume as mechanical application dominates certified operations avoiding synthetic input contamination risks.
- Powder:Concentrated freeze-dried formulations requiring reconstitution prior to field deployment. Specialty crop valleys in California utilize powder concentrates for high-value vegetable transplant production where precise dosing controls input costs.
- Tablet:Compressed carrier matrices designed for dissolution in irrigation systems or transplant water. Greenhouse and nursery operations in Florida and Texas represent primary uptake channels for this labor-reducing format.
Liquid formulations hold installed capacity. Granular products are rotating up the share rankings.
End User:
Application intensity and certification requirements create divergent customer profiles across commodity and specialty production systems.
- Agriculture:Broadacre row-crop and small-grain operations spanning millions of acres where microbial inoculants substitute for synthetic nitrogen in corn, soybean, and wheat rotations. USDA Organic certification mandates in the Corn Belt accelerate procurement integration into standard input cycles.
- Horticulture:Fruit, nut, and vegetable production systems with high per-acre input intensity and premium price realization. California Central Valley growers drive demand as state-level fertilizer regulations mandate heavy metal screening and pathogen detection for all organic inputs.
- Landscaping:Turf management, golf course maintenance, and municipal green space operations seeking reduced synthetic chemical footprints. Municipal procurement policies in water-sensitive jurisdictions across Arizona and Colorado favor biological alternatives for runoff compliance.
- Organic Farming:Certified operations subject to USDA National Organic Program synthetic input prohibitions. Midwest and California operations guarantee baseline demand regardless of commodity price cycles.
Agriculture commands volume concentration. Horticulture is climbing the fastest on margin contribution.
Application:
Placement precision and microbial mortality risk separate soil-based methods from targeted plant-contact approaches.
- Soil Enhancement:Broadcast or banded incorporation of microbial inoculants into root zone environments. Conventional corn operations in Nebraska and Kansas apply this method for bulk nitrogen fixation despite higher microbial loss rates versus targeted placement.
- Plant Growth:Direct root or rhizosphere inoculation during transplanting or establishment phases. Vine and tree crop producers in Washington and Oregon utilize plant growth applications for perennial establishment where long-term microbial colonization justifies labor investment.
- Seed Treatment:Microbial coating of seeds prior to planting ensuring proximity to emerging root systems. Fastest-expanding application method as precision placement reduces mortality versus broadcast soil methods; major seed companies integrate biological coatings into premium germplasm offerings.
- Foliar Application:Aerial or ground-based spraying of microbial suspensions onto plant surfaces for phyllosphere colonization. Limited adoption due to UV sensitivity and desiccation risk constraining microbial survival on leaf surfaces.
Soil Enhancement retains volume leadership. Seed Treatment is gaining share fastest on mortality reduction advantages.
Distribution Channel:
Procurement channel selection reflects farm scale consolidation and input dealer relationship erosion across the region.
- Online Retail:Direct-to-farm e-commerce platforms enabling subscription-based microbial procurement bypassing traditional cooperatives. Iowa and Minnesota display fastest channel migration as farm consolidation reduces local input dealer relevance.
- Specialty Stores:Independent organic input retailers serving certified operations with technical consultation and product curation. California and Vermont maintain dense specialty store networks aligned with organic producer clustering.
- Agricultural Supply:Farmer cooperatives and regional input dealers with established credit relationships and agronomic support services. Dominant channel for conventional row-crop operations in Illinois and Indiana where input bundling with fertilizer and crop protection simplifies procurement.
- Wholesale:Bulk procurement by large-scale farming operations, institutional buyers, and private-label distributors. Prairie grain operations in Saskatchewan and Manitoba source through wholesale channels given scale economies and limited retail infrastructure.
Agricultural Supply maintains channel dominance. Online Retail is rotating up the share rankings on consolidation-driven relationship fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American biofertilizer trade flows reveal a net importer position for specialized microbial formulations, with domestic fermentation capacity concentrated in the Midwest Corn Belt and Prairie Provinces while premium inoculant strains move cross-border between the United States and Canada.
United States
Iowa and Illinois corn-soybean operations drive bulk nitrogen-fixing inoculant procurement through state nutrient management compliance pathways. The USDA National Organic Program mandates synthetic input restrictions that guarantee baseline demand regardless of commodity price cycles. California's Central Valley specialty crop valleys impose heavy metal screening requirements that filter smaller international suppliers from distribution networks.
Canada
Saskatchewan and Manitoba canola-wheat rotations remain underpenetrated relative to US Corn Belt saturation, creating expansion corridors for phosphate-solubilizing fungal formulations. Health Canada and PMRA microbial strain approval pathways govern product commercialization timelines across Prairie grain operations. Ontario's greenhouse and nursery clusters in the Niagara Peninsula absorb tablet-formatted inoculants for labor-reducing irrigation integration.
Mexico
Sinaloa and Sonora vegetable export zones generate demand for powder-concentrate biofertilizers serving high-value tomato and pepper production bound for US markets. The country's national agricultural regulator oversees microbial input registration through pathways aligned with EPA biopesticide frameworks. Guanajuato's berry production corridors near Irapuato deploy liquid rhizobacteria suspensions compatible with existing drip irrigation infrastructure.
North America Biofertilizer Market Key Industry Players
On the supply side, the industry is consolidating around integrated fermentation specialists and agricultural input conglomerates with captive microbial development pipelines. Three archetypes dominate competitive positioning: enzyme-manufacturing incumbents leveraging strain development synergies, dedicated yeast and bacteria specialists spanning multiple inoculant categories, and controlled-composting operators standardizing organic matter content for premium organic certification compliance. Dominant competitive moves include backward integration into fermentation capacity and strategic partnerships with seed companies for treatment-application integration.
Within the integrated manufacturing tier, Novonesis anchors strain development through enzyme-manufacturing footprint synergies, while Lallemand Inc occupies a specialist position spanning yeast and bacteria categories across multiple inoculant formats. Suståne Natural Fertilizer Inc. exemplifies the controlled-process archetype, differentiating through standardized organic matter content achieved via proprietary composting methodologies.
| Leading Market Players |
|---|
| Novonesis |
| Lallemand Inc |
| Rizobacter |
| Suståne Natural Fertilizer Inc. |
| Corteva Agriscience |
| The Andersons Inc. |
| Koppert Biological Systems Inc. |
| Kiwa Bio-Tech Products Group Corporation |
| Nutrien Ltd |
| Others |
Cost & Logistics Intelligence
Fermentation capacity utilization rates across the Midwest Corn Belt and Prairie Provinces shape supplier pricing posture and procurement behavior throughout the North American biofertilizer trade. Overcapacity in liquid rhizobacteria production compresses spot pricing for commodity-grade formulations, while constrained granular carrier supply tightens premiums for organic-certified mechanical application products.
Pricing Analysis
Industrial OEM buyers anchor the three-tier pricing structure across premium, standard, and economy levels in this market. Premium formulations carrying USDA Organic certification and third-party heavy metal screening command spreads over commodity liquid suspensions, with volume scale and after-sales technical support bundling as secondary differentiation drivers. Pricing pressure stems from synthetic nitrogen price cycles, particularly low-cost urea availability during commodity downturns that compress biofertilizer competitiveness in conventional corn operations. Organic-certified row-crop growers display lowest price sensitivity due to mandatory input restrictions, while conventional Midwest soybean operations exhibit highest elasticity to per-acre cost comparisons.
Supply Chain Analysis
Export-control regimes limiting microbial strain technology flows shape supply security calculations for North American biofertilizer producers. Fermentation capacity concentrates in the United States, Canada, and Mexico, with strain development pipelines drawing from proprietary culture collections and university research partnerships. Raw material dependencies center on molasses and yeast extract feedstocks for microbial propagation, plus peat and clay carriers for granular formulation stability. Single-source vulnerability runs through concentrated enzyme-manufacturing footprints that anchor integrated strain development. Distribution runs through agricultural cooperatives and direct-to-farm subscription channels, with seed company partnerships emerging as the fastest-growing downstream structure for precision placement integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America biofertilizer market is positioned for cyclical recovery as synthetic nitrogen price volatility and carbon credit methodology maturation reset farmer input economics. USDA Organic certification mandates provide non-discretionary demand baselines that insulate the sector from commodity downturn severity.
For Market Incumbents: Insulate strain viability performance through captive fermentation capacity expansion in Iowa and Illinois, where nutrient management compliance creates sticky demand. Secure seed treatment integration partnerships with major germplasm providers to lock out emerging microbial coating specialists. Invest in Health Canada PMRA registration pipelines to preempt Canadian prairie expansion corridors before regional competitors establish distribution.
For New Entrants and Emerging Players: Build out direct-to-farm subscription services targeting Minnesota and Iowa farm consolidation zones where traditional cooperative relationships are fragmenting. Target Saskatchewan and Manitoba canola-wheat rotations as the most penetrable geography relative to US Corn Belt saturation. Leverage soil DNA profiling partnerships with digital agriculture platforms to differentiate through prescription-based microbial matching rather than commodity inoculant competition.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation specialists with seed treatment integration contracts and season-long delivery subscriptions. Long-term viability across the five-to-ten year window rests on carbon credit methodology adoption that monetizes soil carbon sequestration beyond yield effects. Prioritize acquisition targets with Health Canada strain approvals and California heavy metal screening compliance already secured. Watch EPA biopesticide registration streamlining progress as the key inflection signal for novel rhizobacteria commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive microbial production reduces strain viability risk and secures supply for seed treatment partnerships. |
| Seed Treatment Technology Partnership | Precision placement integration with Corteva and Bayer germplasm platforms locks in premium formulation demand. |
| Health Canada PMRA Registration Acceleration | Early strain approval in Saskatchewan and Manitoba opens underpenetrated prairie expansion corridors. |
| Carbon Credit Methodology Alignment | Soil carbon sequestration protocol qualification attaches monetary value beyond yield optimization alone. |
| Direct-to-Farm Subscription Channel Buildout | Bypassing agricultural cooperatives captures farm consolidation-driven procurement relationship fragmentation. |
Research Approach
A standing panel of fermentation facility operators, seed company biologicals directors, USDA Organic certification auditors, and agricultural cooperative procurement managers provided ongoing calibration for this study. Primary fieldwork combined structured interviews with secondary validation through EPA biopesticide registration databases, Health Canada PMRA microbial strain approval records, and USDA National Organic Program compliance filings. State-level fertilizer regulatory frameworks from Iowa, Illinois, and California supplemented trade flow analysis and customs data for cross-border strain movements. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the analysis window.
Scenario bracketing anchored the quantitative framework, with demand trajectories tested against synthetic nitrogen price cycle extremes and carbon credit adoption speed variations. Segmentation dimensions spanned formulation chemistry, application precision, end-user certification requirements, and procurement channel migration patterns. CAGRs derived from installed fermentation capacity expansion schedules, farm consolidation rates, and regulatory compliance timeline assumptions. Industry-specific forecast inputs incorporated USDA Organic acreage conversion data and state nutrient management plan implementation schedules.
Stress conditions across synthetic nitrogen price volatility, carbon credit methodology adoption delays, and microbial strain viability degradation rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fermentation capacity utilization and seed treatment integration penetration. Material shifts in EPA biopesticide registration timelines or Health Canada strain approval pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
Bio Rational Fungicides Market
Bio-Agriculture
Rhizobium-Based Biofertilizer Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
Asia-Pacific Agricultural Biologicals Market
Bio-Agriculture
Middle East and Africa Animal Genetics Market
Bio-Agriculture
Europe Biofertilizer Market
Bio-Agriculture
Bio-Insecticide Market
Bio-Agriculture
United States Biopesticides Market
Bio-Agriculture
Europe Biopesticides Market
Bio-Agriculture
China Agricultural Biologicals Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
Nannochloropsis Market
Bio-Agriculture
Bionematicides Market
Bio-Agriculture
Europe Biocontrol Agents Market
Bio-Agriculture
Biosolids Market