
 United Kingdom Biopesticides Market | 2026-2036
United Kingdom Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Biopesticides Market Analytics
Organic growers and specialty crop farmers is redrawing procurement patterns across the United Kingdom biopesticides sector. BASF SE leverages its microbial strain library to anchor biological solutions in cereal and vegetable programs. Bayer AG sustains field trial networks that validate biocontrol efficacy under UK climatic conditions. Syngenta UK Limited competes through distribution partnerships with major agronomy service providers.
United Kingdom biopesticides comprise living organisms, naturally occurring substances, and plant-incorporated protectants formulated to suppress agricultural pests through non-chemical modes of action, typically requiring storage temperatures between 4°C and 25°C to preserve viable cell counts. These products serve commercial farming operations seeking residue compliance and resistance rotation within integrated pest management protocols. Microbial pesticides dominate current volume flows, reflecting established fermentation supply chains and farmer familiarity with Bacillus thuringiensis and Trichoderma-based formulations. Biochemical pesticides occupy premium price tiers where botanical extracts and semiochemicals command margins from high-value fruit and protected salad crops. Plant-incorporated protectants remain nascent, constrained by UK regulatory timelines for genetically modified organism approvals and limited domestic breeding infrastructure.
The UK's Health and Safety Executive enforces pesticide authorization under retained EU Regulation 1107/2009, while the Farming Rules for Water restrict chemical active ingredient runoff into protected water bodies. The Sustainable Farming Incentive and forthcoming Environmental Land Management schemes redirect public support toward biological alternatives, tightening market access for synthetic chemistries. Stakeholders must monitor divergence between UK and EU regulatory frameworks as independent scientific assessments reshape product approval timelines and maximum residue limit harmonization.
Market Dynamics
The Sustainable Farming Incentive redirects subsidy flows toward integrated pest management, compressing demand timelines for biological alternatives while specialty vegetable growers accelerate microbial product procurement.
Growth Catalysts
- Retained EU Regulation 1107/2009:The Health and Safety Executive's pesticide authorization framework creates predictable pathways for microbial active substance approvals, reducing regulatory uncertainty for fermentation-based manufacturers.
- East Anglia horticulture belt:Intensive vegetable operations in Norfolk and Suffolk deploy Bacillus thuringiensis rotations to manage resistance in protected salad crops, clustering demand geographically.
- Microbial fermentation infrastructure:Established UK bioprocessing capacity for Trichoderma and entomopathogenic fungi lowers production cost curves relative to imported biochemical alternatives.
Market Restraints
- Storage temperature sensitivity:Viable cell count degradation above 25°C limits distribution reach during summer months, constraining shelf-life extension investments.
- EU divergence risk:Independent UK scientific assessments under the Health and Safety Executive may misalign with EFSA evaluations, complicating maximum residue limit harmonization for export-oriented growers.
- Synthetic chemistry substitution:Pyrethroid and neonicotinoid alternatives retain cost advantages in broadacre cereal applications, delaying biological penetration outside high-value horticulture.
Strategic Opportunities
- Environmental Land Management schemes:Defra's forthcoming habitat restoration incentives expand addressable acreage beyond conventional farming into agroforestry and pollinator corridor management.
- Semiochemical-biological convergence:Mating disruption pheromones paired with entomopathogenic nematodes create combination product categories for codling moth and tortrix moth control in Kent apple orchards.
- Direct-to-grower digital channels:Agronomy service platforms bypass traditional distribution markups, enabling microbial concentrate subscription models for precision dosing in glasshouse operations.
Industry Challenges
- Formulation chemist scarcity:UK universities produce limited graduates with combined expertise in fermentation microbiology and agricultural adjuvant development, constraining R&D pipeline velocity.
- Field trial validation timelines:Three-year efficacy datasets under UK climatic variability delay product registration, extending payback periods for strain library investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Biopesticides Market |
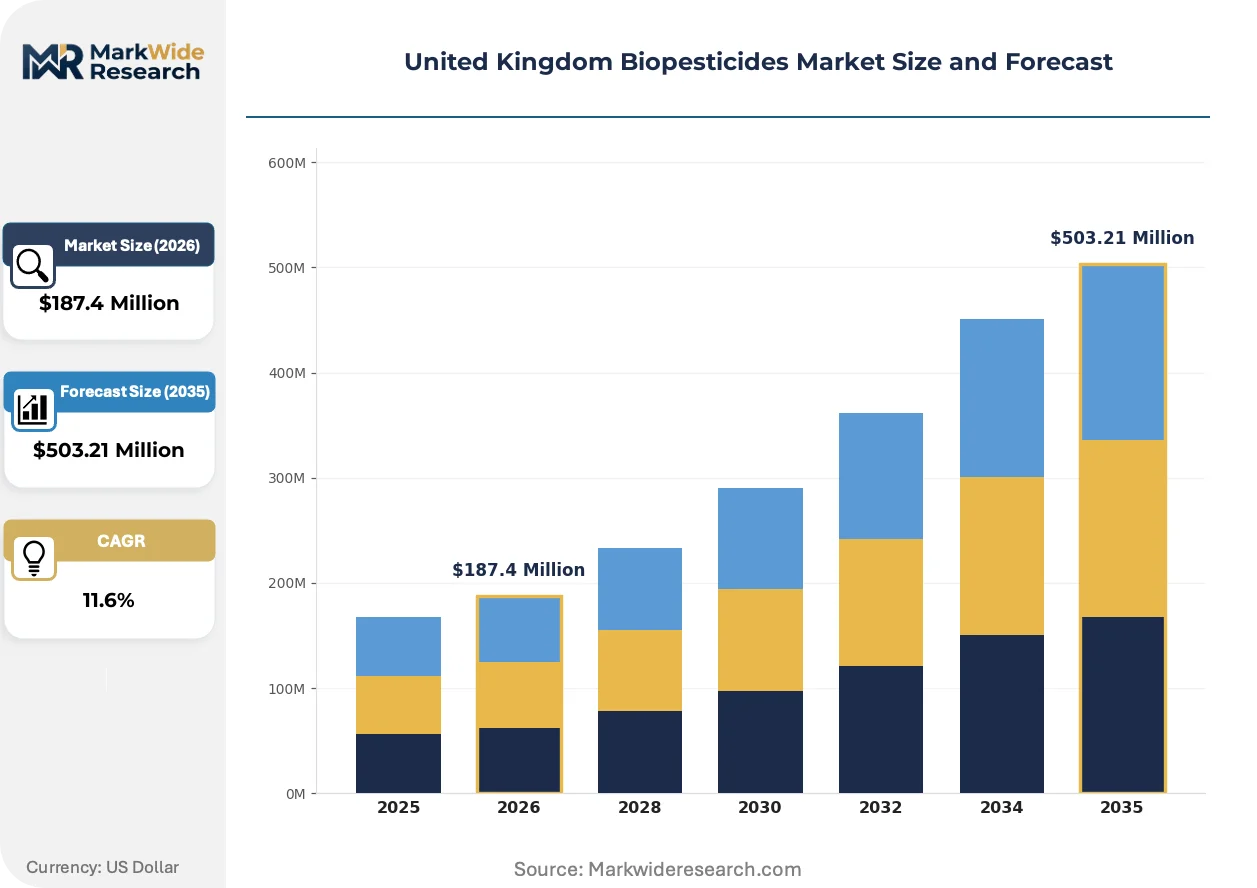
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Pesticides, Biochemical Pesticides, Plant-Incorporated Protectants, Others Application: Agriculture, Horticulture, Turf, Forestry End User: Farmers, Crop Protection Companies, Research Institutions, Organic Growers Distribution Channel: Direct Sales, Retail, Online, Wholesale |
| Companies Covered | BASF SE, Bayer AG, Syngenta UK Limited, Bionema Limited, Koppert Biological Systems, FMC Corporation, UPL, Environmental Crop Management Limited, Novonesis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Biopesticides Market Evolving Landscape
Biological active substance development is fragmenting traditional crop protection procurement patterns as growers layer multiple microbial modes of action into resistance management protocols.
RNA interference technology is fragmenting conventional insecticide categories by enabling species-specific suppression without off-target effects. Protected strawberry producers in Herefordshire pilot double-stranded RNA formulations against spotted wing drosophila. This precision mechanism compresses market space for broad-spectrum chemical alternatives while requiring new applicator training infrastructure.
The Farming Rules for Water tighten active ingredient runoff restrictions into protected water bodies, forcing arable operators toward buffer-zone-compatible biological applications. Catchment-sensitive farming areas in the West Midlands face disproportionate compliance pressure. Potato and vegetable growers respond by substituting microbial fungicides for synthetic azole programs in high-risk erosion zones.
Buyer aggregation through cooperative purchasing groups alters procurement power distribution across the value chain. Producer organizations in Lincolnshire and Cambridgeshire negotiate microbial concentrate volumes directly with fermentation facilities, displacing traditional agronomy merchant intermediaries. This concentration trend pressures distributor margins while rewarding manufacturers with flexible bulk formulation capabilities.
United Kingdom Biopesticides Market Segmentation
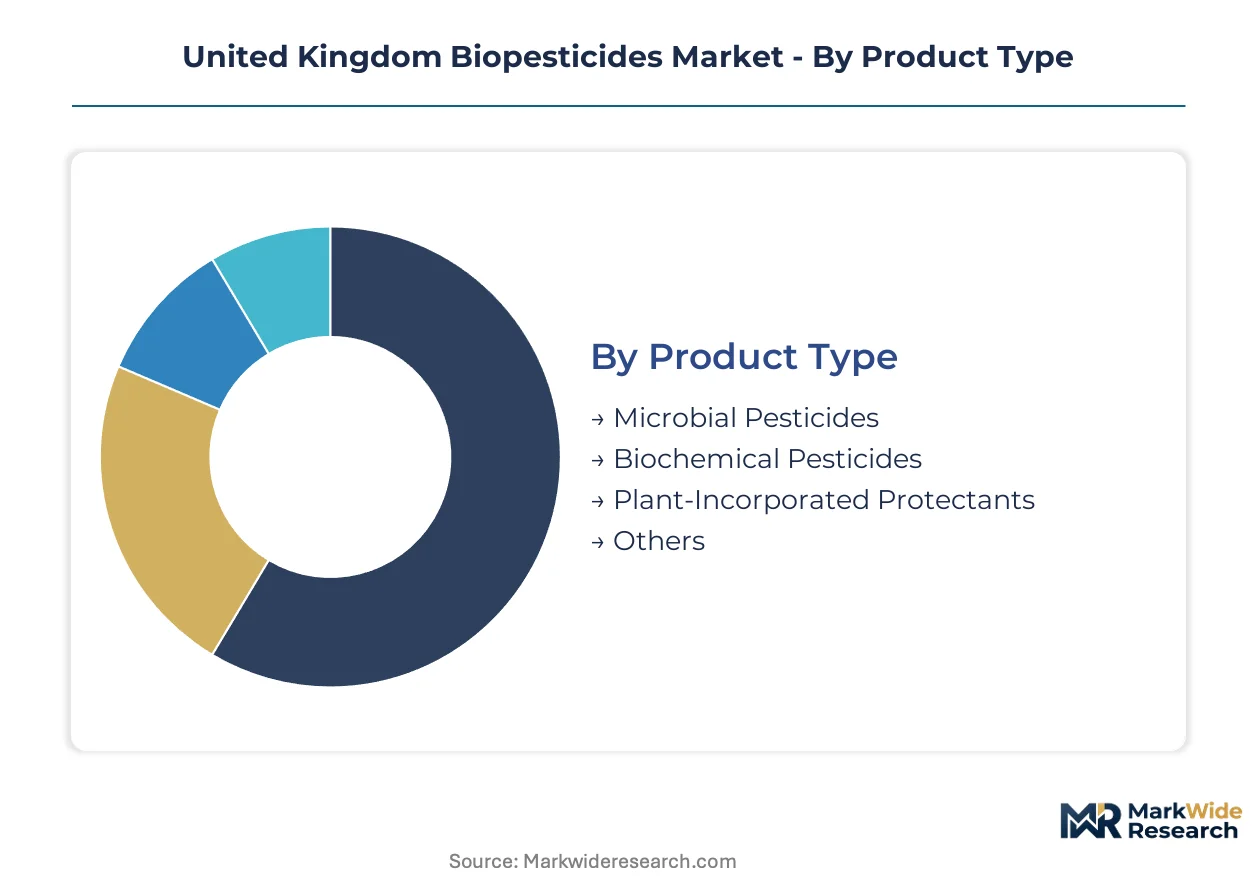
Product type, application, and distribution channel configurations determine procurement economics and regulatory compliance pathways for UK biopesticide suppliers. Segment boundaries shift as the Sustainable Farming Incentive redirects subsidy flows toward integrated pest management protocols.
Product Type:
Domestic fermentation capacity concentrates in microbial pesticides, while biochemical alternatives rely more heavily on imported botanical extracts and semiochemicals.
- Microbial Pesticides:Living organisms including Bacillus thuringiensis and Trichoderma species formulated as wettable powders or liquid concentrates. Norfolk and Suffolk vegetable operations deploy these rotations extensively in protected salad crop systems to manage resistance pressure under the Farming Rules for Water.
- Biochemical Pesticides:Naturally occurring substances such as botanical extracts, semiochemicals, and plant growth regulators. Kent apple orchards and Herefordshire strawberry producers absorb premium-priced mating disruption pheromones and RNA interference formulations for codling moth and spotted wing drosophila control.
- Plant-Incorporated Protectants:Genetically modified crops producing pesticidal proteins. UK regulatory timelines under the Health and Safety Executive constrain commercial availability, limiting this segment to research trial plots pending GMO approval divergence from EFSA frameworks.
- Others:Mineral oils, soaps, and other non-living physical control agents. Lincolnshire producer organizations source these for organic certification compliance in field vegetable rotations.
Microbial pesticides hold the largest share; momentum sits with biochemical pesticides.
Application:
Cost tier stratification separates intensive horticulture investment from broadacre cereal constraints, with premium pricing concentrated in protected cropping systems.
- Agriculture:Arable cereal and oilseed rape operations. West Midlands catchment-sensitive farming areas substitute microbial fungicides for synthetic azole programs to comply with buffer-zone restrictions under the Farming Rules for Water.
- Horticulture:High-value protected and field-grown vegetables, fruits, and ornamentals. East Anglia's intensive belt drives volume concentration, with glasshouse tomato and pepper producers layering multiple microbial modes of action into resistance management protocols.
- Turf:Golf courses, sports pitches, and amenity grasslands. Sports turf managers in southeast England deploy entomopathogenic nematodes for chafer grub control, constrained by summer temperature sensitivity during distribution.
- Forestry:Woodland and plantation pest suppression. Defra's Environmental Land Management schemes expand addressable acreage into agroforestry and pollinator corridor management applications.
Horticulture commands premium pricing tiers; forestry applications are climbing the fastest as habitat restoration incentives mature.
End User:
Customer type determines technical support intensity and formulation packaging requirements, from bulk concentrate procurement to ready-to-use retail formats.
- Farmers:Commercial arable and horticultural operators. Cooperative purchasing groups in Cambridgeshire negotiate direct fermentation facility contracts, displacing traditional agronomy merchant intermediaries.
- Crop Protection Companies:Formulators and distributors blending active substances into finished products. These entities require strain library access and three-year UK climatic efficacy datasets to satisfy Health and Safety Executive registration requirements.
- Research Institutions:Universities and agricultural research centers conducting field trials. Rothamsted Research and similar bodies validate biocontrol efficacy under UK-specific climatic variability, generating data for regulatory submissions.
- Organic Growers:Certified organic operators with zero synthetic chemistry tolerance. Soil Association certification requirements drive strict procurement protocols for residue compliance and input approval lists.
Farmers represent the dominant volume segment; research institutions are gaining share fastest as strain library investments accelerate.
Distribution Channel:
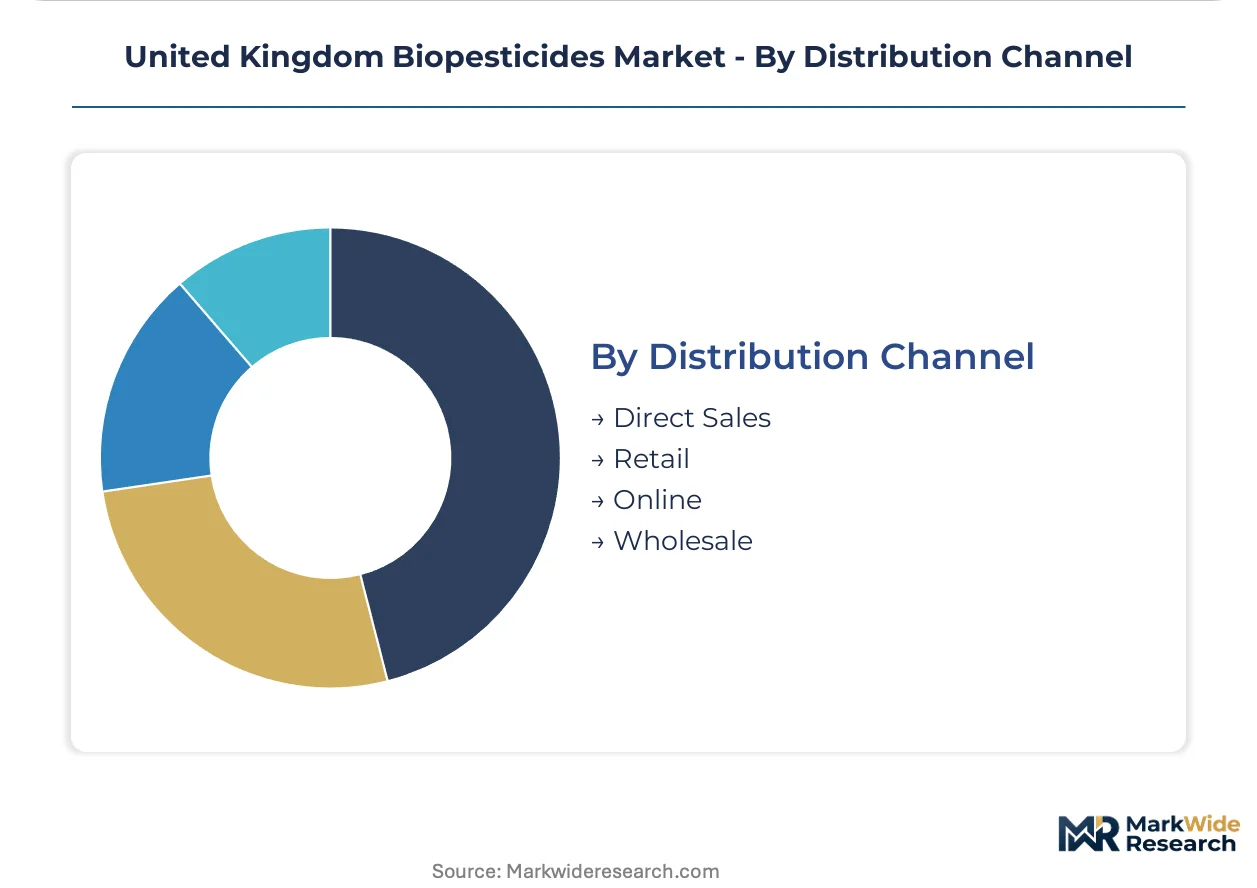
Supply concentration in direct sales and wholesale channels reflects the technical complexity of microbial product handling, while digital platforms fragment traditional merchant structures.
- Direct Sales:Manufacturer-to-grower relationships bypassing intermediaries. Agronomy service platforms enable microbial concentrate subscription models for precision dosing in glasshouse operations.
- Retail:Garden centers and farm supply stores serving small-scale and amateur growers. Limited shelf-life and temperature sensitivity constrain product range depth in this channel.
- Online:E-commerce platforms and direct-to-grower digital channels. These routes expand reach to remote Scottish and Welsh operations outside traditional distribution networks.
- Wholesale:Bulk supply to agronomy merchants and cooperative purchasing groups. Lincolnshire and Cambridgeshire producer organizations leverage this channel for volume concentration and margin compression.
Direct sales dominate value capture; online channels are expanding most quickly as digital agronomy platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UK biopesticide exports flow primarily toward Irish horticulture operations and Dutch distribution hubs serving continental European protected cropping systems. Domestic demand concentrates in England's intensive vegetable belts where regulatory pressure on synthetic chemistry accelerates biological substitution.
East Anglia
Norfolk and Suffolk glasshouse operations deploy Bacillus thuringiensis rotations for resistance management in protected salad crops. The Farming Rules for Water restrict synthetic azole runoff into the Broads protected water bodies. Norwich-based producer organizations negotiate direct fermentation contracts with microbial manufacturers.
West Midlands
Catchment-sensitive farming areas substitute microbial fungicides for synthetic chemistry to comply with buffer-zone restrictions near the Severn and Avon river systems. Defra's Sustainable Farming Incentive redirects subsidy flows toward integrated pest management protocols. Worcestershire potato growers pilot entomopathogenic nematode applications for wireworm suppression.
Kent and Southeast
Apple orchard operators in the Garden of England absorb premium-priced mating disruption pheromones for codling moth control. The Health and Safety Executive enforces retained EU Regulation 1107/2009 for pesticide authorization. Canterbury-area strawberry producers trial RNA interference formulations against spotted wing drosophila.
Scotland
Soft fruit operations in Perthshire and Angus deploy microbial biocontrols to meet Soil Association organic certification requirements. The Scottish Government's Agriculture Reform Programme redirects support toward environmental land management. Dundee-area research institutions validate strain efficacy under cooler climatic conditions.
United Kingdom Biopesticides Market Competitive Landscape
Player mix skews toward multinational agrochemical conglomerates with microbial strain libraries and domestic biological specialists with regional fermentation capacity. BASF SE and Bayer AG anchor the consolidated tier through retained EU regulatory dossiers and established field trial networks. Three archetypes dominate: global conglomerates leveraging chemical-biological portfolios, mid-scale specialists with UK-specific strain adaptations, and cooperative purchasing groups displacing traditional distribution. Competitive moves center on direct-to-grower digital platform development and three-year climatic efficacy dataset generation for Health and Safety Executive registrations.
Among Germany-based conglomerates, BASF SE and Bayer AG occupy positions as archetype anchors for multinational biological-chemical integration. Syngenta UK Limited exemplifies the regional subsidiary model with distribution partnerships across major agronomy service providers. Domestic specialist Bionema Limited represents the mid-scale fermentation-focused tier with UK-specific strain development capabilities.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta UK Limited |
| Bionema Limited |
| Koppert Biological Systems |
| FMC Corporation |
| UPL |
| Environmental Crop Management Limited |
| Novonesis |
| Others |
Value Network & Pricing Analysis
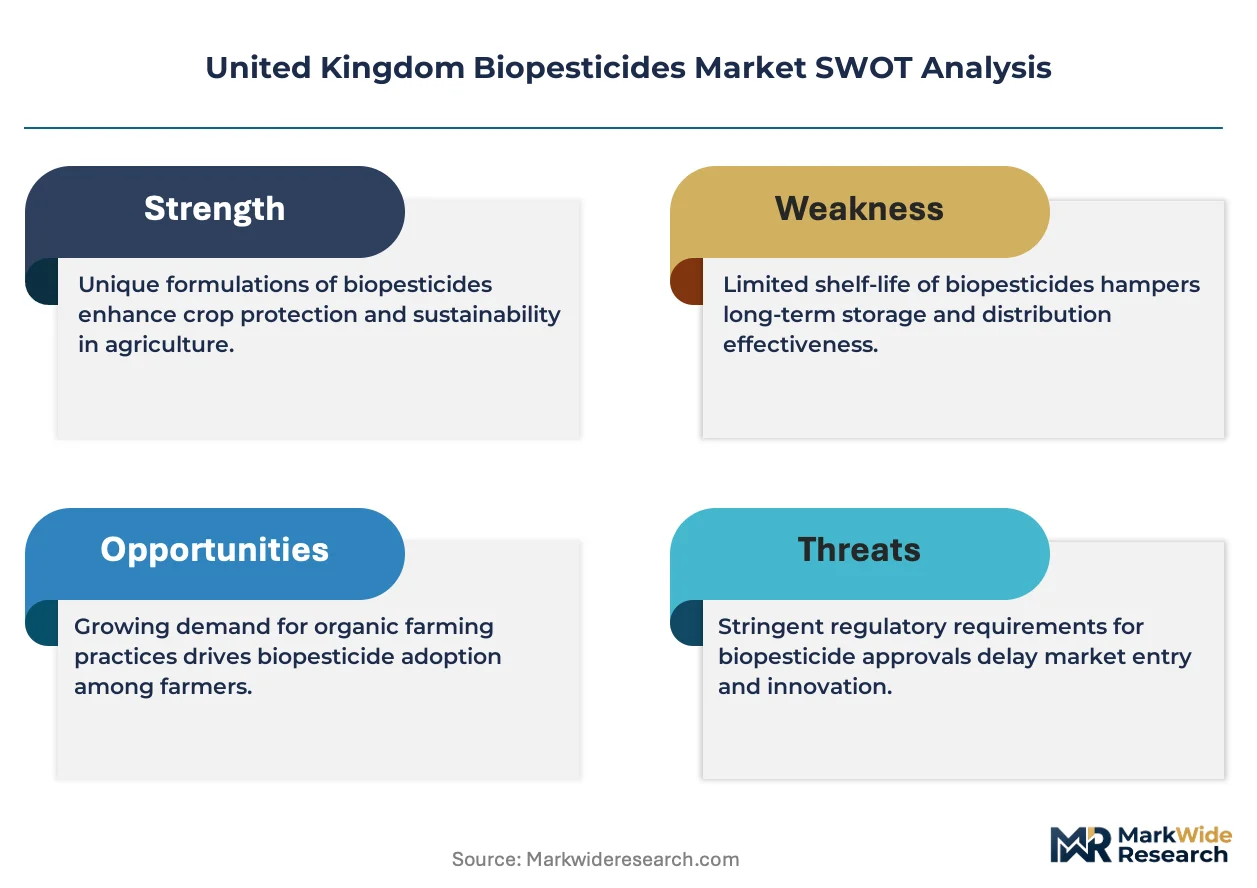
The Health and Safety Executive's retained EU Regulation 1107/2009 authorization framework gates both supplier qualification and price differentiation simultaneously, as microbial product registration dossiers require three-year UK climatic efficacy datasets that only established fermentation facilities can generate. This regulatory barrier segments the market between premium-priced registered biocontrols and unregistered commodity alternatives.
Pricing Analysis
Next-generation RNA interference formulations command substantial premiums over established Bacillus thuringiensis and Trichoderma-based products, while prior-generation mineral oils and soaps occupy economy tiers. Pricing stratifies across premium biochemical pesticides, standard microbial concentrates, and economy physical control agents, with certification grade under Soil Association standards and volume scale through cooperative purchasing groups driving differentiation. Cost compression in standard microbial tiers is intensifying as Lincolnshire producer organizations negotiate direct fermentation facility contracts. Specialty vegetable growers in East Anglia's protected cropping systems show least price sensitivity, while broadacre cereal operators in the West Midlands resist biological substitution against cheaper synthetic pyrethroids.
Supply Chain Analysis
Container availability constraints on inbound botanical extract shipments from India and semiochemical feedstocks from the Netherlands elevate working capital requirements for biochemical pesticide formulators. Domestic UK fermentation capacity for microbial active substances draws from proprietary strain libraries and molasses-based growth media, while critical adjuvant chemistry sources from Germany and specialty packaging materials from China. Single-source vulnerability concentrates in entomopathogenic nematode production, where limited domestic multiplication facilities create chokepoints. Distribution runs through agronomy service platforms and cooperative purchasing groups that displace traditional merchant intermediaries in Cambridgeshire and Lincolnshire.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom biopesticides market represents high-growth disruption as RNA interference technology fragments conventional insecticide categories and the Sustainable Farming Incentive redirects subsidy flows toward integrated pest management protocols.
For Market Incumbents: Compound defensive positioning by deepening strain library investments for Health and Safety Executive registration dossiers and acquiring UK-specific fermentation capacity to block mid-scale specialist expansion. Synthetic chemistry substitution in broadacre cereals and emerging RNA interference entrants threaten established microbial margins, making captive supply of entomopathogenic fungi a critical lever. For New Entrants and Emerging Players: Differentiate on climate-adapted strain development by targeting Scottish soft fruit operations and West Midlands catchment-sensitive farming areas where regulatory pressure exceeds incumbent coverage. Agroforestry applications under Environmental Land Management schemes offer the most penetrable white space, with direct-to-grower digital subscription models enabling precision dosing without distribution infrastructure. For Investors and Strategic Acquirers: The Health and Safety Executive's divergence from EFSA assessment timelines reshapes the acquisition landscape toward domestic registration capability rather than EU dossier portability. Five-to-ten year viability hinges on strain library depth and climatic validation infrastructure, making mid-scale UK fermentation specialists with existing registration pipelines the priority acquisition archetype. Watch for Defra's Environmental Land Management scheme rollout velocity as the inflection signal indicating addressable acreage expansion beyond conventional horticulture.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Expansion | Deepens proprietary microbial catalogs for Health and Safety Executive registration dossiers. |
| Direct-to-Grower Platform Launch | Enables subscription-based microbial concentrate delivery for precision glasshouse dosing. |
| Climate Validation Partnership | Secures three-year UK efficacy datasets through Rothamsted Research field trial networks. |
| Cooperative Supply Agreement | Locks volume commitments from Lincolnshire and Cambridgeshire producer organizations. |
| RNA Interference Pipeline Entry | Positions for codling moth and spotted wing drosophila control in Kent and Herefordshire. |
Research Methodology
The analysis maps microbial pesticide, biochemical pesticide, and plant-incorporated protectant sub-sectors, each validated through fermentation facility technical directors, agronomy service procurement leads, and Soil Association certification officers. Primary interviews with crop protection company formulators and East Anglia vegetable grower cooperative representatives combined with secondary validation against Health and Safety Executive authorization databases, Defra subsidy scheme documentation, and retained EU Regulation 1107/2009 regulatory filings. Bottom-up strain library capacity assessments and top-down subsidy flow modeling enabled triangulation across supply-side and demand-side estimates.
Consistency checks validated volume and value outputs against UK bioprocessing capacity disclosures, microbial product import trade data, and Sustainable Farming Incentive enrollment statistics across the projection horizon. The analytical framework modeled product type, application, end user, and distribution channel segmentation, with CAGRs derived from regulatory timeline probability weighting and subsidy scheme maturity curves. Climatic variability effects on field trial timelines and divergence risk between UK and EU maximum residue limit harmonization served as key forecast inputs.
Material uncertainties — Health and Safety Executive assessment pace, Environmental Land Management scheme acreage allocation, and summer temperature excursion frequency affecting viable cell counts — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory divergence trajectory and subsidy scheme continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
US Bio Pesticides Market
Bio-Agriculture
United States Bio-Fungicide Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Hydroponics Nutrients Market
Bio-Agriculture
Bloodroot Market
Bio-Agriculture
Asia-Pacific Biofertilizers Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
France Biopesticides Market
Bio-Agriculture
Poultry Manure Biofertilizers Market
Bio-Agriculture
Hybrid Seeds Market
Bio-Agriculture
Vietnam Biopesticides Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
Latin America Biostimulants Market