
 Asia-Pacific Biofertilizers Market | 2026-2036
Asia-Pacific Biofertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Biofertilizers Market Outlook
Microbial count specifications above 10^8 CFU per gram is redrawing procurement criteria across the Asia-Pacific biofertilizers landscape. Novozymes A/S leverages its enzyme fermentation expertise to anchor premium strain development for tropical soil conditions. Gujarat State Fertilizers & Chemicals Ltd sustains one of the region's largest azotobacter production facilities, while Kiwa Bio-Tech specializes in bacillus-based formulations for high-salinity farmlands in coastal China.
Asia-Pacific biofertilizers are living microbial inoculants—typically containing nitrogen-fixing bacteria, phosphate-solubilizing fungi, or plant growth-promoting rhizobacteria cultured on organic carriers such as lignite or peat—that restore soil microbiome function and reduce synthetic nitrogen dependency in intensive cropping systems. Liquid biofertilizers command expanding shelf space due to superior cell viability during monsoon season distribution, whereas granular formulations retain stronger penetration among smallholder cooperatives with limited spray equipment. The agriculture end-use segment dominates volume flows, though horticulture applications in protected cultivation are generating disproportionate margin pools for producers with greenhouse-specific formulations.
India's FSSAI and BIS standards for organic input certification are tightening contaminant thresholds and reshaping formulation chemistry across domestic manufacturing bases. China's MEE enforcement of dual carbon goals is redirecting provincial fertilizer subsidies toward microbial alternatives in the Yangtze River basin. Stakeholders must track how Australia's TGA-equivalent organic regulator harmonizes strain registration protocols with ASEAN mutual recognition frameworks, as this alignment will determine which producers gain cross-border formulation approval without redundant field trials.
Market Dynamics
Urea subsidy reduction across India's Indo-Gangetic Plain is forcing rice cultivators toward microbial nitrogen-fixing inoculants, while China's MEE enforcement of dual carbon goals redirects provincial fertilizer procurement toward certified bio-inputs.
Growth Catalysts
- India's PLI scheme for agri-input manufacturing:Domestic microbial strain production capacity is accelerating as capital subsidies flow toward fermentation infrastructure.
- Intensive shrimp-rice rotation systems:Vietnam's Mekong Delta demands nitrogen-fixing inoculants to manage salinity stress and synthetic input restrictions.
- Microbial count specifications above 10^8 CFU per gram:Procurement criteria are tightening across state agricultural departments, favoring producers with advanced quality control.
Market Restraints
- Input cost volatility:Lignite and peat carrier materials face price swings as energy markets fluctuate, squeezing formulation margins.
- Technical shelf-life limitation:Liquid biofertilizers require cold chain distribution that monsoon season infrastructure cannot reliably support.
- Regulatory friction from India's FSSAI:Contaminant threshold tightening forces reformulation cycles that delay product registration.
Strategic Opportunities
- Underpenetrated horticulture in protected cultivation:Greenhouse-specific bacillus formulations command premium pricing in coastal China's high-salinity zones.
- Technology convergence of enzyme fermentation and strain development:Tropical soil adaptation capabilities separate premium producers from commodity suppliers.
- Australia's TGA-equivalent organic regulator:Harmonization with ASEAN mutual recognition frameworks will unlock cross-border formulation approval without redundant field trials.
Industry Challenges
- Certification timeline compression:India's BIS standards for organic input certification demand extended field validation periods that strain working capital.
- Integration complexity with legacy urea distribution:State fertilizer cooperatives lack microbial product handling protocols, creating channel friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Biofertilizers Market |
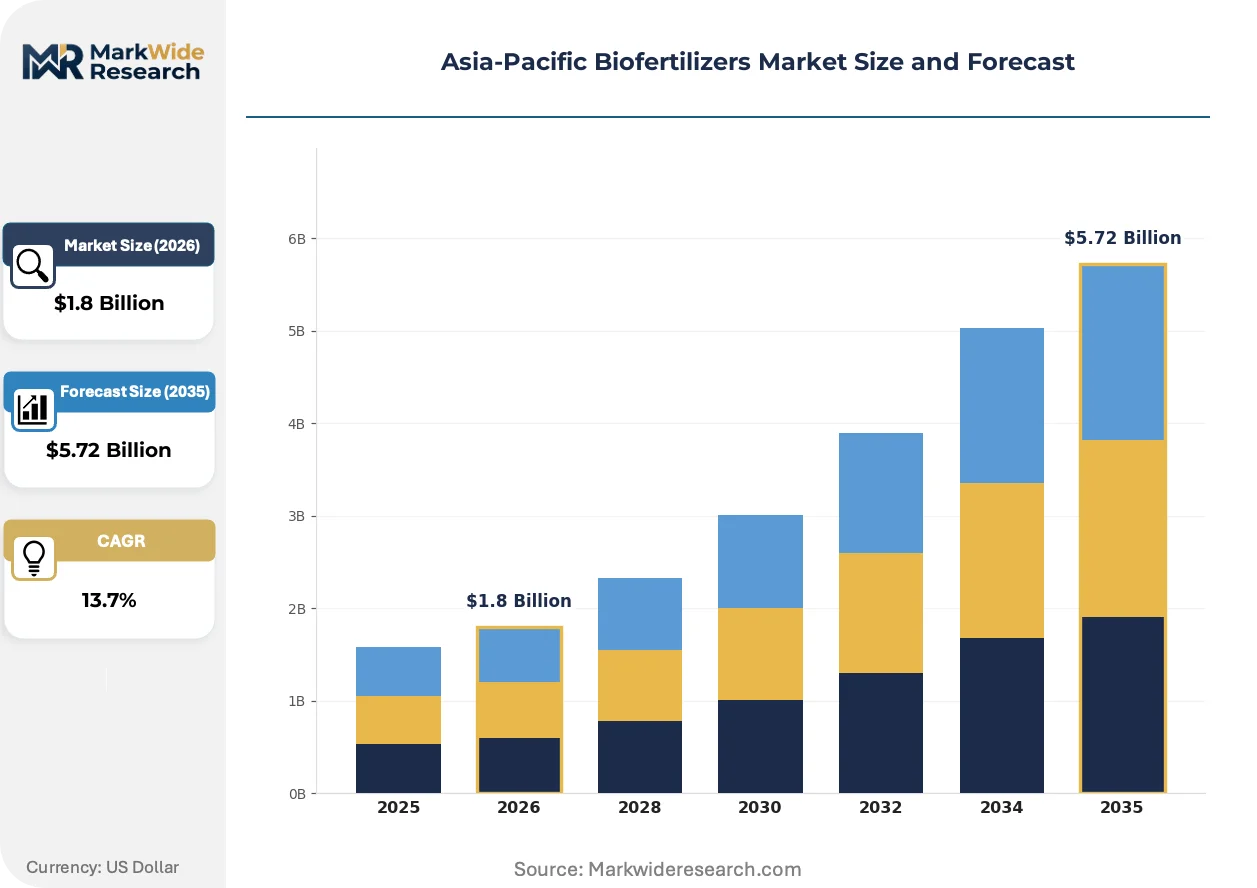
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Biofertilizers, Granular Biofertilizers, Bioorganic Fertilizers, Microbial Fertilizers End Use Industry: Agriculture, Horticulture, Landscaping, Forestry Form: Powder, Liquid, Granule, Pellet Distribution Channel: Online Retail, Agricultural Cooperatives, Direct Sales, Wholesale |
| Companies Covered | Biostadt India Limited, Gujarat State Fertilizers & Chemicals Ltd, Indian Farmers Fertiliser Cooperative Limited, Kiwa Bio-Tech, The Fertilizers and Chemicals Travancore Limited, Camson Bio Technologies Limited, Lallemand Inc., Novozymes A/S, AgriLife, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Biofertilizers Market Strategic Shifts
Formulation chemistry is pivoting toward liquid carriers with superior cell viability, while regulatory alignment across ASEAN is reshaping cross-border approval pathways for microbial strain registrations.
Encapsulated nitrogen-fixing bacteria in polymer matrices is decomposing the traditional lignite-carrier supply chain. Rice cooperatives in Vietnam's Mekong Delta are adopting these formulations at twice the rate of conventional granular products. The technology is decomposing procurement relationships with legacy peat suppliers and compressing distribution margins for undifferentiated carriers.
China's MEE enforcement of dual carbon goals is redirecting provincial fertilizer subsidies toward microbial alternatives in the Yangtze River basin. Industrial consequence includes mandatory carbon intensity disclosures for synthetic nitrogen producers. Granular biofertilizer manufacturers with ISO-certified fermentation facilities are capturing these redirected procurement flows.
Buyer concentration among state agricultural departments is consolidating supplier qualification criteria around microbial count specifications and shelf-life guarantees. Smallholder cooperatives with limited spray equipment remain anchored to granular formats, while larger commercial farms negotiate direct liquid formulation contracts. This bifurcation is most visible in India's Gujarat and Maharashtra state procurement systems.
Asia-Pacific Biofertilizers Market Segmentation
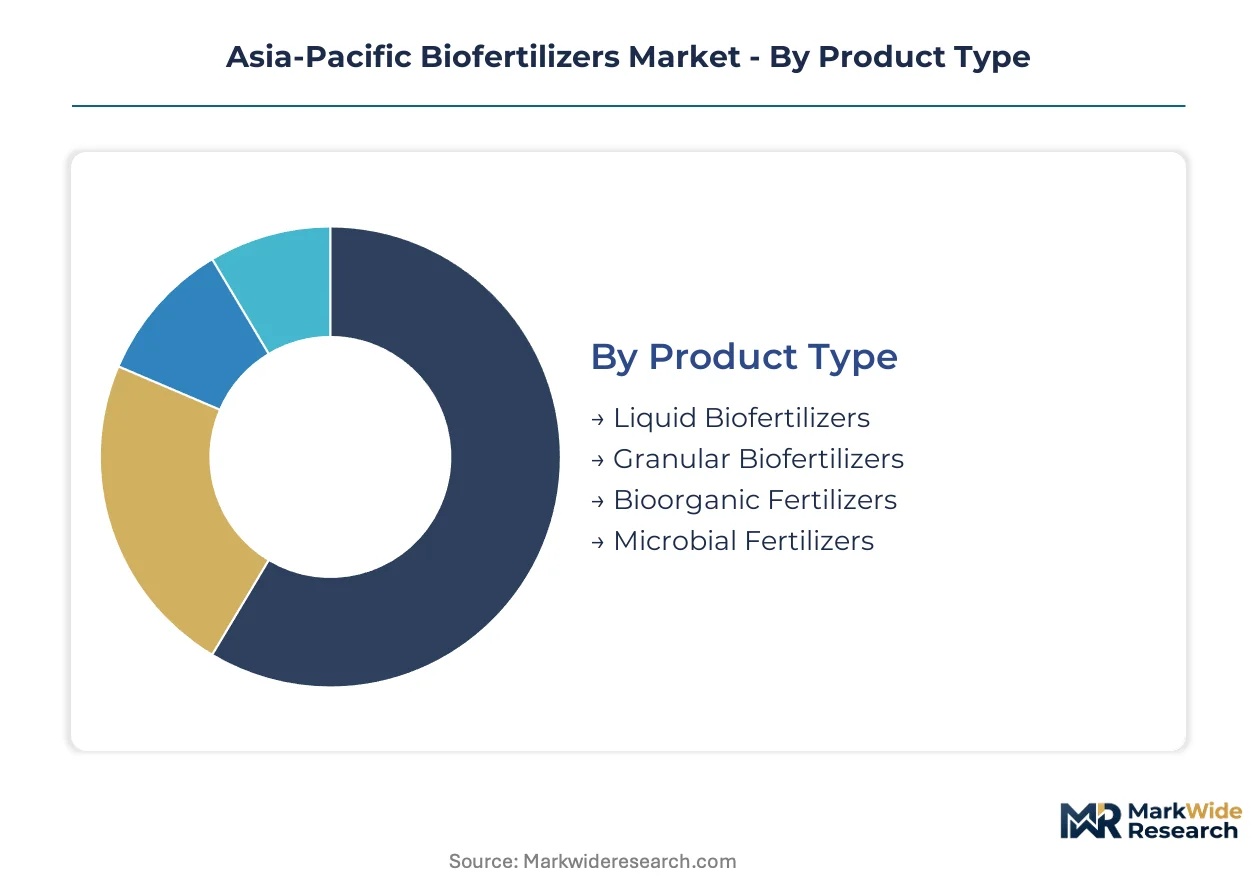
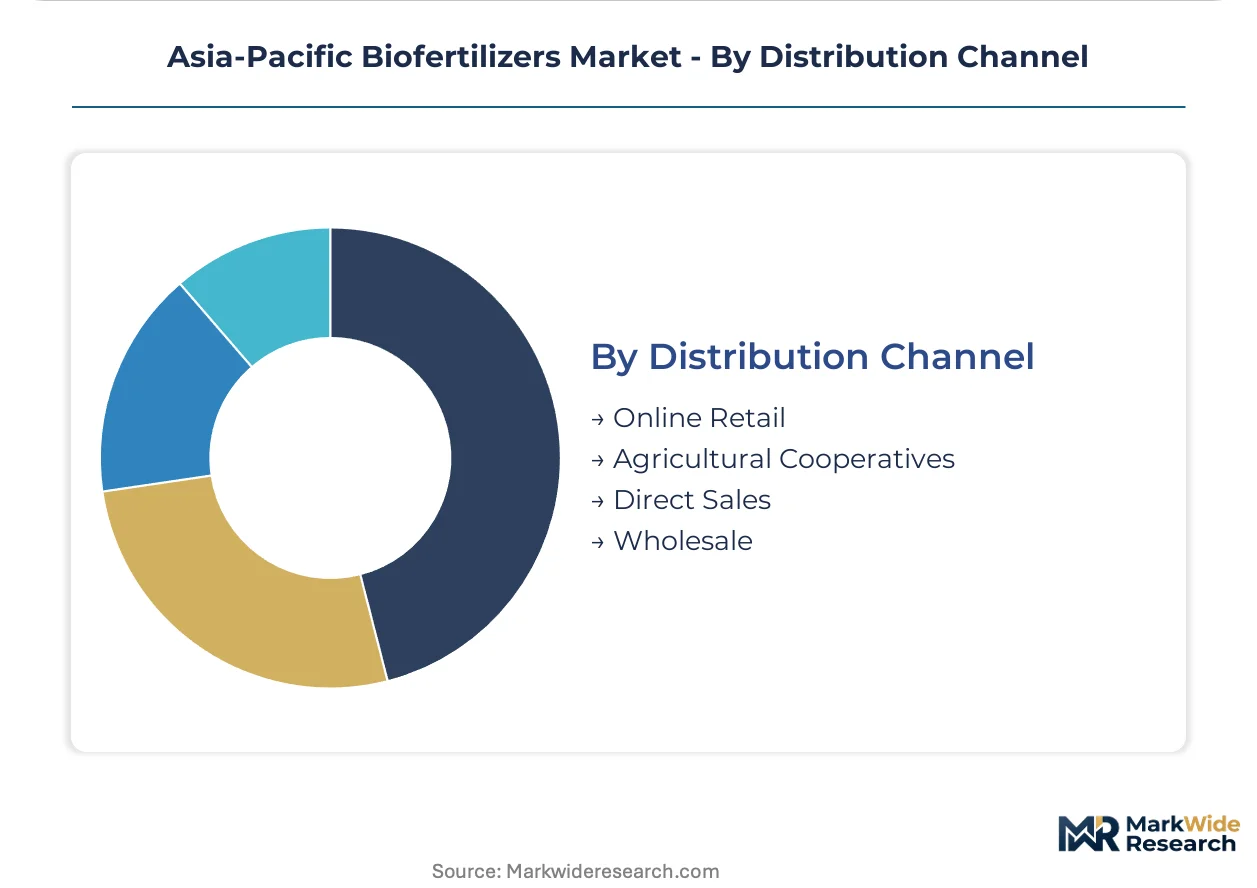
Asia-Pacific biofertilizer procurement flows through sharply divergent channels depending on formulation type and farm scale. Channel-mix patterns reveal where margin pools concentrate versus where volume scales.
Product Type:
Liquid formulations dominate commercial farm direct contracts, while granular products anchor cooperative procurement systems across state fertilizer distribution networks.
- Liquid Biofertilizers:Cell suspensions in aqueous carriers maintain viability above 10^8 CFU per milliliter through monsoon season distribution. Vietnam's Mekong Delta shrimp-rice rotations absorb the bulk of regional liquid volumes due to injection compatibility with existing irrigation infrastructure.
- Granular Biofertilizers:Microbial inoculants adsorbed onto lignite or peat carriers suit smallholder cooperatives lacking spray equipment. India's Gujarat State Fertilizers & Chemicals Ltd channels these through state agricultural department tenders in Gujarat and Maharashtra.
- Bioorganic Fertilizers:Combined organic matter and microbial formulations serve India's organic certification transition zones under FSSAI tightening standards.
- Microbial Fertilizers:Pure culture preparations with defined strain specifications command premium positioning in China's Yangtze River basin carbon-reduction procurement zones.
By volume, Granular Biofertilizers leads. By growth pace, Liquid Biofertilizers is climbing the fastest.
End Use Industry:
Margin concentration varies dramatically across end-use applications, with protected cultivation commanding pricing multiples over open-field commodity crops.
- Agriculture:Rice cultivation across India's Indo-Gangetic Plain generates baseline demand volumes as urea subsidy reductions accelerate microbial nitrogen fixation adoption.
- Horticulture:Protected cultivation in coastal China's high-salinity zones absorbs bacillus-based formulations at premium pricing tiers unavailable to open-field grain producers.
- Landscaping:Municipal greening contracts in Australia's urban centers specify certified organic inputs under TGA-equivalent organic regulator frameworks.
- Forestry:Plantation reforestation programs in Indonesia and Malaysia apply phosphate-solubilizing inoculants to accelerate establishment on degraded soils.
Agriculture captures absolute volume leadership. Horticulture delivers the steepest margin expansion trajectory.
Form:
Physical form determines cold-chain requirements, shelf-life guarantees, and the technical service intensity each customer segment demands.
- Powder:Lyophilized cultures with extended ambient stability suit remote distribution to Indonesia's outer island smallholders beyond reliable cold-chain reach.
- Liquid:Requires refrigerated transport and shorter inventory cycles, limiting penetration to peri-urban commercial farming zones with reliable logistics.
- Granule:Lignite-based carriers integrate seamlessly with existing urea spreading equipment across India's state fertilizer cooperative networks.
- Pellet:Compressed formulations with polymer coatings enable precision placement in Vietnam's intensive shrimp-rice rotation systems.
Granule form dominates current procurement volumes. Pellet form is gaining share fastest among precision agriculture adopters.
Distribution Channel:
Channel structure reflects the legacy synthetic fertilizer infrastructure that biofertilizer producers must either leverage or circumvent.
- Online Retail:E-commerce platforms serve hobby farmers and urban gardeners with small-pack liquid formulations, though logistics constraints limit viable service areas.
- Agricultural Cooperatives:India's state-level fertilizer cooperatives move granular products at volume but lack microbial handling protocols, creating technical service gaps.
- Direct Sales:Large commercial farms in Thailand and Vietnam negotiate liquid formulation contracts directly with fermentation facilities, bypassing distribution markups.
- Wholesale:Regional distributors aggregate fragmented smallholder demand across Indonesia's archipelago, absorbing inventory risk in exchange for margin.
Agricultural Cooperatives channel the highest absolute volumes. Direct Sales is expanding most quickly among commercial farm consolidation zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for microbial strains tilts the Asia-Pacific biofertilizers trade balance toward fermentation technology exporters. Domestic capacity expansion across India and China is compressing cross-border formulation flows while elevating regional carrier material trade.
India
Urea subsidy reduction across the Indo-Gangetic Plain accelerates nitrogen-fixing inoculant procurement by rice cultivators. India's PLI scheme for agri-input manufacturing channels capital subsidies toward domestic microbial strain production. Gujarat State Fertilizers & Chemicals Ltd anchors azotobacter production capacity in Gujarat and Maharashtra state procurement networks.
China
Intensive shrimp-rice rotation systems in coastal provinces absorb bacillus-based formulations for salinity stress management. China's MEE enforcement of dual carbon goals redirects provincial fertilizer subsidies toward microbial alternatives in the Yangtze River basin. Kiwa Bio-Tech positions formulation supply for high-salinity farmlands across coastal China clusters.
Vietnam
The Mekong Delta demands nitrogen-fixing inoculants compatible with existing irrigation injection infrastructure. Vietnam's state agricultural departments tighten microbial count specifications above 10^8 CFU per gram in procurement tenders. Pellet formulations with polymer coatings gain share fastest among precision agriculture adopters in intensive rotation zones.
Australia
Municipal greening contracts in urban centers specify certified organic inputs under TGA-equivalent organic regulator frameworks. Australia's organic certification harmonization negotiations with ASEAN mutual recognition frameworks determine cross-border formulation approval pathways. Fermentation facilities serving protected cultivation horticulture command premium positioning unavailable to open-field suppliers.
Indonesia
Plantation reforestation programs in outer islands apply phosphate-solubilizing inoculants to degraded soils beyond reliable cold-chain reach. Lyophilized powder formulations with extended ambient stability suit remote distribution logistics. Regional distributors aggregate fragmented smallholder demand across the archipelago, absorbing inventory risk in exchange for margin.
Asia-Pacific Biofertilizers Market Competitive Environment
Concentration sits with state-affiliated fertilizer cooperatives and enzyme fermentation specialists that control strain development pipelines. The vendor base spans three tiers: integrated agri-input conglomerates with captive distribution, specialized microbial technology firms with tropical soil adaptation capabilities, and regional formulation packagers dependent on third-party strain supply. Consolidation pressure intensifies as procurement criteria tighten around microbial count specifications and shelf-life guarantees. Strategic moves center on backward integration into fermentation infrastructure and geographic expansion through ASEAN mutual recognition framework alignment.
Among India-based integrated producers, Biostadt India Limited, Gujarat State Fertilizers & Chemicals Ltd, and Indian Farmers Fertiliser Cooperative Limited exemplify the state-linked cooperative archetype that dominates granular biofertilizer procurement through government tender systems. Novozymes A/S represents the enzyme fermentation specialist tier, leveraging bioprocessing expertise to anchor premium strain development for tropical conditions. Kiwa Bio-Tech occupies a position within the specialized microbial technology segment, with formulation positioning for high-salinity agricultural zones. Lallemand Inc. and AgriLife exemplify the diversified microbial technology providers competing on strain specificity and application protocol development.
| Leading Market Players |
|---|
| Biostadt India Limited |
| Gujarat State Fertilizers & Chemicals Ltd |
| Indian Farmers Fertiliser Cooperative Limited |
| Kiwa Bio-Tech |
| The Fertilizers and Chemicals Travancore Limited |
| Camson Bio Technologies Limited |
| Lallemand Inc. |
| Novozymes A/S |
| AgriLife |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between India's state agricultural departments and domestic fermentation facilities lock in both supply access and price visibility for azotobacter and bacillus formulations, insulating procurement from lignite carrier cost swings while compressing margins for spot-market suppliers.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the Asia-Pacific biofertilizers landscape. Premium tiers attach to liquid formulations with ISO-certified microbial counts above 10^8 CFU per gram and cold-chain guarantees, while economy tiers cover granular lignite-carrier products through state cooperative tenders. Pricing pressure stems from India's PLI scheme accelerating domestic strain production capacity and diluting import-dependent premium positioning. Smallholder cooperatives exhibit highest price sensitivity due to working capital constraints, whereas protected cultivation horticulture buyers in coastal China absorb premium tiers with limited negotiation leverage.
Supply Chain Analysis
Inventory cycles for liquid biofertilizers compress to monsoon-season windows, forcing fermentation facilities to synchronize batch releases with distribution infrastructure reliability. Raw material dependencies center on lignite and peat carrier substrates from Indonesia and Australia, plus defined microbial strain libraries from Denmark and the Netherlands. Single-source vulnerability concentrates in tropical-adapted strain development pipelines controlled by enzyme fermentation specialists. Distribution runs through India's state fertilizer cooperative networks for granular products, while direct sales channels serve Vietnam's Mekong Delta commercial farms with liquid formulation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation infrastructure capable of tropical strain adaptation sits in limited supply across the Asia-Pacific region, creating acquisition scarcity for producers seeking backward integration into microbial culture production.
For Market Incumbents: Compound fermentation capacity advantages by securing captive lignite supply agreements in Indonesia before carrier material cost volatility escalates. Invest in BIS certification compliance ahead of India's FSSAI threshold tightening to capture state tender volumes that reformulation-lagged competitors forfeit. For New Entrants and Emerging Players: Differentiate on polymer-encapsulated pellet formulations for Vietnam's precision irrigation infrastructure, a segment where established granular suppliers lack technical service depth. Target Australia's TGA-equivalent organic regulator harmonization process as a regulatory arbitrage entry point before ASEAN mutual recognition frameworks consolidate. For Investors and Strategic Acquirers: Specialized microbial technology firms with tropical soil adaptation capabilities and existing strain registration in multiple Asia-Pacific jurisdictions represent the highest-conviction acquisition archetype. Watch India's PLI scheme capital subsidy disbursement velocity as the inflection signal for domestic production capacity overshoot versus sustained supply scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Infrastructure | Captures margin pools currently extracted by Danish and Dutch strain suppliers. |
| Polymer Encapsulation Technology Licensing | Enables pellet formulation entry into Vietnam's precision agriculture zones. |
| BIS Certification Pre-Investment | Positions suppliers ahead of India's FSSAI contaminant threshold enforcement. |
| ASEAN Mutual Recognition Alignment | Unlocked cross-border strain approval without redundant field trials in Australia. |
| Long-Term Lignite Supply Agreement | Hedges carrier material cost volatility from Indonesian energy market fluctuations. |
Study Parameters
A spread of perspectives from fermentation facility operations directors, state agricultural department procurement officers, microbial strain R&D leads, and cooperative distribution managers converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from India's BIS certification records, China's MEE subsidy redirection disclosures, Vietnam's state tender documentation, and customs trade data for lignite carrier flows. Bottom-up strain production capacity estimates triangulated against top-down fertilizer procurement budget allocations across the analysis window.
Segmentation dimensions modeled include formulation type, physical form, end-use application intensity, and farm scale tier throughout the forecast period. CAGRs derived from trend extrapolation of microbial count specification tightening and urea subsidy reduction trajectories, cross-referenced with PLI scheme capacity buildout schedules and MEE carbon-reduction procurement redirection patterns. Industry-specific inputs incorporated monsoon season distribution viability constraints and cold-chain infrastructure penetration differentials by geography.
Forecasts assume regulatory continuity in India's FSSAI and BIS regimes, China's MEE dual carbon enforcement, and Australia's TGA-equivalent organic certification framework; material policy shifts would require re-modeling strain registration timelines and subsidy flow distributions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Middle East and Africa Biofertilizers Market
Bio-Agriculture
North America Biostimulants Market
Bio-Agriculture
China Biofuels Market
Bio-Agriculture
United Kingdom Biopesticides Market
Bio-Agriculture
Bionematicides Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
China Feed Probiotics Market
Bio-Agriculture
Asia-Pacific Agricultural Biologicals Market
Bio-Agriculture
North America Biopesticides Market
Bio-Agriculture
Plant-Based Biologics Market
Bio-Agriculture
South America Biopesticides Market
Bio-Agriculture
Biological Control Market
Bio-Agriculture
Africa Biofertilizer Market
Bio-Agriculture
Brazil Biocontrol Agents Market
Bio-Agriculture
Lignocellulosic Biomass Market
Bio-Agriculture
Agriculture Biologicals Testing Market