
 Asia-Pacific Biopesticides Market | 2026-2036
Asia-Pacific Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Biopesticides Market Outlook
Specialty crop exporters and organic-certified farming cooperatives is reorganizing procurement priorities across the Asia-Pacific biopesticides supply base. Bayer AG leverages its microbial strain library to sustain technical leadership in bacterial biopesticide formulations. Koppert anchors biological control distribution networks across Southeast Asian horticulture corridors. Gujarat State Fertilizers & Chemicals Ltd dominates domestic manufacturing scale for fermentation-derived biocontrol agents serving Indian agricultural cooperatives.
Asia-Pacific biopesticides comprise living organisms or naturally derived metabolites formulated to suppress agricultural pests through ecological mechanisms rather than chemical toxicity. These products typically utilize bacterial endospores, fungal conidia, or viral occlusion bodies at concentrations ranging from 10^8 to 10^11 colony-forming units per gram, applied via foliar spray or soil drench to achieve pest mortality through infection, antibiosis, or competition. Bacterial biopesticides occupy the largest current revenue position given established efficacy against lepidopteran larvae and compatibility with conventional spray equipment. Fungal biopesticides represent the fastest-expanding category as trichoderma-based soil treatments gain traction in protected cultivation systems across China and Vietnam. Plant-made biopesticides command premium positioning where botanical extract standardization meets export market residue protocols.
India's Central Insecticides Board and China's Ministry of Agriculture and Rural Affairs regulate biopesticide registration through distinct efficacy and toxicology requirements that shape product development pipelines and market access timelines. The FAO/WHO Joint Meeting on Pesticide Residues provides harmonized maximum residue limits that enable cross-border trade in biocontrol-treated produce, directly influencing formulation choices by exporters targeting European retail channels. Stakeholders must monitor regulatory divergence between national biologicals registration pathways and emerging carbon-accounting frameworks that could revalue microbial biocontrol within scope-three emissions reporting.
Market Dynamics
India's PLI scheme for agrochemical innovation and China's dual carbon goals are accelerating domestic fermentation capacity for biocontrol strains, reshaping supply-side investment patterns across the Asia-Pacific biopesticides landscape.
Growth Catalysts
- Export residue protocols:European retail channel maximum residue limits under FAO/WHO Joint Meeting on Pesticide Residues are compelling Southeast Asian specialty crop exporters to substitute chemical pesticides with microbial biocontrol agents.
- Integrated pest management adoption:Maharashtra and Gujarat horticulture cooperatives are embedding bacterial biopesticides into spray programs for lepidopteran larvae control.
- Fermentation infrastructure expansion:China's Ministry of Agriculture and Rural Affairs registration pathways are incentivizing domestic production of trichoderma-based soil treatments for protected cultivation.
Market Restraints
- Input cost volatility:Molasses and soybean meal prices for bacterial endospore fermentation fluctuate with commodity cycles, compressing margins for domestic Indian manufacturers.
- Regulatory friction:Divergent efficacy requirements between India's Central Insecticides Board and China's Ministry of Agriculture and Rural Affairs extend product development timelines by 18-24 months for cross-border formulations.
- Technical shelf-life limitations:Fungal conidia viability in tropical storage conditions degrades below 10^8 colony-forming units per gram within 12 months, constraining distribution reach in Indonesian archipelago logistics.
Strategic Opportunities
- Vietnam protected cultivation:Greenhouse vegetable expansion in Lam Dong and Da Lat provinces lacks established biocontrol distribution networks, creating first-mover positioning for microbial strain suppliers.
- Carbon-accounting integration:Scope-three emissions reporting frameworks could revalue microbial biocontrol within corporate sustainability disclosures, particularly for export-oriented Thai horticulture conglomerates.
- Drone spray compatibility:Aerial application of bacillus thuringiensis formulations is converging with precision agriculture platforms in Australian broadacre cotton regions.
Industry Challenges
- Formulation chemist scarcity:Fermentation-derived metabolite stabilization expertise concentrates in Gujarat and Jiangsu research clusters, creating recruitment bottlenecks for emerging Vietnamese manufacturers.
- Registration data package costs:Toxicology and field efficacy trials required by national biologicals registration pathways demand capital outlays exceeding $500,000 per active ingredient.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Biopesticides Market |
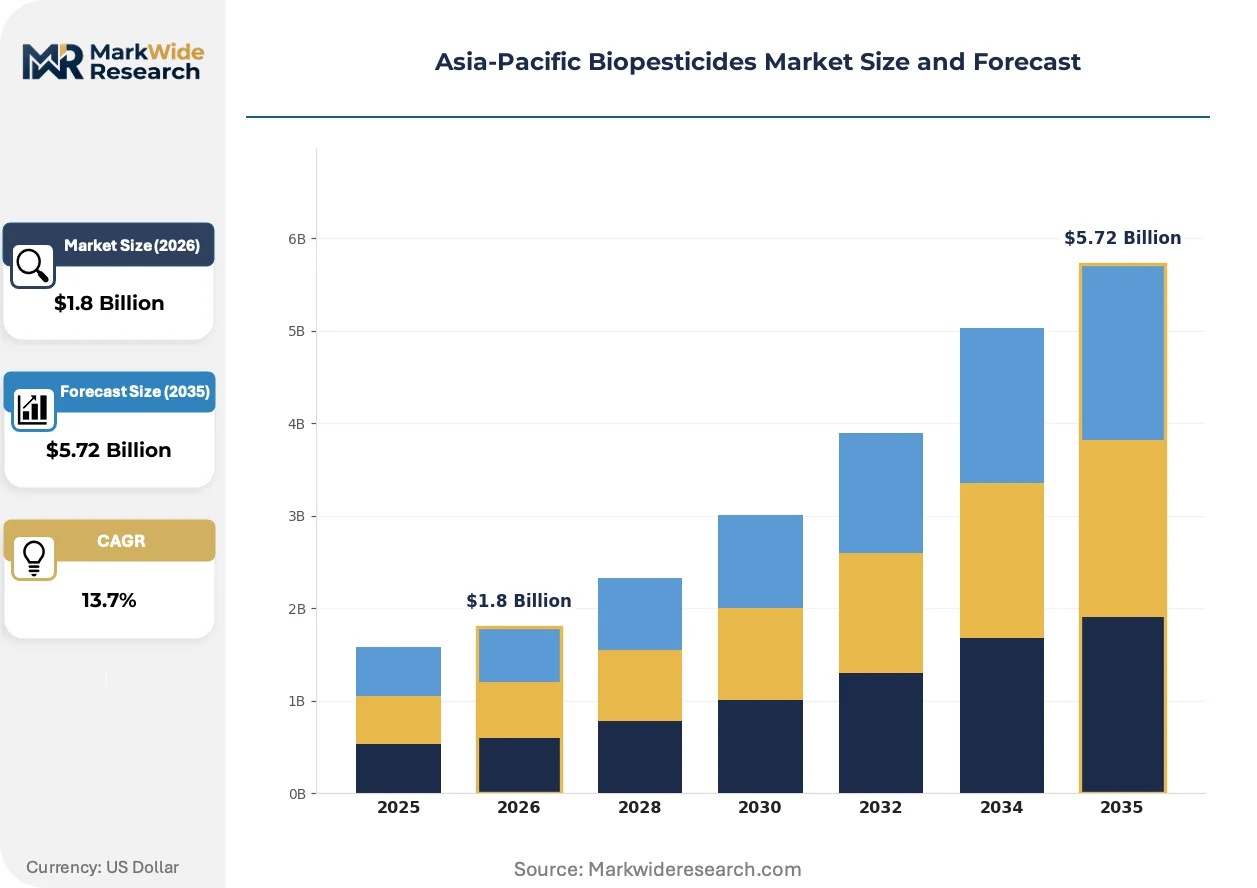
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial Biopesticides, Fungal Biopesticides, Plant-Made Biopesticides, Virus-Based Biopesticides Formulation Type: Liquid Formulations, Granular Formulations, Powder Formulations, Microencapsulation Application: Agricultural Crops, Horticultural Crops, Turf & Ornamentals, Others End User: Farmers, Agricultural Cooperatives, Distributors, Research Institutions |
| Companies Covered | BASF SE, Bayer AG, Valent Biosciences LLC, Syngenta AG, Gujarat State Fertilizers & Chemicals Ltd, Marrone Bio Innovations, Koppert, Andermatt Biocontrol AG, Nufarm Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Biopesticides Market Strategic Shifts
Microbial strain libraries and formulation chemistry are converging with digital agriculture platforms, compressing development cycles and redefining technical leadership criteria across Asia-Pacific biopesticide supply chains.
Metabolite-based biopesticides derived from bacterial fermentation are fragmenting traditional product categories. Australian cotton growers and Vietnamese dragon fruit cooperatives are adopting these formulations for faster knockdown against sucking pests. The technology is fragmenting established bacterial biopesticide market positions by enabling broader spectrum claims and reduced application intervals.
China's dual carbon goals are redirecting state subsidies toward biocontrol manufacturing facilities with verified renewable energy inputs. Industrial consequence includes preferential land allocation and tax treatment for fermentation plants achieving carbon-neutral process heat. Jiangsu and Shandong province biocontrol producers are responding by retrofitting coal-fired sterilization systems with biomass boilers.
Direct procurement relationships between horticulture cooperatives and fermentation facilities are displacing layered distribution networks. Indian grape and pomegranate exporters in Nashik and Sangli districts are contracting captive supply agreements with Gujarat State Fertilizers & Chemicals Ltd to secure residue-compliant bacillus subtilis formulations. This pattern is most visible in Maharashtra's western agricultural belt where integrated pest management adoption is deepest.
Asia-Pacific Biopesticides Market Segmentation
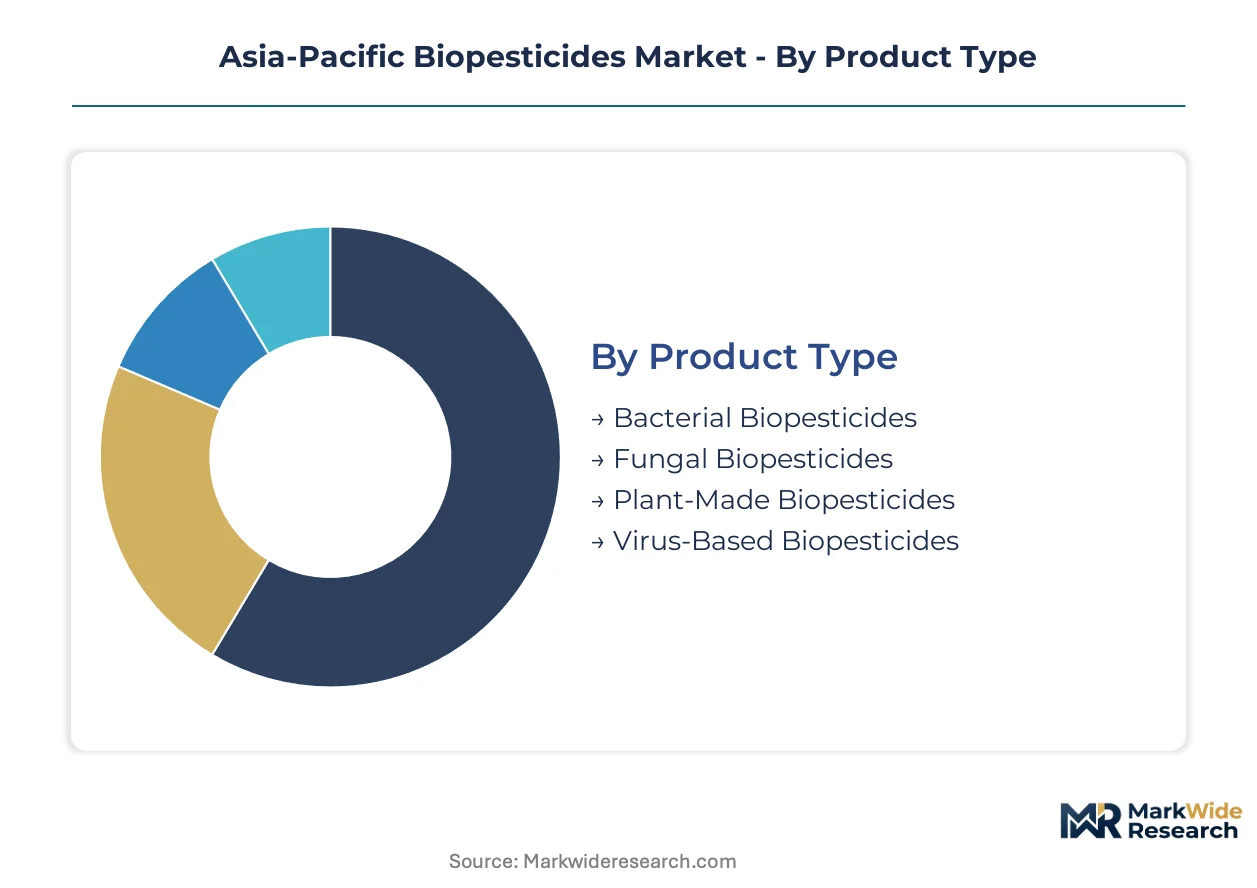
Segmentation reveals how biocontrol procurement channels diverge across crop systems and user sophistication levels. Product type and formulation choices determine whether supply flows through distributor networks or direct cooperative contracts.
Product Type:
Bacterial biopesticides move through conventional agrochemical distributors, while fungal and plant-made variants increasingly bypass layered channels for direct grower relationships.
- Bacterial Biopesticides:These formulations utilize bacillus subtilis and bacillus thuringiensis endospores at concentrations of 10^9 to 10^11 colony-forming units per gram. Maharashtra and Gujarat horticulture cooperatives are embedding these into spray programs for lepidopteran larvae control, driven by export residue compliance requirements. Bacterial biopesticides dominate installed base. Fungal biopesticides is where expansion concentrates.
- Fungal Biopesticides:Trichoderma-based soil treatments utilize fungal conidia for nematode suppression and soil-borne pathogen control. China's protected cultivation expansion in Shandong and Jiangsu provinces is accelerating demand for these formulations, supported by the Ministry of Agriculture and Rural Affairs registration pathways incentivizing domestic production.
- Plant-Made Biopesticides:Botanical extracts from neem, pyrethrum, and other plant sources command premium positioning where standardization meets European retail channel residue protocols.
- Virus-Based Biopesticides:Nucleopolyhedrovirus formulations target specific lepidopteran pests with high host specificity and minimal non-target effects.
Bacterial biopesticides dominate installed base. Fungal biopesticides is where expansion concentrates.
Formulation Type:
Cost tiers separate premium microencapsulation from commodity liquid and powder forms, with granular variants occupying the mid-market for soil application systems.
- Liquid Formulations:Aqueous suspensions of bacterial endospores or fungal conidia compatible with conventional spray equipment and drone application systems. Australian cotton regions are adopting these for aerial bacillus thuringiensis delivery.
- Granular Formulations:Clay-carrier matrices for soil-drench application of trichoderma and other fungal biocontrol agents. Vietnam's Lam Dong greenhouse vegetable expansion lacks established distribution networks for these products, creating first-mover positioning opportunities.
- Powder Formulations:Dry formulations with extended shelf stability for tropical storage conditions, though conidia viability degrades below effective thresholds within 12 months in Indonesian archipelago logistics.
- Microencapsulation:Advanced encapsulation technologies extending field persistence and protecting active agents from ultraviolet degradation. Premium pricing reflects formulation chemist scarcity concentrated in Gujarat and Jiangsu research clusters.
Liquid formulations capture the highest volume throughput. Microencapsulation commands the steepest expansion trajectory.
Application:
Application segmentation tracks the divergence between broadacre commodity systems and intensive horticulture with residue-sensitive export orientation.
- Agricultural Crops:Field-scale deployment in rice, cotton, and soybean systems where cost per hectare drives formulation selection. Indian PLI scheme incentives are expanding domestic fermentation capacity for these volume applications.
- Horticultural Crops:High-value fruit and vegetable production where export market residue limits under FAO/WHO Joint Meeting on Pesticide Residues mandate biocontrol substitution. Nashik and Sangli grape and pomegranate exporters are contracting captive supply agreements for residue-compliant formulations.
- Turf & Ornamentals:Golf course and landscape maintenance applications with lower price sensitivity and emphasis on aesthetic outcomes.
- Others:Forestry, public health, and industrial vegetation management applications with specialized registration requirements.
Horticultural crops absorb premium biocontrol formulations. Agricultural crops represent the deepest volume penetration.
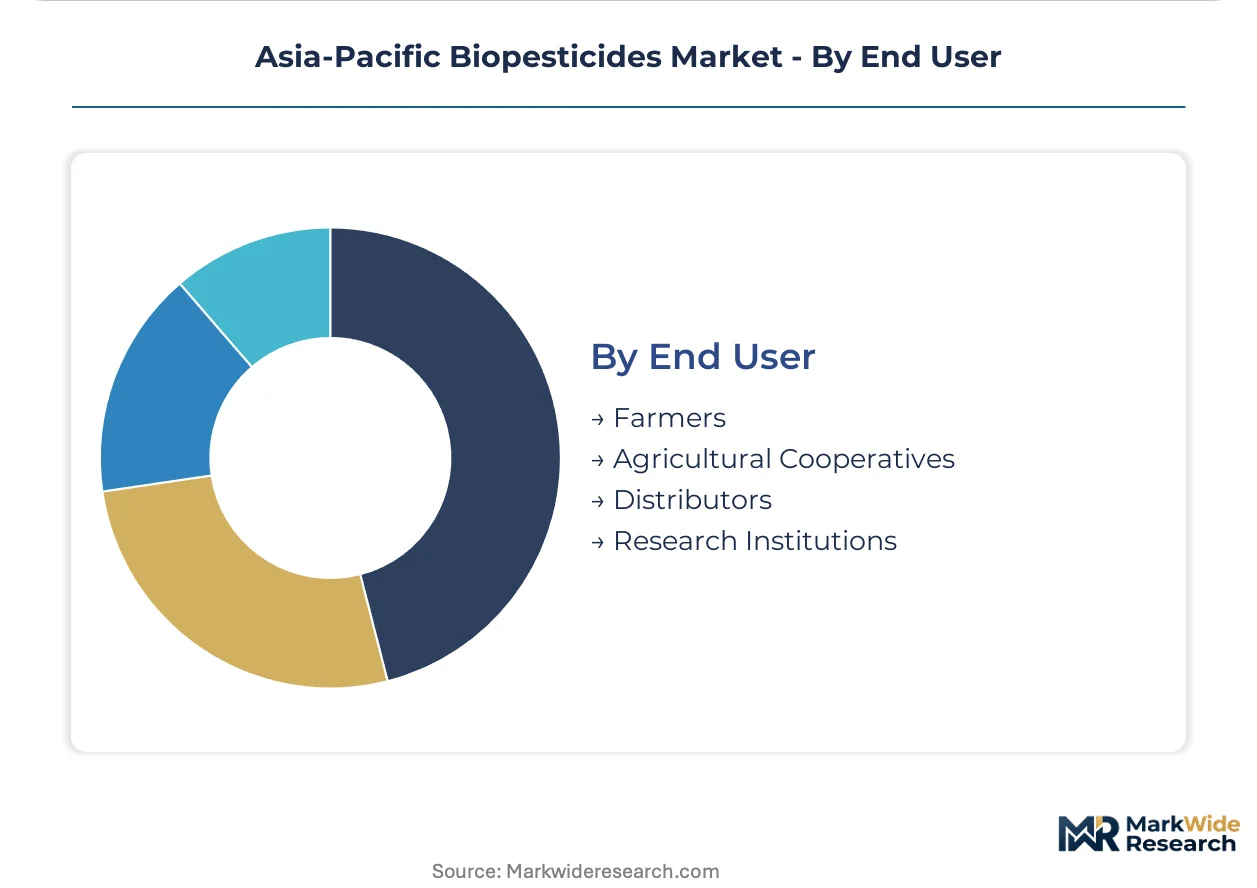
End User:
Customer type determines procurement sophistication, with cooperatives and large farmers bypassing traditional distributors for direct fermentation facility relationships.
- Farmers:Individual growers accessing biocontrol products through retail distributor networks and extension service recommendations.
- Agricultural Cooperatives:Consolidated procurement entities in Maharashtra's western agricultural belt embedding bacterial biopesticides into integrated pest management programs. These cooperatives are displacing layered distribution networks through direct contracting with Gujarat State Fertilizers & Chemicals Ltd.
- Distributors:Agrochemical supply chain intermediaries facing margin compression as direct procurement relationships proliferate.
- Research Institutions:Public and private sector entities conducting field efficacy trials required for Central Insecticides Board and Ministry of Agriculture and Rural Affairs registration pathways.
Agricultural cooperatives drive the fastest volume growth. Distributors retain dominance in fragmented smallholder access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity for biocontrol strains clusters in Gujarat and Jiangsu provinces, with state-level carbon mandates and production-linked incentives redirecting capital toward domestic manufacturing scale.
India
Maharashtra and Gujarat horticulture cooperatives are embedding bacterial biopesticides into integrated pest management programs for grape and pomegranate exports. The PLI scheme for agrochemical innovation accelerates domestic fermentation capacity expansion. Nashik and Sangli districts anchor direct procurement relationships with Gujarat State Fertilizers & Chemicals Ltd for residue-compliant formulations.
China
Protected cultivation expansion in Shandong and Jiangsu provinces drives demand for trichoderma-based soil treatments in greenhouse vegetable systems. The Ministry of Agriculture and Rural Affairs registration pathways incentivize domestic production of fungal biocontrol agents. Dual carbon goals redirect state subsidies toward fermentation facilities with verified renewable energy inputs and biomass boiler retrofits.
Vietnam
Greenhouse vegetable expansion in Lam Dong and Da Lat provinces lacks established biocontrol distribution networks, creating first-mover positioning for microbial strain suppliers. The national agricultural extension service promotes integrated pest management adoption in highland horticulture corridors. Da Lat anchors emerging demand for granular formulations in soil-drench application systems.
Australia
Broadacre cotton regions in Queensland and New South Wales are adopting aerial application of bacillus thuringiensis formulations via precision agriculture platforms. The Australian Pesticides and Veterinary Medicines Authority regulates biopesticide registration with efficacy requirements distinct from chemical pesticide pathways. Darling Downs and Namoi Valley anchor drone spray compatibility trials for microbial biocontrol delivery.
Indonesia
Archipelago logistics constrain distribution reach for fungal conidia formulations with tropical shelf-life degradation below effective thresholds within 12 months. The Ministry of Agriculture regulates biological product registration through field efficacy requirements adapted to humid tropical conditions. Java and Sumatra anchor demand for powder formulations with extended stability for smallholder rice systems.
Asia-Pacific Biopesticides Market Competitive Environment
Concentration sits with multinational agrochemical conglomerates leveraging microbial strain libraries and established distribution networks, while domestic fermentation specialists capture cooperative direct procurement relationships through manufacturing scale. Three archetypes define competitive positioning: global innovators with formulation chemistry leadership, regional distributors with horticulture corridor access, and state-linked manufacturers with fermentation infrastructure. Capacity expansion and backward integration into captive strain production dominate strategic moves as residue compliance tightens in export markets.
Among global innovators, Bayer AG and BASF SE anchor technical leadership in bacterial biopesticide formulations through microbial strain libraries and formulation chemistry expertise. Gujarat State Fertilizers & Chemicals Ltd exemplifies the state-linked manufacturing archetype, occupying a position in domestic Indian production scale for fermentation-derived biocontrol agents. Koppert sits within the regional distribution tier, representing biological control network access across Southeast Asian horticulture corridors.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Valent Biosciences LLC |
| Syngenta AG |
| Gujarat State Fertilizers & Chemicals Ltd |
| Marrone Bio Innovations |
| Koppert |
| Andermatt Biocontrol AG |
| Nufarm Limited |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Maharashtra horticulture cooperatives and Gujarat State Fertilizers & Chemicals Ltd lock in both residue-compliant bacillus subtilis supply and price visibility for export-oriented grape and pomegranate growers. These captive supply agreements concentrate procurement power among cooperative buyers while insulating fermentation facilities from molasses and soybean meal commodity volatility.
Pricing Analysis
The FAO/WHO Joint Meeting on Pesticide Residues dictates the pricing tier structure by mandating maximum residue limits that separate premium microencapsulated formulations from standard liquid suspensions. Certification grade and volume scale drive price differentiation, with export-certified bacterial endospores commanding substantial premiums over domestic-grade alternatives. Cost compression in commodity liquid formulations is intensifying because Indian PLI scheme incentives are expanding domestic fermentation capacity. Smallholder farmers accessing products through retail distributors exhibit the highest price sensitivity, while agricultural cooperatives contracting directly with manufacturers demonstrate the lowest.
Supply Chain Analysis
Container availability constraints on the Shanghai-Singapore trade lane are elevating inbound logistics costs for Australian cotton growers importing bacillus thuringiensis formulations. Manufacturing concentration rests on India, China, and Vietnam, with fermentation infrastructure clustering in Gujarat and Jiangsu provinces. Raw material dependencies draw from molasses feedstock, soybean meal nitrogen sources, and clay carrier matrices for granular formulations. Single-source vulnerability concentrates in fungal conidia production where tropical shelf-life degradation constrains Indonesian archipelago distribution. Distribution runs through direct cooperative contracts displacing layered agrochemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific biopesticides market is entering a cyclical recovery phase as residue compliance tightening in European retail channels restarts procurement investment cycles stalled by pandemic-era logistics disruptions.
For Market Incumbents: Secure microbial strain library exclusivity through patent extensions on bacillus thuringiensis variants to defend against emerging domestic Chinese fermentation specialists. Backward integration into captive molasses sourcing in Maharashtra and Gujarat mitigates input cost volatility threatening margin stability in bacterial endospore production.
For New Entrants and Emerging Players: China's Ministry of Agriculture and Rural Affairs registration fast-track for trichoderma-based soil treatments opens first-mover positioning in Vietnam's Lam Dong greenhouse vegetable expansion. Target granular formulation supply gaps in Da Lat province where established biocontrol distribution networks remain absent, deploying direct technical sales teams to bypass incumbent distributor relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation facilities with captive cooperative supply agreements locking in multi-year offtake commitments. Long-term viability hinges on carbon-accounting integration where scope-three emissions reporting frameworks revalue microbial biocontrol within corporate sustainability disclosures. Acquisition targets should demonstrate verified renewable energy inputs for process heat. The signal to monitor is Jiangsu province biomass boiler retrofit completion rates as a proxy for state subsidy capture efficiency.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Production | Gujarat State Fertilizers & Chemicals Ltd's captive bacillus subtilis libraries reduce dependency on external microbial suppliers. |
| Carbon-Neutral Fermentation Retrofit | Jiangsu province biomass boiler installations align with China's dual carbon goals and unlock preferential tax treatment. |
| Direct Cooperative Contracting | Maharashtra horticulture cooperatives disintermediate distributor margins through captive supply agreements with Gujarat manufacturers. |
| Drone Spray Compatibility Development | Australian cotton regions in Queensland validate aerial bacillus thuringiensis delivery via precision agriculture platforms. |
| Registration Data Package Investment | Central Insecticides Board toxicology trials exceeding $500,000 per active ingredient create regulatory moats against undercapitalized entrants. |
Study Parameters
Operator-level perspectives from fermentation facility managers, horticulture cooperative procurement heads, agrochemical distributor network leads, and regulatory affairs specialists anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation from India's Central Insecticides Board registration filings, China's Ministry of Agriculture and Rural Affairs approval databases, FAO/WHO pesticide residue guidelines, and customs trade data on biocontrol ingredient flows. Bottom-up volume estimates from state-level fermentation capacity triangulated against top-down market sizing from export value tracking across the analysis window.
Sensitivity analysis tested forecast robustness against molasses price volatility scenarios and regulatory approval timeline variations throughout the projection horizon. The analytical framework modeled segmentation across product type, formulation chemistry, application crop system, and end-user procurement sophistication. CAGRs were derived from installed base growth rates adjusted for technology substitution patterns and residue compliance acceleration curves. Industry-specific inputs incorporated PLI scheme disbursement trajectories and dual carbon goal implementation timelines affecting manufacturing cost structures.
Decision-makers should treat outputs as directional under assumptions of sustained export market residue limit tightening and stable fermentation input commodity pricing; material deviation would warrant model refresh. Specific risk factors include regulatory friction extending cross-border product development timelines and tropical storage conditions degrading fungal conidia viability below effective thresholds. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
North America Biological Organic Fertilizer Market
Bio-Agriculture
Italy Biopesticides Market
Bio-Agriculture
Red Algae Market
Bio-Agriculture
GCC Biofertilizer Market
Bio-Agriculture
Agriculture Biologicals Testing Market
Bio-Agriculture
South America Biopesticides Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
Brazil Biopesticides Market
Bio-Agriculture
Biofuel Enzymes Market
Bio-Agriculture
India Biostimulants Market
Bio-Agriculture
Aquatic Animal Vaccines Market
Bio-Agriculture
Bio Rational Fungicides Market
Bio-Agriculture
North America Biopesticides Market
Bio-Agriculture
Biocontrol Agents Market
Bio-Agriculture
Bio-Based Levulinic Acid Market
Bio-Agriculture
Transgenic Animals Market