
 Redox Enzymes Market | 2026-2036
Redox Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Redox Enzymes Market Intelligence
Aftermarket enzyme formulation services is fragmenting across regional contract manufacturers as pharmaceutical clients seek localized supply security. Novozymes leverages its Danish fermentation infrastructure to sustain bulk oxidoreductase output for European biosensor manufacturers. BASF anchors industrial peroxidase production through captive chemical synthesis capabilities at Ludwigshafen. Amano Enzyme specializes in high-purity dehydrogenases for diagnostic applications, competing primarily on Japanese pharmaceutical qualification standards.
Redox enzymes catalyze electron-transfer reactions using cofactors such as NAD(P)+, FAD, or metal ions, operating optimally across pH ranges of 4.0 to 9.0 depending on source organism and immobilization substrate. These biocatalysts enable selective oxidation and reduction transformations that chemical routes cannot achieve without harsh conditions or stoichiometric reagents. Oxidoreductases command the largest product type position due to their versatility in pharmaceutical intermediate synthesis and biosensor signal amplification. Immobilization technology exhibits the fastest technology trajectory as manufacturers seek reusable catalyst architectures that reduce downstream processing costs. Fermentation technology remains the mature volume backbone, though margin pools increasingly favor recombinant strains engineered for cofactor regeneration efficiency.
EPA bioremediation guidelines and REACH Annex XIV authorization requirements shape product purity specifications and market access conditions for redox enzyme suppliers serving North American and European industrial clients. FDA enzyme master file expectations for pharmaceutical-grade biocatalysts add qualification layers that favor established producers with documented quality management systems. Stakeholders must monitor CRISPR-edited strain regulatory classifications and evolving carbon-accounting rules for fermentation-derived products.
Market Dynamics
Immobilization technology is compressing unit economics for redox enzyme users by enabling catalyst reuse across 50+ batch cycles, shifting margin pools from enzyme sales toward process engineering services and substrate-specific carrier design.
Growth Catalysts
- REACH Annex XIV authorization:European industrial clients face mandatory substitution timelines for stoichiometric oxidants, pulling demand toward enzymatic alternatives that satisfy ECHA purity benchmarks without process redesign.
- Continuous flow biocatalysis:Pharmaceutical manufacturers retrofit existing batch infrastructure with packed-bed enzyme reactors, cutting solvent volumes and downstream purification steps for high-value chiral intermediates.
- German fermentation clusters:Specialized infrastructure around Hamburg and Frankfurt concentrates upstream strain development, downstream processing, and analytical qualification capabilities within 200-kilometer radii.
Market Restraints
- Cofactor cost volatility:NAD+ and FAD prices fluctuate with nicotinamide agricultural yields and synthetic riboflavin feedstock costs, compressing margins for non-regenerative process configurations.
- Danish supply concentration:Bulk oxidoreductase output depends on a narrow base of fermentation facilities with documented pharmaceutical-grade quality systems, creating single-source vulnerability for European biosensor manufacturers.
- Thermal stability ceiling:Wild-type redox enzymes denature above 45°C, limiting compatibility with high-temperature chemical process streams and requiring costly protein engineering or cooling infrastructure.
Strategic Opportunities
- India's PLI scheme for active pharmaceutical ingredients:Domestic enzyme formulation capabilities qualify for production-linked incentives, attracting contract manufacturing investment away from established European suppliers.
- CRISPR-edited strain regulatory clarity:FDA guidance on gene-edited production organisms is creating a compliance pathway that rewards early movers with abbreviated enzyme master file review timelines.
- Biosensor signal amplification:Peroxidase-integrated diagnostic platforms are penetrating point-of-care testing channels previously served by optical or electrochemical methods alone.
Industry Challenges
- Protein engineering talent scarcity:Computational enzyme design requires rare combinations of structural biology and machine learning expertise, extending strain development timelines for mid-tier producers.
- Fermentation capacity lead times:Stainless steel bioreactor installation and GMP qualification demand 18-24 month capital cycles, misaligning supply expansion with demand inflection points.
- Cross-jurisdiction master file harmonization:FDA, EMA, and PMDA enzyme documentation requirements diverge on stability data packages, forcing redundant analytical expenditure for multi-regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Redox Enzymes Market |
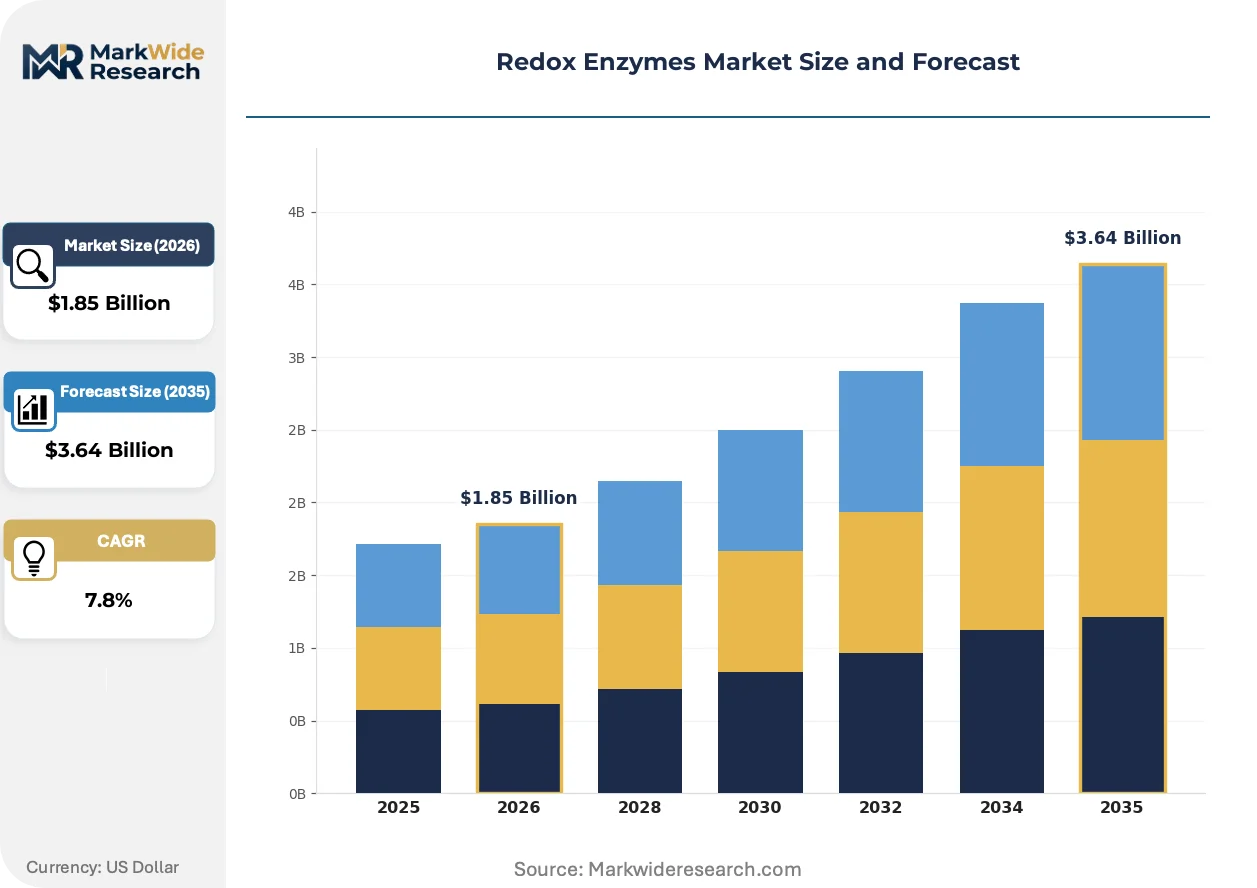
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxidoreductases, Dehydrogenases, Peroxidases, Catalases Application: Biosensors, Bioremediation, Agriculture, Pharmaceuticals End User: Biotechnology Firms, Research Institutions, Agricultural Companies, Food Industry Technology: Recombinant Technology, Fermentation Technology, Chemical Synthesis, Immobilization Technology |
| Companies Covered | Novozymes, BASF, Amano Enzyme, DSM, Sunson, Soufflet Group, AB Enzymes, Dupont, Hansen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Redox Enzymes Market Strategic Shifts & Innovations
Enzyme immobilization architectures are converging with continuous processing equipment, compressing the traditional separation between catalyst supply and process design. This integration is reshaping supplier-customer relationships and value capture points.
Carrier-free cross-linked enzyme aggregates (CLEAs) are hybridizing with magnetic nanoparticle cores to enable rapid separation from product streams. Pharmaceutical intermediate manufacturers in Germany and Switzerland are piloting these systems at 100-liter scales. The technology is hybridizing catalyst recovery rates with magnetic separation speed, cutting filtration costs by eliminating centrifugation steps.
EPA bioremediation guidelines for chlorinated solvent degradation are tightening analytical detection thresholds for treated groundwater. Industrial site remediation contractors must now document enzyme-derived degradation product profiles at sub-ppb levels. Soil and groundwater treatment applications in the US Midwest are responding by specifying peroxidase formulations with certified lot-to-lot activity variance below 5%.
Diagnostic laboratories are consolidating enzyme procurement through group purchasing organizations that bundle oxidoreductase supply with calibration and technical support services. This channel compression is displacing direct manufacturer relationships for mid-volume clinical chemistry applications. The shift is most visible in Japan, where hospital consortia negotiate three-year enzyme supply frameworks with embedded price adjustment clauses tied to cofactor input costs.
Redox Enzymes Market Segmentation
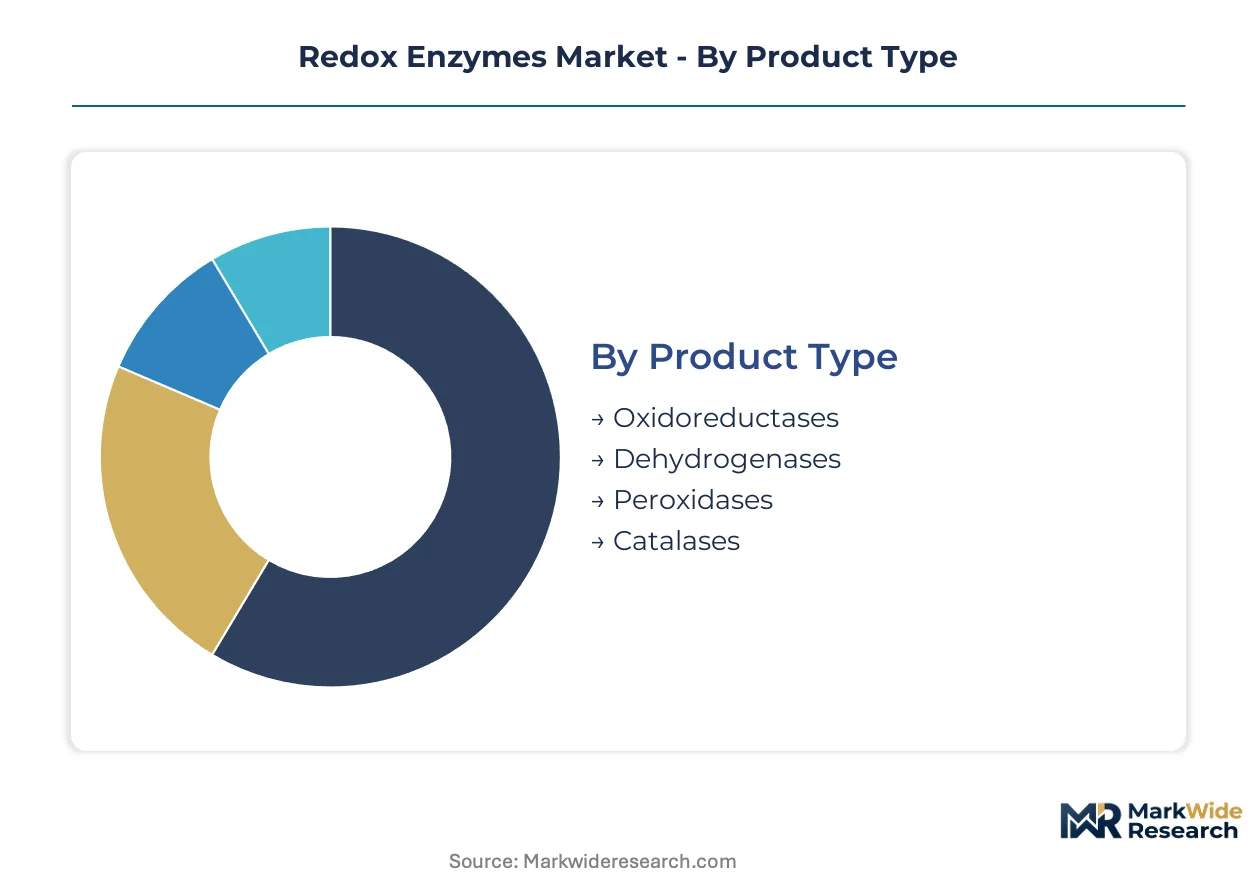
Redox enzyme procurement patterns diverge sharply across application contexts, with pharmaceutical-grade specifications commanding tenfold purity premiums over industrial bioremediation formulations. Technology selection and end-user scale jointly determine margin architecture, creating distinct competitive arenas within each segment boundary.
Product Type:
Mature commodity enzymes anchor volume throughput while engineered variants capture expanding premium niches in precision biocatalysis.
- Oxidoreductases:These electron-transfer catalysts operate with NAD(P)+ or FAD cofactors across pH ranges of 4.0 to 9.0, enabling selective transformations impossible under harsh chemical conditions. Pharmaceutical intermediate manufacturers in Germany and Switzerland specify these for chiral alcohol synthesis, with demand intensifying as REACH Annex XIV timelines force substitution of stoichiometric oxidants.
- Dehydrogenases:Specialized in hydride transfer reactions, these enzymes require precise cofactor regeneration systems to maintain economic viability. Japanese diagnostic laboratories concentrate procurement through hospital consortia, embedding three-year supply frameworks with price adjustment clauses tied to nicotinamide input costs.
- Peroxidases:Hydrogen peroxide-dependent enzymes specified for EPA bioremediation protocols in the US Midwest.
- Catalases:Oxygen-evolving enzymes deployed for residual peroxide elimination in food processing and textile bleaching.
Oxidoreductases retain volume leadership; immobilized dehydrogenase formulations hold the steepest expansion curve in high-value pharmaceutical applications.
Application:
Regulatory detection thresholds and reimbursement economics jointly determine specification intensity across downstream use cases.
- Biosensors:Signal amplification platforms integrate peroxidase or oxidoreductase layers to enhance electrochemical or optical readout sensitivity. Danish fermentation infrastructure supplies bulk oxidoreductase to European manufacturers, though single-source vulnerability concerns are prompting qualification of secondary suppliers.
- Bioremediation:EPA guidelines for chlorinated solvent degradation now mandate sub-ppb analytical detection for treated groundwater, forcing contractors toward certified low-variance enzyme lots. Peroxidase formulations with activity variance below 5% command substantial price premiums over standard industrial grades.
- Agriculture:Soil amendment and crop protection applications driving demand for cost-optimized catalase and peroxidase blends.
- Pharmaceuticals:Chiral intermediate synthesis and API manufacturing requiring GMP-qualified enzyme master files.
Bioremediation absorbs the highest volume tonnage; biosensor integration is climbing fastest as point-of-care diagnostic platforms proliferate.
End User:
Procurement sophistication stratifies sharply between regulated life sciences and price-sensitive primary sector applications.
- Biotechnology Firms:Continuous flow biocatalysis adopters retrofit packed-bed enzyme reactors to cut solvent volumes and purification steps. These users specify immobilized catalyst architectures with documented 50+ batch cycle durability, shifting supplier relationships toward process engineering partnerships.
- Research Institutions:Academic and government laboratories drive specification innovation but represent fragmented, small-lot demand. CRISPR-edited strain development for novel redox enzyme expression originates primarily in German and Swiss university clusters before commercial licensing.
- Agricultural Companies:Large-scale soil and crop applications prioritizing unit cost over activity consistency.
- Food Industry:Oxygen scavenging and peroxide elimination in packaging and processing operations.
Biotechnology firms dominate value capture; research institutions supply the pipeline for next-generation biocatalyst development.
Technology:
Production methodology determines regulatory pathway complexity and capital intensity thresholds for market entry.
- Immobilization Technology:Carrier-free cross-linked enzyme aggregates hybridized with magnetic nanoparticle cores enable rapid separation from product streams. German and Swiss pharmaceutical intermediate manufacturers pilot these systems at 100-liter scales, eliminating centrifugation steps and cutting filtration costs.
- Fermentation Technology:Stainless steel bioreactor infrastructure with GMP qualification demands 18-24 month capital cycles. Hamburg and Frankfurt fermentation clusters concentrate upstream strain development, downstream processing, and analytical qualification within tight geographic radii.
- Recombinant Technology:CRISPR-edited strain development awaiting FDA regulatory clarity for abbreviated enzyme master file pathways.
- Chemical Synthesis:Captive production at integrated chemical complexes for non-phosphate cofactor analogs.
Fermentation technology sustains volume leadership; immobilization architectures are gaining share fastest through continuous processing equipment integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade oxidoreductases dominate procurement in Germany and Switzerland, while industrial bioremediation applications concentrate in the United States Midwest, creating divergent specification intensity across major consumption centers.
United States
EPA bioremediation protocols for chlorinated solvent degradation drive peroxidase demand among Midwestern site remediation contractors. The agency's sub-ppb analytical detection thresholds force certified low-variance enzyme lots with activity variance below 5%. Indianapolis and Chicago industrial corridors host the primary contractor networks specifying these formulations.
Germany
REACH Annex XIV authorization timelines compel pharmaceutical manufacturers toward enzymatic oxidant substitution for chiral intermediate synthesis. Hamburg and Frankfurt fermentation clusters concentrate upstream strain development, downstream processing, and analytical qualification capabilities within 200-kilometer radii serving Western European export markets.
Japan
Diagnostic laboratory consolidation through hospital consortia drives oxidoreductase procurement frameworks with three-year supply commitments. PMDA enzyme master file expectations add qualification layers favoring established producers with documented quality management systems. Tokyo-Osaka metropolitan corridors concentrate the contract manufacturing infrastructure.
India
PLI scheme incentives for active pharmaceutical ingredient production attract contract manufacturing investment toward domestic enzyme formulation capabilities. CDSCO regulatory pathways for imported biocatalysts create compliance friction that local qualification can circumvent. Hyderabad and Mumbai pharmaceutical clusters anchor the emerging supplier base.
Switzerland
Specialized fermentation infrastructure serves high-purity dehydrogenase demand for diagnostic and pharmaceutical applications. Swissmedic enzyme documentation requirements align with EMA standards while maintaining distinct stability data package expectations. Basel and Zurich pharmaceutical corridors concentrate the precision biocatalysis ecosystem.
Redox Enzymes Market Key Industry Players
Capability concentration sits with Danish and German fermentation specialists; scale advantage sits with diversified chemical conglomerates with captive synthesis infrastructure. The market structures around three tiers: integrated chemical producers with backward enzyme production, specialized fermentation houses with pharmaceutical-grade quality systems, and regional contract manufacturers serving price-sensitive industrial applications. Dominant competitive moves include fermentation capacity expansion with GMP qualification and strategic partnerships between enzyme suppliers and continuous processing equipment vendors.
Among the specialized fermentation tier, Novozymes anchors oxidoreductase supply to European biosensor manufacturers through its Danish infrastructure. BASF occupies a position exemplifying integrated chemical production, leveraging Ludwigshafen captive capabilities for industrial peroxidase output. Amano Enzyme represents the high-purity diagnostic specialist archetype, competing primarily on Japanese pharmaceutical qualification standards.
| Leading Market Players |
|---|
| Novozymes |
| BASF |
| Amano Enzyme |
| DSM |
| Sunson |
| Soufflet Group |
| AB Enzymes |
| Dupont |
| Hansen |
| Others |
Cost & Logistics Intelligence
Cofactor cost volatility from nicotinamide agricultural yields determines both the spread between regenerative and non-regenerative process pricing tiers and the geographic clustering of fermentation capacity around captive cofactor synthesis. Buyers facing NAD+ price swings demand long-term offtake contracts with embedded adjustment clauses, compressing spot-market liquidity and favoring vertically integrated suppliers with upstream control over riboflavin feedstock costs.
Pricing Analysis
Long-term offtake contracts with cofactor cost pass-through clauses dominate pharmaceutical-grade procurement, while spot transactions persist for industrial bioremediation grades. Price differentiation separates GMP-certified master file holders from standard industrial suppliers by certification burden and documented batch consistency. Cost compression in the industrial tier intensifies as Indian contract manufacturers qualify for PLI scheme incentives and undercut European spot pricing. Agricultural soil amendment buyers exhibit highest price sensitivity; diagnostic laboratories with hospital consortium frameworks show lowest sensitivity due to embedded technical support bundling.
Supply Chain Analysis
Tariff exposure between Danish fermentation clusters and German pharmaceutical manufacturers dominates supply chain risk assessment for European oxidoreductase procurement. Bulk production concentrates in Denmark, Germany, and Japan, with strain development capabilities anchored in Hamburg-Frankfurt radii and Tokyo-Osaka corridors. Raw material dependencies span nicotinamide agricultural supplies, synthetic riboflavin feedstocks, and specialized stainless steel bioreactor components. Single-source vulnerability from concentrated Danish pharmaceutical-grade output creates qualification urgency for secondary suppliers. Distribution runs through regional contract manufacturers for industrial grades and direct manufacturer relationships for diagnostic and pharmaceutical tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Process engineering service contracts are expanding faster than standalone enzyme sales as continuous flow biocatalysis adopters seek integrated catalyst-recovery system design. This service-attach dynamic favors suppliers capable of delivering substrate-specific carrier architectures alongside biocatalyst supply.
For Market Incumbents: Build regulatory documentation moats by accelerating enzyme master file submissions ahead of FDA guidance finalization on CRISPR-edited strains. Expand Hamburg and Frankfurt fermentation capacity with integrated downstream processing to capture REACH Annex XIV substitution demand. Deepen backward integration into cofactor regeneration technology to offset nicotinamide price volatility threatening margin stability in non-regenerative process configurations. For New Entrants and Emerging Players: Pursue qualification as secondary oxidoreductase suppliers for European biosensor manufacturers seeking to diversify beyond Danish single-source dependency. Target India's PLI scheme-eligible contract manufacturing segment where CDSCO regulatory friction disadvantages imported biocatalysts. Lead with immobilization technology partnerships that bundle catalyst supply with continuous processing equipment integration. For Investors and Strategic Acquirers: FDA guidance on gene-edited production organisms reshapes the acquisition landscape toward CRISPR-edited strain developers with abbreviated master file pathways. Five-to-ten-year viability hinges on regulatory navigation capability rather than commodity scale. Target fermentation specialists with documented quality management systems and existing pharmaceutical customer relationships. Watch for ECHA substitution timeline acceleration as the signal indicating demand inflection for enzymatic oxidant alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cofactor Synthesis | Captive NAD+ regeneration capacity insulates margins from agricultural commodity swings. |
| Continuous Processing Equipment Partnership | Immobilized catalyst architectures bundled with packed-bed reactor design capture service revenue. |
| CRISPR-Edited Strain Regulatory Submission | Early FDA master file filings secure abbreviated review timelines before guidance finalization. |
| Indian PLI Scheme Qualification | Domestic enzyme formulation capabilities circumvent CDSCO import friction for API producers. |
| Secondary Supplier Qualification Programs | European biosensor manufacturers diversify beyond Danish fermentation concentration risk. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with fermentation technology directors, pharmaceutical procurement leads, diagnostic laboratory managers, and bioremediation contractors; and secondary validation against ECHA substitution timelines, FDA enzyme master file databases, EPA bioremediation protocol amendments, and CDSCO regulatory circulars. Bottom-up triangulation across strain development timelines, bioreactor capacity announcements, and cofactor price indices was cross-checked against top-down market sizing from application-specific demand modeling.
Forecast inputs considered oxidoreductase versus dehydrogenase product mix shifts, immobilization technology adoption curves in continuous flow pharmaceutical manufacturing, REACH Annex XIV compliance deadlines across European member states, and PLI scheme disbursement trajectories in India. Segmentation modeling spanned product type, application, end-user sophistication tier, and technology platform. CAGRs were derived from weighted scenario analysis across regulatory compliance intensity and cofactor cost regime assumptions.
Sensitivities concentrate around FDA guidance timing on CRISPR-edited strains, ECHA authorization acceleration for stoichiometric oxidant substitution, and nicotinamide supply disruptions from agricultural yield variability. Forecasts reflect documented assumptions on regulatory pathway clarity and fermentation capacity lead times. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Global Specialty Enzymes Market
Industrial Biotechnology
Haematococcus Pluvialis Market
Industrial Biotechnology
United States Biocatalyst Market
Industrial Biotechnology
Hydrolase Enzymes Market
Industrial Biotechnology
Japan Biocatalyst Market
Industrial Biotechnology
Protease Enzyme Market
Industrial Biotechnology
Global Carbohydrase Market
Industrial Biotechnology
Europe Biocatalyst Market
Industrial Biotechnology
Global Enzymes Market
Industrial Biotechnology
Industrial Enzymes Market
Industrial Biotechnology
Americas Enzymes Market
Industrial Biotechnology
Glucoamylase Market
Industrial Biotechnology
Esterase Market
Industrial Biotechnology
North America Biocatalysts Market
Industrial Biotechnology
Styrene Monooxygenase Market
Industrial Biotechnology
Inulinase Market