
 North America Biological Organic Fertilizer Market | 2026-2036
North America Biological Organic Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biological Organic Fertilizer Market Analytics
Agricultural co-op distribution networks is rewriting access patterns for biological inputs across North America. Nutrien Ltd leverages its retail footprint to bundle biological fertilizers with precision agriculture services. Sustane Natural Fertilizer anchors premium compost supply through long-term contracts with municipal organic waste programs. BioSTAR Renewables competes by converting food waste streams into certified organic fertilizers at regional scale.
Biological organic fertilizers are nutrient-bearing materials derived from plant, animal, or microbial sources that undergo composting, fermentation, or enzymatic processing to stabilize nitrogen, phosphorus, and potassium in plant-available forms. These inputs typically contain 2-8% total nitrogen by dry weight and rely on soil microbial activity for mineralization, serving primarily to rebuild soil organic matter while reducing synthetic chemical runoff. Compost products dominate volume sales due to established waste-to-value supply chains and broad crop compatibility, while seaweed extract commands premium positioning in high-value fruit and vegetable systems where foliar application delivers rapid micronutrient uptake. Soil application leads method-based revenue because of compatibility with existing farm equipment, though drip irrigation integration is gaining traction among greenhouse operators seeking precision nutrient delivery.
USDA National Organic Program standards govern input eligibility for certified organic operations, while EPA Clean Water Act provisions drive state-level restrictions on synthetic fertilizer application near watersheds. California's Department of Food and Agriculture administers additional material registration requirements that filter smaller unverified suppliers from commercial channels. Canada complements this framework through CFIA fertilizer registration and provincial nutrient management regulations in Ontario and Quebec. Stakeholders must monitor evolving carbon credit protocols that could subsidize biological input costs for early-adopting growers.
Market Dynamics
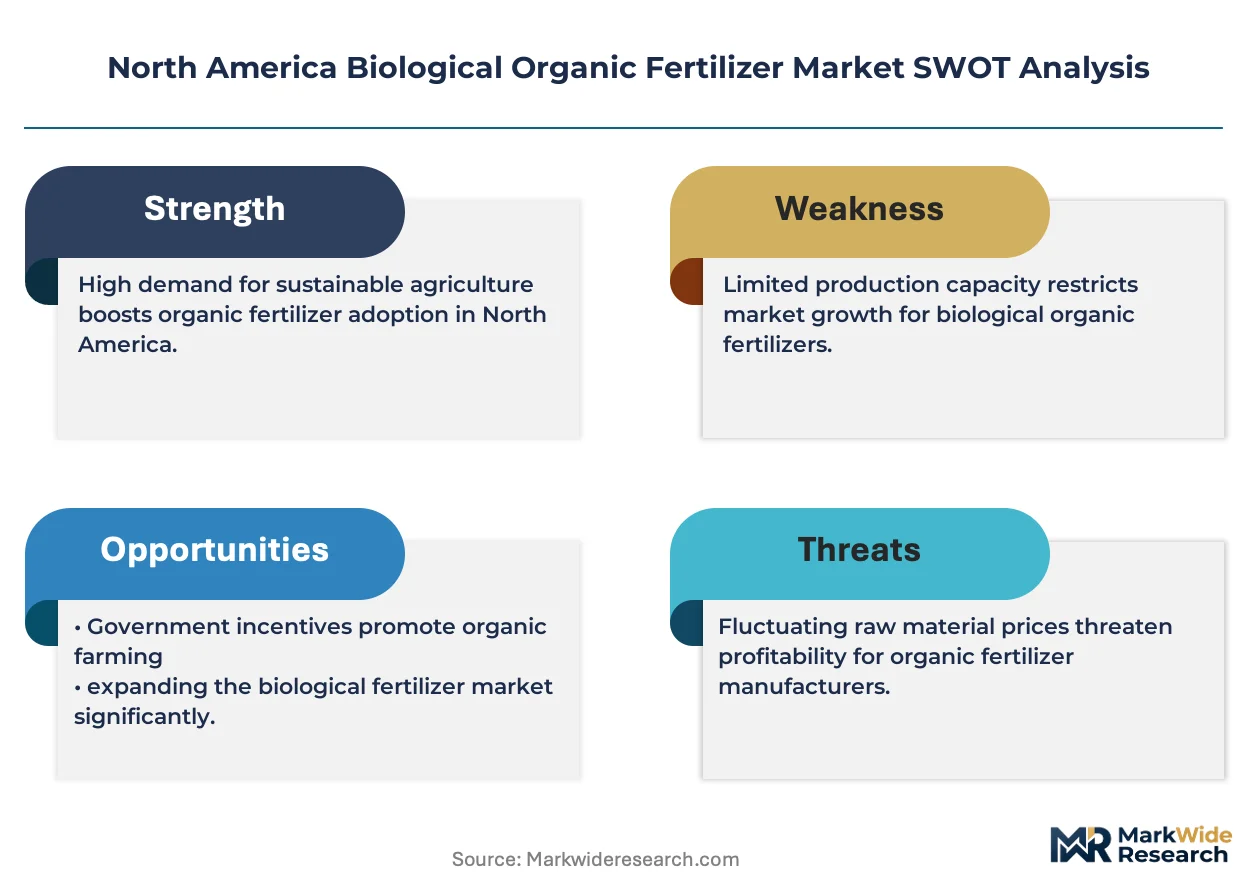
State-level nutrient management plans across California and Florida are tightening synthetic nitrogen limits, forcing specialty crop growers to expand compost and manure applications while manufacturers accelerate investment in verified biological inputs.
Growth Catalysts
- USDA Organic certification requirements:Certification mandates are accelerating manufacturer investment in verified biological inputs as growers seek compliant alternatives to synthetic fertilizers.
- Compost products:Established waste-to-value supply chains and broad crop compatibility position compost as the dominant volume driver across Midwest Corn Belt operations.
- EPA water quality standards:Federal watershed protection rules are driving state-level restrictions on synthetic fertilizer application near sensitive water bodies.
Market Restraints
- Input cost volatility:Municipal organic waste feedstock prices fluctuate with seasonal collection volumes and competing diversion programs.
- Technical limitation:Biological fertilizers rely on soil microbial activity for mineralization, creating unpredictable nutrient release timing compared to synthetic alternatives.
- Substitution threat:Controlled-release synthetic fertilizers retain cost advantages for commodity grain operations with thin margin structures.
Strategic Opportunities
- Carbon credit protocols:Emerging agricultural carbon programs could subsidize biological input costs for early-adopting growers in the Pacific Northwest.
- Drip irrigation integration:Precision nutrient delivery through existing greenhouse infrastructure creates premium positioning for liquid biological formulations.
- Seaweed extract:Foliar application in high-value fruit and vegetable systems commands premium pricing through rapid micronutrient uptake advantages.
Industry Challenges
- CFIA fertilizer registration:Canadian regulatory timelines create compliance bottlenecks for cross-border product launches into Ontario and Quebec markets.
- Soil microbiome expertise:Agronomists with specialized knowledge of microbial mineralization rates remain scarce across agricultural extension services.
- Equipment compatibility:Existing farm machinery requires modification to handle variable-density compost products without clogging or uneven distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biological Organic Fertilizer Market |
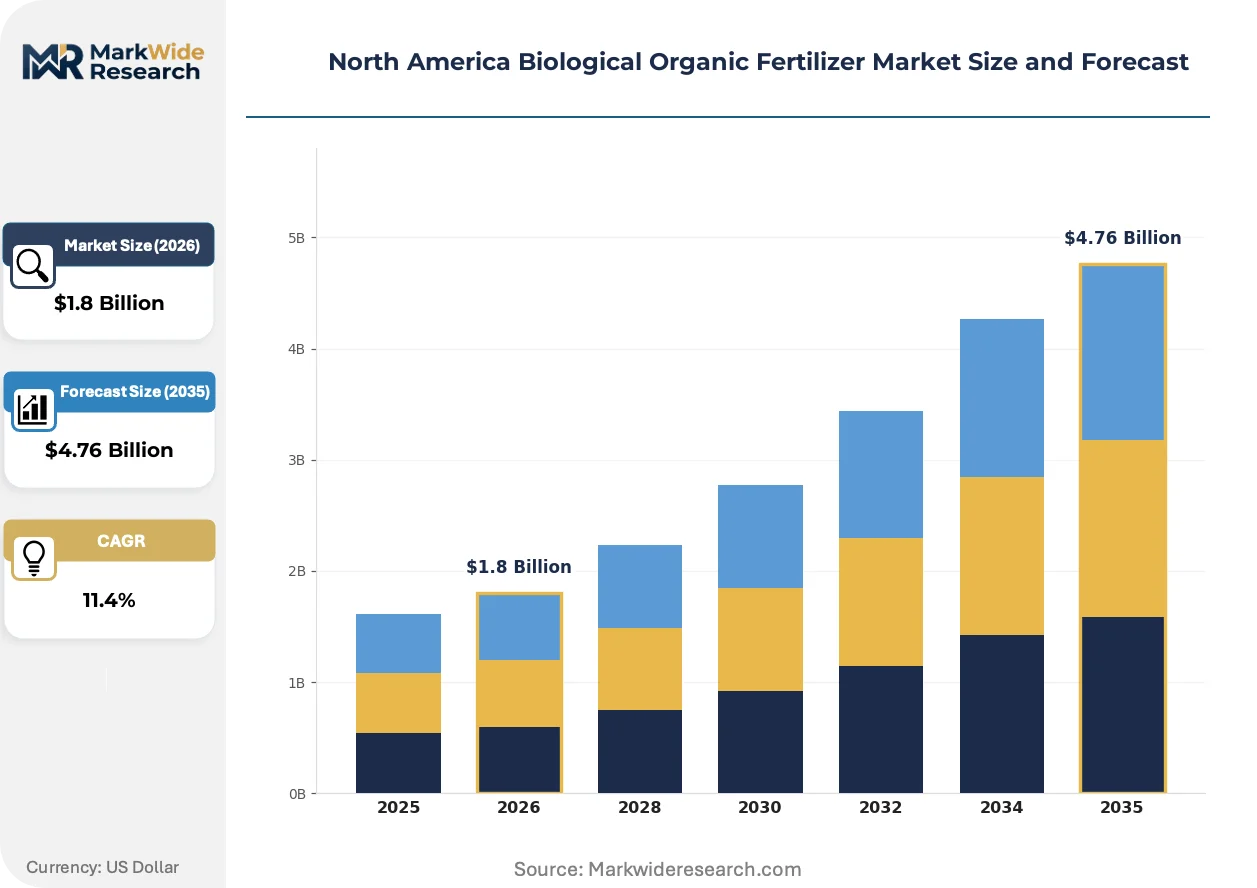
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compost, Manure, Biochar, Seaweed Extract Application Method: Soil Application, Foliar Application, Drip Irrigation, Seed Treatment Crop Type: Cereals, Fruits, Vegetables, Turf End User: Agricultural Producers, Gardeners, Nurseries, Greenhouses |
| Companies Covered | Nutrien Ltd, Sustane Natural Fertilizer, BioSTAR Renewables, True Organic Products, California Organic Fertilizers, Plantin, Helena Agri-Enterprises, The Scotts Miracle-Gro Company, The Andersons, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biological Organic Fertilizer Market Evolving Landscape
Precision agriculture technologies are converging with biological input manufacturing, reshaping how nutrient management services bundle hardware, data analytics, and certified organic amendments into integrated offerings.
Sensor-enabled application equipment is digitizing nutrient delivery across large-scale agricultural producers. Midwest Corn Belt operators are retrofitting spreaders with real-time organic matter sensors to adjust application rates on-the-go. Variable-rate technology is compressing the efficiency gap between biological and synthetic fertilizer systems by matching input placement to soil microbial activity zones.
California's Department of Food and Agriculture administers material registration requirements that filter smaller unverified suppliers from commercial channels. The state's additional compliance layer beyond federal standards creates a two-tier market structure. Premium manufacturers with dedicated regulatory affairs teams capture shelf space in agricultural co-op networks while unregistered competitors exit formal distribution.
Buyer concentration among agricultural co-ops is consolidating procurement decisions for biological inputs. Large-scale Midwest producers now negotiate multi-year supply agreements directly with compost manufacturers, bypassing traditional retail intermediaries. This direct contracting pattern is most visible in Iowa and Illinois grain operations where volume commitments secure priority access to certified organic waste streams.
North America Biological Organic Fertilizer Market Segmentation
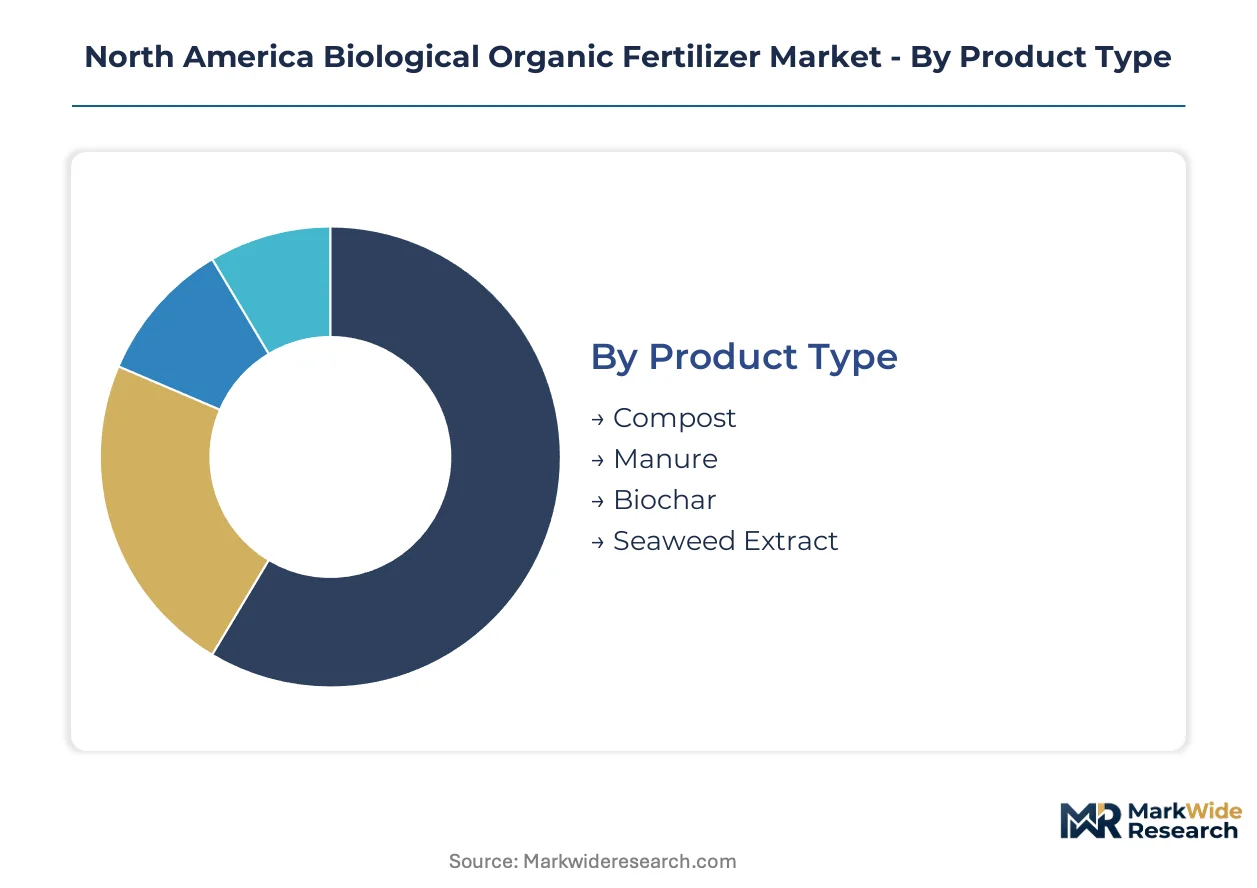
Segmentation in North America's biological organic fertilizer market reveals how product chemistry, application technology, and customer scale interact to create distinct competitive arenas. Each dimension carries unique regulatory exposure and margin structures that shape manufacturer positioning.
Product Type:
Mature compost and manure products dominate volume flows, while emerging categories like biochar and seaweed extract capture premium positioning through differentiated agronomic claims.
- Compost:Stabilized organic matter derived from municipal green waste and agricultural residues, typically containing 1-3% nitrogen and 40-60% organic carbon. Midwest Corn Belt grain operations drive bulk procurement through direct contracts with waste processors seeking diversion compliance under state landfill reduction mandates.
- Manure:Animal waste processed through anaerobic digestion or aerobic composting to reduce pathogens and odor, with nutrient profiles varying by livestock source. Dairy and poultry operations in Wisconsin and Pennsylvania supply concentrated demand from nearby row-crop farmers facing EPA watershed restrictions on synthetic nitrogen.
- Biochar:Carbon-rich residue from pyrolysis of woody biomass, valued for soil carbon sequestration potential and cation exchange capacity improvement.
- Seaweed Extract:Marine-derived biostimulants concentrated through cold-press or alkaline extraction, commanding premium pricing in California and Florida specialty crop systems.
Compost retains volume leadership; seaweed extract holds the steepest expansion curve.
Application Method:
Cost tier stratification separates capital-intensive precision delivery from equipment-light broadcast methods, with mid-tier systems gaining traction among scale-transitioning operations.
- Soil Application:Broadcast or incorporated placement using modified spreaders, dominating Midwest commodity grain systems where equipment compatibility minimizes adoption friction.
- Foliar Application:Spray delivery of diluted extracts directly to plant tissue, enabling rapid micronutrient correction in high-value California strawberry and Florida citrus operations.
- Drip Irrigation:Liquid biological formulations injected through existing greenhouse and orchard infrastructure, concentrated among Pacific Northwest vegetable producers.
- Seed Treatment:Microbial inoculants applied to planting stock, expanding fastest among organic corn and soybean growers seeking early root colonization.
Soil application maintains installed-base dominance; drip irrigation integration climbs the fastest as greenhouse operators retrofit infrastructure.
Crop Type:
Customer margin profiles segment sharply between thin-margin commodity systems and premium-priced specialty production, with input manufacturers calibrating formulation complexity accordingly.
- Cereals:Corn, wheat, and soybean systems across Iowa, Illinois, and Nebraska, where biological inputs compete primarily on cost parity with synthetic alternatives.
- Fruits:Tree and vine crops in California Central Valley and Washington Yakima Valley, where organic certification premiums justify higher input spending.
- Vegetables:Fresh market and processing crops in Florida, Arizona, and Mexico-border regions, with compressed growing cycles demanding reliable nutrient timing.
- Turf:Golf courses, sports fields, and residential lawns, concentrated in affluent suburban corridors with aesthetic performance requirements.
Cereals command absolute volume; fruits generate the highest per-acre input spending.
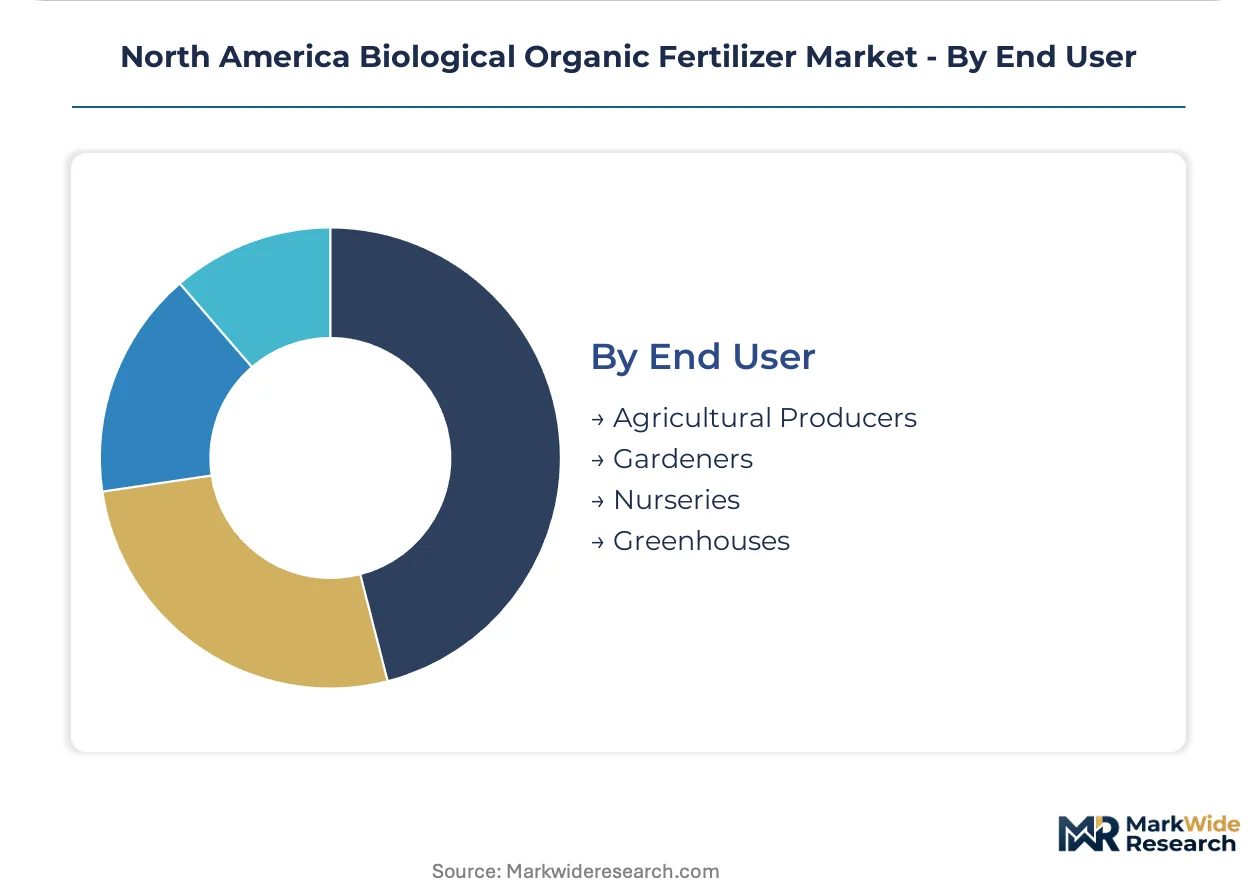
End User:
Procurement scale divides the market between institutional buyers with technical staff and dispersed consumers relying on retail guidance, with distribution infrastructure configured accordingly.
- Agricultural Producers:Large-scale Midwest and Plains operations purchasing through co-op networks and direct manufacturer relationships, driving standardization in product specifications.
- Gardeners:Residential consumers accessing bagged retail products through home improvement chains and garden centers, with purchasing decisions influenced by organic labeling claims.
- Nurseries:Container and field stock producers requiring consistent media amendments, concentrated in Oregon, Michigan, and Texas propagation centers.
- Greenhouses:Controlled-environment vegetable and ornamental operations, predominantly in Ontario, Quebec, and northeastern US states with year-round production requirements.
Agricultural producers anchor procurement volume; greenhouses are expanding most quickly as controlled-environment agriculture scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California specialty crop corridors while Midwest commodity grain operations compress margins through volume contracting. Canadian regulatory registration timelines create supply bottlenecks that advantage pre-positioned suppliers. Mexico's northern irrigation districts emerge as contested expansion zones for cross-border waste-to-fertilizer processors.
United States
California Central Valley strawberry and almond growers drive premium-grade compost procurement under the state's Department of Food and Agriculture material registration regime. EPA Clean Water Act enforcement tightens synthetic nitrogen application windows across Chesapeake Bay watershed states. Iowa and Illinois grain operations anchor bulk volume through direct multi-year supply agreements with municipal waste processors.
Canada
Ontario and Quebec greenhouse operators retrofit drip irrigation systems for liquid biological formulations to meet CFIA fertilizer registration standards. Provincial nutrient management regulations in the Great Lakes basin restrict manure spreading seasons, accelerating demand for stabilized compost alternatives. British Columbia's organic vegetable exporters in the Fraser Valley secure certified input supply chains for EU market access compliance.
Mexico
Sonora and Baja California vegetable producers serving US winter markets adopt California-registered biological inputs to maintain organic certification continuity. CONAFOR forestry waste programs supply pyrolysis feedstock for biochar manufacturing targeting carbon credit-eligible operations. Jalisco's berry expansion zones attract cross-border compost distributors from California waste-to-value processors.
North America Biological Organic Fertilizer Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying verified organic matter streams. The vendor base organizes around three functional layers: agricultural co-ops bundling biological inputs with precision services, municipal waste processors securing long-term feedstock contracts, and specialty extract manufacturers serving high-value crop systems. Consolidation pressure runs through direct contracting between large-scale Midwest producers and compost manufacturers, bypassing traditional retail channels. Strategic partnerships linking waste generators to fertilizer processors dominate capacity expansion moves.
Among North American platform operators, Nutrien Ltd and The Andersons exemplify co-op-anchored distribution models integrating biological fertilizers with agronomic advisory services. California Organic Fertilizers occupies a position within the premium-grade compost segment serving specialty crop certification requirements. Helena Agri-Enterprises represents the crop-input retailer archetype bridging manufacturer portfolios to regional grower networks.
| Leading Market Players |
|---|
| Nutrien Ltd |
| Sustane Natural Fertilizer |
| BioSTAR Renewables |
| True Organic Products |
| California Organic Fertilizers |
| Plantin |
| Helena Agri-Enterprises |
| The Scotts Miracle-Gro Company |
| The Andersons |
| Others |
Value Network & Pricing Analysis
Municipal organic waste processors in Ontario and Quebec anchor upstream supply, concentrating margin capture among CFIA-registered manufacturers with dedicated regulatory affairs teams while unverified competitors exit formal channels. California's Department of Food and Agriculture material registration regime filters smaller suppliers, creating a two-tier structure where premium compost commands certification-linked pricing.
Pricing Analysis
The customization-premium spread separates standard municipal compost contracts from configured-to-order seaweed extract formulations for California strawberry operations. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with USDA Organic and CFIA registration tiers commanding 15-40% markups over unverified alternatives. Cost compression in bulk Midwest grain markets is intensifying because direct producer-processor contracting bypasses traditional retail markups. Agricultural co-ops demonstrate highest price sensitivity due to thin commodity margins, while greenhouse operators show lowest sensitivity given precision delivery requirements.
Supply Chain Analysis
Export-control regimes on pyrolysis technology from Germany and Japan limit biochar manufacturing equipment flows into North American markets. Geographic supply concentrates in Canada for peat and forestry waste, Mexico for seasonal vegetable production residue, and US Midwest for corn stover and manure. Raw material dependencies include municipal green waste streams, dairy and poultry manure, and marine biomass for seaweed extraction. Single-source vulnerability runs through California's Central Valley compost processors serving specialty crop certification requirements. Distribution runs through agricultural co-op networks bundling biological inputs with precision agriculture advisory services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biological organic fertilizers represent a service-attach opportunity where recurring soil testing and agronomic advisory layers expand faster than standalone product sales. Precision agriculture bundling now generates higher lifetime value per acre than commodity compost transactions.
For Market Incumbents: Insulate margin position by deepening backward integration into municipal organic waste streams through long-term diversion contracts with Ontario and Quebec municipal programs. Accelerate CFIA and California Department of Food and Agriculture registration investment to filter unverified competitors from co-op shelf space. Controlled-release synthetic fertilizers threaten substitution in Iowa and Illinois grain operations; defend by retrofitting spreader fleets with sensor-enabled variable-rate technology. For New Entrants and Emerging Players: Pursue white-space positioning in Mexico's Sonora and Baja California vegetable corridors serving US winter organic markets, where California-registered input continuity commands premium placement. Target Pacific Northwest greenhouse drip irrigation retrofit demand for liquid biological formulations. Seed treatment microbial inoculants for organic corn and soybean growers offer the most penetrable entry vector through direct-to-producer digital agronomy platforms. For Investors and Strategic Acquirers: Capital is best deployed toward waste-to-value processors with captive municipal feedstock contracts and established regulatory registration across multiple state and provincial jurisdictions. Long-term viability favors operators with integrated precision agriculture service layers rather than standalone commodity compost manufacturers. Watch CFIA fertilizer registration timeline compression as the signal indicating when cross-border supply bottlenecks ease and competitive intensity accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Waste Streams | Captive supply of municipal organic waste secures feedstock priority under Ontario landfill reduction mandates. |
| Precision Agriculture Service Bundling | Nutrien Ltd's retail footprint demonstrates how biological inputs attach to sensor-enabled variable-rate application contracts. |
| CFIA Registration Acceleration | Pre-positioned suppliers capture Ontario and Quebec greenhouse demand while competitors face compliance bottlenecks. |
| Drip Irrigation Formulation Development | Pacific Northwest vegetable producers retrofit greenhouse infrastructure for liquid biological nutrient delivery. |
| Carbon Credit Protocol Alignment | Biochar manufacturers targeting British Columbia organic exporters secure EU market access compliance premiums. |
Research Methodology
A standing panel of compost facility operations managers, agricultural co-op procurement directors, CFIA regulatory affairs specialists, and precision agriculture agronomists provided ongoing calibration across primary interview cycles. Secondary validation drew from USDA National Organic Program input databases, EPA Clean Water Act enforcement records, California Department of Food and Agriculture material registrations, and municipal waste diversion compliance reports. Bottom-up volume modeling triangulated against top-down spending estimates from agricultural co-op financial disclosures.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product chemistry tier, application method, crop type margin profile, and end-user procurement scale. CAGRs derived from historical adoption curves in California specialty crop systems and Midwest grain operation transitions, calibrated against state-level nutrient management plan implementation timelines and carbon credit protocol development trajectories.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity price cycles and municipal budget constraints for waste diversion programs would shift the trajectory. Forecasts reflect assumptions on regulatory enforcement consistency and precision agriculture hardware adoption rates. Material shifts in EPA watershed restriction scope or USDA Organic certification requirement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
United States Biocontrol Agents Market
Bio-Agriculture
India Agricultural Biologicals Market
Bio-Agriculture
Global Biofortification Market
Bio-Agriculture
Indonesia Biopesticides Market
Bio-Agriculture
Asia-Pacific Biostimulants Market
Bio-Agriculture
China Feed Probiotics Market
Bio-Agriculture
Bio-Based Levulinic Acid Market
Bio-Agriculture
Plant Based Biosurfactants Market
Bio-Agriculture
Bio-Insecticide Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
Biochar Machine Market
Bio-Agriculture
Europe Biopesticides Market
Bio-Agriculture
United Kingdom Biopesticides Market
Bio-Agriculture
Biostimulants Market
Bio-Agriculture
Biological Control Market
Bio-Agriculture
Middle East and Africa Biopesticides Market