
 Nannochloropsis Market | 2026-2036
Nannochloropsis Market Size, Share, and Industry Trends Forecast 2026-2036
Nannochloropsis Market Intelligence
Multi-source algae procurement is expanding as aquaculture feed formulators diversify beyond traditional marine ingredients. Corbion sustains one of the largest fermentation-based supply networks for omega-3 lipids, while Cellana Inc. anchors its position through closed-system photobioreactor operations in Hawaii. Algatechnologies competes on astaxanthin and nannochloropsis co-production, leveraging Israeli desert sunlight for year-round cultivation.
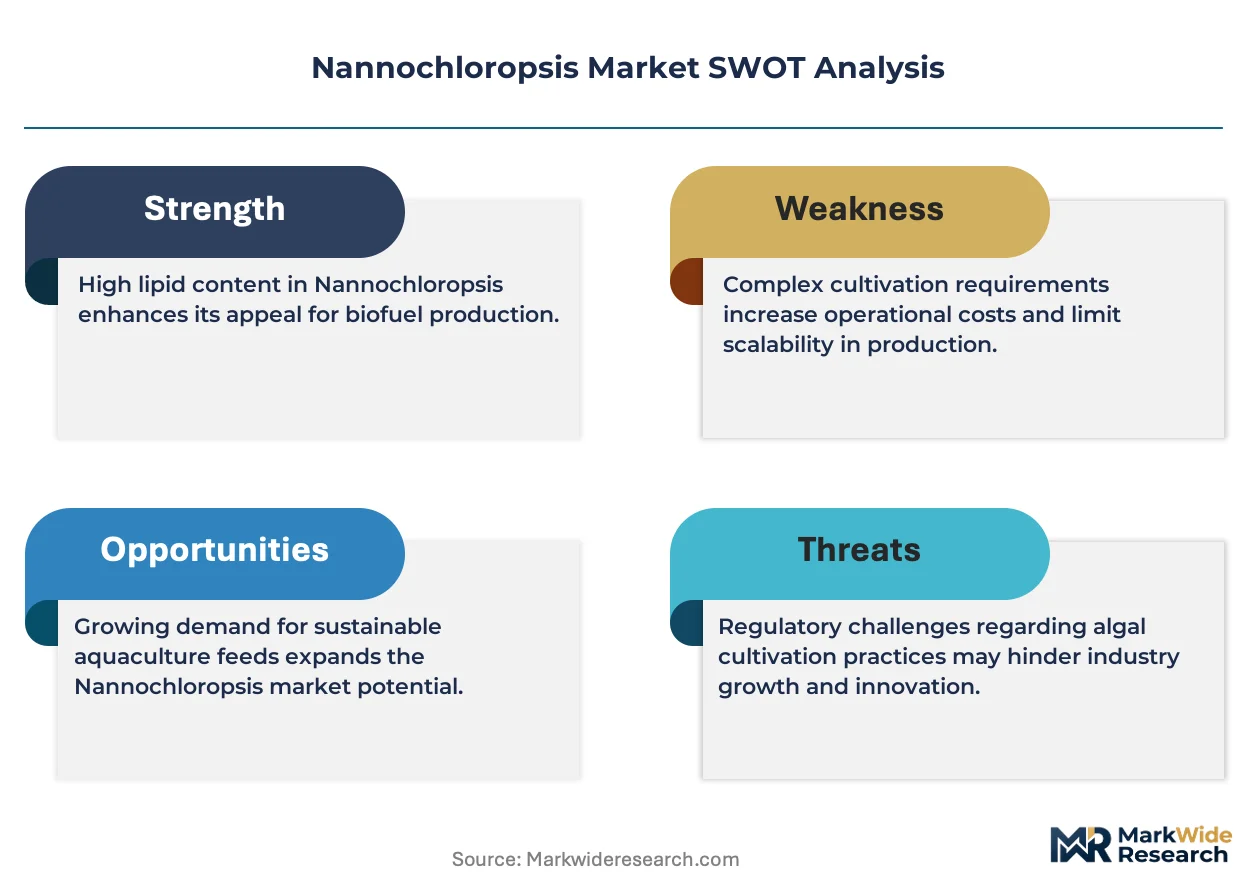
Nannochloropsis constitutes a genus of marine microalgae distinguished by high eicosapentaenoic acid content and rapid lipid accumulation under saline conditions, typically cultivated in photobioreactors or open raceway ponds for extraction of omega-3 oils and whole-cell biomass. The organism serves primarily as a sustainable replacement for fish-derived oils in aquafeed and as a feedstock for third-generation biofuel refining. Oil extract commands the dominant margin pool due to downstream pharmaceutical and nutraceutical purification requirements, while aquaculture feed application leads volume offtake as shrimp and salmon producers reformulate diets. Photobioreactor deployment attracts capital despite higher unit costs because it delivers consistent EPA titers and reduces contamination risk compared to open pond alternatives.
EMA feed additive guidelines and EU Green Deal sustainability targets are tightening permissible thresholds for wild-caught fishmeal inclusion, directly accelerating algae oil substitution timelines. REACH compliance for novel lipid extracts adds registration burdens that favor established producers with dedicated regulatory affairs capacity. FDA Generally Recognized as Safe determinations for algal EPA influence market access for dietary supplement positioning in the United States. Stakeholders must monitor how FAO aquaculture certification schemes evolve their ingredient traceability requirements, since these standards increasingly determine offtake eligibility for premium seafood supply chains.
Market Dynamics
EU Green Deal sustainability targets and EMA feed additive guidelines are compressing substitution timelines for fish-derived omega-3 oils, redirecting capital toward algae fermentation infrastructure and photobioreactor deployments.
Growth Catalysts
- EU Green Deal mandates:Binding thresholds on wild-caught marine ingredients in aquafeed are accelerating algae oil adoption timelines across Norwegian salmon operations.
- Photobioreactor technology:Closed-system cultivation delivers consistent EPA titers with reduced contamination risk compared to open raceway alternatives.
- Aquaculture feed reformulation:Shrimp and salmon producers in Southeast Asia are scaling commercial offtake agreements for algae-based lipid substitutes.
Market Restraints
- Input cost volatility:Seawater salinity management and artificial lighting requirements drive operational expenditure swings in photobioreactor facilities.
- Supply concentration risk:Fermentation-based EPA production clusters among a limited set of European and North American biotechnology operators.
- REACH registration friction:Novel lipid extract compliance burdens favor established producers with dedicated regulatory affairs capacity.
Strategic Opportunities
- Underpenetrated Brazilian aquaculture:Tilapia and native species producers lack established algae oil supply contracts despite expanding production volumes.
- Third-generation biofuel feedstock:Nannochloropsis lipid fractions are attracting refinery investment for renewable diesel and aviation fuel applications.
- Japanese nutraceutical channel expansion:PMDA functional food approvals create pathway for EPA-fortified consumer products beyond pharmaceutical positioning.
Industry Challenges
- Phycologist talent scarcity:Specialized algae strain optimization and cultivation engineering expertise concentrates among academic and government research institutions.
- Photobioreactor capex intensity:Stainless steel bioreactor vessels, LED array installations, and climate control systems demand substantial upfront capital deployment.
- FAO certification alignment:Aquaculture stewardship council traceability requirements for premium seafood supply chains complicate biomass sourcing documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nannochloropsis Market |
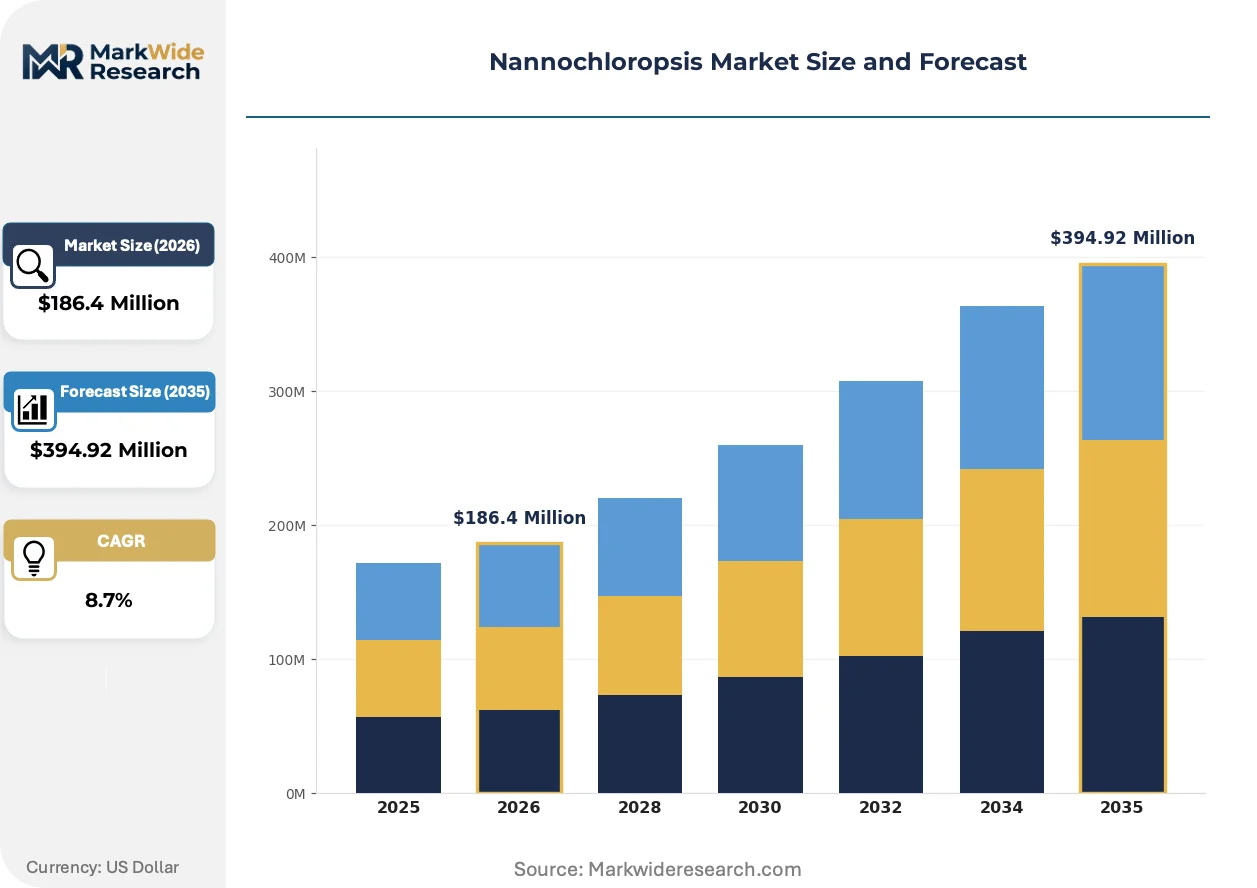
| Market Size in 2026 | $186.4 Million |
| Market Size in 2035 | $394.92 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dried Powder, Oil Extract, Live Culture, Freeze-Dried Flakes Application: Aquaculture Feed, Biodiesel Production, Nutraceuticals, Animal Nutrition End User: Fish Farmers, Biofuel Manufacturers, Dietary Supplement Companies, Livestock Producers Deployment: Photobioreactor, Open Pond, Closed System, Hybrid Cultivation |
| Companies Covered | Corbion, Cyanotech Corporation, AlgaEnergy, Cellana Inc., BASF SE, Lyxia Corporation, Reed Mariculture, Algatechnologies, iwi Life, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nannochloropsis Market Strategic Shifts & Innovations
Algae cultivation systems are bifurcating between high-control photobioreactor architectures and cost-optimized open pond designs, with downstream purification technology determining margin capture rather than biomass yield alone.
Continuous harvesting technology is expanding into commercial nannochloropsis operations, enabling real-time lipid extraction without batch disruption. Norwegian integrated aquaculture operators are piloting these systems at industrial scale. The approach is compressing working capital cycles and reducing biomass degradation losses compared to conventional centrifuge-based harvest methods.
REACH registration requirements for novel lipid extracts are tightening purity and documentation standards across European markets. ECHA compliance timelines now extend 18-24 months for new EPA concentrate entrants. Algae oil suppliers are responding by pre-submitting technical dossiers and establishing dedicated regulatory affairs functions in Brussels and Helsinki.
Salmon feed formulators are consolidating supplier relationships around dual-source omega-3 procurement models. Norwegian and Chilean farming operations now require algae oil commitments alongside residual fish oil allocations in contract negotiations. This behavioral shift is most visible in long-term offtake agreements spanning three to five production cycles.
Nannochloropsis Market Segmentation
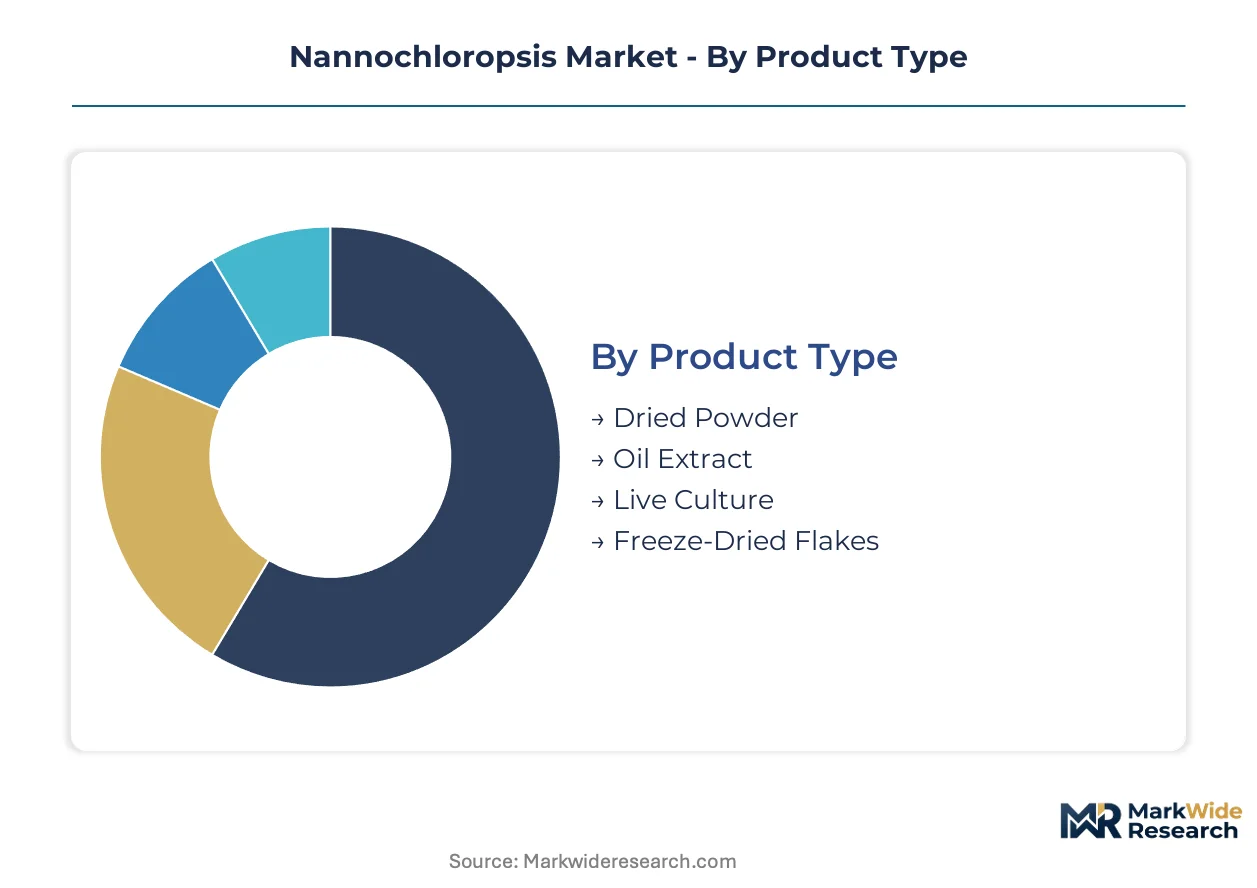
Nannochloropsis suppliers structure their portfolios around lipid extraction economics versus whole-cell biomass throughput. Segmentation choices directly determine capital allocation between high-margin pharmaceutical purification and volume-oriented aquafeed supply contracts.
Product Type:
Oil extract commands premium positioning through downstream pharmaceutical processing requirements, while dried powder dominates tonnage offtake in commodity feed channels.
- Oil Extract:Refined EPA concentrates exceeding 50% purity serve pharmaceutical and high-grade nutraceutical formulations. Norwegian salmon feed formulators now mandate algae oil inclusion in long-term procurement contracts as fish oil substitution accelerates under EU Green Deal thresholds.
- Dried Powder:Whole-cell biomass with intact cell walls delivers cost-efficient omega-3 delivery for shrimp and tilapia operations. Southeast Asian aquaculture clusters in Vietnam and Indonesia absorb the majority of global powder volumes as farmed shrimp production expands.
- Live Culture:Fresh nannochloropsis suspensions support hatchery-stage marine larvae nutrition and rotifer enrichment protocols.
- Freeze-Dried Flakes:Shelf-stable formats target ornamental fish breeders and specialized aquarium markets requiring extended storage stability.
Mature deployment sits with Oil Extract. Newer deployment is concentrated in Dried Powder.
Application:
Customer procurement patterns split between reformulation mandates in established aquaculture and experimental offtake in emerging biofuel channels.
- Aquaculture Feed:Salmon and shrimp diet reformulation drives the steepest expansion trajectory as marine ingredient inclusion caps tighten across EU and Norwegian regulatory frameworks. Integrated farming operations in Chile and Norway now specify algae-derived lipids in three-to-five-cycle supply agreements.
- Nutraceuticals:EPA concentrates for dietary supplements require pharmaceutical-grade purification infrastructure. Cellana and Corbion fermentation networks supply this channel with consistent titer specifications that open pond cultivation cannot match.
- Biodiesel Production:Third-generation renewable diesel and aviation fuel applications attract refinery investment for nannochloropsis lipid fractions.
- Animal Nutrition:Poultry and swine feed trials evaluate algae biomass as protein and pigment sources beyond omega-3 delivery.
Contract maturity concentrates in Aquaculture Feed. Pilot-scale validation dominates Biodiesel Production.
End User:
Procurement sophistication varies sharply between consolidated aquaculture operators and fragmented livestock segments.
- Fish Farmers:Norwegian and Chilean salmon producers leverage scale to secure dedicated algae oil allocations. Mowi and Cermaq procurement teams now require dual-source omega-3 documentation for ASC certification compliance.
- Dietary Supplement Companies:US and Japanese nutraceutical brands source EPA concentrates through FDA GRAS and PMDA functional food pathways respectively. Regulatory dossier requirements favor established fermentation suppliers with dedicated compliance capacity.
- Biofuel Manufacturers:Refinery operators evaluate algae lipid fractions for renewable diesel blending.
- Livestock Producers:Poultry and cattle operations represent underpenetrated demand with limited established supply relationships.
Integrated supply relationships concentrate with Fish Farmers. Emerging procurement activity clusters in Biofuel Manufacturers.
Deployment:
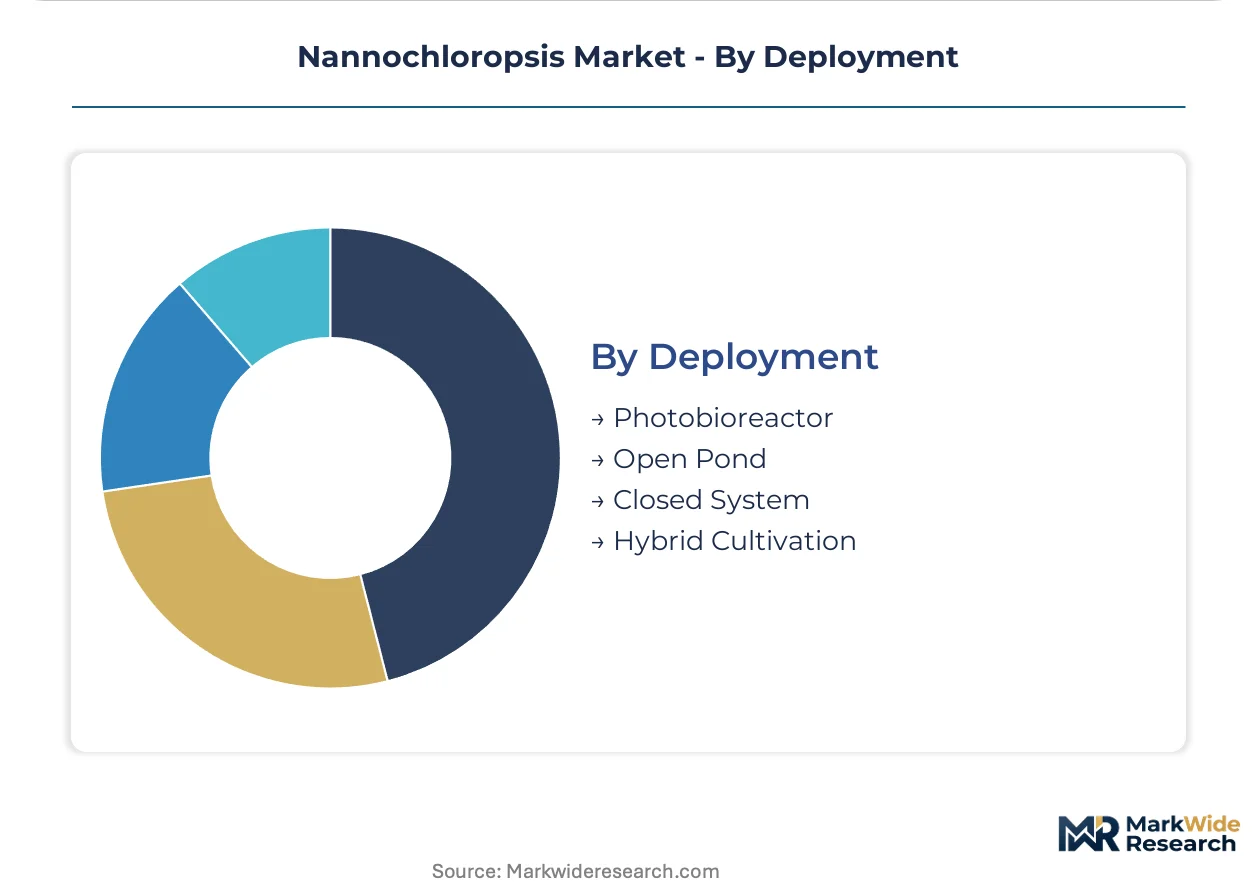
Capital intensity and contamination risk define the technology selection calculus across production geographies.
- Photobioreactor:Closed tubular or flat-panel systems deliver consistent EPA titers and exclude invasive species. Israeli desert installations and Hawaiian operations by Cellana demonstrate year-round production despite higher unit capital costs.
- Open Pond:Raceway designs minimize infrastructure investment but suffer seasonal productivity swings and contamination losses. Chinese and Indian producers favor this approach for domestic aquafeed biomass.
- Closed System:Fermentation-based heterotrophic cultivation by Corbion and similar operators achieves highest cell densities and lipid fractions.
- Hybrid Cultivation:Combined phototrophic and heterotrophic phases optimize capital efficiency for specific strain performance targets.
Commercial scale concentrates in Photobioreactor and Open Pond. Technology validation efforts focus on Hybrid Cultivation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal saline aquaculture zones and photobioreactor installations cluster along temperate shorelines with established omega-3 processing infrastructure. Norway, Chile, China, Israel, and the United States host the dominant production and consumption nodes.
Norway
Salmon farming operations in Bergen and Trondheim drive algae oil procurement as Mowi and Cermaq reformulate feed rations. EU Green Deal marine ingredient caps apply directly through EEA alignment, accelerating substitution timelines. Integrated aquaculture clusters along the Norwegian coast now mandate dual-source omega-3 documentation for ASC certification compliance.
Chile
Atlantic salmon producers in the Los Lagos and Aysén regions expand algae oil contracts to meet export market sustainability requirements. Chile's national fisheries service enforces traceability protocols that favor certified alternative ingredients. Puerto Montt processing hubs concentrate pilot-scale photobioreactor validation projects for local biomass supply.
China
Domestic shrimp aquaculture in Guangdong and Hainan provinces absorbs dried nannochloropsis powder for cost-efficient feed supplementation. The Ministry of Agriculture and Rural Affairs promotes microalgae cultivation under rural revitalization programs. Qingdao marine biotechnology institutes anchor strain optimization research for industrial-scale deployment.
Israel
Negev Desert photobioreactor facilities exploit year-round solar irradiance for consistent EPA production. National bioeconomy initiatives under the Israel Innovation Authority fund algae cultivation scale-up. Kibbutz-based agrotech clusters near Eilat demonstrate closed-system integration with desalination infrastructure.
United States
Hawaiian photobioreactor operations supply consistent titer specifications for pharmaceutical-grade EPA concentrates. FDA GRAS determinations for algal omega-3 facilitate dietary supplement market access. Kona marine science parks host cultivation engineering trials linking academic research to commercial fermentation partnerships.
Nannochloropsis Market Key Industry Players
Global majors compete with regional champions across cultivation technology and regulatory compliance capacity. The vendor base organizes around fermentation specialists, photobioreactor operators, and open-pond biomass producers. Three archetypes dominate: biotechnology platforms with pharmaceutical-grade purification infrastructure, desert-solar photobioreactor specialists, and coastal aquaculture-integrated suppliers. Competitive moves concentrate on long-term offtake contracting and REACH registration dossier pre-submission.
Within the fermentation-based tier, Corbion anchors European supply networks with heterotrophic cultivation scale. Cellana Inc. exemplifies photobioreactor deployment in high-insolation coastal environments. Algatechnologies occupies a position bridging astaxanthin co-production with nannochloropsis omega-3 supply, leveraging Israeli desert installations for year-round output consistency.
| Leading Market Players |
|---|
| Corbion |
| Cyanotech Corporation |
| AlgaEnergy |
| Cellana Inc. |
| BASF SE |
| Lyxia Corporation |
| Reed Mariculture |
| Algatechnologies |
| iwi Life |
| Others |
Cost & Logistics Intelligence
Photobioreactor technology maturation is compressing production economics while concentrating supply among operators with capital access, simultaneously reshaping cost structures and supplier power dynamics across omega-3 lipid markets.
Pricing Analysis
Regulatory compliance bundling separates REACH-registered EPA concentrates from unregistered commodity biomass, with certification tier and volume scale as primary price differentiation drivers. Cost compression in dried powder segments is intensifying because Chinese and Indian open-pond producers expand capacity. Shrimp feed formulators in Southeast Asia exhibit highest price sensitivity, while Norwegian salmon integrators prioritize titer consistency over unit cost.
Supply Chain Analysis
Biomass recycling and spent culture media recovery flows remain underdeveloped, constraining circular economy claims for most operators. Production gravity centers on Norway, Israel, and China, with fermentation inputs drawing from European biotechnology suppliers and LED array manufacturing anchored in East Asian electronics clusters. Single-source vulnerability concentrates in heterotrophic strain IP held by Corbion and limited fermentation partners. Distribution runs through aquafeed compounders with integrated oil extraction capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal compliance deadlines are compressing weaker open-pond operators out of premium supply chains, favoring consolidation around photobioreactor and fermentation platforms with regulatory affairs capacity.
For Market Incumbents: Deepen backward integration into desalination and renewable power infrastructure to lock in input cost advantages against emerging desert-solar competitors in the Middle East and North Africa. Prioritize REACH dossier pre-submission for next-generation EPA concentrates before ECHA review timelines extend further, defending market access against fermentation specialists with established Brussels regulatory functions. For New Entrants and Emerging Players: The mid-tier price gap between pharmaceutical-grade oil extracts and commodity dried powders offers white-space entry for aquafeed compounders seeking dual-source omega-3 documentation without purity premiums. Brazilian tilapia operations and Indonesian shrimp clusters present the most penetrable demand nodes given limited existing algae oil contracts. Pursue toll-processing partnerships with established photobioreactor operators rather than greenfield capex deployment. For Investors and Strategic Acquirers: Re-rating potential sits with Israeli desert-solar photobioreactor specialists given EU import dependency and EEA regulatory alignment accelerating Norwegian offtake commitments. Long-term viability over the next decade hinges on continuous harvesting technology commercialization and aviation fuel offtake scaling. Monitor FAO aquaculture certification scheme revisions for ingredient traceability requirements as the inflection signal determining premium supply chain eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Harvesting Technology Deployment | Norwegian salmon integrators Mowi and Cermaq pilot real-time lipid extraction to compress working capital cycles. |
| REACH Registration Dossier Pre-Submission | Established suppliers secure 18-24 month regulatory lead time over novel EPA concentrate entrants in European markets. |
| Desert-Solar Photobioreactor Expansion | Israeli operators leverage year-round irradiance to deliver consistent EPA titers unmatched by seasonal open-pond alternatives. |
| Aviation Fuel Feedstock Partnership | Refinery investment in nannochloropsis lipid fractions diversifies revenue beyond aquaculture feed commodity margins. |
| Dual-Source Omega-3 Procurement Mandates | Norwegian and Chilean farming operations now require algae oil commitments alongside residual fish oil in contract negotiations. |
Research Approach
FAO aquaculture production databases, ECHA REACH registration filings, and EU Green Deal policy documents formed the secondary backbone, cross-referenced with primary interviews of photobioreactor operations directors, salmon feed procurement leads at integrated aquaculture firms, and regulatory affairs specialists at fermentation-based omega-3 suppliers. Bottom-up cultivation capacity estimates and top-down aquafeed reformulation demand projections were triangulated against customs trade data for algae oil and dried biomass flows.
Historical trendline analysis of photobioreactor deployment costs and open-pond yield volatility informed the projection framework across the analysis window, with segmentation by product type, application, cultivation technology, and regional regulatory cluster. CAGRs were derived from elasticity modeling of fish oil substitution rates against EU marine ingredient caps and Norwegian ASC certification penetration. Strain optimization timelines and continuous harvesting technology adoption curves served as industry-specific forecast inputs.
Inputs from EMA feed additive guideline consultations and FAO certification scheme working groups were available through the study window; gaps in commercial-scale continuous harvesting operational data introduce uncertainty bands around working capital efficiency assumptions. Forecasts reflect documented substitution elasticity and regulatory compliance timelines. Practitioners should monitor ECHA novel food approval decisions and aviation fuel refinery offtake announcements for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
Biological Control Market
Bio-Agriculture
Bioethanol Yeast Market
Bio-Agriculture
Biological Seed Treatment Market
Bio-Agriculture
China Biocontrol Agents Market
Bio-Agriculture
Bio-Based Succinic Acid Market
Bio-Agriculture
US Biofungicide Market
Bio-Agriculture
Azotobacter Based Biofertilizer Market
Bio-Agriculture
Europe Bioethanol Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
Asia-Pacific Biofertilizers Market
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
Biochar Machine Market
Bio-Agriculture
Plant Based Biosurfactants Market
Bio-Agriculture
China Biostimulants Market