
 Bioactive Bone Grafts Market | 2026-2036
Bioactive Bone Grafts Market Size, Share, and Industry Trends Forecast 2026-2036
Bioactive Bone Grafts Market Outlook
Asset-light leasing models for advanced bioreactor manufacturing is reconfiguring capital barriers for mid-tier entrants in the bioactive bone grafts space. Medtronic Plc leverages its integrated supply chain to dominate synthetic scaffold production at scale. Stryker Corporation sustains technology leadership through specialized ceramic-hydroxyapatite formulations. Zimmer Biomet Holdings Inc. anchors its position via deep orthopedic clinic partnerships across major metropolitan hospital networks.
Bioactive bone grafts comprise synthetic, natural, composite, or allograft materials engineered with bioactive glass, calcium phosphate ceramics, or collagen matrices that stimulate osteogenesis, osteoconduction, and osteoinduction at defect sites. These grafts typically exhibit porosity exceeding 50% and surface-area-to-volume ratios optimized for vascular infiltration, serving primarily to bridge critical-sized bone defects where autograft harvest carries donor-site morbidity risks. Synthetic grafts command the largest revenue pool due to unlimited supply scalability and zero disease transmission risk, while composite formulations represent the fastest-expanding segment as surgeons demand dual-phase mechanical strength and biological signaling. Orthopedic surgery applications generate the deepest margin pools, though dental surgery grafts show accelerating uptake driven by implantology volume expansion.
The FDA's 510(k) premarket notification framework and the EU Medical Device Regulation (MDR) CE marking requirements impose stringent biocompatibility and clinical performance standards that filter substandard entrants while rewarding documented osteogenic efficacy. Health Canada and the Pharmaceuticals and Medical Devices Agency (PMDA) in Japan maintain parallel but distinct approval pathways that shape regional product launch sequencing and labeling claims. Stakeholders must monitor evolving regulatory harmonization between the FDA and EU MDR, as divergent evidentiary requirements for novel bioactive additives could fragment development roadmaps and delay cross-border commercialization.
Market Dynamics
Orthopedic clinics now demand graft formulations combining immediate mechanical load-bearing with sustained osteoinductive signaling, compressing product development cycles and forcing manufacturers to abandon single-phase material platforms.
Growth Catalysts
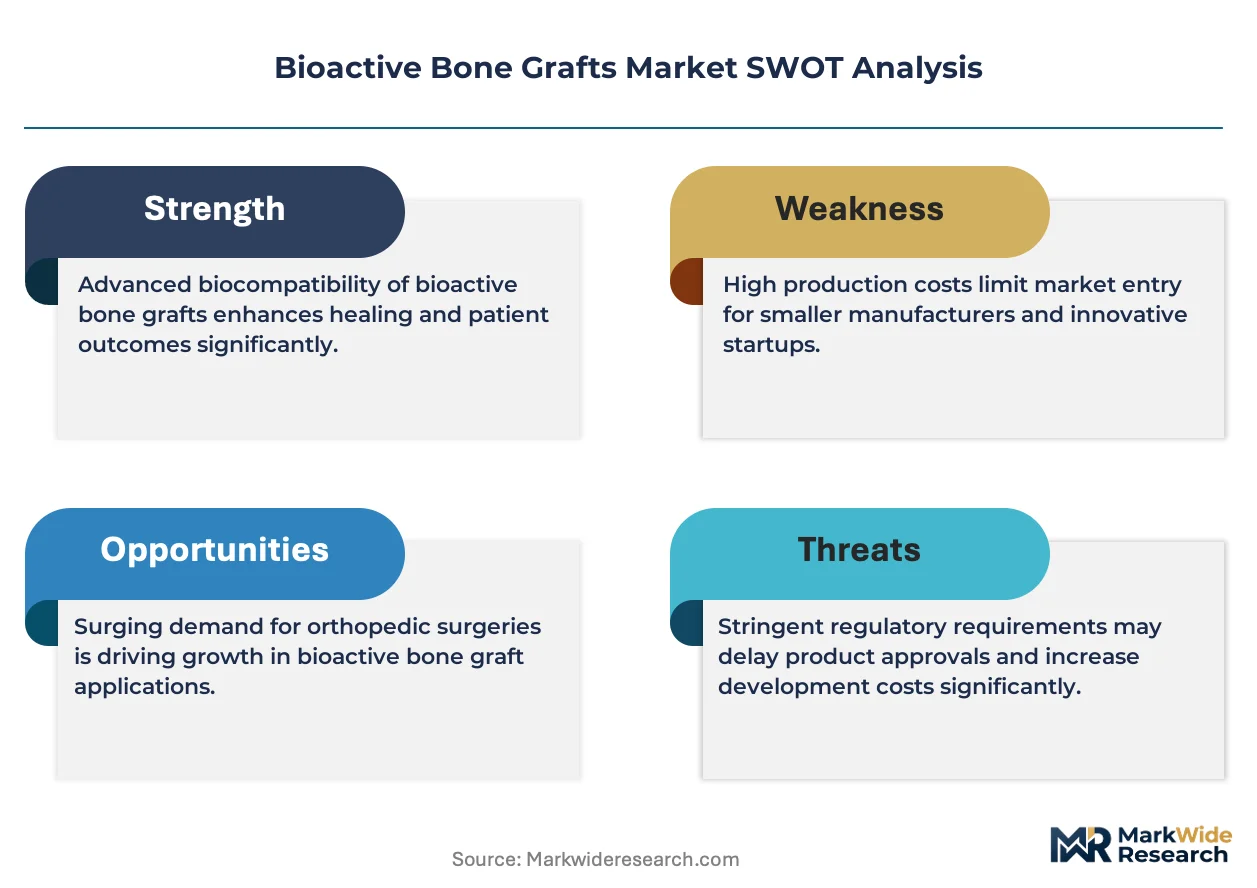
- FDA 510(k) Pathway:The streamlined premarket notification framework accelerates commercialization timelines for synthetic bone graft substitutes, reducing regulatory friction for osteoconductive scaffold entrants.
- Hospital Procurement Networks:United States health system consolidation creates concentrated purchasing power that favors suppliers with documented osteogenic efficacy and established reimbursement codes.
- Composite Formulation Advances:Dual-phase ceramic-collagen matrices now satisfy surgeon demands for simultaneous biological signaling and mechanical strength in critical-sized defect repair.
Market Restraints
- Raw Material Concentration:High-purity beta-tricalcium phosphate supply concentrates among limited specialty chemical processors, exposing manufacturers to input volatility and qualification delays.
- EU MDR Compliance Burden:The Medical Device Regulation's expanded clinical evidence requirements for bioactive additives extend CE marking timelines and elevate documentation costs for European market access.
- Autograft Persistence:Gold-standard iliac crest harvest maintains preference in trauma centers despite donor-site morbidity, constraining synthetic graft penetration in acute fracture settings.
Strategic Opportunities
- Dental Implantology Expansion:Rising edentulism rates and immediate-loading protocols in oral surgery create unmet demand for socket preservation grafts with rapid vascular integration.
- Japan PMDA Harmonization:Convergence between Japanese Pharmaceuticals and Medical Devices Agency standards and FDA osteoinductivity testing protocols enables streamlined multi-regional filing strategies.
- Point-of-Care Bioreactor Leasing:Asset-light manufacturing models permit mid-tier entrants to access advanced cell-seeding infrastructure without capital-intensive facility construction.
Industry Challenges
- Biomaterial Characterization Expertise:Scarce talent pools in surface-area-to-volume optimization and porosity engineering constrain R&D throughput for next-generation scaffold architectures.
- Multi-Jurisdictional Labeling Complexity:Divergent evidentiary requirements between FDA osteoinduction claims and EU MDR biological activity classifications fragment global product roadmaps.
- Legacy Sterilization Validation:Terminal sterilization protocols for bioactive glass formulations require extensive endotoxin and pyrogen testing that extends batch release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioactive Bone Grafts Market |
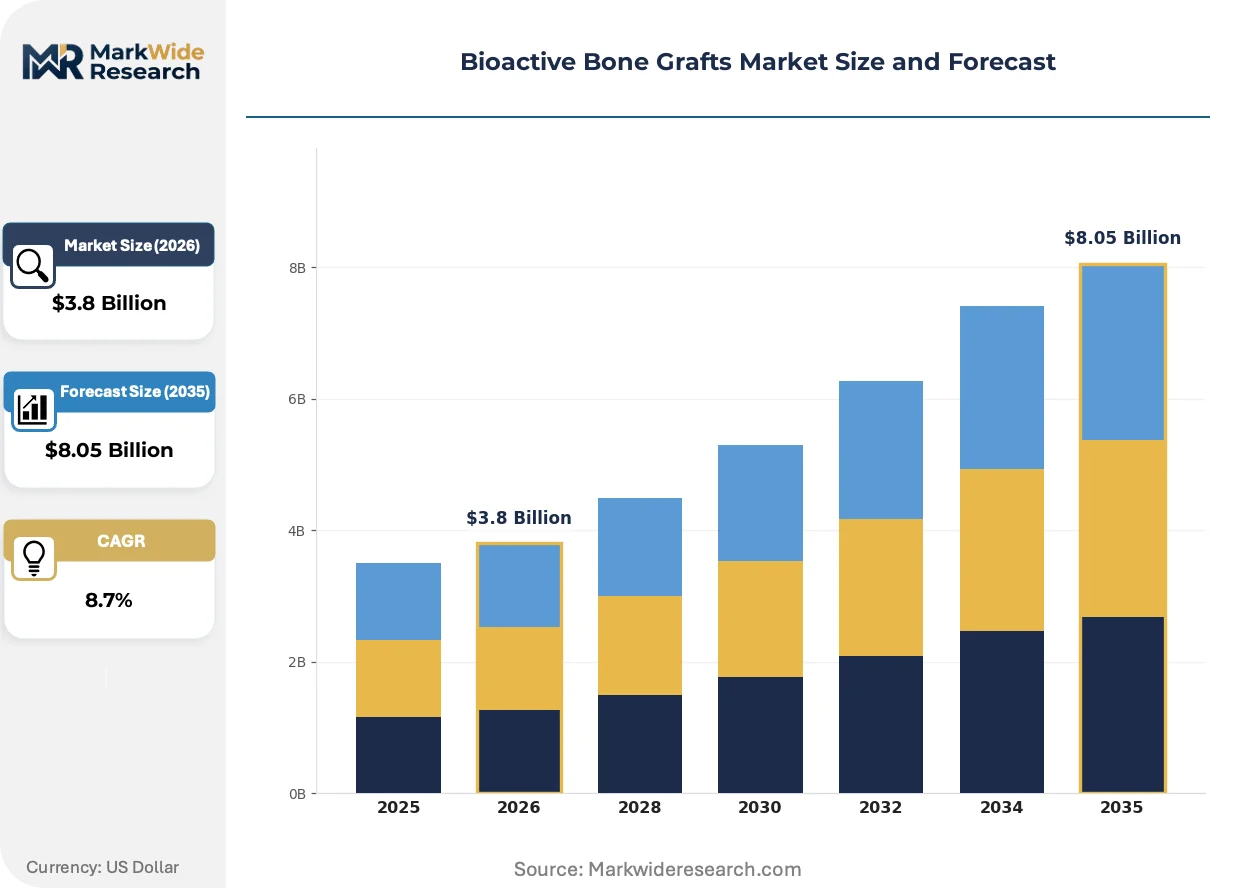
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Natural, Composite, Allograft End User: Orthopedic Clinics, Hospitals, Dental Clinics, Research Institutions Application: Orthopedic Surgery, Dental Surgery, Sports Medicine, Reconstruction Form: Granules, Putty, Gels, Scaffolds |
| Companies Covered | Medtronic Plc, Stryker Corporation, Zimmer Biomet Holdings Inc., NuVasive Inc., Orthofix Holdings Inc., Smith & Nephew Plc, Baxter International Inc., DePuy Synthes, Dentsply Sirona Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioactive Bone Grafts Market Strategic Shifts
Material science convergence with digital surgical planning is redefining graft selection criteria, shifting competitive advantage from supply scale toward patient-specific biological performance matching.
3D-printed patient-specific scaffolds with architected porosity gradients are collapsing the traditional trade-off between structural integrity and vascular infiltration kinetics. Academic medical centers in Germany and the United States now integrate these platforms into complex revision arthroplasty protocols. The technology is collapsing average hospital stay durations for pelvic reconstruction cases by eliminating secondary grafting procedures.
EU MDR Article 10 clinical evaluation requirements now mandate post-market surveillance data for bioactive additives with novel ion-release profiles. Manufacturers must maintain systematic literature review protocols and periodic safety update reports that extend far beyond legacy Medical Device Directive obligations. Synthetic graft categories with hydroxyapatite surface modifications face the steepest compliance cost escalation as notified bodies apply heightened scrutiny to resorption rate claims.
Orthopedic service line administrators now unbundle graft procurement from implant purchasing agreements, creating standalone vendor selection processes based on total episode cost metrics. Independent purchasing committees at metropolitan hospital networks in Texas and California evaluate osteoconductive performance per dollar against autograft harvest avoidance value. This behavioral shift is most visible in spine fusion procedures where bundled payment pilots from commercial payers reward biological integration speed over upfront material cost minimization.
Bioactive Bone Grafts Market Segmentation
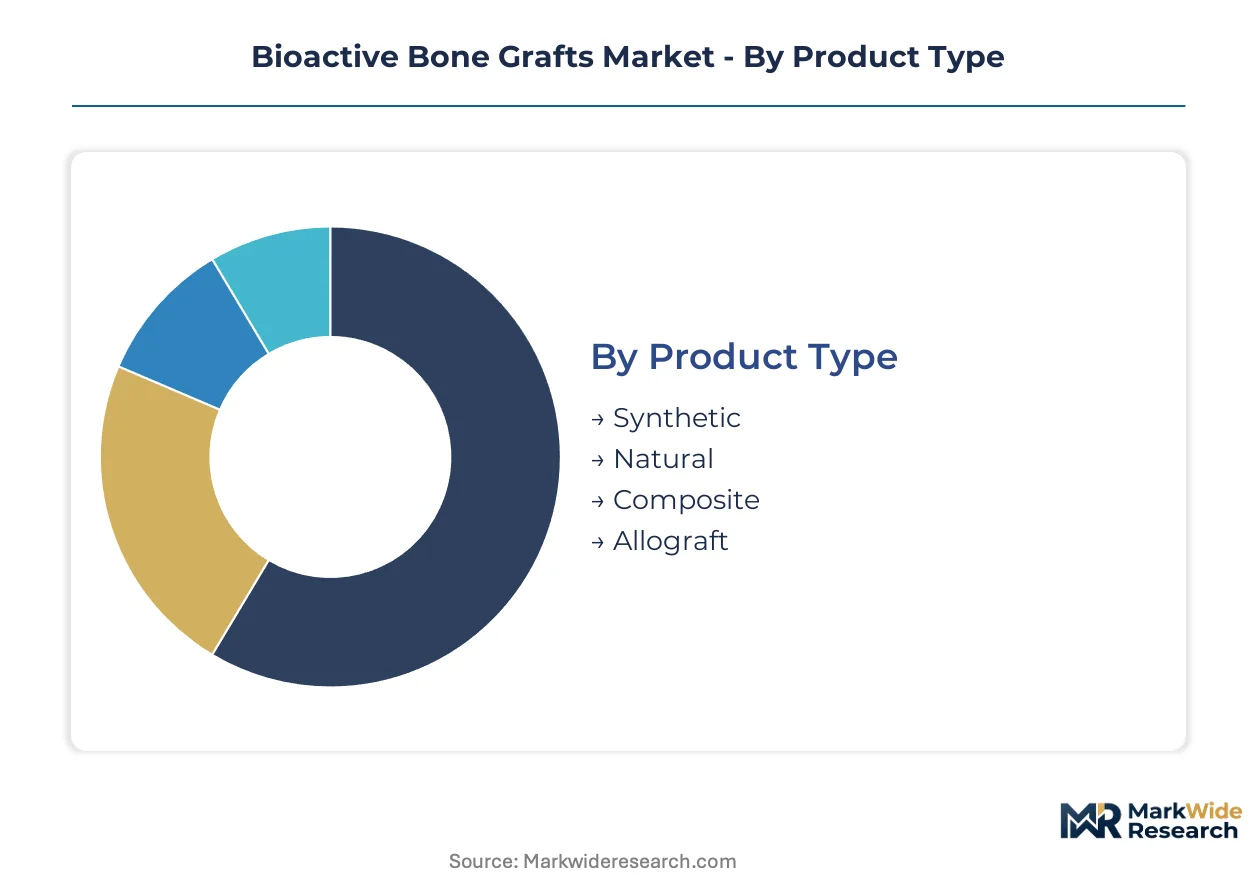
Product architecture in bioactive bone grafts determines clinical utility across defect types and surgical workflows. Segmentation reveals how material composition, delivery format, and care setting interact to shape procurement decisions and reimbursement pathways.
Product Type:
Synthetic formulations anchor mature revenue streams while composite platforms accelerate technical differentiation.
- Synthetic:Engineered from beta-tricalcium phosphate, hydroxyapatite, or bioactive glass with porosity exceeding 50% and controlled resorption kinetics. Hospital procurement networks in the United States concentrate demand here due to unlimited supply scalability, zero disease transmission risk, and established 510(k) clearance pathways that compress commercialization timelines.
- Composite:Dual-phase ceramic-collagen matrices combine immediate mechanical load-bearing with sustained osteoinductive signaling. Orthopedic clinics in Germany and the United States are expanding adoption fastest as surgeons demand simultaneous biological performance and structural integrity for critical-sized defects.
- Natural:Derived from demineralized bone matrix or xenograft sources, processed to retain native growth factors. Supply constraints from donor tissue availability limit penetration despite osteoinductive advantages.
- Allograft:Cadaveric bone processed through terminal sterilization protocols with extensive endotoxin and pyrogen testing. Extended batch release cycles and tissue bank dependency constrain manufacturer margins.
Synthetic grafts retain volume leadership; composite formulations hold the steepest expansion curve.
End User:
Procurement authority concentrates in consolidated health systems while specialty clinics drive formulation innovation.
- Orthopedic Clinics:Generate the deepest margin pools through high-volume spine and joint reconstruction procedures. Texas and California metropolitan networks now unbundle graft procurement from implant purchasing agreements, creating standalone vendor selection based on total episode cost metrics.
- Hospitals:Academic medical centers in Germany and the United States integrate 3D-printed patient-specific scaffolds into complex revision arthroplasty protocols. Bundled payment pilots from commercial payers reward biological integration speed over upfront material cost minimization.
- Dental Clinics:Rising edentulism rates and immediate-loading protocols in oral surgery create unmet demand for socket preservation grafts with rapid vascular integration.
- Research Institutions:Drive preclinical validation of novel ion-release profiles and architected porosity gradients under EU MDR Article 10 clinical evaluation requirements.
Hospitals dominate procurement volume; dental clinics are gaining share fastest as implantology expands.
Application:
Surgical complexity determines the trade-off between mechanical performance and biological signaling intensity.
- Orthopedic Surgery:Spine fusion procedures reward osteoconductive performance per dollar against autograft harvest avoidance value. Pelvic reconstruction cases show collapsing average hospital stay durations as patient-specific scaffolds eliminate secondary grafting procedures.
- Dental Surgery:Socket preservation and ridge augmentation demand rapid vascular integration with minimal inflammatory response. Immediate-loading protocols accelerate uptake of bioactive glass formulations.
- Sports Medicine:Athlete-specific return-to-play timelines favor synthetic grafts with predictable resorption rates over autograft morbidity.
- Reconstruction:Trauma centers maintain gold-standard iliac crest harvest preference despite donor-site morbidity, constraining synthetic penetration in acute fracture settings.
Orthopedic surgery commands the largest revenue base; dental surgery shows the most rapid demand acceleration.
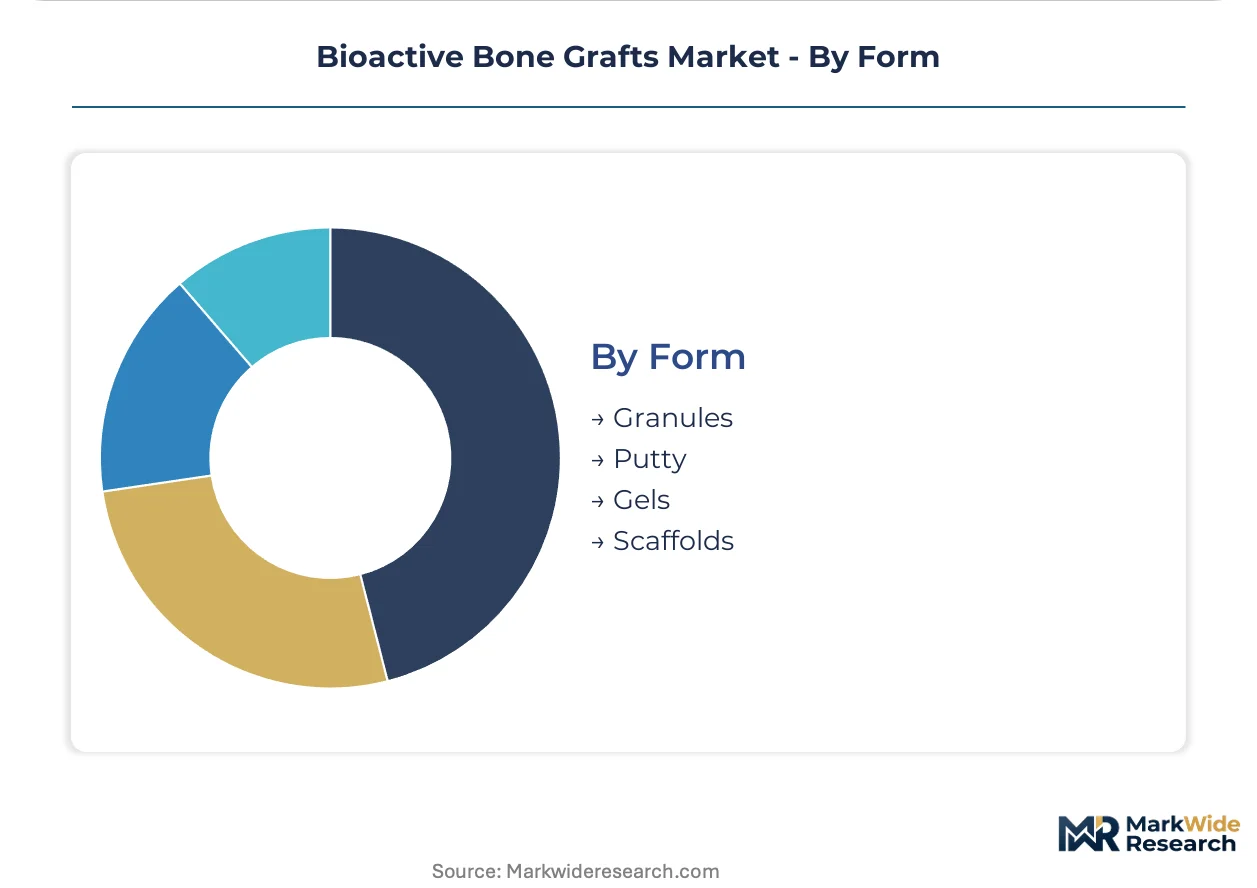
Form:
Delivery mechanism selection reflects surgical workflow integration and defect geometry complexity.
- Granules:Particulate ceramics and bioactive glass enable precise defect filling with immediate vascular access. Standard in dental socket preservation and small-volume orthopedic defects.
- Putty:Moldable composites combining mineral phase with collagen or synthetic carriers allow intraoperative contouring. Preferred in spinal fusion cages and irregular defect sites.
- Gels:Injectable formulations with sustained release kinetics for minimally invasive delivery. Emerging adoption in arthroscopic sports medicine procedures.
- Scaffolds:3D-printed architected structures with gradient porosity collapse the traditional trade-off between structural integrity and vascular infiltration kinetics. Academic centers lead integration into revision arthroplasty.
Granules and putty retain combined volume dominance; scaffolds demonstrate the most aggressive technology-led expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy harmonization and hospital procurement consolidation are redrawing commercialization pathways across major orthopedic markets. Regulatory convergence between FDA and PMDA testing protocols is compressing multi-regional filing timelines for synthetic graft developers.
United States
Hospital network consolidation in Texas and California metropolitan areas concentrates purchasing power among integrated delivery systems. The FDA 510(k) premarket notification framework accelerates clearance timelines for osteoconductive scaffolds with established predicate devices. Academic medical centers in Boston and the Research Triangle lead adoption of 3D-printed patient-specific scaffolds for complex revision arthroplasty.
Germany
EU MDR Article 10 clinical evaluation requirements mandate post-market surveillance data for bioactive additives with novel ion-release profiles. Notified bodies apply heightened scrutiny to hydroxyapatite surface modification claims, extending CE marking timelines. Industrial clusters in Baden-Württemberg and Bavaria host specialized ceramic processors supplying beta-tricalcium phosphate to scaffold manufacturers.
Japan
PMDA convergence with FDA osteoinductivity testing protocols enables streamlined multi-regional filing strategies for synthetic graft entrants. Aging demographics and rising edentulism rates drive socket preservation graft demand in oral surgery. The Kanto region surrounding Tokyo anchors domestic manufacturing of bioactive glass formulations for dental implantology applications.
United Kingdom
NHS procurement frameworks favor suppliers with documented osteogenic efficacy and established health technology assessment pathways. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR standards for biological activity classifications. London and the Southeast concentrate orthopedic research institutions validating composite ceramic-collagen matrices for critical-sized defects.
China
NMPA medical device registration requirements for bone graft substitutes impose biocompatibility testing standards comparable to FDA benchmarks. Domestic manufacturers in the Yangtze River Delta scale synthetic hydroxyapatite production to capture import substitution opportunities. Shanghai-based research hospitals pilot architected porosity scaffolds under accelerated regulatory pilot programs.
Bioactive Bone Grafts Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidated hospital procurement networks in the United States favor suppliers with integrated supply chains and established reimbursement codes. Three archetypes dominate: diversified orthopedic conglomerates with scaffold manufacturing scale, specialized ceramic-hydroxyapatite formulators, and dental-focused graft developers. Competitive moves center on composite formulation patenting and point-of-care bioreactor leasing partnerships.
Within the diversified orthopedic tier, Medtronic Plc and Stryker Corporation occupy positions exemplifying integrated supply chain control over synthetic scaffold production. Zimmer Biomet Holdings Inc. represents the deep clinical partnership archetype, anchoring its presence through orthopedic clinic relationships across major metropolitan hospital networks. These three entities collectively illustrate how scale, formulation specialization, and channel access define competitive positioning in bioactive bone graft commercialization.
| Leading Market Players |
|---|
| Medtronic Plc |
| Stryker Corporation |
| Zimmer Biomet Holdings Inc. |
| NuVasive Inc. |
| Orthofix Holdings Inc. |
| Smith & Nephew Plc |
| Baxter International Inc. |
| DePuy Synthes |
| Dentsply Sirona Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in high-purity beta-tricalcium phosphate processing across Baden-Württemberg and Bavaria industrial clusters drives supplier rationing behavior and elevates spot pricing volatility for scaffold manufacturers. This utilization squeeze concentrates pricing power among specialty chemical processors while forcing graft producers toward long-term offtake commitments that lock in margin structures.
Pricing Analysis
Certification level creates the primary spread across the market, with FDA 510(k)-cleared formulations commanding substantial premia over CE-marked equivalents in United States hospital procurement networks. Three-tier pricing structure across premium, standard, and economy levels stratifies by osteoinductive claim substantiation and batch-to-batch consistency metrics. Cost compression in standard-grade synthetic grafts is intensifying because domestic manufacturers in the Yangtze River Delta scale hydroxyapatite production for import substitution. Orthopedic clinics in consolidated Texas and California metropolitan networks exhibit highest price sensitivity, while academic medical centers in Boston and the Research Triangle prioritize biological integration speed over per-unit cost minimization.
Supply Chain Analysis
Upstream feedstock concentration in Germany, China, and Japan anchors global beta-tricalcium phosphate and bioactive glass precursor availability. High-purity ceramic powders, collagen matrices, and terminal sterilization equipment constitute critical input dependencies. Single-source vulnerability in specialty chemical processing exposes manufacturers to qualification delays when switching qualified suppliers. Distribution runs through consolidated health system procurement networks in the United States and NHS frameworks in the United Kingdom, with direct-to-clinic channels gaining traction in dental implantology segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as 3D-printed patient-specific scaffold ecosystems integrate with digital surgical planning workflows, creating interoperability barriers that favor first-mover clinical data accumulation.
For Market Incumbents: Entrench channel control through exclusive bioreactor leasing partnerships with orthopedic clinic networks across major metropolitan hospital systems. Deepen backward integration into high-purity beta-tricalcium phosphate processing to neutralize raw material concentration risks. Prioritize composite formulation patent thickets around dual-phase ceramic-collagen matrices as emerging entrant differentiation vectors accelerate.
For New Entrants and Emerging Players: Pursue dental implantology white-space opportunities in socket preservation grafts, where immediate-loading protocol adoption outpaces incumbent supply responsiveness. Target Japan's Kanto region for PMDA-converged filing strategies that enable streamlined multi-regional market access. Deploy point-of-care bioreactor leasing models to bypass capital-intensive facility construction barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among scaffold manufacturers with embedded digital surgical planning platform integrations. Long-term viability hinges on clinical data moats accumulated through academic medical center partnerships. Target acquisition archetypes include specialized ceramic-hydroxyapatite formulators with EU MDR Article 10 compliance infrastructure already operational. Monitor Japan PMDA-FDA harmonization progress as inflection indicator for multi-regional filing efficiency gains.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Formulation Patenting | Dual-phase ceramic-collagen matrices command premium positioning in critical-sized defect repair protocols. |
| Point-of-Care Bioreactor Leasing | Asset-light models collapse capital barriers for mid-tier entrants seeking advanced cell-seeding infrastructure. |
| EU MDR Article 10 Compliance Investment | Post-market surveillance capabilities differentiate suppliers as notified bodies heighten scrutiny on resorption claims. |
| Hospital System Partnership Expansion | Standalone graft procurement unbundling from implant agreements creates vendor selection based on episode cost metrics. |
| PMDA-FDA Harmonization Strategy | Converged osteoinductivity testing protocols enable compressed multi-regional commercialization timelines. |
Study Parameters
Cross-validation between orthopedic surgeon interviews and hospital purchasing committee records anchors the qualitative findings on procurement behavior shifts. Primary fieldwork encompassed scaffold manufacturing executives, biomedical engineers, GPO contracts managers, and dental implantology specialists across the United States, Germany, and Japan. Secondary sources included FDA 510(k) filings, EU MDR notified body guidance documents, CMS Medicare reimbursement databases, and hospital procurement contract disclosures. Bottom-up demand modeling triangulated against top-down market sizing from synthetic graft production capacity estimates.
Calibration against historical 510(k) clearance timelines and CE marking duration patterns validated the projection framework across the analysis window. Segmentation dimensions encompassed product type, end user, application, and form factor with regional regulatory cluster overlays. CAGRs derived from procedure volume growth trajectories, pricing trend extrapolation, and technology substitution curves. Industry-specific inputs included orthopedic surgery procedure databases, dental implantology volume forecasts, and bioactive glass formulation adoption rates.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles and commercial payer bundled payment expansion would shift the trajectory. Forecasts incorporate assumptions regarding regulatory harmonization progress and raw material supply stability that warrant periodic reassessment. Cross-checking against external procedure volume benchmarks from national orthopedic registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Europe Bioresorbable Vascular Scaffold Market
Biomedical Engineering
Biological Derived Devices Market
Biomedical Engineering
Bioabsorbable Osteosynthesis Devices Market
Biomedical Engineering
Biomems Market
Biomedical Engineering
Global Robotic Prosthetic Market
Biomedical Engineering
Bioimplants Market
Biomedical Engineering
3D Bioprinted Human Tissue Market
Biomedical Engineering
Bioactive Coating Devices Market
Biomedical Engineering
Protein Engineering Market
Biomedical Engineering
Tissue Engineered Skin Substitute Market
Biomedical Engineering
Bioabsorbable Implant Market
Biomedical Engineering
Bionic Eye Market
Biomedical Engineering
Tissue Expansion Market
Biomedical Engineering
North America Biosurgery Market
Biomedical Engineering
Tissue Extraction System Market
Biomedical Engineering
Bioprosthetics Market