
 Asia-Pacific Biocontrol Agents Market | 2026-2036
Asia-Pacific Biocontrol Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Biocontrol Agents Market Insights
Specialty horticulture buyers are reorganizing procurement away from broad-acre commodity growers across the Asia-Pacific biocontrol landscape. Koppert Biological Systems Inc. leverages its Netherlands-to-Asia distribution infrastructure to dominate greenhouse vegetable segments. Biobest Group NV sustains R&D intensity in bumblebee pollination and beneficial insect systems. UPL Limited anchors its position through backward integration into fermentation-based microbial production in India.
Biocontrol agents comprise living organisms or their derivatives—entomopathogenic fungi, predatory mites, pheromone disruptors, and bacterial metabolites—formulated to suppress agricultural pests below economic injury thresholds through ecological mechanisms rather than chemical toxicity. Microbial agents lead volume consumption across the region, while macrobial agents command premium pricing in protected cultivation. Liquid formulations capture the fastest growth trajectory, driven by foliar spray compatibility in high-value fruit and vegetable systems. Semiochemicals occupy a concentrated margin pool where mating-disruption patents limit supplier entry.
India's Central Insecticides Board under the Ministry of Agriculture regulates biocontrol product registration through sequential toxicity and field-efficacy protocols. China's Ministry of Agriculture and Rural Affairs enforces GB standards for microbial pesticide quality and shelf-life labeling. Australia's APVMA maintains parallel data requirements that shape export formulation strategies for regional manufacturers. Stakeholders must monitor regulatory harmonization talks between ASEAN member states, as divergent registration timelines currently fragment market access for multi-country suppliers.
Market Dynamics
India's PLI scheme and China's GB standards for biological inputs are accelerating domestic manufacturing capacity, compressing import dependency while reshaping competitive positioning across microbial formulation supply chains.
Growth Catalysts
- Export-zone vegetable intensification:Maharashtra and Karnataka states in India drive concentrated biocontrol adoption through pesticide residue protocols demanded by European fresh produce buyers.
- GB standards enforcement:China's Ministry of Agriculture and Rural Affairs mandates microbial pesticide quality and shelf-life labeling, standardizing domestic production benchmarks.
- Semiochemical patent pools:Mating-disruption chemistry concentrates supplier margins, attracting specialized R&D investment into pheromone disruptor systems.
Market Restraints
- Fermentation feedstock volatility:Molasses and soybean meal price swings compress margin stability for microbial agent manufacturers dependent on carbohydrate-based culture media.
- Registration timeline fragmentation:India's Central Insecticides Board sequential toxicity protocols and Australia's APVMA parallel data requirements create divergent compliance burdens for multi-country suppliers.
- Shelf-life technical limitation:Viable spore counts in liquid formulations degrade under ambient temperature logistics, constraining distribution reach beyond cold-chain infrastructure.
Strategic Opportunities
- ASEAN regulatory harmonization:Divergent registration timelines across Southeast Asian member states present consolidation upside for first-movers in unified standard development.
- Protected cultivation macrobial premium:Bumblebee pollination and beneficial insect systems command pricing power in greenhouse vegetable segments underserved by microbial commoditization.
- Foliar spray compatibility convergence:Liquid formulation technology integrates with existing spraying equipment, reducing grower switching costs in high-value fruit systems.
Industry Challenges
- Field-efficacy certification timelines:India's sequential toxicity and field-efficacy protocols extend product commercialization cycles, straining working capital for development-stage entrants.
- Integration complexity with chemical programs:Biocontrol agent compatibility testing against synthetic pesticide residues demands specialized technical service capacity that distributor networks often lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Biocontrol Agents Market |
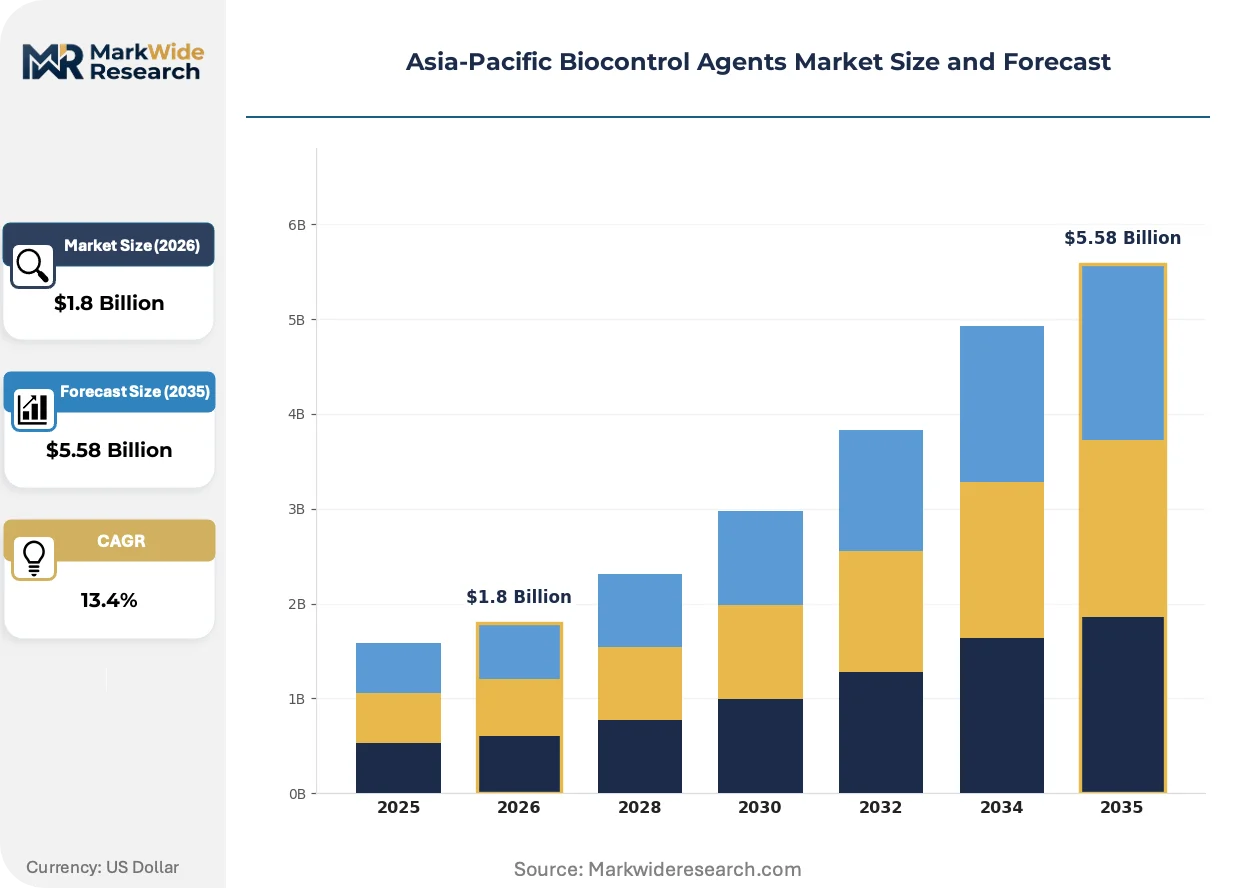
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.58 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Agents, Macrobial Agents, Semiochemicals, Biopesticides End Use Industry: Agriculture, Horticulture, Forestry, Turf Management Formulation Type: Liquid Formulations, Granular Formulations, Powder Formulations, Emulsifiable Concentrates Application Method: Soil Application, Foliar Application, Seed Treatment, Integrated Pest Management |
| Companies Covered | Biobest Group NV, Koppert Biological Systems Inc., Samriddhi Crops India Pvt Ltd, Andermatt Group AG, T. Stanes and Company Limited, Henan Jiyuan Baiyun Industry Co Ltd, KN Bio Sciences India Pvt Ltd, Sonkul Agro Industries, UPL Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Biocontrol Agents Market Trends and Innovations
Formulation chemistry and regulatory data requirements are actively compressing competitive moats, while procurement reorganization among horticulture buyers redistributes channel power toward technical service providers.
RNA interference and peptide-based biopesticides are fragmenting traditional microbial agent categories. Greenhouse operators in Japan and South Korea adopt these modalities at pilot scale, seeking rotation partners for resistance management. The technology is fragmenting established supplier relationships as specialty biochemistry firms bypass incumbent distribution networks through direct technical sales.
China's GB standards for microbial pesticide quality and shelf-life labeling are compressing informal supplier participation. Domestic manufacturers must upgrade fermentation and formulation infrastructure to meet documented viability thresholds. The protected cultivation segment responds fastest, as export-oriented greenhouse operators face dual pressure from import market residue standards and domestic regulatory compliance.
Horticulture buyers now consolidate technical service and supply contracts under single-source arrangements, displacing fragmented procurement across separate chemical and biological distributors. Premium vegetable exporters in India's Nashik and Hosur clusters lead this consolidation, bundling biocontrol with residue testing and traceability documentation. The shift concentrates volume with distributors possessing in-house entomology and pathology expertise rather than pure logistics capabilities.
Asia-Pacific Biocontrol Agents Market Segmentation
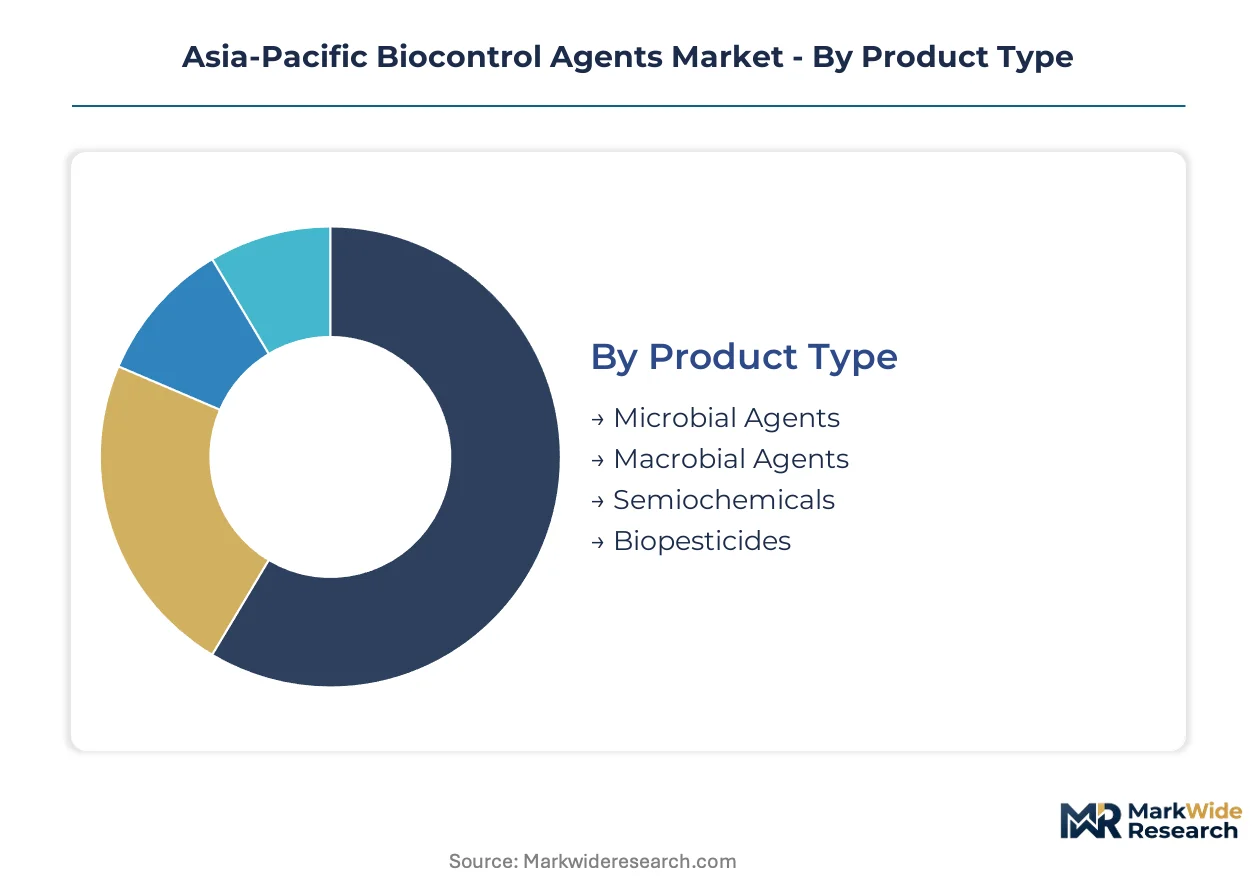
Biocontrol segmentation in Asia-Pacific reflects divergent margin economics across living versus non-living modalities and formulation complexity tiers. Procurement consolidation among horticulture exporters is compressing traditional category boundaries as buyers demand multi-modal integrated programs.
Product Type:
Margin pools concentrate in semiochemicals where mating-disruption patents limit supplier entry, while microbial agents compete on fermentation scale and formulation stability.
- Microbial Agents:Comprise living bacteria, fungi, and viruses formulated as spore suspensions or cell concentrates. Demand concentrates in India's Maharashtra vegetable export zones where European residue protocols drive Bacillus thuringiensis and Trichoderma adoption against fruit borers and soil pathogens.
- Macrobial Agents:Include predatory mites, parasitic wasps, and beneficial nematodes requiring cold-chain distribution. Premium pricing holds in Japan and South Korea's greenhouse sectors where Phytoseiulus persimilis and Steinernema carpocapsae address spider mite and root weevil pressure in protected strawberry and tomato systems.
- Semiochemicals:Pheromone disruptors and kairomone attractants with concentrated supplier margins.
- Biopesticides:Botanical extracts and protein-based compounds competing with synthetic chemistry on cost.
Microbial agents hold installed capacity. Semiochemicals are rotating up the share rankings.
End Use Industry:
Volume concentrates in agriculture's broad-acre applications, though value per hectare peaks in horticulture's intensive production systems.
- Agriculture:Row crop applications of fungal biopesticides and bacterial metabolites across rice, cotton, and soybean systems. India's Karnataka state drives concentrated adoption through state-level integrated pest management subsidies targeting pink bollworm and rice stem borer.
- Horticulture:High-value fruit and vegetable production requiring residue-compliant protection. Australia's protected tomato and capsicum sectors anchor demand for beneficial insect releases, with Biobest Group NV and Koppert Biological Systems Inc. dominating technical service contracts.
- Forestry:Entomopathogenic fungi for plantation pest management.
- Turf Management:Golf course and sports field applications of nematodes and microbial fungicides.
Horticulture commands value per hectare. Agriculture is rotating up the share rankings.
Formulation Type:
Customer switching costs vary sharply across formulation categories, with liquid formats integrating into existing spray infrastructure while granular requires specialized application equipment.
- Liquid Formulations:Aqueous suspensions and oil-based concentrates compatible with conventional sprayers. China's Shandong and Jiangsu greenhouse clusters drive fastest adoption as GB standards enforcement mandates documented shelf-life viability, favoring suppliers with fermentation-to-formulation integration.
- Granular Formulations:Clay or polymer-based carriers for soil-dwelling microbes. Australia's broad-acre cotton and grain sectors anchor demand where aerial application compatibility matters less than extended field persistence.
- Powder Formulations:Dust and wettable powder formats for seed treatment and manual application.
- Emulsifiable Concentrates:Oil-in-water systems for lipophilic active ingredients.
Liquid formulations hold installed capacity. Granular formulations are rotating up the share rankings.
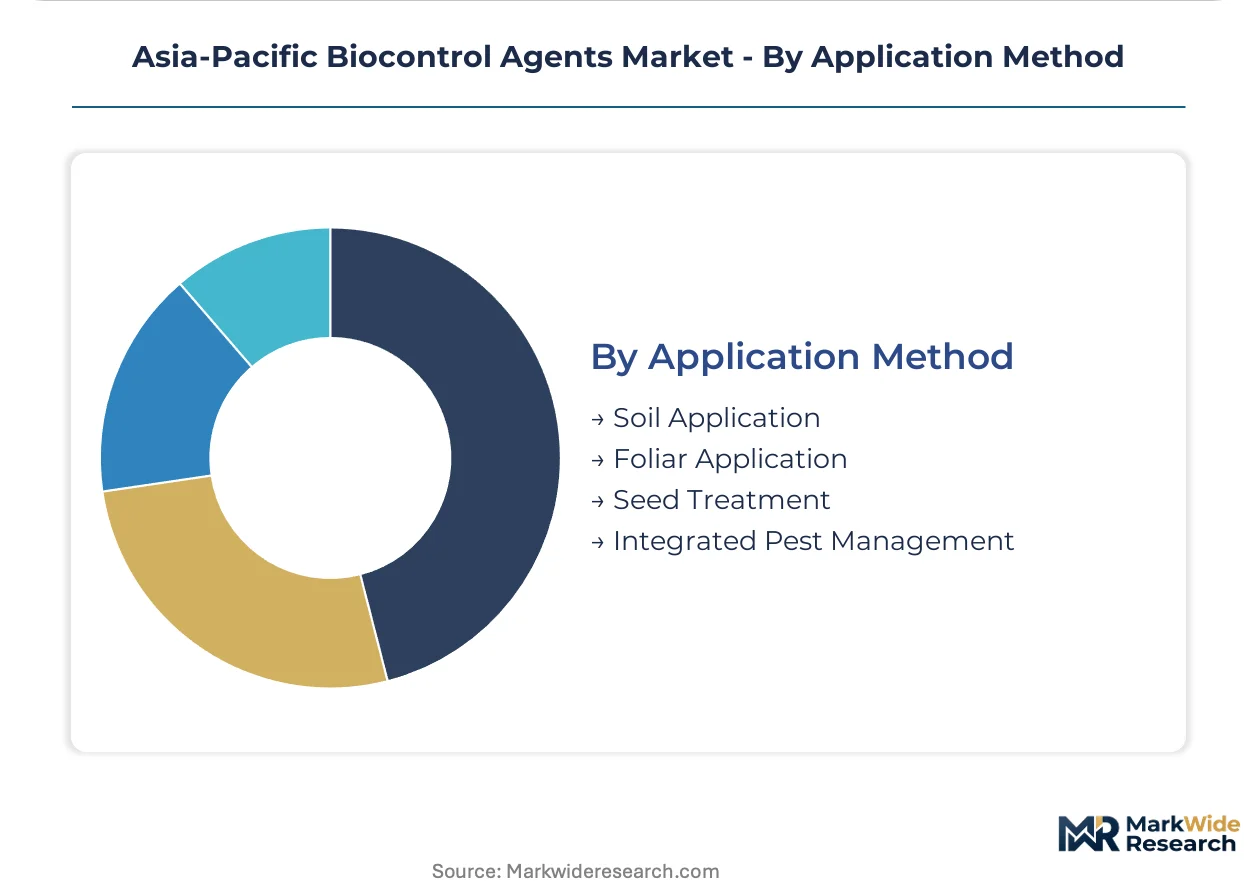
Application Method:
Technical service intensity scales with application complexity, from standardized foliar sprays to customized integrated pest management program design.
- Soil Application:Direct incorporation of microbial inoculants, nematodes, or granules into root zones. India's Nashik grape cluster drives specialized demand for Trichoderma and Pseudomonas soil drenches against root rot in export-oriented table grape production.
- Foliar Application:Aerial and ground-based spraying of microbial suspensions and botanical extracts. Southeast Asia's banana and mango export sectors concentrate demand, with residue testing protocols from EU and Japanese buyers dictating application timing and pre-harvest intervals.
- Seed Treatment:Microbial coatings applied at planting.
- Integrated Pest Management:Multi-tactic programs combining biological, cultural, and selective chemical methods.
Foliar application holds installed capacity. Integrated pest management is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented vegetable growers in Maharashtra and Karnataka states anchor procurement volume, while greenhouse operators across Japan and South Korea drive premium-tier demand for macrobial systems.
India
Maharashtra's Nashik grape cluster and Karnataka's vegetable export zones concentrate biocontrol adoption through European residue protocols. The Central Insecticides Board under the Ministry of Agriculture enforces sequential toxicity and field-efficacy registration protocols. Domestic manufacturing capacity expands through the PLI scheme, with fermentation-based microbial production scaling in Hyderabad and Pune industrial corridors.
China
Shandong and Jiangsu greenhouse clusters drive liquid formulation demand as GB standards enforcement mandates documented shelf-life viability. The Ministry of Agriculture and Rural Affairs regulates microbial pesticide quality through national standard certification. Export-oriented protected cultivation operators in Shouguang and Xuzhou upgrade fermentation infrastructure to meet dual pressure from import market residue standards and domestic compliance.
Japan
Protected strawberry and tomato sectors in Chubu and Kyushu regions anchor premium pricing for beneficial insect systems. METI guidelines shape technical service intensity requirements for biocontrol distribution networks. Greenhouse operators in Aichi and Fukuoka prefectures pilot RNA interference and peptide-based biopesticides at commercial scale.
Australia
Broad-acre cotton and grain sectors in Queensland and New South Wales drive granular formulation demand for aerial application compatibility. The APVMA maintains parallel data requirements that shape export formulation strategies for regional manufacturers. Protected tomato and capsicum growers in Bundaberg and Bowen clusters consolidate technical service contracts under single-source arrangements.
South Korea
Greenhouse vegetable producers in Gyeonggi and South Gyeongsang provinces drive adoption of mating-disruption pheromone systems. National agricultural technology extension programs subsidize integrated pest management program design. Protected cultivation operators in Icheon and Jinju integrate biocontrol with residue testing and traceability documentation for Japanese export markets.
Asia-Pacific Biocontrol Agents Market Competitive Landscape
Player mix skews toward integrated microbial manufacturers and specialized macrobial distributors. Market structure concentrates around fermentation-scale operators and greenhouse technical service providers. Two strategic archetypes dominate: backward-integrated fermentation specialists with captive culture media supply, and distribution-heavy technical service platforms with in-house entomology expertise. Competitive moves center on regulatory data package accumulation and cold-chain logistics infrastructure expansion.
Within the integrated manufacturing tier, UPL Limited and Biobest Group NV exemplify divergent scale positions. Koppert Biological Systems Inc. occupies the technical service platform archetype alongside regional specialists. Samriddhi Crops India Pvt Ltd and T. Stanes and Company Limited represent India-based fermentation operators. Henan Jiyuan Baiyun Industry Co Ltd anchors Chinese domestic production capacity.
| Leading Market Players |
|---|
| Biobest Group NV |
| Koppert Biological Systems Inc. |
| Samriddhi Crops India Pvt Ltd |
| Andermatt Group AG |
| T. Stanes and Company Limited |
| Henan Jiyuan Baiyun Industry Co Ltd |
| KN Bio Sciences India Pvt Ltd |
| Sonkul Agro Industries |
| UPL Limited |
| Others |
Pricing and Supply Chain Analysis
Fermentation-scale economies in Hyderabad and Pune industrial corridors concentrate manufacturing cost advantages among backward-integrated microbial producers, compressing price floors for commodity Bacillus and Trichoderma formulations while preserving premium tiers for cold-chain macrobial systems.
Pricing Analysis
Cost-plus contracts with molasses and soybean meal indexation dominate microbial agent procurement, tying formulation prices to carbohydrate feedstock volatility. Three-tier pricing structure across premium macrobial systems, standard microbial concentrates, and economy-grade powder formulations reflects cold-chain requirements and viability certification tiers. Price erosion runs through economy microbial tiers as China's GB standards enforcement and India's PLI scheme expand domestic fermentation capacity. Export-zone vegetable growers in Maharashtra and Karnataka exhibit highest price sensitivity, while Japanese greenhouse operators accept premium pricing for beneficial insect technical service bundles.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Indian vegetable export processors facing European residue protocol deadlines, contrasting with strategic stockpiling of viable spore concentrates by Chinese Shandong greenhouse operators navigating GB standards shelf-life mandates. Supply concentrates in India, China, and the Netherlands, with fermentation infrastructure and beneficial insect breeding facilities anchoring regional hubs. Raw material dependencies include molasses culture media, soybean meal nitrogen sources, and specialized cold-chain packaging. Single-source vulnerability concentrates in bumblebee colony suppliers serving Japan and South Korea protected cultivation. Distribution runs through technical service platforms with in-house entomology expertise rather than pure logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biocontrol procurement is reorganizing as a service-attach opportunity, with residue testing and traceability documentation contracts expanding faster than standalone agent supply as European and Japanese buyers consolidate vendor relationships.
For Market Incumbents: Fortify fermentation-to-formulation integration through captive molasses supply agreements and cold-chain infrastructure expansion, defending against RNA interference and peptide-based biopesticide substitutes fragmenting traditional microbial categories. Prioritize regulatory data package accumulation for ASEAN harmonization to preempt registration timeline fragmentation from compressing multi-country market access. For New Entrants and Emerging Players: Anchor in Australia's protected tomato and capsicum sectors where technical service consolidation creates white-space for specialized macrobial distributors with entomology expertise. Target granular formulation supply to Queensland cotton aerial applicators underserved by liquid-focused incumbents. Pursue direct technical sales models bypassing fragmented chemical distribution networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation-scale operators with captive culture media supply and documented GB standards compliance over pure distribution plays. Long-term viability hinges on regulatory data asset accumulation and cold-chain logistics control. Watch ASEAN regulatory harmonization talks as the inflection signal for multi-country market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | India's PLI scheme subsidizes domestic Bacillus and Trichoderma production scale-up in Hyderabad corridors. |
| Cold-Chain Infrastructure Partnership | Japanese greenhouse operators demand viable spore guarantees through temperature-controlled distribution networks. |
| Regulatory Data Package Accumulation | ASEAN harmonization preparation requires sequential toxicity and field-efficacy documentation investment. |
| Technical Service Platform Integration | Maharashtra grape exporters consolidate residue testing and traceability under single-source biocontrol contracts. |
| RNA Interference R&D Licensing | Japanese and South Korean greenhouse pilots seek rotation partners for resistance management programs. |
Research Methodology
The analysis maps microbial agent fermentation, macrobial beneficial insect systems, semiochemical mating-disruption chemistry, and biopesticide botanical extracts, each validated through plant protection product managers, greenhouse technical service directors, export-zone procurement leads, and regulatory affairs specialists at India's Central Insecticides Board and China's Ministry of Agriculture. Primary fieldwork combined with secondary validation against GB standards documentation, APVMA registration databases, ASEAN trade flow records, and PLI scheme disclosure filings. Bottom-up fermentation capacity estimates and top-down export-zone adoption rates triangulate volume figures.
Consistency checks validated outputs against customs data for microbial concentrate trade flows and greenhouse area expansion statistics from Japan's METI and South Korea's rural development administration. Segmentation modeling spanned product type, end-use industry, formulation complexity, and application method across the projection horizon. CAGRs derived from capacity utilization curves and adoption elasticity to residue protocol stringency. Industry-specific inputs included molasses price index trajectories and cold-chain infrastructure penetration rates.
Material uncertainties — fermentation feedstock volatility, ASEAN regulatory timeline convergence, and RNA interference commercialization pace — sit outside the modeled envelope. Forecasts reflect documented assumptions on PLI scheme continuation and GB standards enforcement intensity. Practitioners should keep alternative scenarios live as ASEAN harmonization negotiations and peptide-based biopesticide pilot scale evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Bio-Seeds Market
Bio-Agriculture
Latin America Biostimulants Market
Bio-Agriculture
Aquatic Animal Vaccines Market
Bio-Agriculture
Europe Bioethanol Market
Bio-Agriculture
Bacterial Biopesticides Market
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Bloodroot Market
Bio-Agriculture
Seed Biostimulants Market
Bio-Agriculture
Europe Biological Organic Fertilizer Market
Bio-Agriculture
Italy Biopesticides Market
Bio-Agriculture
Microphytes Market
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
China Biopesticides Market
Bio-Agriculture
Ulva Lactuca Market
Bio-Agriculture
Biofumigation Market
Bio-Agriculture
Global Bio-Organic Acid Market