
 Europe Plant-Based Biologics Market | 2026-2036
Europe Plant-Based Biologics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Plant-Based Biologics Market Analytics
European biopharmaceutical manufacturing capacity is shifting toward plant-based expression platforms as traditional mammalian cell culture faces yield constraints. Medicago leverages proprietary plant molecular farming technology to anchor vaccine production pipelines across the region. Protalix Biotherapeutics sustains specialized recombinant protein programs through its proprietary plant cell culture systems. Icon Genetics competes with advanced viral vector expression platforms tailored for European therapeutic developers.
Plant-based biologics comprise therapeutic proteins, vaccines, and monoclonal antibodies produced through genetically engineered plant hosts such as Nicotiana benthamiana, with manufacturing typically yielding complex glycoproteins within 6-8 weeks from gene insertion to protein harvest. The primary commercial purpose centers on reducing production costs, eliminating mammalian pathogen risks, and enabling rapid scale-up for pandemic response or personalized medicine applications. Recombinant proteins and monoclonal antibodies command the dominant share of current output value, reflecting their established therapeutic utility and higher margin profiles compared to vaccine intermediates. Plant molecular farming leads technology deployment, though bioreactor-based plant cell culture is gaining traction among contract manufacturers seeking contained, GMP-compliant production environments.
EMA's biosimilar approval pathways and the EU Green Deal's pharmaceutical sustainability mandates are reshaping investment criteria for new production facilities across member states. REACH compliance and ECHA guidance on genetically modified organism containment further constrain facility design and operational protocols for molecular farming operations. Stakeholders must monitor evolving EMA guidance on plant-specific glycosylation patterns and their implications for immunogenicity assessments in therapeutic applications.
Market Dynamics
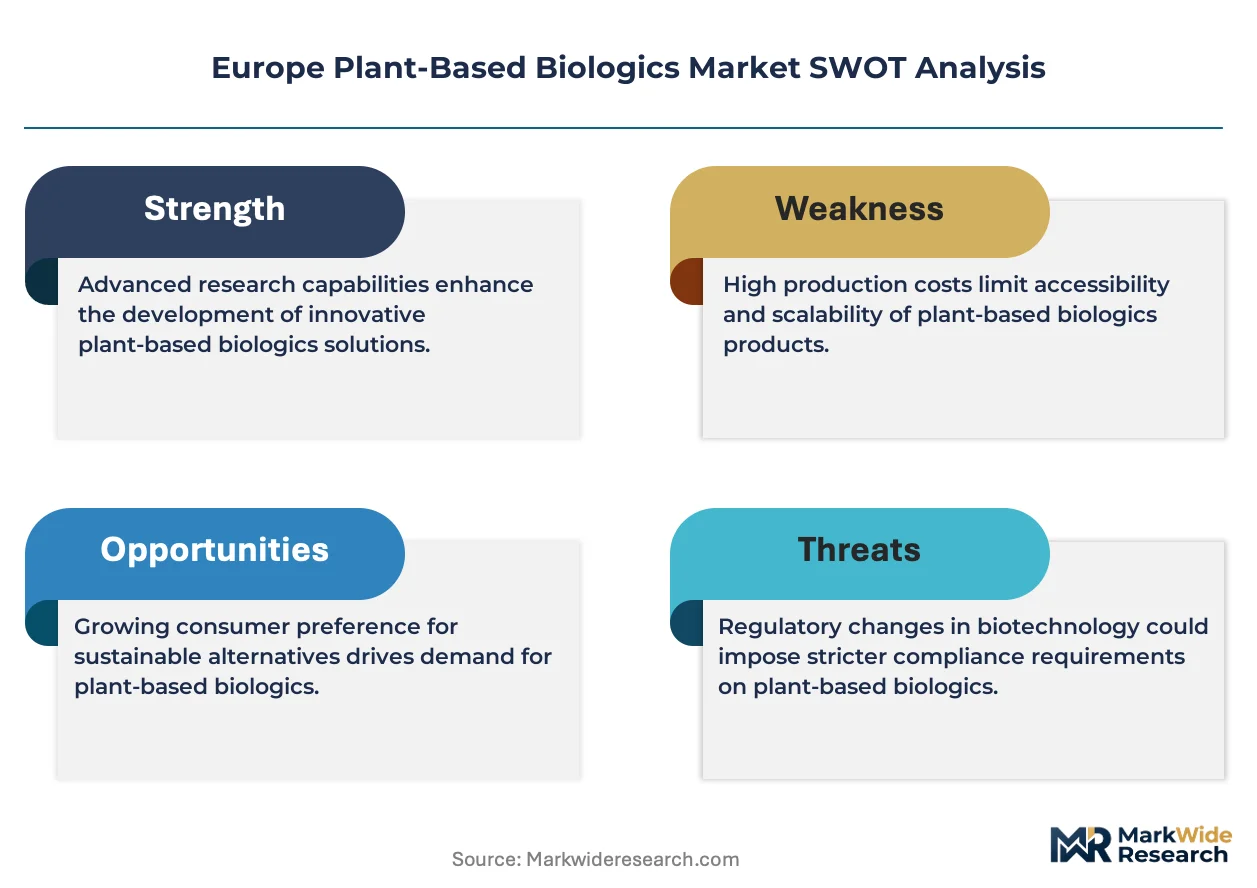
EMA's evolving biosimilar guidance for plant-specific glycosylation patterns is forcing pharmaceutical manufacturers across Germany, France, and the Netherlands to revalidate expression platforms and accelerate molecular farming infrastructure investment.
Growth Catalysts
- EU Green Deal pharmaceutical sustainability mandates:Binding carbon reduction targets for manufacturing facilities are redirecting capital toward plant-based expression systems that eliminate energy-intensive mammalian cell culture bioreactors.
- Nicotiana benthamiana transient expression:Contract manufacturers in the Netherlands are deploying this technology to compress therapeutic protein production timelines from months to weeks.
- Germany:Federal funding for pandemic preparedness infrastructure is specifically earmarking molecular farming capacity for rapid vaccine scale-up.
Market Restraints
- Specialized containment infrastructure costs:REACH-compliant GMO containment facilities require capital expenditure levels that exclude mid-scale entrants from facility ownership.
- Downstream purification bottlenecks:Protein extraction from plant biomass demands chromatography resin volumes that concentrate supply risk with specialized vendors.
- Immunogenicity assessment complexity:EMA's plant-specific glycosylation evaluation protocols extend regulatory timelines beyond mammalian-derived biologic pathways.
Strategic Opportunities
- France:ANSM's accelerated pathways for plant-derived vaccines create first-mover positioning for manufacturers establishing Paris-Saclay corridor facilities.
- Monoclonal antibody production for oncology:Plant-based expression enables cost structures that penetrate price-sensitive therapeutic categories currently served by mammalian platforms.
- CSRD-aligned sustainability reporting:Pharmaceutical procurement teams are embedding Scope 3 emissions criteria that favor molecular farming suppliers with verified carbon footprints.
Industry Challenges
- Glycoengineering expertise scarcity:Humanizing plant N-glycan profiles requires protein scientists with hybrid plant molecular biology and immunology training that European universities currently underproduce.
- Multi-product facility validation:Switching between recombinant proteins and viral vectors in shared plant-based production suites demands extensive cleaning validation protocols that compress facility utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Plant-Based Biologics Market |
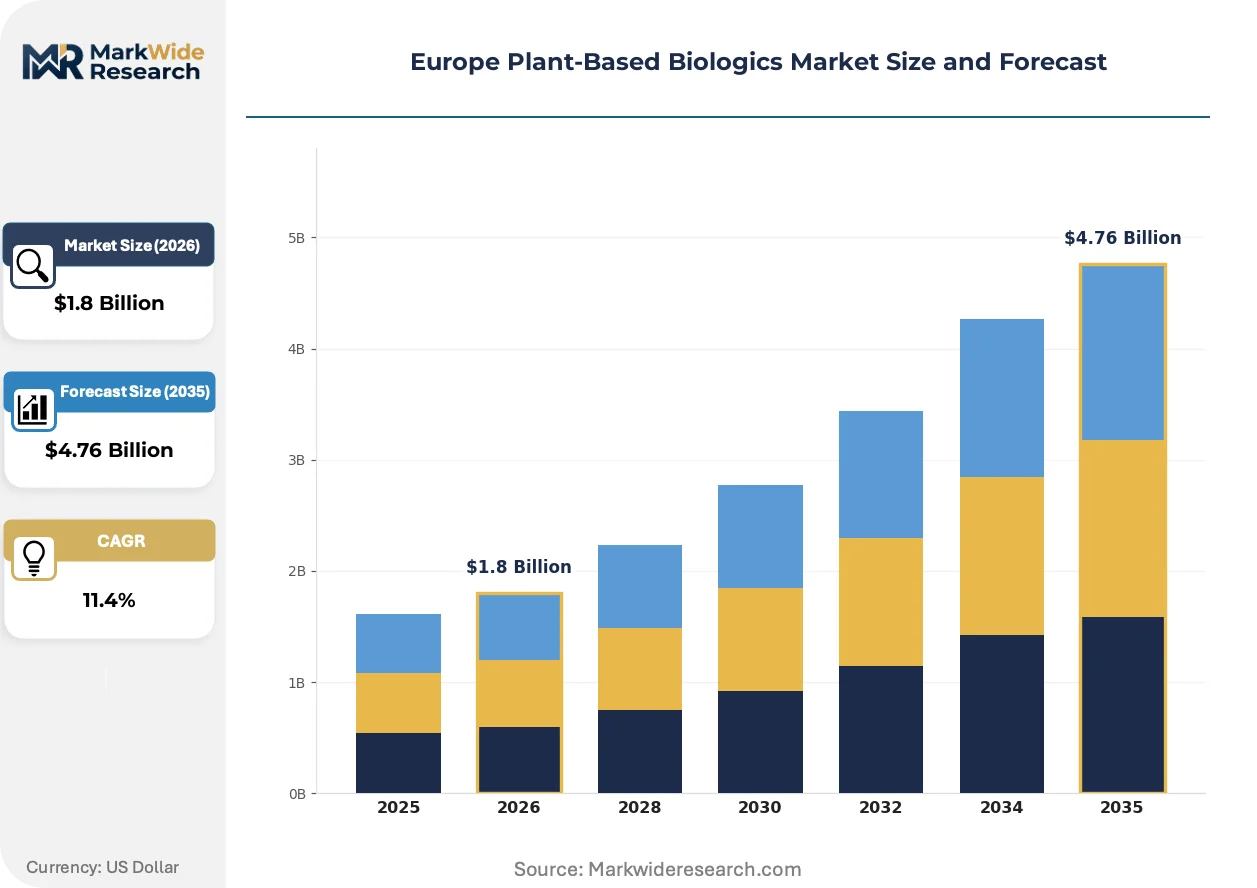
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Recombinant Proteins, Enzymes Application: Therapeutic, Vaccine Development, Diagnostics, Research End User: Pharmaceutical Companies, Biotech Firms, Research Institutions, Contract Manufacturers Technology: Plant Molecular Farming, Agrobacterium-mediated Transformation, Genetic Engineering, Bioreactors |
| Companies Covered | Medicago, PlantForm Corporation, Icon Genetics, Nomad Biosciences, Viridos, Greenovation Biotech, BioVax, Phytopharma, Protalix Biotherapeutics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Plant-Based Biologics Market Evolving Landscape
Plant molecular farming is transitioning from niche vaccine production to mainstream therapeutic protein manufacturing as European regulators codify acceptance criteria and contract manufacturers scale GMP-compliant capacity.
Transient expression systems in Nicotiana benthamiana enable rapid protein production without stable transgenic line development. German and French CDMOs are adopting this technology for clinical-stage monoclonal antibody programs requiring accelerated timelines. Plant molecular farming is expanding into established mammalian-dominated therapeutic categories by demonstrating comparable glycoprotein quality at reduced production cost structures.
EMA's draft guidance on plant-specific glycosylation immunogenicity assessments is establishing the regulatory framework for therapeutic protein approval. This policy development removes the historical approval pathway uncertainty that constrained pharmaceutical manufacturer investment. Biotechnology developers in the Netherlands and Belgium are restructuring CMC packages to align with these emerging standards.
Procurement teams at European pharmaceutical manufacturers are embedding sustainability metrics into supplier qualification criteria. Contract manufacturers with verified low-carbon molecular farming operations are displacing traditional mammalian cell culture suppliers in RFP shortlists. This pattern concentrates in German and French headquarters where CSRD reporting obligations elevate supply chain emissions visibility.
Europe Plant-Based Biologics Market Segmentation
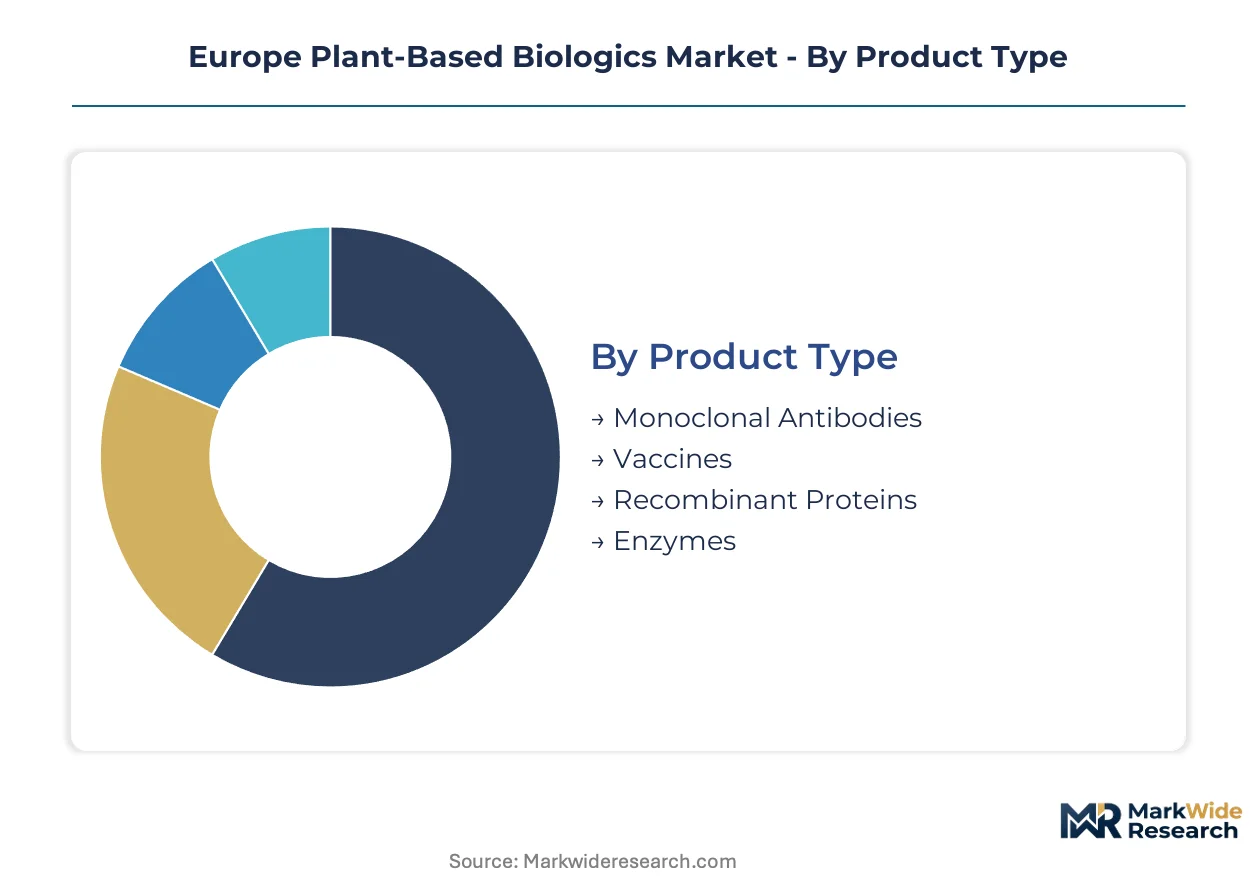
Segmentation in plant-based biologics reveals how therapeutic value concentrates across protein complexity tiers and production technology readiness. Understanding these divisions exposes where molecular farming platforms compete directly with mammalian cell culture versus carving out distinct application niches.
Product Type:
Standalone biologic categories dominate revenue capture, while embedded production intermediates serve as technology proving grounds for platform expansion.
- Monoclonal Antibodies:Complex glycoproteins requiring humanized N-glycan profiles for therapeutic efficacy. Demand concentrates in German and French oncology pipelines where EMA glycosylation guidance is accelerating platform validation. Manufacturing cost advantages versus mammalian systems drive CDMO investment in Nicotiana benthamiana capacity.
- Recombinant Proteins:Encompasses cytokines, growth factors, and blood factors with established clinical utility. Dutch contract manufacturers scale transient expression systems for these proteins to serve price-sensitive therapeutic categories including enzyme replacement therapies.
- Vaccines:Viral-like particles and subunit vaccines exploit rapid plant-based scale-up for pandemic preparedness. German federal funding prioritizes this segment for surge manufacturing capacity.
- Enzymes:Industrial and therapeutic enzymes leverage plant expression for cost-sensitive applications. Lower regulatory burden accelerates commercial timelines compared to injectable biologics.
Recombinant proteins lead volumes today; monoclonal antibodies are gaining share fastest.
Application:
Cost tier stratification separates premium-priced therapeutic approvals from lower-margin development services and diagnostic supply.
- Therapeutic:Injectable biologics for chronic disease management command highest price points and strictest regulatory scrutiny. EMA biosimilar pathways for plant-derived therapeutics are unlocking pharmaceutical manufacturer procurement.
- Vaccine Development:Prophylactic and therapeutic vaccine candidates exploit rapid molecular farming scale-up. French ANSM accelerated pathways specifically target this application for pandemic response infrastructure.
- Diagnostics:Recombinant antigens and detection reagents serve lower-margin, higher-volume demand. Research institutions in Belgium and the Netherlands drive procurement for assay development.
- Research:Preclinical-grade proteins for target validation and mechanism studies. Price sensitivity here limits adoption to academic and early-stage biotechnology budgets.
Therapeutic applications dominate value capture; vaccine development is expanding most quickly.
End User:
Customer type determines facility scale and regulatory burden, from multinational GMP requirements to flexible research-grade production.
- Pharmaceutical Companies:Multinational drug developers integrating plant-based platforms for biosimilar portfolios and supply chain resilience. CSRD reporting obligations elevate sustainability criteria in supplier selection.
- Contract Manufacturers:CDMOs in Germany, France, and the Netherlands build dedicated molecular farming capacity to serve fragmented biotechnology demand. Multi-product facility validation challenges compress utilization rates.
- Biotech Firms:Venture-backed developers pursuing novel therapeutic modalities. Capital constraints favor outsourced production over captive facility investment.
- Research Institutions:Academic and government laboratories advancing platform science. EU funding programs support precompetitive infrastructure development.
Pharmaceutical companies anchor demand today; contract manufacturers are climbing the fastest.
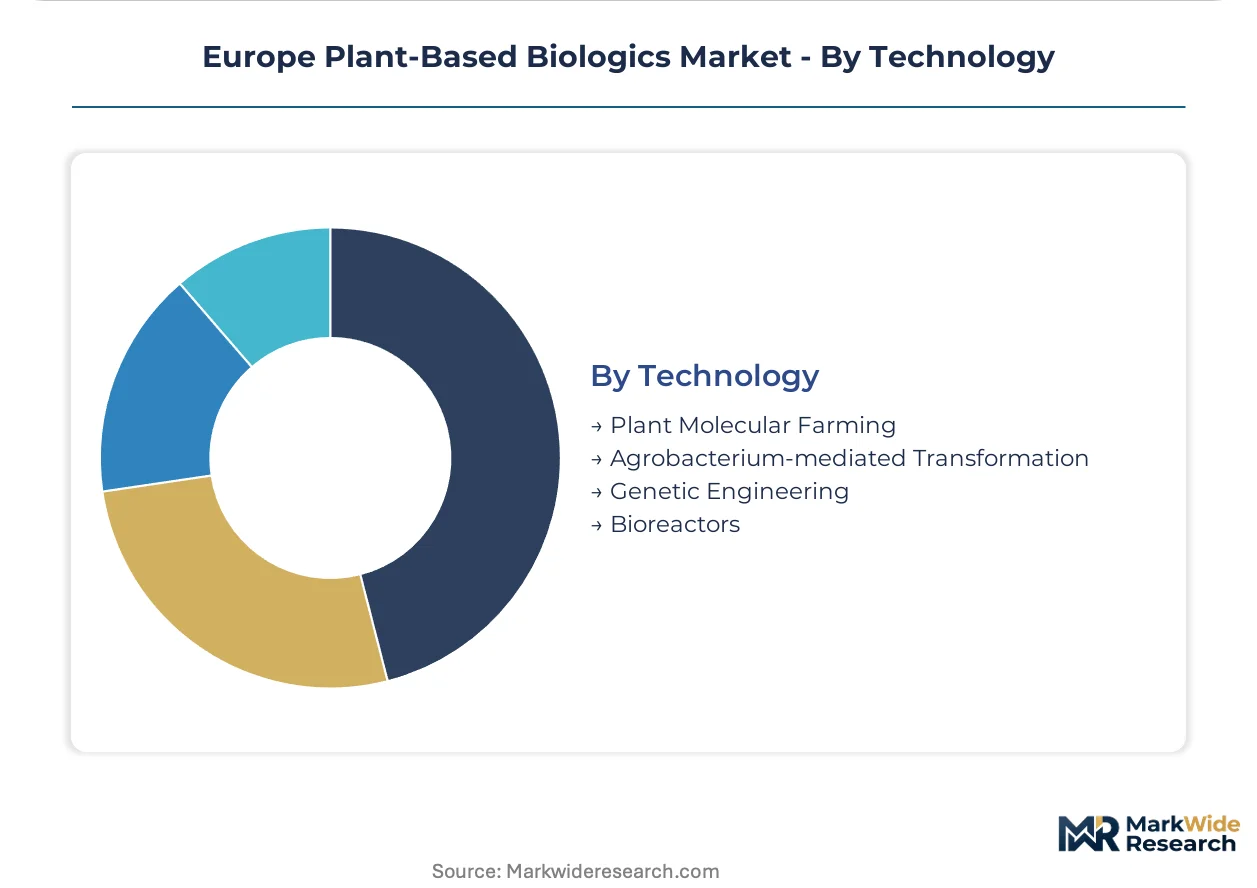
Technology:
Maturity gradients separate proven transient expression systems from emerging contained production modalities still establishing GMP track records.
- Plant Molecular Farming:Transient Agrobacterium-mediated expression in whole plants dominates current commercial deployment. Medicago and Icon Genetics anchor European technology leadership in this modality.
- Bioreactors:Contained plant cell culture systems eliminate field-grown biomass handling. Contract manufacturers adopt this technology for GMP compliance and multi-product flexibility.
- Genetic Engineering:Stable transgenic line development for seed-based protein accumulation. Longer development timelines limit adoption to high-volume, well-characterized products.
- Agrobacterium-mediated Transformation:The specific viral vector delivery mechanism underlying transient expression. Technical expertise concentrates in Belgian and Dutch research clusters.
Plant molecular farming leads deployment today; bioreactors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA's evolving guidance on plant-specific glycosylation patterns has widened the cost-of-compliance gap between member states, redirecting molecular farming investment toward jurisdictions with streamlined GMO containment protocols and aligned federal funding mechanisms.
Germany
Federal pandemic preparedness programs and Baden-Württemberg's biotech cluster drive demand for rapid vaccine scale-up capacity. The country's national pharmaceutical regulator coordinates with ECHA on REACH-compliant GMO facility standards. Munich and Heidelberg anchor contract manufacturing expansion where CDMOs deploy Nicotiana benthamiana transient expression systems.
France
Paris-Saclay corridor laboratories and ANSM's accelerated approval pathways attract plant-derived vaccine developers seeking reduced regulatory timelines. The EU Green Deal's pharmaceutical sustainability mandates redirect procurement toward low-carbon production platforms. Lyon and Strasbourg concentrate bioreactor-based plant cell culture investment from multinational pharmaceutical manufacturers.
Netherlands
Wageningen University's molecular farming expertise and Rotterdam port logistics support contract manufacturing scale-up for export-oriented biologics. EMA's draft immunogenicity assessment protocols are field-tested by Dutch CDMOs preparing CMC packages. Leiden and Utrecht host multi-product facilities navigating cleaning validation challenges between recombinant protein and viral vector programs.
Belgium
Flemish biotech funding and Ghent's agrobiotechnology cluster sustain Agrobacterium-mediated transformation expertise for European therapeutic developers. The country's national pharmaceutical regulator aligns with EMA on biosimilar pathway convergence for plant-derived monoclonal antibodies. Brussels-Antwerp corridor facilities specialize in glycoengineering services for humanized N-glycan profiles.
Switzerland
Swissmedic's pragmatic regulatory stance and Basel's pharmaceutical headquarters concentration create procurement pull for sustainable biologics supply chains. CSRD-aligned sustainability reporting obligations at multinational HQs elevate Scope 3 emissions criteria in supplier selection. Zurich and Geneva research institutions advance stable transgenic line development for seed-based protein accumulation.
Europe Plant-Based Biologics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue differentiated glycoengineering capabilities and contained production modalities. The market structure concentrates around three strategic archetypes: molecular farming specialists leveraging transient expression systems, bioreactor-focused CDMOs pursuing GMP compliance advantages, and integrated pharmaceutical manufacturers building captive molecular farming capacity. Dominant competitive moves include strategic partnerships between technology licensors and contract manufacturers, plus capacity expansion into multi-product facilities serving fragmented biotechnology demand.
Within the molecular farming specialist tier, Medicago and Icon Genetics exemplify platform-anchored competitive positioning, while Protalix Biotherapeutics occupies a distinct position emphasizing contained plant cell culture systems. These entities represent alternative technological bets on production modality—field-grown biomass versus bioreactor containment—with implications for regulatory pathway complexity and customer risk tolerance. Geography concentrates competitive presence: Canadian-anchored Medicago, German-rooted Icon Genetics, and Israeli-structured Protalix Biotherapeutics each leverage regional funding ecosystems and regulator relationships to advance platform validation.
| Leading Market Players |
|---|
| Medicago |
| PlantForm Corporation |
| Icon Genetics |
| Nomad Biosciences |
| Viridos |
| Greenovation Biotech |
| BioVax |
| Phytopharma |
| Protalix Biotherapeutics |
| Others |
Value Network & Pricing Analysis
Chromatography resin spot prices and specialized agrobacterium strain costs cascade through European molecular farming supply chains, compressing margins at contract manufacturers while concentrating pricing power with vendors serving GMP-compliant containment infrastructure.
Pricing Analysis
Distributor markups on downstream purification consumables absorb margin from Dutch and German CDMOs operating multi-product facilities. Project-based pricing for clinical-stage monoclonal antibodies stratifies across GMP certification tiers, with EMA-aligned quality grades commanding premiums over research-grade production. Cost compression in viral vector programs intensifies as bioreactor resin volumes concentrate supply risk with single-source vendors. Biotechnology firms with venture-constrained budgets exhibit highest price sensitivity; multinational pharmaceutical procurement teams prioritize verified carbon footprints over unit cost minimization.
Supply Chain Analysis
Direct-to-pharmaceutical channels handle commercial-scale therapeutic protein demand, while research-grade orders flow through distributor networks serving Belgian and Dutch academic institutions. Agrobacterium strain supply concentrates in Belgium, Germany, and the Netherlands, with Ghent and Wageningen anchoring transformation expertise. Nicotiana benthamiana seed stock and chromatography resin volumes draw from specialized vendors with limited geographic diversification. Single-source dependency on REACH-compliant GMO containment equipment creates vulnerability to ECHA regulatory revisions. Distribution runs through Rotterdam port logistics for export-oriented biologics, with Leiden and Utrecht hosting multi-product facilities managing cleaning validation protocols between recombinant protein and viral vector campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA's draft guidance on plant-specific glycosylation immunogenicity assessments functions as a regulatory compounder, accelerating pharmaceutical manufacturer procurement of validated molecular farming capacity as approval pathway uncertainty resolves.
For Market Incumbents: To counter glycoengineering expertise scarcity, Medicago and Icon Genetics should deepen captive training partnerships with Wageningen and Ghent academic clusters while expanding multi-product facility footprints in Germany's Baden-Württemberg corridor to capture federal pandemic preparedness funding. For New Entrants and Emerging Players: Capture white-space positioning in French ANSM accelerated vaccine pathways and CSRD-aligned sustainability procurement at German pharmaceutical headquarters. Paris-Saclay corridor facilities offer lowest regulatory friction for plant-derived therapeutic entry. Lead with verified carbon footprint credentials in RFP responses to multinational procurement teams. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-product facility validation costs exclude mid-scale entrants from facility ownership. Long-term viability hinges on platform-anchored competitive positioning with demonstrated EMA regulatory alignment. Target acquisition archetypes: bioreactor-focused CDMOs with contained production modality expertise and established GMP track records. Monitor EMA finalization of plant-specific glycosylation guidance as inflection signal for therapeutic protein procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Glycoengineering Partnership | Humanized N-glycan capabilities unlock EMA therapeutic approval pathways for German oncology pipelines. |
| Multi-Product Facility Expansion | Shared production suites between recombinant proteins and viral vectors raise utilization rates for Dutch CDMOs. |
| CSRD-Aligned Carbon Certification | Verified low-carbon operations displace mammalian suppliers in pharmaceutical procurement shortlists. |
| Containment Infrastructure Investment | REACH-compliant GMO facilities meet ECHA standards while excluding capital-constrained competitors. |
| Academic Cluster Integration | Wageningen and Ghent partnerships address glycoengineering talent scarcity constraining platform expansion. |
Research Methodology
Coverage spans Germany, France, the Netherlands, Belgium, and Switzerland, with primary inputs from each jurisdiction combined with secondary validation. Interviews with molecular farming technology leads, EMA regulatory affairs specialists, pharmaceutical procurement directors, CDMO operations managers, and academic plant biotechnology researchers anchored qualitative assessment. Secondary sources included EMA submission databases, EU Green Deal policy documentation, ECHA REACH guidance filings, and national pandemic preparedness program announcements. Bottom-up facility capacity estimates triangulated against top-down pharmaceutical manufacturer procurement survey data.
Segmentation granularity modeled product type, application, end user, and technology dimensions at the country level across the projection horizon. Treatment line stratification separated prophylactic vaccines from therapeutic proteins, while regulatory cluster differentiation captured EMA pathway convergence versus ANSM accelerated procedures. CAGRs derived from facility investment pipeline analysis and pharmaceutical manufacturer procurement intention surveys. Industry-specific inputs included chromatography resin supply lead times and GMO containment equipment vendor capacity constraints.
EMA guidance finalization delays, REACH regulatory revisions, and chromatography resin supply disruptions are the dominant revision risks to forecast assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
United States Biocontrol Agents Market
Bio-Agriculture
Latin America Biopesticide Market
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Indonesia Biopesticides Market
Bio-Agriculture
Plant-Based Biologics Market
Bio-Agriculture
United States Biofertilizer Market
Bio-Agriculture
China Agricultural Biologicals Market
Bio-Agriculture
Agricultural Biologicals Market
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
Hydroponics Nutrients Market
Bio-Agriculture
Europe Biopesticides Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
North America Biological Organic Fertilizer Market
Bio-Agriculture
India Feed Probiotics Market
Bio-Agriculture
India Biofertilizer Market