
 China Biocontrol Agents Market | 2026-2036
China Biocontrol Agents Market Size, Share, and Industry Trends Forecast 2026-2036
China Biocontrol Agents Market Insights
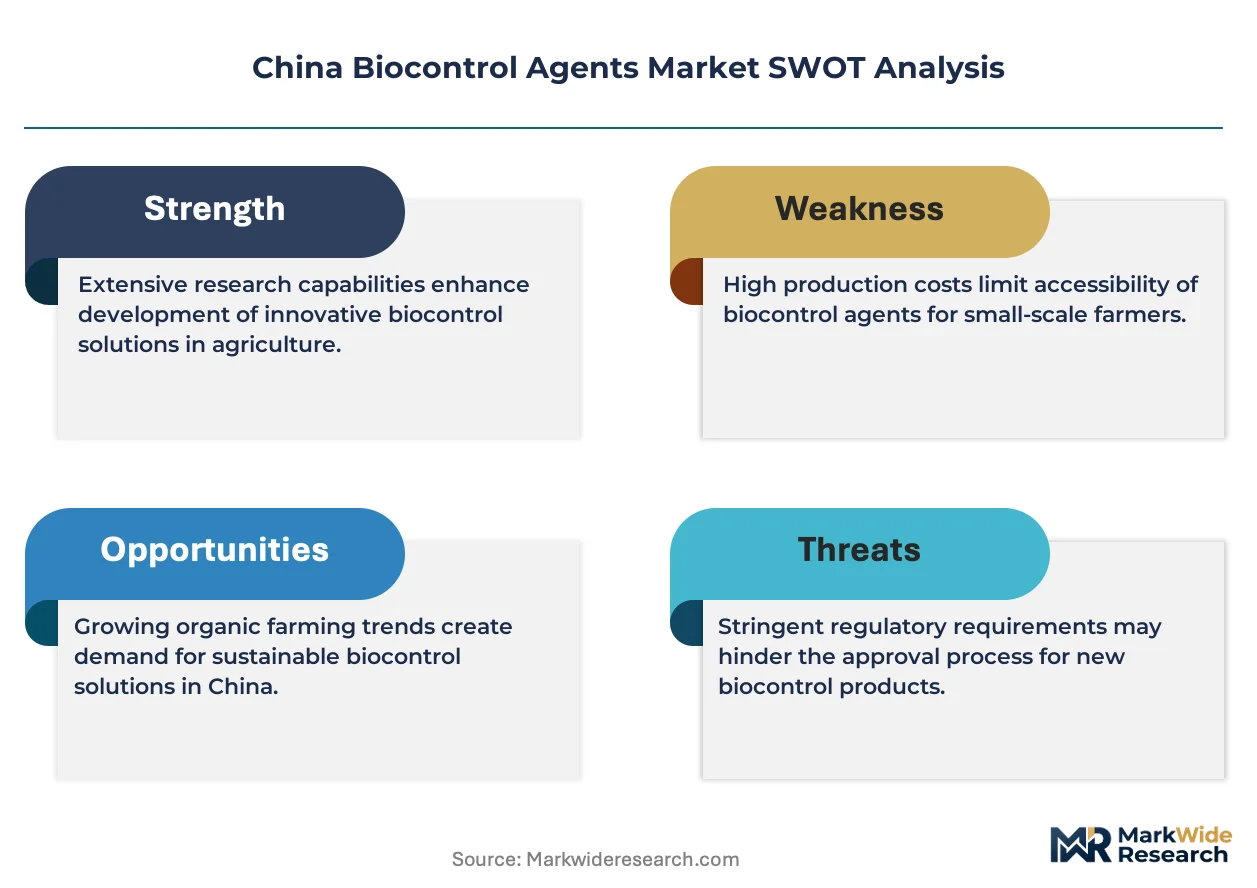
China's green agriculture action plan is rebalancing input procurement toward non-chemical crop protection. Koppert Biological Systems Inc. leverages its bumblebee pollination-biocontrol bundling to secure greenhouse contracts across eastern provinces. BASF SE anchors its position through in-house fermentation capacity for Bacillus-based formulations. Genliduo Bio-Tech Corporation Ltd. specializes in domestic strain development for regional pest profiles.
Biocontrol agents comprise living organisms or their derivatives—primarily bacteria, fungi, viruses, nematodes, and botanical extracts—formulated to suppress agricultural pests through predation, parasitism, competition, or antibiosis, with typical application rates of 10^6 to 10^9 colony-forming units per hectare for microbial products. Microbial Agents command the largest revenue share due to established manufacturing infrastructure and farmer familiarity with Bacillus thuringiensis and Trichoderma products. Liquid Formulations are gaining fastest among formulation types as drip irrigation and aerial drone application expand in precision agriculture zones.
China's Ministry of Agriculture and Rural Affairs, the National Health Commission through GB 2763 maximum residue limits, and provincial agricultural bureaus collectively restrict chemical pesticide approvals while subsidizing biological alternatives. MEE environmental compliance audits now require biocontrol documentation for organic certification exports to the European Union. Stakeholders must monitor strain patent filings and provincial subsidy quota adjustments to anticipate capacity allocation shifts.
Market Dynamics
China's Ministry of Agriculture and Rural Affairs residue limit tightening under GB 2763 is forcing greenhouse operators to replace chemical pesticides with microbial formulations, compressing substitution timelines from five-year adoption cycles to eighteen-month procurement switches.
Growth Catalysts
- GB 2763 Maximum Residue Limits:The National Health Commission's tightened chemical thresholds create immediate compliance-driven demand for Bacillus and Trichoderma alternatives in vegetable export zones.
- Shandong greenhouse expansion:Provincial horticulture belt operators are expanding microbial agent procurement to meet European Union organic certification requirements for tomato and cucumber exports.
- Drip irrigation infrastructure:Precision agriculture zones in the Yangtze River Delta are retrofitting liquid-compatible application systems, enabling direct microbial inoculation at planting.
Market Restraints
- Fermentation input volatility:Molasses and soybean meal price swings for Bacillus thuringiensis substrate production compress margin stability for domestic manufacturers.
- Strain IP concentration:Core Bacillus and Pseudomonas strain patents remain concentrated with international agricultural biotechnology holders, limiting domestic formulation freedom-to-operate.
- Technical shelf-life constraints:Viable colony-forming unit degradation during summer transport through inland provinces restricts distribution radius from production facilities.
Strategic Opportunities
- Sichuan and Yunnan underpenetration:Highland vegetable zones in southwestern provinces lack established microbial agent distribution networks, presenting first-mover channel establishment potential.
- Drone application convergence:Aerial spraying platforms combined with microencapsulation technology enable uniform coverage across rice paddy systems previously inaccessible to ground application.
- MEE environmental compliance documentation:Ministry of Ecology and Environment audit requirements for organic export certification create bundled service opportunities combining strain supply with compliance paperwork.
Industry Challenges
- Microbiologist talent scarcity:Strain isolation and fermentation optimization expertise concentrates in Beijing and Shanghai research institutes, limiting provincial manufacturer R&D capacity.
- Organic certification timeline compression:Three-year field conversion periods for GB/T 19630 organic status delay revenue realization for growers transitioning from chemical programs.
- Legacy chemical inventory integration:Distributor networks with embedded pesticide credit relationships resist biocontrol product slotting fees and technical training investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Biocontrol Agents Market |
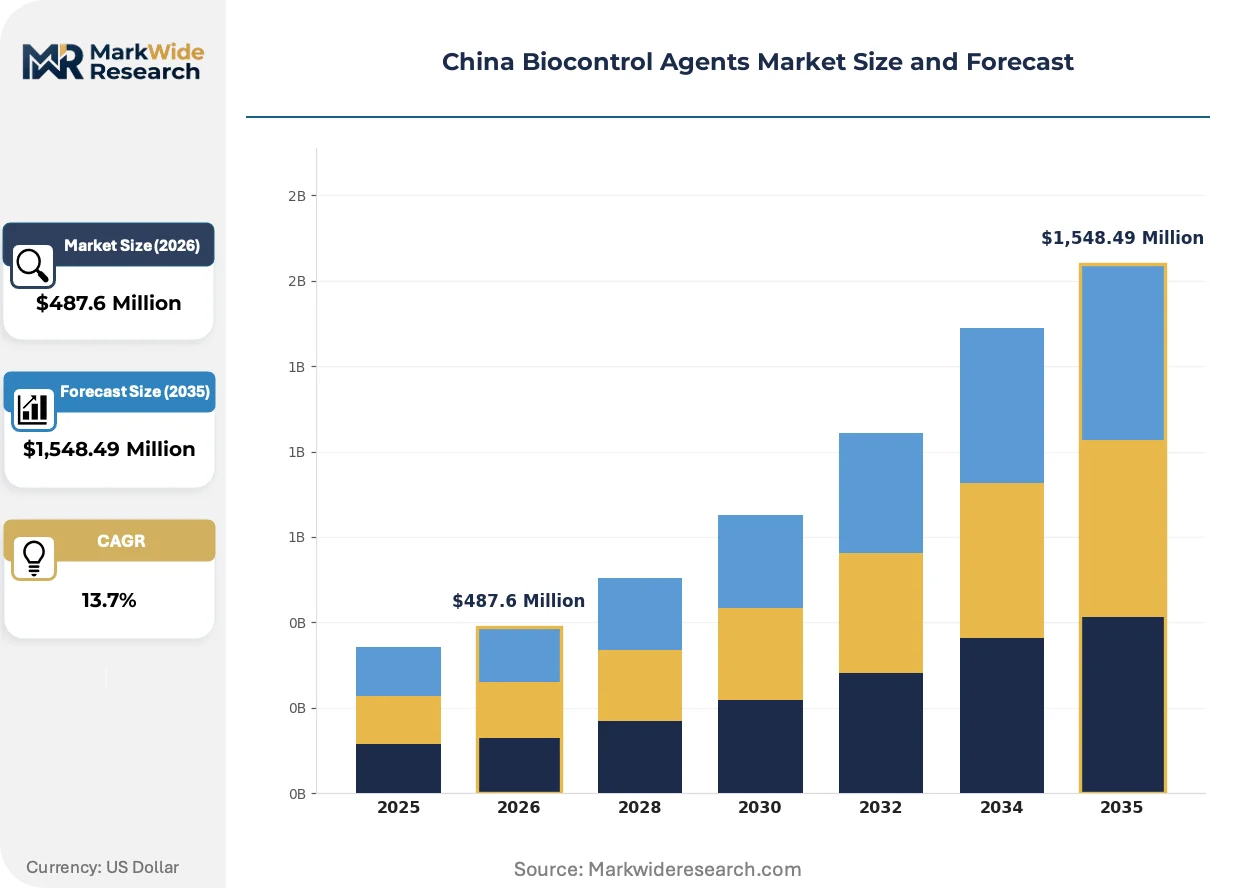
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,548.49 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Agents, Insect Growth Regulators, Biochemical Pesticides, Plant Extracts Application: Agricultural Crops, Horticultural Crops, Turf Management, Post-Harvest Treatment Formulation Type: Liquid Formulations, Granular Formulations, Powder Formulations, Coated Granules Distribution Channel: Online Retail, Direct Sales, Agricultural Cooperatives, Specialty Stores |
| Companies Covered | Koppert Biological Systems Inc., Biobest Group NV, Henan Jiyuan Baiyun Industry Co. Ltd, Andermatt Group AG, Isagro SPA, Valent Biosciences LLC, Biolchim SPA, Genliduo Bio-Tech Corporation Ltd., BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Biocontrol Agents Market Trends and Innovations
Precision application hardware and regulatory documentation automation are compressing the gap between microbial formulation development and field deployment, reconfiguring how greenhouse operators evaluate biocontrol procurement.
CRISPR-guided strain enhancement is automating the selection of Bacillus subtilis variants with enhanced surfactin production for fungal pathogen suppression. Shandong and Jiangsu greenhouse cooperatives are piloting these optimized strains at commercial scale this growing season. The technology is automating quality control protocols that previously required six-month field efficacy trials, collapsing validation timelines to eight weeks.
China's Ministry of Ecology and Environment now mandates biocontrol documentation for organic certification exports to the European Union under revised audit protocols. This regulatory layer adds compliance cost but creates service bundling opportunities for suppliers with in-house certification expertise. Yangtze River Delta export-oriented vegetable operations are absorbing these requirements fastest, integrating documentation into procurement specifications.
Greenhouse operators are consolidating supplier relationships from twelve chemical-plus-biological vendors to three full-service biocontrol partners. This consolidation eliminates product-stacking complexity and shifts technical risk to suppliers who guarantee efficacy outcomes. The pattern is most visible in Shandong's Weifang and Qingzhou greenhouse clusters, where procurement committees now prioritize strain technical support over per-liter pricing.
China Biocontrol Agents Market Segmentation
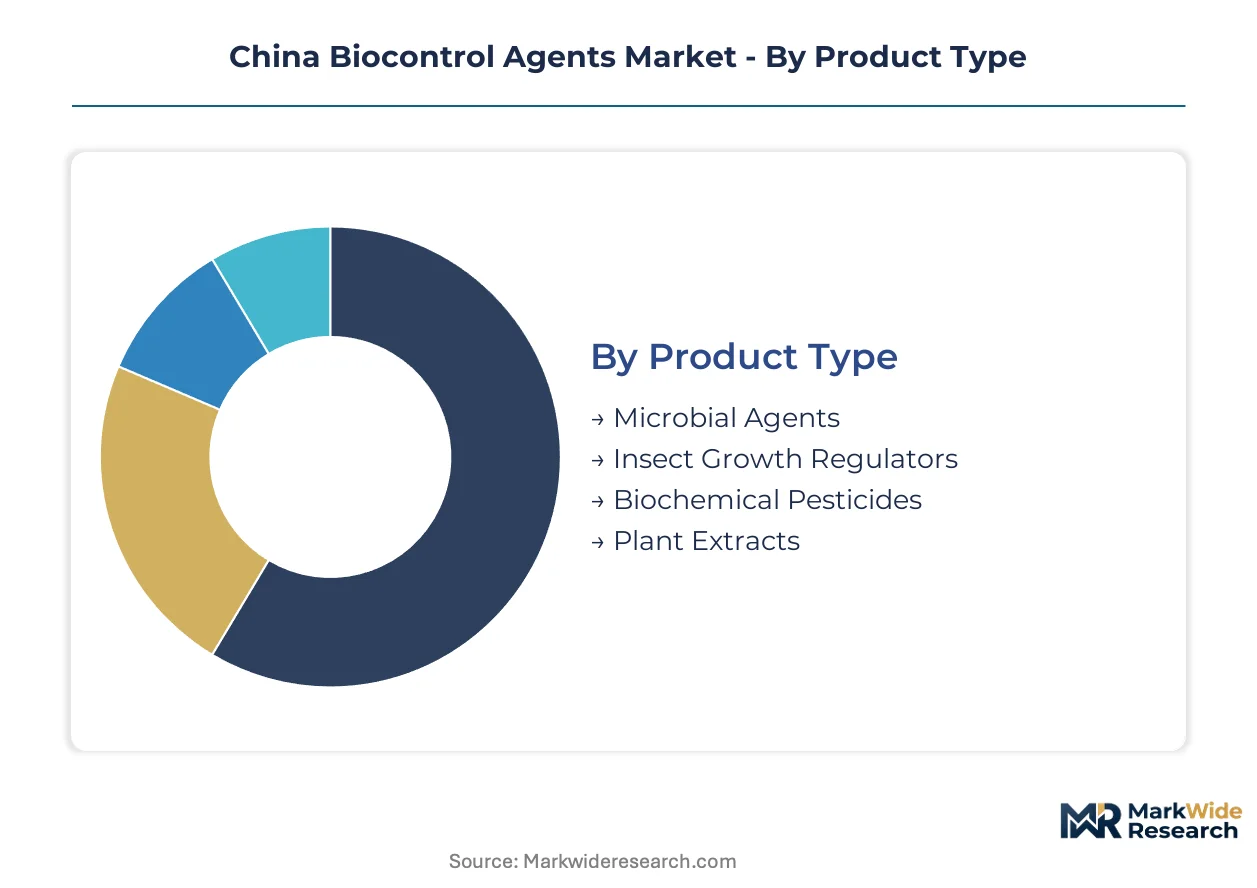
Segmentation in China's biocontrol market determines which products qualify for GB/T 19630 organic certification and MEE export documentation. Procurement committees in Shandong and Jiangsu greenhouse clusters now specify segment-level compliance requirements in supplier contracts.
Product Type:
Certification burden varies sharply across product categories, with microbial agents requiring strain patent documentation and plant extracts demanding heavy metal testing under GB 2763 residue protocols.
- Microbial Agents:Living organisms—primarily Bacillus thuringiensis, Trichoderma, and Pseudomonas—formulated at 10^6 to 10^9 CFU per hectare. Greenhouse operators in the Yangtze River Delta concentrate procurement here for tomato and cucumber exports to the European Union, where MEE documentation requirements favor established strain lineages with multi-year field efficacy data.
- Insect Growth Regulators:Synthetic mimics of juvenile hormones and ecdysteroids that disrupt molting cycles without direct toxicity. Shandong fruit fly management programs absorb the bulk of domestic demand, though registration timelines with the Ministry of Agriculture and Rural Affairs lag microbial alternatives by 8-12 months.
- Biochemical Pesticides:Naturally occurring substances like pheromones and plant growth regulators. Require SAMR registration distinct from conventional pesticides.
- Plant Extracts:Botanical compounds derived from neem, pyrethrum, and other species. Heavy metal contamination screening adds 15-20% to testing costs under GB 2763 protocols.
Microbial Agents sit at the top of the volume ranking, with Plant Extracts climbing the fastest as European Union organic importers diversify active ingredient portfolios.
Application:
Cost tiering separates export-oriented operations absorbing premium biocontrol pricing from domestic-market growers optimizing input costs per hectare.
- Agricultural Crops:Rice, wheat, and corn systems across the Yangtze and Yellow River basins. Drip irrigation retrofitting in Jiangsu and Anhui enables liquid microbial inoculation at planting, though scale economics favor chemical pesticides in grains destined for domestic feed markets.
- Horticultural Crops:Greenhouse tomatoes, cucumbers, and peppers in Shandong, Jiangsu, and Zhejiang. European Union organic certification premiums justify 3-4x biocontrol input costs versus conventional chemicals.
- Turf Management:Golf courses and municipal parks in Beijing, Shanghai, and Shenzhen. MEE environmental compliance audits drive substitution away from banned herbicides.
- Post-Harvest Treatment:Storage and transport applications for fruit exports. SAMR food contact approvals limit supplier pool to established microbial formulation houses.
Horticultural Crops command the highest per-hectare biocontrol spend, with Post-Harvest Treatment expanding most quickly as stone fruit exporters to Southeast Asia adopt biological coatings.
Formulation Type:
Application infrastructure maturity determines formulation preference, with precision agriculture zones favoring liquid compatibility and labor-constrained regions defaulting to granular broadcast methods.
- Liquid Formulations:Aqueous suspensions and emulsifiable concentrates compatible with drip irrigation and aerial drone systems. The Yangtze River Delta's retrofitting of greenhouse fertigation infrastructure positions liquid products for steepest adoption curves, though summer transport through inland provinces degrades viable colony-forming units without cold chain investment.
- Granular Formulations:Clay or peat-based carriers embedding microbial spores for soil incorporation. Sichuan and Yunnan highland vegetable zones lacking drip infrastructure rely on manual broadcast application.
- Powder Formulations:Dry flowable and wettable powder variants for dusting and spray tank mixing. Shelf stability exceeds liquid alternatives but requires agitation equipment scarce in smallholder cooperatives.
- Coated Granules:Polymer-encapsulated slow-release variants. Premium pricing limits deployment to high-value horticultural export operations.
Liquid Formulations lead current volume, with Coated Granules gaining share fastest among drone-application rice paddy operators.
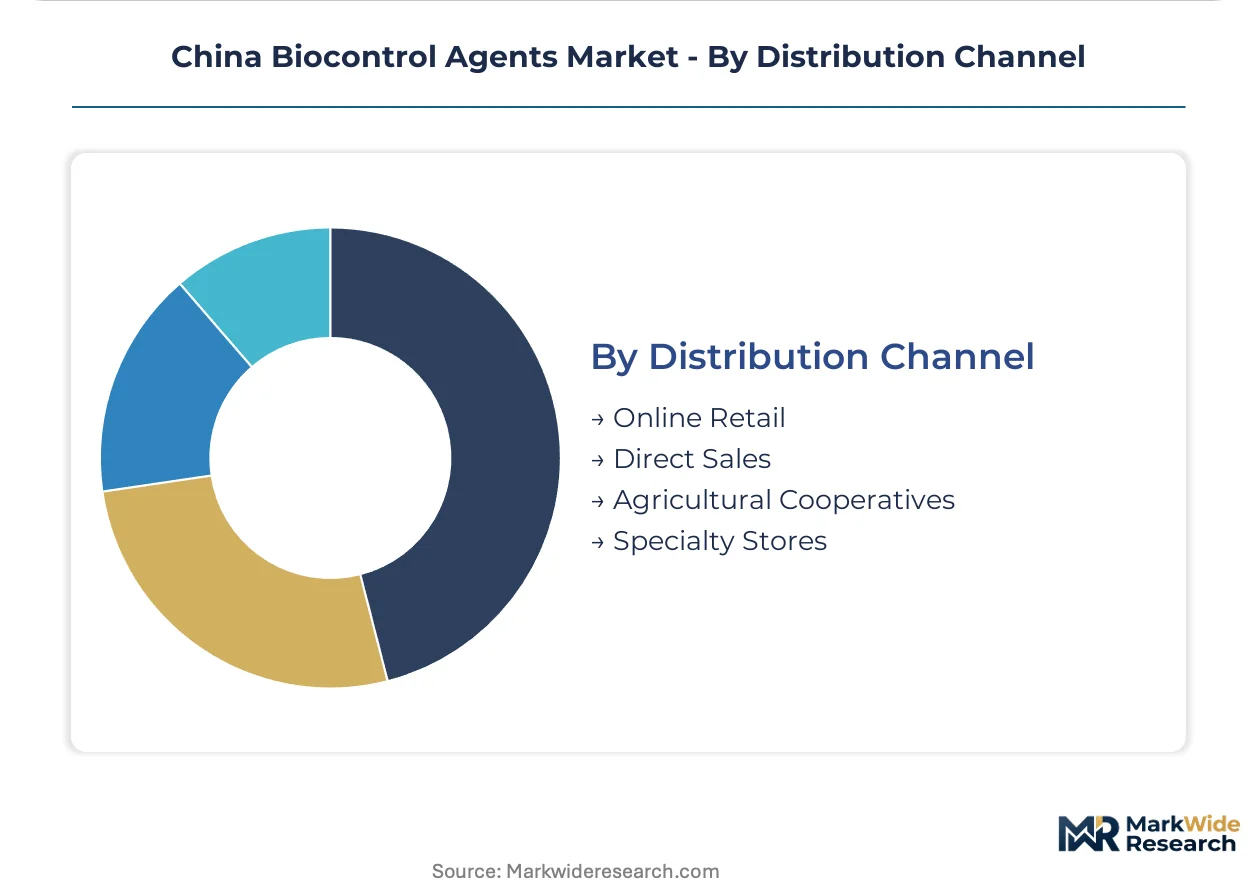
Distribution Channel:
Customer type fragmentation—state farms, private greenhouse cooperatives, individual smallholders—drives channel specialization and technical service bundling requirements.
- Direct Sales:Manufacturer technical teams contract directly with Shandong and Jiangsu greenhouse cooperatives exceeding 50 hectares. Strain technical support and MEE documentation services bundle with product supply, consolidating vendor relationships from twelve to three per procurement committee.
- Agricultural Cooperatives:Provincial and county-level buying consortia aggregate smallholder demand. Credit terms and seasonal delivery scheduling match legacy chemical pesticide distributor relationships.
- Specialty Stores:County-level agrochemical retailers with technical staff trained in microbial application timing. Inventory turnover constraints favor shelf-stable granular and powder formulations over liquid alternatives.
- Online Retail:E-commerce platforms reaching individual smallholders in underpenetrated southwestern provinces. Product quality verification and cold chain logistics remain unresolved.
Direct Sales captures the highest revenue per transaction, with Online Retail ascending most quickly as platform operators invest in agricultural specialist verification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's biocontrol industry traces its commercial roots to the state-run microbial pesticide programs of the 1970s, which established fermentation infrastructure still serving today's private manufacturers. Provincial specialization now concentrates production capacity and application expertise across distinct agricultural zones.
Shandong Province
Greenhouse vegetable operators in Weifang and Qingzhou are expanding microbial agent procurement to meet European Union organic certification requirements for tomato and cucumber exports. The provincial agriculture bureau channels GB/T 19630 conversion subsidies toward cooperatives exceeding 50 hectares. Shandong's horticulture belt now hosts the densest concentration of full-service biocontrol technical teams.
Jiangsu Province
Precision agriculture zones across the Yangtze River Delta are retrofitting drip irrigation infrastructure for liquid microbial inoculation at planting. Nanjing and Suzhou greenhouse clusters absorb premium-priced Bacillus formulations for export-oriented pepper and eggplant production. Provincial environmental compliance audits now require biocontrol documentation under MEE protocols for EU-bound shipments.
Zhejiang Province
Hangzhou and Ningbo agricultural technology parks pilot CRISPR-enhanced Bacillus subtilis strains with accelerated surfactin production for fungal suppression. The provincial science and technology commission funds eight-week validation protocols replacing traditional six-month field trials. Zhejiang's export vegetable cooperatives are consolidating supplier relationships from twelve vendors to three full-service partners.
Sichuan Province
Highland vegetable zones around Chengdu lack established microbial agent distribution networks, presenting first-mover channel establishment potential for liquid and granular formulation suppliers. The provincial agricultural bureau maintains looser chemical pesticide oversight than eastern counterparts, though GB 2763 residue limits still constrain export-oriented growers. Cold chain infrastructure gaps restrict summer transport of viable colony-forming units from coastal production facilities.
Yunnan Province
Kunming and surrounding plateau agriculture districts rely on manual broadcast application of granular microbial formulations due to absent drip irrigation infrastructure. The provincial commerce department targets Southeast Asian fruit export growth, creating demand for post-harvest biocontrol coatings. Yunnan's flower export industry drives early adoption of bumblebee pollination-biocontrol bundling services.
China Biocontrol Agents Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technical service bundling and strain documentation capabilities. The market structures around three tiers: international agricultural biotechnology holders with core Bacillus and Pseudomonas strain patents, domestic manufacturers with in-house fermentation capacity, and regional distributors with embedded greenhouse cooperative relationships. Consolidation pressures favor suppliers guaranteeing efficacy outcomes over per-liter pricing. Dominant competitive moves include backward integration into substrate production and geographic expansion into underpenetrated southwestern provinces.
Among international specialists, Koppert Biological Systems Inc. and Biobest Group NV exemplify the pollination-biocontrol bundling archetype securing greenhouse contracts through technical service integration. BASF SE anchors the fermentation-integrated tier with captive Bacillus-based formulation capacity. Genliduo Bio-Tech Corporation Ltd. represents domestic strain development specialists targeting regional pest profiles in eastern provincial markets. These three occupy distinct positioning vectors rather than direct price competition, with technology licensing and provincial quota access serving as primary differentiation levers.
| Leading Market Players |
|---|
| Koppert Biological Systems Inc. |
| Biobest Group NV |
| Henan Jiyuan Baiyun Industry Co. Ltd |
| Andermatt Group AG |
| Isagro SPA |
| Valent Biosciences LLC |
| Biolchim SPA |
| Genliduo Bio-Tech Corporation Ltd. |
| BASF SE |
| Others |
Pricing and Supply Chain Analysis
Molasses and soybean meal price indices cascade through Bacillus thuringiensis substrate production into three distinct pricing tiers for microbial formulations, with fermentation input volatility compressing margins for domestic manufacturers while export-oriented greenhouse operators absorb premium pricing for MEE-compliant documentation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates full-service biocontrol partners with strain technical support from commodity microbial suppliers and generic formulation traders. Price differentiation centers on GB/T 19630 organic certification grade and bundled MEE documentation services for EU-bound exports. Pricing pressure stems from fermentation input cost swings, with Shandong greenhouse cooperatives least price-sensitive due to organic export premiums and Sichuan smallholders most sensitive due to absent drip irrigation infrastructure.
Supply Chain Analysis
GB 2763 residue compliance and MEE environmental audit documentation gate supplier qualification, with production concentrated in Shandong, Jiangsu, and Zhejiang provinces where 1970s state-run microbial pesticide programs established enduring fermentation infrastructure. Raw material dependencies center on molasses, soybean meal, and pharmaceutical-grade carriers for spore stabilization. Single-source vulnerability runs through core Bacillus and Pseudomonas strain patents held by international agricultural biotechnology holders. Distribution runs through direct sales technical teams for large greenhouse cooperatives and provincial agricultural cooperatives aggregating smallholder demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's biocontrol agents market compounds steadily as GB 2763 maximum residue limits tighten chemical pesticide thresholds, forcing compliance-driven procurement switches across eastern provincial greenhouse belts.
For Market Incumbents: Lock in full-service biocontrol partnerships by consolidating technical support capabilities and securing backward integration into substrate production. Defend against emerging domestic strain developers by patenting CRISPR-enhanced Bacillus variants and expanding in-house fermentation capacity in Jiangsu precision agriculture zones.
For New Entrants and Emerging Players: Capture first-mover channel establishment in Sichuan and Yunnan highland vegetable zones where established microbial agent distribution networks remain absent. Target granular formulation supply for manual broadcast application in southwestern provinces lacking drip irrigation infrastructure, leveraging provincial agricultural cooperative credit terms to match legacy chemical distributor relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where microbiologist talent scarcity concentrates strain isolation expertise in Beijing and Shanghai research institutes. Long-term viability favors domestic manufacturers with captive fermentation capacity and MEE documentation bundling capabilities. Watch provincial subsidy quota adjustments as the inflection signal for capacity allocation shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Molasses and soybean meal cost control stabilizes Bacillus thuringiensis fermentation margins against commodity volatility. |
| CRISPR-Enhanced Strain Development | Accelerated surfactin production validation compresses eight-week protocols versus traditional six-month field trials. |
| MEE Documentation Bundling Services | Combined strain supply with compliance paperwork captures EU organic certification export demand in Yangtze River Delta. |
| Drone Application Microencapsulation | Uniform aerial coverage enables rice paddy market penetration previously inaccessible to ground application methods. |
| Southwestern Provincial Channel Expansion | First-mover establishment in Sichuan and Yunnan highland zones exploits absent microbial agent distribution networks. |
Research Methodology
Multiple input streams — primary interviews with fermentation plant managers, greenhouse cooperative procurement committees, and provincial agricultural bureau officials; secondary validation through SAMR registration databases, MEE environmental audit protocols, and GB 2763 residue limit filings; plus customs and trade data — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Segmentation-level data across microbial agents, insect growth regulators, biochemical pesticides, and plant extracts by formulation type and application were reconciled against provincial production capacity disclosures and subsidy program allocations throughout the projection horizon. CAGRs were derived from trend extrapolation of GB/T 19630 organic certification conversion timelines and Shandong greenhouse expansion trajectories, with cross-checks against fermentation infrastructure utilization rates.
Strain patent litigation, provincial subsidy quota reallocations, and summer transport cold chain infrastructure gaps are the dominant revision risks to forecast assumptions. A model refresh is warranted upon material change in MEE environmental audit protocol stringency for EU-bound organic exports.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Italy Biopesticides Market
Bio-Agriculture
North America Biological Organic Fertilizer Market
Bio-Agriculture
Animal Eubiotics Market
Bio-Agriculture
Hydroponics Nutrients Market
Bio-Agriculture
United Kingdom Biopesticides Market
Bio-Agriculture
Biochar Machine Market
Bio-Agriculture
North America Biofertilizer Market
Bio-Agriculture
Bloodroot Market
Bio-Agriculture
Middle East and Africa Animal Genetics Market
Bio-Agriculture
Europe Feed Probiotics Market
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
Africa Biostimulants Market
Bio-Agriculture
Transgenic Animals Market
Bio-Agriculture
United States Bio-Fungicide Market
Bio-Agriculture
Europe Biopesticides Market
Bio-Agriculture
Silage Inoculant and Enzyme Market