
 South America Feed Prebiotics Market | 2026-2036
South America Feed Prebiotics Market Size, Share, and Industry Trends Forecast 2026-2036
South America Feed Prebiotics Market Analytics
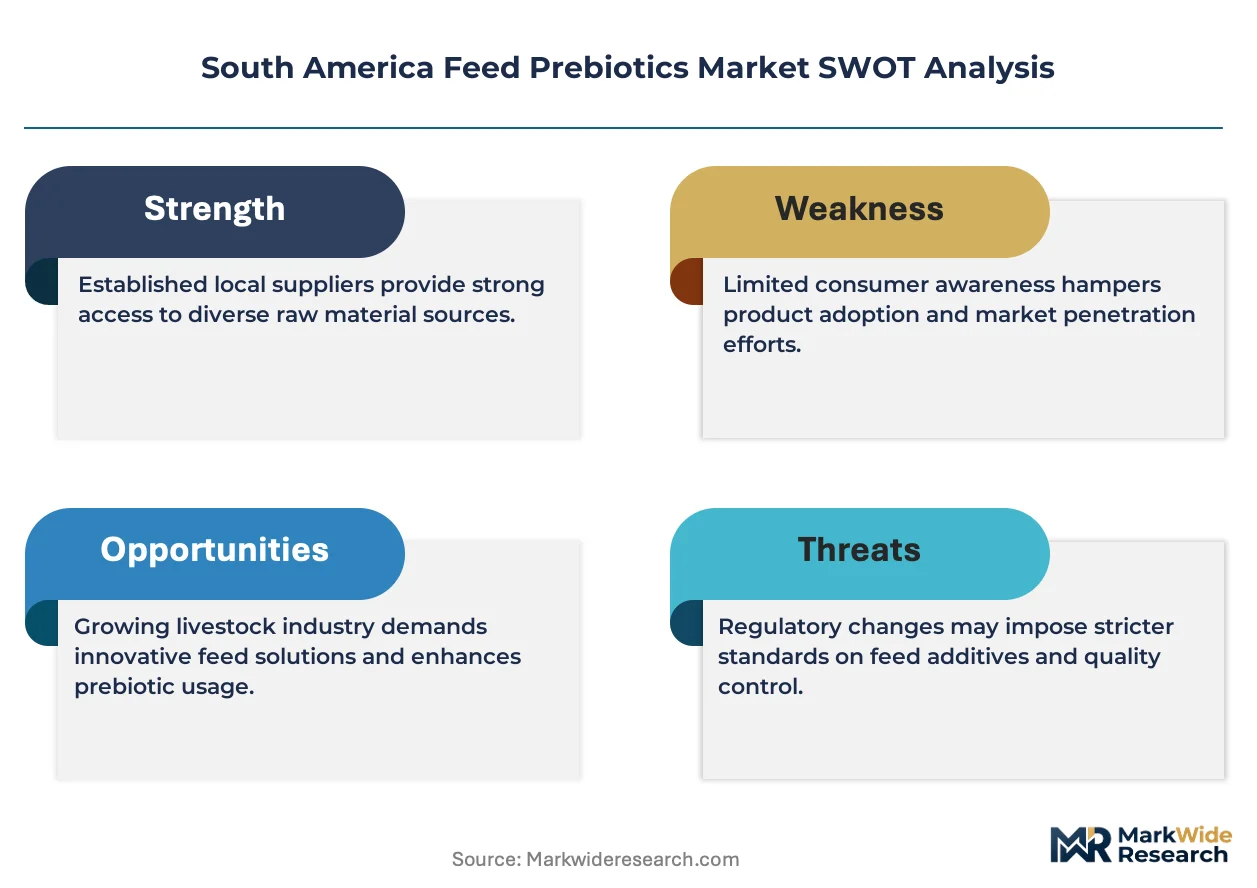
Pharmaceutical-grade prebiotic specifications is reorganizing procurement priorities across South American compound feed operations. Beneo GmbH leverages its chicory-root extraction expertise to dominate inulin supply chains serving Brazilian integrators. Cargill Inc. anchors distribution through its existing nutrition service infrastructure across Argentina and Colombia. Alltech Inc. differentiates via yeast-derived mannan-oligosaccharide portfolios tailored to regional pathogen pressures.
Feed prebiotics are non-digestible oligosaccharides, typically extracted from chicory root or synthesized enzymatically, that selectively stimulate beneficial gut microbiota in monogastric and ruminant animals; standard commercial grades contain minimum 90% inulin or fructooligosaccharide purity with specified degrees of polymerization. Their primary purpose is to improve feed conversion efficiency and reduce therapeutic antibiotic dependence in intensive livestock systems. Inulin and galacto-oligosaccharides command margin premiums due to established efficacy data in poultry gut health applications. Powder formulations lead volume shipments for integration into mash and pelleted feeds, while liquid variants gain traction in automated drinking water supplementation systems for swine operations.
Brazil's MAPA establishes feed additive registration requirements, while ANVISA governs veterinary product quality standards; Argentina's SENASA enforces parallel import and manufacturing compliance protocols. These frameworks elevate documentation burdens for new entrants but reinforce product quality credibility among commercial buyers. Stakeholders must monitor evolving antibiotic reduction mandates across Mercosur jurisdictions to anticipate formulation demand shifts.
Market Dynamics
Antibiotic reduction mandates across Mercosur jurisdictions are compressing formulation timelines and forcing integrators to validate prebiotic efficacy under tighter regulatory scrutiny than ever before.
Growth Catalysts
- ANVISA veterinary oversight harmonization:Streamlined registration pathways accelerate commercialization for feed additive suppliers targeting Brazilian poultry operations.
- Chicory-root extraction scale-up:Domestic processing investments in Paraná state reduce import dependency for inulin raw material.
- Poultry integrator consolidation:Santa Catarina and Rio Grande do Sul integrators are standardizing in-feed additive programs across contract grower networks.
Market Restraints
- Fructan raw material concentration:European chicory-root suppliers control 70% of pharmaceutical-grade inulin feedstock, exposing Brazilian formulators to euro-denominated input volatility.
- SENASA import documentation burdens:Argentina's parallel compliance protocols extend registration timelines by 8-14 months versus MAPA pathways.
- Enzymatic synthesis cost premium:Synthetic galacto-oligosaccharide production remains 40% above extraction-based inulin on a per-kilogram basis.
Strategic Opportunities
- Colombian cattle feed penetration:Ruminant prebiotic applications remain underdeveloped relative to monogastric saturation in southern Brazil.
- Automated drinking water systems:Liquid mannan-oligosaccharide delivery bypasses pelleting temperature degradation constraints in swine nurseries.
- Mercosur antibiotic-free certification:Emerging export market standards create first-mover advantage for validated gut health protocols.
Industry Challenges
- Microbiome assay standardization gaps:Inconsistent CFU enumeration methods across Brazilian and Argentine laboratories complicate efficacy benchmarking.
- Pelleting thermal degradation:Inulin polymerization chains fragment above 85°C, forcing feed mills to retrofit conditioning systems or switch to thermostable alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Feed Prebiotics Market |
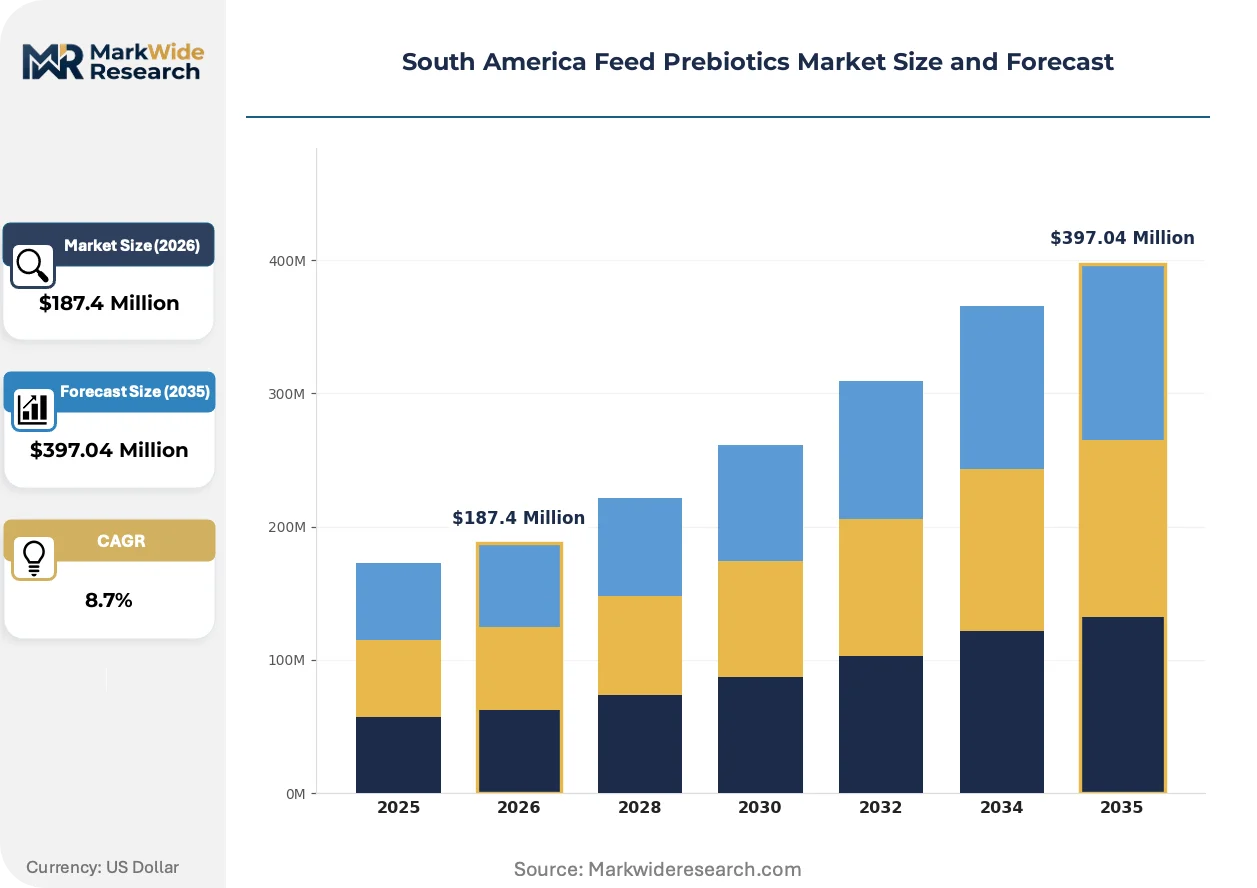
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inulin, Oligofructose, Galacto-Oligosaccharides, Mannan-Oligosaccharides Animal Type: Poultry, Swine, Ruminants, Aquaculture Form: Granules, Powder, Liquid, Tablets Application: Nutritional, Growth Promotion, Digestive Health, Immune Support |
| Companies Covered | Beneo GmbH, BASF SE, Roquette Freres S.A., DuPont, Cargill Inc., Alltech Inc., Adisseo, Cosucra Groupe Warcoing SA, Tereos, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Feed Prebiotics Market Evolving Landscape
Yeast-derived bioactives and precision fermentation are disrupting traditional plant-extraction supply chains while regulatory pressure on antibiotic growth promoters accelerates microbiome-targeted formulation investment.
Fermentation-based mannan-oligosaccharide production is displacing conventional yeast cell wall extraction in Argentine feed mills. Poultry integrators in Buenos Aires province have adopted enzymatically refined variants at twice the 2019 penetration rate. This shift is compressing margins for legacy autolysis-based suppliers while opening capacity for customized polymer-length specifications.
MAPA's updated feed additive positive list creates explicit prebiotic categories distinct from probiotics and acidifiers. Brazilian compound feed operations must now submit polymerization degree data and selective fermentation selectivity proofs. Southern integrators are responding by consolidating supplier audits around laboratories with ISO 17025 microbiome analysis accreditation.
Direct-to-integrator technical service contracts are replacing distributor-mediated ingredient sales in Colombia and Ecuador. Swine operations in Cundinamarca now specify gut health outcomes in procurement tenders rather than accepting standard inclusion rates. This behavior shift concentrates buying power among operations with in-house veterinary nutritionists.
South America Feed Prebiotics Market Segmentation
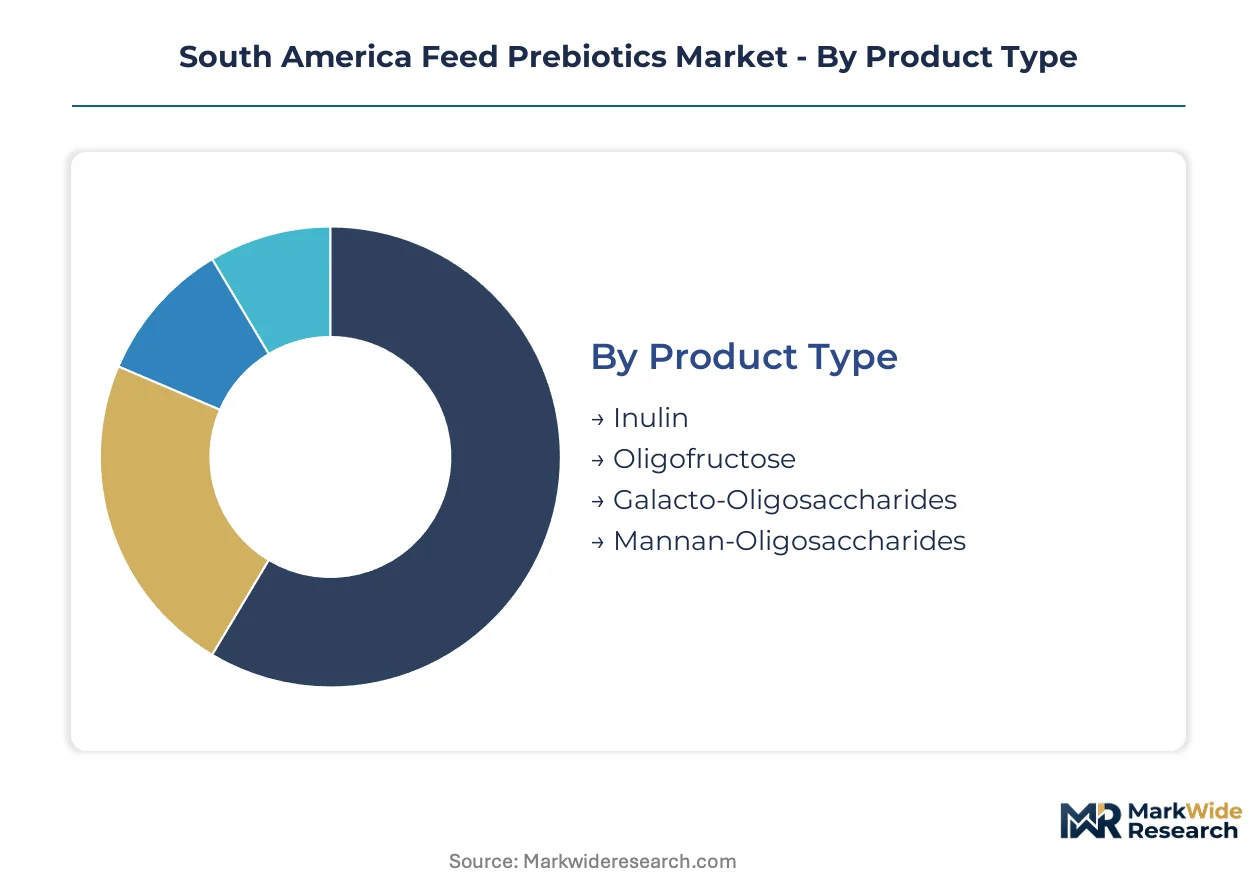
Feed prebiotic segmentation in South America reflects divergent technical requirements across animal production systems and regulatory pathways. Distinct formulation specifications, delivery mechanisms, and efficacy claims create discrete competitive arenas with varying barriers to entry and margin profiles.
Product Type:
Inulin faces the most acute substitution pressure from synthetic galacto-oligosaccharides as enzymatic production costs decline and polymer-length customization becomes commercially viable.
- Inulin:Extracted from chicory root with minimum 90% purity and specified degrees of polymerization. Brazilian poultry integrators in Paraná and Santa Catarina specify pharmaceutical-grade specifications for antibiotic-free certification programs, though thermal degradation above 85°C forces feed mill retrofits.
- Mannan-Oligosaccharides:Yeast-derived bioactives refined through fermentation or autolysis processes. Argentine mills in Buenos Aires province have shifted toward enzymatically refined variants at twice the penetration rate of conventional extraction, driven by pathogen-specific efficacy requirements in broiler operations.
- Oligofructose:Shorter-chain fructans with enhanced solubility for drinking water applications. Colombian swine operations favor this grade for automated delivery systems.
- Galacto-Oligosaccharides:Enzymatically synthesized from lactose feedstock. Production costs remain 40% above extraction-based alternatives, limiting adoption to premium formulation tiers.
Inulin retains volume leadership; galacto-oligosaccharides hold the steepest expansion curve as synthesis economics improve.
Animal Type:
Cost tier stratification separates intensive monogastric systems with dedicated nutrition staff from extensive ruminant operations with lower additive intensity per head.
- Poultry:Brazil's southern belt dominates consumption, with integrators standardizing in-feed programs across contract grower networks. Gut health validation requirements under MAPA's updated positive list concentrate procurement among accredited suppliers.
- Swine:Nursery phase applications drive liquid formulation demand in automated drinking water systems. Cundinamarca operations in Colombia now specify outcome-based procurement tenders.
- Ruminants:Underdeveloped relative to monogastric saturation, with Colombian cattle feed representing the primary expansion opportunity. Microbiome modulation efficacy data remains sparse for forage-based diets.
- Aquaculture:Emerging segment with species-specific formulation requirements. Chilean salmon operations pilot mannan-oligosaccharide inclusion for pathogen resistance.
Poultry commands the largest absolute volume; aquaculture is climbing the fastest as intensive shrimp and finfish production expands.
Form:
Volume concentration favors formats compatible with existing feed mill infrastructure, while liquid systems gain share in operations with veterinary nutritionist staffing.
- Powder:Dominates mash and pelleted feed integration across Brazilian compound feed operations. Thermal degradation constraints force conditioning system retrofits or thermostable alternative selection.
- Liquid:Expanding in swine nurseries and poultry hatcheries with automated drinking water supplementation. Bypasses pelleting temperature constraints but requires calibrated dosing equipment.
- Granules:Flowability advantages for bulk handling in large-scale mill operations. Standard in Argentine feed manufacturing.
- Tablets:Niche format for on-farm top-dressing in smaller operations without integrated feed milling. Limited penetration outside Ecuador and Peru backyard systems.
Powder retains volume leadership; liquid is gaining share fastest as precision delivery infrastructure spreads.
Application:
Margin structure separates commodity nutritional claims from premium immune support positioning with veterinary oversight requirements.
- Digestive Health:Core value proposition with established efficacy data in feed conversion improvement. Brazilian integrators validate through ISO 17025-accredited laboratory partnerships.
- Immune Support:Premium positioning with pathogen-specific claims requiring ANVISA veterinary product oversight. Fastest-growing claim category as antibiotic reduction mandates tighten.
- Nutritional:Baseline prebiotic inclusion without targeted health outcomes. Faces margin compression as outcome-based procurement spreads.
- Growth Promotion:Regulatory-sensitive category overlapping with banned antibiotic growth promoter territory. Formulators must navigate MAPA's explicit prebiotic categorization to avoid compliance violations.
Digestive health retains volume leadership; immune support is expanding most quickly as export certification standards emerge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicory-root processing infrastructure clusters in southern Brazil, creating input dependencies that shape procurement patterns across Mercosur feed operations. Argentine and Colombian markets respond through differentiated regulatory compliance strategies and alternative sourcing pathways.
Brazil
Paraná state's chicory cultivation investments reduce European raw material exposure for inulin processors. MAPA's streamlined feed additive registration compresses commercialization timelines versus historical benchmarks. Santa Catarina and Rio Grande do Sul poultry integrators standardize in-feed prebiotic programs across contract grower networks exceeding 2,000 contracted farms.
Argentina
Buenos Aires province broiler operations drive enzymatically refined mannan-oligosaccharide uptake at twice prior penetration rates. SENASA's parallel import documentation extends registration timelines by 8-14 months relative to Brazilian pathways. Córdoba feed mills concentrate procurement among suppliers with ISO 17025-accredited microbiome validation capabilities.
Colombia
Cundinamarca swine nurseries specify outcome-based gut health procurement tenders rather than standard inclusion rates. The national pharmaceutical regulator governs veterinary product quality standards for immune-support claims. Antioquia cattle feed operations represent the primary underdeveloped vector for ruminant prebiotic applications.
Chile
Salmon aquaculture operations pilot mannan-oligosaccharide inclusion protocols for pathogen resistance in intensive finfish systems. The national fisheries service enforces species-specific additive registration requirements distinct from terrestrial livestock frameworks. Los Lagos region processing facilities concentrate formulation trials for cold-water species applications.
South America Feed Prebiotics Market Competitive Landscape
Concentration sits with European-rooted ingredient specialists controlling pharmaceutical-grade inulin supply chains. Tiered competitive structure separates extraction-based incumbents from fermentation-based challengers and diversified nutrition service providers. Strategic archetypes include chicory-root processors with captive agriculture, yeast-derived bioactive refiners, and integrated feed compounders with technical service infrastructure. Dominant competitive moves encompass backward integration into raw material cultivation and direct-to-integrator technical service contract displacement of distributor channels.
Among European-based specialists, Beneo GmbH and Roquette Freres S.A. exemplify the extraction-based archetype with chicory-root supply chain depth. Cargill Inc. occupies a position representing integrated nutrition service providers leveraging existing distribution infrastructure across Argentine and Colombian markets. These three anchors illustrate divergent strategic vectors: captive raw material control, enzymatic refinement scale, and technical service proximity to end-users.
| Leading Market Players |
|---|
| Beneo GmbH |
| BASF SE |
| Roquette Freres S.A. |
| DuPont |
| Cargill Inc. |
| Alltech Inc. |
| Adisseo |
| Cosucra Groupe Warcoing SA |
| Tereos |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Brazilian poultry integrators and European chicory-root processors lock in both pharmaceutical-grade inulin supply access and euro-denominated price visibility across multi-year procurement cycles. ANVISA's veterinary oversight harmonization compresses commercialization timelines but concentrates buying power among integrators with dedicated veterinary nutritionists who negotiate volume-based tier structures.
Pricing Analysis
MAPA's updated feed additive positive list dictates the pricing tier structure by mandating polymerization degree documentation and selective fermentation selectivity proofs. Three-tier pricing structure across pharmaceutical-grade, standard feed-grade, and economy extraction tiers separates procurement pools, with Brazilian southern belt integrators least price-sensitive due to antibiotic-free certification premiums while Argentine backyard operations face acute cost compression. Price differentiation hinges on ISO 17025 microbiome validation accreditation and thermal stability specifications, with margins tightening in standard grades as enzymatic galacto-oligosaccharide synthesis economics improve.
Supply Chain Analysis
Port congestion at Rotterdam and Antwerp elevates inbound logistics costs for Brazilian formulators sourcing European chicory-root feedstock through Atlantic trade lanes. Supply concentrates in Belgium, France, and the Netherlands for pharmaceutical-grade inulin extraction, while Brazilian domestic processing investments in Paraná state reduce import dependency. Raw material flows draw from chicory root cultivation, yeast biomass fermentation, and lactose feedstock enzymatic conversion, with single-source vulnerability to euro currency volatility representing the dominant structural risk. Distribution runs through Cargill's existing nutrition service infrastructure across Argentina and Colombia, supplemented by direct-to-integrator technical service contracts displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazilian poultry integrator consolidation across Santa Catarina and Rio Grande do Sul contract grower networks exceeding 2,000 farms has shifted procurement leverage toward buyers with in-house veterinary nutritionists and ISO 17025-accredited laboratory partnerships.
For Market Incumbents: Compound defensive positioning through backward integration into Paraná state chicory cultivation and captive fermentation capacity for mannan-oligosaccharide production. Secure MAPA prebiotic category registration ahead of formulation mandate deadlines. Deepen technical service contracts with accredited microbiome validation capabilities to lock out fermentation-based challengers. For New Entrants and Emerging Players: Differentiate on thermostable liquid formulation delivery for Colombian swine nursery automated drinking water systems, bypassing pelleting temperature degradation constraints that plague incumbent powder suppliers. Target Antioquia cattle feed operations as the most penetrable ruminant segment with sparse microbiome modulation efficacy data. Pursue outcome-based procurement tender positioning in Cundinamarca to bypass established inclusion-rate relationships. For Investors and Strategic Acquirers: The market sits at a regulatory harmonization phase that favors extraction-based incumbents with captive raw material control over synthetic fermentation challengers. Long-term viability through the antibiotic reduction mandate window hinges on MAPA registration completion and ANVISA veterinary product pathway navigation. Acquisition target archetype: mid-scale Brazilian compound feed operations with integrated technical service infrastructure and existing integrator relationships. Monitor SENASA import documentation burden reduction as the signal indicating Argentine market opening acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chicory Cultivation | Paraná state processing investments reduce euro-denominated raw material exposure for Brazilian formulators. |
| ISO 17025 Microbiome Validation Accreditation | Southern integrator supplier audits concentrate procurement among laboratories with certified analysis capabilities. |
| Direct-to-Integrator Technical Service Contracts | Cundinamarca swine operations now specify gut health outcomes rather than accepting standard inclusion rates. |
| Thermostable Liquid Formulation Development | Automated drinking water delivery bypasses 85°C pelleting degradation constraints in swine nurseries. |
| Mercosur Antibiotic-Free Certification Alignment | Emerging export market standards create first-mover advantage for validated gut health protocols. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MAPA registration filings, ANVISA veterinary product submissions, and SENASA import compliance records. Primary interviews engaged feed mill procurement directors, poultry integrator veterinary nutritionists, chicory-root processing plant managers, and compound feed distribution channel partners. Secondary validation drew from customs trade data, Mercosur regulatory gazettes, and ISO 17025 accreditation databases. Bottom-up volume estimates triangulated against top-down market sizing across product type, animal species, and application claim dimensions.
Segmentation dimensions modeled span inulin, mannan-oligosaccharides, oligofructose, and galacto-oligosaccharide product types; poultry, swine, ruminant, and aquaculture animal categories; powder, liquid, granule, and tablet formulation formats; and digestive health, immune support, nutritional, and growth promotion applications. CAGRs derived from regression analysis of historical volume trajectories and regulatory mandate implementation schedules. Industry-specific forecast inputs incorporate antibiotic reduction policy timelines and thermal stability specification adoption curves.
Material uncertainties — SENASA documentation burden relaxation, enzymatic synthesis cost parity achievement, and Mercosur export certification standard finalization — sit outside the modeled envelope. Forecasts reflect assumptions regarding MAPA positive list stability and European chicory-root supply continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Microalgae Market
Food Biotechnology
Phycocyanin Market
Food Biotechnology
Flaxseed Gum Market
Food Biotechnology
Bangladesh Starch and Starch Derivative Market
Food Biotechnology
Cultured Meat Market
Food Biotechnology
Bovine Colostrum Market
Food Biotechnology
Carbohydrate Enzyme Preparation Market
Food Biotechnology
Zein Protein Market
Food Biotechnology
Asia Pacific Eubiotics Market
Food Biotechnology
Direct-Fed Microbial Products Market
Food Biotechnology
Perilla Protein Market
Food Biotechnology
Apigenin Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Salmon Polynucleotide (PN) Market
Food Biotechnology
Trypsin Market