
 Biofumigation Market | 2026-2036
Biofumigation Market Size, Share, and Industry Trends Forecast 2026-2036
Biofumigation Market Analysis
Agricultural distributor networks is tilting toward biofumigant-specialized intermediaries as conventional agrochemical channels lose exclusivity. BASF SE leverages its established crop protection infrastructure to anchor shelf presence across European horticulture markets. Marrone Bio Innovations, Inc. competes through R&D intensity in microbial-biofumigant combination therapies. UPL Group extends its geographic dominance via partnerships with regional seed meal processors in India and Brazil.
Biofumigation deploys Brassica-derived glucosinolate hydrolysis products—primarily isothiocyanates and nitriles released upon tissue disruption—to suppress soil-borne pests, pathogens, and weeds without synthetic chemical residues. The process requires specific moisture thresholds and incorporation depths to optimize volatile organic compound release and soil penetration. Mustard seed meal dominates product type revenue due to standardized glucosinolate concentrations and established oilseed crushing coproduction economics. Soil treatment leads application segments because pre-plant incorporation delivers consistent pest suppression across diverse cropping systems. Organic farmers represent the fastest-growing end user category as certification premiums justify higher input costs and labor-intensive application protocols.
EPA biopesticide registration pathways under FIFRA shape product commercialization timelines and label claims for US market entrants. EFSA and EU Green Deal pesticide reduction mandates are restructuring competitive access across European horticulture regions. India's Central Insecticides Board registration requirements under the Insecticides Act govern import and domestic formulation permissions. Stakeholders must monitor evolving residue tolerance harmonization between organic certifiers and national regulators to anticipate market access shifts.
Market Dynamics
The methyl bromide phase-out under the Montreal Protocol has created structural demand displacement toward glucosinolate-based soil treatments, forcing input distributors to rebuild technical service capabilities around Brassica-derived application protocols rather than conventional fumigant handling infrastructure.
Growth Catalysts
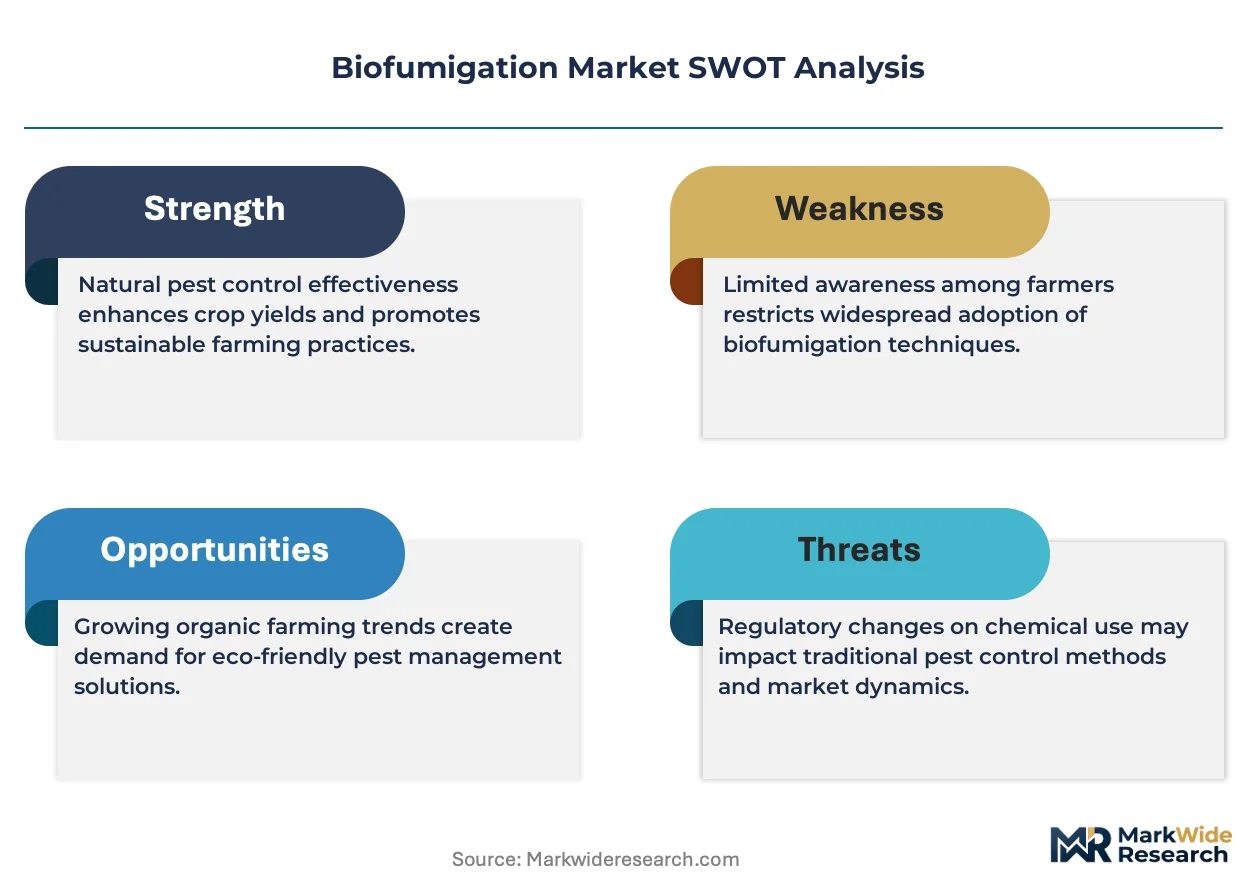
- EU Farm to Fork Strategy:The pesticide reduction mandate accelerates substitution toward biofumigant alternatives in Spanish and Italian specialty crop belts, creating regulatory pull for isothiocyanate-based soil treatments.
- Organic certification premiums:California vegetable producers absorb higher input costs and labor intensity to access price premiums in organic retail channels, expanding acreage under mustard seed meal protocols.
- Soil-borne pathogen resistance:Fusarium and Verticillium wilt pressure in intensive horticulture systems drives adoption of biofumigation as a resistance management rotation tool.
Market Restraints
- Glucosinolate concentration variability:Seed meal quality fluctuates with oilseed crushing coproduction economics, creating input standardization challenges for formulators.
- Application labor intensity:Pre-plant incorporation requires precise moisture thresholds and tillage depth control, elevating operational costs versus shank-injected synthetics.
- Volatile organic compound release timing:Temperature and soil moisture dependency creates efficacy inconsistency that limits adoption in rain-fed cropping systems.
Strategic Opportunities
- Microbial-biofumigant combinations:Convergence of Brassica-derived isothiocyanates with biocontrol inoculants opens synergistic efficacy claims against nematode-pathogen complexes.
- Brazilian expansion:Partnerships with regional seed meal processors unlock access to soybean-corn rotation systems seeking methyl bromide alternatives for nematode suppression.
- Carbon credit monetization:Soil health protocols under voluntary carbon markets create additional revenue streams for growers documenting biofumigation adoption.
Industry Challenges
- Technical service capability gaps:Conventional agrochemical distributors lack expertise in glucosinolate hydrolysis optimization and soil microbiome interaction assessment.
- Residue tolerance harmonization:Divergent standards between USDA organic certifiers and EPA residue tolerance frameworks create label claim uncertainty for multi-certification growers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biofumigation Market |
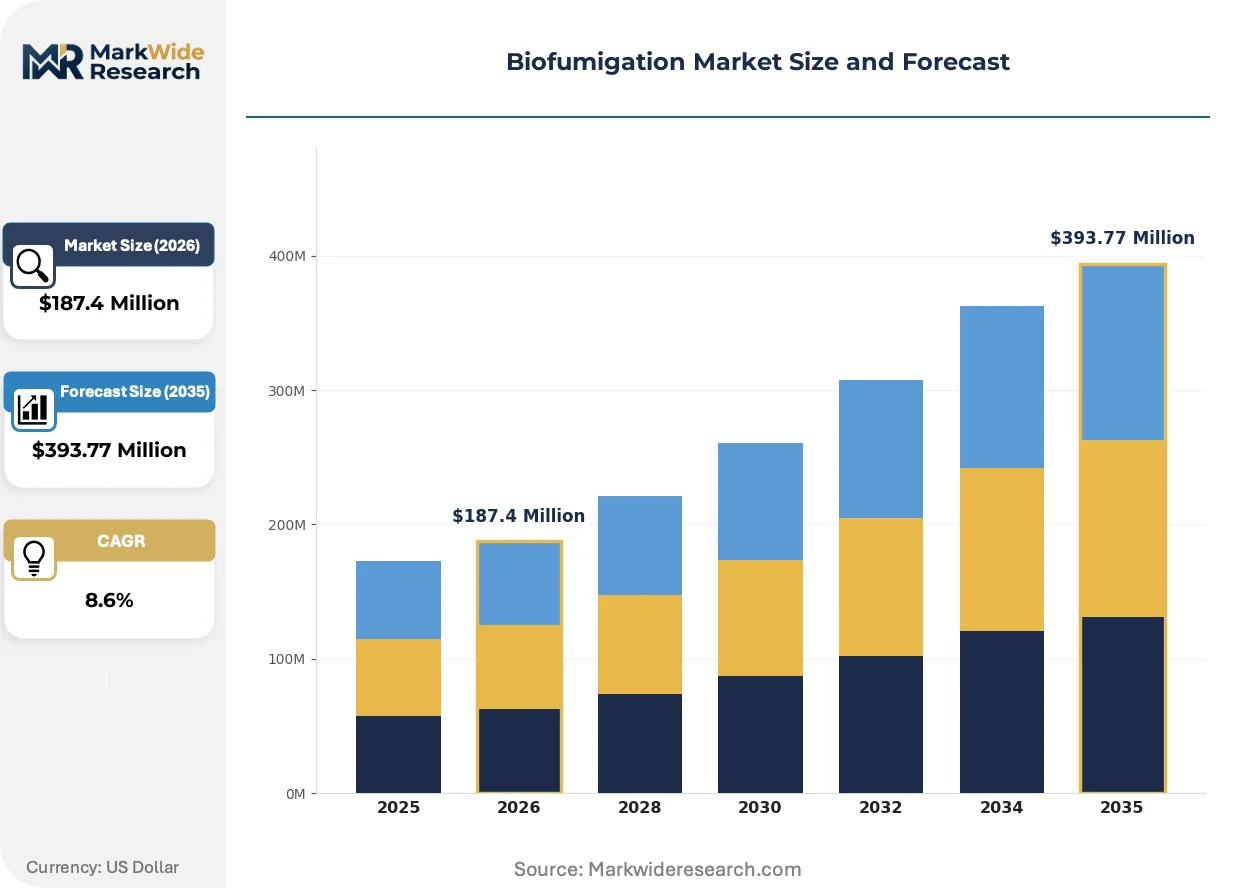
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mustard Seed Meal, Radish Seed Flour, Cabbage Waste, Neem Cake Application: Soil Treatment, Crop Protection, Pest Management, Disease Control End User: Agricultural Producers, Greenhouses, Organic Farmers, Research Institutions Distribution Channel: Online Retail, Agricultural Distributors, Garden Centers, Wholesale Suppliers |
| Companies Covered | Marrone Bio Innovations, Inc., P.H. Petersen, BASF SE, Tozer Seeds, Mighty Mustard, UPL Group, Eastman Chemical Company, Harley Seeds, Isagro USA, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biofumigation Market Emerging Trajectories
Brassica breeding programs and formulation chemistry are converging to standardize isothiocyanate release profiles, while digital agriculture tools enable precision application timing that was previously unavailable to biofumigant users.
Precision delivery systems are hybridizing biofumigation with variable-rate application technology. GPS-guided equipment enables site-specific mustard seed meal placement based on soil pathogen mapping. Large-scale vegetable operations in California's Central Valley deploy these systems to reduce input waste while maintaining suppression thresholds. The technology is hybridizing cost structures toward capital-intensive equipment models that favor consolidated acreage holders over smaller organic producers.
EPA biopesticide registration pathways under FIFRA Section 3 are compressing commercialization timelines for novel glucosinolate formulations. The agency's streamlined review for biochemical pesticides reduces data requirements versus conventional registration. US horticulture regions with methyl bromide critical use exemptions face accelerated label expiration, pushing growers toward EPA-registered biofumigant alternatives with established residue tolerance profiles.
Organic retailers are tightening residue monitoring protocols, altering procurement specifications for contracted growers. Major US grocery chains now require third-party soil treatment documentation for organic vegetable suppliers. California's Salinas Valley and Spain's Almería region exhibit the most visible compliance investment, with packer-shippers absorbing certification audit costs to secure shelf access. This behavioral shift elevates biofumigation preference where synthetic residue risk threatens contract renewal.
Biofumigation Market Segmentation
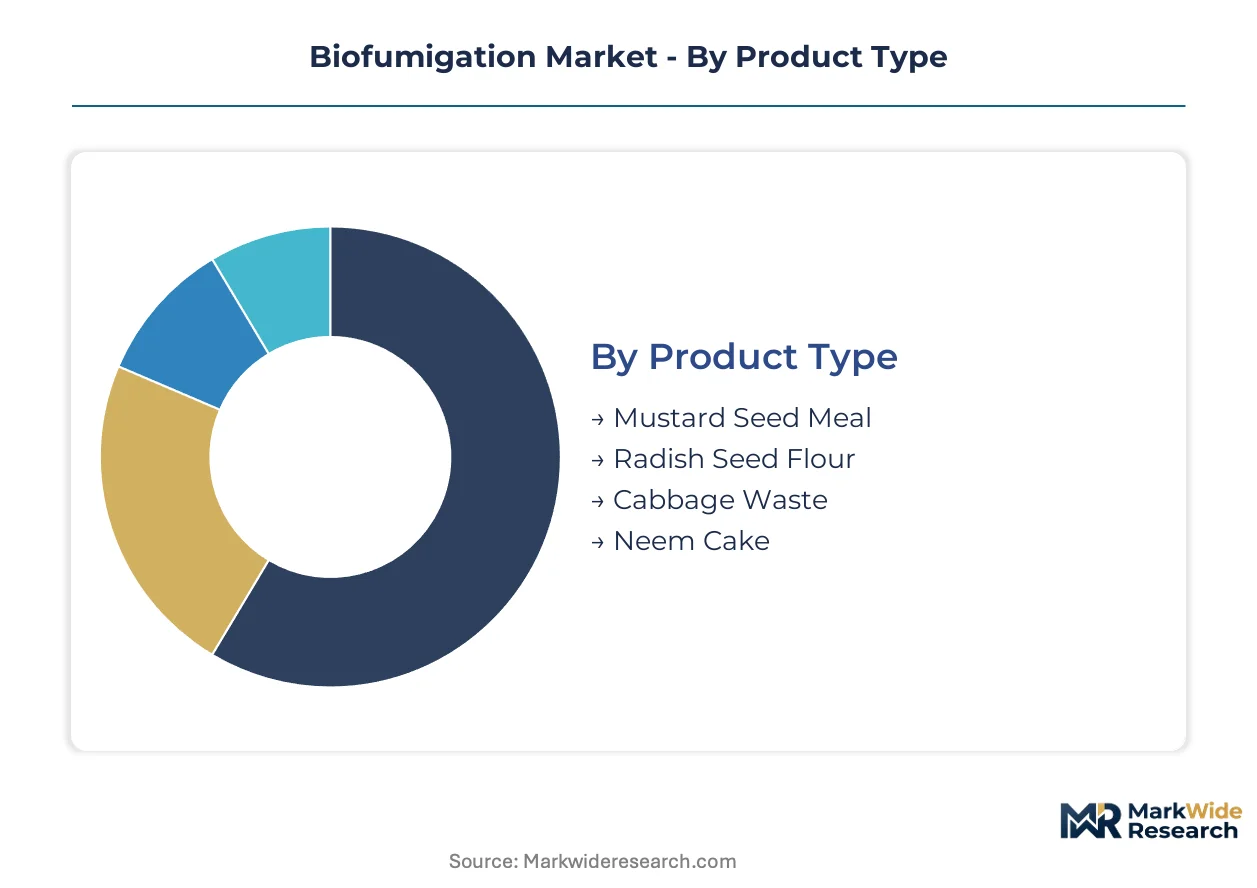
Biofumigation markets fragment across input chemistry, application protocol, and buyer sophistication. Each dimension carries distinct margin structures and technical service requirements that reshape competitive positioning.
Product Type:
Glucosinolate concentration and oilseed crushing coproduction economics determine input standardization and cost structures across Brassica-derived formulations.
- Mustard Seed Meal:Standardized glucosinolate profiles from established oilseed processing deliver consistent isothiocyanate release upon soil incorporation. California Central Valley vegetable operations absorb premium pricing for certified organic meal to secure retail contract compliance.
- Radish Seed Flour:Higher glucoraphanin content generates distinct nitrile-to-isothiocyanate ratios suited for nematode-specific suppression protocols. Italian greenhouse operators in Campania favor radish flour for Meloidogyne management in tomato rotation systems.
- Cabbage Waste:Post-harvest processing residues offer variable glucosinolate loads dependent on cultivar and seasonal timing. Spanish Almería cooperatives aggregate cabbage trimmings from frozen food processors for cost-sensitive open-field applications.
- Neem Cake:Azadirachtin-biofumigant synergy targets insect-pathogen complexes in tropical horticulture. Indian Maharashtra grape growers combine neem cake with mustard meal for dual-mode nematode suppression.
The dominant share belongs to Mustard Seed Meal, while Radish Seed Flour is closing the gap fastest.
Application:
Pre-plant versus in-season timing dictates equipment requirements and labor intensity across cropping systems.
- Soil Treatment:Pre-plant incorporation at 15-20cm depth maximizes volatile organic compound penetration and pathogen suppression window. Large-scale Salinas Valley lettuce operations deploy GPS-guided tillage for precision placement.
- Crop Protection:Foliar-adjacent banding targets rhizosphere pests without full-field disruption. Florida strawberry producers use localized application to preserve beneficial soil microbiome in perennial beds.
- Pest Management:Nematode-focused protocols emphasize soil temperature thresholds for hatch synchronization. Brazilian São Paulo citrus growers time applications to Meloidogyne juvenile emergence peaks.
- Disease Control:Fusarium and Verticillium suppression requires extended anaerobic phases post-incorporation. Dutch greenhouse tomato operations seal treated soils with plastic mulch to prolong biofumigant activity.
Soil Treatment commands the volume base, though Disease Control applications are expanding most quickly in intensive horticulture regions.
End User:
Certification status and scale determine input cost tolerance and technical support needs.
- Agricultural Producers:Conventional specialty crop operators weigh biofumigation against synthetic fumigant cost structures and labor availability. Washington state apple replant programs substitute mustard meal for 1,3-dichloropropene in nematode suppression.
- Greenhouses:Controlled-environment agriculture demands rapid turnaround between crop cycles. Mexican protected horticulture clusters near Querétaro adopt biofumigation to avoid synthetic residue detection in export shipments.
- Organic Farmers:Certification premiums justify higher input costs and labor-intensive protocols. German Demeter biodynamic vegetable growers document biofumigation for carbon credit verification under voluntary soil health programs.
- Research Institutions:University extension services develop region-specific application protocols and train distributor technical staff. UC Davis and Wageningen University anchor global biofumigation research networks.
Agricultural Producers absorb the largest volume, yet Organic Farmers are climbing the fastest as certification premiums expand acreage conversion.
Distribution Channel:
Channel selection reflects buyer scale, technical sophistication, and proximity to application timing.
- Online Retail:Small-scale and hobbyist growers access packaged meal products with standardized application guides. Amazon and specialty agriculture platforms serve suburban organic gardeners in North American and European markets.
- Agricultural Distributors:Full-service agronomy support including soil testing and application equipment rental. Wilbur-Ellis and Helena Agri-Enterprises rebuild technical capabilities around Brassica-derived protocols.
- Garden Centers:Consumer-facing retail with limited technical service for residential and small-farm segments. Independent garden center chains in France and Italy stock mustard meal alongside organic fertilizer lines.
- Wholesale Suppliers:Bulk procurement for large-scale operations with in-house application equipment. California Central Valley cooperatives negotiate direct contracts with oilseed processors for meal supply security.
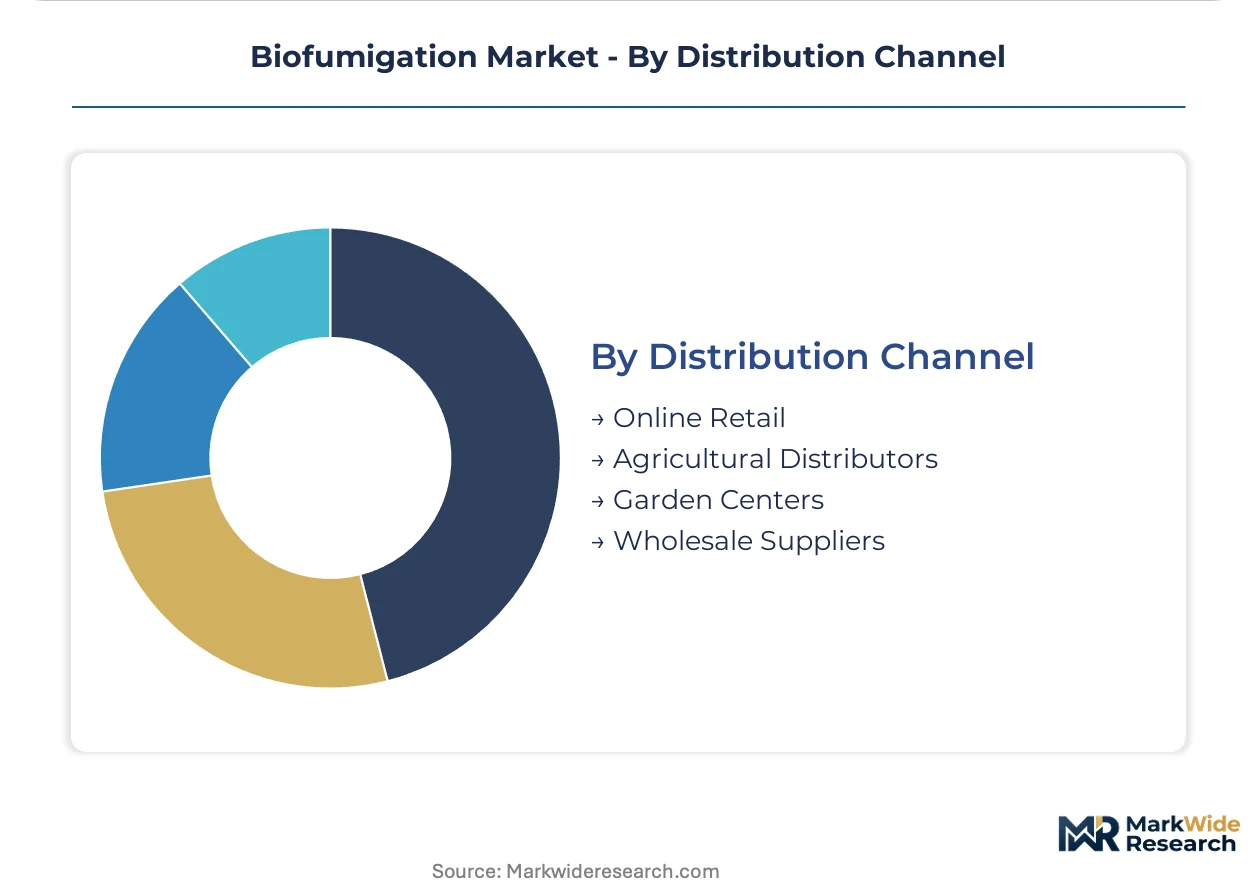
Agricultural Distributors retain the dominant position, while Online Retail is gaining share fastest among entry-level organic producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Farm to Fork Strategy's pesticide reduction mandate is redirecting procurement budgets toward glucosinolate-based soil treatments across Mediterranean horticulture belts. National regulators are tightening residue tolerances while grower cooperatives absorb certification audit costs to secure organic retail contracts.
United States
California's Central Valley vegetable operations drive mustard seed meal demand as methyl bromide critical use exemptions expire. EPA biopesticide registration pathways under FIFRA Section 3 compress commercialization timelines for novel formulations. Salinas Valley lettuce growers deploy GPS-guided tillage for precision biofumigant placement.
Spain
Almería's greenhouse cooperatives aggregate cabbage processing residues for cost-sensitive open-field applications. EFSA residue tolerance frameworks restructure competitive access across Andalusian horticulture regions. Spanish specialty crop distributors rebuild technical service capabilities around Brassica-derived application protocols.
Italy
Campania's tomato rotation systems favor radish seed flour for Meloidogyne nematode suppression in protected agriculture. EU Green Deal pesticide reduction mandates accelerate substitution toward isothiocyanate-based alternatives. Italian greenhouse operators near Naples seal treated soils with plastic mulch to prolong biofumigant activity.
India
Maharashtra grape growers combine neem cake with mustard meal for dual-mode nematode suppression in tropical horticulture. The Central Insecticides Board registration requirements under the Insecticides Act govern import and domestic formulation permissions. UPL Group partnerships with regional seed meal processors anchor supply security across western India.
Brazil
São Paulo citrus growers time biofumigant applications to Meloidogyne juvenile emergence peaks in soybean-corn rotation systems. The country's national agricultural regulator monitors residue tolerance harmonization for export shipment compliance. Brazilian cooperatives seek methyl bromide alternatives as international phase-out deadlines approach.
Biofumigation Market Vendor Landscape
On the supply side, the industry is bifurcating between multinational agrochemical incumbents and specialized biopesticide innovators. Established crop protection networks compete with regional seed meal processors for distributor shelf presence. Three strategic archetypes dominate: integrated oilseed processors leveraging crushing coproduction economics, microbial-biofumigant combination specialists, and distributor-anchored technical service providers. Competitive moves concentrate on partnerships with regional processors and R&D intensity in formulation chemistry.
Within the integrated agrochemical tier, BASF SE anchors European horticulture market presence through established crop protection infrastructure. Marrone Bio Innovations, Inc. occupies a position among R&D-intensive specialists developing microbial-biofumigant combination therapies. UPL Group exemplifies geographic expansion strategy via partnerships with seed meal processors in India and Brazil.
| Leading Market Players |
|---|
| Marrone Bio Innovations, Inc. |
| P.H. Petersen |
| BASF SE |
| Tozer Seeds |
| Mighty Mustard |
| UPL Group |
| Eastman Chemical Company |
| Harley Seeds |
| Isagro USA, Inc. |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp barge freight corridors for oilseed meal shipments impose cost dynamics that amplify pricing power among crushing coprocessors while forcing downstream differentiation between certified organic and conventional mustard meal tiers across European horticulture supply chains.
Pricing Analysis
Certification level (USDA organic versus conventional) creates the primary spread between mustard seed meal tiers. Three-tier pricing structure across premium organic, transitional, and economy conventional levels dominates transactional models. Cost compression in economy tiers is intensifying because oilseed crushing capacity expansions in India and Brazil are flooding spot markets. Organic vegetable producers in California's Central Valley exhibit the lowest price sensitivity due to retail contract premiums, while open-field Spanish cooperatives absorb the highest price pressure.
Supply Chain Analysis
Regional seed meal processors in India, Brazil, and the United States hold dominant crushing capacity for Brassica-derived inputs. Supply chains draw from rapeseed-mustard seed oil crushing coproduction, neem cake azadirachtin extraction, and cabbage waste aggregation from frozen food processors. Single-source vulnerability concentrates around monsoon-dependent Indian mustard harvests that feed global glucosinolate supply. Distribution runs through agricultural distributor networks that are rebuilding technical service capabilities around biofumigant application protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biofumigation markets are recovering from methyl bromide phase-out cyclicality as regulatory deadlines force substitution investments across specialty crop belts.
For Market Incumbents: Pre-empt microbial-biofumigant combination patent filings before Marrone Bio Innovations extends its R&D lead in nematode-pathogen complex therapies. Anchor shelf presence through backward integration into regional oilseed crushing assets in India and Brazil, mirroring UPL Group's partnership strategy. Lock in California Central Valley cooperatives with multi-year certified organic meal offtake agreements to block BASF SE's distributor channel control. For New Entrants and Emerging Players: Brazilian soybean-corn rotation systems underpenetrated by glucosinolate-based nematode suppression represent the most accessible white-space target. Radish seed flour for Meloidogyne-specific protocols in Italian Campania greenhouse clusters offers a second entry vector. Pursue direct partnerships with São Paulo citrus grower cooperatives rather than competing through established agrochemical distributor networks. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational agrochemical parents divesting non-core biopesticide divisions as they consolidate around synthetic crop protection. Five-to-ten year viability hinges on EU Farm to Fork Strategy pesticide reduction mandate durability and organic certification premium sustainability. Monitor EFSA residue tolerance framework harmonization negotiations with USDA organic certifiers as the critical inflection signal for multi-certification grower contract volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Microbial-Biofumigant Combination Development | Marrone Bio Innovations anchors R&D leadership in synergistic nematode-pathogen therapies. |
| Regional Seed Meal Processor Partnership | UPL Group extends geographic dominance via India and Brazil crushing coproduction economics. |
| Precision Application Technology Deployment | California Central Valley lettuce operations deploy GPS-guided tillage for input waste reduction. |
| Carbon Credit Verification Protocol | German Demeter biodynamic growers document biofumigation for voluntary soil health program revenue. |
| EPA Biopesticide Registration Acceleration | FIFRA Section 3 streamlined review compresses novel glucosinolate formulation commercialization timelines. |
Methodological Framework
A spread of perspectives from oilseed crushing plant managers, organic certification auditors, agricultural distributor technical service leads, and specialty crop procurement officers converged on the working assumptions shaping demand projections. Primary fieldwork combined with secondary validation from EPA biopesticide registration databases, EFSA residue tolerance frameworks, EU Farm to Fork Strategy implementation reports, and oilseed trade flow customs data. Bottom-up acreage adoption modeling and top-down input supplier revenue triangulation anchored volume estimates.
Demand-supply balance dynamics across the projection horizon reflect segmentation by product type, application protocol, end-user certification status, and distribution channel sophistication. Modeled dimensions include glucosinolate concentration grade, pre-plant versus in-season timing, organic versus conventional farm scale, and direct wholesale versus distributor-mediated procurement. CAGRs were derived from fitted adoption curves calibrated to methyl bromide critical use exemption expiration schedules and EU Green Deal pesticide reduction milestone compliance patterns.
Practitioners should monitor oilseed crushing capacity utilization rates, organic certification premium compression in retail channels, and EFSA-USDA residue tolerance harmonization progress for early signals of forecast revision. Quarterly review of EPA biopesticide registration approval velocities and EU member state Farm to Fork implementation variance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Artificial Insemination Market
Bio-Agriculture
China Feed Probiotics Market
Bio-Agriculture
China Biofuels Market
Bio-Agriculture
Bio Rational Fungicides Market
Bio-Agriculture
Bioherbicides Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
Latin America Biopesticide Market
Bio-Agriculture
US Biofungicide Market
Bio-Agriculture
Microphytes Market
Bio-Agriculture
North America Biological Organic Fertilizer Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
Seed Biostimulants Market
Bio-Agriculture
Africa Biological Organic Fertilizers Market
Bio-Agriculture
France Biopesticides Market
Bio-Agriculture
Bloodroot Market
Bio-Agriculture
Global Biofortification Market