
 India Biocontrol Agents Market | 2026-2036
India Biocontrol Agents Market Size, Share, and Industry Trends Forecast 2026-2036
India Biocontrol Agents Market Insights
Buyer concentration among Maharashtra and Karnataka agricultural cooperatives is hardening as farmer producer organizations consolidate procurement of microbial inoculants. T. Stanes and Company Limited anchors its position through century-old distribution relationships across south Indian plantation belts. Koppert Biological Systems leverages its Dutch parentage to introduce specialized Trichoderma strains calibrated for tropical humidity regimes. Manidharma Biotech Private Limited competes through aggressive pricing on Bacillus thuringiensis formulations aimed at vegetable-growing clusters.
Biocontrol agents comprise living organisms or their derivatives—predominantly fungal propagules, bacterial endospores, botanical extracts, and synthetic pheromone lures—formulated to suppress agricultural pests below economic injury thresholds through antagonism, competition, or behavioral disruption. Microbial products dominate current volumes, with Trichoderma and Pseudomonas preparations commanding the largest share of farmer expenditure; botanical segments extract margin from neem-based azadirachtin concentrates positioned against export-oriented residue compliance. Application concentration tilts heavily toward agricultural crops, though horticultural products generate premium pricing from integrated pest management mandates in grape and pomegranate belts.
BIS certification requirements for microbial pesticide formulations and CDSCO oversight on novel strain registrations create compliance barriers that favor established domestic manufacturers over import-dependent entrants. The PLI scheme for agrochemical manufacturing extends eligibility to biopesticide fermentation infrastructure, redirecting capital toward domestic spore production capacity. Stakeholders must monitor how state-level organic farming missions in Gujarat and Madhya Pradesh revise input subsidy lists to include or exclude specific biocontrol categories.
Market Dynamics
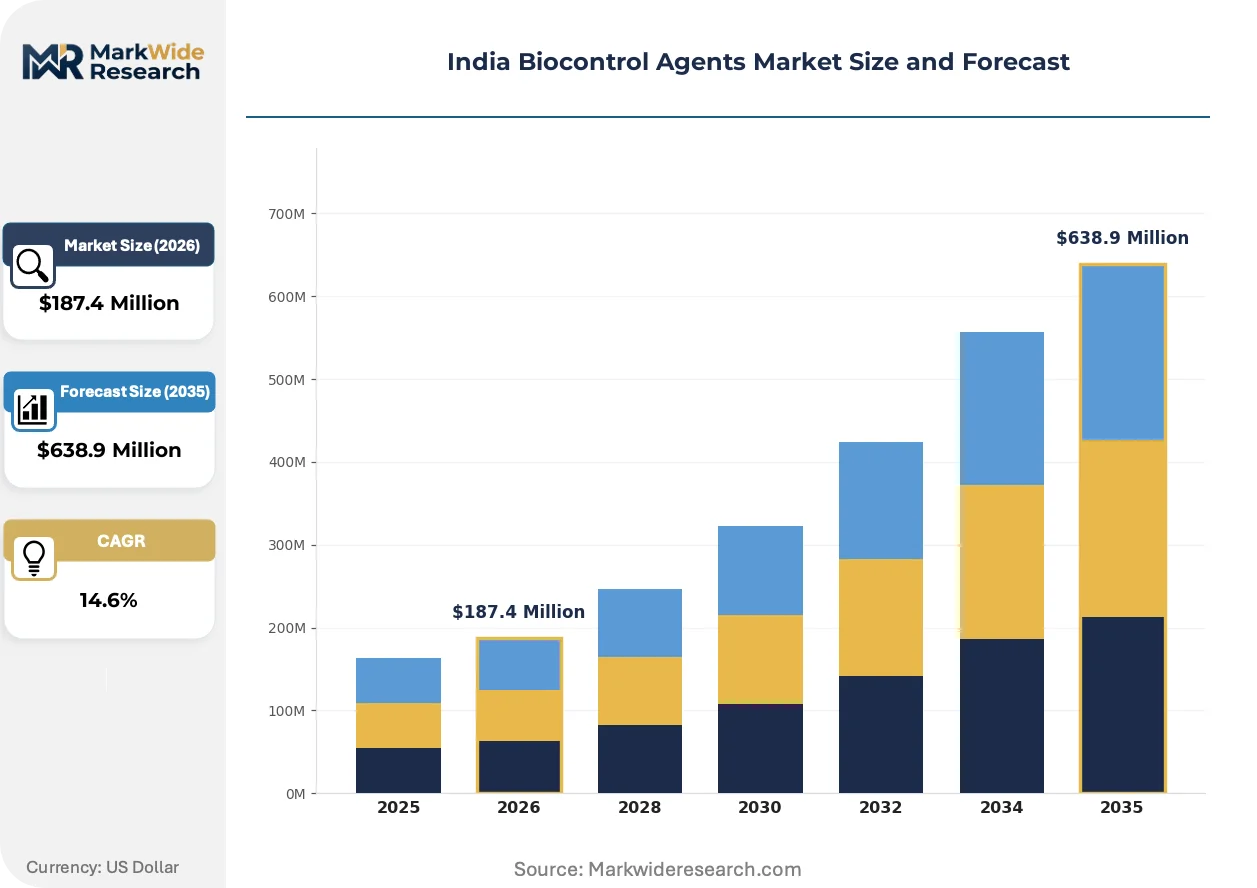
Farmer producer organizations in Maharashtra and Karnataka are consolidating procurement volumes, compressing supplier margins while demanding residue-compliance documentation that only formal microbial inoculant manufacturers can reliably provide.
Growth Catalysts
- FSSAI residue limit enforcement:Export-bound grape and pomegranate growers in Nashik and Solapur districts now mandate biocontrol documentation, pulling microbial inoculants into standard integrated pest management protocols.
- PLI scheme extension:Fermentation infrastructure for biopesticide spore production now qualifies for production-linked incentives, redirecting domestic capital toward captive manufacturing capacity.
- Sugarcane belt consolidation:Western India's farmer producer organizations embed Trichoderma and Bacillus-based products into cooperative input packages, creating anchored demand streams.
Market Restraints
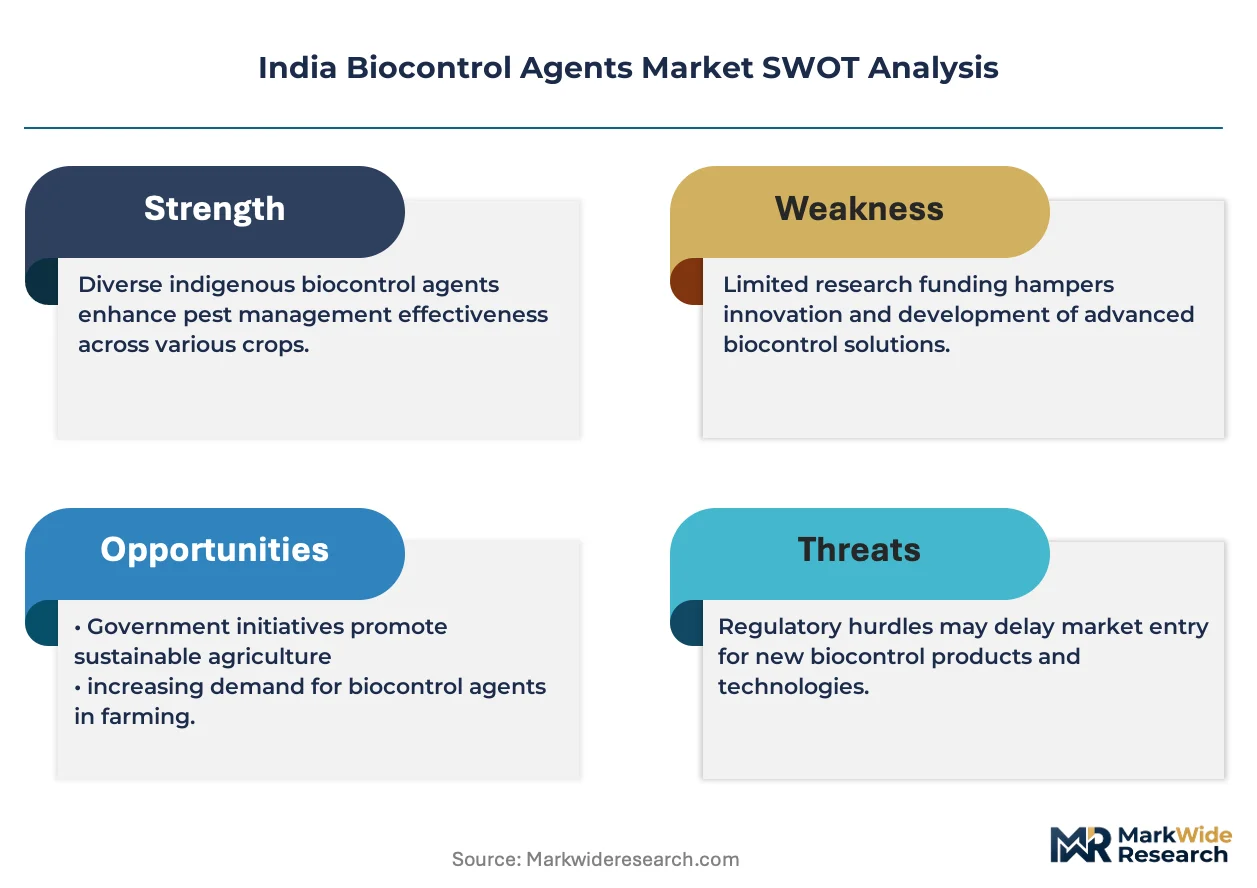
- CDSCO strain registration timelines:Novel microbial strain approvals require 18-24 month evaluation windows, freezing product pipelines for import-dependent entrants.
- Molasses price volatility:Fermentation feedstock costs swing with sugar sector output, squeezing margin on domestic spore production.
- Synthetic pyrethroid substitution:Low-cost chemical alternatives retain pricing advantage in uninsured vegetable plots, capping biocontrol penetration in price-sensitive segments.
Strategic Opportunities
- Madhya Pradesh organic missions:State-level input subsidy revisions are expanding eligible biocontrol categories, opening procurement channels for neem-based azadirachtin concentrates.
- Pheromone lure convergence:Integration of synthetic pheromones with drone-based dispersal systems is creating precision behavioral disruption services for mango and citrus belts.
- Direct-to-farmer digital channels:Agritech platforms are disintermediating traditional mandi-based distribution, enabling technical advisory bundled with microbial inoculant sales.
Industry Challenges
- Formulation chemist scarcity:Domestic talent pools lack expertise in tropical humidity stabilization of fungal propagules, forcing reliance on expatriate technical consultants.
- BIS certification bottlenecks:Microbial pesticide testing queue times at designated laboratories extend market entry by 8-12 months for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Biocontrol Agents Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial, Botanical, Bio-based Pesticides, Pheromones Application: Agricultural Crops, Horticultural Products, Turf, Ornamental Plants End User: Farmers, Agronomists, Agricultural Cooperatives, Research Institutions Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | T. Stanes and Company Limited, Sonku Agro Industries, KN Bio Sciences India Pvt Ltd, Samriddhi Crops India Pvt Ltd, RAJSHREE BIOSOLUTIONS, Agro Bio-Tech Research Centre Ltd, Manidharma Biotech Private Limited, Koppert Biological Systems, Andermatt Group AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Biocontrol Agents Market Trends and Innovations
Formulation science and regulatory data requirements are compressing the competitive set toward manufacturers with integrated fermentation and analytics capabilities, marginalizing trading-only operations.
Encapsulation technology using biodegradable polymer matrices is unifying shelf-life extension with controlled-release functionality in Trichoderma preparations. Maharashtra horticulture cooperatives are piloting these formulations at scale during the 2024-25 growing cycle. The technology is unifying previously separate product categories—soil treatment and foliar application—into single-application protocols that reduce labor costs for grape growers.
FSSAI's tightening maximum residue limits for export-oriented produce categories is mandating biocontrol documentation across the value chain. This regulatory pressure is compressing synthetic pesticide tolerance in premium horticulture segments. Grape and pomegranate processing units in Nashik district now require supplier certification of biocontrol usage as a condition of procurement.
Cooperative procurement committees are consolidating vendor lists to three approved suppliers per input category, replacing fragmented individual farmer purchases. This concentration is displacing informal channel intermediaries who previously supplied unregistered microbial products. The shift is most visible in Karnataka's tomato and capsicum growing clusters around Hoskote and Kolar.
India Biocontrol Agents Market Segmentation
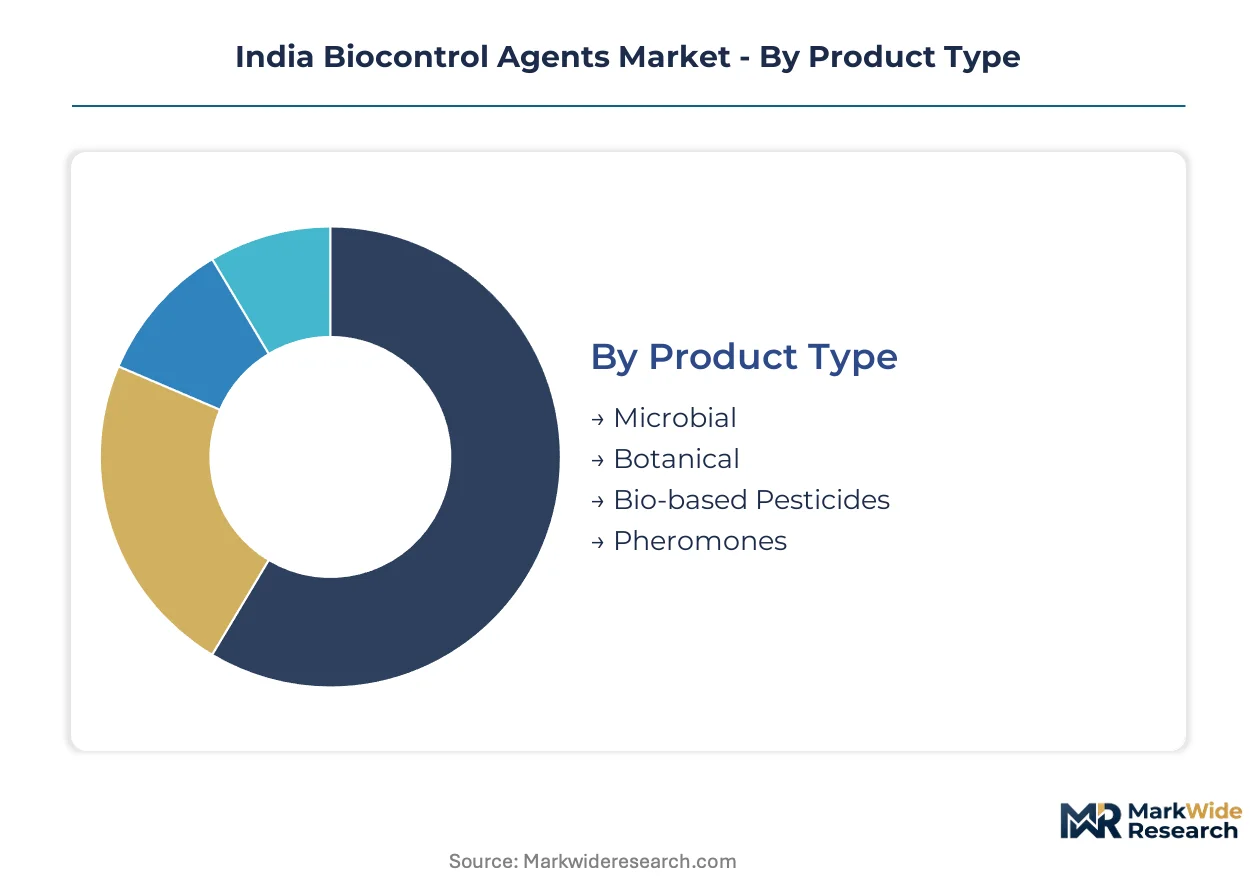
Segmentation in India's biocontrol market reveals how regulatory pressure and residue compliance reshape procurement patterns across farmer types and crop systems. Each dimension exposes distinct margin structures and technical requirements that manufacturers must navigate.
Product Type:
Product selection cycles track closely with FSSAI enforcement waves, as growers replace synthetic chemistries with compliant alternatives ahead of export inspections.
- Microbial:Fungal propagules and bacterial endospores—primarily Trichoderma and Bacillus formulations—dominate farmer expenditure through established efficacy in integrated pest management protocols. Maharashtra and Karnataka horticulture cooperatives consolidate procurement of these inoculants as residue documentation requirements tighten on export-bound grapes and pomegranates.
- Botanical:Neem-based azadirachtin concentrates extract premium pricing from export-oriented compliance mandates, with Madhya Pradesh organic farming missions expanding subsidy eligibility for these categories.
- Bio-based Pesticides:Semi-synthetic derivatives bridge conventional and biological approaches for price-sensitive vegetable plots.
- Pheromones:Synthetic lures enable precision behavioral disruption in mango and citrus belts, with drone-dispersal integration creating service-based revenue models.
Microbial sits at the top of the volume ranking, with Pheromones climbing the fastest.
Application:
Application focus determines pricing power, with horticultural segments commanding premiums through integrated pest management mandates while broadacre crops operate on thinner margins.
- Agricultural Crops:Western India's sugarcane belt anchors demand volume, with farmer producer organizations embedding Trichoderma and Bacillus inoculants into cooperative input packages. BIS certification requirements for microbial pesticide formulations create compliance barriers that favor established domestic manufacturers in this high-tonnage segment.
- Horticultural Products:Grape and pomegranate processing units in Nashik district now mandate biocontrol documentation as a procurement condition, pulling microbial products into standard protocols. Encapsulation technology using biodegradable polymer matrices is unifying soil treatment and foliar application into single-application formats that reduce labor costs.
- Turf:Golf course and sports field maintenance drives specialized demand for consistent performance under irrigation stress.
- Ornamental Plants:Nursery operations require aesthetic-preservation formulations with minimal phytotoxicity risk.
Agricultural Crops generates the largest revenue base, though Horticultural Products achieves the steepest expansion trajectory.
End User:
Customer type dictates contract structure, with institutional buyers consolidating vendor lists while individual farmers remain accessible through emerging digital channels.
- Farmers:Individual growers in uninsured vegetable plots face persistent synthetic pyrethroid substitution pressure, capping biocontrol penetration in price-sensitive segments. Direct-to-farmer agritech platforms are disintermediating traditional mandi-based distribution, enabling technical advisory bundled with microbial inoculant sales.
- Agricultural Cooperatives:Procurement committees in Karnataka's tomato and capsicum clusters around Hoskote and Kolar consolidate vendor lists to three approved suppliers per input category, displacing informal channel intermediaries who previously supplied unregistered products.
- Agronomists:Technical advisors influence product selection through prescription authority in plantation belts.
- Research Institutions:CDSCO strain registration timelines of 18-24 months for novel microbial approvals position these entities as critical validation partners for pipeline products.
Agricultural Cooperatives capture the fastest-growing procurement volume, with Farmers remaining the largest addressable base.
Distribution Channel:
Channel configuration reflects supply chain consolidation, with formal distribution networks displacing fragmented intermediaries as documentation requirements intensify.
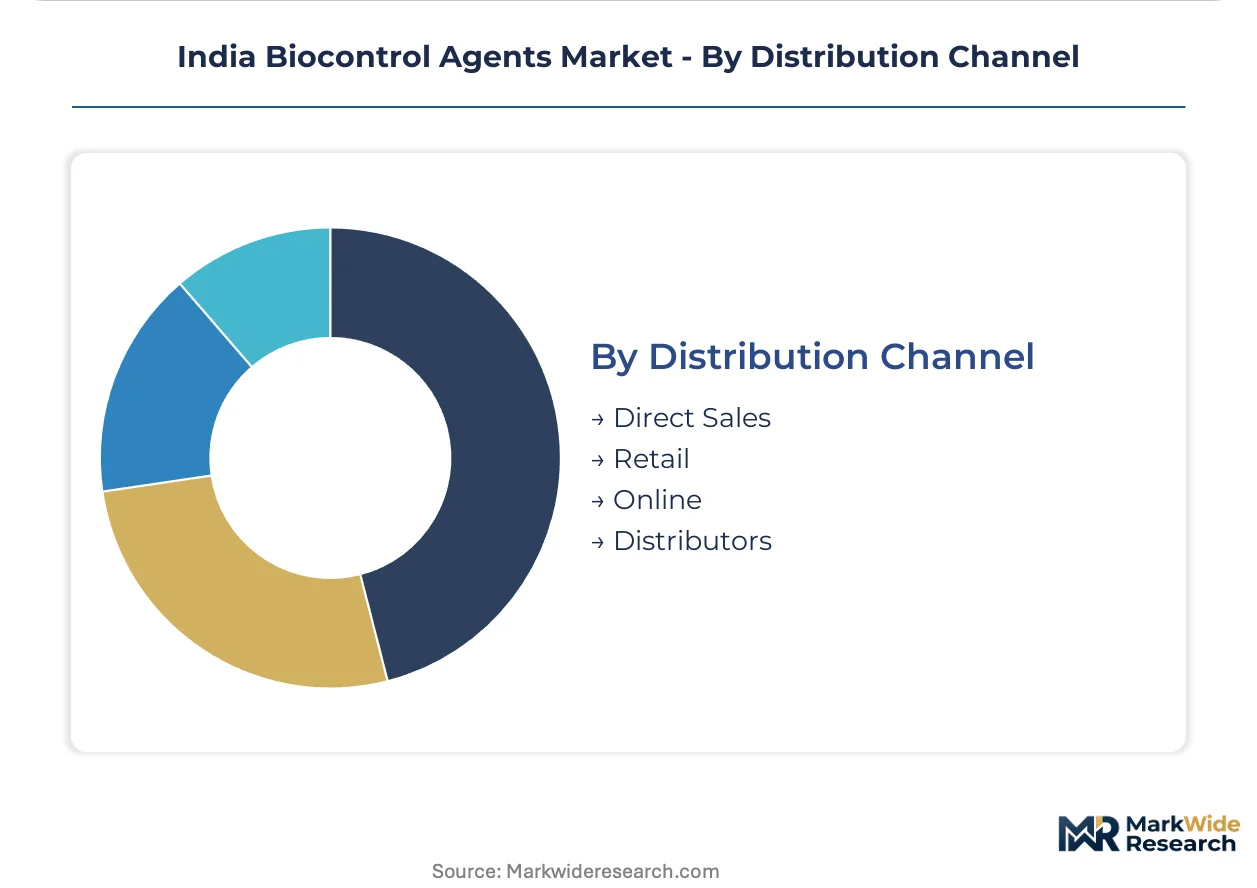
- Distributors:Established networks with century-old relationships across south Indian plantation belts anchor market access for microbial formulations, though cooperative procurement compression squeezes margins.
- Direct Sales:Technical service bundling enables premium capture for complex pheromone and encapsulation products requiring application training.
- Retail:Input shops serve individual farmers with standardized, shelf-stable formulations.
- Online:Digital platforms penetrate price-transparent segments with commodity biocontrol products, though cold-chain requirements limit microbial delivery reach.
Distributors maintain volume leadership, with Direct Sales expanding most quickly through technical advisory integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's biocontrol penetration outpaces neighboring agricultural economies, yet state-level subsidy implementation creates sharper demand gradients than national averages suggest. Western and southern states anchor procurement volumes through cooperative infrastructure, while northern and central regions expand through organic mission programs.
Maharashtra
Nashik and Solapur grape belts drive residue-compliant biocontrol procurement as FSSAI enforcement tightens on export shipments. The state's organic farming mission subsidizes Trichoderma formulations through district agriculture offices. Farmer producer organizations in the sugarcane belt around Kolhapur and Sangli consolidate Bacillus-based inoculant purchases into cooperative input packages.
Karnataka
Horticulture cooperatives in Hoskote and Kolar tomato clusters mandate vendor certification, displacing informal microbial suppliers. The state's biotechnology policy incentivizes domestic fermentation capacity through capital subsidies. Bengaluru's proximity to research institutions accelerates pilot adoption of encapsulated Trichoderma formulations in nearby grape and pomegranate belts.
Gujarat
Cotton and groundnut cultivation in Saurashtra and north Gujarat generates demand for integrated pest management inputs. State-level organic farming missions revise eligible biocontrol categories annually, redirecting procurement toward neem-based concentrates. Anand and Vadodara districts host emerging microbial formulation facilities serving cooperative networks.
Madhya Pradesh
Soybean and wheat belts in Malwa and Nimar regions expand biocontrol adoption through state organic mission subsidies. The agriculture department's input support program now includes azadirachtin concentrates for vegetable clusters around Indore and Bhopal. Limited cold-chain infrastructure constrains microbial product distribution to eastern tribal districts.
Andhra Pradesh and Telangana
Chilli and cotton cultivation in Guntur and Warangal districts creates demand for pheromone-based pest disruption. State horticulture missions promote biocontrol in mango and citrus belts through demonstration plots. Hyderabad's life sciences cluster incubates local microbial strain development, though CDSCO registration timelines delay commercial rollout.
India Biocontrol Agents Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across India's biocontrol landscape, creating tiered competitive dynamics. Century-old domestic manufacturers leverage established distribution networks in plantation belts, while international entrants introduce specialized tropical formulations. Three archetypes dominate: heritage Indian conglomerates with fermentation infrastructure, international biological specialists with strain libraries, and regional formulators competing on price. Capacity expansion and cooperative procurement consolidation represent the dominant competitive moves, as vendors race to secure approved-supplier status with consolidating farmer producer organizations.
Within the heritage domestic tier, T. Stanes and Company Limited anchors market presence through century-old distribution relationships across south Indian plantation belts. Koppert Biological Systems and Andermatt Group AG represent the international specialist archetype, introducing proprietary strain technologies calibrated for tropical humidity regimes. Manidharma Biotech Private Limited occupies a position among aggressive regional formulators targeting price-sensitive vegetable-growing clusters with standardized Bacillus preparations.
| Leading Market Players |
|---|
| T. Stanes and Company Limited |
| Sonku Agro Industries |
| KN Bio Sciences India Pvt Ltd |
| Samriddhi Crops India Pvt Ltd |
| RAJSHREE BIOSOLUTIONS |
| Agro Bio-Tech Research Centre Ltd |
| Manidharma Biotech Private Limited |
| Koppert Biological Systems |
| Andermatt Group AG |
| Others |
Pricing and Supply Chain Analysis
FSSAI residue limit enforcement gates qualified supply access and premium-tier pricing power across Maharashtra and Karnataka horticulture belts. Grape and pomegranate processing units in Nashik district now require supplier certification of biocontrol usage, compressing unregistered microbial suppliers into economy tiers while BIS-certified manufacturers capture documentation-linked premiums.
Pricing Analysis
Capacity additions in Gujarat and Madhya Pradesh are reshaping price floors for Bacillus-based formulations through PLI-subsidized fermentation infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified encapsulated Trichoderma from generic spore suspensions and unregistered trader products. Cost compression in standard tiers is intensifying because cooperative procurement committees consolidate vendor lists to three approved suppliers per input category. Individual farmers in uninsured vegetable plots exhibit highest price sensitivity, while export-oriented horticulture cooperatives absorb premium pricing for residue-compliance documentation.
Supply Chain Analysis
Direct-to-cooperative channels handle consolidated procurement volumes from Maharashtra and Karnataka farmer producer organizations. Domestic manufacturing concentrates in Tamil Nadu, Gujarat, and Maharashtra through established fermentation infrastructure. Raw material sourcing draws from sugar sector molasses output, agricultural substrate streams, and imported proprietary strain libraries. Single-source vulnerability runs through CDSCO-designated testing laboratories where microbial pesticide certification queue times extend market entry timelines. Distribution runs through century-old plantation belt networks anchored by T. Stanes and emerging agritech platforms disintermediating traditional mandi intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in premium-tier microbial formulations as FSSAI enforcement eliminates unregistered competitors from export-facing value chains. PLI scheme subsidies on fermentation infrastructure provide a structural cost-down pathway for domestic manufacturers scaling encapsulated Trichoderma capacity.
For Market Incumbents: Anticipate cooperative procurement compression by securing approved-supplier status with consolidating farmer producer organizations in Karnataka's Hoskote tomato clusters and Maharashtra's Kolhapur sugarcane belt. Deepen backward integration into captive spore production capacity to offset molasses feedstock volatility. Invest in BIS certification pipeline acceleration to outpace CDSCO testing queue bottlenecks that freeze import-dependent entrant pipelines. For New Entrants and Emerging Players: The premium-to-economy price-point gap in pheromone-based behavioral disruption products opens white-space targeting in Andhra Pradesh and Telangana mango belts where drone-dispersal integration remains underdeveloped. Focus technical advisory bundling through direct-to-farmer agritech platforms penetrating price-transparent segments. Prioritize Madhya Pradesh organic mission subsidy eligibility for neem-based azadirachtin concentrates where state-level procurement channels expand fastest. For Investors and Strategic Acquirers: Roll-up economics work for regional formulators with BIS certification infrastructure because cooperative vendor consolidation is displacing fragmented trading-only operations. Target mid-cap manufacturers with integrated fermentation and analytics capabilities positioned for encapsulation technology scale-up. Monitor CDSCO strain registration timeline compression as inflection signal for pipeline product commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Infrastructure | PLI scheme eligibility redirects capital toward captive spore production capacity in Gujarat and Maharashtra. |
| BIS Certification Acceleration | Compressed testing queue access differentiates established manufacturers from import-dependent entrants facing 18-24 month delays. |
| Encapsulation Technology Scale-Up | Biodegradable polymer matrix formulations unify soil and foliar applications for Nashik grape cooperative adoption. |
| Direct-to-Farmer Platform Partnership | Agritech channel disintermediation enables technical advisory bundling with microbial inoculant sales in price-transparent segments. |
| Cooperative Procurement Committee Engagement | Approved-supplier status with consolidating farmer producer organizations anchors demand streams in Karnataka horticulture belts. |
Research Methodology
Direct dialogue with fermentation plant managers, cooperative procurement committee members, CDSCO regulatory affairs specialists, and agritech platform operators grounded qualitative findings in operational reality. Secondary validation drew from FSSAI residue limit notifications, BIS microbial pesticide certification records, state organic mission subsidy circulars, and PLI scheme beneficiary disclosures. Bottom-up farmer expenditure estimates triangulated against top-down manufacturer capacity assessments across the analysis window.
Bottom-up modeling segmented the market by product type, application, end user, and distribution channel with additional granularity on state-level subsidy eligibility variations. CAGRs derived from cooperative procurement volume trajectories, export inspection compliance adoption curves, and fermentation capacity expansion pipelines throughout the forecast period. Molasses price volatility assumptions and CDSCO registration timeline scenarios informed sensitivity bounds.
Caveats apply where PLI scheme extension decisions, state organic mission subsidy list revisions, or FSSAI maximum residue limit adjustments could materially shift the outlook. Forecasts reflect documented assumptions on cooperative consolidation velocity and encapsulation technology adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
Transgenic Animals Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
China Feed Probiotics Market
Bio-Agriculture
China Biofertilizer Market
Bio-Agriculture
Middle East and Africa Biopesticides Market
Bio-Agriculture
France Biopesticides Market
Bio-Agriculture
Global Biofortification Market
Bio-Agriculture
United States Biofertilizer Market
Bio-Agriculture
Middle East and Africa Animal Genetics Market
Bio-Agriculture
Plant-Based Biologics Market
Bio-Agriculture
Europe Biostimulants Market
Bio-Agriculture
Asia-Pacific Biostimulants Market
Bio-Agriculture
United States Biocontrol Agents Market
Bio-Agriculture
Brazil Biostimulants Market
Bio-Agriculture
Nannochloropsis Market