
 Global Cell Harvesting Market | 2026-2036
Global Cell Harvesting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cell Harvesting Market Foresight
Single-use plastics is rebalancing product economics across cell harvesting consumables as bioprocessors weigh contamination risk against polymer cost volatility. Thermo Fisher Scientific leverages its integrated bioproduction portfolio to sustain pull-through on harvest reagents and instrumentation. Danaher Corporation anchors its position through Cytiva's chromatography and filtration franchises that extend into downstream cell recovery workflows.
Cell harvesting encompasses the mechanical, enzymatic, or immunomagnetic retrieval of viable cells from culture vessels, matrices, or bioreactors, typically requiring maintenance of membrane integrity above 90% and sterility assurance through closed-system architecture for subsequent therapeutic or research use. Automated Systems dominate capital expenditure budgets as contract manufacturing organizations scale GMP-compliant throughput, while Magnetic Separation Units capture expanding share in chimeric antigen receptor T-cell workflows where CD4/CD8 specificity commands premium positioning. Enzymatic Detachment retains volume leadership in adherent cultures though Mechanical Separation gains ground in microcarrier-based stem cell expansion where enzyme-free protocols simplify regulatory filings.
FDA's guidance on chemistry, manufacturing, and controls for cell therapy products shapes harvest protocol validation requirements, while EMA's ATMP framework and Japan's PMDA regenerative medicine safety regulations create parallel compliance tracks for multinational sponsors. ISO 20399 on ancillary materials for cell therapy further constrains supplier qualification, narrowing vendor pools to those with documented extractables and leachables profiles. Stakeholders must monitor evolving GMP annex expectations for automated closed-system harvesting as regulatory divergence between FDA process validation and EMA risk-based approaches intensifies qualification burdens.
Market Dynamics
Closed-system architecture requirements from FDA and EMA are compressing vendor pools and forcing bioprocessors to requalify entire harvest workflows around extractables and leachables documentation, reshaping competitive positioning toward integrated platform suppliers.
Growth Catalysts
- Biopharmaceutical Production Scaling:Cell therapy manufacturing expansion in the United States, Germany, and Japan is pulling through demand for GMP-compliant automated harvest systems capable of maintaining 90% membrane integrity at commercial throughput.
- EMA ATMP Framework:The European Medicines Agency's advanced therapy medicinal product regulations are tightening quality standards for downstream cell recovery, creating compliance-driven replacement cycles for legacy open-system equipment.
- Magnetic Separation Technology:CD4/CD8 specificity in chimeric antigen receptor T-cell workflows is commanding premium positioning for immunomagnetic retrieval systems, displacing enzymatic methods in high-value therapeutic applications.
Market Restraints
- Polymer Cost Volatility:Single-use plastics face input cost swings that destabilize consumables economics, forcing bioprocessors to weigh contamination risk against margin compression in harvest reagent portfolios.
- Supplier Concentration Risk:ISO 20399 compliance documentation narrows qualified ancillary material vendors to those with extractables profiles, creating dependency on a shrinking pool of documented suppliers.
- Enzymatic Protocol Limitations:Adherent culture harvest methods face substitution pressure from enzyme-free mechanical separation in microcarrier-based stem cell expansion, where simplified regulatory filings accelerate protocol displacement.
Strategic Opportunities
- Japan Regenerative Medicine Infrastructure:PMDA safety regulations and METI industrial policy are converging to build ATMP manufacturing clusters in Kobe and Osaka, opening demand for localized harvest system integration services.
- Contract Manufacturing Channel:CDMOs scaling GMP throughput represent an underpenetrated buyer segment for automated closed-system harvesting platforms with validated batch records.
- FDA Process Validation Convergence:Divergence between FDA process validation and EMA risk-based approaches intensifies qualification burdens, creating service revenue for vendors offering harmonized compliance documentation across both tracks.
Industry Challenges
- Closed-System Engineering Talent:Bioprocess engineers with combined expertise in sterile fluid dynamics and cell biology remain scarce, extending implementation timelines for automated harvest deployments.
- GMP Annex Reconfiguration:Evolving expectations for automated closed-system harvesting require facility retrofitting and revalidation, compressing capital efficiency for brownfield biomanufacturing sites.
- Extractables Documentation Burden:Supplier qualification against ISO 20399 demands extensive analytical chemistry investment, stretching mid-tier consumables vendors beyond internal capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cell Harvesting Market |
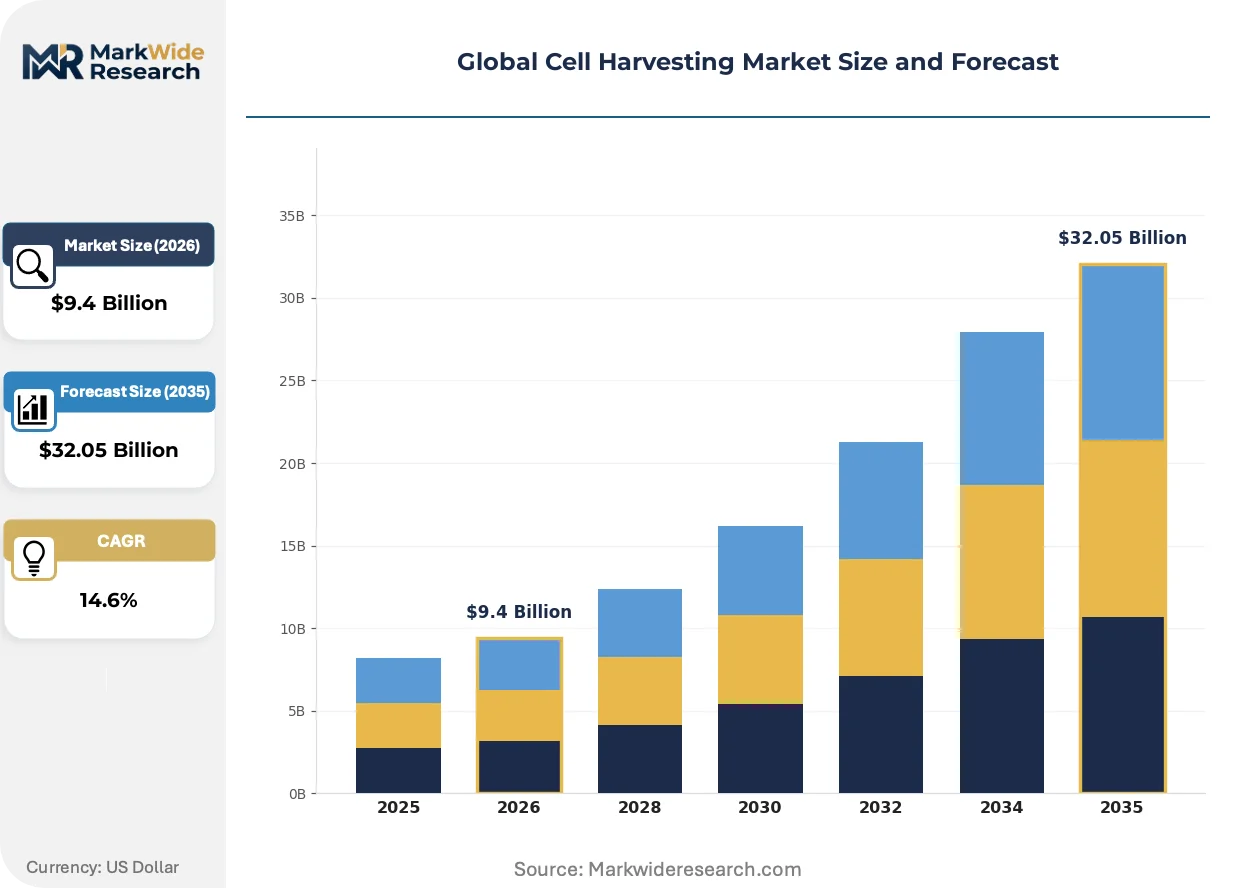
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $32.05 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Tools, Centrifugal Devices, Filtration Equipment, Magnetic Separation Units Technology: Enzymatic Detachment, Mechanical Separation, Density Gradient, Immunomagnetic, Vacuum Assisted Application: Stem Cell Research, Biopharmaceutical Production, Regenerative Medicine, Cell Therapy, Tissue Engineering End User: Biotech Companies, Pharmaceutical Firms, Research Institutes, Contract Manufacturing Organizations |
| Companies Covered | Thermo Fisher Scientific, Sartorius AG, PerkinElmer, Danaher Corporation, Terumo Corporation, Miltenyi Biotec, Cytiva, Merck KGaA, Lonza Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cell Harvesting Market Shifts & Advancements
Harvest technology is pivoting from open manual protocols toward integrated closed systems, with regulatory documentation requirements and cell therapy manufacturing scale driving convergence between hardware, consumables, and compliance services.
Single-use bioreactor harvest assemblies are decentralizing cell recovery workflows by enabling distributed manufacturing nodes outside centralized cleanroom infrastructure. Regional cell therapy developers in Germany and Japan are adopting these systems to reduce logistics risk for temperature-sensitive therapeutic products. This decentralization is compressing the geographic radius between production and patient infusion sites, reshaping cold chain requirements and local regulatory inspection protocols.
REACH annex revisions on polymer extractables are forcing European bioprocessors to requalify harvest consumables against extended substance documentation requirements. The industrial consequence is accelerated substitution of legacy plastic formulations toward medical-grade fluoropolymers with pre-validated leachables profiles. CDMOs serving EMA-regulated trials are most affected, responding by consolidating supplier relationships toward vendors with registered substance databases.
Buyer consolidation among top-twenty cell therapy sponsors is concentrating procurement leverage and compressing switching cycles for harvest platform decisions. Equipment vendors face unbundling pressure as CDMOs separate hardware acquisition from validation service contracts, favoring modular systems with transferable protocols. This pattern is most visible in the United States, where venture-backed therapeutic developers are outsourcing manufacturing earlier in clinical progression to conserve capital.
Global Cell Harvesting Market Segmentation
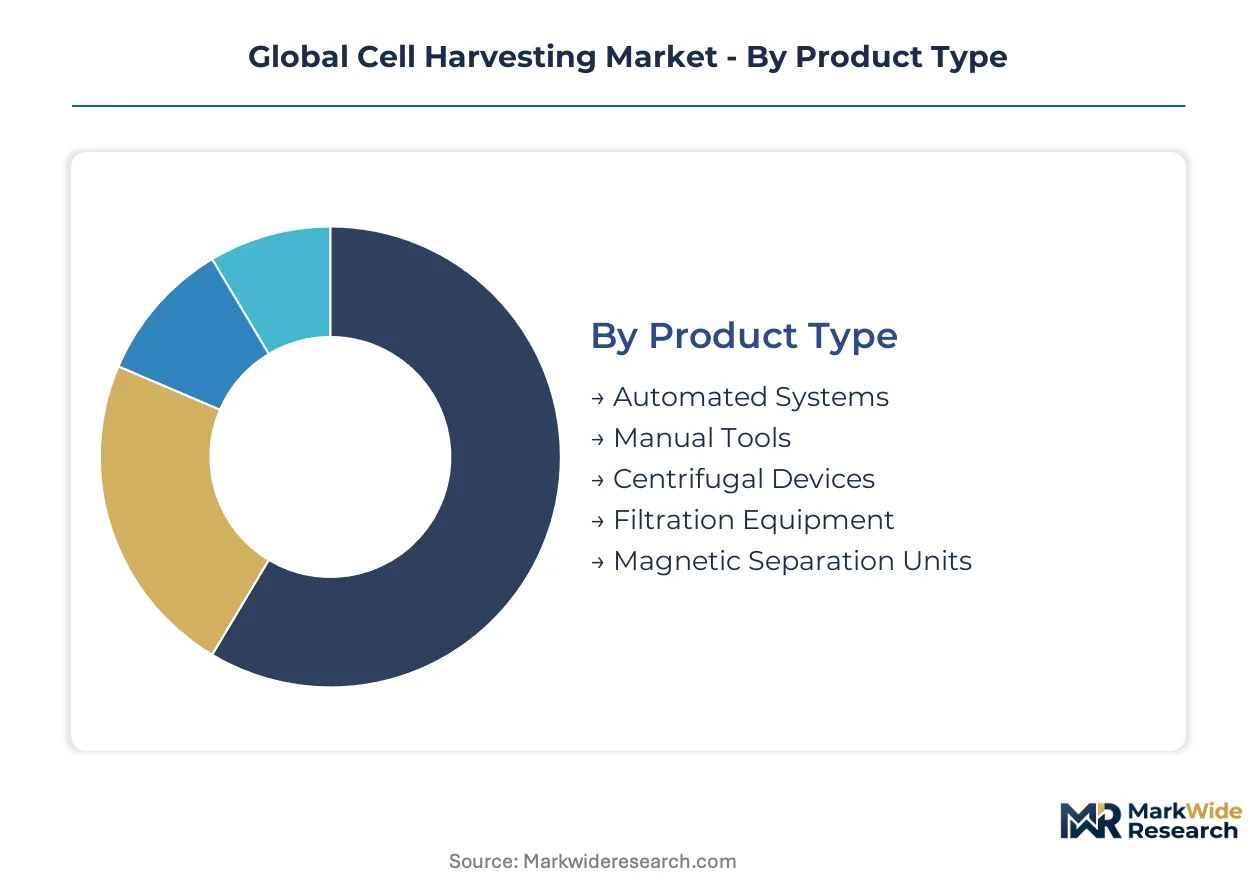
Cell harvesting segmentation reveals divergent procurement patterns between therapeutic manufacturing and research applications. Product type choices hinge on GMP compliance requirements, while technology selection balances membrane integrity targets against regulatory filing complexity.
Product Type:
Automated Systems command premium positioning while Manual Tools retain volume leadership in research settings.
- Automated Systems:Closed-system platforms integrate sterile fluid handling with programmable harvest protocols to maintain membrane integrity above 90% at commercial throughput. Demand concentrates among contract manufacturing organizations scaling GMP-compliant operations in the United States and Germany, driven by FDA and EMA closed-system mandates.
- Magnetic Separation Units:Immunomagnetic retrieval platforms enable CD4/CD8 specificity in chimeric antigen receptor T-cell workflows through antibody-coated bead separation. Japanese bioprocessors in Kobe and Osaka clusters are adopting these systems for PMDA-regulated regenerative medicine manufacturing.
- Manual Tools:Handheld scrapers and aspiration devices serve academic research laboratories with lower throughput requirements and minimal validation documentation.
- Centrifugal Devices:Density-based cell recovery systems separate populations by sedimentation rate for downstream processing applications.
- Filtration Equipment:Tangential flow and depth filtration assemblies concentrate cell suspensions while removing debris from culture harvests.
Mature deployment sits with Manual Tools in academic settings. Newer deployment is concentrated in Automated Systems for commercial therapeutic manufacturing.
Technology:
Enzyme-free protocols are gaining share as regulatory filings simplify, though enzymatic methods retain adherent culture dominance.
- Enzymatic Detachment:Protease-based dissociation cleaves cell adhesion proteins for gentle retrieval from tissue culture plastic. Biopharmaceutical production in Germany relies heavily on these methods for established antibody-producing cell lines.
- Mechanical Separation:Shear-based or scraping protocols eliminate enzyme exposure and associated leachables documentation. Microcarrier-based stem cell expansion in Japanese manufacturing clusters is adopting these methods to streamline PMDA safety filings.
- Immunomagnetic:Antibody-mediated selection isolates target cell populations with surface marker specificity for therapeutic applications.
- Density Gradient:Centrifugation through media of varying osmolarity separates cells by buoyancy for research-grade preparations.
- Vacuum Assisted:Negative pressure aspiration enables rapid harvest from large-scale vessels with minimal mechanical stress.
Volume concentration remains with Enzymatic Detachment for legacy adherent workflows. Steepest expansion trajectory belongs to Mechanical Separation in stem cell manufacturing.
Application:
Cell therapy manufacturing pulls premium technology investment while research applications optimize for flexibility.
- Cell Therapy:Chimeric antigen receptor T-cell and tumor-infiltrating lymphocyte production demands sterile closed-system harvest with full batch traceability. United States-based sponsors scaling commercial manufacturing are driving specification tightening for automated platforms.
- Biopharmaceutical Production:Monoclonal antibody and recombinant protein workflows require high-yield recovery from bioreactor cultures. German CDMOs serving EMA-regulated trials are consolidating procurement around qualified single-use harvest assemblies.
- Stem Cell Research:Pluripotent and adult stem cell isolation prioritizes viability maintenance over throughput in laboratory settings.
- Regenerative Medicine:Tissue-derived cell products for wound healing and orthopedics require harvest methods preserving differentiation potential.
- Tissue Engineering:Scaffold-based constructs need retrieval protocols compatible with extracellular matrix preservation.
Established demand centers on Biopharmaceutical Production. Emerging deployment clusters in Cell Therapy are reshaping vendor qualification requirements.
End User:
Procurement authority is shifting from research institutes toward manufacturing-focused organizations with GMP infrastructure.
- Contract Manufacturing Organizations:CDMOs aggregate demand across multiple sponsor programs, enabling capital investment in validated automated harvest platforms. United States-based cell therapy CDMOs are expanding capacity fastest, pulling through integrated system purchases with service contract attachments.
- Pharmaceutical Firms:Large sponsors with in-house advanced therapy capabilities maintain proprietary harvest protocols for pipeline assets. Japanese pharmaceutical companies are building captive regenerative medicine capacity under METI industrial policy support.
- Biotech Companies:Venture-backed therapeutic developers outsource manufacturing earlier, reducing direct harvest equipment ownership.
- Research Institutes:Academic laboratories prioritize cost minimization and protocol flexibility over standardization.
Traditional procurement volume sits with Research Institutes. Accelerating deployment is concentrated in Contract Manufacturing Organizations scaling GMP throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced therapy manufacturing clusters in Kobe, Japan, and the Research Triangle Park in North Carolina concentrate cell harvesting infrastructure through targeted tax incentives and regulatory fast-tracking programs.
United States
FDA's chemistry, manufacturing, and controls guidance for cell therapy products is compressing vendor pools around closed-system harvest documentation. The Research Triangle Park in North Carolina anchors commercial-scale CAR-T manufacturing facilities. Venture-backed therapeutic developers in Greater Boston are outsourcing manufacturing earlier, pulling automated harvest platform demand toward CDMOs.
Germany
EMA's ATMP framework and REACH annex revisions on polymer extractables are forcing requalification of legacy harvest consumables. The Rhine-Main biotech corridor around Frankfurt hosts CDMOs consolidating procurement around qualified single-use harvest assemblies. German bioprocessors serving EMA-regulated trials face accelerated substitution toward medical-grade fluoropolymers with pre-validated leachables profiles.
Japan
PMDA regenerative medicine safety regulations and METI industrial policy are converging to build ATMP manufacturing clusters. Kobe and Osaka anchor captive regenerative medicine capacity under government-supported infrastructure programs. Japanese pharmaceutical companies are adopting mechanical separation methods to streamline PMDA safety filings for microcarrier-based stem cell expansion.
United Kingdom
The Medicines and Healthcare products Regulatory Agency's post-Brexit ATMP guidance is creating parallel compliance tracks for multinational sponsors. The Golden Triangle between London, Oxford, and Cambridge concentrates academic research laboratories with manual harvest tool demand. UK-based cell therapy developers are navigating divergent FDA and MHRA process validation requirements.
Switzerland
Swissmedic's alignment with EMA ATMP standards is attracting advanced therapy sponsors seeking regulatory harmonization. The Basel biopharma cluster hosts large sponsors maintaining proprietary harvest protocols for pipeline assets. Swiss CDMOs are investing in automated closed-system platforms to serve both European and North American sponsor programs.
Global Cell Harvesting Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform suppliers capturing premium positioning in GMP-compliant therapeutic manufacturing while research-grade consumables remain fragmented. The market structure tilts toward consolidation at the automated systems tier, where validation documentation and regulatory compliance capabilities create vendor stickiness. Three archetypes dominate: diversified life science conglomerates with bioproduction portfolios, pure-play cell therapy equipment specialists, and CDMOs backward-integrating into proprietary harvest technologies. Competitive moves center on M&A to secure extractables documentation capabilities and strategic partnerships to harmonize FDA-EMA qualification protocols.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify platform suppliers leveraging integrated bioproduction portfolios to sustain pull-through on harvest reagents and instrumentation. Sartorius AG occupies a position among European-based specialists with chromatography and filtration franchises extending into downstream cell recovery workflows. These three entities anchor the vendor landscape through documented ISO 20399 compliance and closed-system engineering capabilities that mid-tier competitors struggle to replicate.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Sartorius AG |
| PerkinElmer |
| Danaher Corporation |
| Terumo Corporation |
| Miltenyi Biotec |
| Cytiva |
| Merck KGaA |
| Lonza Group AG |
| Others |
Supply & Pricing Matrix
Captive integration into ISO 20399-compliant extractables documentation anchors both supply security and premium pricing power for automated harvest system vendors, while outsourcing consumables production to undocumented suppliers compresses margins through regulatory requalification costs. This structural split between integrated platform suppliers and fragmented consumables vendors concentrates pricing leverage among Thermo Fisher Scientific, Danaher Corporation, and Sartorius AG.
Pricing Analysis
Volume leadership in manual tools runs on thin margins, while premium positioning in automated systems commands substantial markups through validation service bundling. Price differentiation hinges on GMP certification tier and closed-system engineering complexity, with FDA-validated platforms capturing significant premiums over research-grade alternatives. Pricing pressure stems from REACH annex revisions forcing fluoropolymer substitution in European consumables. Academic laboratories exhibit highest price sensitivity, whereas CDMOs prioritize compliance documentation over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor hub-and-spoke patterns for temperature-sensitive harvest reagents and single-use assemblies. Manufacturing concentration rests on medical-grade polymer suppliers in Germany, precision fluid handling component producers in the United States, and magnetic bead substrate specialists in Japan. Single-source vulnerability around fluoropolymer formulations creates exposure to ECHA substance restriction updates. Distribution runs through qualified cold chain logistics partners serving GMP-certified manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around extractables documentation capabilities, with ISO 20399 compliance burdens forcing mid-tier consumables vendors toward exit or acquisition.
For Market Incumbents: Lock in supplier relationships with registered substance databases before REACH annex revisions accelerate fluoropolymer substitution timelines. Secure backward integration into magnetic bead substrate production to defend margin position against Miltenyi Biotec's immunomagnetic specialization. Prioritize harmonized FDA-EMA qualification protocols as a service revenue layer. For New Entrants and Emerging Players: EMA ATMP framework compliance in Germany opens a window for modular harvest system components that unbundle from incumbent platform ecosystems. Target Japanese CDMOs in Kobe and Osaka clusters with mechanical separation tools that streamline PMDA safety filings for microcarrier-based stem cell expansion. Lead with enzyme-free protocol validation services rather than hardware. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified life science conglomerates seeking extractables documentation capabilities. Long-term viability favors vendors with captive ISO 20399 analytical chemistry infrastructure spanning the projection horizon. Monitor EMA-FDA regulatory divergence intensity as an inflection signal for harmonization service demand.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20399 Compliance Investment | Analytical chemistry capabilities narrow qualified vendor pools to documented suppliers. |
| Harmonized FDA-EMA Qualification Services | Regulatory divergence creates service revenue for protocol documentation across both tracks. |
| Mechanical Separation Platform Development | Enzyme-free protocols simplify PMDA filings for Japanese stem cell manufacturers. |
| Regional Distribution Hub Expansion | Kobe and Osaka clusters require localized cold chain infrastructure for regenerative medicine. |
| CDMO Partnership Structuring | Validation service contracts attach recurring revenue to automated system deployments. |
Research Methodology
Multi-period observation of FDA guidance evolution, EMA ATMP framework implementation, and PMDA safety regulation updates anchored the trend analysis, supplemented by interviews with bioprocess engineering directors, CDMO operations heads, regulatory affairs leads at cell therapy sponsors, and procurement managers at German single-use consumables distributors. Secondary validation drew from FDA CMC guidance documents, EMA CAT meeting minutes, PMDA regenerative medicine consultation records, and ISO 20399 technical committee drafts. Bottom-up segment sizing triangulated against top-down therapeutic manufacturing capacity expansion announcements.
Segment-weighting across product type, technology protocol, application, and end-user procurement authority shaped the analytical framework. Modeled dimensions included GMP compliance tier, closed-system architecture complexity, and regional regulatory cluster. CAGRs were derived from capacity expansion trajectories and replacement cycle analysis throughout the forecast period. Industry-specific inputs incorporated CAR-T manufacturing scale-up announcements and stem cell therapy clinical progression rates.
The model assumes a particular technology adoption path toward automated closed-system harvesting; alternative pathways emphasizing manual tool standardization would alter the outlook. Forecasts reflect documented assumptions on regulatory convergence timelines and polymer substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Cell Sorting Market
Biomedical Technology
Strand Displacement Amplification (SDA) Market
Biomedical Technology
Global Glycomics/Glycobiology Market
Biomedical Technology
Biologics Outsourcing Market
Biomedical Technology
Global Stem Cell Assay Market
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
Cosmid DNA Isolation Market
Biomedical Technology
Global Laser Capture Microdissection Market
Biomedical Technology
Brain Biomarkers Market
Biomedical Technology
Particle-Enhanced Turbidimetric Immunoassays Market
Biomedical Technology
Asia-Pacific Proteomics Market
Biomedical Technology
Global Cell Counting Market
Biomedical Technology
Global Tissue Microarray Market
Biomedical Technology
Global Autologous Conditioned Plasma Market
Biomedical Technology
Fluorescent in Situ Hybridization Market