
 North America Biotechnology Market | 2026-2036
North America Biotechnology Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biotechnology Market Analytics
FDA Good Manufacturing Practice certification is reorganizing competitive access in North American biologics production, forcing contract manufacturers to absorb validation costs that smaller entrants cannot shoulder. Thermo Fisher Scientific leverages its integrated instrument-reagent-service architecture to dominate upstream supply relationships across the region. Amgen sustains one of the largest mammalian cell culture footprints in California, while Regeneron Pharmaceuticals specializes in novel antibody engineering platforms that differentiate its pipeline from conventional approaches.
Biotechnology encompasses the application of living organisms, cellular components, and biomolecular processes to develop therapeutic proteins, genetic medicines, and diagnostic tools, typically requiring sterile fermentation or cell culture conditions maintained at 37 degrees Celsius with precise pH and dissolved oxygen control. Biopharmaceuticals and monoclonal antibodies occupy the deepest margin pools due to chronic disease indications and biosimilar defense strategies, while gene therapy segments attract concentrated R&D investment despite manufacturing complexity. Synthetic biology and CRISPR applications in drug development are expanding fastest, though recombinant DNA technology still anchors the majority of commercial production volumes across pharmaceutical companies and contract research organizations.
FDA's Biologics License Application framework, Health Canada's ICH Q5D compliance requirements, and the EPA's biotechnology emissions oversight collectively determine facility siting, product approval timelines, and environmental liability exposure for North American operators. The IRA's Medicare price negotiation provisions are reshaping revenue modeling for established biologics, pushing developers toward orphan indications and next-modality platforms. Stakeholders must monitor how FDA's emerging gene therapy guidance and state-level biomanufacturing tax incentives reshape capital allocation between the United States and Canadian production corridors.
Market Dynamics
FDA's accelerated approval pathways are compressing development timelines and pulling contract manufacturing capacity toward Massachusetts and North Carolina clusters, forcing facility investment patterns to reorganize around speed-to-clinic metrics rather than traditional scale economics.
Growth Catalysts
- IRA Biomanufacturing Tax Credits:The Inflation Reduction Act's production incentives are redirecting capital toward domestic fermentation capacity expansion across United States coastal corridors.
- Continuous Bioprocessing:Perfusion cell culture technologies are reducing facility footprints and enabling modular manufacturing deployments that bypass traditional stainless-steel infrastructure requirements.
- Oncology Pipeline Density:CAR-T and bispecific antibody development programs are consuming available mammalian cell culture capacity and justifying premium pricing for expedited manufacturing slots.
Market Restraints
- Plasmid DNA Supply Concentration:Limited qualified suppliers of GMP-grade plasmids for viral vector production are creating single-source dependencies that amplify batch failure risks.
- FDA Validation Burden:Process validation requirements for biologics license applications are extending facility qualification timelines and freezing capital in non-revenue-generating compliance activities.
- Protein A Resin Cost Volatility:Chromatography media price fluctuations are compressing downstream processing margins and forcing developers toward multi-column periodic counter-current alternatives.
Strategic Opportunities
- Canadian Biologics Incentives:Health Canada's expanding manufacturing tax credits and streamlined clinical trial frameworks are attracting U.S. developers to establish production corridors in Ontario and Quebec.
- AI-Driven Cell Line Development:Machine learning platforms for clone selection and media optimization are converging with automated bioreactor systems to compress cell line development timelines.
- Orphan Indication Pivot:Medicare price negotiation exemptions for rare disease therapies are redirecting pipeline investment toward smaller patient populations with higher reimbursement durability.
Industry Challenges
- Gene Therapy Manufacturing Talent Scarcity:Viral vector production expertise remains concentrated among a limited pool of specialists, constraining capacity expansion at emerging facilities.
- Legacy ERP Integration Friction:Paper-based batch record systems at established biologics plants are creating data integrity risks during digital transformation initiatives required for real-time release testing.
- Biosimilar Defense Capex Requirements:Originators must invest in manufacturing complexity upgrades to maintain differentiation against incoming biosimilar competition, diverting funds from novel platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biotechnology Market |
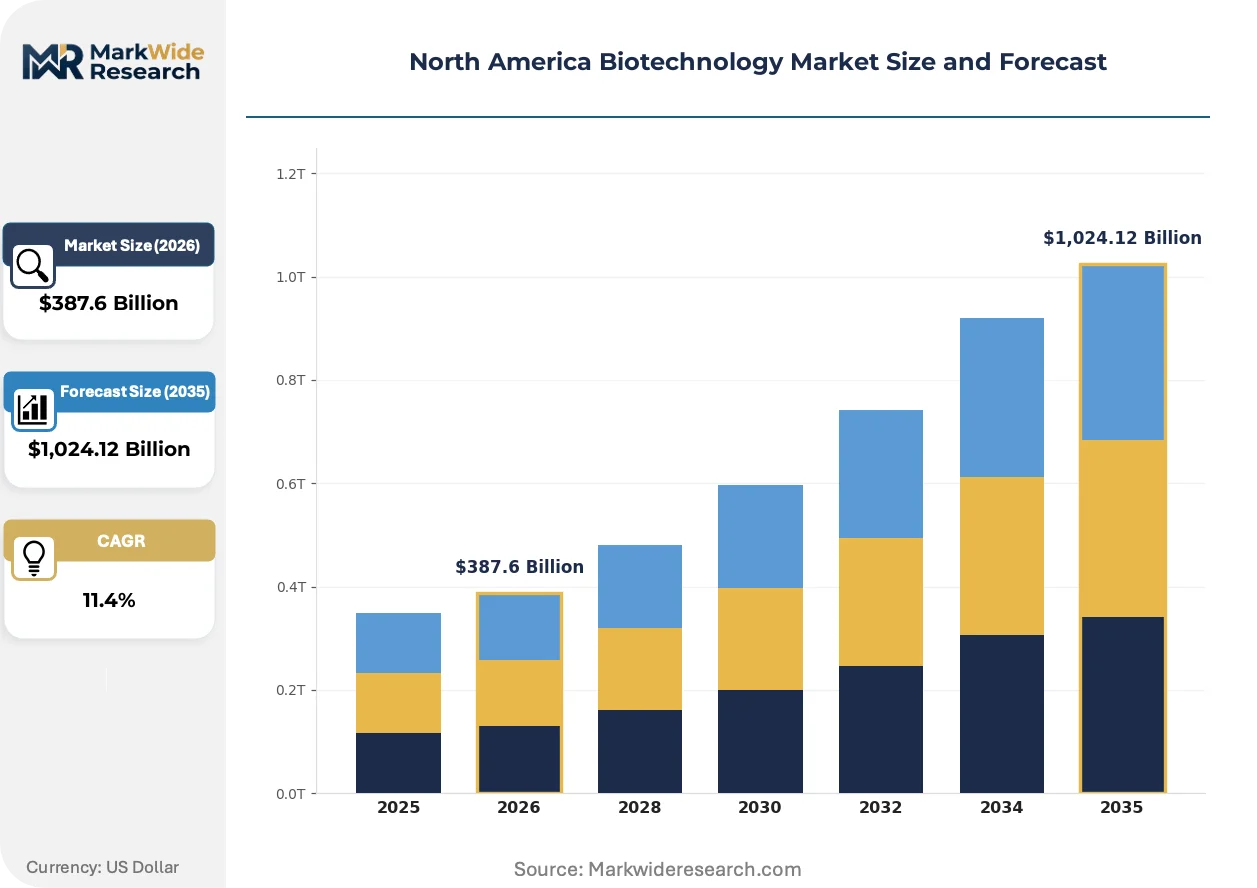
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopharmaceuticals, Gene Therapy, Monoclonal Antibodies, Vaccines Application: Drug Development, Clinical Trials, Diagnostics, Research End User: Pharmaceutical Companies, Academic Institutions, Contract Research Organizations, Hospitals Technology: CRISPR, Recombinant DNA Technology, Synthetic Biology, Cell Culture |
| Companies Covered | Pfizer, Amgen, Thermo Fisher Scientific, Merck KGaA, Lonza Group, Biogen, AstraZeneca, Gilead Sciences, Regeneron Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biotechnology Market Evolving Landscape
Single-use technologies and modular facility designs are dismantling traditional capital-intensive manufacturing paradigms, enabling geographic flexibility and accelerating the shift toward distributed production networks across North American biotechnology corridors.
Single-use bioreactor systems are displacing stainless-steel infrastructure as the dominant production platform for clinical-phase biologics. Mid-cap developers and contract manufacturers are adopting disposable technologies to eliminate cleaning validation burdens and enable rapid product changeovers. This shift is compressing facility construction timelines and enabling manufacturing capacity to follow pipeline geography rather than concentrating in historical biotech hubs.
Health Canada's ICH Q5D compliance harmonization with FDA standards is reducing regulatory friction for cross-border biologics development. Dual-approval pathway efficiencies are enabling sponsors to leverage Canadian clinical data for U.S. submissions and vice versa. Developers with integrated North American regulatory strategies are capturing timeline advantages over competitors pursuing sequential national filings.
Biopharma procurement teams are consolidating supplier relationships around integrated instrument-reagent-service architectures that reduce vendor management complexity. Large molecule developers are shifting from transactional equipment purchases toward multi-year platform partnerships that embed consumable lock-in and technical support. This consolidation is most visible among Massachusetts and California clusters where facility density enables preferred vendor negotiations.
North America Biotechnology Market Segmentation
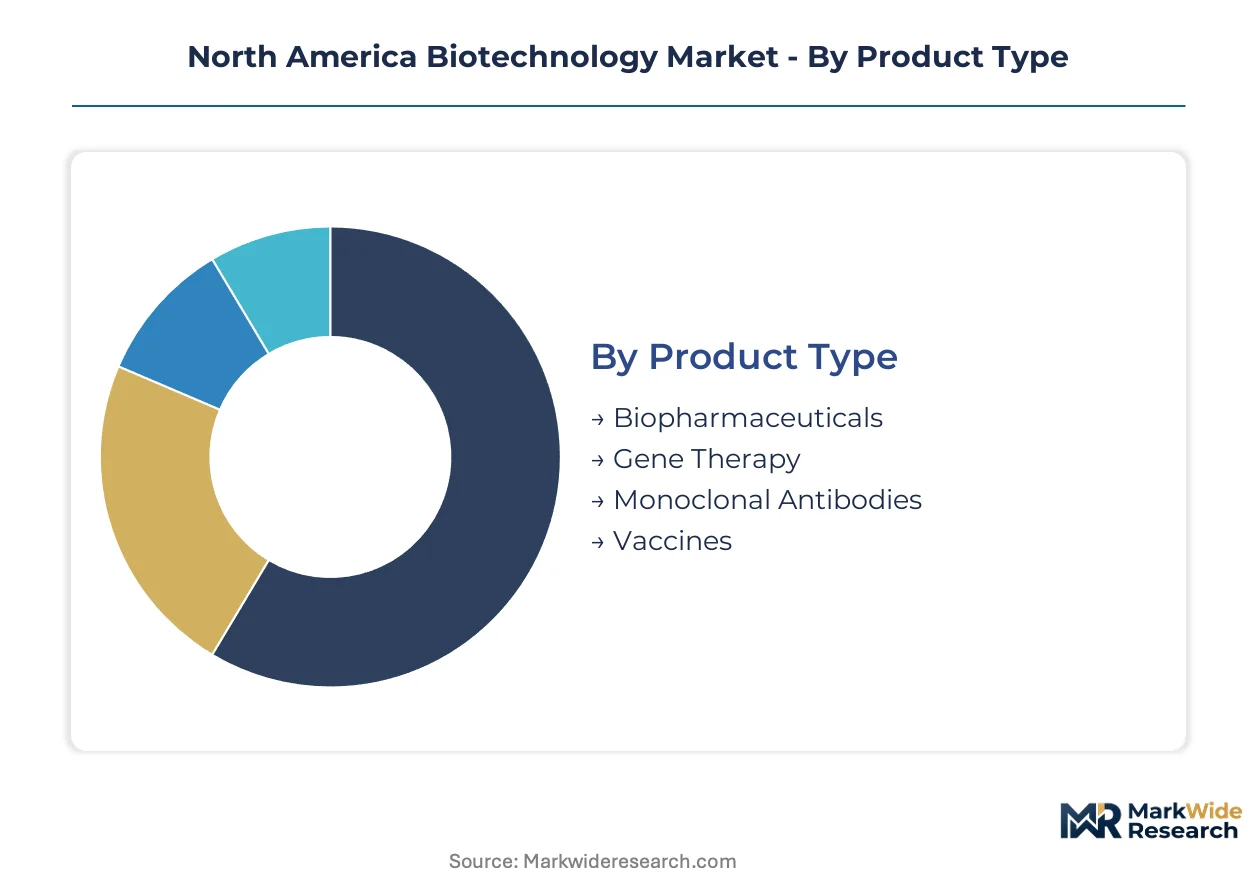
Biotechnology segmentation reveals how manufacturing complexity, regulatory pathways, and reimbursement durability concentrate value across distinct product and technology categories. Understanding these divisions exposes where capital deployment and competitive positioning diverge most sharply.
Product Type:
Gene therapy platforms face acute substitution pressure from next-generation gene editing modalities, while established biologics confront biosimilar erosion that reshapes investment priorities across therapeutic portfolios.
- Biopharmaceuticals:Therapeutic proteins and peptides manufactured through recombinant fermentation or mammalian cell culture, requiring precise temperature and pH control throughout upstream and downstream processing. Demand concentrates among Massachusetts and California clusters where FDA-validated facilities anchor chronic disease revenue streams, though IRA Medicare price negotiation compresses margins for mature molecules.
- Monoclonal Antibodies:Y-shaped immunoglobulins targeting specific antigens, produced via fed-batch or perfusion bioreactor systems with Protein A chromatography purification. North Carolina's Research Triangle and Boston suburbs absorb the majority of new capacity investment as bispecific formats and antibody-drug conjugates command premium manufacturing slots.
- Gene Therapy:Viral vector-delivered genetic medicines addressing monogenic disorders, constrained by plasmid DNA supply bottlenecks and limited GMP manufacturing expertise. FDA's accelerated approval pathway for rare diseases sustains pipeline momentum despite batch-to-batch variability challenges.
- Vaccines:Prophylactic and therapeutic immunizations spanning mRNA, viral vector, and recombinant subunit platforms, with fill-finish capacity often determining regional supply security. Post-pandemic capacity expansion has created regional oversupply in certain modalities.
Biopharmaceuticals anchor the volume base while gene therapy gains share at the steepest rate.
Application:
Cost tier stratification separates capital-intensive clinical-phase manufacturing from lower-infrastructure research applications, with diagnostics occupying a mid-tier position shaped by reimbursement variability.
- Drug Development:Discovery through Phase III therapeutic candidate advancement, consuming the majority of mammalian cell culture capacity and driving continuous bioprocessing adoption. Massachusetts and California corridors concentrate preclinical through early-clinical manufacturing investment.
- Clinical Trials:GMP material production for human studies, where single-use technologies enable rapid protocol pivots and multi-product facility utilization. FDA's streamlined IND review compresses timelines for sponsors with established quality systems.
- Diagnostics:Companion and standalone testing platforms, including PCR, next-generation sequencing, and immunoassay systems. Reimbursement codes and FDA 510(k) pathways determine commercial velocity more than technical performance.
- Research:Non-GMP reagents and tools for exploratory studies, characterized by lower regulatory burden and higher price sensitivity. Academic procurement cycles and grant funding availability drive demand fluctuation.
Drug development commands the largest capital allocation while clinical trials demonstrate the most rapid capacity expansion.
End User:
Customer type differentiation reflects procurement sophistication, with pharmaceutical companies demanding integrated service architectures that smaller academic buyers cannot justify.
- Pharmaceutical Companies:Large and mid-cap developers with internal manufacturing footprints and extensive contract manufacturing relationships. Thermo Fisher Scientific and similar integrated suppliers dominate upstream procurement through multi-year platform partnerships.
- Contract Research Organizations:Outsourced service providers managing discovery, preclinical, and clinical functions for sponsor companies, increasingly adopting single-use and modular manufacturing to enable geographic flexibility.
- Academic Institutions:University and research foundation laboratories with limited GMP capabilities, focused on early discovery and technology translation. Grant funding cycles and core facility access constraints limit capital intensity.
- Hospitals:Medical centers with cell and gene therapy treatment capabilities, requiring point-of-care manufacturing infrastructure for autologous therapies. FDA's expanded access programs and institutional review board frameworks govern operational scope.
Pharmaceutical companies sustain the revenue foundation while contract research organizations expand most aggressively into manufacturing services.
Technology:
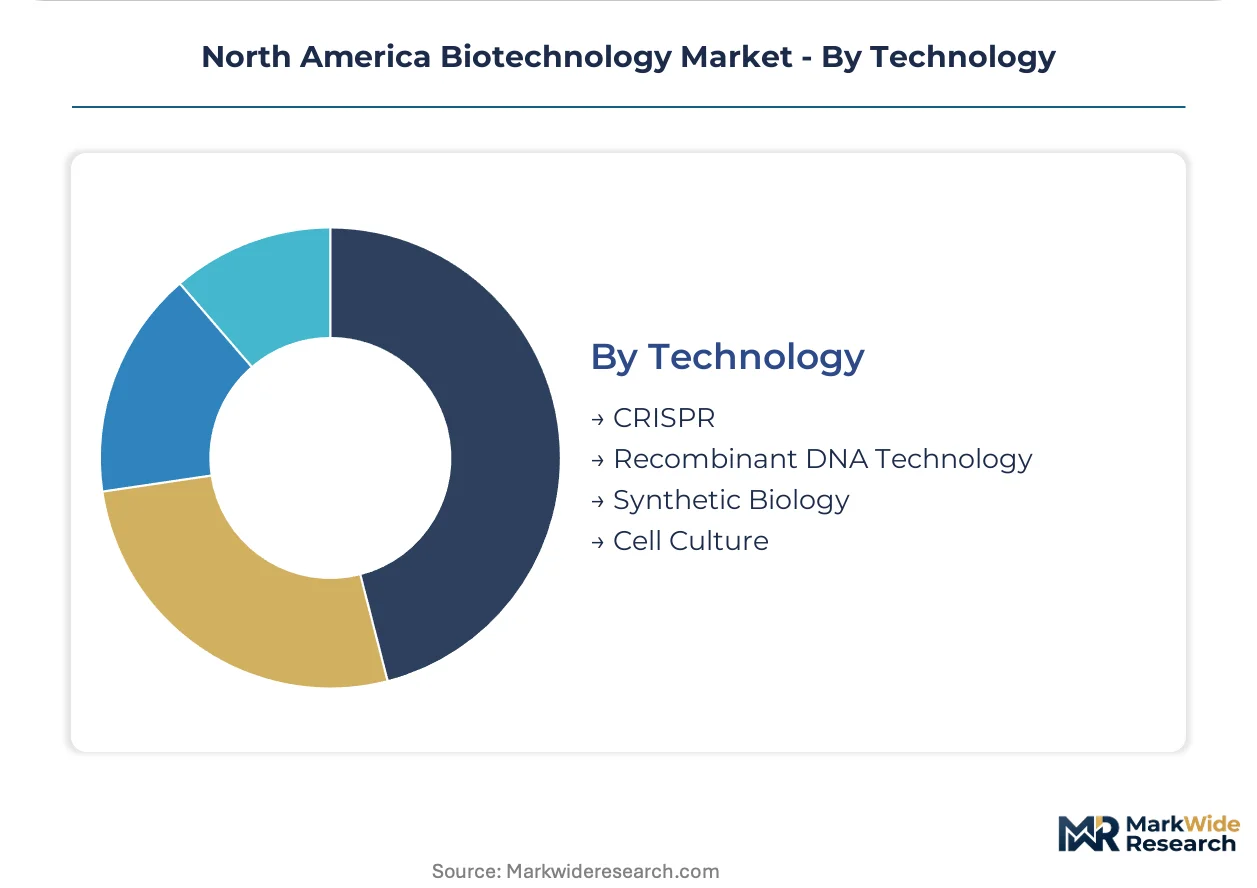
Technology maturity curves separate proven recombinant platforms from emerging modalities, with synthetic biology attracting concentrated venture investment despite limited commercial scale.
- Recombinant DNA Technology:Insertion of foreign genes into host organisms for protein production, remaining the dominant commercial platform across insulin, growth factors, and therapeutic enzymes. Established validation packages and regulatory precedents reduce approval risk.
- Cell Culture:Mammalian and microbial propagation systems for biologics manufacturing, with perfusion and continuous processing technologies displacing traditional fed-batch methods. Amgen and Regeneron maintain among the largest mammalian footprints in California and New York.
- CRISPR:Programmable gene editing nucleases for therapeutic and research applications, facing manufacturing complexity around guide RNA synthesis and delivery vector production. FDA's emerging gene therapy guidance shapes development timelines.
- Synthetic Biology:Engineered biological systems and chassis organisms for novel molecule production, spanning biofuels, materials, and pharmaceutical precursors. R&D investment outpaces commercial revenue by substantial margins.
Recombinant DNA technology retains the broadest installed base while synthetic biology climbs the fastest toward scaled commercial application.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical companies and contract manufacturers concentrate procurement power in coastal corridors, while academic medical centers anchor demand for cell and gene therapy infrastructure across the continent.
United States
Massachusetts and North Carolina absorb the majority of mammalian cell culture capacity expansion as oncology pipelines densify. FDA's accelerated approval pathways compress development timelines, pulling investment toward speed-to-clinic metrics. The Greater Boston cluster hosts the densest concentration of contract manufacturing organizations serving preclinical through Phase III biologics production.
Canada
Health Canada's expanding biologics manufacturing tax credits attract U.S. developers to establish production corridors in Ontario and Quebec. Streamlined clinical trial frameworks enable sponsors to leverage Canadian data for FDA submissions. The Toronto-Montreal corridor concentrates viral vector and plasmid DNA manufacturing investment.
Mexico
Medical device and diagnostic reagent manufacturing expands near the U.S. border to serve just-in-time supply chains for American hospital networks. COFEPRIS regulatory harmonization efforts with FDA standards reduce cross-border approval friction. Baja California and Nuevo León host the majority of biopharmaceutical packaging and fill-finish operations.
North America Biotechnology Market Competitive Landscape
Player mix skews toward integrated life sciences conglomerates with instrument-reagent-service architectures dominating upstream supply relationships. The vendor base stratifies across three tiers: full-platform providers capturing multi-year partnerships, specialized contract manufacturers securing premium slots for complex modalities, and regional service providers competing on geographic proximity. Consolidation pressures intensify as validation costs for FDA Good Manufacturing Practice certification force smaller entrants toward acquisition or exit. Capacity expansion and strategic partnerships represent the dominant competitive moves reshaping facility investment patterns.
Among integrated platform providers, Thermo Fisher Scientific and Merck KGaA exemplify the instrument-reagent-service archetype that locks in long-term consumable demand. Amgen occupies a position representing the large-cap biopharma with captive mammalian manufacturing footprints, while Regeneron Pharmaceuticals exemplifies the antibody engineering specialist differentiating through novel platform approaches rather than scale economics.
| Leading Market Players |
|---|
| Pfizer |
| Amgen |
| Thermo Fisher Scientific |
| Merck KGaA |
| Lonza Group |
| Biogen |
| AstraZeneca |
| Gilead Sciences |
| Regeneron Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with Protein A resin suppliers lock in downstream processing access and insulate biologics manufacturers from chromatography media price volatility. These arrangements tether pricing visibility to GMP-grade raw material security across Massachusetts and North Carolina manufacturing clusters.
Pricing Analysis
Cost-plus contracts indexed to commodity chemical baskets dominate upstream raw material procurement, with fermentation media and buffer components repricing quarterly. Price differentiation hinges on FDA validation tier and batch scale, with commercial-phase GMP commands premium over clinical-grade material. Pricing pressure stems from IRA Medicare price negotiation compressing margins on mature biologics. Large-cap pharmaceutical companies exhibit lowest price sensitivity due to captive manufacturing, while mid-cap developers and CROs negotiate aggressively on single-use consumables.
Supply Chain Analysis
Inbound logistics costs from European chromatography resin manufacturers through Port of Boston and Port of Wilmington fluctuate with container availability across trans-Atlantic lanes. Plasmid DNA supply concentrates in the United States and Germany, while specialty fermentation media draws from Switzerland and Singapore. Single-source dependency on qualified GMP plasmid suppliers creates batch failure vulnerability. Distribution runs through cold-chain logistics networks anchored by regional distribution centers in Philadelphia and Chicago.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America biotechnology market functions as a regulatory entrenchment story where FDA validation history creates switching costs that lock in incumbent contract manufacturers. Network effects concentrate around integrated instrument-reagent-service platforms that embed multi-year consumable demand.
For Market Incumbents: Fortify mammalian cell culture capacity in Research Triangle and Greater Boston corridors to capture CAR-T and bispecific antibody manufacturing demand. Deepen backward integration into plasmid DNA production to neutralize single-source supply risk. Prioritize continuous bioprocessing technology adoption to compress facility footprints and accelerate speed-to-clinic timelines for oncology pipelines. For New Entrants and Emerging Players: Lead with AI-driven cell line development platforms targeting mid-cap developers seeking compressed timelines for IND-enabling studies. Canadian biologics manufacturing incentives in Ontario and Quebec offer the most penetrable geographic entry point. Position around modular single-use facility designs that bypass stainless-steel infrastructure requirements and enable rapid product changeovers. For Investors and Strategic Acquirers: Capital is best deployed toward contract manufacturing organizations with established FDA Master Files and viral vector production expertise. Long-term viability over the next decade hinges on gene therapy manufacturing capabilities as pipeline density accelerates. Watch FDA's emerging gene therapy guidance release as the signal for inflection in capital allocation toward next-modality platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Expands mammalian cell culture capacity to serve dense oncology pipelines in Massachusetts clusters. |
| Regulatory Approval Pathway | Accelerates FDA Biologics License Application timelines through prior validation package leverage. |
| Backward Integration | Captures plasmid DNA supply security and neutralizes single-source dependency for viral vector production. |
| Strategic Partnership | Locks in multi-year platform partnerships embedding consumable demand through integrated instrument-reagent-service architectures. |
| Geographic Expansion | Accesses Health Canada biologics manufacturing incentives across Ontario and Quebec production corridors. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, contract manufacturing officers, and hospital procurement managers and refined through secondary validation. FDA filings, Health Canada submissions, ClinicalTrials.gov records, and formulary databases anchored bottom-up demand estimation. Top-down triangulation cross-checked against SEC 10-K disclosures and industry association capacity surveys.
Variance decomposition across therapeutic modality, manufacturing scale tier, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level volume trajectories and pricing elasticity assumptions across the projection horizon. Modeled inputs incorporated pipeline density metrics for oncology and rare disease programs alongside facility investment patterns in coastal manufacturing corridors.
The analysis sits within stated boundaries; outcomes outside sustained IRA biomanufacturing tax credit availability and FDA accelerated approval pathway stability would require recalibration. Forecasts reflect assumptions around plasmid DNA supply expansion and continuous bioprocessing adoption rates. Regulatory guidance shifts on gene therapy manufacturing or Medicare price negotiation scope expansion would necessitate model revision. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Lupus Nephritis Market
Biopharmaceuticals
Global Breast Cancer Drugs Market
Biopharmaceuticals
Oral Chemotherapy Market
Biopharmaceuticals
A - Estradiol Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Interleukin 1 Beta (IL-1β) ELISA Kit Market
Biopharmaceuticals
Global Carcinoembryonic Antigen (CEA) Market
Biopharmaceuticals
Fenbendazole Market
Biopharmaceuticals
North America and Europe Pegylated Drugs Market
Biopharmaceuticals
Global Staphylococcal Infection Drugs Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Iran Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
Biopharmaceutical CMO and CRO Market
Biopharmaceuticals
Sezary Syndrome Market
Biopharmaceuticals
Mammalian Polyclonal Igg Antibody Market