
 Marine and Marine Management Software Market | 2026-2036
Marine and Marine Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Marine and Marine Management Software Market Intelligence
China's massive investment in automated port infrastructure and 5G connectivity is reshaping competitive positioning for software vendors. This digital transformation requires sophisticated management platforms for vessel traffic, cargo handling, and port logistics. Wärtsilä Voyage specializes in integrated navigation and fleet operations solutions, while ABB provides electrification and automation systems that interface with management software. These firms compete on the breadth of their integrated hardware and software ecosystems.
Marine and marine management software comprises integrated application suites designed to digitize and automate maritime operations. These platforms often integrate real-time data from IoT sensors and Automatic Identification System (AIS) transponders to provide a unified operational view. Cloud-based deployment models are rapidly displacing legacy on-premise systems due to scalability and lower upfront costs. While shipping companies are the largest end-user segment, demand from port authorities for vessel traffic and terminal management solutions represents a high-growth area.
Regulatory mandates are a primary catalyst for software adoption in the maritime sector. The International Maritime Organization’s (IMO) decarbonization rules and the EU's Monitoring, Reporting, and Verification (MRV) regulation require precise fuel consumption and emissions tracking. These compliance obligations necessitate software for data collection, analysis, and reporting. Stakeholders now face a critical decision between adopting comprehensive, integrated suites from major vendors or assembling modular, best-of-breed solutions from specialized providers.
Market Dynamics
Regulatory pressure for decarbonization is the central force shaping the marine software market. Mandates from the International Maritime Organization (IMO) are compelling ship operators to adopt digital tools for precise monitoring, reporting, and optimization of fuel consumption and emissions.
Growth Catalysts
- Regulatory Compliance:The IMO's Carbon Intensity Indicator (CII) and Energy Efficiency Existing Ship Index (EEXI) rules necessitate software for continuous data collection and analysis, creating a mandatory adoption cycle for fleet operators worldwide.
- Data Integration:The proliferation of IoT sensors and AIS transponders on vessels generates vast amounts of real-time data, which requires sophisticated software platforms to integrate and translate into actionable operational insights for crew and shore-based teams.
- Digital Port Infrastructure:Modernization initiatives in major port ecosystems, including those in Singapore, Shanghai, and Rotterdam, drive demand for software that can interface with digital terminal operations and vessel traffic service systems, improving port call efficiency.
Market Restraints
- High Implementation Cost:The significant upfront investment required for comprehensive, integrated software suites presents a substantial barrier for small-to-mid-sized fleet operators with limited capital budgets, slowing market-wide penetration.
- Lack of Data Standardization:The absence of universal data protocols across different marine equipment manufacturers and software vendors creates significant integration challenges, increasing the complexity and cost of creating a unified operational view.
- Industry Conservatism:A traditional resistance to change and a reliance on legacy, paper-based processes within parts of the maritime industry can hinder the adoption of new digital technologies, despite their proven efficiency benefits.
Strategic Opportunities
- Predictive Maintenance Analytics:Leveraging AI and machine learning to analyze real-time sensor data from onboard machinery offers a significant opportunity for software vendors to provide predictive maintenance solutions that reduce vessel downtime and maintenance costs.
- Autonomous Shipping Technology:The development of autonomous and remotely operated vessels creates a new frontier for highly sophisticated command, control, and navigation software, representing a long-term, high-value growth segment.
- Cloud-Based Solutions for SMEs:Developing scalable, cost-effective Software-as-a-Service (SaaS) platforms tailored to the needs of smaller shipping companies and charterers opens a large, underpenetrated segment of the market.
Industry Challenges
- Maritime Cybersecurity Threats:The increasing connectivity of shipboard and shore-based systems exposes critical operational data, such as navigation and cargo information, to a growing risk of sophisticated cyberattacks, demanding robust security measures.
- Skilled Workforce Shortage:A deficit of maritime professionals equipped with data science, IT integration, and software management skills creates a bottleneck for shipping companies looking to effectively implement and utilize advanced digital platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine and Marine Management Software Market |
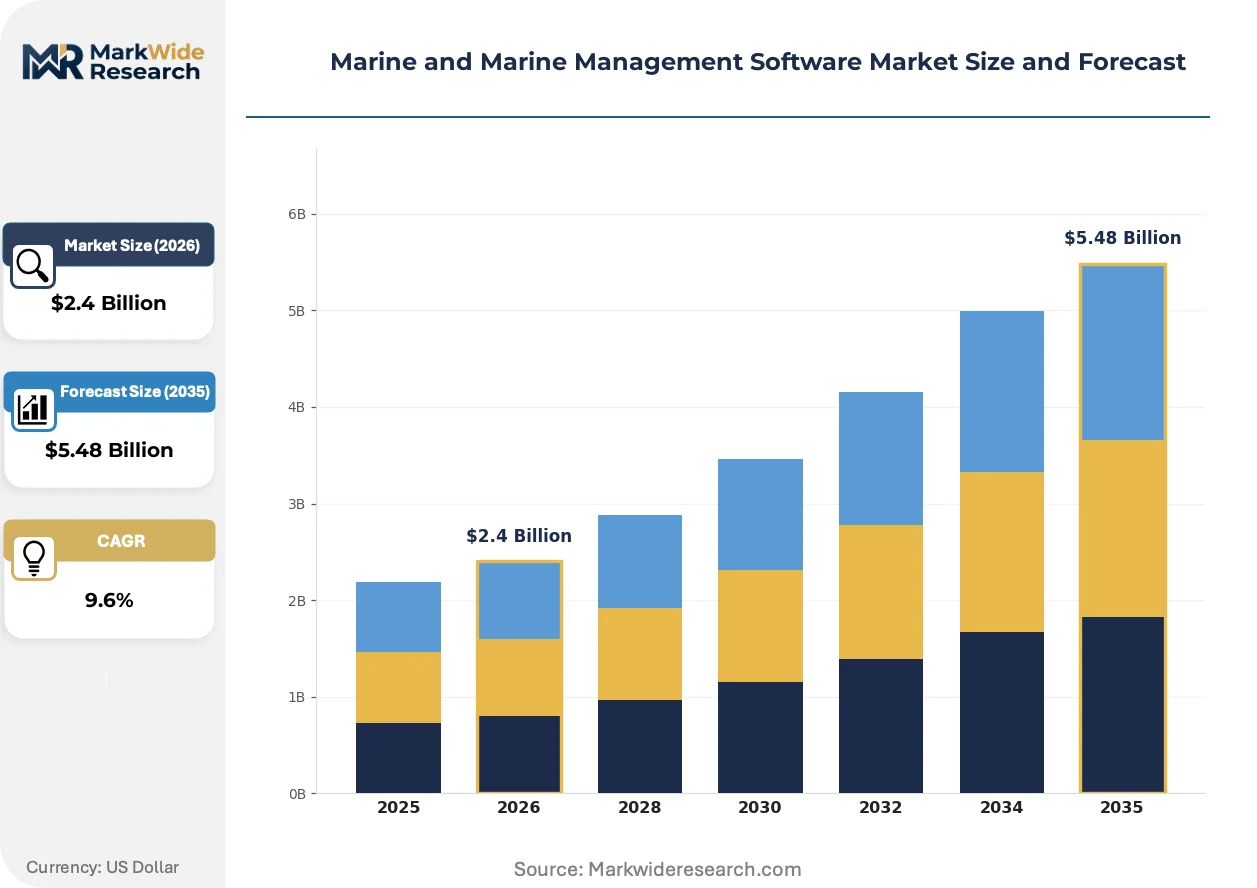
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.48 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fleet Management, Vessel Tracking, Maintenance Scheduling, Cargo Management, Crew Management Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Application: Route Optimization, Fuel Monitoring, Regulatory Compliance, Safety Management, Inventory Control End User: Shipping Companies, Port Authorities, Offshore Operators, Maritime Logistics Providers, Harbor Services |
| Companies Covered | ABB, Lloyd's Register, Dockmaster, Oracle, Harbour Assist, Chetu Inc., MARINA MASTER Ltd., MESPAS AG, Wärtsilä Voyage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine and Marine Management Software Market Strategic Shifts & Innovations
Convergence of operational technology (OT) from vessel hardware with information technology (IT) platforms defines the current innovation cycle. This integration is essential for creating the data-driven decision-making frameworks required for modern fleet and port management.
Digital twin technology creates a virtual, dynamic replica of a physical vessel, including its engines, navigation systems, and structural components. Shipping companies and naval architects are adopting these models for performance simulation, crew training, and lifecycle management. This technology is digitizing the entire asset lifecycle, enabling optimization from the initial design phase through to operational deployment and eventual decommissioning.
The European Union's Monitoring, Reporting, and Verification (MRV) regulation imposes strict requirements for tracking CO2 emissions on voyages to, from, and between EU ports. This rule forces vessel operators to deploy certified software for accurate fuel consumption data collection, aggregation, and reporting to verifiers. The container shipping and cruise line segments, which have frequent port calls in Europe, are most impacted, accelerating their investment in compliance-specific software modules.
A clear behavioral shift is underway from perpetual software licenses toward subscription-based SaaS models delivered via the cloud. This transition allows shipping companies to convert large, upfront capital outlays into predictable, recurring operational expenses, lowering the barrier to entry for advanced analytics. This model is gaining the most traction among charter operators and regional ferry services that prioritize financial flexibility and scalability.
Marine and Marine Management Software Market Segmentation
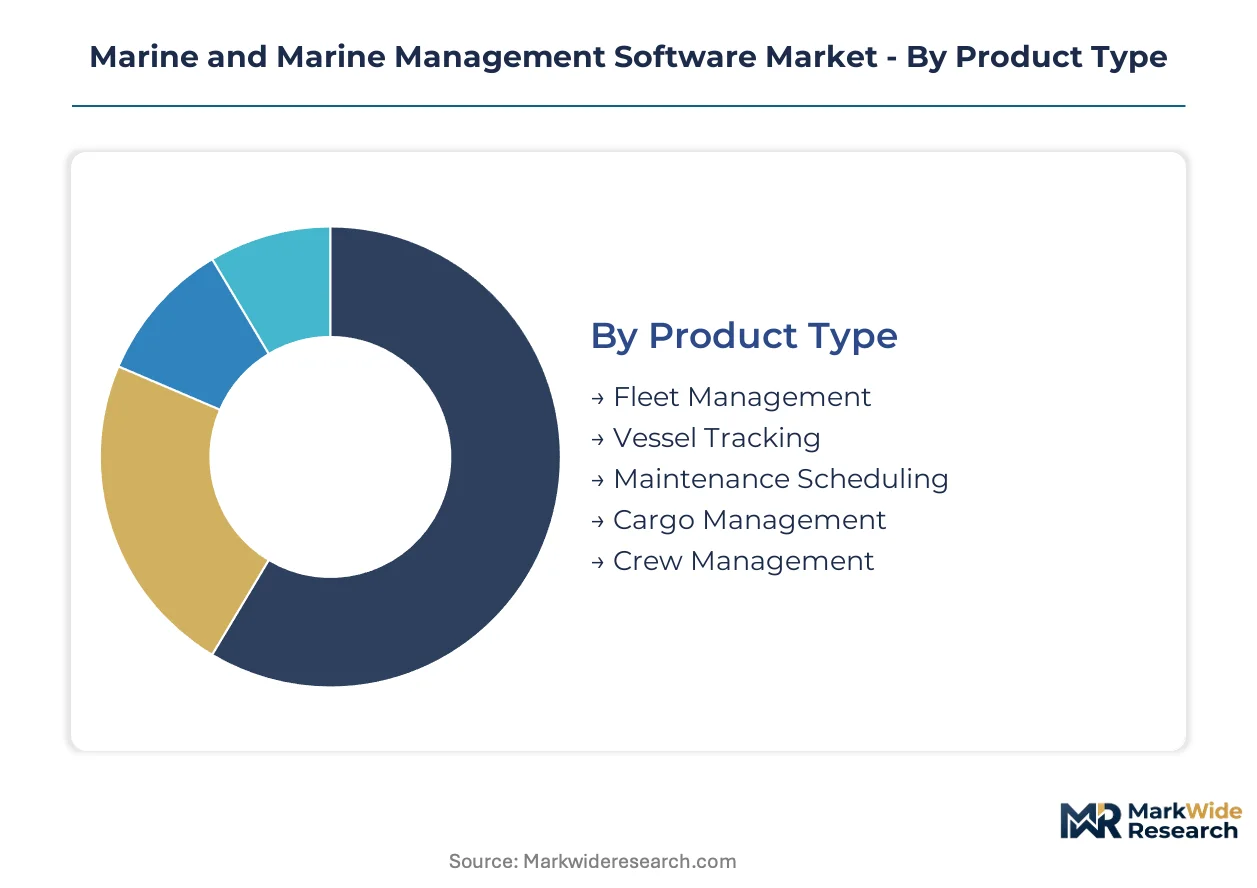
The marine and marine management software market segments into distinct categories reflecting varied operational needs and technological approaches. Understanding these divisions helps stakeholders identify areas of concentrated demand and emerging growth trajectories. This granular view reveals how different components of the maritime industry procure and utilize digital solutions.
Product Type:
Product type segments within marine software exhibit varying development and adoption cycles, from established core functions to rapidly evolving specialized modules.
- Fleet Management:These comprehensive platforms integrate multiple operational aspects, including scheduling, performance monitoring, and compliance. Demand concentrates among large shipping companies seeking unified control across global fleets to optimize resource allocation and reduce operational overheads.
- Vessel Tracking:This software utilizes AIS and satellite data to provide real-time vessel location, speed, and course information. Port authorities and maritime security agencies in major hubs like Singapore and Rotterdam rely on these systems for traffic control and situational awareness.
- Maintenance Scheduling:Software for maintenance scheduling automates the planning and execution of vessel upkeep, extending asset lifespan and ensuring regulatory compliance.
- Cargo Management:Cargo management solutions streamline the loading, stowage, and discharge processes, ensuring efficient utilization of vessel capacity and accurate documentation.
- Crew Management:Crew management software handles personnel scheduling, certification tracking, and payroll, optimizing human resource deployment across diverse maritime operations.
Fleet Management software dominates the installed base. Vessel Tracking solutions are where expansion concentrates due to security and efficiency mandates.
Deployment:
Deployment models reflect the maturity of digital infrastructure adoption and varying operational priorities across maritime stakeholders.
- Cloud-Based:These solutions are hosted remotely and accessed via the internet, offering scalability and reduced upfront infrastructure costs. Smaller shipping companies and new entrants in Europe are increasingly adopting cloud platforms for their operational flexibility.
- On-Premise:Installed and run directly on a company's own servers and infrastructure, these systems offer maximum data control and customization. Large, established shipping lines with extensive legacy systems in Asia often prefer on-premise deployments for security reasons.
- Hybrid:Hybrid models combine elements of both on-premise and cloud deployments, allowing for flexible data management and workload distribution.
- Edge Computing:Edge computing processes data closer to its source on vessels, reducing latency and enabling real-time analytics for critical shipboard operations.
Cloud-based solutions are gaining share fastest, while on-premise systems retain a significant footprint among legacy operators.
Application:
Software applications address specific operational challenges, ranging from environmental compliance to optimizing vessel performance.
- Regulatory Compliance:These applications enable maritime operators to adhere to international rules, such as IMO's decarbonization mandates and EU MRV regulations. Demand is particularly strong among container shipping and cruise lines frequently calling at European ports.
- Fuel Monitoring:Software for fuel monitoring tracks consumption rates in real-time, providing data for efficiency improvements and emissions reporting. Ship operators globally leverage these tools to reduce operational costs and meet environmental targets.
- Route Optimization:Route optimization software calculates the most efficient paths for vessels, considering weather, currents, and port congestion to save time and fuel.
- Safety Management:Safety management applications help maintain compliance with maritime safety standards, managing crew training, incident reporting, and emergency procedures.
- Inventory Control:Inventory control software tracks spare parts and supplies on vessels and at shore bases, optimizing procurement and minimizing stockouts.
Regulatory Compliance and Fuel Monitoring applications are experiencing the steepest expansion trajectory, driven by environmental mandates.
End User:
End-user segments reflect diverse organizational structures and operational scales within the maritime industry.
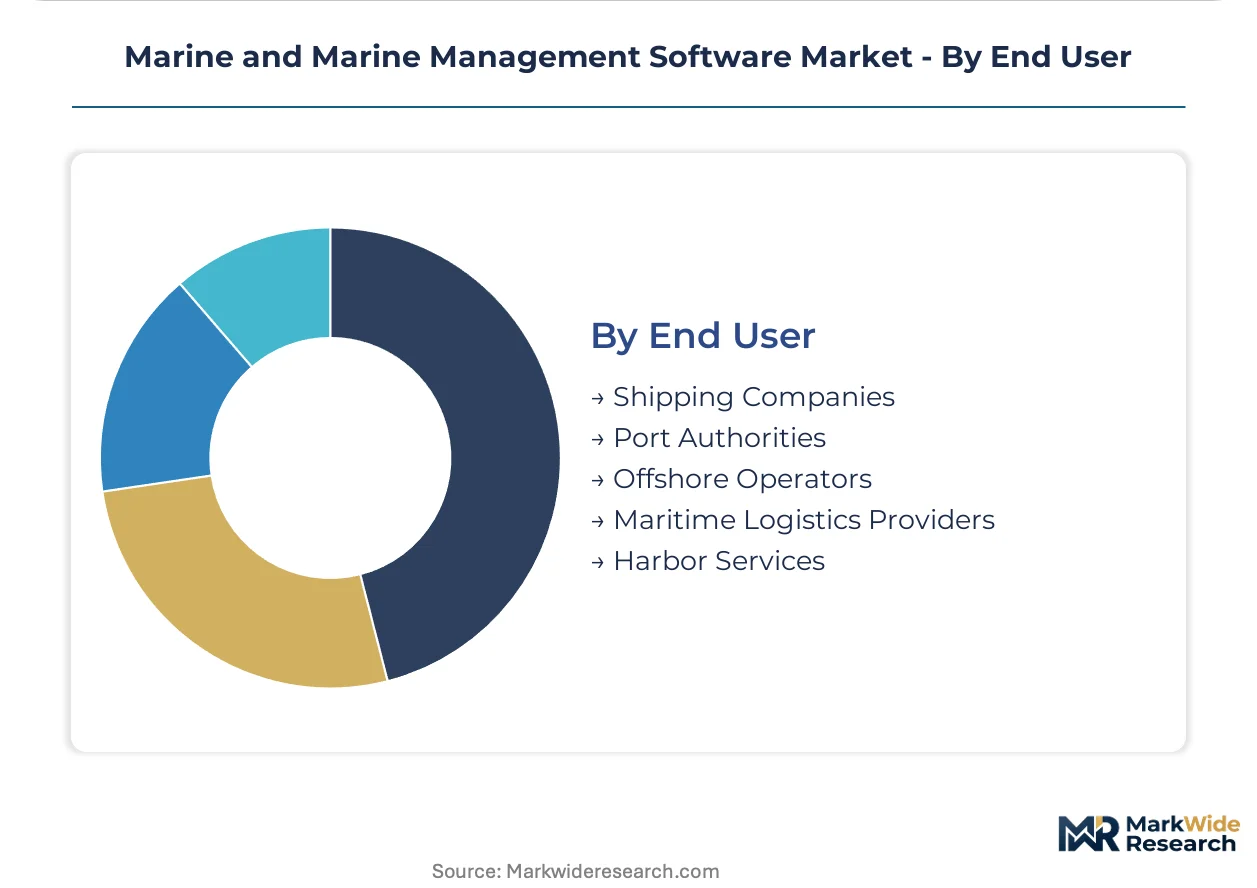
- Shipping Companies:This segment includes vessel owners and operators, ranging from large container lines to bulk carriers and tankers. They primarily invest in software for fleet management, operational efficiency, and regulatory adherence across their global operations.
- Port Authorities:Port authorities manage vessel traffic, terminal operations, and logistics within port ecosystems. They seek solutions for vessel traffic services, berth management, and digital infrastructure integration, particularly in major hubs like Shanghai.
- Offshore Operators:Offshore operators, including oil and gas exploration and wind farm support vessels, utilize specialized software for project management and asset integrity.
- Maritime Logistics Providers:These providers use software to manage cargo flows, warehousing, and multimodal transport, integrating land and sea logistics chains efficiently.
- Harbor Services:Harbor services encompass tugs, pilotage, and bunkering operations, relying on software for scheduling, resource allocation, and billing.
Shipping Companies represent the largest end-user segment, while Port Authorities demonstrate significant potential for future software adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The International Maritime Organization's (IMO) decarbonization rules compel maritime operators globally. This drives software adoption for compliance and operational efficiency. Demand concentrates in regions with high shipping traffic and advanced port infrastructure.
Singapore
Digital port infrastructure and vessel traffic management drive software demand in Singapore. The Maritime and Port Authority of Singapore (MPA) actively promotes smart shipping initiatives. Singapore Port, a major transshipment hub, is an early adopter of digital port solutions.
China
China's massive investment in automated port infrastructure and 5G connectivity fuels software demand. The country's dual carbon goals and national digital transformation policies impact software adoption. Shanghai and Ningbo-Zhoushan ports invest heavily in sophisticated management platforms.
Netherlands
Port logistics optimization and environmental compliance solutions are crucial for the Netherlands maritime sector. The EU MRV regulation and the broader EU Green Deal drive emissions tracking requirements. Rotterdam Port implements advanced software for port call optimization and vessel traffic services.
United States
Fleet operational efficiency and supply chain visibility solutions are critical drivers for the United States maritime industry. US Coast Guard regulations and environmental protection standards necessitate compliance software. Major port complexes like Los Angeles/Long Beach integrate software for cargo handling and intermodal logistics.
United Kingdom
Demand for maritime cybersecurity and digital navigation solutions is growing in the United Kingdom. The UK Maritime and Coastguard Agency (MCA) compliance requirements influence software development. London and other coastal cities host maritime tech firms developing integrated navigation and fleet operations solutions.
Marine and Marine Management Software Market Key Industry Players
Integrated solution providers and specialized software vendors split the market. Large industrial conglomerates offer comprehensive hardware and software ecosystems. Niche players focus on specific modules or cloud-based solutions. Strategic partnerships and portfolio diversification are common competitive moves.
ABB and Wärtsilä Voyage exemplify integrated solution providers, offering broad hardware and software ecosystems. Oracle represents large enterprise software vendors, extending their platforms into maritime management. These firms differentiate by the breadth of their offerings and integration capabilities.
| Leading Market Players |
|---|
| ABB |
| Lloyd's Register |
| Dockmaster |
| Oracle |
| Harbour Assist |
| Chetu Inc. |
| MARINA MASTER Ltd. |
| MESPAS AG |
| Wärtsilä Voyage |
| Others |
Cost & Logistics Intelligence
Skilled workforce undercapacity in software development teams drives vendor behavior and influences pricing for specialized maritime solutions. This talent shortage particularly impacts the development of advanced AI and cybersecurity features, leading to higher costs for sophisticated platforms.
Pricing Analysis
Pricing for marine management software exhibits geographic variations, with higher costs often observed in regions with stringent regulatory mandates like the EU. Subscription-based SaaS models represent the dominant pricing structure, allowing operational expense conversion. Price differentiation stems from the level of customization required and the breadth of integrated features offered. Pricing softness affects basic modules due to increased vendor competition, while comprehensive integrated suites command premium rates. Smaller shipping companies and charter operators demonstrate higher price sensitivity compared to large fleet owners.
Supply Chain Analysis
Export controls on advanced computing technologies could impact the supply chain for marine management software, particularly for AI-driven analytics modules. Software development capabilities concentrate in countries like the United States, India, and China. The software supply chain relies on cloud infrastructure providers and real-time data feeds from IoT sensors and AIS transponders. Cybersecurity threats represent a significant structural risk, given the critical operational data involved. Distribution runs through direct sales channels from major vendors and specialized value-added resellers targeting niche maritime segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine management software market presents a significant service-attach opportunity, with recurring software subscriptions and advanced data analytics services expanding faster than initial platform deployments. This shift allows vendors to build long-term revenue streams and deeper client relationships.
For Market Incumbents: Insulate existing customer bases against new entrant disruption by deepening integration capabilities with vessel hardware and port systems. Consolidate market share through strategic acquisitions of specialized software firms offering AI-driven predictive maintenance or autonomous shipping solutions. Leverage significant R&D investment to maintain a technology lead, particularly in cybersecurity, addressing growing maritime cybersecurity threats. Enhance after-sales service and support to reinforce client loyalty.
For New Entrants and Emerging Players: Establish a beachhead in the underpenetrated small-to-mid-sized fleet operator segment by offering scalable, cost-effective cloud-based SaaS platforms. Target specific regulatory compliance modules, such as EU MRV reporting, as a focused entry point. Leverage agile development and a strong customer support model to differentiate against larger, slower-moving incumbents. A direct-to-consumer digital sales approach can reach these smaller operators efficiently.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downwards across cloud-based software providers, signaling long-term viability and attractive returns over a 5-10 year horizon. Seek acquisition targets specializing in AI/ML analytics for predictive maintenance or autonomous shipping software, which represent high-growth, high-value segments. Monitor the increasing integration of operational technology (OT) with information technology (IT) as a key inflection signal. Companies with strong intellectual property in data integration and cybersecurity present compelling opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Powered Predictive Maintenance Modules | Reduces vessel downtime and operational costs for shipping companies through real-time data analysis. |
| Expand Cloud-Based SaaS Offerings for SMEs | Captures a large, underpenetrated market segment of smaller shipping companies with flexible solutions. |
| Strengthen Cybersecurity Protocols and Features | Protects critical operational data from increasing maritime cyberattacks, ensuring system integrity for port authorities. |
| Integrate Digital Twin Technology for Asset Lifecycle | Optimizes vessel performance and design from initial stages through decommissioning for naval architects. |
| Form Strategic Partnerships with Port Authorities | Enhances port call efficiency and vessel traffic management in major port ecosystems like Singapore. |
Research Approach
A spread of perspectives from CTOs, IT procurement officers, and port operations managers converged on the working assumptions for this market analysis. The methodology combined extensive primary interviews with industry stakeholders and rigorous secondary validation. Data sources included SEC filings of major vendors, industry association reports, maritime regulatory databases, and port authority annual reports. This approach facilitated bottom-up data aggregation and top-down market sizing triangulation.
Demand-supply balance dynamics informed the analytical framework across the analysis window, projecting market evolution. The model segmented the market by product type, deployment model, application, end-user, and regional adoption pattern. Compound Annual Growth Rates (CAGRs) were derived by analyzing historical growth trends and projected technological advancements. Key forecast inputs included regulatory compliance timelines and digital port infrastructure investment plans.
Stress conditions across global trade volumes and cybersecurity incident rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions concerning regulatory stability and technological adoption rates. Material shifts in geopolitical stability or major cyberattack frequency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Yacht Painting and Maintenance Market
Marine
Passenger Vessel Propeller Market
Marine
Digital Nautical Charts Market
Marine
Global Maritime Information Market
Marine
Boat Console Market
Marine
Marine Lighting Market
Marine
Marine Fasteners Market
Marine
Sailboat Market
Marine
Asia-Pacific Electric Boat Market
Marine
Marine Shaft Power Meter Market
Marine
China Controllable Pitch Marine Propeller Market
Marine
Global Foldable Inflatable Boats Market
Marine
Offshore Autonomous Underwater Vehicle (AUV) Market
Marine
Rigid Inflatable Boats (RIB) Market
Marine
Marine Fender Market
Marine
Marine Fender Systems Market