
 Marine Lighting Market | 2026-2036
Marine Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Lighting Market Analysis
LED phosphor compounds is pivoting away from legacy halogen architectures across marine fixture lines. KOITO Manufacturing leverages its automotive LED heritage to transfer chip-on-board thermal management into salt-air environments. Lumishore anchors its position through proprietary through-hull sealing that sustains depth ratings beyond 100 meters. OSRAM Licht AG competes on spectral tunability for aquaculture and research vessel applications.
Marine lighting encompasses sealed luminaires engineered to IEC 60598-2-1 ingress protection standards, with housings cast in marine-grade aluminum or bronze alloys to resist chloride corrosion across navigation, deck, underwater, and interior functions. LED fixtures now dominate newbuild specifications due to lumen-per-watt efficiency and 50,000-hour rated lifespans that compress total cost of ownership for commercial operators. Navigation and underwater applications command premium positioning, while interior lighting segments compete on fixture aesthetics and dimming protocol compatibility. Hybrid power source configurations pairing battery storage with solar topping are gaining traction in sailing yacht and patrol craft segments where auxiliary generator runtime carries fuel penalties.
IMO SOLAS Chapter V mandates specific luminous intensity and arc-of-visibility standards for navigation lights, while the EU MDR framework governs electrical safety marking for fixtures sold into European-flagged vessels. The US Coast Guard enforces 33 CFR compliance for domestic commercial craft, creating a multi-jurisdictional certification burden that favors suppliers with in-house testing laboratories. Stakeholders must monitor emerging cyan-red spectral requirements for minimizing marine ecosystem disruption in sensitive habitat zones.
Market Dynamics
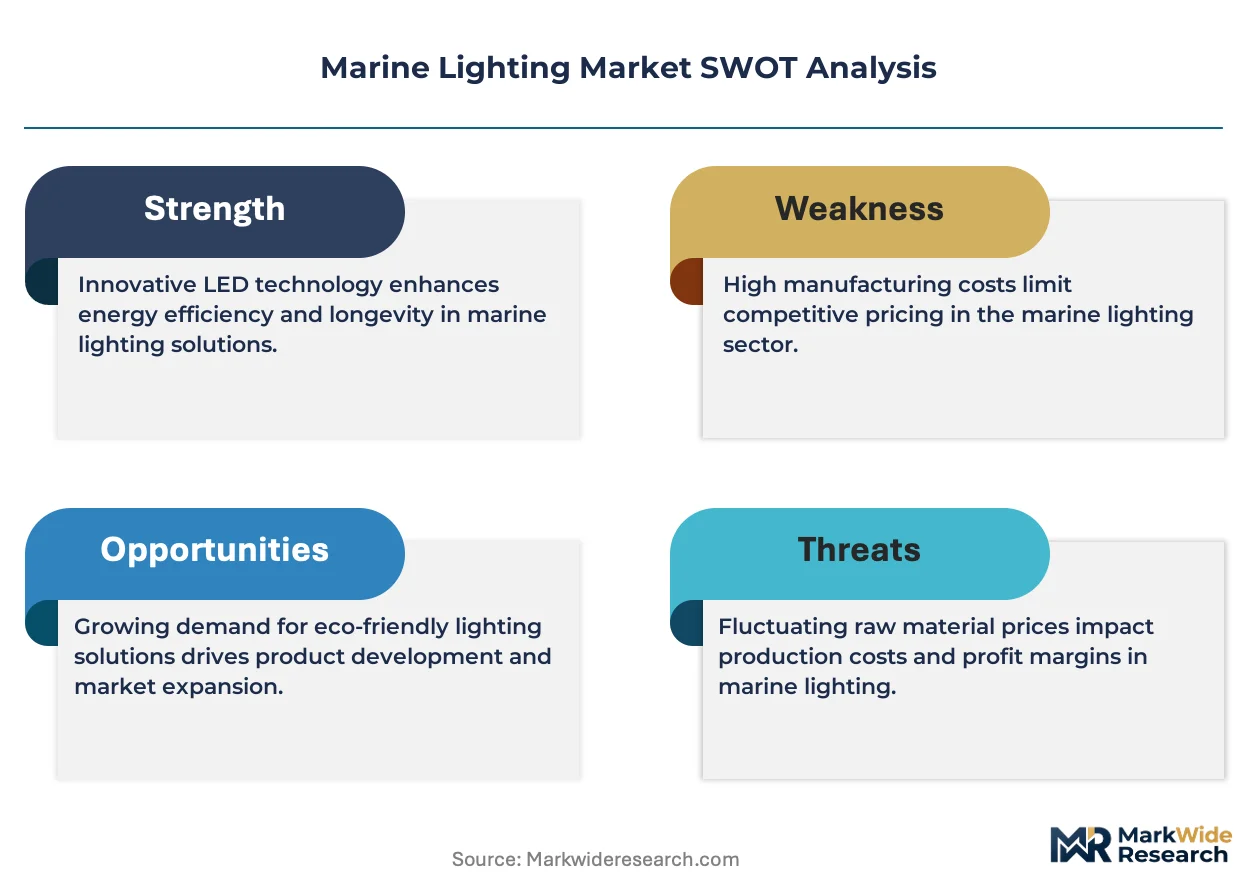
LED phosphor chemistry is modularizing fixture architectures across commercial and leisure vessel fleets, compressing thermal management costs while forcing incumbent suppliers to requalify salt-air-rated housings for IEC 60598-2-1 compliance.
Growth Catalysts
- SOLAS Chapter V luminous intensity mandates:Tightening arc-of-visibility standards for navigation lights are compelling fleet operators to replace legacy halogen fixtures with sealed LED arrays.
- Japanese shipyard concentration:Imabari's cluster of newbuild yards generates concentrated demand for marine-grade aluminum luminaires with 50,000-hour rated lifespans.
- Hybrid solar-battery topping systems:Sailing yacht and patrol craft segments are adopting auxiliary power configurations that favor low-draw LED circuits over generator-dependent halogen loads.
Market Restraints
- Marine-grade aluminum ingot volatility:Chloride-resistant housing alloys face input cost swings tied to primary metal markets, compressing margin buffers for fixture casters.
- Multi-jurisdictional certification burden:Suppliers must maintain parallel testing streams for US Coast Guard 33 CFR, EU MDR electrical safety marking, and IMO SOLAS navigation standards.
- Through-hull sealing technical ceiling:Depth ratings beyond 100 meters require proprietary elastomer compounds that resist cold-flow under hydrostatic pressure, limiting supplier pool.
Strategic Opportunities
- Cyan-red spectral mandates for habitat zones:Emerging regulatory requirements for minimizing marine ecosystem disruption create premium positioning for tunable-spectral fixtures in research and aquaculture vessels.
- Norwegian offshore supply vessel retrofit cycles:Ulsteinvik's maintenance-heavy fleet presents concentrated demand for interior dimming protocol upgrades compatible with DALI and DMX control systems.
- LiDAR-assisted collision avoidance convergence:Integration of LED navigation arrays with sensor fusion architectures opens specification wins in autonomous surface vessel programs.
Industry Challenges
- IP68 sealing technician scarcity:Qualified personnel for ingress protection testing against IEC 60598-2-1 salt spray protocols command wage premiums in US Gulf Coast and North Sea shipyard clusters.
- Legacy halogen fixture stranded asset risk:Commercial operators face compressed replacement windows as spare part availability for obsolete navigation lamp formats contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Lighting Market |
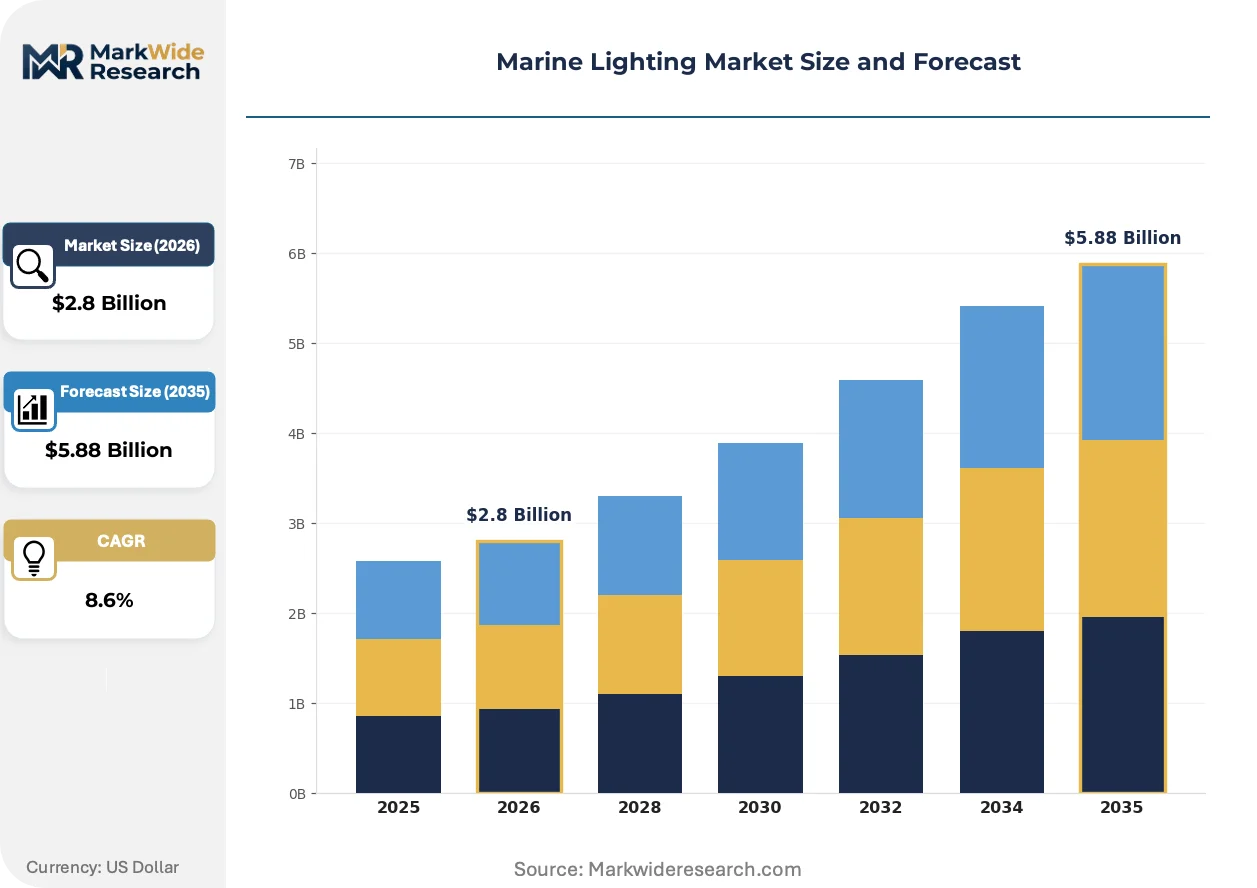
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Lights, Fluorescent Lights, Halogen Lights, Xenon Lights Application: Navigation, Deck Lighting, Underwater Lighting, Interior Lighting Power Source: Solar, Battery, AC, Hybrid Installation Type: Fixed, Portable, Integrated, Modular |
| Companies Covered | KOITO Manufacturing, Lumishore, OSRAM Licht AG, Glamox, Lumitec Lighting, Hella Marine, Aqualuma LED Lighting, OceanLED, Signify, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Lighting Market Emerging Trajectories
Phosphor-converted LED architectures are fragmenting fixture supply chains into discrete thermal, optical, and sealing subsystems. Three concurrent developments are compressing traditional integration models.
Chip-on-board LED arrays with ceramic substrate thermal vias are modularizing navigation and underwater fixture lines. Commercial ferry operators in the Baltic and North Sea are specifying these configurations for 24-hour operational cycles. The technology is modularizing supplier relationships, allowing shipyards to source thermal management, optics, and housings from distinct vendors rather than integrated fixture houses.
EU MDR electrical safety marking requirements are tightening conformity assessment procedures for fixtures sold into European-flagged vessels. Manufacturers must now maintain technical documentation and quality management systems beyond previous self-certification models. The regulation most affects interior lighting segments, where aesthetic fixture producers without in-house testing laboratories face compliance timeline compression.
Fleet operators are unbundling after-sales service contracts from initial fixture procurement. Large container lines and cruise operators now separately tender lamp replacement, sealing inspection, and control system calibration. The shift is most visible in Mobile Bay's shipyard cluster, where third-party marine electrical contractors capture maintenance revenue previously retained by original fixture suppliers.
Marine Lighting Market Segmentation
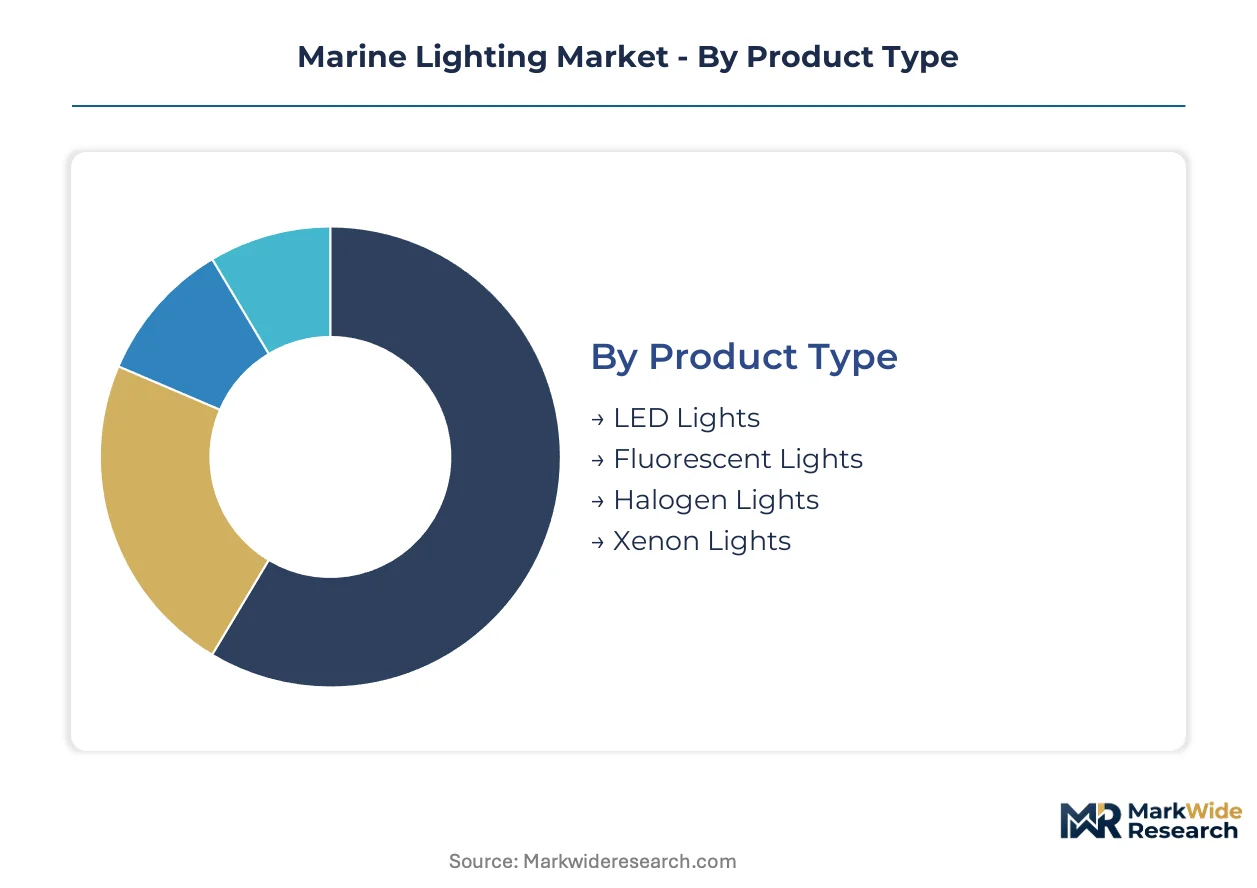
Marine lighting procurement decisions fragment across four technical dimensions, each imposing distinct certification burdens and supply chain requirements on fixture suppliers. Shipyards and fleet operators weight lumen efficiency, ingress protection ratings, and power source compatibility differently across vessel categories, creating segmented demand pools with minimal overlap.
Product Type:
Supply concentration in LED chip manufacturing has reshaped fixture sourcing patterns, with phosphor-converted arrays now dominating newbuild specifications across commercial and leisure fleets.
- LED Lights:Phosphor-converted arrays with ceramic substrate thermal vias deliver 50,000-hour rated lifespans and lumen-per-watt efficiency exceeding legacy halogen by 300%. Japanese shipyards in Imabari specify these for 24-hour operational cycles on container vessels and ferries.
- Fluorescent Lights:T5 and T8 tube configurations persist in engine room and galley retrofits where fixture replacement costs dominate energy efficiency calculations. Baltic Sea ferry operators retain these for interior task lighting in crew quarters.
- Halogen Lights:Tungsten-halogen navigation lamps face stranded asset risk as IMO SOLAS spare part availability contracts. Legacy fleets in Southeast Asian waters still carry these for emergency backup circuits.
- Xenon Lights:High-intensity discharge configurations command niche positioning in searchlight and spotlight applications requiring extreme throw distances. Offshore supply vessels operating in Norwegian waters specify these for deck illumination.
LED Lights absorb the bulk of installed capacity; Fluorescent Lights is expanding most quickly in cost-sensitive retrofit segments.
Application:
Cost tier differentiation separates navigation and underwater applications—where depth ratings and arc-of-visibility precision command premium positioning—from interior segments competing on dimming protocol compatibility.
- Navigation:Sealed luminaires engineered to IEC 60598-2-1 ingress protection standards with housings cast in marine-grade aluminum or bronze alloys. US Coast Guard 33 CFR compliance mandates specific luminous intensity and arc-of-visibility standards for commercial craft operating in Mobile Bay.
- Deck Lighting:Surface-mounted fixtures with IP68 sealing resist salt spray and mechanical impact from cargo handling. Container terminals in Rotterdam specify these for 24-hour loading operations.
- Underwater Lighting:Through-hull configurations with proprietary elastomer compounds sustain depth ratings beyond 100 meters. Yacht builders in Italy and Florida integrate these for aesthetic hull illumination and fish attraction.
- Interior Lighting:Aesthetic fixture lines compete on DALI and DMX dimming protocol compatibility for passenger vessel cabins and cruise ship public spaces. EU MDR electrical safety marking tightens conformity assessment for European-flagged vessels.
Navigation commands the steepest price premiums per fixture; Interior Lighting shows the fastest volume expansion as cruise fleet capacity grows.
Power Source:
Volume concentration in hybrid configurations reflects fuel penalty calculations for auxiliary generator runtime across sailing yacht and patrol craft segments.
- Solar:Photovoltaic topping circuits with battery buffering serve unmanned navigation aids and remote monitoring stations. Coastal installations in the Mediterranean and Caribbean leverage these for off-grid marker lights.
- Battery:Lithium-ion and AGM configurations power portable work lights and emergency backup circuits. Offshore wind service vessels specify these for maintenance operations during generator shutdown.
- AC:Shore power and shipboard generator feeds remain standard for interior lighting on large commercial vessels with continuous electrical loads.
- Hybrid:Solar-battery topping paired with AC fallback minimizes generator runtime for sailing yachts and coast guard patrol craft. Mobile Bay shipyards specify these for reduced fuel consumption profiles.
AC retains the largest installed base; Hybrid configurations gain share fastest in environmentally regulated waters.
Installation Type:
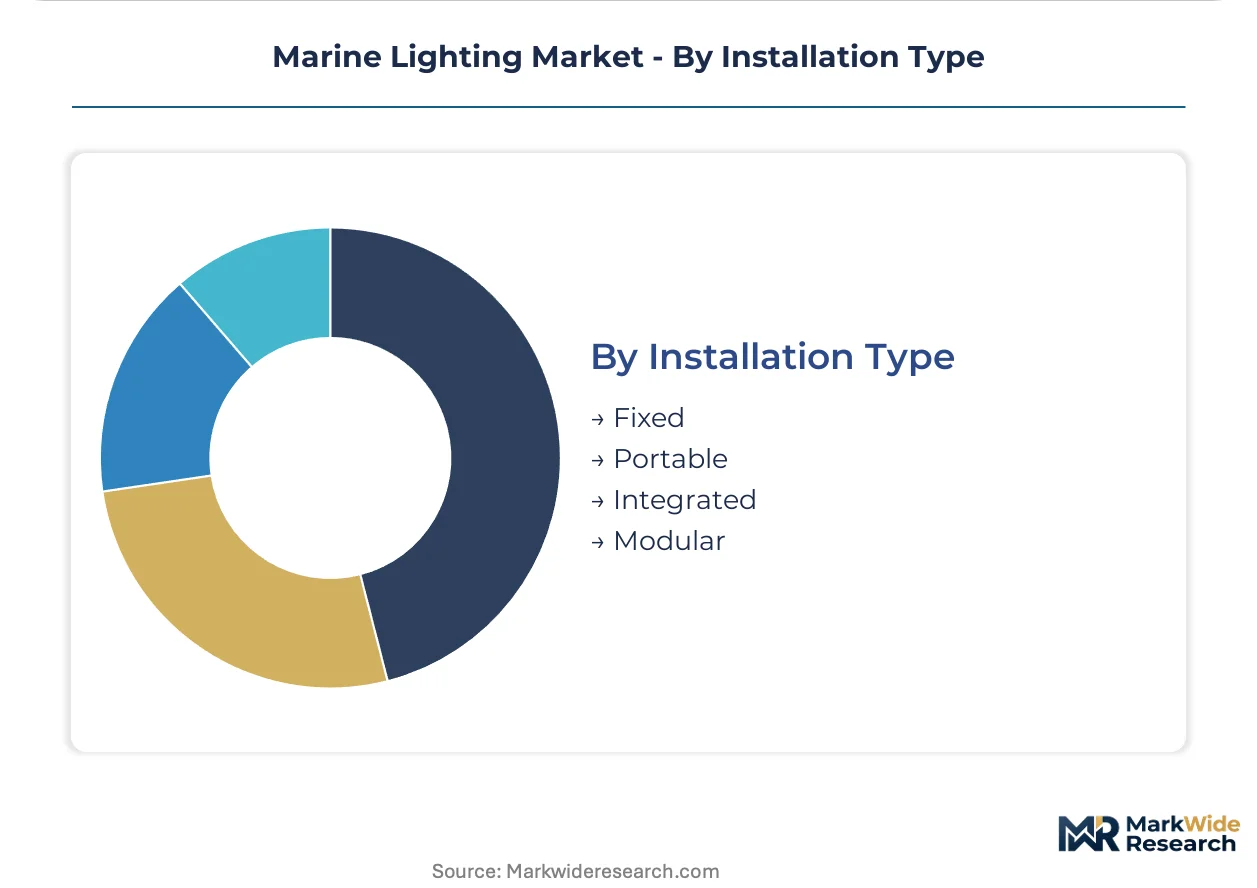
Customer type fragmentation separates shipyard newbuild procurement—favoring integrated and modular architectures—from aftermarket maintenance operations prioritizing portable and fixed replacement units.
- Fixed:Permanently mounted navigation and deck luminaires with hardwired electrical connections. Commercial operators favor these for reduced maintenance access requirements.
- Portable:Battery-powered work lights and temporary illumination for drydock and repair operations. Third-party marine electrical contractors in Ulsteinvik carry extensive portable inventories.
- Integrated:Factory-installed fixtures bundled with vessel electrical systems during newbuild construction. Japanese and Korean shipyards specify these for production line efficiency.
- Modular:Field-replaceable LED engines, drivers, and optics that extend fixture housing lifespans. Fleet operators unbundle after-sales service contracts to capture lamp replacement and sealing inspection revenue.
Fixed installations dominate current fleet composition; Modular designs are climbing the fastest as operators extend asset replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese, Norwegian, and United States shipyard clusters concentrate demand for marine-grade aluminum luminaires with 50,000-hour rated lifespans. SOLAS Chapter V mandates and hybrid power configurations are reshaping procurement patterns across these concentrated manufacturing zones.
United States
Mobile Bay's shipyard cluster generates concentrated demand for navigation and deck lighting compliant with US Coast Guard 33 CFR standards. The US Coast Guard enforces arc-of-visibility specifications that compel fleet operators toward sealed LED arrays. Gulf Coast operators specify hybrid solar-battery configurations to minimize auxiliary generator runtime in environmentally regulated waters.
Japan
Imabari's newbuild yards drive specification of phosphor-converted LED fixtures with ceramic substrate thermal vias for 24-hour operational cycles. METI oversees industrial standards alignment with IEC 60598-2-1 ingress protection protocols. Japanese container vessel and ferry operators prioritize lumen-per-watt efficiency to compress total cost of ownership across extended deployment schedules.
Norway
Ulsteinvik's offshore supply vessel fleet presents concentrated demand for interior dimming protocol upgrades compatible with DALI and DMX control systems. Norwegian regulators emphasize habitat protection measures that favor tunable-spectral fixtures in research and aquaculture applications. North Sea operators face compressed maintenance windows that accelerate modular fixture adoption for field-replaceable LED engines.
Italy
Yacht builders in Italian manufacturing zones integrate through-hull underwater lighting with proprietary elastomer sealing for depth ratings beyond 100 meters. EU MDR electrical safety marking tightens conformity assessment procedures for fixtures sold into European-flagged vessels. Mediterranean leisure vessel producers compete on aesthetic fixture lines with protocol compatibility for passenger cabin installations.
South Korea
Korean shipyards specify integrated factory-installed fixtures bundled with vessel electrical systems during newbuild construction. The country's national maritime regulator aligns commercial craft standards with IMO SOLAS navigation mandates. Busan-Ulsan manufacturing clusters favor production line efficiency through captive supply relationships with thermal management subsystem vendors.
Marine Lighting Market Vendor Landscape
Modular subsystem unbundling dominates the current landscape as shipyards source thermal management, optics, and housings from distinct vendors rather than integrated fixture houses. The vendor base spans three tiers: automotive LED heritage players transferring chip-on-board architectures, marine specialists with proprietary sealing IP, and lighting conglomerates competing on spectral tunability. Strategic archetypes include salt-air-rated housing specialists, phosphor chemistry innovators, and aquaculture-focused spectral engineers. Technology licensing and geographic expansion through shipyard cluster proximity represent the dominant competitive vectors.
Within the automotive-transfer archetype, KOITO Manufacturing exemplifies players leveraging thermal management heritage into marine environments. Lumishore anchors the marine-specialist tier through proprietary through-hull sealing capabilities. OSRAM Licht AG occupies a position among spectral engineering specialists addressing research and aquaculture vessel applications. These three entities represent distinct strategic postures without implying specific market share or operational scale.
| Leading Market Players |
|---|
| KOITO Manufacturing |
| Lumishore |
| OSRAM Licht AG |
| Glamox |
| Lumitec Lighting |
| Hella Marine |
| Aqualuma LED Lighting |
| OceanLED |
| Signify |
| Others |
Supply Flow & Price Mechanics
Qualified IP68 sealing technicians on the US Gulf Coast and in North Sea shipyard clusters command wage premiums that compress margin buffers for fixture suppliers and widen spreads between premium-certified and standard-grade product tiers.
Pricing Analysis
Volume concentrates in standard-grade LED navigation fixtures while margins accrue to premium-tier underwater and research-vessel applications with proprietary depth-rated sealing. Price differentiation hinges on IEC 60598-2-1 certification grade and after-sales service bundling. Cost compression in the standard tier intensifies as phosphor-converted LED arrays commoditize, while pricing holds firm in navigation segments where US Coast Guard 33 CFR compliance mandates limit supplier pools. Commercial ferry operators exhibit highest price sensitivity; yacht builders and research vessel operators show lowest sensitivity due to performance-critical specifications.
Supply Chain Analysis
Freight costs for marine-grade aluminum ingots from Japanese and Norwegian smelters feed into fixture casting operations concentrated in Japan, South Korea, and Italy. Supply chains draw from phosphor compound specialists in Taiwan, ceramic substrate vendors in Japan, and elastomer sealant formulators in Germany. Single-source vulnerability around proprietary through-hull sealing compounds beyond 100-meter depth ratings creates bottleneck risk. Distribution runs through shipyard cluster procurement offices and third-party marine electrical contractors capturing aftermarket service revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive advantage in marine lighting is becoming a vertical-integration race, with players pursuing captive control over thermal management subsystems and in-house IEC 60598-2-1 testing laboratories to compress certification timelines.
For Market Incumbents: Cement proprietary sealing IP through exclusive elastomer compound partnerships that resist cold-flow under hydrostatic pressure, while expanding captive ceramic substrate thermal via production to offset phosphor supply volatility. Modular fixture architectures from emerging subsystem vendors threaten integrated fixture houses; backward integration into chip-on-board LED engine manufacturing defends margin position. For New Entrants and Emerging Players: The 40-60% price-point gap between premium navigation fixtures and economy interior lines opens white-space targeting in the Ulsteinvik offshore supply vessel retrofit segment, where DALI and DMX dimming protocol upgrades lag newbuild specifications. Target Mediterranean yacht interior lighting for fastest penetration, leveraging EU MDR electrical safety marking compliance as a qualification barrier against non-European competitors. For Investors and Strategic Acquirers: Re-rating potential sits with marine-specialist fixture houses possessing proprietary through-hull sealing capabilities given tightening cyan-red spectral mandates for habitat zone applications. Long-term viability favors suppliers with demonstrated salt-air-rated housing heritage and shipyard cluster proximity in Imabari, Ulsteinvik, or Mobile Bay. Watch for LiDAR-assisted collision avoidance program wins as inflection indicators for autonomous surface vessel specification traction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrate Production | Captive thermal via supply secures chip-on-board LED performance for 24-hour operational cycles. |
| In-House IEC 60598-2-1 Testing Laboratory Investment | Parallel US Coast Guard 33 CFR and EU MDR compliance streams compress certification timelines for multi-jurisdictional sales. |
| Proprietary Elastomer Sealing Compound Partnership | Exclusive depth-rating IP beyond 100 meters limits competitor access to research and aquaculture vessel specifications. |
| Shipyard Cluster Proximity Expansion | Co-located technical support captures modular fixture replacement revenue in Imabari and Ulsteinvik maintenance cycles. |
| Spectral Tunability R&D Program | Cyan-red wavelength control addresses emerging Norwegian habitat protection mandates for sensitive ecosystem zones. |
Methodological Framework
Independent corroboration across shipyard procurement directors, marine electrical contractors, and thermal management subsystem vendors underwrites the qualitative findings. Primary interviews with fixture design engineers, IP68 sealing technicians, and fleet maintenance managers combined with secondary validation from IMO SOLAS regulatory filings, US Coast Guard 33 CFR documentation, EU MDR technical standards, and Japanese METI industrial guidelines. Bottom-up vessel fleet analysis and top-down lighting spend estimates triangulate market sizing.
Comparable-period anchoring to historical newbuild delivery schedules and retrofit cycle patterns shaped the projection horizon across the analysis window. Segmentation modeling incorporated product type, application function, power source configuration, and installation category, with vessel class and operational intensity as industry-specific dimensions. CAGRs were derived from fitted growth curves applied to segment-level baselines, incorporating phosphor-converted LED adoption curves and hybrid power source penetration rates as forecast inputs.
Inputs from shipyard production databases and fleet operator maintenance records were available through the study window; gaps in autonomous surface vessel program specification data introduce uncertainty bands around LiDAR-integrated navigation array forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Filter Market
Marine
Global Foldable Inflatable Boats Market
Marine
Autonomous Ships Market
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
Hydraulic Marine Cranes Market
Marine
Marine Pipes Market
Marine
Marine and Marine Management Software Market
Marine
Marine Stabilizers Market
Marine
Marine Fender Market
Marine
Sailboat Propellers Market
Marine
Digital Nautical Charts Market
Marine
Pneumatic Marine Fender Market
Marine
Hybrid Fishing Boats Market
Marine
Hydrogen Ships Market
Marine
Marine Electronics Market
Marine
Marine Transport Refrigeration Unit Market