
 Passenger Vessel Propeller Market | 2026-2036
Passenger Vessel Propeller Market Size, Share, and Industry Trends Forecast 2026-2036
Passenger Vessel Propeller Market Analytics
Marine propulsion engineering talent is rotating toward computational fluid dynamics and additive manufacturing, tightening the labor pool for traditional foundry crafts. Wartsila leverages its Helsinki R&D campus to sustain technology leadership in controllable-pitch systems. Nakashima Propeller Co., Ltd. anchors premium supply to Japanese shipyards through in-house nickel-aluminum-bronze casting. Schottel Group competes in azimuth thruster integration, extending its reach beyond conventional shaftline propellers.
Passenger vessel propellers are hydrodynamic devices that convert rotational shaft power into thrust through precisely profiled blade sections operating in water, typically manufactured via sand casting or investment casting of copper-based alloys with critical tolerances below 0.5 millimeters on blade pitch. Their primary purpose is to propel ferries, cruise ships, and yachts with optimized efficiency across varying speed and load profiles. Controllable-pitch propellers command the largest revenue share due to operational flexibility in multi-route ferry fleets. Composite materials represent the fastest-growing segment as shipyards seek weight reduction for high-speed passenger craft. Fixed-blade designs dominate the aftermarket replacement cycle for smaller harbor ferries where capital constraints limit upgrade investments.
IMO sulfur cap regulations and EEDI Phase 3 standards compel propeller manufacturers to redesign blade geometries for lower cavitation and higher efficiency at reduced engine loads. Classification societies including Lloyd's Register, DNV, and ClassNK enforce material certification and fatigue testing protocols that filter out uncertified suppliers. Stakeholders must monitor the pace of ammonia and methanol engine adoption, as these fuels will require propeller torque and cavitation characteristics distinct from conventional diesel-electric configurations.
Market Dynamics
IMO emission reduction mandates are forcing ferry operators to retire inefficient fixed-pitch systems and adopt controllable-pitch propellers with optimized blade geometries for reduced fuel consumption across variable route profiles.
Growth Catalysts
- EEDI Phase 3 standards:The International Maritime Organization's Energy Efficiency Design Index compels newbuild passenger vessels to demonstrate measurable propulsion efficiency gains, accelerating replacement demand for high-performance propeller designs.
- Copper-nickel alloy advances:Enhanced cavitation resistance in nickel-aluminum-bronze formulations extends operational lifespans for high-speed ferry propellers operating in abrasive coastal waters.
- Japan's coastal ferry modernization:Domestic route consolidation and aging fleet replacement programs concentrate procurement volume for advanced controllable-pitch systems in East Asian shipyards.
Market Restraints
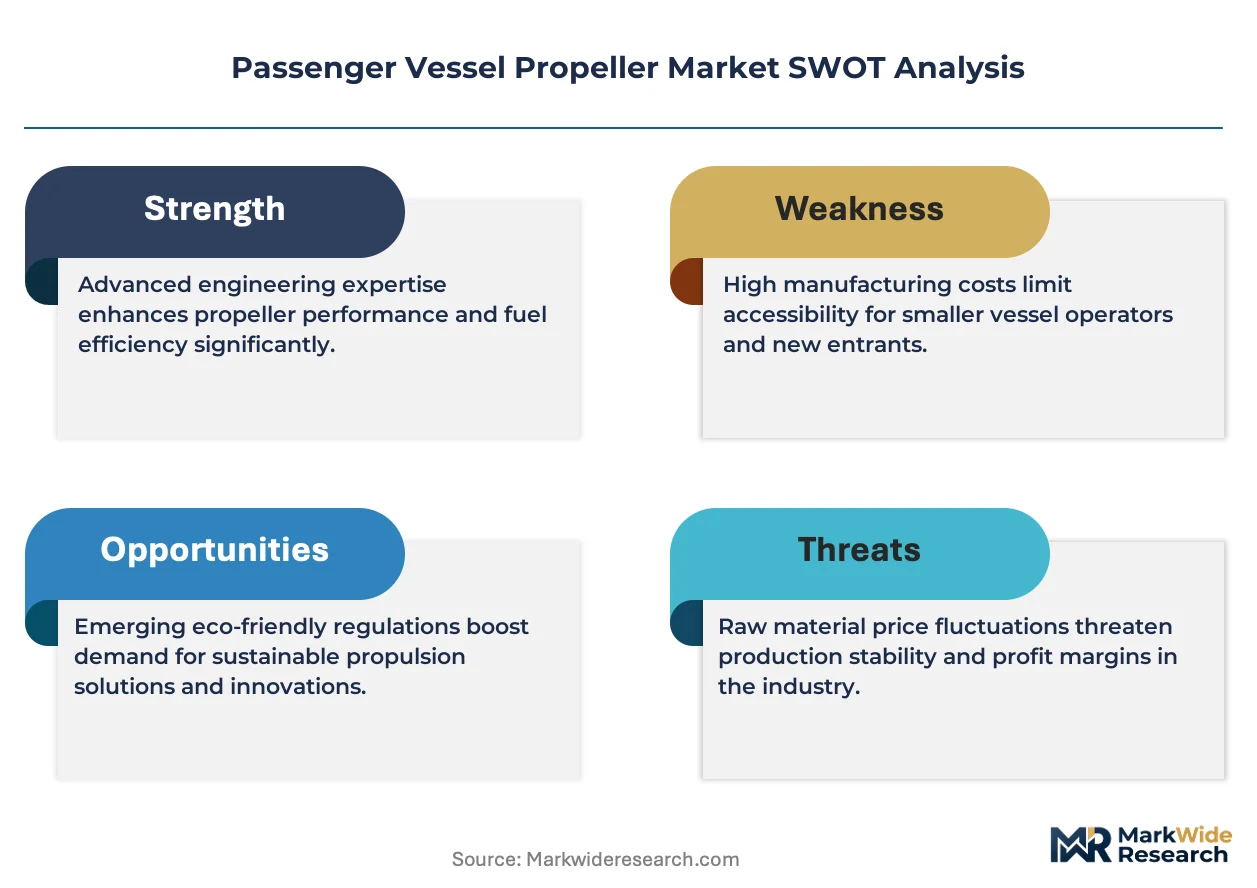
- Foundry capacity concentration:Premium nickel-aluminum-bronze casting capabilities cluster in German and Japanese specialized facilities, creating supply bottlenecks for complex blade geometries.
- Classification society certification timelines:Lloyd's Register and DNV material qualification protocols extend product validation cycles to 18-24 months for new alloy formulations.
- Computational fluid dynamics talent scarcity:Marine hydrodynamics expertise migrates toward aerospace and automotive sectors, constraining in-house design capabilities at traditional propeller manufacturers.
Strategic Opportunities
- Ammonia engine compatibility:Torque characteristics and cavitation profiles for ammonia-fueled propulsion systems require entirely new propeller design paradigms, opening white space for first-mover engineering firms.
- South Korean shipbuilder vertical integration:Hyundai Heavy Industries and Samsung Heavy Industries are consolidating supplier bases, creating captive procurement channels for qualified propeller specialists.
- Composite blade retrofit kits:Carbon fiber reinforced polymer propeller blades offer 40-60% weight reduction for high-speed passenger craft, penetrating the premium yacht and fast ferry segments.
Industry Challenges
- Additive manufacturing qualification gaps:Laser powder bed fusion for propeller repair lacks unified ISO certification standards, blocking adoption for critical maritime applications.
- Legacy shaftline integration complexity:Azimuth thruster retrofits require structural hull modifications and powertrain reconfiguration, extending drydock periods and disrupting fleet availability.
- Cross-border material traceability:EU Conflict Minerals Regulation and US Jones Act compliance impose divergent documentation requirements on copper alloy supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passenger Vessel Propeller Market |
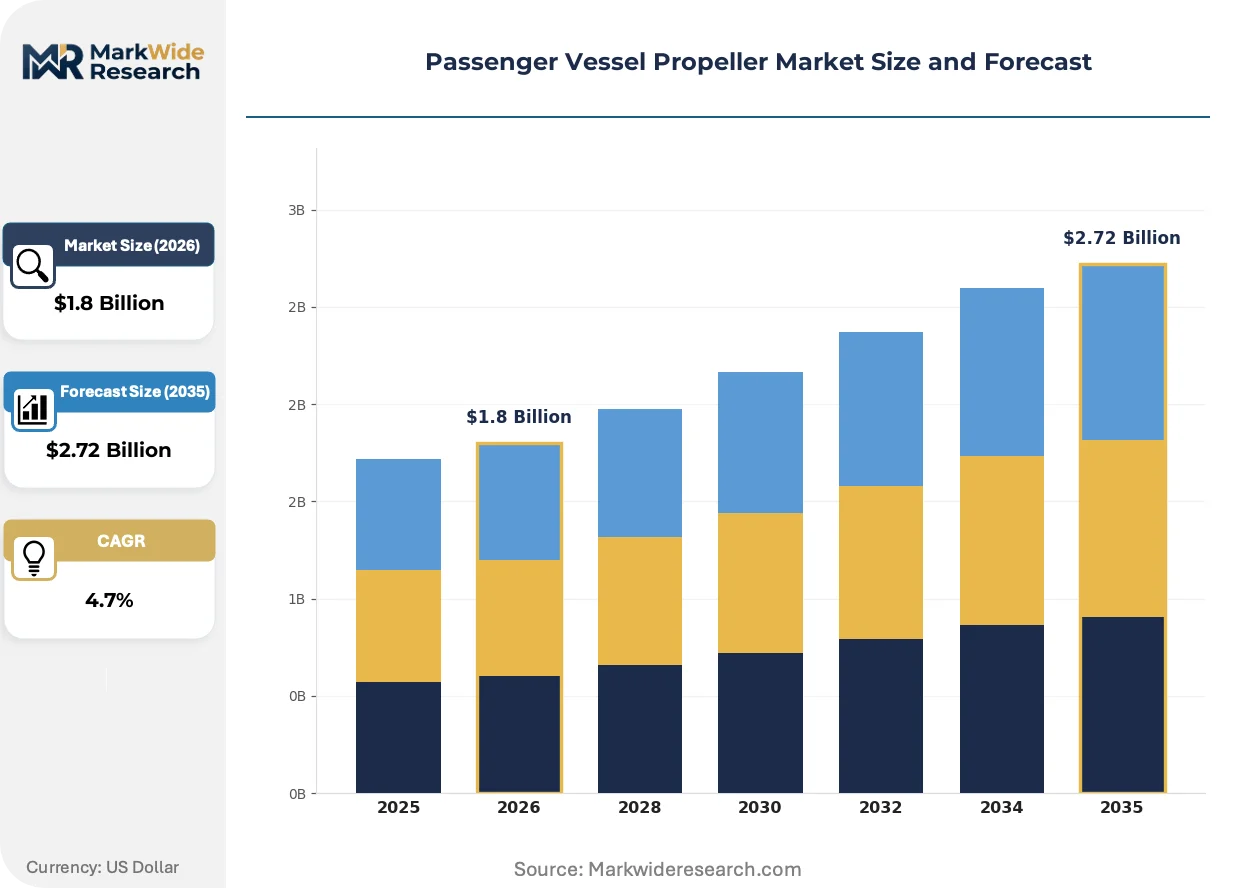
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Fixed Blade, Variable Pitch, Controllable Pitch, Ducted Material: Stainless Steel, Bronze, Aluminum, Composite Application: Ferries, Cruise Ships, Yachts, Cargo Vessels Power Rating: Below 1000 HP, 1000-5000 HP, 5000-10000 HP, Above 10000 HP |
| Companies Covered | Hyundai Heavy Industries, Nakashima Propeller Co., Ltd., Wartsila, VEEM Marine, Rolls-Royce, MAN Energy Solutions SE, Schottel Group, Kawasaki Heavy Industries Ltd., Mecklenburger Metallguss GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passenger Vessel Propeller Market Evolving Landscape
Computational fluid dynamics and additive manufacturing are converging to compress propeller design cycles and enable topology-optimized blade geometries previously unmanufacturable through conventional casting methods.
Topology-optimized propeller blades generated through generative design algorithms distribute material precisely where hydrodynamic loads concentrate, eliminating excess mass from low-stress regions. High-speed ferry operators in the Mediterranean and Baltic corridors are piloting these designs for 8-12% efficiency gains at cruise speeds. Conventional sand-cast blade production is supplanting manual pattern-making with automated digital workflows that reduce iteration cycles from months to weeks.
EU Green Deal maritime provisions and the FuelEU Maritime regulation establish binding greenhouse gas intensity limits for passenger vessels calling at European ports from 2025. Shipowners must document well-to-wake emissions profiles, creating compliance pressure that favors propeller upgrades over engine replacements for near-term fleet compliance. Ferry operators in Denmark, Norway, and the Netherlands are prioritizing propeller efficiency investments to hedge against carbon levy exposure.
Long-term service agreements are displacing transactional spare-part procurement as shipowners seek to transfer operational risk to propulsion system suppliers. Classification society-approved condition monitoring systems enable predictive maintenance scheduling based on actual blade wear rather than calendar-based replacement. German and Japanese ferry operators are consolidating vendor relationships under decade-long performance contracts that bundle propeller supply, installation, and lifecycle maintenance.
Passenger Vessel Propeller Market Segmentation
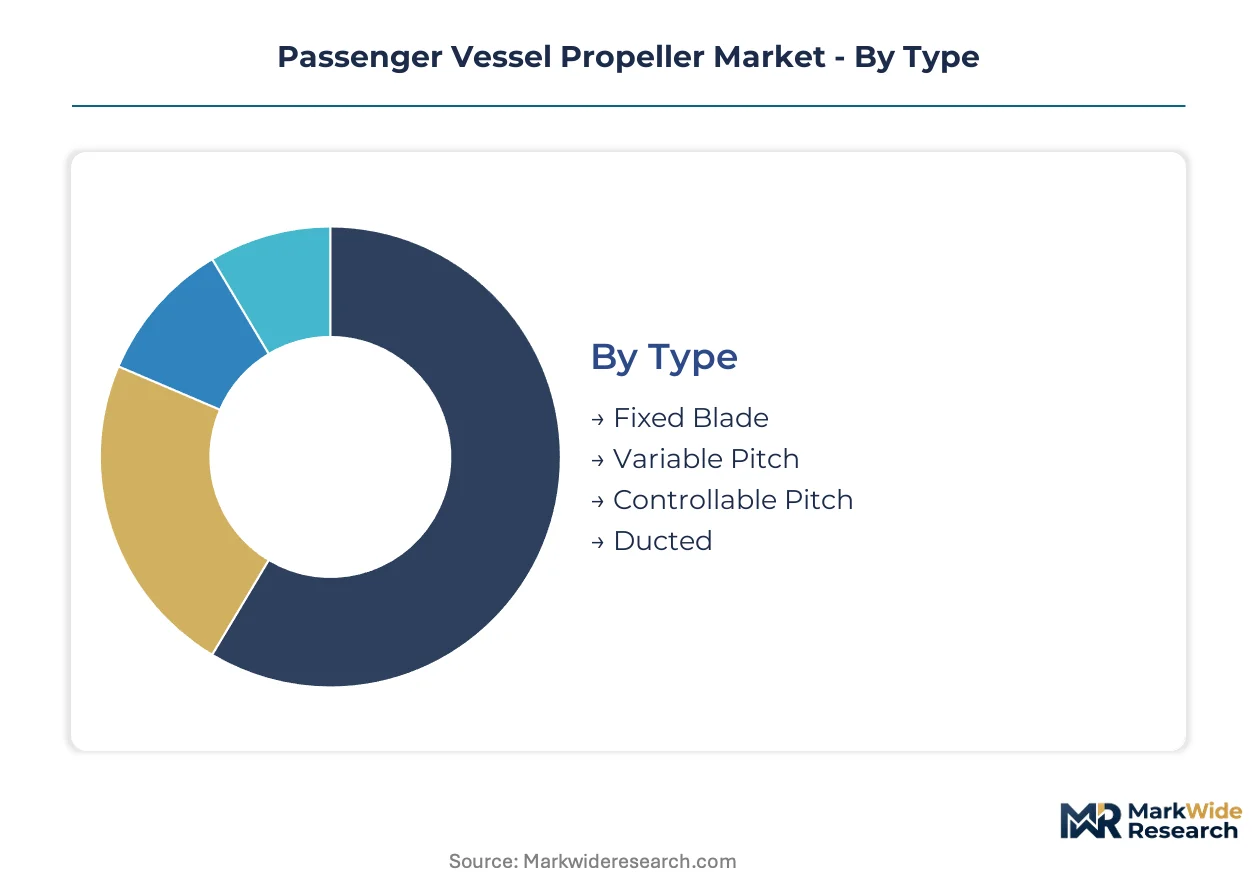
Propeller segmentation in passenger vessels reflects divergent regulatory pressures across route types and vessel classes. IMO EEDI Phase 3 compliance timelines and FuelEU Maritime greenhouse gas intensity limits create tiered procurement patterns that favor specific technical configurations over others.
Type:
Classification societies enforce distinct certification protocols for each propeller architecture, with Lloyd's Register and DNV applying stricter cavitation testing standards to controllable-pitch systems operating in variable-load conditions.
- Fixed Blade:Sand-cast nickel-aluminum-bronze construction with immutable pitch geometry optimized for single-route ferry operations. Harbor ferry operators in Japan and Germany specify these designs where capital constraints override efficiency gains, accepting higher fuel consumption for lower acquisition cost.
- Controllable Pitch:Hydromechanical hub mechanisms enabling real-time blade angle adjustment across 0-90 degrees for multi-route operational profiles. Mediterranean and Baltic ferry fleets concentrate procurement here to satisfy EEDI efficiency mandates without engine replacement.
- Variable Pitch:Self-adjusting blade geometry responding to hydrodynamic load changes without external control input. Coastal cruise operators in Norway pilot these systems for automated optimization in tidal current corridors.
- Ducted:Accelerating nozzle shrouds surrounding the propeller disc to enhance thrust coefficient at low advance ratios. Ice-class ferries in Finland and Sweden specify ducted configurations for improved bollard pull in constrained waterways.
Controllable-pitch systems handle the majority of throughput; composite-integrated ducted designs are gaining share fastest in premium ice-class specifications.
Material:
Material selection traces directly to foundry certification status under ClassNK and Lloyd's Register protocols, with nickel-aluminum-bronze casting facilities in Japan and Germany commanding premium positioning.
- Bronze:Nickel-aluminum-bronze alloys with 9-11% aluminum content deliver superior cavitation erosion resistance in abrasive coastal waters. Japanese shipyards specify domestic castings from certified suppliers for coastal ferry newbuilds under METI modernization programs.
- Composite:Carbon fiber reinforced polymer matrices achieving 40-60% mass reduction versus metallic equivalents. High-speed ferry operators in Greece and Italy adopt these for reduced shaft bearing loads and improved acceleration profiles.
- Stainless Steel:Martensitic and duplex grades for smaller harbor craft where corrosion resistance outweighs acoustic performance requirements.
- Aluminum:Cast aluminum alloys limited to recreational yacht applications below 500 HP where weight minimization dominates over durability metrics.
Bronze commands the installed base; composite formulations are expanding most quickly in speed-sensitive segments.
Application:
Vessel type determines drydock accessibility and thus replacement cycle economics, with cruise ships facing the highest opportunity costs from propulsion downtime.
- Ferries:High-frequency route operations with 15-25 year replacement cycles driven by IMO emission compliance deadlines rather than mechanical failure. Coastal consolidation programs in Japan and Denmark concentrate procurement volume.
- Cruise Ships:Multi-engine redundant configurations requiring synchronized propeller performance across shaftlines. Caribbean and Mediterranean operators prioritize cavitation reduction for passenger comfort metrics.
- Yachts:Custom specifications emphasizing acoustic signature suppression over hydrodynamic efficiency.
- Cargo Vessels:Secondary passenger accommodation configurations with propeller requirements subordinate to cargo handling priorities.
Ferries absorb the dominant procurement volume; cruise ship retrofits show the steepest expansion trajectory amid EEDI enforcement.
Power Rating:
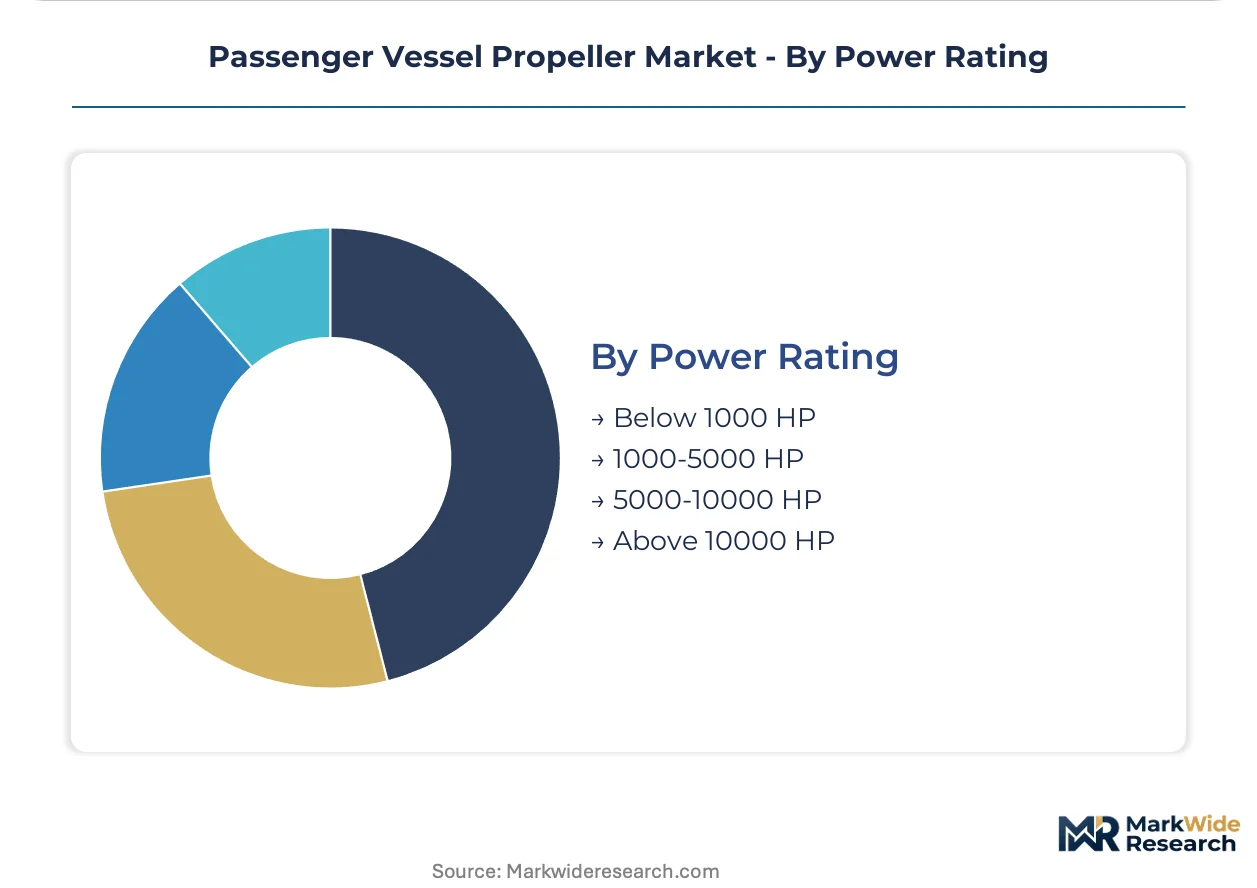
Torque transmission requirements scale non-linearly with power class, with 5000-10000 HP systems requiring integrated shaftline dynamics analysis beyond standalone propeller specification.
- 1000-5000 HP:Coastal and short-sea ferry propulsion with controllable-pitch hubs dominating for route flexibility. Operators in the Netherlands and Norway specify these systems for North Sea corridor services.
- Above 10000 HP:Large cruise ship and fast ferry applications requiring twin-screw configurations with synchronized pitch control. German and Italian shipyards concentrate procurement for Mediterranean and Baltic cruise newbuilds.
- Below 1000 HP:Harbor craft and water taxi applications with fixed-blade economics prevailing.
- 5000-10000 HP:Mid-size RoPax ferries with hybrid-electric integration requirements complicating propeller torque matching.
1000-5000 HP systems carry the largest order backlog; above-10000 HP configurations are climbing fastest on newbuild contract value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and German foundries where nickel-aluminum-bronze certification scarcity commands 15-25% premiums over South Korean and Chinese equivalents. This asymmetry shapes procurement patterns across coastal ferry modernization programs worldwide.
Japan
Domestic ferry fleet renewal under METI coastal corridor consolidation drives controllable-pitch system demand. The country's shipbuilding regulator enforces ClassNK material certification that filters out non-domestic suppliers. Tokyo-Osaka shipyard clusters anchor premium casting capacity for nickel-aluminum-bronze formulations.
Germany
Baltic Sea ferry operators retrofit fixed-pitch systems to meet EU Green Deal maritime emission deadlines. Lloyd's Register protocols extend validation cycles for new alloy formulations. Hamburg-Rostock industrial corridors concentrate azimuth thruster integration expertise for ice-class specifications.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries consolidate captive supplier bases for cruise ship newbuilds. The national shipbuilding regulator mandates EEDI Phase 3 compliance documentation for export vessels. Busan-Ulsan manufacturing clusters integrate propeller supply into vertically controlled production chains.
United States
Jones Act compliance requirements protect domestic foundry capacity for harbor ferry replacements. EPA vessel emission standards pressure operators toward efficiency-optimized blade geometries. Pacific Northwest shipyards pilot composite blade retrofits for high-speed passenger craft.
Italy
Mediterranean cruise operators prioritize cavitation reduction for passenger comfort metrics under FuelEU Maritime regulations. DNV-GL certification timelines govern procurement scheduling for Genoa-Trieste shipyard clusters. Composite material adoption accelerates in premium yacht specifications.
Passenger Vessel Propeller Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. Premium-tier specialists concentrate in German and Japanese foundries where certification scarcity erects barriers. Scale-driven integrators in South Korea leverage shipbuilder relationships for captive procurement channels. Two dominant competitive moves define current positioning: backward integration into nickel-aluminum-bronze casting capacity and strategic partnerships with ammonia engine developers for next-generation torque specifications.
Among Japanese specialists, Nakashima Propeller Co., Ltd. exemplifies the premium-tier archetype through certified foundry integration. Wartsila anchors technology leadership in controllable-pitch systems from its Helsinki-based operations. Schottel Group occupies a position bridging conventional shaftline and azimuth thruster segments. These three represent distinct strategic postures—certified materials dominance, hydromechanical system innovation, and thruster integration breadth—rather than overlapping competitive territory.
| Leading Market Players |
|---|
| Hyundai Heavy Industries |
| Nakashima Propeller Co., Ltd. |
| Wartsila |
| VEEM Marine |
| Rolls-Royce |
| MAN Energy Solutions SE |
| Schottel Group |
| Kawasaki Heavy Industries Ltd. |
| Mecklenburger Metallguss GmbH |
| Others |
Value Network & Pricing Analysis
Foundry utilization rates above 85% at certified nickel-aluminum-bronze facilities in Japan and Germany compress supply elasticity and sustain price floors for complex blade geometries. This capacity tightness propagates through procurement cycles, forcing shipyards to accept longer lead times or premium tier positioning.
Pricing Analysis
Configured-to-order propeller systems command 35-50% premiums over standardized fixed-blade equivalents due to hydromechanical hub complexity and custom blade profiling. Pricing stratifies across premium, standard, and economy tiers based on ClassNK certification grade and foundry location. Cost compression in economy-tier harbor ferry specifications is intensifying because South Korean shipbuilders leverage captive procurement channels. Coastal ferry operators in Japan and Germany exhibit highest price sensitivity, while Mediterranean cruise lines prioritize acoustic performance over unit cost.
Supply Chain Analysis
Strait of Malacca transit congestion exposes raw material flows to scheduling volatility, with copper concentrate shipments from Chile and Peru facing documented delays. Nickel-aluminum-bronze casting capacity concentrates in Japan, Germany, and South Korea, drawing from copper concentrate, aluminum ingot, and nickel cathode feedstocks. Single-source vulnerability at Lloyd's Register-certified foundries creates qualification bottlenecks for new alloy formulations. Distribution runs through shipbuilder-integrated procurement channels rather than independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ammonia engine adoption represents a technological inflection that will obsolete existing torque-matched propeller designs, compressing the window for incumbent repositioning.
For Market Incumbents: Secure backward integration into nickel-aluminum-bronze casting capacity to defend margin position against South Korean shipbuilder consolidation. Lock in decade-long service agreements with Japanese and German ferry operators to transfer operational risk and create switching costs. Prioritize CFD talent retention as marine hydrodynamics expertise migrates toward aerospace sectors. For New Entrants and Emerging Players: Differentiate on ammonia-compatible propeller design capabilities ahead of engine certification timelines. Target composite blade retrofit kits for high-speed Mediterranean ferry operators seeking weight reduction without hull modification. Pursue direct engineering partnerships with classification societies to compress certification cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors certified foundry assets with Lloyd's Register and ClassNK material qualification over pure design houses. Long-term viability hinges on torque specification capabilities for alternative fuels. Acquisition focus should center on German and Japanese specialists with in-house casting and ammonia engine developer relationships. Monitor Lloyd's Register protocol amendments for alternative fuel propulsion as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel-Aluminum-Bronze Casting | Captive supply of certified alloys insulates margin from foundry capacity bottlenecks at Lloyd's Register-approved facilities. |
| Ammonia Engine Compatibility Program | First-mover torque specification capabilities open procurement channels with Hyundai Heavy Industries and Wärtsilä. |
| Long-Term Service Agreement Expansion | Performance-based contracts with Danish and Norwegian ferry operators transfer operational risk and create recurring revenue. |
| Composite Blade Manufacturing Scale-Up | Carbon fiber reinforced polymer production addresses weight reduction demand from Greek and Italian high-speed ferry operators. |
| Classification Society Partnership | Direct DNV and ClassNK collaboration accelerates validation cycles for topology-optimized additive manufacturing repairs. |
Research Methodology
Initial hypotheses were tested against primary input from marine propulsion engineers, ferry fleet procurement directors, shipyard technical managers, and classification society surveyors and refined through secondary validation. Primary fieldwork encompassed structured interviews across Japanese coastal ferry operators, German Baltic shipyards, and South Korean cruise newbuild programs. Secondary sources included Lloyd's Register certification databases, ClassNK material approval registers, IMO EEDI compliance filings, and customs trade data for copper alloy imports. Bottom-up vessel fleet analysis and top-down shipbuilding output triangulation anchored market sizing.
Variance decomposition across propeller type, material grade, power rating, and application segments structured the analytical framework over the projection horizon. CAGRs were derived from installed base replacement cycles, newbuild contract flows, and efficiency upgrade penetration curves. Forecast inputs incorporated IMO EEDI Phase 3 enforcement timelines, FuelEU Maritime greenhouse gas intensity limits, and ammonia engine development milestones from MAN Energy Solutions and Wärtsilä.
Material uncertainties — ammonia engine certification delays, foundry capacity expansion decisions, and classification society protocol amendments — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and shipowner compliance behavior. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Sailboat Propellers Market
Marine
Boat Cleat Market
Marine
Controllable Pitch Marine Propeller Market
Marine
Furnace Boats Market
Marine
North Sea Offshore Support Vessels Market
Marine
Marine Glass Market
Marine
Electric Outboard Engines Market
Marine
Freighter Conversions Market
Marine
Japan Marine Composites Market
Marine
Boat Trolling Motor Market
Marine
Marine Winch Motors Market
Marine
Pneumatic Marine Fender Market
Marine
Global Submarine Market
Marine
Marine Lighting Market
Marine
Jack-Up Vessels Market
Marine
Fishing Vessel Market