
 Global Maritime Information Market | 2026-2036
Global Maritime Information Market Size, Share, and Industry Trends Forecast 2026-2036
Global Maritime Information Market Foresight
Platform licensing revenue is tilting away from perpetual software sales toward subscription-based maritime data services. Windward Limited leverages predictive risk analytics to differentiate its vessel screening platforms for financial institutions and insurers. SAAB Group anchors its position through integrated naval and commercial maritime surveillance systems spanning radar and satellite communications. Thales Group specializes in encrypted SATCOM terminals that sustain premium positioning among defense and coast guard end users.
Maritime information encompasses the collection, processing, and distribution of vessel position data, meteorological conditions, cargo manifests, and regulatory compliance records through satellite communications, automatic identification systems, and cloud-based analytics platforms. These systems integrate AIS transponder signals, synthetic aperture radar imagery, and IoT sensor feeds to deliver real-time situational awareness for safe navigation and supply chain optimization. Vessel Tracking and Navigation Data command established revenue pools given mandatory IMO carriage requirements, while Cloud Platforms and Blockchain Solutions represent the fastest-expanding technology layers as operators seek interoperable data exchange across port ecosystems. Fleet Optimization applications lead adoption among shipping companies pursuing fuel efficiency, whereas Security Surveillance and Risk Assessment segments attract higher margins from insurance firms and government agencies managing territorial waters.
The International Maritime Organization shapes product standards through SOLAS Chapter V carriage requirements for AIS and GMDSS equipment, while the EU Green Deal and its FuelEU Maritime initiative force operators to submit verified emissions data through certified reporting platforms. The US Coast Guard enforces NAIS interoperability standards that dictate receiver specifications for domestic vessel traffic systems. Stakeholders must monitor how emerging cybersecurity mandates from flag state regulators reshape data encryption and access control requirements across multi-vendor maritime networks.
Market Dynamics
The International Maritime Organization's SOLAS Chapter V amendments have triggered a forced replacement cycle across commercial fleets, compelling operators to discard legacy AIS transponders and GMDSS equipment before regulatory deadlines.
Growth Catalysts
- FuelEU Maritime compliance deadlines:European Union regulations mandate verified emissions reporting through certified platforms, forcing shipping operators to procure integrated monitoring systems that combine fuel consumption sensors with satellite uplinks.
- Singapore's vessel traffic density:The Maritime and Port Authority operates the world's most concentrated AIS receiver network, creating sustained procurement demand for real-time berth scheduling optimization tools among terminal operators.
- Synthetic aperture radar integration:SAR imagery providers are fusing satellite-based vessel detection with AIS signals to deliver all-weather tracking capabilities for coast guard surveillance applications.
Market Restraints
- Encrypted SATCOM terminal cost structures:Defense-grade Thales Group hardware commands premium pricing that excludes smaller coastal nations from upgrading legacy VHF-based coastal monitoring networks.
- Flag state cybersecurity fragmentation:Divergent national data encryption mandates from Panama, Liberia, and Marshall Islands registries create compliance complexity for fleet-wide system standardization.
- Terrestrial AIS range limitations:Coastal receiver networks fail to capture vessel positions beyond 40 nautical miles, creating persistent coverage gaps that satellite constellations have not fully closed at viable price points.
Strategic Opportunities
- Blockchain-enabled cargo manifest exchange:Port authorities in Rotterdam and Antwerp are piloting distributed ledger platforms that eliminate document reconciliation delays between customs, shippers, and terminal operators.
- Predictive risk analytics for marine insurers:Windward Limited's behavioral screening models identify vessel anomalies before port state control inspections, enabling premium differentiation based on operational risk scores.
- IoT sensor convergence with cloud platforms:Reefer container operators are integrating temperature, humidity, and location feeds into unified dashboards that optimize cold chain handoffs between maritime and land-based logistics providers.
Industry Challenges
- Satellite communications engineer scarcity:Specialized talent capable of integrating L-band, Ku-band, and emerging LEO constellations commands compensation premiums that strain mid-tier system integrators.
- Multi-vendor interoperability certification:Coast guard procurement officers face extended validation timelines when combining radar, AIS, and SATCOM subsystems from competing defense contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Maritime Information Market |
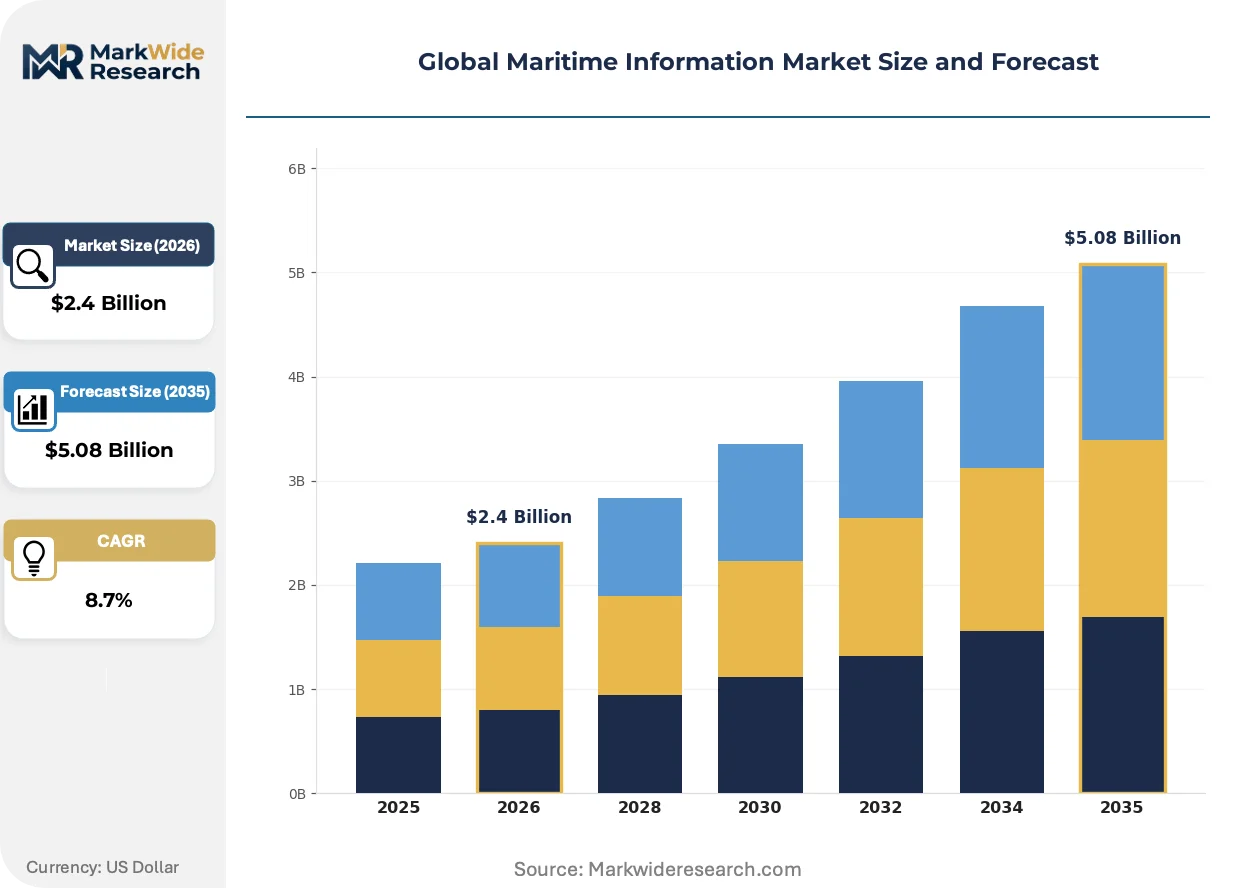
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Navigation Data, Weather Forecasting, Vessel Tracking, Cargo Management, Compliance Monitoring, Port Operations Technology: SATCOM, AIS Systems, Radar Systems, IoT Sensors, Cloud Platforms, Blockchain Solutions Application: Fleet Optimization, Risk Assessment, Route Planning, Regulatory Reporting, Supply Chain Coordination, Security Surveillance End User: Shipping Companies, Shipbuilders, Logistics Providers, Port Authorities, Insurance Firms, Maritime Research Centers |
| Companies Covered | Windward Limited, SAAB Group, Thales Group, ORBCOMM Inc., Spire Global, Inmarsat Global Limited, Iridium Communications Inc., exactEarth, L3Harris Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Maritime Information Market Shifts & Advancements
Maritime information systems are undergoing a platform architecture transformation. Cloud-native deployment models and API-first data exchange protocols are compressing vendor lock-in durations while expanding buyer switching options.
LEO satellite constellations from Starlink and OneWeb are rendering obsolete geostationary SATCOM terminals for commercial fleet broadband. Container ship operators are retrofitting vessels with flat-panel phased array antennas that deliver 20x bandwidth improvements at 60% lower latency. This technology is compressing the replacement cycle for legacy Inmarsat FleetBroadband installations from ten years to four.
The European Union's CSRD disclosure requirements now extend to maritime transport operators above 500 gross tonnage. Verified emissions reporting through certified third-party platforms has become mandatory for EU port calls. Mediterranean short-sea shipping segments are responding fastest, with Greek and Italian ferry operators consolidating fuel monitoring systems ahead of 2026 enforcement.
Charterers are unbundling vessel screening from fixed-term contracts. Commodity traders and cargo owners now subscribe to standalone risk intelligence platforms rather than relying on shipbroker-provided vessel histories. This pattern is most visible in Singapore and London trading desks, where real-time sanctions screening has displaced quarterly compliance reviews.
Global Maritime Information Market Segmentation
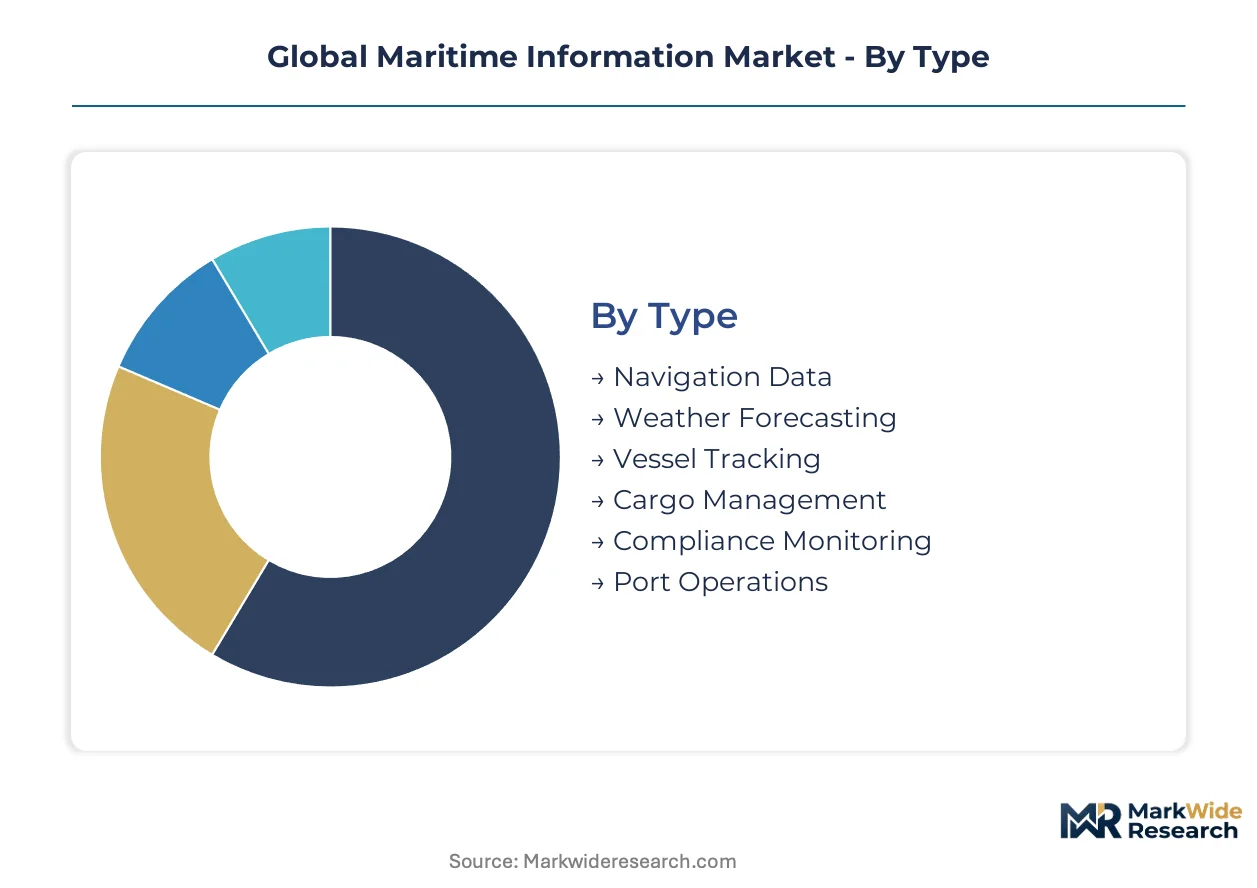
Maritime information systems fragment across multiple technical and commercial dimensions. Procurement patterns diverge sharply between defense-grade encrypted terminals and commercial cloud subscriptions. Understanding these segment boundaries clarifies where pricing power concentrates and where commoditization threatens margins.
Type:
After-sales service intensity varies dramatically across information types, with real-time systems demanding continuous satellite uplink maintenance and legacy compliance modules requiring only periodic calibration.
- Vessel Tracking:Automatic Identification System transponders broadcast position, speed, and heading via VHF radio and satellite relays. Singapore's Maritime and Port Authority maintains the densest coastal receiver network globally, driving replacement demand as IMO SOLAS Chapter V mandates upgraded carriage requirements.
- Navigation Data:Electronic chart display and information systems integrate bathymetric surveys, notice-to-mariners updates, and dynamic positioning feeds. Norwegian coastal ferry operators and Japanese coastal bulk carriers represent concentrated upgrade demand as ECDIS software mandates tighten.
- Weather Forecasting:Meteorological routing services fuse satellite imagery with ocean current models to optimize fuel consumption.
- Cargo Management:Reefer container monitoring platforms track temperature, humidity, and shock events through integrated IoT sensor arrays.
- Compliance Monitoring:Emissions verification systems aggregate fuel consumption data for EU FuelEU Maritime and IMO Carbon Intensity Indicator reporting.
- Port Operations:Berth scheduling optimization tools synchronize vessel arrival windows with terminal crane availability and customs clearance timelines.
By volume, Navigation Data leads given universal SOLAS carriage requirements. By growth pace, Compliance Monitoring is ahead as emissions verification mandates expand beyond European waters.
Technology:
Cost tier stratification separates defense-procured hardware from commercial software subscriptions, with satellite terminals commanding capital expenditure budgets while cloud analytics flow through operating expenditure approvals.
- Cloud Platforms:API-first architectures enable real-time data fusion across AIS, radar, and IoT feeds without on-premise infrastructure. Mediterranean short-sea operators and Singapore-based commodity traders are consolidating fragmented vessel screening tools into unified SaaS dashboards.
- Blockchain Solutions:Distributed ledger protocols create immutable cargo manifest records shared between shippers, customs authorities, and terminal operators. Rotterdam and Antwerp port authorities pilot document reconciliation systems that eliminate paper-based handoff delays.
- SATCOM:L-band, Ku-band, and emerging LEO constellation terminals sustain vessel connectivity beyond coastal VHF range.
- AIS Systems:Transponder hardware and coastal receiver networks broadcast vessel identity and kinematic data on dedicated maritime frequencies.
- Radar Systems:Synthetic aperture radar satellites detect vessel signatures independent of cooperative transponder emissions.
- IoT Sensors:Container-mounted devices transmit location, environmental, and security status through cellular and satellite backhaul.
By installed base, AIS Systems dominates given regulatory mandates. By expansion trajectory, Cloud Platforms are climbing the fastest as operators abandon perpetual license models.
Application:
Customer type determines solution complexity, with government agencies procuring integrated surveillance suites while commercial fleets prioritize standalone optimization modules.
- Fleet Optimization:Fuel consumption analytics, speed routing algorithms, and engine performance monitoring reduce operating expenditure for container lines and bulk operators. Greek ferry companies are consolidating siloed monitoring systems ahead of Mediterranean emissions enforcement deadlines.
- Security Surveillance:Coast guard agencies fuse AIS, radar, and optical imagery for territorial water monitoring and sanctions enforcement. US Coast Guard NAIS interoperability standards dictate receiver specifications for domestic vessel traffic systems.
- Risk Assessment:Behavioral screening models identify vessel anomalies for marine insurers and commodity traders.
- Route Planning:Dynamic voyage optimization balances fuel cost, schedule reliability, and weather avoidance.
- Regulatory Reporting:Automated data aggregation formats emissions and safety records for flag state and port state control submissions.
- Supply Chain Coordination:Port-to-port visibility platforms synchronize maritime arrival with inland logistics handoffs.
By deployment scale, Fleet Optimization leads among commercial operators. By margin capture, Security Surveillance is gaining share fastest given defense procurement premiums.
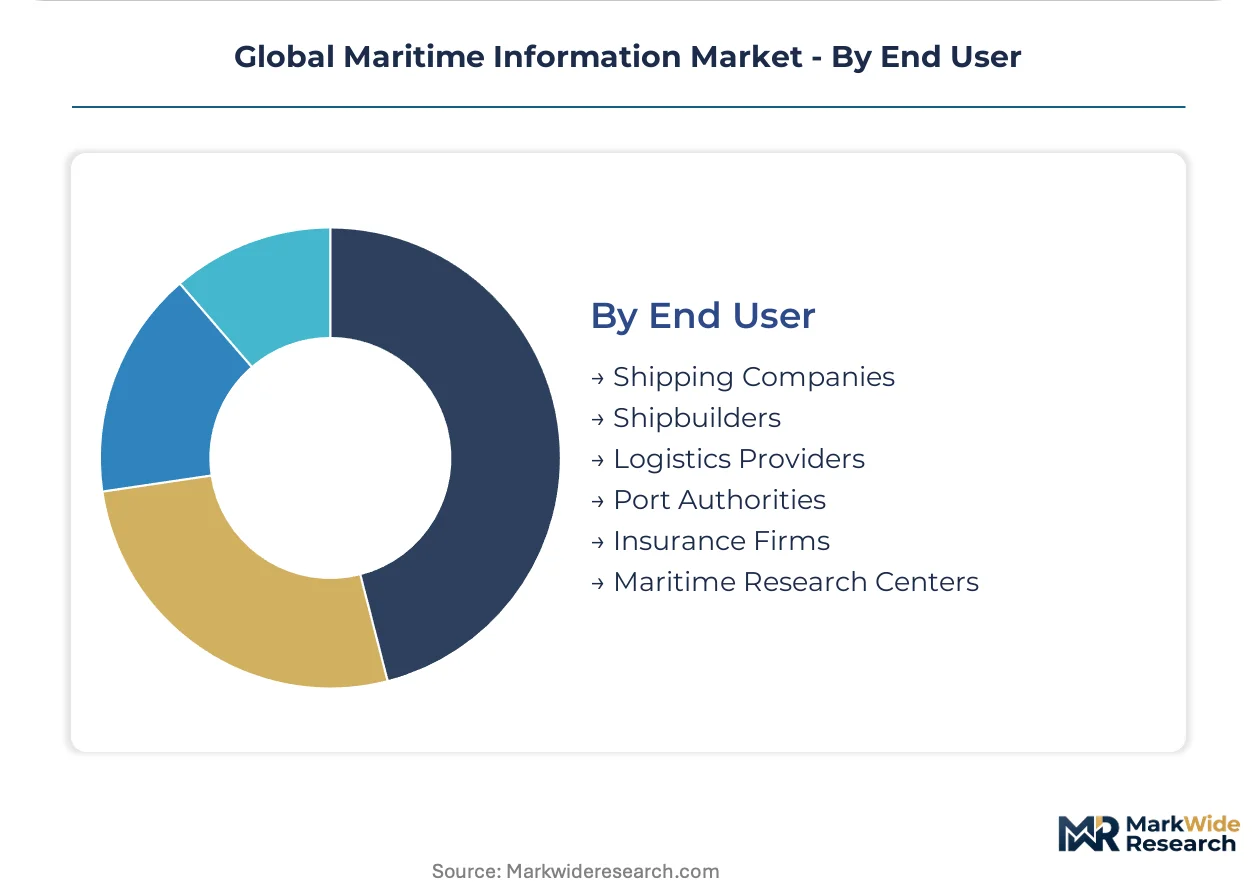
End User:
Volume concentration tilts toward fleet operators, while margin accrues to specialized integrators serving fragmented regulatory compliance demand.
- Shipping Companies:Container lines, tanker operators, and dry bulk carriers procure integrated vessel tracking, navigation, and optimization suites. Japanese and Greek fleet managers are prioritizing FuelEU-compliant monitoring ahead of European port call requirements.
- Port Authorities:Terminal operators and vessel traffic services demand real-time berth scheduling and congestion management tools. Singapore's Maritime and Port Authority sustains procurement velocity through continuous AIS network densification.
- Insurance Firms:Marine underwriters subscribe to standalone risk intelligence platforms for vessel screening and premium differentiation.
- Logistics Providers:Freight forwarders and third-party logistics operators track container status across multimodal chains.
- Shipbuilders:New construction yards integrate information systems during vessel outfitting rather than post-delivery retrofit.
- Maritime Research Centers:Academic and government laboratories access historical vessel movement datasets for pattern analysis and climate impact studies.
By fleet count, Shipping Companies dominate procurement volume. By platform sophistication, Port Authorities are expanding most quickly as smart port investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Singapore and Norway absorb premium pricing for encrypted terminals without volume elasticity, while operators in Greece and India prioritize cost-optimized cloud subscriptions over capital-intensive hardware deployments.
Singapore
The Maritime and Port Authority operates the densest coastal AIS receiver network globally, driving sustained procurement of real-time berth scheduling systems among terminal operators. The Port of Singapore Authority's smart port initiative mandates API-first data exchange protocols across all vessel traffic management vendors. Jurong Port and Tuas Mega Port anchor this demand concentration as container throughput expansion accelerates sensor network densification.
Norway
Coastal ferry operators and offshore supply vessel managers command premium positioning for encrypted SATCOM terminals serving North Sea oil platforms. The Norwegian Maritime Authority enforces stringent cybersecurity mandates for critical infrastructure vessel communications that exceed baseline IMO requirements. Bergen and Stavanger host specialized system integrators serving the offshore energy fleet's all-weather connectivity requirements.
Greece
Mediterranean short-sea shipping operators consolidate fragmented fuel monitoring systems ahead of EU FuelEU Maritime enforcement deadlines. The Hellenic Ministry of Maritime Affairs coordinates emissions verification platform certifications with Brussels regulatory timelines. Piraeus container terminal operators and Aegean ferry companies drive subscription-based compliance software adoption over hardware-heavy alternatives.
United States
The US Coast Guard enforces NAIS interoperability standards that dictate receiver specifications for domestic vessel traffic systems along Atlantic and Gulf coasts. The Maritime Security Program and Jones Act compliance requirements shape procurement patterns for integrated surveillance suites. Houston Ship Channel and Port of Long Beach operators sustain demand for multi-sensor fusion platforms combining radar, AIS, and optical feeds.
Japan
Coastal bulk carriers and automotive export terminals prioritize ECDIS software upgrades as METI tightens electronic chart carriage requirements. The Japan Coast Guard expands satellite-based vessel detection capabilities for territorial water monitoring around disputed maritime zones. Nagoya and Yokohama port clusters anchor system integration demand as shipbuilders outfit new construction with native information system architectures.
Global Maritime Information Market Competitive Landscape
Defense-grade integrators and commercial SaaS providers split the market along capital-expenditure versus operating-expenditure procurement lines. Tier-one defense contractors anchor encrypted terminal segments through coast guard and naval relationships, while venture-backed analytics specialists capture fleet optimization and risk assessment subscriptions. Three archetypes dominate: integrated naval-commercial surveillance houses, standalone maritime risk intelligence platforms, and satellite constellation operators bundling connectivity with value-added data services. Competitive moves concentrate on strategic partnerships between constellation operators and analytics layer vendors, plus geographic expansion through port authority pilot programs.
Within the defense-integrated tier, SAAB Group and Thales Group exemplify positioning that spans radar manufacturing through encrypted SATCOM terminal supply. Windward Limited occupies a distinct archetype as a standalone risk intelligence specialist serving financial and insurance verticals without hardware dependencies. Spire Global represents the satellite-native analytics model, leveraging owned constellation assets to bypass third-party connectivity arrangements. These three anchors illustrate how vendor selection criteria diverge sharply between government procurement officers prioritizing security certification and commercial fleet managers optimizing for API flexibility and subscription economics.
| Leading Market Players |
|---|
| Windward Limited |
| SAAB Group |
| Thales Group |
| ORBCOMM Inc. |
| Spire Global |
| Inmarsat Global Limited |
| Iridium Communications Inc. |
| exactEarth |
| L3Harris Technologies, Inc. |
| Others |
Supply & Pricing Matrix
Singapore's dense AIS receiver network infrastructure anchors global capacity for vessel tracking hardware, with terminal manufacturers clustering around the Maritime and Port Authority's procurement specifications to capture downstream pricing power across Asian port modernization programs.
Pricing Analysis
After-sales service revenue from satellite uplink maintenance and transponder calibration drives lifetime value beyond initial hardware sales. Three-tier pricing structure across defense-grade encrypted terminals, commercial SaaS subscriptions, and economy hardware bundles captures divergent buyer budgets. Price differentiation rests on cybersecurity certification tiers and integration complexity with legacy port systems. Cost compression in commercial cloud analytics is intensifying because LEO constellation operators are bypassing traditional geostationary intermediaries. Smaller coastal nations exhibit highest price sensitivity, while NATO-aligned coast guard agencies absorb premium positioning without volume elasticity.
Supply Chain Analysis
Contract manufacturing for SATCOM terminals concentrates with Thales Group's French production facilities and SAAB Group's Swedish integration centers, with specialized foundry capacity for phased-array antennas limiting second-source options. Component sourcing draws from Taiwan for semiconductor fabrication, South Korea for display modules, and Germany for precision sensor assemblies. Raw material dependencies include rare earth elements for antenna substrates, gallium nitride for RF amplification, and specialized alloys for marine-grade enclosures. Single-source vulnerability in LEO constellation payload manufacturing creates bottleneck exposure. Distribution runs through defense procurement channels for encrypted hardware and API-first platforms for commercial SaaS deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as mandatory FuelEU Maritime compliance deadlines force fleet-wide monitoring system procurement ahead of enforcement windows.
For Market Incumbents: Insulate encrypted terminal margins by deepening certification investment for NATO coast guard interoperability standards, while consolidating API partnerships with emerging LEO operators to neutralize bandwidth cost threats from Starlink and OneWeb. Vertical integration into synthetic aperture radar analytics preserves differentiation against pure-play software entrants. For New Entrants and Emerging Players: Mid-tier Mediterranean ferry operators in Greece and Italy represent the most penetrable entry point, with emissions verification software subscriptions outpacing hardware-heavy alternatives. Southeast Asian port authorities piloting smart port initiatives offer second-wave expansion targets. A channel partnership strategy with classification societies accelerates trust-building without direct sales infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors satellite-native analytics platforms with owned constellation assets over hardware-dependent integrators. Long-term viability hinges on data layer control rather than terminal manufacturing scale. Acquisition targets should demonstrate API-first architecture and established port authority pilot relationships. Watch for inflection when EU FuelEU Maritime enforcement triggers consolidation among fragmented compliance software vendors.| Strategic Initiative | Industry Significance |
|---|---|
| LEO Constellation Partnership | Starlink and OneWeb alliances compress latency for real-time berth scheduling applications. |
| Blockchain Cargo Manifest Pilot | Rotterdam and Antwerp deployments eliminate document reconciliation delays between customs authorities. |
| Predictive Risk Analytics Platform | Windward Limited's behavioral screening models enable marine insurer premium differentiation. |
| IoT Sensor Convergence | Reefer container operators unify temperature and location feeds across cold chain handoffs. |
| Encrypted SATCOM Terminal Upgrade | Thales Group hardware sustains premium positioning among defense and coast guard end users. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet operations directors, port authority procurement officers, maritime cybersecurity consultants, and satellite communications engineers; and secondary validation through IMO SOLAS amendment documentation, EU FuelEU Maritime regulatory filings, US Coast Guard NAIS interoperability standards, customs trade databases, and SEC filings from listed maritime technology vendors. Bottom-up vessel count modeling and top-down market sizing triangulated volume estimates.
Forecast inputs span vessel tracking hardware replacement cycles, SaaS subscription penetration rates, and regulatory compliance deadline clustering across segmentation dimensions including technology layer, application type, and end-user category. CAGRs were derived from installed base growth and average revenue per unit trajectories across the projection horizon. Industry-specific inputs include AIS transponder carriage mandates and LEO constellation coverage expansion timelines.
Macroeconomic conditions sit as an overlay; deviation in freight rate indices, fuel price volatility, or defense budget allocations would shift the trajectory. Forecasts reflect assumptions around regulatory enforcement timing and satellite constellation deployment pace. Quarterly review of port authority capital expenditure announcements and flag state cybersecurity mandate developments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Beacon Market
Marine
Yacht Painting and Maintenance Market
Marine
Submarine Propulsion Systems Market
Marine
Boat Cleat Market
Marine
Marine Transport Refrigeration Unit Market
Marine
Electric Ship Market
Marine
Asia-Pacific Leisure Boat Marine Coating Market
Marine
Mooring Ropes Market
Marine
Marine Pipes Market
Marine
Sailboat Market
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
Japan Marine Composites Market
Marine
Marine Interiors Market
Marine
Marine Turbocharger Market
Marine
Marine Electronics Market
Marine
Marine Fin Stabilizer Market