
 Asia-Pacific Electric Boat Market | 2026-2036
Asia-Pacific Electric Boat Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electric Boat Market Analytics
High-density lithium-ion battery pack integration with hydrofoil hull architectures is rewriting vessel efficiency benchmarks across the Asia-Pacific. Candela Technology AB leverages its computer-stabilized foil system to dominate premium commuter routes in Scandinavian-influenced Australian markets. Torqeedo GmbH sustains deep aftermarket penetration through outboard motor retrofit kits that anchor its position across Southeast Asian charter fleets. Frauscher Bootswerft GmbH & Co KG specializes in aluminum-hulled patrol configurations that compete directly with legacy diesel tenders for government coastal security contracts.
An electric boat converts stored electrical energy into propulsive thrust through battery packs, electric motors, and power management systems, typically achieving zero direct emissions at speeds up to 50 knots depending on hull form and energy density. These vessels serve recreational cruising, commercial passenger transport, and light cargo duty across harbors, inland waterways, and coastal corridors where emission restrictions apply. Battery electric technology leads installed base but hybrid electric configurations capture expanding share among commercial operators requiring extended range without shore charging infrastructure. Small boats concentrate volume in recreational segments across Japan's Seto Inland Sea and South Korea's coastal marinas, while cargo boats represent an emerging margin pool as port authorities in Singapore and Busan pilot shore-powered loading systems.
Japan's METI enforces maritime decarbonization targets that phase out heavy fuel oil in designated coastal zones, while Australia's national maritime regulator imposes increasingly stringent harbor emission controls that elevate electric propulsion from preference to compliance necessity. China's SAMR coordinates GB standards for battery safety and charging interoperability that shape which vessel platforms gain domestic type approval. Stakeholders must weigh battery supply chain concentration against the regulatory trajectory that will determine which technology configurations secure preferential financing and port access across the region's fragmented jurisdictional landscape.
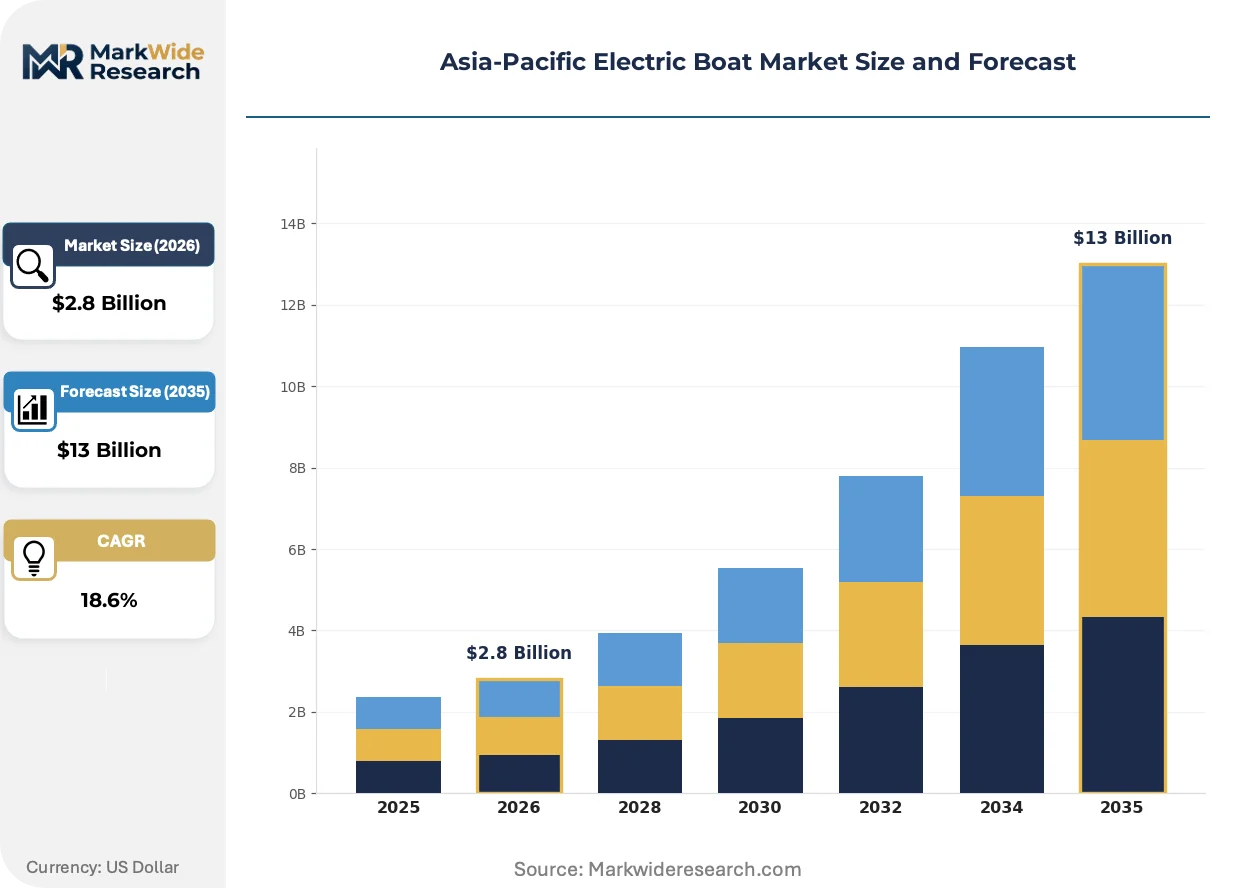
Market Dynamics
High-density lithium-ion battery pack integration with hydrofoil hull architectures is rewriting vessel efficiency benchmarks across the Asia-Pacific, compressing operational cost structures for commercial ferry operators while forcing incumbent diesel-engine suppliers into defensive retrofit strategies.
Growth Catalysts
- Japan's METI maritime decarbonization roadmap:Phase-out mandates for heavy fuel oil in designated coastal zones are converting compliance pressure into procurement acceleration for battery-electric and hybrid-electric platforms.
- Thailand's island-hopping passenger services:Archipelago geography concentrates route distances within optimal electric range, eliminating range anxiety barriers that constrain mainland adoption.
- Hydrofoil hull stabilization systems:Computer-controlled foil architectures reduce drag coefficients by lifting hulls above waterline, extending battery range per kilowatt-hour without energy density breakthroughs.
Market Restraints
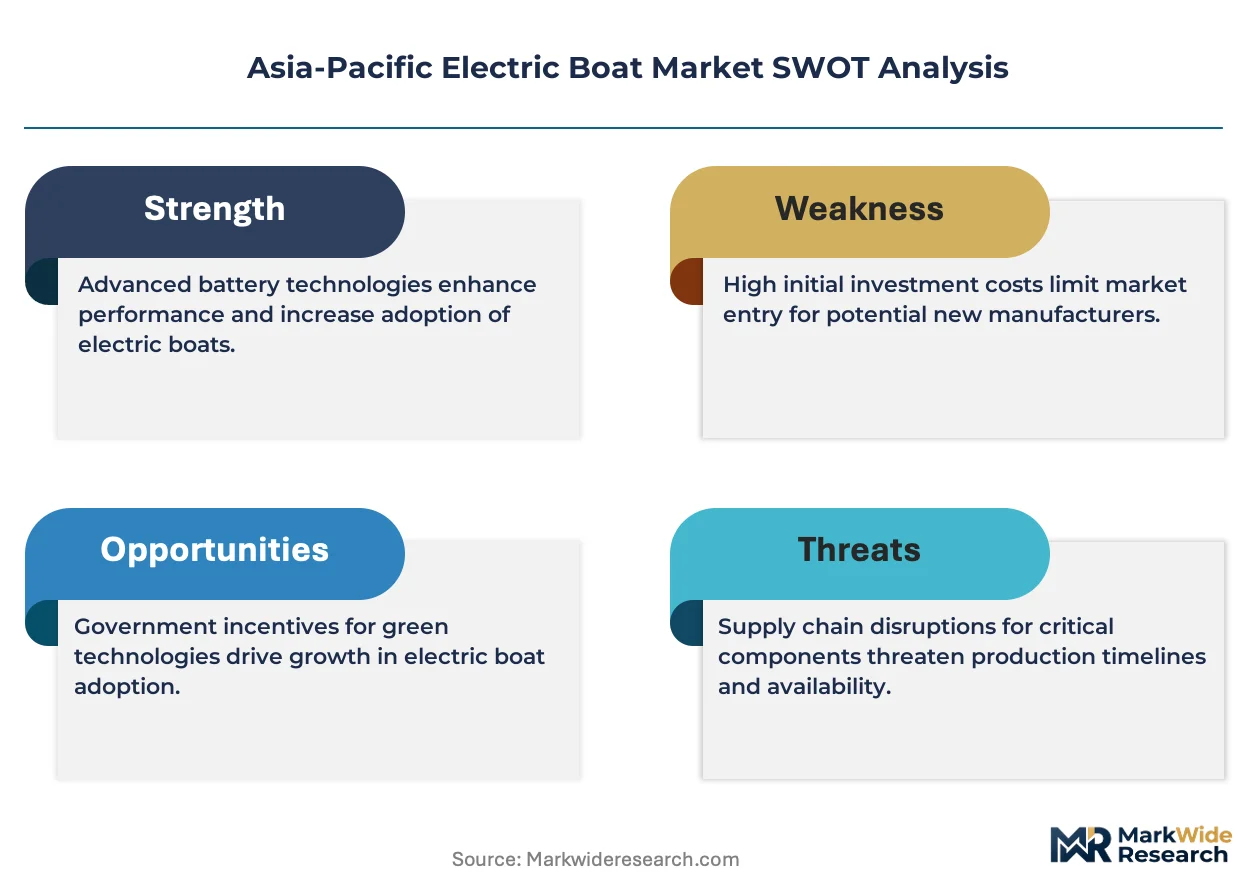
- Lithium-ion cathode supply concentration:Processing capacity for nickel-manganese-cobalt formulations clusters in Chinese industrial zones, exposing vessel builders to single-source geopolitical and logistics risk.
- Shore charging infrastructure gaps:Southeast Asian archipelago ports lack standardized high-voltage DC fast-charging installations, forcing hybrid configurations that retain fossil-fuel range extenders.
- Aluminum hull material cost volatility:Lightweight alloy prices fluctuate with energy-intensive smelting input costs, compressing margin predictability for patrol and security tender manufacturers.
Strategic Opportunities
- Australia's harbor tourism sector:Premium whale-watching and reef-cruise operators command ticket price premiums that absorb battery capital costs, creating margin pools unavailable to commodity ferry services.
- China's dual carbon goals:National emission intensity targets channel state-backed financing toward electric vessel platforms that qualify for green bond issuance and preferential port tariff structures.
- Autonomous docking and collision-avoidance convergence:Integration of lidar positioning with electric propulsion control systems enables single-operator vessels that reduce labor costs for thin-margin cargo routes.
Industry Challenges
- Marine electrical engineering talent scarcity:Vessel yards transitioning from mechanical diesel expertise to high-voltage battery management and thermal runaway mitigation face recruitment bottlenecks in regional labor markets.
- Multi-jurisdiction type approval complexity:China's SAMR battery safety standards, Japan's JIS maritime certifications, and Australia's national maritime regulator harbor emission controls create fragmented compliance timelines that delay platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electric Boat Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Watercraft, Fishing Boats, Yachts, Cargo Boats End User: Recreational Users, Commercial Operators, Government Agencies, Environmental Organizations Technology: Battery Electric, Hybrid Electric, Fuel Cell Electric, Solar Assisted Size: Small Boats, Medium Boats, Large Boats, Superyachts |
| Companies Covered | Candela Technology AB, Duffy Electric Boat Company, Frauscher Bootswerft GmbH & Co KG, Quadrofoil D.O.O, Vision Marine Technologies Inc, Aquawatt Mechatronik und Yachtbau, Torqeedo GmbH, Corvus Energy, Andaman Boatyard, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electric Boat Market Evolving Landscape
Propulsion architecture decisions now precede hull design in Asia-Pacific vessel procurement cycles, reversing traditional naval engineering sequences and elevating battery system vendors to tier-one supplier status alongside legacy engine manufacturers.
Solid-state battery chemistry is hybridizing with conventional lithium-ion pack architectures to extend cycle life in high-salinity marine environments. Japanese coastal operators with intensive daily utilization profiles are piloting ceramic-electrolyte cells that tolerate deeper discharge depths without thermal degradation. This chemistry transition is compressing total-cost-of-ownership parity timelines against diesel reference points.
China's SAMR coordinates GB standards for battery safety and charging interoperability that determine which vessel platforms secure domestic type approval. Manufacturers seeking access to state-financed fleet renewal programs must engineer to these specifications regardless of export market requirements. Coastal cargo operators in the Bohai Rim are responding by consolidating procurement around pre-approved platform configurations that streamline financing.
Charter fleet procurement patterns in South Korea's coastal marinas are migrating from outright vessel purchase toward power-by-the-hour service contracts. Torqeedo GmbH and regional distributors are capturing recurring revenue streams that displace traditional marine engine maintenance networks. This financing-structure rotation is most visible in Jeju Island's recreational boating cluster, where seasonal cash-flow volatility favors operational expenditure models over capital deployment.
Asia-Pacific Electric Boat Market Segmentation
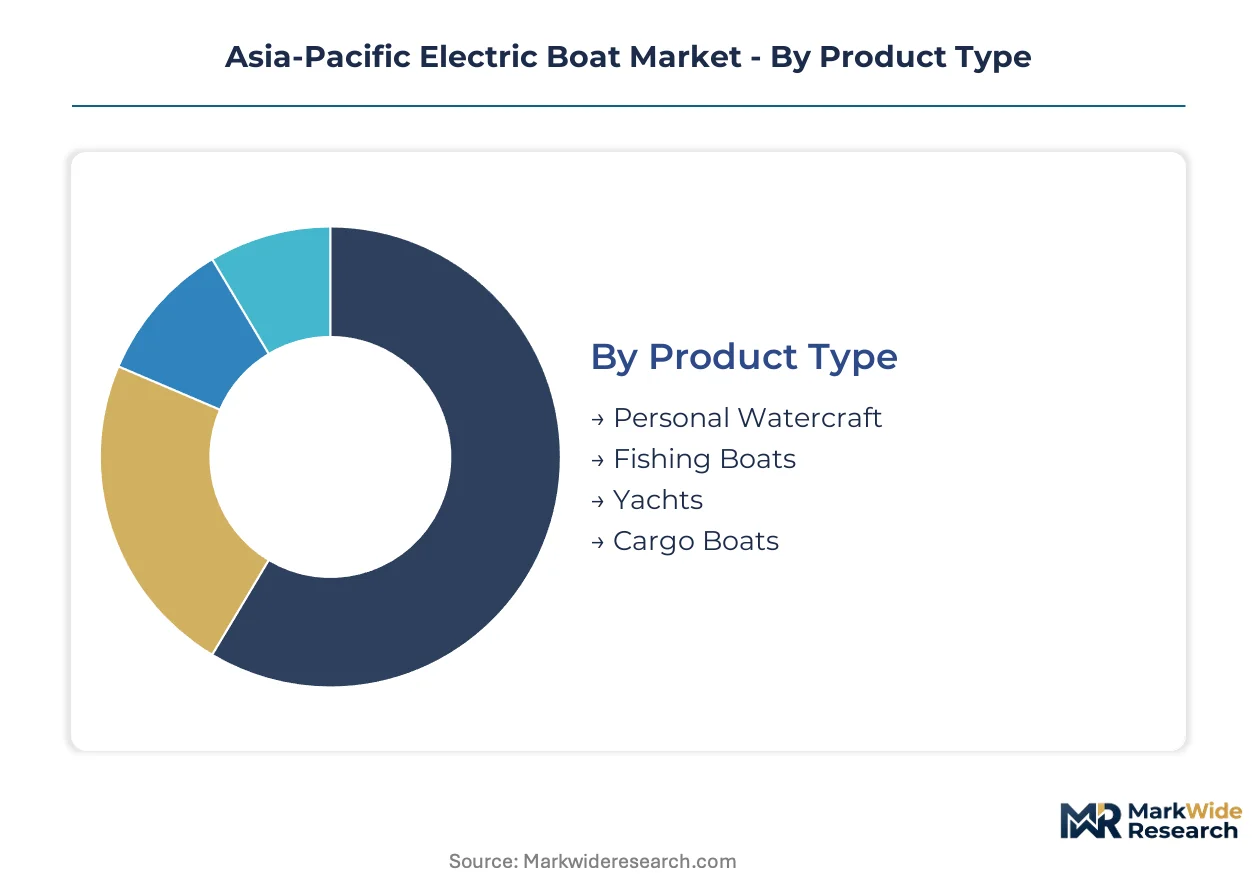
Segmentation in the Asia-Pacific electric boat market reveals how propulsion technology, vessel size, and end-use application create distinct procurement patterns across coastal corridors. Understanding these divides exposes where battery economics work and where hybrid configurations retain advantage.
Product Type:
Application focus determines hull configuration, battery pack sizing, and shore charging compatibility across distinct maritime use cases.
- Personal Watercraft:Compact jet-driven platforms with sub-50 kWh battery packs serve Australia's harbor tourism circuits and Thailand's resort fleets. Operators in Phuket and the Whitsundays absorb premium capital costs through per-passenger ticketing models that amortize hardware across high seasonal utilization.
- Fishing Boats:Aluminum-hulled workboats with 100-200 kWh installations dominate Japan's Seto Inland Sea and South Korea's coastal marinas. South Korean charter cooperatives favor power-by-the-hour service contracts that convert seasonal cash-flow volatility into operational expenditure structures.
- Yachts:Premium fiberglass configurations with integrated solar canopy systems concentrate in Singapore's marina developments and Sydney Harbour.
- Cargo Boats:Flat-deck shallow-draft vessels with shore-powered loading systems pilot in Singapore's Jurong Port and Busan's New Port complexes.
Recreational configurations command the established base. The steepest expansion runs through commercial cargo platforms.
End User:
Customer type shapes financing structure, regulatory compliance burden, and vessel utilization intensity across the value chain.
- Recreational Users:Individual owners and charter guests in Jeju Island's boating cluster and Australia's reef-cruise markets prioritize silent operation and zero harbor emissions. These buyers accept battery replacement cycles of 5-7 years as acceptable trade-offs for regulatory compliance in protected marine zones.
- Commercial Operators:Ferry companies across Indonesia's Bali-Lombok corridor and Vietnam's Ha Long Bay archipelagos require 12-16 hour daily utilization profiles that stress conventional lithium-ion thermal management. Indonesian operators are piloting solid-state ceramic-electrolyte configurations to extend cycle life in high-salinity environments.
- Government Agencies:Patrol and security tender procurement in the Philippines and Malaysia specifies aluminum hulls with rapid-recharge capability for coastal surveillance rotations.
- Environmental Organizations:Research and monitoring vessels in the Great Barrier Reef Marine Park and Komodo National Park operate under strict emission controls that mandate electric propulsion for permit eligibility.
Commercial ferry operators anchor procurement volume. Government fleet renewal programs are climbing the fastest.
Technology:
Propulsion architecture selection precedes hull design in contemporary procurement cycles, reversing traditional naval engineering sequences.
- Battery Electric:High-density lithium-ion packs with nickel-manganese-cobalt cathodes dominate installations under 500 kWh. China's SAMR GB standards for battery safety and charging interoperability determine which platforms secure domestic type approval and state-financed fleet renewal access.
- Hybrid Electric:Diesel-electric range extenders capture expanding share among archipelago operators lacking standardized high-voltage DC fast-charging infrastructure. Thai island-hopping services deploy these configurations to eliminate range anxiety on 40-60 nautical mile legs.
- Fuel Cell Electric:Proton-exchange membrane systems with hydrogen storage pilot in Japan's METI-funded coastal demonstration zones around Osaka Bay.
- Solar Assisted:Photovoltaic canopy integration supplements shore charging for slow-speed harbor cruise operators in Sydney and Auckland.
Battery electric leads installed base. Hybrid configurations are expanding most quickly where charging infrastructure remains fragmented.
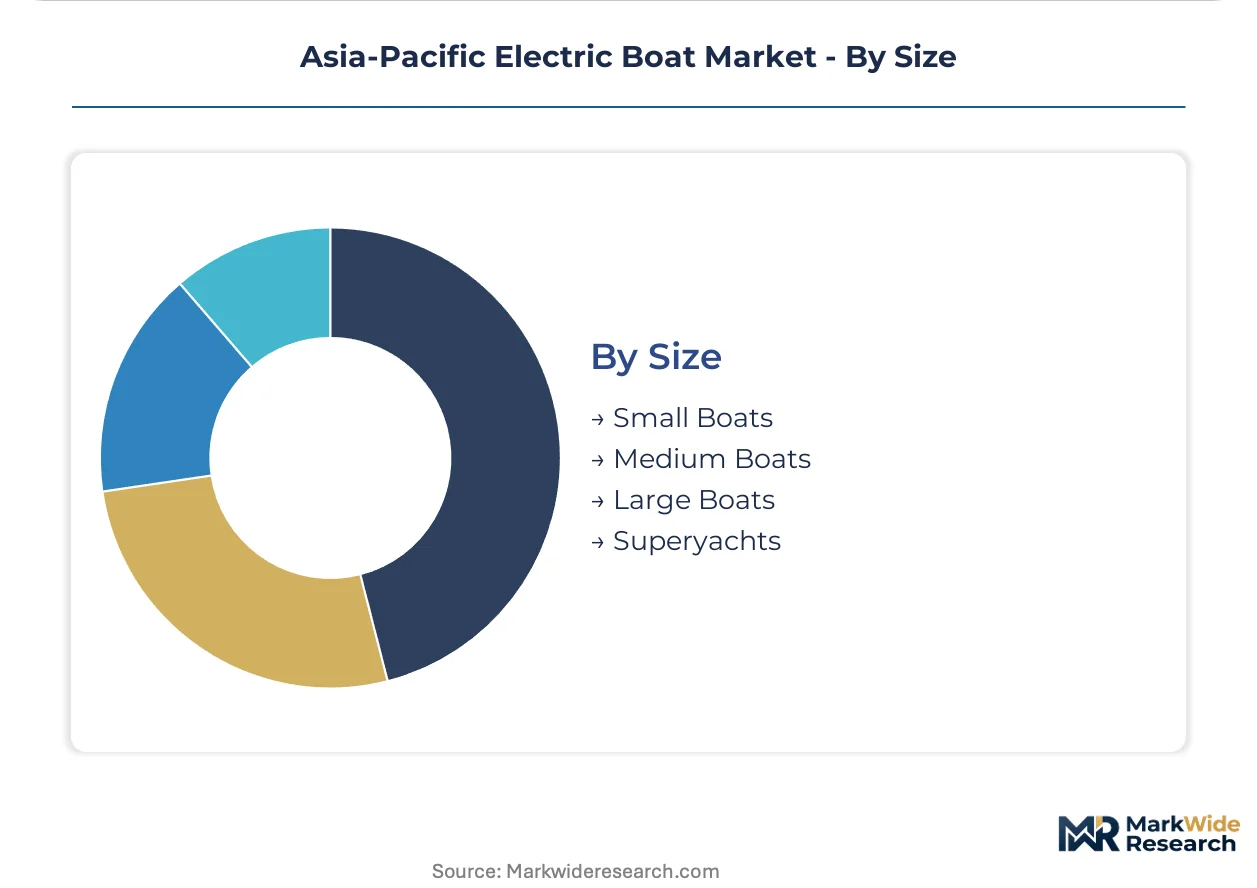
Size:
Vessel displacement dictates energy storage volume, hull material selection, and crew certification requirements across regulatory jurisdictions.
- Small Boats:Sub-8 meter craft with outboard electric motor retrofits concentrate volume in Japan's Seto Inland Sea recreational marinas and South Korea's coastal charter fleets. Torqeedo GmbH's aftermarket penetration anchors this segment through dealer networks that displace traditional marine engine maintenance.
- Medium Boats:8-24 meter ferries and patrol craft with integrated battery-electric systems serve Thailand's Phi Phi Island routes and Australia's harbor commuter corridors. Computer-stabilized hydrofoil architectures from Candela Technology AB reduce drag coefficients by lifting hulls above waterline, extending range per kilowatt-hour.
- Large Boats:24-40 meter passenger ferries with 1-2 MWh battery installations pilot in China's Bohai Rim coastal cargo consolidation programs.
- Superyachts:Custom fiberglass configurations with hybrid diesel-electric systems concentrate in Singapore's marina developments for ultra-high-net-worth owners.
Small boats dominate recreational volume. Medium boats are gaining share fastest in commercial passenger applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese battery pack manufacturers supply Southeast Asian ferry operators through direct procurement contracts, while Australian harbor tourism vessels source integrated electric propulsion systems from European technology licensors. Trade corridors concentrate component flows through Singapore's port logistics hub before final assembly in regional shipyards.
China
Coastal cargo consolidation programs in the Bohai Rim drive demand for 24-40 meter electric vessels with 1-2 MWh installations. SAMR coordinates GB standards for battery safety and charging interoperability that determine type approval eligibility for state-financed fleet renewal. Dalian and Qingdao shipyards dominate domestic production for Bohai Rim operators seeking preferential green bond financing.
Japan
Daily utilization profiles exceeding 12-16 hours stress conventional lithium-ion thermal management in Seto Inland Sea fishing cooperatives. METI enforces maritime decarbonization targets that phase out heavy fuel oil in designated coastal zones, converting compliance pressure into procurement acceleration. Osaka Bay hosts METI-funded fuel cell demonstration zones with proton-exchange membrane pilot installations.
Australia
Premium whale-watching and reef-cruise operators in the Whitsundays command ticket price premiums that absorb battery capital costs. The national maritime regulator imposes increasingly stringent harbor emission controls that elevate electric propulsion from preference to compliance necessity. Sydney Harbour commuter corridors and Queensland's tourism clusters concentrate medium-boat deployments with hydrofoil architectures.
Thailand
Archipelago geography concentrates route distances within optimal electric range for Phi Phi Island and Bali-Lombok corridor services, eliminating range anxiety barriers. Island-hopping passenger services deploy hybrid configurations on 40-60 nautical mile legs where high-voltage DC fast-charging infrastructure remains fragmented. Phuket resort fleets absorb premium capital costs through per-passenger ticketing models with high seasonal utilization.
South Korea
Coastal marinas in Jeju Island exhibit procurement patterns migrating from outright vessel purchase toward power-by-the-hour service contracts. Charter cooperatives favor operational expenditure structures that convert seasonal cash-flow volatility into predictable maintenance budgets. Busan's New Port complexes pilot shore-powered loading systems for flat-deck cargo vessels with shallow-draft configurations.
Asia-Pacific Electric Boat Market Competitive Landscape
On the supply side, the industry is tiered between integrated platform developers, component specialists, and aftermarket retrofit providers. Scandinavian and German engineering houses occupy premium positions through hydrofoil stabilization and high-voltage battery management expertise. Chinese fabricators compete on pack-scale manufacturing cost for domestic coastal cargo programs. Two dominant competitive moves are shaping positioning: technology licensing agreements that transfer foil-stabilization IP to regional shipyards, and power-by-the-hour service contracts that displace traditional marine engine maintenance networks.
Within the premium integrated-platform tier, Candela Technology AB and Frauscher Bootswerft GmbH & Co KG exemplify divergent specialization strategies. The Swedish developer occupies a position in computer-stabilized hydrofoil systems for commuter routes, while the Austrian fabricator anchors government coastal security procurement through aluminum-hulled patrol configurations. Torqeedo GmbH represents the aftermarket retrofit archetype, with German-engineered outboard motor kits penetrating Southeast Asian charter fleets through regional distributor networks that displace legacy diesel maintenance infrastructure.
| Leading Market Players |
|---|
| Candela Technology AB |
| Duffy Electric Boat Company |
| Frauscher Bootswerft GmbH & Co KG |
| Quadrofoil D.O.O |
| Vision Marine Technologies Inc |
| Aquawatt Mechatronik und Yachtbau |
| Torqeedo GmbH |
| Corvus Energy |
| Andaman Boatyard |
| Others |
Value Network & Pricing Analysis
Chinese lithium-ion cathode processing clusters for nickel-manganese-cobalt formulations capture upstream margin pools that downstream vessel builders across Southeast Asian archipelagos must negotiate through long-term offtake structures or accept spot-price volatility exposure.
Pricing Analysis
Next-generation solid-state ceramic-electrolyte configurations command substantial premiums over conventional lithium-ion packs, while prior-generation lead-acid retrofits occupy collapsing price tiers in harbor tourism circuits. Three-tier pricing structure across hydrofoil-stabilized premium platforms, standard displacement-hull configurations, and economy outboard retrofits reflects battery energy density and hull complexity. Cost compression in economy charter segments is intensifying because Torqeedo GmbH's power-by-the-hour service contracts convert capital expenditure into operational expenditure models. Commercial ferry operators in Indonesia's Bali-Lombok corridor exhibit highest price sensitivity due to thin-margin daily utilization profiles, while Australia's premium whale-watching operators absorb battery capital costs through ticket price premiums.
Supply Chain Analysis
Extended payment terms from Chinese battery pack manufacturers to Dalian and Qingdao shipyards are compressing working capital cycles for Southeast Asian ferry operators lacking supply-chain finance facilities. Geographic concentration centers on China's cathode processing zones, South Korea's electrolyte membrane production, and Japan's ceramic-electrolyte pilot lines. Raw material dependencies encompass refined lithium carbonate, nickel sulfate, and aluminum alloy sheet for lightweight hull fabrication. Single-source vulnerability from Chinese GB standards coordination creates type-approval bottlenecks that delay platform launches. Distribution runs through Singapore's port logistics hub before final assembly in regional shipyards serving Thailand's island-hopping corridors and Australia's harbor commuter routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment, where METI decarbonization mandates and SAMR battery safety standards create compliance barriers that substitute technologies cannot easily circumvent.
For Market Incumbents: Harden certification entrenchment by engineering to China's SAMR GB standards for battery safety and charging interoperability, securing preferential state-financed fleet renewal access. Deepen backward integration into lithium-ion cathode supply through offtake agreements with Chinese processing clusters, insulating margin pools from nickel-manganese-cobalt price volatility. This defends against emerging solid-state entrants threatening cycle-life advantages in high-salinity marine environments. For New Entrants and Emerging Players: Build out power-by-the-hour service contract capabilities in South Korea's Jeju Island recreational boating cluster, where seasonal cash-flow volatility favors operational expenditure models over capital deployment. Target aluminum-hulled patrol configurations for Philippines and Malaysia government coastal security procurement, where rapid-recharge specifications compete against legacy diesel tenders. Pursue technology licensing agreements that transfer hydrofoil-stabilization IP to regional shipyards lacking computer-controlled foil expertise. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated platform developers with proprietary battery management systems and established type-approval pathways across China's SAMR, Japan's JIS, and Australia's national maritime regulator frameworks. Long-term viability hinges on regulatory compliance entrenchment rather than pure technology differentiation, as emission mandates convert preference to necessity. Watch for solid-state ceramic-electrolyte cycle-life breakthroughs in Japanese coastal demonstration zones as the inflection signal for chemistry-transition investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrofoil Hull Technology Licensing | Transfers Candela's computer-stabilized foil IP to regional shipyards serving Australia's commuter corridors. |
| Power-by-the-Hour Service Contracts | Converts Torqeedo's outboard retrofit penetration into recurring revenue streams across Southeast Asian charter fleets. |
| Solid-State Battery Pilot Programs | METI-funded Osaka Bay demonstrations validate ceramic-electrolyte cycle life for 12-16 hour daily utilization profiles. |
| Shore Charging Infrastructure Partnerships | Addresses high-voltage DC fast-charging gaps fragmenting Thailand's island-hopping hybrid deployments. |
| Aluminum Hull Patrol Platform Certification | Positions Frauscher configurations for Philippines and Malaysia government coastal security tender awards. |
Research Methodology
Operator-level perspectives from ferry fleet managers, shipyard procurement directors, battery system integration engineers, and maritime regulatory compliance officers anchored the qualitative base for this study. Primary interviews across these stakeholder categories combined with secondary validation from SAMR GB standards documentation, METI maritime decarbonization policy filings, and Australian national maritime regulator harbor emission control directives. Bottom-up vessel deployment tallies from Bohai Rim cargo consolidation programs, Seto Inland Sea fishing cooperatives, and Whitsundays tourism operators triangulated against top-down market sizing.
Scenario-bracketing around charging infrastructure buildout pace, solid-state battery chemistry maturation, and aluminum alloy price volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass propulsion architecture, vessel displacement tier, end-use application intensity, and regional regulatory cluster stringency. CAGRs derived from deployment trajectory analysis of state-financed fleet renewal programs and commercial operator procurement cycles. Industry-specific forecast inputs incorporated hydrofoil hull adoption curves and power-by-the-hour contract penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by solid-state battery specialists or hydrogen fuel cell platform developers would shift outcomes beyond modeled ranges. Macroeconomic deviation in lithium carbonate pricing, regulatory acceleration of coastal zone emission mandates, or breakthrough energy density improvements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Jet Boat Market
Marine
Tele-Operated Marine Drone Market
Marine
Deep-V Boat Market
Marine
Ship Rudders Market
Marine
Marine and Marine Management Software Market
Marine
Marine Spreader Lights Market
Marine
Ballast Water Management Market
Marine
Electric Boat and Ship Market
Marine
Mooring Ropes Market
Marine
LNG Bunkering Vessel Market
Marine
Boat Console Market
Marine
Asia-Pacific Marine Communication Systems Market
Marine
Unmanned Marine Vehicles Market
Marine
North Sea Offshore Support Vessels Market
Marine
Global Maritime Information Market
Marine
Marine Glass Market