
 Digital Nautical Charts Market | 2026-2036
Digital Nautical Charts Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Nautical Charts Market Insights
The gap between premium vector chart services and basic raster alternatives is broadening as regulatory mandates harden. Jeppesen leverages its ICAO heritage to dominate aviation-cum-maritime crossover accounts with integrated mission planning. C-MAP anchors its position through deep hydrographic data partnerships with national maritime authorities across Northern Europe. Navionics competes aggressively in recreational boating through dense community-sourced depth contour layers.
Digital nautical charts are georeferenced electronic databases of maritime features, soundings, and navigational aids rendered at scales from 1:500 harbor plans to 1:5 million ocean passages, designed to prevent grounding and collision through real-time position overlay against bathymetric and obstruction data. Vector charts lead commercial adoption because their object-oriented structure enables selective layer display and automated alarm generation for safety contour breaches. Cloud-based access grows fastest among fishing companies and smaller shipping agencies seeking to eliminate per-vessel license maintenance overhead. Raster charts retain residual demand in training and education where visual fidelity to paper traditions aids competency transfer.
The International Maritime Organization's ECDIS mandate, enforced by flag state administrations and port state control regimes, compels vessel operators to maintain compliant electronic chart portfolios or face detention risk. The IHO S-100 framework and IEC 61174 testing standards shape product interoperability and type-approval pathways, creating barriers for uncertified entrants. Stakeholders must monitor the transition from S-57 to S-101 data encoding, as this shift will force fleet-wide software upgrades and recertification investments.
Market Dynamics
Cloud-based ENC delivery platforms are compressing distribution timelines and eliminating physical media logistics, forcing chart providers to rebuild revenue models around subscription access rather than perpetual licenses.
Growth Catalysts
- IMO ECDIS Mandate:Flag state administrations in Panama, Liberia, and the Marshall Islands enforce carriage requirements that compel fleet operators to maintain compliant electronic chart portfolios or face port state control detention.
- Vector Chart Technology:Object-oriented S-57 and emerging S-101 data structures enable selective layer display and automated safety contour alarms that raster formats cannot replicate.
- Port Complex Concentration:Singapore, Rotterdam, and Shanghai handle the densest vessel traffic and impose the strictest electronic navigation compliance verification regimes.
Market Restraints
- Hydrographic Data Access Costs:National maritime authorities in Norway, the United Kingdom, and Australia charge licensing fees for bathymetric source data that inflate production costs for ENC developers.
- Certification Bottlenecks:IEC 61174 type-approval testing creates multi-month validation timelines that delay product releases and freeze smaller competitors from commercial shipping segments.
- Raster Chart Substitution:Recreational boating and training institutions retain demand for visually familiar paper-equivalent formats that limit vector premium pricing power.
Strategic Opportunities
- Indonesian Archipelago Expansion:The world's largest island nation lacks comprehensive ENC coverage across its 17,000 islands, creating white space for hydrographic data partnerships with Bakamla.
- Fishing Fleet Digitization:Artisanal and industrial fishing operators in Vietnam, Peru, and Senegal represent underpenetrated demand for cloud-based chart access without per-vessel license maintenance.
- S-101 Transition Services:The IHO-mandated shift from S-57 to S-101 encoding forces fleet-wide software upgrades and recertification investments that service providers can capture.
Industry Challenges
- Hydrographic Surveyor Shortage:Specialized bathymetric data collection expertise concentrates within national naval services and a handful of commercial contractors, constraining raw data supply.
- Legacy ECDIS Integration:Type-approved systems installed during the 2012-2018 mandate phase lack processing capacity for high-density S-101 vector datasets, forcing hardware replacement cycles.
- Cross-Format Compatibility Testing:Vessel operators must maintain parallel raster and vector portfolios during transition periods, doubling validation workload for bridge crews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Nautical Charts Market |
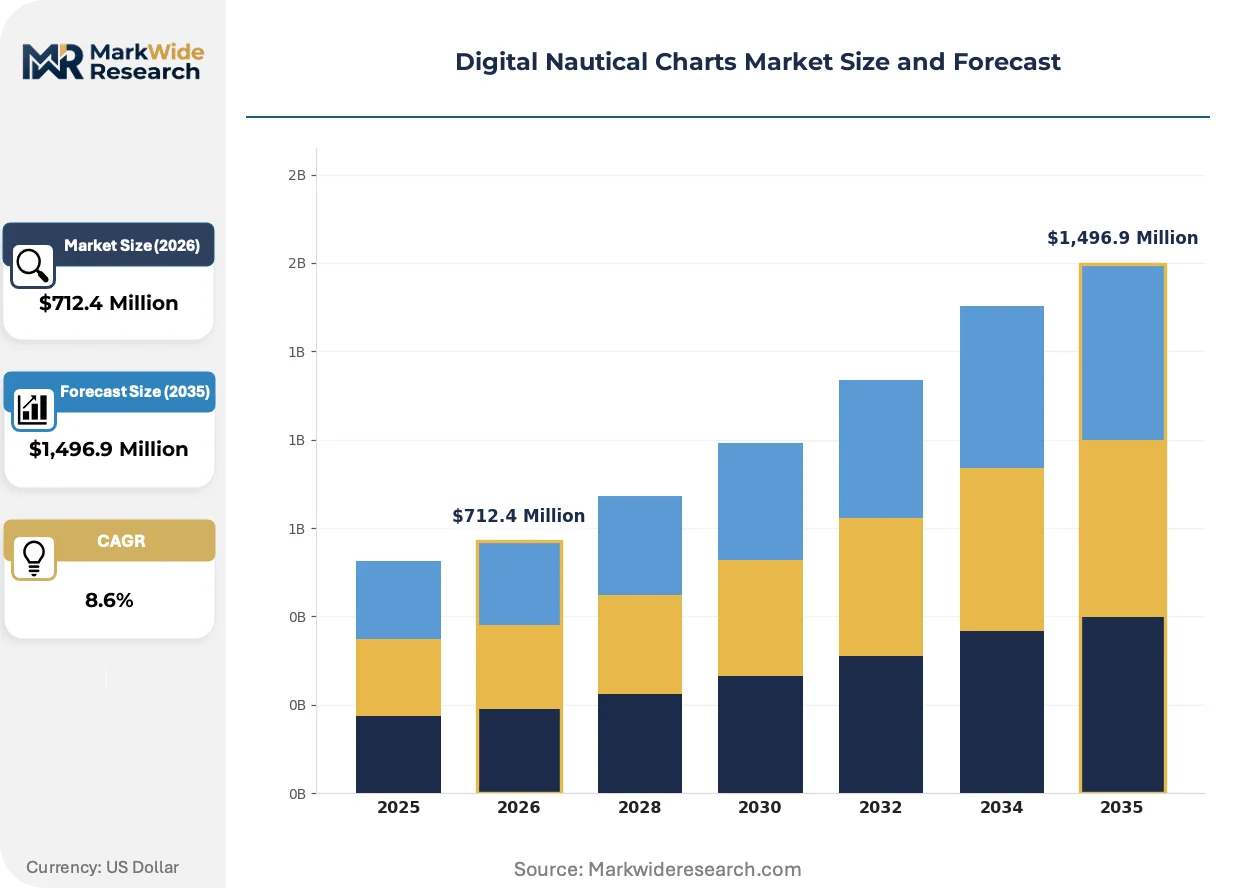
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,496.9 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Chart Type: Vector Charts, Raster Charts, 3D Charts, Electronic Chart Display End User: Maritime Operators, Fishing Companies, Shipping Agencies, Recreational Boat Owners Delivery Mode: Online Subscription, Downloadable Files, Pre-Installed Software, Cloud-Based Access Usage Area: Commercial Shipping, Recreational Boating, Fishing Industries, Training and Education |
| Companies Covered | Jeppesen, Navionics, C-MAP, Electronic Charts Company, ChartCo, Japan Hydrographic Charts & Publications, ChartWorld, Furuno Electric, Raymarine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Nautical Charts Market Trends and Innovations
Real-time hydrographic updates and autonomous vessel navigation requirements are compressing chart refresh cycles from quarterly to continuous, restructuring how maritime data flows from survey vessel to bridge display.
Machine learning bathymetric interpolation is automating depth contour generation from sparse multibeam survey tracks. Hydrographic offices in Canada and New Zealand deploy neural networks to infill unmeasured seafloor regions between survey lines. Commercial shipping operators accept algorithmically derived soundings for route planning in data-sparse corridors, reducing reliance on exhaustive physical surveys.
The IHO S-100 framework implementation is mandating standardized data encoding across maritime safety information products. National hydrographic services in France, Japan, and Brazil restructure production pipelines to output machine-readable feature catalogs. ENC developers face recertification costs as type-approval bodies adapt IEC 61174 testing protocols for the new framework.
Fishing companies and coastal cargo operators are consolidating purchasing through fleet management platform subscriptions. Maritime software integrators in Norway and the Netherlands bundle ENC access with vessel tracking and fuel optimization tools. Smaller shipping agencies eliminate per-vessel license administration by delegating chart procurement to third-party platform providers.
Digital Nautical Charts Market Segmentation
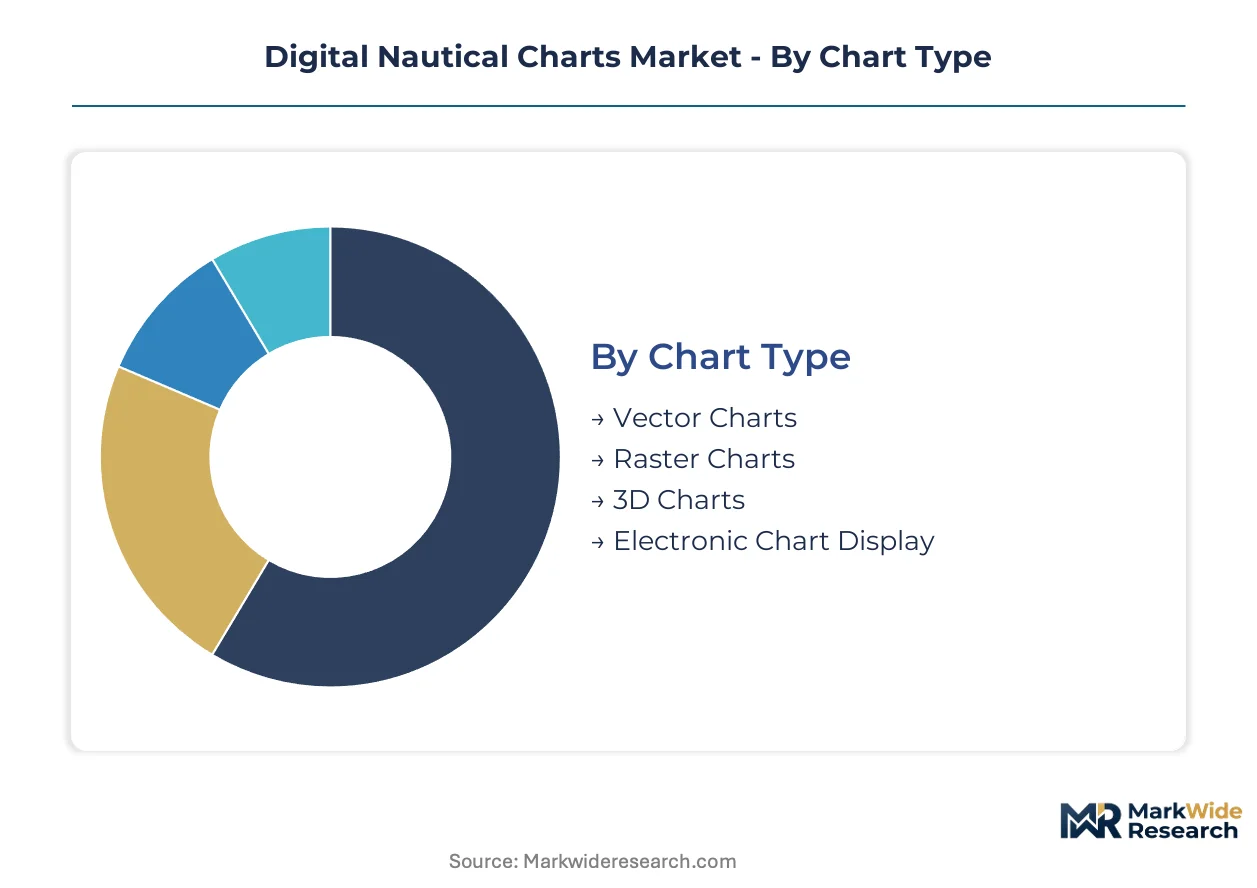
Digital nautical charts serve divergent operational requirements across vessel types and regulatory environments. Segmentation reveals how vector technology commands commercial shipping premiums while raster formats retain residual demand in training and recreational applications.
Chart Type:
Volume concentrates in legacy formats, while premium pricing attaches to object-oriented data structures that enable automated safety systems.
- Vector Charts:Object-oriented S-57 and S-101 data structures encode maritime features as discrete entities with embedded attribution. Commercial shipping fleets in Singapore, Rotterdam, and Shanghai mandate these formats for ECDIS compliance and automated safety contour alarms.
- Raster Charts:Pixel-based image files replicate paper chart appearance through scanned or rendered bitmaps. Training institutions and recreational boaters in coastal Mediterranean and Caribbean markets favor these formats for visual familiarity during competency transfer.
- 3D Charts:Bathymetric surface models enable subsea visualization for offshore construction and submarine cable routing.
- Electronic Chart Display:Integrated hardware-software systems bundle chart data with proprietary rendering engines.
Mature deployment sits with Raster Charts. Newer deployment is concentrated in Vector Charts.
End User:
Procurement authority varies sharply between regulated commercial operators and discretionary recreational purchasers.
- Maritime Operators:Deep-sea and coastal cargo carriers face mandatory ECDIS carriage requirements under IMO regulations enforced by Panama, Liberia, and Marshall Islands flag states. These operators purchase through multi-year enterprise licenses with mandatory update subscriptions.
- Shipping Agencies:Third-party fleet managers consolidate procurement across vessel portfolios, favoring cloud-based access models that eliminate per-vessel license administration.
- Fishing Companies:Artisanal and industrial operators in Vietnam, Peru, and Senegal adopt cloud subscriptions to avoid upfront license costs.
- Recreational Boat Owners:Leisure craft operators purchase through mobile applications and chart plotter manufacturers.
Revenue concentration aligns with Maritime Operators. User base expansion is climbing fastest among Fishing Companies.
Delivery Mode:
Distribution economics favor recurring subscription models over perpetual licenses that burden smaller operators with maintenance overhead.
- Cloud-Based Access:Browser and API-delivered chart streams enable real-time updates without local data management. Norwegian and Dutch maritime software integrators bundle this access with vessel tracking and fuel optimization platforms.
- Online Subscription:Recurring payment models provide continuous ENC updates and regulatory compliance verification.
- Downloadable Files:Static dataset downloads suit vessels with intermittent connectivity.
- Pre-Installed Software:OEM-integrated chart packages ship with ECDIS hardware from type-approved manufacturers.
Legacy infrastructure relies on Downloadable Files. Steepest expansion trajectory belongs to Cloud-Based Access.
Usage Area:
Application context determines chart scale, update frequency, and regulatory scrutiny intensity.
- Commercial Shipping:SOLAS-class vessels require comprehensive ENC portfolios with weekly update cycles. Port state control regimes in Singapore and Rotterdam enforce compliance through inspection and detention authority.
- Fishing Industries:Mobile fleets require flexible coverage across jurisdictional boundaries with lower regulatory burden than SOLAS vessels.
- Recreational Boating:Leisure applications prioritize harbor detail and community-sourced depth data over official hydrographic survey accuracy.
- Training and Education:Maritime academies maintain parallel raster and vector portfolios to build competency across legacy and modern bridge systems.
Established infrastructure serves Commercial Shipping. Adoption momentum is gaining share fastest in Fishing Industries.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's port complex commands the densest vessel traffic and strictest electronic navigation compliance verification regimes worldwide. The city-state's Maritime and Port Authority enforces ECDIS carriage requirements through rigorous port state control inspections. This concentration of regulatory scrutiny and commercial shipping volume anchors regional demand for vector-based ENC systems.
United States
The National Oceanic and Atmospheric Administration operates the nation's primary hydrographic service through its Office of Coast Survey. NOAA distributes Electronic Navigational Charts through public-private partnerships with commercial integrators. Houston and Long Beach port authorities mandate weekly ENC update cycles for tanker and container fleets calling their terminals.
Norway
The Norwegian Hydrographic Service maintains comprehensive S-57 and S-101 vector coverage of the country's fjord-indented coastline. Maritime software integrators in Oslo and Bergen bundle cloud-based ENC access with vessel tracking and fuel optimization platforms. The Norwegian Maritime Authority enforces IEC 61174 type-approval standards through flag state certification programs.
United Kingdom
The United Kingdom Hydrographic Office licenses bathymetric source data to ENC developers under commercial terms that inflate production costs. Southampton and London house Europe's largest maritime insurance and classification society clusters. The Maritime and Coastguard Agency coordinates port state control enforcement with Rotterdam and Antwerp authorities.
Japan
The Japan Hydrographic and Oceanographic Department produces official ENC coverage for the archipelago's congested coastal waters. Tokyo Bay and Osaka Bay port complexes require real-time chart updates for container and bulk carrier operations. The country's shipowners' association coordinates fleet-wide ECDIS compliance with flag state administrations in Panama and Liberia.
Brazil
The Brazilian Navy's Directorate of Hydrography and Navigation maintains partial ENC coverage of the country's extensive coastline. Santos and Rio de Janeiro ports handle South America's largest container volumes under growing electronic navigation mandates. The national maritime authority is expanding hydrographic survey capacity to close data gaps in the Amazon delta region.
Digital Nautical Charts Market Competitive Landscape
Capital-heavy hydrographic data producers compete with asset-light software integrators across distinct value chain positions. The market structures around three tiers: national hydrographic services controlling raw bathymetric data, specialized ENC developers converting source data into certified products, and maritime software platforms aggregating chart access with fleet management tools. Strategic differentiation concentrates through exclusive hydrographic data partnerships, cloud-based delivery infrastructure, and S-101 transition service capabilities. Consolidation pressures intensify as flag state certification requirements raise fixed compliance costs.
Within the integrated navigation solutions tier, Jeppesen leverages aviation heritage to anchor crossover accounts requiring unified mission planning. C-MAP exemplifies the hydrographic partnership archetype through deep data relationships with Northern European maritime authorities. Navionics occupies a distinct position serving recreational boating demand through community-sourced depth contributions. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without overlapping segment focus.
| Leading Market Players |
|---|
| Jeppesen |
| Navionics |
| C-MAP |
| Electronic Charts Company |
| ChartCo |
| Japan Hydrographic Charts & Publications |
| ChartWorld |
| Furuno Electric |
| Raymarine |
| Others |
Pricing and Supply Chain Analysis
Bathymetric source data licensing fees from national maritime authorities in Norway, the United Kingdom, and Australia cascade through production cost structures, compressing margins for ENC developers while enabling tiered pricing separation between certified commercial-grade portfolios and unregulated recreational offerings.
Pricing Analysis
ECDIS carriage compliance outcomes anchor value-based pricing, with maritime operators paying premiums for IEC 61174 type-approved vector portfolios that eliminate port state control detention risk. Price differentiation separates SOLAS-grade certification tiers from recreational boating licenses, with the former commanding subscription premiums tied to weekly update cycles and automated safety contour alarms. Cost compression in recreational raster segments intensifies because community-sourced depth data from Navionics erodes proprietary hydrographic value. Maritime operators exhibit least price sensitivity due to regulatory mandate enforcement, while artisanal fishing companies in Vietnam and Senegal demonstrate highest elasticity as they weigh cloud subscription costs against paper chart alternatives.
Supply Chain Analysis
Multibeam sonar survey capacity rests on specialized vessel fleets concentrated in Norway, the United Kingdom, and Japan, with national naval services and commercial contractors like Fugro controlling raw bathymetric data generation. ENC developers source from hydrographic offices, S-57/S-101 encoding specialists, and cloud infrastructure providers, creating layered input dependencies. Single-source vulnerability concentrates in hydrographic surveyor expertise, where naval service retirements and commercial competition constrain data pipeline expansion. Distribution runs through maritime software integrators in Oslo and Bergen that bundle chart access with fleet management platforms, compressing direct-to-vessel sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where IMO ECDIS mandates create barrier-to-entry moats that protect certified incumbents while freezing uncertified competitors from commercial shipping segments.
For Market Incumbents: Anchor defensive positioning through exclusive hydrographic data partnerships with Northern European maritime authorities that lock competitors out of high-fidelity bathymetric source material. Deepen vertical integration into S-101 encoding and IEC 61174 recertification service capabilities to capture fleet-wide software upgrade cycles. Counter cloud-based delivery disruption by bundling ENC access with vessel tracking and fuel optimization tools through maritime software integrators in Norway and the Netherlands. For New Entrants and Emerging Players: Begin with Indonesian archipelago white space where Bakamla partnerships can establish hydrographic data relationships before incumbent encirclement hardens. Target Vietnamese and Senegalese fishing fleet digitization as the most penetrable segment, leveraging cloud subscription models that eliminate per-vessel license maintenance overhead for price-sensitive artisanal operators. Pursue go-to-market positioning through mobile-first chart plotter integrations that bypass ECDIS hardware certification bottlenecks. For Investors and Strategic Acquirers: First-mover S-101 transition service contracts among Panama and Liberia flag state fleets is the leading indicator that recertification revenue streams are materializing at scale. Long-term viability favors asset-light software integrators with cloud delivery infrastructure over capital-heavy hydrographic data producers facing survey vessel depreciation cycles. Monitor hydrographic office privatization discussions in Brazil and Japan as acquisition trigger signals for national data asset commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| S-101 Encoding Transition Services | Captures fleet-wide software upgrade revenue as IHO mandates replace S-57 data structures. |
| Cloud-Based Delivery Platform Buildout | Eliminates physical media logistics while enabling real-time ENC updates for fishing companies. |
| Hydrographic Data Partnership Expansion | Locks in exclusive bathymetric source access with Bakamla across Indonesia's 17,000 islands. |
| Maritime Software Integrator Acquisition | Bundles ENC access with vessel tracking tools through Norwegian and Dutch platform providers. |
| Machine Learning Bathymetric Infilling | Automates depth contour generation from sparse multibeam tracks in data-sparse corridors. |
Research Methodology
Multi-period observation of ECDIS installation rates, port state control detention incidents, and ENC update frequency patterns anchored the trend analysis, supplemented by interviews with fleet operations managers at Panama and Liberia flag state registries, hydrographic office production directors, maritime software integrator platform engineers, and bridge system procurement officers at Singapore and Rotterdam port authorities. Secondary validation drew from IMO circulars, IHO S-100 framework documentation, IEC 61174 type-approval registries, and national maritime authority licensing fee schedules. Bottom-up vessel fleet segmentation triangulated against top-down hydrographic service production capacity estimates.
Input-output matrices mapped bathymetric survey generation through ENC encoding, certification, and delivery stages across the analysis window, with segmentation dimensions spanning chart type, vessel class, delivery mode, and regional regulatory cluster. CAGRs derived from vessel fleet growth projections, mandate compliance deadlines, and cloud subscription adoption curves. Industry-specific forecast inputs incorporated hydrographic surveyor workforce constraints and S-101 transition timeline assumptions.
Underlying measurement precision varies by segment; SOLAS-class commercial shipping carries tighter precision than artisanal fishing fleet estimates due to mandatory registry reporting requirements. Forecasts reflect documented assumptions regarding flag state enforcement intensity and hydrographic office digitization pace. Regulatory mandate delays, hydrographic survey vessel availability shocks, and S-101 recertification bottlenecks constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Europe Recreational Boating Market
Marine
Marine LED Lights Market
Marine
Autonomous Underwater Vehicle (AUV) Market
Marine
Marine Elevators Market
Marine
India Boat Davits Market
Marine
Hydraulic Marine Cranes Market
Marine
Electric Boat and Ship Market
Marine
Marine Suspension Seat Bases Market
Marine
Asia-Pacific Leisure Boat Marine Coating Market
Marine
Singapore Container Transshipment Market
Marine
Steel Ship Plate Market
Marine
Buoys and Beacon Market
Marine
Mooring Ropes Market
Marine
Boat Ladder Market
Marine
Marine Winch Motors Market
Marine
Yacht Shell Doors Market