
 United Kingdom Used Car Market | 2026-2036
United Kingdom Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Used Car Market Analytics
Certified pre-owned tiering is bifurcating the United Kingdom used car landscape into warranty-backed inventory and unverified private stock. Bristol Street Motors leverages its franchise network to anchor certified volume across the Midlands and North. Audi competes on technology leadership, using its digital service history infrastructure to differentiate residual value guarantees. Citygate Automotive Ltd specializes in premium segment refurbishment, sustaining margin pools on low-mileage executive saloons.
A used car constitutes a previously registered motor vehicle sold through secondary ownership transfer, typically evaluated by age, mileage, service history, and cosmetic condition against manufacturer-grade inspection protocols. The United Kingdom market channels these assets through dealership networks, online platforms, and auction houses to balance liquidity with consumer protection. SUV and hatchback body styles dominate transaction volume, while electric and hybrid fuel types capture the fastest structural expansion as battery health diagnostics standardize. Dealership sales channels occupy the premium margin tier, whereas online platforms extend reach into price-sensitive first-time buyer segments.
The Driver and Vehicle Standards Agency enforces roadworthiness testing through MOT certification, shaping minimum quality thresholds for marketable inventory. The Financial Conduct Authority governs consumer credit arrangements, restricting predatory financing on higher-risk used vehicle loans. The Competition and Markets Authority monitors online platform transparency, mandating accurate mileage and damage disclosure. Stakeholders must monitor how battery degradation standards for used electric vehicles crystallize under emerging industry protocols.
Market Dynamics
The UK's 2030 ban on new petrol and diesel sales is forcing rapid inventory restructuring across dealership networks, with residual value programs and battery health diagnostics emerging as the decisive competitive variables.
Growth Catalysts
- Fleet electrification mandates:Corporate procurement policies now prioritize pre-owned electric and hybrid vehicles to meet internal carbon targets ahead of regulatory deadlines. Fleet operators accelerate volume commitments.
- DVSA MOT modernization:Enhanced roadworthiness testing protocols for electrified powertrains create quality transparency that builds consumer confidence in secondary-market battery-electric transactions.
- Charging infrastructure density:Greater London and Southeast England's rapid charger networks reduce range anxiety, concentrating used electric vehicle turnover in these corridors.
Market Restraints
- Battery degradation uncertainty:Absence of standardized state-of-health metrics creates valuation opacity that suppresses lender appetite for high-mileage electric vehicle financing.
- Supply concentration in franchise networks:Certified pre-owned inventory remains captive to manufacturer-dealer relationships, limiting price discovery and liquidity for independent traders.
- Residual value volatility:Rapid model-cycle turnover in battery technology compresses depreciation curves for early-generation electric vehicles, eroding margin predictability.
Strategic Opportunities
- Midlands and North England penetration:Charging infrastructure buildout in Birmingham, Manchester, and Leeds creates underserved demand for certified used electric inventory outside the Southeast corridor.
- Battery health certification services:Independent diagnostic platforms can capture margin from standardized state-of-health reporting as the Financial Conduct Authority tightens disclosure requirements.
- Digital auction integration:Online platforms connecting fleet divestment with retail buyers disintermediate traditional wholesale channels, capturing spread compression.
Industry Challenges
- Technician certification gaps:High-voltage battery repair and diagnostic skills remain scarce, constraining refurbishment throughput for electrified inventory.
- Legacy system integration:Dealer management systems require costly upgrades to track battery warranty transfers and service history across multiple ownership events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Used Car Market |
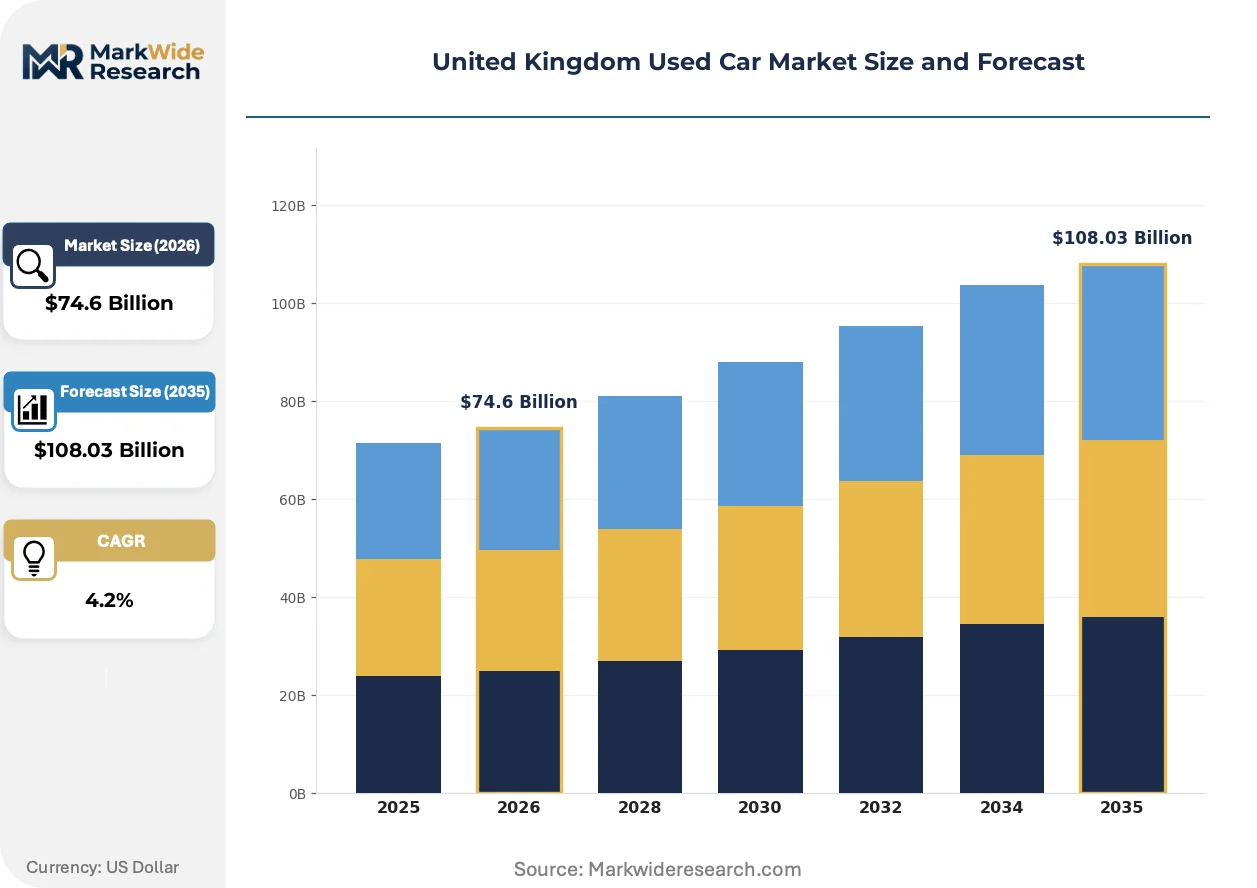
| Market Size in 2026 | $74.6 Billion |
| Market Size in 2035 | $108.03 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Fuel Type: Petrol, Diesel, Electric, Hybrid Sales Channel: Dealerships, Private Sellers, Online Platforms, Auctions Customer Type: First-time Buyers, Families, Professionals, Retirees |
| Companies Covered | Audi, Robins and Day, Bristol Street Motors, EMG Motor Group, Holdcroft, Penske Automotive, Group 1 Automotive, Citygate Automotive Ltd, Jaguar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Used Car Market Evolving Landscape
Digital verification infrastructure and electrification policy are rewiring how value is assessed and transferred in secondary vehicle markets, compressing information asymmetries that historically protected incumbent channels.
Artificial intelligence-driven vehicle inspection is bifurcating the appraisal process between automated condition scoring and human judgment. Large dealer groups deploy computer-vision systems to standardize cosmetic damage assessment across multiple sites. This compression of subjective evaluation is enabling centralized pricing decisions that override local manager discretion.
The Financial Conduct Authority's consumer credit conduct rules are tightening disclosure obligations on used vehicle financing arrangements. Lenders must now verify affordability against stricter criteria, reducing subprime penetration. Independent dealerships face compliance cost escalation that favors scaled operators with dedicated compliance functions.
Fleet remarketing cycles are compressing as corporate sustainability targets accelerate replacement schedules. Three-year lease structures are giving way to 24-month rotations, flooding wholesale channels with younger, lower-mileage inventory. This volume surge is visible in auction throughput data from Birmingham and Manchester trade centers.
United Kingdom Used Car Market Segmentation
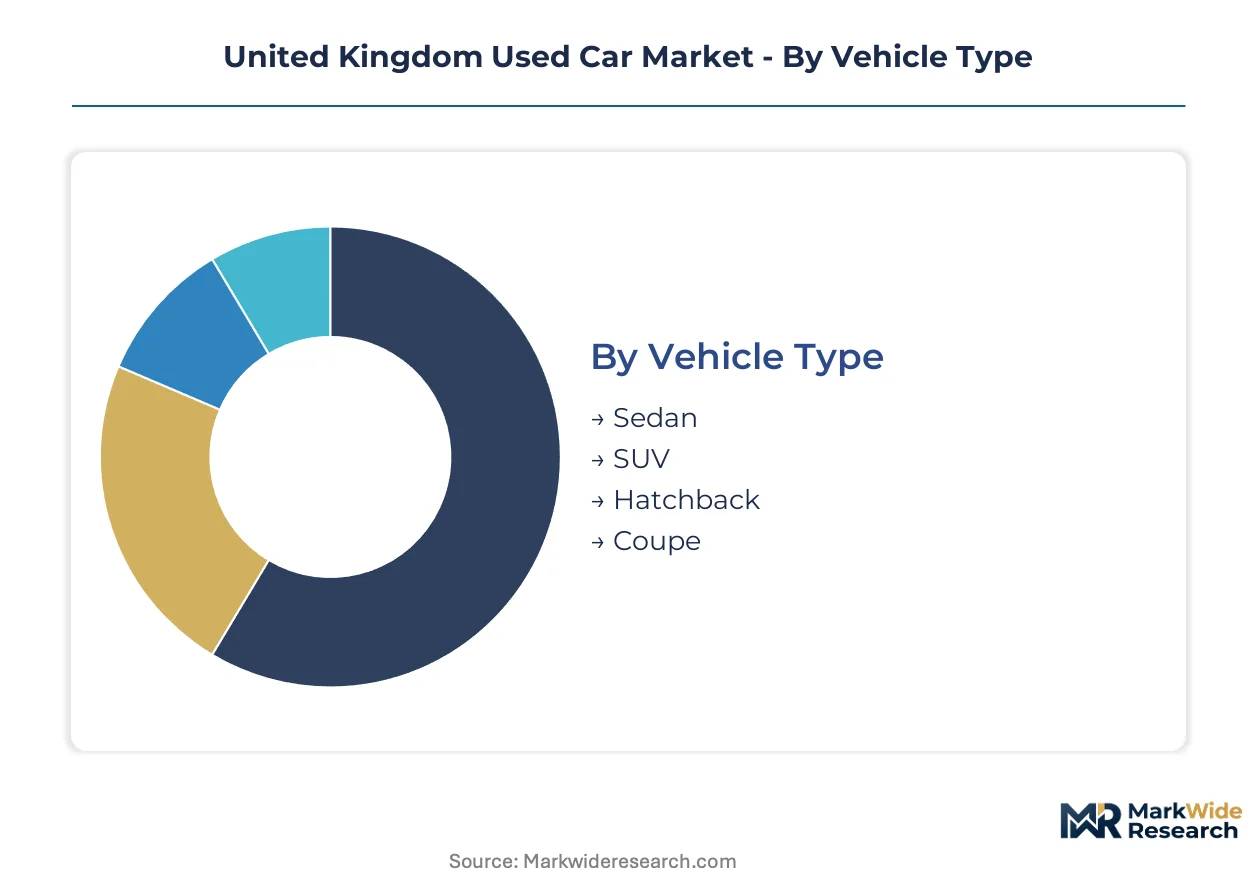
Segmentation in the United Kingdom used car market reveals how electrification policy and channel specialization are reallocating profit pools. Distinct buyer cohorts and powertrain technologies now command differentiated pricing power and inventory velocity.
Vehicle Type:
SUV and hatchback segments face intensifying substitution pressure as fleet electrification redirects procurement toward body styles with superior battery packaging efficiency.
- SUV:Higher ground clearance and modular platform architectures accommodate battery packs without compromising cabin space. Demand clusters in suburban Greater London and the Southeast where charging infrastructure density supports larger electrified household vehicles.
- Hatchback:Compact dimensions and lower curb weights maximize electric range efficiency on urban duty cycles. Manchester and Birmingham buyers favor this format for congested city-center commuting where parking constraints dominate.
- Sedan:Executive saloon formats retain residual value strength in premium tier refurbishment channels serving professional segments.
- Coupe:Low-volume specialty segment dependent on enthusiast demand and seasonal purchase patterns.
SUV retains volume leadership; hatchback holds the steepest expansion curve.
Fuel Type:
Cost tier stratification separates powertrain segments into premium electrified inventory and depreciated combustion-era stock.
- Electric:Battery health diagnostics and state-of-health certification now determine financeability. Greater London's rapid charger concentration enables highest turnover velocity for certified pre-owned battery-electric units.
- Hybrid:Plug-in and self-charging variants bridge range anxiety gaps in Midlands corridors where infrastructure buildout lags the Southeast. Birmingham and Leeds buyers prioritize this technology for mixed urban-rural driving profiles.
- Petrol:Depreciation acceleration ahead of the 2030 sales ban compresses margin windows for independent traders holding aging inventory.
- Diesel:Commercial fleet divestment floods wholesale channels with high-mileage units facing urban clean air zone restrictions.
Hybrid commands the largest transaction volume; electric is climbing the fastest.
Sales Channel:
Channel selection correlates directly with buyer risk tolerance and financing access requirements across customer life stages.
- Dealerships:Franchise networks anchor certified pre-owned volume with warranty-backed inventory and manufacturer residual value programs. Midlands and North England penetration by Bristol Street Motors and Citygate Automotive Ltd extends coverage beyond Southeast concentration.
- Online Platforms:Digital marketplaces capture price-sensitive first-time buyers through transparent pricing and remote viewing tools. Competition and Markets Authority disclosure mandates now standardize mileage and damage reporting across these channels.
- Private Sellers:Unverified stock appeals to cash buyers with technical expertise to assess condition independently.
- Auctions:Fleet remarketing compression to 24-month cycles floods Birmingham and Manchester trade centers with young, low-mileage inventory.
Dealerships dominate premium tier revenue; online platforms are gaining share fastest among entry-level segments.
Customer Type:
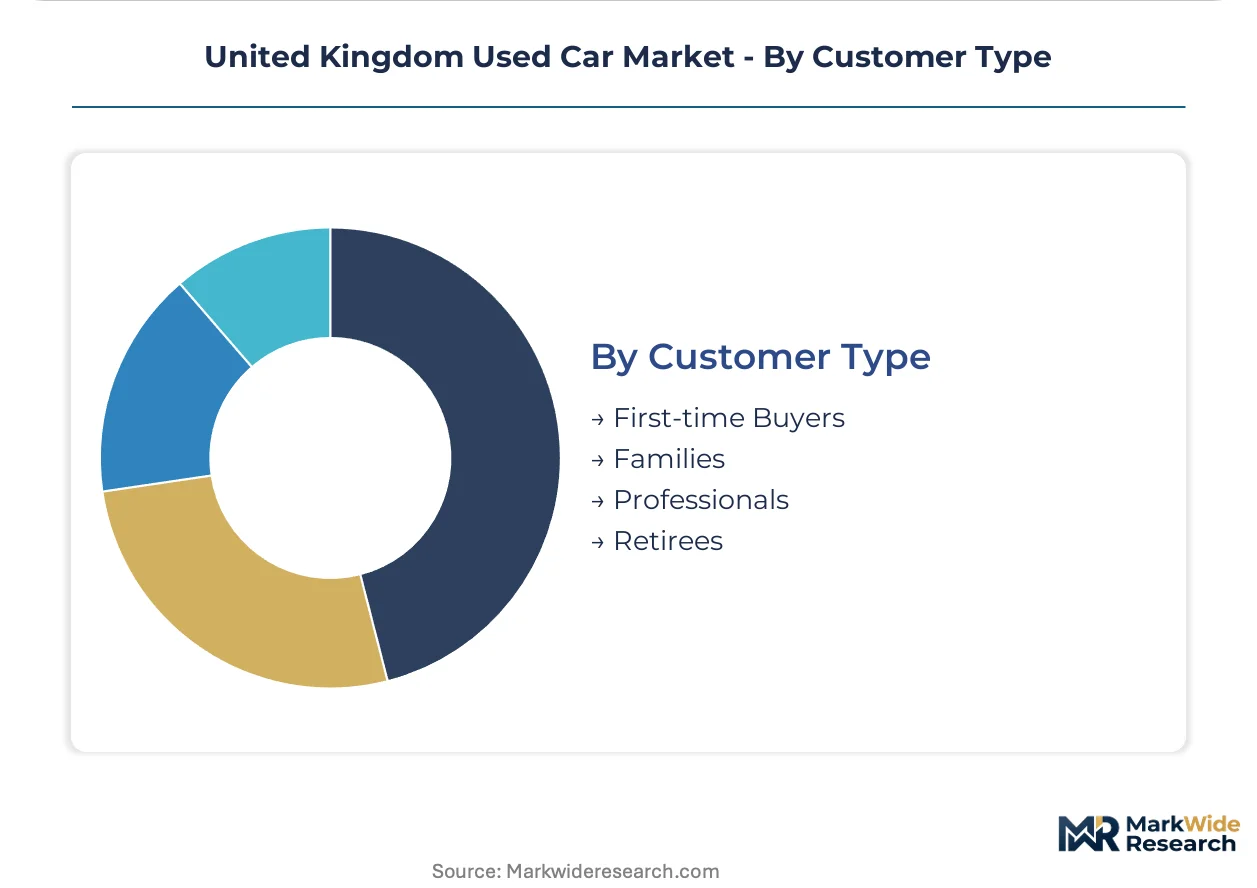
Application-based segmentation maps vehicle requirements to household lifecycle stages and commuting patterns.
- Families:Multi-occupant transport needs prioritize SUV and hybrid formats with safety ratings and cabin flexibility. Southeast England's charging density supports electrified family vehicle turnover.
- Professionals:Low-mileage executive saloons and premium SUVs sustain refurbishment margin pools for specialist operators.
- First-time Buyers:Price sensitivity and financing constraints channel demand toward hatchback formats through online platforms.
- Retirees:Reduced annual mileage profiles favor nearly-new inventory with remaining manufacturer warranty coverage.
Families represent the largest addressable base; professionals deliver the highest per-unit margin contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom's used car market operates as a net importer of pre-owned electric inventory from European fleet channels, while exporting depreciated combustion-era stock to Commonwealth markets ahead of the 2030 sales ban.
London and Southeast England
Rapid charger density above 150 units per 100,000 residents powers the fastest electrified used vehicle turnover in the UK. The Financial Conduct Authority's consumer credit conduct rules tighten disclosure obligations on financing arrangements across Greater London dealerships. Citygate Automotive Ltd anchors certified pre-owned volume in this corridor, capitalizing on executive saloon refurbishment demand.
Midlands
Birmingham and Leicester buyers favor hybrid hatchbacks for congested urban commuting where parking constraints dominate. The Driver and Vehicle Standards Agency enforces enhanced MOT roadworthiness testing protocols for electrified powertrains across West Midlands testing centers. Bristol Street Motors leverages its franchise network to extend certified inventory coverage into this historically underserved electrification corridor.
North England
Manchester and Leeds corridors show accelerating demand for certified used electric SUVs as charging infrastructure buildout lags Southeast density. The Competition and Markets Authority monitors online platform transparency, mandating accurate mileage disclosure across digital marketplaces serving Yorkshire and Lancashire buyers. EMG Motor Group positions refurbishment capacity to capture emerging electrified family vehicle turnover.
Scotland
Edinburgh and Glasgow markets exhibit pronounced seasonality in electrified SUV demand tied to rural driving profiles and winter range anxiety concerns. Scotland's net-zero emissions target accelerates fleet electrification mandates among public sector procurement programs. Independent traders in the Central Belt face margin compression from rapid battery technology model-cycle turnover.
Wales
Cardiff and Newport corridors concentrate transaction volume in hybrid formats bridging urban-rural driving requirements. Welsh Government clean air zone consultations shape future diesel commercial vehicle restrictions in valley urban centers. Holdcroft extends franchise network reach into South Wales, targeting family segment electrification with warranty-backed inventory.
United Kingdom Used Car Market Competitive Landscape
Concentration sits with multi-site franchise operators commanding certified pre-owned tiering and manufacturer residual value programs. The vendor base fragments across independent traders, digital platforms, and auction houses serving price-sensitive entry segments. Three archetypes dominate: scale-driven dealer groups with proprietary refurbishment infrastructure, technology-differentiated premium brand captives leveraging digital service history, and fleet remarketing specialists compressing wholesale cycles. Competitive moves center on geographic expansion into charging infrastructure growth corridors and backward integration into battery health certification services.
Within the scale-driven tier, Bristol Street Motors and EMG Motor Group exemplify multi-region franchise operators extending certified inventory coverage beyond Southeast concentration. Audi and Jaguar occupy positions as premium brand captives competing on technology leadership and digital verification infrastructure. Citygate Automotive Ltd represents the specialist archetype, anchoring margin pools on low-mileage executive saloon refurbishment in Greater London.
| Leading Market Players |
|---|
| Audi |
| Robins and Day |
| Bristol Street Motors |
| EMG Motor Group |
| Holdcroft |
| Penske Automotive |
| Group 1 Automotive |
| Citygate Automotive Ltd |
| Jaguar |
| Others |
Value Network & Pricing Analysis
Driver and Vehicle Standards Agency MOT certification gates both supply qualification and price differentiation simultaneously, separating warranty-backed certified inventory from unverified private stock while compressing margins for traders unable to meet inspection thresholds.
Pricing Analysis
First-time buyers anchor pricing stratification across premium, standard, and economy tiers. Certified pre-owned inventory commands manufacturer residual value guarantees and extended warranty bundling, while unverified private stock trades at steep discounts reflecting information asymmetry. Cost compression in petrol segments is intensifying because the 2030 sales ban accelerates depreciation curves ahead of regulatory deadlines. Fleet procurement officers show least price sensitivity due to carbon target compliance requirements, whereas independent cash buyers exhibit highest sensitivity to cosmetic condition discounts.
Supply Chain Analysis
High-voltage battery refurbishment capacity constrains electrified inventory throughput across United Kingdom workshop networks. Supply draws from German OEM component streams, South Korean battery cell manufacturing, and domestic fleet remarketing channels. Single-source vulnerability sits with lithium-ion cell supply concentrated in Asian production hubs. Distribution runs through franchise dealership networks for certified tier inventory, while digital auction platforms disintermediate wholesale channels for independent trader access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against direct-to-consumer digital platforms disintermediating traditional dealership relationships, requiring channel control investments to retain pricing power.
For Market Incumbents: Compound franchise network density in Midlands and North England charging corridors before infrastructure maturity attracts platform competitors. Integrate backward into battery health certification services as the Financial Conduct Authority tightens disclosure requirements. Prioritize technician certification programs to remove refurbishment throughput constraints on electrified inventory. For New Entrants and Emerging Players: Differentiate on standardized state-of-health reporting for high-mileage electric vehicles where lender valuation opacity suppresses financeability. Target Manchester and Leeds family segments with hybrid SUV formats bridging range anxiety gaps. Deploy mobile inspection units to capture unverified private stock certification fees ahead of platform aggregation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across battery refurbishment infrastructure as technician scarcity and equipment specialization raise barrier thresholds. Mid-scale regional dealer groups with proprietary workshop capacity represent optimal acquisition targets. Monitor fleet remarketing cycle compression as the signal indicating wholesale channel liquidity stress.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Health Certification Investment | Standardized state-of-health reporting unlocks lender financeability for high-mileage electric inventory. |
| Midlands Network Expansion | Birmingham and Manchester charging buildout creates underserved demand for certified electrified stock. |
| Digital Auction Platform Integration | Direct fleet-to-retail connections compress wholesale spreads and accelerate inventory velocity. |
| Technician Certification Program | High-voltage diagnostic skills scarcity constrains refurbishment throughput for battery-electric units. |
| Residual Value Guarantee Structuring | Manufacturer-backed programs differentiate certified tiers from unverified private market stock. |
Research Methodology
Cross-validation between dealership operations directors and fleet procurement managers anchors the qualitative findings against auction throughput data and vehicle registration databases. Primary interviews with refurbishment workshop heads, online platform executives, and Financial Conduct Authority compliance officers combined with secondary validation from DVSA MOT certification records, SMMT production data, and charging infrastructure deployment trackers. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the United Kingdom market.
Sensitivity analysis on battery degradation assumptions and fleet remarketing cycle compression shapes the analytical framework across the projection horizon. Segmentation dimensions model vehicle type, fuel architecture, sales channel, and customer lifecycle stage. CAGRs derive from installed base dynamics and replacement demand curves. Forecast inputs incorporate charging infrastructure density trajectories and residual value program penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained electrification policy support and battery technology stability would require recalibration. Forecasts reflect assumptions on regulatory timeline adherence and lender risk appetite evolution. Practitioners should keep alternative scenarios live as clean air zone expansion and battery chemistry transitions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Thailand Used Car Market
Used Vehicles
Kuwait Used Car Market
Used Vehicles
Japan Used Car Market
Used Vehicles
Philippines Used Car Market
Used Vehicles
Used Cars in Russia Market
Used Vehicles
North America Used Car Market
Used Vehicles
GCC Used Car Market
Used Vehicles
UAE Used Cars Industry Market
Used Vehicles
Saudi Arabia Used Car Market
Used Vehicles
Poland Used Car Market
Used Vehicles
Brazil Used Car Market
Used Vehicles
Vintage Car Market
Used Vehicles
Vietnam Used Car Market
Used Vehicles
Used Semi Truck Market
Used Vehicles
Russia Used Car Market
Used Vehicles
Canada Used Car Market