
 Fleet Management Software Market | 2026-2036
Fleet Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Fleet Management Software Market Intelligence
Market Context
Logistics providers is pivoting toward integrated fleet platforms as last-mile delivery complexity rises. Samsara leverages IoT-native architecture to dominate real-time visibility for refrigerated transport. Geotab anchors its position through open-platform telematics that third-party developers extend. Motive specializes in AI-powered dashcam systems that reduce insurance liability for commercial carriers.
Technical Definition and Segments
Fleet management software denotes digital platforms that aggregate GPS positioning, engine diagnostics, fuel consumption metrics, and driver behavior data through onboard telematics units and mobile interfaces to optimize vehicle utilization and regulatory compliance. Cloud-based deployment leads solution uptake because operators avoid capital-intensive server infrastructure while gaining elastic compute for seasonal fleet scaling. Vehicle tracking and route optimization represent mature, high-volume segments where margin pools have compressed; AI-driven analytics within integration-level offerings captures expanding value as predictive maintenance commands premium pricing. Driver behavior monitoring grows fastest among solution types as insurers tie premiums to telematics-verified safety scores.
Regulatory Frame
The EPA enforces greenhouse gas emissions standards for medium- and heavy-duty vehicles that compel fleet operators to deploy fuel management and idling-reduction software. The Federal Motor Carrier Safety Administration's ELD mandate locks in baseline telematics penetration, while the EU Green Deal's Fit for 55 package extends carbon reporting obligations to commercial road transport across member states. Stakeholders must monitor how emerging AI liability frameworks reshape vendor accountability for automated routing decisions.
Market Dynamics
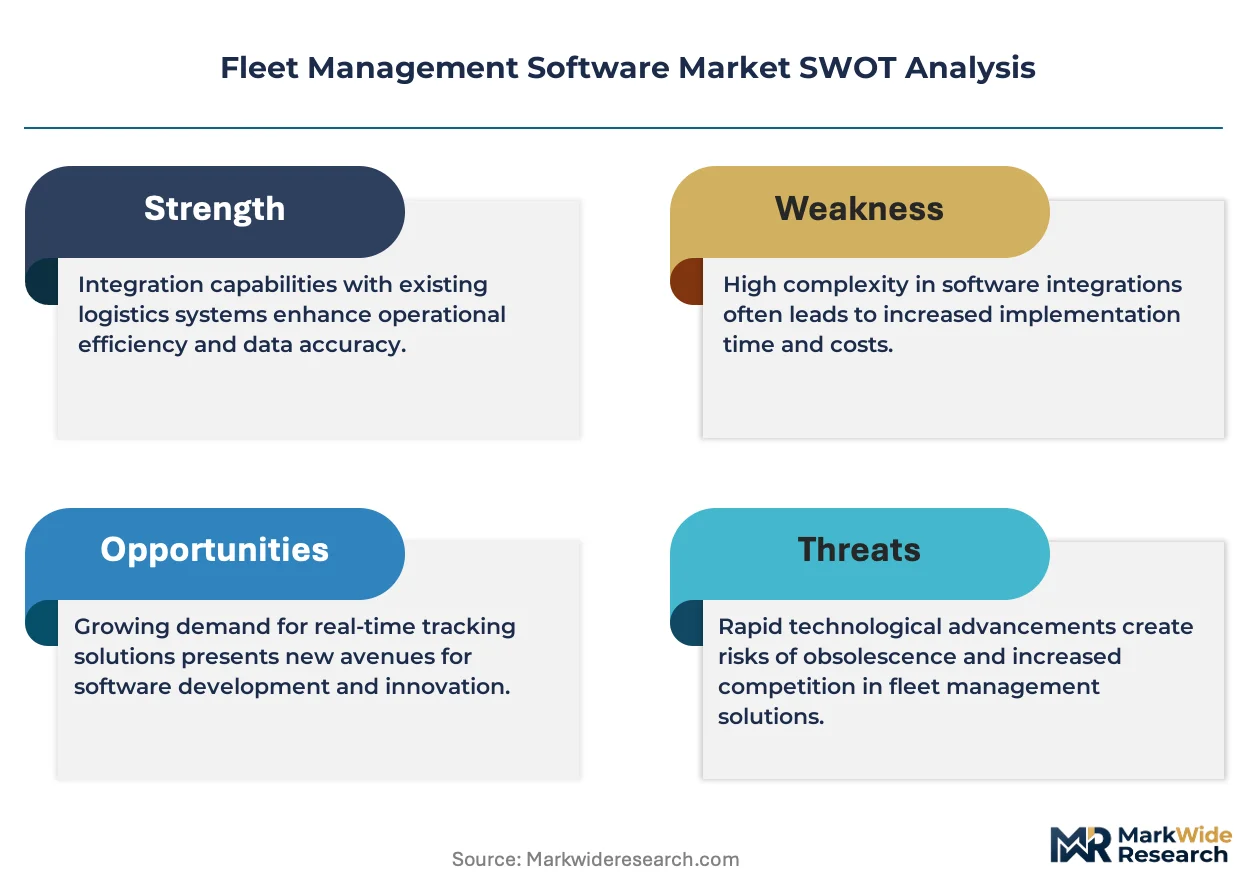
Fleet operators face a structural imperative to unify fragmented telematics, compliance, and maintenance systems under single-platform architectures as ELD mandates and emissions rules harden data requirements.
Growth Catalysts
- EPA greenhouse gas standards:Medium- and heavy-duty fleet operators in the United States must deploy fuel optimization software to meet tightening emissions thresholds, forcing baseline platform adoption.
- Last-mile delivery complexity:E-commerce logistics providers require dynamic route optimization to manage same-day delivery windows and driver scheduling density.
- AI-powered dashcam systems:Commercial carriers adopt computer-vision safety tools to qualify for telematics-verified insurance premium reductions.
Market Restraints
- Cloud infrastructure concentration:Three hyperscale providers dominate backend hosting for fleet SaaS, creating single-point vulnerability for operator data continuity.
- Telematics hardware commoditization:OBD-II dongle margins have compressed below sustainable levels, forcing software vendors to absorb hardware subsidy costs.
- Lithium battery supply volatility:Electric fleet conversion timelines depend on cell chemistry cost stability that mining concentration in Chile and Australia undermines.
Strategic Opportunities
- India logistics digitization:National highway corridor modernization and GST compliance requirements create first-mover advantage for integrated fleet platforms in refrigerated transport.
- EU Green Deal Fit for 55:Carbon reporting obligations for commercial road transport mandate emissions tracking software across member state fleets.
- Edge-AI convergence with 5G:Low-latency vehicle-to-infrastructure communication enables real-time predictive maintenance alerts without cloud round-trip delays.
Industry Challenges
- Embedded systems integration:Legacy fleet management platforms require costly API redevelopment to connect with modern IoT sensor networks and third-party logistics software.
- Telematics data science talent:Shortage of engineers capable of building predictive models from noisy vehicle diagnostic streams delays AI feature deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fleet Management Software Market |
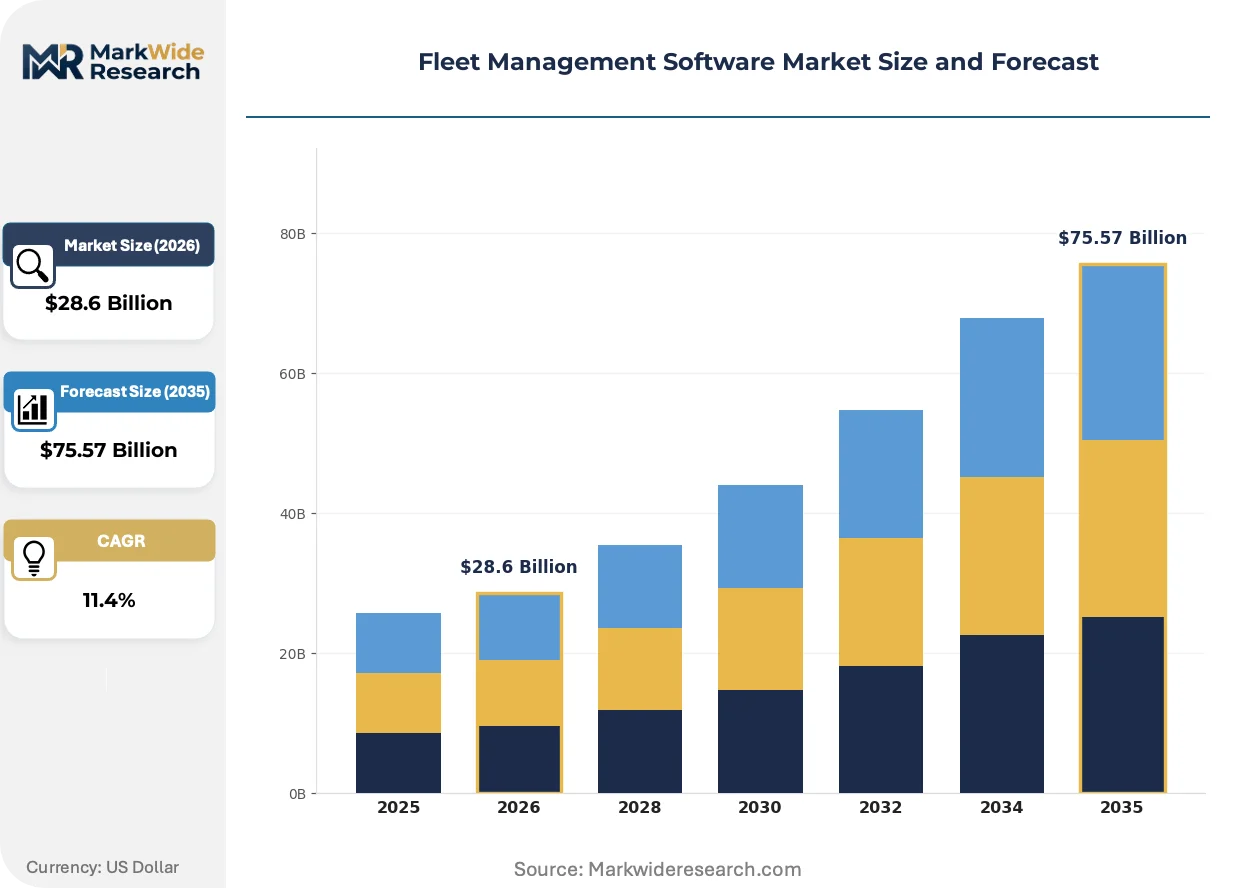
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Type: Vehicle Tracking, Route Optimization, Driver Behavior Monitoring, Fuel Management, Maintenance Scheduling End User Industry: Logistics Providers, Construction Firms, Public Transportation Authorities, Delivery Services Integration Level: Basic API, Advanced Telematics, IoT Connectivity, AI-Driven Analytics |
| Companies Covered | Fleetio, Motive, Samsara, Webfleet, RTA Fleet360, Geotab, Teletrac Navman, ABAX, Verizon Connect, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fleet Management Software Market Strategic Shifts & Innovations
Edge computing architectures and open-platform telematics standards are redistributing data processing authority away from centralized cloud hubs toward vehicle-level intelligence.
Blockchain-based vehicle identity verification is decentralizing trust in multi-party logistics networks. Refrigerated transport operators in Europe adopt distributed ledger systems to share temperature compliance records across cold-chain handoffs without intermediary data brokers. This architecture compresses audit timelines from days to minutes while eliminating disputes over custody transfer documentation.
The EU AI Act's risk classification framework imposes documentation and human-oversight requirements on automated routing algorithms that make safety-critical decisions. Fleet software vendors must redesign machine-learning pipelines to maintain explainability logs for each dispatch recommendation. Commercial carriers operating cross-border routes face compliance complexity as member states implement divergent national guidance on algorithmic accountability.
Subscription-based fleet intelligence services displace perpetual-license pricing among mid-sized logistics operators. Third-party logistics providers in Germany and the Netherlands favor usage-scaled SaaS contracts that align software costs with seasonal fleet utilization rather than fixed asset bases. This shift compresses vendor cash conversion cycles while accelerating platform switching as operators test competitive alternatives without capital commitment.
Fleet Management Software Market Segmentation
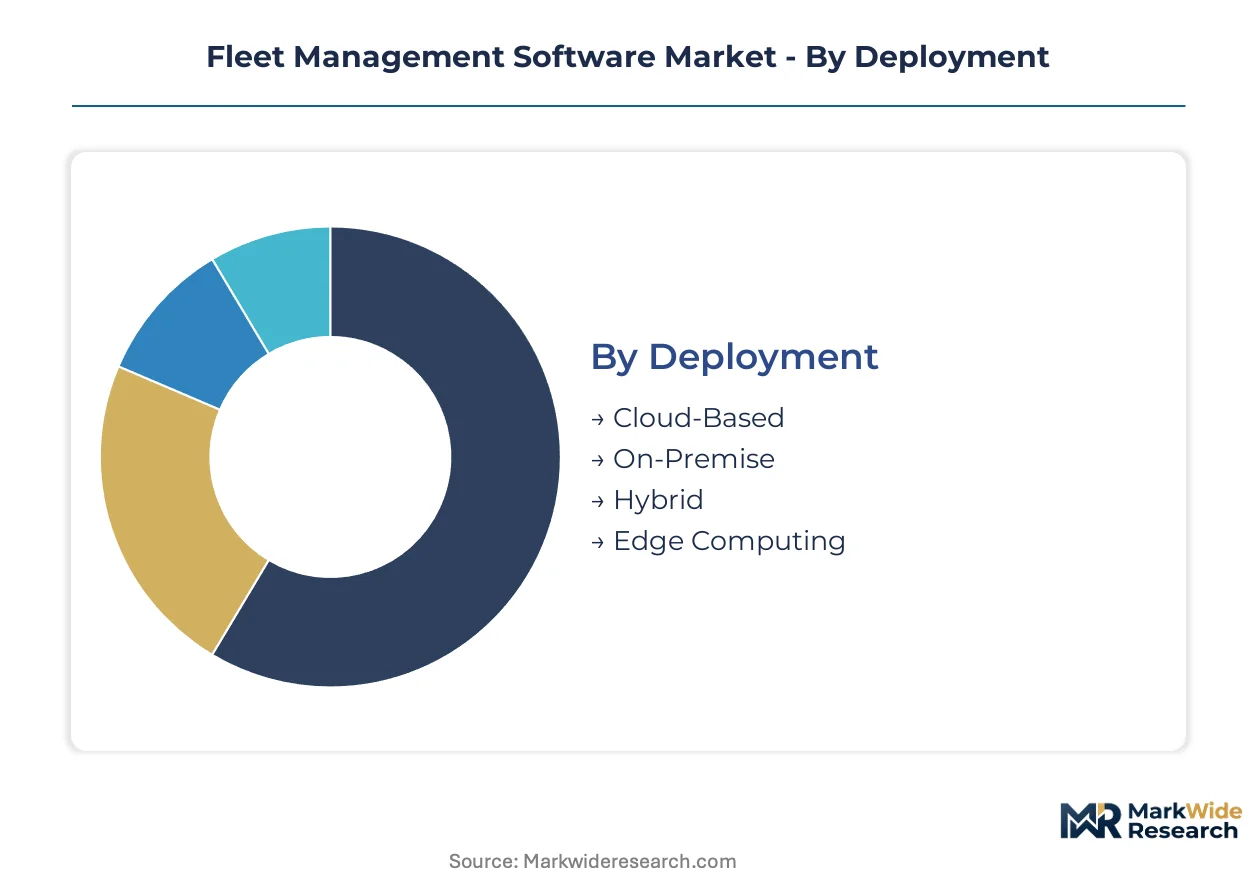
Fleet operators select software configurations based on fleet scale, regulatory exposure, and data sovereignty requirements. Deployment architecture and solution depth determine total cost of ownership and integration complexity across vehicle classes.
Deployment:
Customization versus standardization tension peaks in deployment choice, as operators balance elastic scaling needs against data residency mandates and latency requirements.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server capital expenditure while providing automatic updates and seasonal capacity scaling. Logistics providers in Germany and the Netherlands favor usage-scaled contracts that align software costs with fleet utilization cycles rather than fixed asset bases.
- On-Premise:Dedicated server installations within operator facilities satisfy data sovereignty requirements and air-gapped security protocols. Defense contractors and government fleet operators in the United States mandate on-premise deployments to comply with federal cybersecurity frameworks.
- Hybrid:Split architectures process sensitive compliance data locally while pushing analytics workloads to public cloud infrastructure. Construction firms with dispersed job sites deploy hybrid models to maintain operations during connectivity outages.
- Edge Computing:Vehicle-level processing units execute real-time decisions without cloud round-trip delays. Refrigerated transport operators adopt edge architectures for instantaneous temperature threshold alerts during cold-chain handoffs.
Leading the category by volume: Cloud-Based. Expanding most quickly: Edge Computing.
Solution Type:
Application maturity varies sharply across solution types, with established tracking functions competing against emerging AI-powered safety modules for platform investment priority.
- Vehicle Tracking:GPS positioning combined with geofencing and historical route replay forms the baseline capability in fleet platforms. Margin pools have compressed as telematics hardware commoditizes and basic tracking becomes table stakes.
- Route Optimization:Algorithmic dispatch systems calculate multi-stop sequences accounting for traffic patterns, delivery windows, and vehicle capacity constraints. E-commerce logistics providers in the United States deploy dynamic optimization to manage same-day delivery density and driver scheduling complexity.
- Driver Behavior Monitoring:Accelerometer data and computer-vision dashcam analysis score harsh braking, speeding, and distraction events. Commercial carriers adopt these tools to qualify for telematics-verified insurance premium reductions.
- Fuel Management:Idling detection, route efficiency scoring, and alternative fuel tracking support EPA greenhouse gas compliance mandates. Medium- and heavy-duty fleet operators deploy fuel optimization software to meet tightening emissions thresholds.
- Maintenance Scheduling:Predictive algorithms flag component degradation patterns from engine diagnostic streams before failure occurrence. AI-driven predictive maintenance commands premium pricing as operators quantify downtime cost avoidance.
Highest revenue concentration: Vehicle Tracking. Gaining share fastest: Driver Behavior Monitoring.
End User Industry:
Customer type segmentation reveals divergent purchasing criteria, with compliance-driven public sector procurement contrasting against margin-sensitive private fleet economics.
- Logistics Providers:Third-party and fourth-party logistics operators require multi-tenant platforms supporting heterogeneous fleet mixes and shipper-specific reporting portals. Cloud-native architectures dominate as 3PLs avoid capital-intensive infrastructure investments.
- Construction Firms:Heavy equipment tracking and unauthorized use alerts protect high-value asset fleets across dispersed project sites. Telematics adoption lags other sectors due to equipment replacement cycles and fragmented operator sophistication.
- Public Transportation Authorities:Municipal and regional transit agencies mandate open data standards and accessibility compliance in procurement specifications. Federal transit administration grants in the United States accelerate platform modernization timelines.
- Delivery Services:Last-mile operators prioritize dynamic routing and proof-of-delivery capture over long-haul fuel optimization. Same-day delivery density requirements in urban United States markets drive adoption of real-time dispatch algorithms.
Dominant purchaser by fleet count: Logistics Providers. Steepest adoption trajectory: Delivery Services.
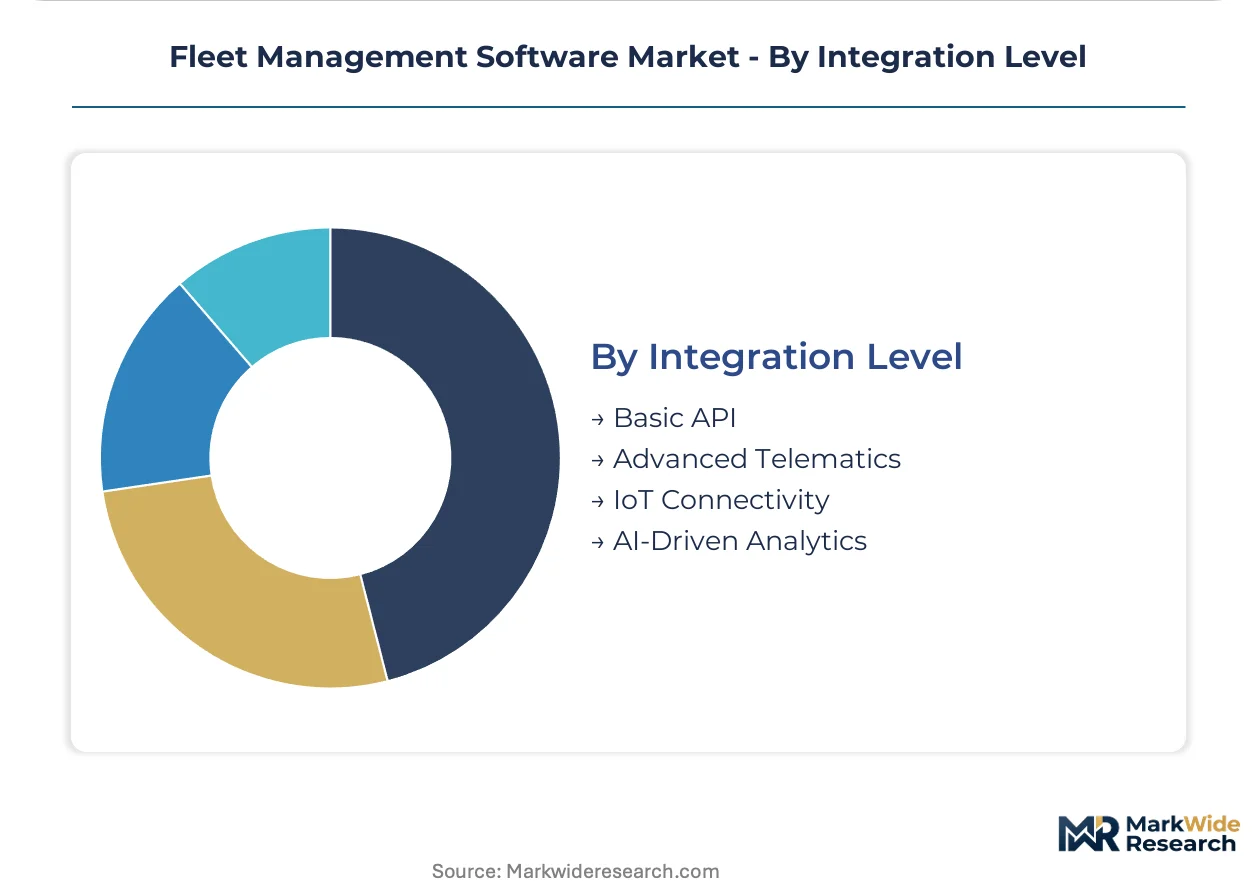
Integration Level:
Technical depth stratification determines platform switching costs and vendor lock-in intensity, with basic connectivity giving way to predictive intelligence layers.
- Basic API:Standardized data exchange protocols enable rudimentary connectivity between telematics hardware and back-office systems. Smaller operators deploy basic APIs as entry points before committing to platform consolidation investments.
- Advanced Telematics:Bidirectional communication channels support remote diagnostics, firmware updates, and parameter configuration from centralized dashboards. Open-platform vendors anchor market position through third-party developer ecosystems extending core functionality.
- IoT Connectivity:Sensor network integration captures cargo condition, trailer utilization, and environmental parameters beyond standard vehicle telemetry. Refrigerated transport operators deploy IoT layers for temperature compliance documentation across cold-chain custody transfers.
- AI-Driven Analytics:Machine learning pipelines transform noisy diagnostic streams into predictive maintenance alerts and driver risk scoring. The EU AI Act imposes documentation and human-oversight requirements on automated routing algorithms making safety-critical decisions.
Widest installed base: Advanced Telematics. Climbing the fastest: AI-Driven Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones and logistics corridor incentives concentrate fleet software demand in specific national markets. EPA mandates in the United States, ELD compliance deadlines, and EU carbon reporting rules create regulatory-driven procurement windows. Industrial clusters in Germany, China, and the United States anchor platform deployment.
United States
Third-party logistics providers in California and Texas deploy cloud-native platforms to manage cross-border freight density. The Federal Motor Carrier Safety Administration's ELD mandate locks in baseline telematics penetration for interstate carriers. The Inland Empire logistics cluster east of Los Angeles drives real-time visibility adoption for port-to-warehouse drayage operations.
Germany
Automotive suppliers and heavy freight operators in Bavaria and Baden-Württemberg prioritize predictive maintenance modules. The EU Green Deal's Fit for 55 package extends carbon reporting obligations to commercial road transport across member states. The Rhine-Alpine logistics corridor between Rotterdam and Milan anchors telematics deployment for multimodal freight coordination.
China
E-commerce logistics networks in the Yangtze River Delta and Pearl River Delta require dynamic route optimization for same-day delivery density. MIIT telematics standards and dual carbon goals compel fleet digitization in commercial road transport. The Shanghai logistics hub drives adoption of integrated platforms connecting port operations with inland distribution centers.
India
National highway corridor modernization and GST compliance requirements create first-mover opportunity for integrated fleet platforms. The Ministry of Road Transport and Highways mandates GPS-based vehicle tracking for commercial freight under AIS-140 standards. The Delhi-Mumbai Industrial Corridor anchors cold-chain telematics deployment for pharmaceutical and agricultural distribution.
Fleet Management Software Market Key Industry Players
Top-tier vendors anchor the integrated-platform tier, while specialized dashcam and compliance-tool providers occupy adjacent niches. The vendor base stratifies across three layers: full-stack IoT-native platforms, open-telemetry middleware specialists, and hardware-anchored point solutions. Two strategic archetypes dominate: cloud-native challengers with AI-first architectures and legacy telematics incumbents extending through API ecosystems. Competitive moves concentrate on M&A for sensor-network capabilities and strategic partnerships with insurance underwriters for telematics-verified premium programs.
Within the IoT-native platform tier, Samsara and Motive exemplify the computer-vision and real-time visibility archetype. Geotab anchors the open-platform middleware position through third-party developer ecosystems. Among specialized compliance vendors, Fleetio occupies a position serving mid-sized operators with subscription-scaled deployment models.
| Leading Market Players |
|---|
| Fleetio |
| Motive |
| Samsara |
| Webfleet |
| RTA Fleet360 |
| Geotab |
| Teletrac Navman |
| ABAX |
| Verizon Connect |
| Others |
Cost & Logistics Intelligence
Telematics hardware component costs cascade through fleet software pricing tiers as OBD-II dongle commoditization compresses margins at the entry level and forces vendors to absorb hardware subsidies in SaaS bundles. Cloud infrastructure concentration among three hyperscale providers concentrates backend cost leverage, while seasonal fleet scaling demands push mid-sized operators toward usage-scaled contracts that align payments with utilization cycles rather than fixed asset bases.
Pricing Analysis
Short lead-time deployment premiums distinguish urgent implementations from standard onboarding schedules in fleet software procurement. Three-tier pricing structure across premium, standard, and economy levels segments buyers by integration depth, with AI-driven analytics and predictive maintenance commanding top-tier positioning. Cost compression in the hardware-anchored entry tier is intensifying because OBD-II dongle margins have collapsed below sustainable thresholds. Small fleet operators exhibit highest price sensitivity, while enterprise logistics providers prioritize total cost of ownership over upfront licensing.
Supply Chain Analysis
Semiconductor supply for telematics control units rests on Taiwanese foundry capacity and South Korean memory fabrication, with Chinese contract manufacturers dominating final device assembly. Lithium cell chemistry for electric fleet conversion draws from Chilean mining operations and Australian hard-rock extraction, while GPS module production centers on Chinese and Taiwanese component suppliers. Single-source vulnerability in rare earth processing creates chokepoint exposure for magnetic sensor inputs. Distribution runs through direct vendor sales teams serving enterprise accounts and value-added resellers targeting mid-market operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet management software has become a vertical-integration race as vendors pursue captive control over sensor hardware manufacturing to escape commodity margin traps and differentiate through proprietary data pipelines.
For Market Incumbents: Lock in platform consolidation momentum by acquiring specialized dashcam and cold-chain sensor developers before competitors capture insurance partnership channels. The threat of open-platform middleware specialists eroding integration depth demands defensive API ecosystem expansion. Backward integration into telematics hardware production preserves margin pools that OBD-II commoditization is destroying. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass incumbent vendor relationships and enable rapid pilot-to-contract conversion for cloud-native challengers. India's refrigerated transport digitization under AIS-140 mandates represents the most penetrable geography, with GST compliance complexity creating urgent demand for integrated platforms. Freemium driver safety scoring tools build data assets that qualify operators for telematics-verified insurance programs. For Investors and Strategic Acquirers: Distressed-cycle entries favor IoT-native platform specialists with proven insurance underwriter partnerships in the United States and Germany. Long-term viability hinges on AI feature deployment velocity and edge computing architecture readiness. The signal to watch is ELD mandate enforcement intensity in emerging markets, which would accelerate baseline telematics penetration and expand addressable fleet counts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies fragmented telematics, compliance, and maintenance systems under single-architecture control. |
| Strategic Partnership | Insurance underwriter collaborations monetize driver behavior data through premium reduction programs. |
| Acquisition of Specialist Firm | Computer-vision dashcam developers add AI-powered safety modules to core fleet platforms. |
| Geographic Expansion | India's highway corridor modernization and GST compliance create first-mover positioning opportunity. |
| Product Launch | Edge-AI predictive maintenance alerts differentiate offerings from cloud-dependent competitors. |
Research Approach
Independent corroboration across fleet operator interviews, telematics vendor disclosures, and regulatory filing databases underwrites the qualitative findings in this study. Primary fieldwork engaged fleet managers at third-party logistics providers, compliance officers at commercial carriers, platform engineers at SaaS vendors, and insurance underwriters developing telematics-verified premium programs. Secondary validation drew from EPA emissions enforcement records, FMCSA ELD mandate compliance data, EU Green Deal implementation guidance, and SEC filings of publicly traded fleet technology providers. Bottom-up fleet count modeling and top-down software spend estimates triangulate market sizing.
Rate-of-change decomposition separates baseline telematics penetration from AI-driven analytics expansion and edge computing migration across the analysis window. Segmentation dimensions include deployment architecture, solution type depth, end-user industry vertical, and integration complexity tier. CAGRs derive from logistic curve fitting of adoption saturation patterns and elasticity-adjusted pricing trajectories. Forecast inputs incorporate ELD mandate enforcement schedules, EPA greenhouse gas threshold tightening timelines, and electric fleet conversion capital allocation surveys.
The model holds under steady regulatory enforcement and cloud infrastructure cost stability; deviation in lithium supply disruption or AI liability framework divergence would shift conversion timelines and vendor accountability costs. Forecasts reflect documented assumptions about telematics hardware commoditization velocity and insurance partnership program expansion. A small set of named triggers warrants ongoing watch: EU AI Act implementation guidance, India AIS-140 enforcement intensity, and hyperscale cloud provider market concentration policy responses.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Long Haul Solutions Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Indonesia Ride Hailing Market
Smart Transportation Solutions
Fleet Management Solution Market
Smart Transportation Solutions
Global IoT Fleet Management Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
Automated Parking Systems Market
Smart Transportation Solutions
Rail Freight Digital Transformation Market
Smart Transportation Solutions
Smart Parking Technologies Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Shared Mobility Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Personal Transporter Market
Smart Transportation Solutions
Ride-Hailing Market
Smart Transportation Solutions
Contactless Ticketing Market