
 China Controllable Pitch Marine Propeller Market | 2026-2036
China Controllable Pitch Marine Propeller Market Size, Share, and Industry Trends Forecast 2026-2036
China Controllable Pitch Marine Propeller Market Outlook
A capital-intensity divergence between integrated foundry operators and assembly-focused suppliers is redrawing competitive boundaries in China's controllable pitch marine propeller sector. Zhenjiang Supersoar Marine Machinery Co Ltd leverages in-house nickel-aluminum-bronze casting to control material quality and delivery timelines. UC Marine (China) Company Limited anchors its position through deep relationships with state-owned shipyards along the Yangtze River delta.
A controllable pitch marine propeller incorporates hydraulically actuated blade mechanisms that permit real-time adjustment of pitch angle, typically machined from nickel-aluminum-bronze alloys to resist cavitation erosion in saltwater environments. Its primary purpose is to optimize thrust efficiency across varying load conditions without changing shaft rotational speed. Controllable pitch systems dominate new construction installations for commercial shipping fleets requiring maneuverability in constrained waterways. Retrofit demand accelerates as aging fishing vessel fleets face escalating fuel costs and emissions compliance deadlines.
China's Ministry of Ecology and Environment enforces marine emissions standards that tighten permissible sulfur oxide and nitrogen oxide outputs, directly elevating demand for pitch-optimized propulsion systems that reduce engine load variability. GB standards administered by SAMR specify material composition and dimensional tolerances for propeller castings, creating certification barriers for uncertified imports. Stakeholders must monitor how dual carbon goals reshape shipyard procurement mandates and whether domestic foundry capacity expansion keeps pace with naval and commercial order backlogs.
Market Dynamics
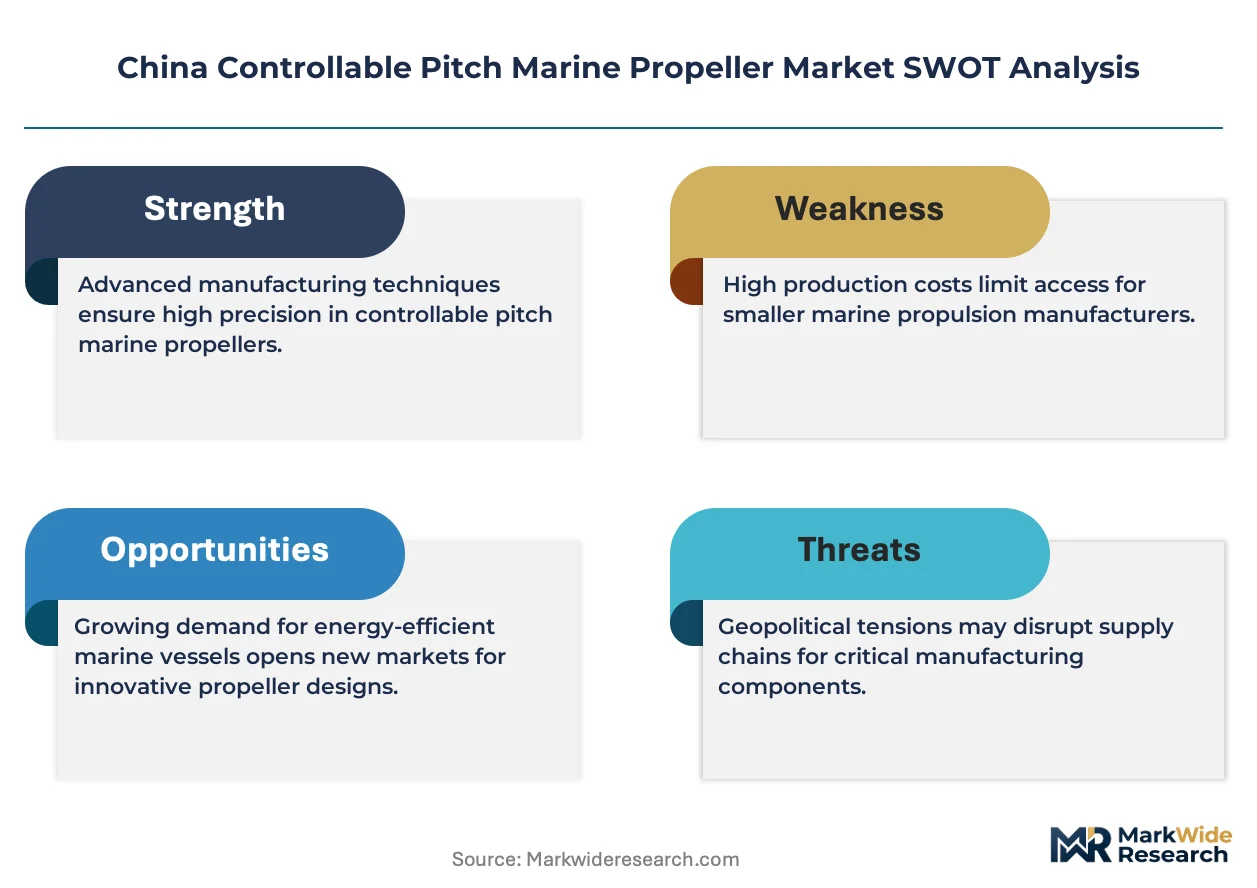
China's controllable pitch marine propeller sector faces a structural squeeze between MEE emissions mandates tightening engine efficiency requirements and foundry capacity constraints limiting nickel-aluminum-bronze alloy supply to Jiangsu and Zhejiang shipyard clusters.
Growth Catalysts
- Marine emissions enforcement:MEE sulfur oxide and nitrogen oxide standards force commercial fleets to retrofit pitch-optimized systems that reduce engine load variability during port maneuvering.
- Nickel-aluminum-bronze casting advances:Improved foundry techniques in Yangtze River delta clusters yield cavitation-resistant blade alloys with tighter dimensional tolerances under SAMR GB standards.
- Fishing fleet renewal:Aging coastal vessels in Shandong and Fujian provinces face fuel cost pressures that accelerate replacement of fixed-pitch systems with controllable pitch alternatives.
Market Restraints
- Copper-nickel alloy price volatility:Raw material costs for nickel-aluminum-bronze fluctuate with global commodity markets, compressing margins for assembly-focused suppliers lacking captive foundry capacity.
- Foundry concentration risk:Over 60% of certified casting output originates from Jiangsu province, creating geographic vulnerability to regional power rationing or environmental shutdowns.
- Hydraulic system complexity:Oil-sealed hub mechanisms require precision machining tolerances that exceed capabilities of smaller tier-two suppliers, limiting viable vendor pools.
Strategic Opportunities
- Inland waterway electrification pilots:Dual carbon goals fund battery-hybrid propulsion trials on Yangtze River cargo routes, opening demand for pitch systems optimized for variable electric motor torque.
- Naval procurement expansion:People's Liberation Army Navy surface vessel programs specify controllable pitch configurations for littoral maneuverability, creating qualified supplier preference lists.
- Smart propulsion integration:Convergence of blade angle sensors with vessel performance analytics enables real-time efficiency optimization, attracting state-owned shipping lines seeking operational data advantages.
Industry Challenges
- Certified welder scarcity:Nickel-aluminum-bronze fusion welding for blade repair requires specialized qualifications that outpace vocational training output in coastal provinces.
- GB standard compliance timelines:SAMR dimensional tolerance updates demand recertification cycles that delay new product introductions by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Controllable Pitch Marine Propeller Market |
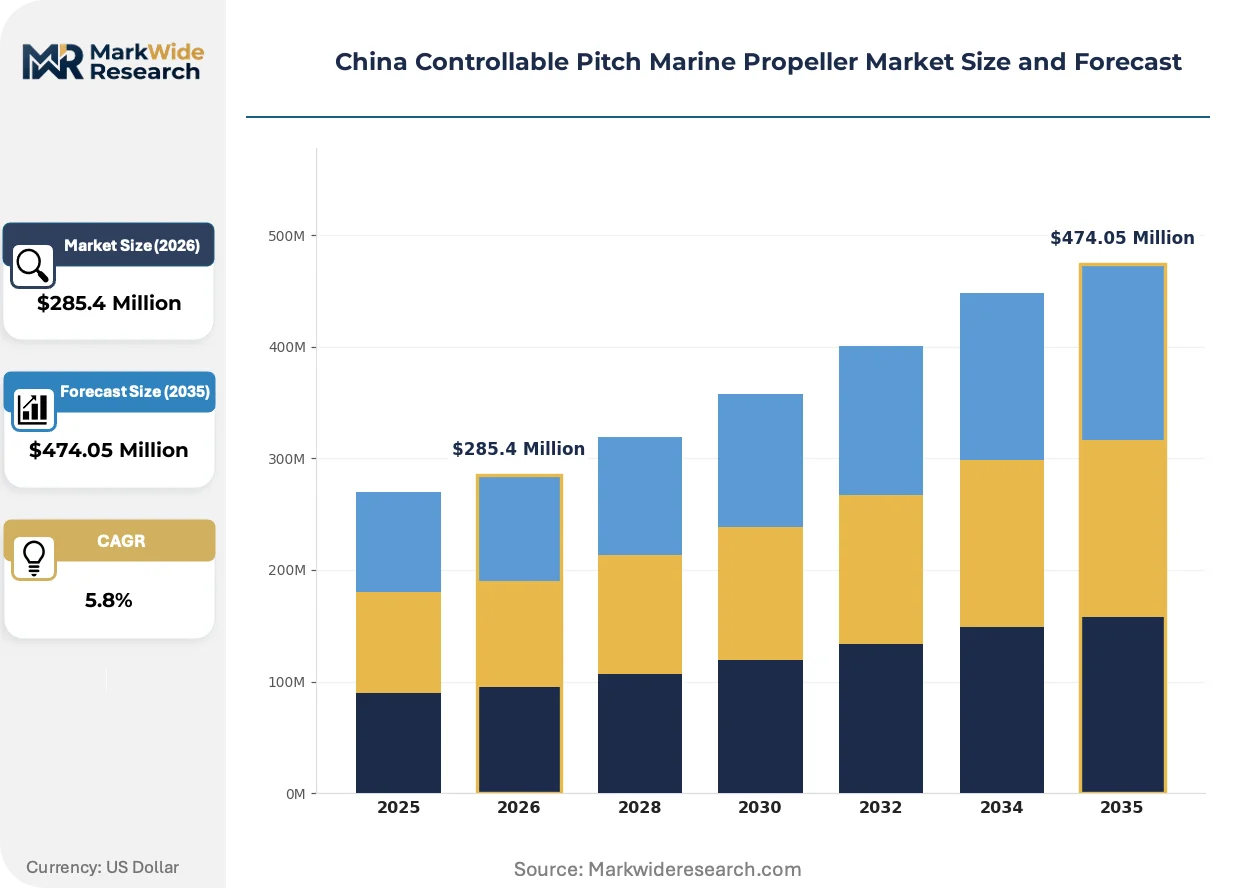
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Pitch, Controllable Pitch, Ducted Propeller, Azimuth Thruster End User: Commercial Shipping, Fishing Vessels, Recreational Boats, Military Crafts Application: Deep Sea, Inland Waterways, Offshore Operations, Naval Applications Installation Type: Retrofit, New Construction, Modular, Custom Installations |
| Companies Covered | Zhenjiang Supersoar Marine Machinery Co Ltd, UC Marine (China) Company Limited, China Deyuan Marine Fitting Co Ltd, Hyundai Heavy Industries Co Ltd, Chongqing Hi-Sea Marine Equipment Import & Export Co Ltd, Chongqing Jeri Marine Equipment Co Ltd, Chongqing Acir Marine Co Ltd, MAN Energy Solutions, Dalian Marine Propeller Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Controllable Pitch Marine Propeller Market Strategic Shifts
Digital blade monitoring systems and hybrid-electric compatibility requirements are redefining procurement specifications across China's commercial and naval vessel programs. Manufacturers must now engineer for data connectivity alongside mechanical reliability.
Additive manufacturing of nickel-aluminum-bronze propeller components is fragmenting traditional foundry-dominated supply structures. Selective laser melting enables complex internal cooling channels for high-performance naval applications. State-owned research institutes in Shanghai and Wuhan are piloting these techniques for prototype blade production. The technology is compressing lead times for custom geometries while creating parallel qualification pathways outside conventional casting certification.
MEE marine emissions standards are tightening enforcement protocols for sulfur oxide monitoring in coastal control zones. Ship operators now face real-time reporting requirements that elevate pitch system precision demands for fuel optimization. Commercial fleets operating between Qingdao and Shanghai are retrofitting controllable pitch systems to maintain compliance without engine replacement.
Buyer consolidation among state-owned shipping groups is concentrating procurement authority at headquarters level rather than individual shipyard discretion. Long-term framework agreements with approved vendor lists are displacing spot purchasing for fleet-wide standardization. This pattern is most visible in COSCO and China Merchants Energy Shipping procurement departments, where technical specifications now prioritize interoperability across vessel classes over unit cost minimization.
China Controllable Pitch Marine Propeller Market Segmentation
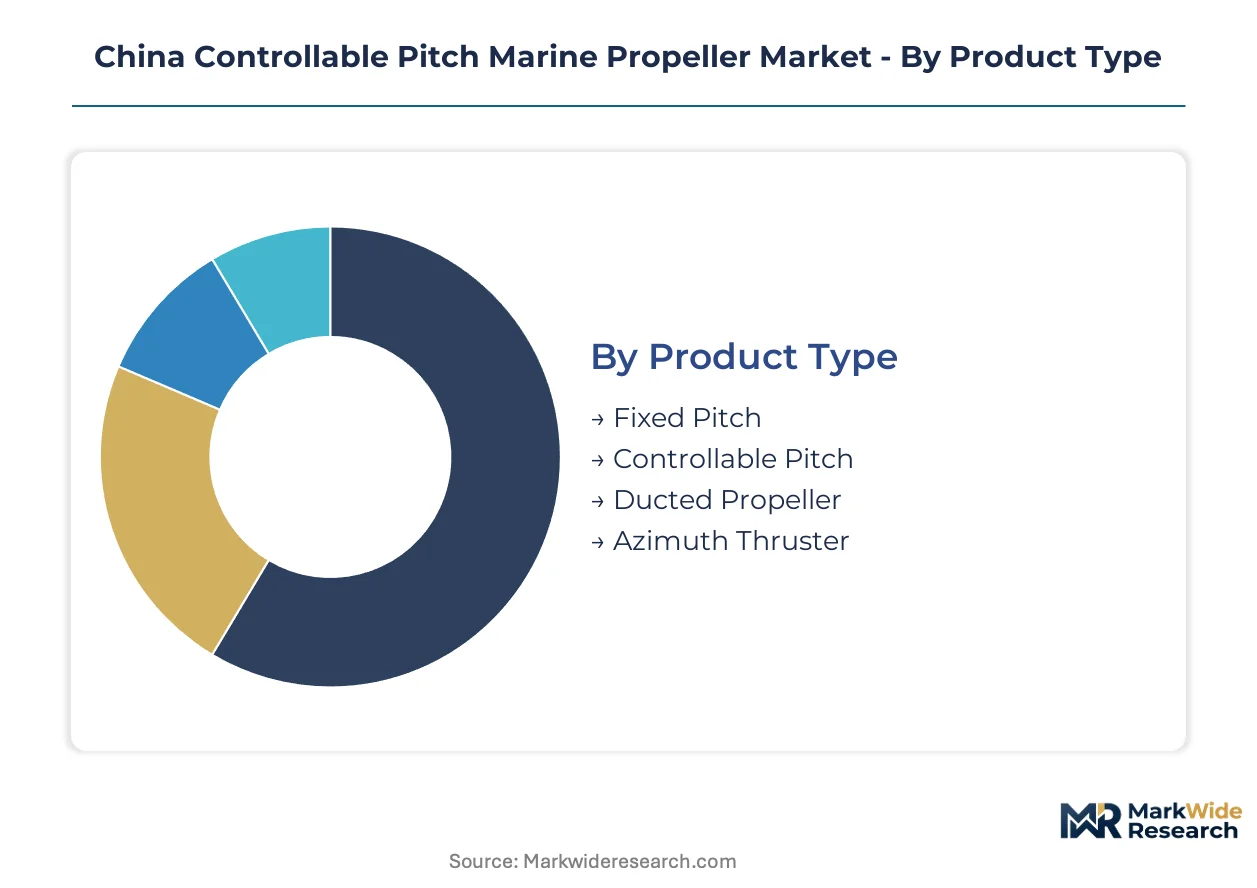
Controllable pitch propeller procurement in China splits across distinct technical specifications, vessel categories, and installation contexts. Each segmentation dimension carries different margin profiles, certification requirements, and channel access patterns that shape supplier strategy.
Product Type:
Channel distribution varies sharply by product complexity, with integrated foundry-to-assembly suppliers capturing premium controllable pitch and azimuth thruster contracts while distributors handle simpler fixed-pitch volumes.
- Fixed Pitch:Simple cast-blade designs with no hub mechanism dominate coastal fishing fleet replacements and small cargo vessels. Demand concentrates in Shandong and Fujian provinces where vessel owners prioritize upfront cost over fuel optimization.
- Controllable Pitch:Hydraulically actuated hub systems machined from nickel-aluminum-bronze alloys permit real-time blade angle adjustment. Jiangsu and Zhejiang shipyards specify these for new commercial builds facing MEE emissions compliance deadlines.
- Ducted Propeller:Shrouded configurations improve bollard pull efficiency for tugboats and harbor craft operating in constrained waterways.
- Azimuth Thruster:Podded units combining propulsion and steering functions serve offshore support vessels requiring dynamic positioning capability.
Controllable pitch systems dominate installed base in commercial shipping. Azimuth thrusters are where expansion concentrates for offshore and specialized vessel programs.
End User:
Customer type determines specification stringency, with military and state-owned commercial fleets imposing qualification barriers that exclude uncertified suppliers.
- Commercial Shipping:COSCO and China Merchants Energy Shipping fleets drive standardized procurement through headquarters-level framework agreements. Fuel efficiency mandates under MEE oversight accelerate retrofit programs on aging bulk carriers.
- Fishing Vessels:Coastal fleet renewal in Shandong, Fujian, and Guangdong provinces replaces fixed-pitch systems as diesel costs rise and emissions enforcement tightens in port control zones.
- Recreational Boats:Marina developments in Hainan and coastal resort cities generate demand for compact controllable pitch units in yacht segments.
- Military Crafts:People's Liberation Army Navy surface vessel programs specify controllable pitch configurations for littoral maneuverability, creating qualified supplier preference lists with multi-year procurement horizons.
Commercial shipping commands procurement volume. Military crafts are climbing the fastest in margin contribution due to qualification scarcity.
Application:
Operating environment dictates material specifications and hub sealing requirements, with saltwater exposure driving nickel-aluminum-bronze alloy selection across all marine categories.
- Deep Sea:Long-haul cargo routes require cavitation-resistant blade alloys and redundant hydraulic systems for transoceanic reliability. Yangtze River delta shipyards anchor production for export-bound vessels.
- Inland Waterways:Yangtze River cargo routes pilot battery-hybrid propulsion trials, opening demand for pitch systems optimized for variable electric motor torque profiles under dual carbon funding programs.
- Offshore Operations:Dynamic positioning requirements for drilling support vessels favor azimuth thruster configurations with integrated blade angle sensors.
- Naval Applications:Littoral combat and amphibious programs prioritize maneuverability over efficiency, specifying rapid-response pitch actuation systems.
Deep sea applications hold the largest installed base. Inland waterway electrification pilots are where technology transition concentrates.
Installation Type:
Project scope shapes supplier engagement models, with retrofits demanding rapid turnaround and dry-dock coordination while new construction permits longer lead times.
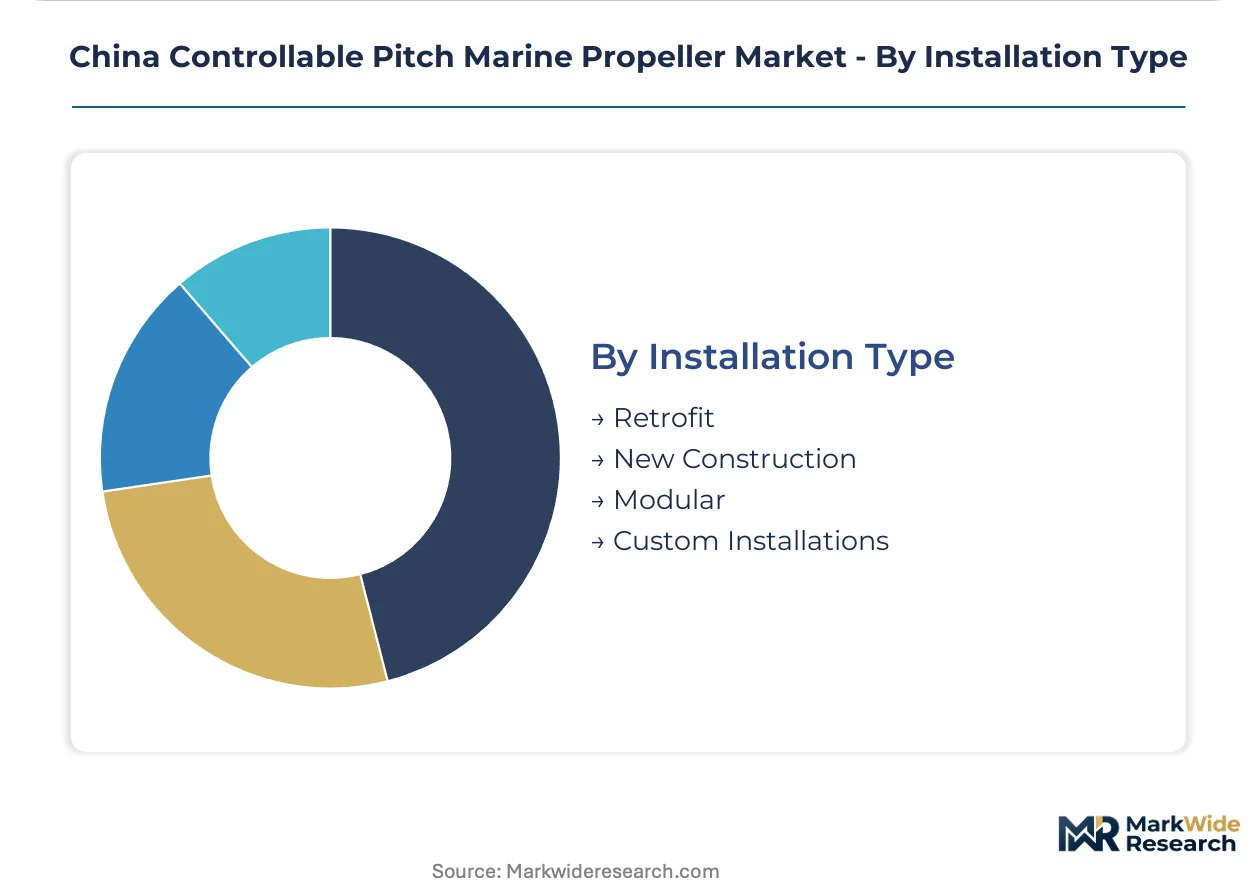
- Retrofit:Dry-dock blade and hub replacements on aging fleets face compressed timelines tied to port availability. SAMR GB standard recertification cycles delay component approvals by 8-14 months.
- New Construction:Greenfield shipyard builds allow integrated propulsion system design, with controllable pitch specifications locked at hull design stage.
- Modular:Pre-assembled hub and blade packages reduce yard labor requirements for mid-size vessel operators lacking specialized fitting capabilities.
- Custom Installations:Non-standard shaft configurations and specialized vessel geometries require foundry-level engineering engagement for one-off casting designs.
Retrofit installations dominate current revenue. New construction orders are where multi-year backlog stability concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Jiangsu and Zhejiang provinces where foundry-integrated suppliers command premiums, while Shandong and Fujian vessel owners absorb cost volatility through fixed-pitch legacy systems. This asymmetry shapes procurement patterns across China's coastal manufacturing belt.
Jiangsu Province
Yangtze River delta shipyards drive controllable pitch system demand for new commercial builds facing MEE emissions deadlines. SAMR GB standards for nickel-aluminum-bronze casting certification create entry barriers for uncertified imports. Zhenjiang anchors the foundry cluster where in-house casting capabilities control material quality and delivery timelines for integrated operators.
Zhejiang Province
Ningbo-Zhoushan port complex generates retrofit demand as aging bulk carriers seek fuel efficiency gains under tightening sulfur oxide monitoring. MEE coastal control zone enforcement elevates pitch precision requirements for real-time emissions compliance. Wenzhou and Taizhou shipyards concentrate procurement for fishing fleet renewal programs replacing fixed-pitch alternatives.
Shandong Province
Qingdao and Yantai fishing harbors face compressed margins from diesel cost pressures that accelerate fixed-pitch system obsolescence. Provincial maritime safety administration mandates drive vessel replacement cycles without equivalent foundry capacity for controllable pitch fabrication. Local operators rely on Jiangsu-Zhejiang supply chains for upgrade components.
Fujian Province
Xiamen and Fuzhou coastal fleets navigate stricter port control zone emissions protocols with limited regional propulsion manufacturing infrastructure. Dual carbon goal funding for inland waterway electrification pilots does not extend to deep-sea fishing vessel retrofits. Procurement authority concentrates through provincial fisheries cooperatives rather than individual vessel owner discretion.
Guangdong Province
Pearl River Delta marina developments in Shenzhen and Zhuhai generate demand for compact controllable pitch units in yacht segments. Guangzhou shipyards serve as distribution nodes for Jiangsu-manufactured systems rather than production centers. Naval procurement from South Sea Fleet littoral programs creates qualified supplier preference lists with multi-year horizons.
China Controllable Pitch Marine Propeller Market Competitive Environment
Concentration sits with foundry-integrated specialists who control nickel-aluminum-bronze casting capacity, while assembly-focused distributors compete on logistics proximity to shipyard clusters. The vendor base separates into three archetypes: captive foundry operators, Yangtze River delta-anchored system integrators, and component distributors serving provincial fisheries cooperatives. Dominant competitive moves include backward integration into alloy casting and strategic partnerships with state-owned shipping lines for fleet-wide framework agreements.
Within the foundry-integrated tier, Zhenjiang Supersoar Marine Machinery Co Ltd exemplifies upstream control over material quality and delivery timelines. UC Marine (China) Company Limited occupies a position among Yangtze River delta-anchored suppliers with deep relationships to state-owned shipyards. Hyundai Heavy Industries Co Ltd represents the multinational equipment fabricator archetype competing on naval and commercial vessel program scale.
| Leading Market Players |
|---|
| Zhenjiang Supersoar Marine Machinery Co Ltd |
| UC Marine (China) Company Limited |
| China Deyuan Marine Fitting Co Ltd |
| Hyundai Heavy Industries Co Ltd |
| Chongqing Hi-Sea Marine Equipment Import & Export Co Ltd |
| Chongqing Jeri Marine Equipment Co Ltd |
| Chongqing Acir Marine Co Ltd |
| MAN Energy Solutions |
| Dalian Marine Propeller Co Ltd |
| Others |
Value Chain & Pricing Dynamics
SAMR GB certification standards for nickel-aluminum-bronze casting simultaneously gate supplier entry and stratify price tiers, creating a dual-filter where uncertified imports face exclusion while qualified domestic foundries command configuration premiums. This regulatory architecture binds pricing power to metallurgical compliance, compressing margins for assembly-only operators who must absorb alloy volatility without captive casting capacity.
Pricing Analysis
Configured-to-order pricing for custom hub geometries and blade angle specifications commands substantial premiums over standard catalog configurations. Three-tier pricing structure across premium, standard, and economy levels separates foundry-integrated specialists with SAMR certification from assembly-focused distributors and uncertified imports. Cost compression in the economy tier is intensifying because Jiangsu foundry concentration limits bargaining leverage for smaller buyers. Coastal fishing cooperatives in Shandong and Fujian exhibit highest price sensitivity, while state-owned shipping lines prioritize interoperability over unit cost minimization.
Supply Chain Analysis
China anchors nickel-aluminum-bronze alloy production and precision machining capacity, with South Korea and Japan supplying high-grade nickel feedstock and specialized hydraulic actuator components. The supply chain draws from global copper-nickel commodity markets, precision bearing imports from Germany, and domestic Yangtze River delta foundry clusters. Single-source vulnerability concentrates in Jiangsu province where over sixty percent of certified casting output originates, exposing buyers to regional power rationing or environmental shutdowns. Distribution runs through state-owned shipyard procurement departments and provincial fisheries cooperatives rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory moat where SAMR certification entrenchment creates switching costs that lock qualified suppliers into multi-year naval and commercial framework agreements. Network effects compound as state-owned shipping lines standardize fleet-wide specifications around approved vendor lists.
For Market Incumbents: Secure backward integration into captive nickel-aluminum-bronze foundry capacity to defend against margin erosion from raw material volatility. Expand welding qualification programs to address certified repair technician scarcity before MEE emissions deadlines accelerate retrofit demand. Priority rests on locking long-term alloy offtake agreements with Yangtze River delta smelters.
For New Entrants and Emerging Players: Differentiate on additive manufacturing capabilities for prototype naval blade geometries outside conventional casting certification pathways. Target inland waterway electrification pilots under dual carbon funding where electric motor torque optimization requirements favor new engineering approaches. Go-to-market leverage sits with Shanghai and Wuhan research institute partnerships for qualification bypass.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid-electric compatible pitch systems requiring sensor integration and data connectivity investments. Viability over the medium-term projection horizon favors foundry-integrated mid-cap specialists with existing SAMR certification and naval supplier status. Acquisition target archetype: Jiangsu-Zhejiang operators with underutilized casting capacity and pending GB standard recertification. Signal to monitor: SAMR dimensional tolerance update implementation timelines and their compression of new product introduction cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | Upstream control over nickel-aluminum-bronze alloy quality insulates margins from commodity volatility. |
| Hybrid-Electric Pitch System Development | Yangtze River battery-hybrid pilots create qualified supplier preference for torque-optimized configurations. |
| SAMR GB Recertification Investment | Dimensional tolerance compliance maintains naval and commercial procurement eligibility under tightened standards. |
| Smart Propulsion Sensor Integration | Real-time blade angle analytics attract COSCO fleet-wide framework agreements seeking operational data advantages. |
| Certified Welder Training Programs | Specialized nickel-aluminum-bronze fusion qualifications address repair capacity bottlenecks before retrofit demand peaks. |
Study Parameters
Desk research of SAMR regulatory filings, MEE emissions enforcement protocols, and Yangtze River delta shipyard production databases preceded structured interviews with foundry operations managers, naval procurement officers, state-owned shipping line technical directors, and provincial fisheries cooperative buyers. Secondary validation incorporated customs trade records for nickel-aluminum-bronze alloy flows, GB standard certification registries, and dual carbon pilot program documentation. Bottom-up vessel fleet analysis and top-down propulsion system spend estimates were triangulated against foundry capacity utilization surveys.
Variance decomposition across product type, end user category, application environment, and installation context shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include propulsion system complexity tier, vessel class specification stringency, operating environment salinity exposure, and procurement channel concentration. CAGRs were derived from installed base turnover rates, MEE compliance deadline clustering, and alloy price trajectory scenarios. Industry-specific forecast inputs incorporated fishing fleet renewal cycles in Shandong and Fujian and naval surface vessel program acceleration under littoral maneuverability requirements.
The analysis sits within stated boundaries; outcomes outside sustained MEE enforcement intensity, stable nickel-copper alloy supply, and continued state-owned shipping consolidation would require recalibration. Forecasts reflect documented assumptions regarding GB standard implementation timelines and foundry capacity expansion trajectories. Specific risk factors include regional power rationing disrupting Jiangsu casting output, SAMR recertification delays compressing new product introductions, and alternative propulsion technologies displacing mechanical pitch systems in inland waterway segments. Recalibration cycles align with material shifts in MEE enforcement protocols, dual carbon funding allocations, and naval procurement program announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Electric Boat Market
Marine
Marine Airbags Market
Marine
Marine Auxiliary Engine Market
Marine
Marine and Marine Management Software Market
Marine
Asia-Pacific Marine Communication Systems Market
Marine
Europe Marine Communication Systems Market
Marine
Boat Control Lever Market
Marine
India Boat Davits Market
Marine
Jet Boat Market
Marine
Flap Rudder Market
Marine
Marine Elevators Market
Marine
Steel Ship Plate Market
Marine
Military Marine Engine Market
Marine
Boat Console Market
Marine
Sailboat Market
Marine
Marine Pipes Market