
 Autonomous Navigation Sensing System Market | 2026-2036
Autonomous Navigation Sensing System Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Navigation Sensing System Market Analysis
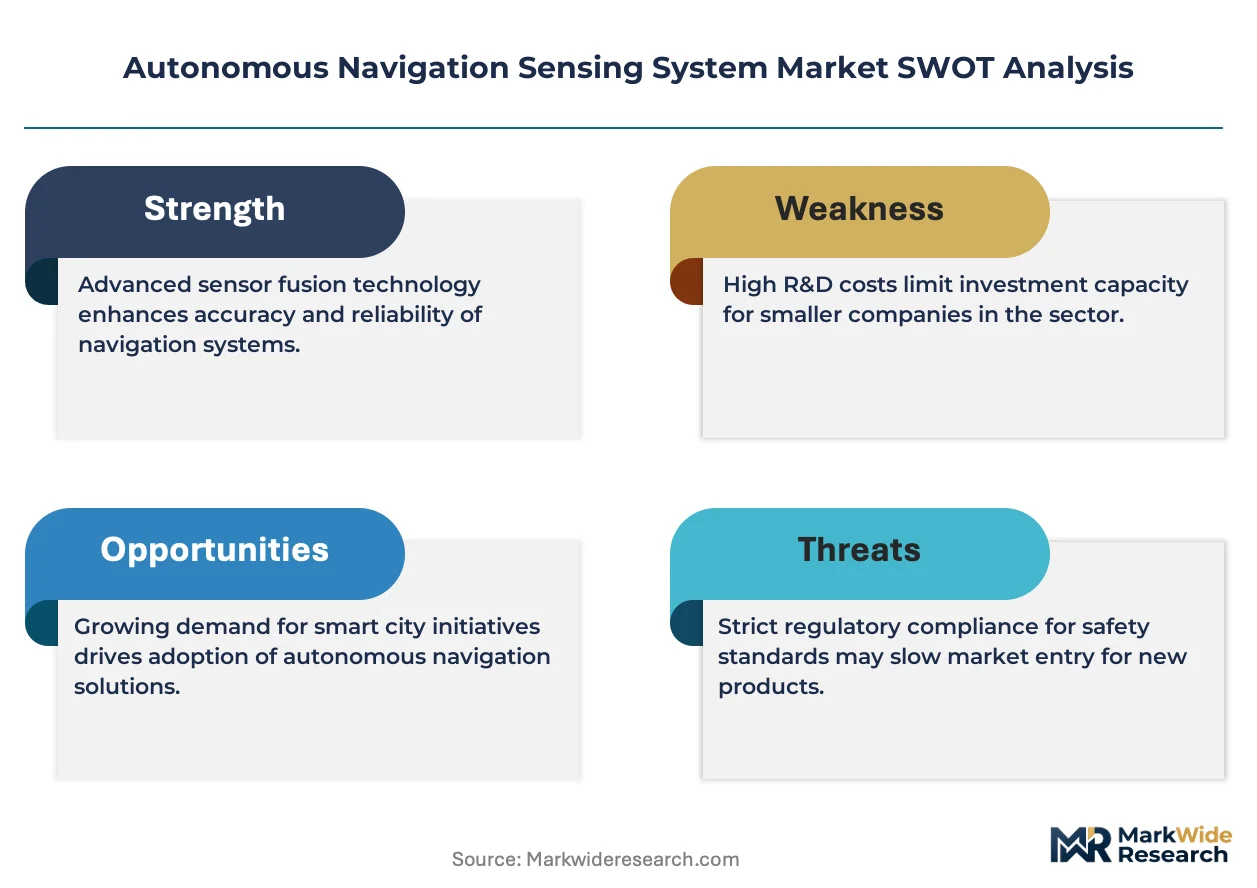
EU AI Act compliance is decoupling hardware certification from software validation, raising engineering costs for new entrants. Honeywell International leverages its aerospace sensor heritage to anchor defense contracts across NATO-aligned programs. BAE Systems competes through in-house production of gallium nitride radar components, sustaining margin control against commercial chip shortages. RTX Corporation dominates naval autonomous navigation, where salt-hardened lidar arrays face limited supplier alternatives.
An autonomous navigation sensing system integrates lidar, radar, camera, and ultrasonic sensors with machine learning algorithms to generate real-time spatial mapping and obstacle avoidance for unmanned platforms operating without human intervention. These systems typically process point-cloud densities exceeding one million points per second while maintaining sub-10-centimeter localization accuracy in GPS-denied environments. Lidar hardware captures the largest value share among product types due to mechanical complexity and precision optics, though solid-state variants are narrowing cost gaps. Sensor fusion technology leads software architecture decisions, as defense end users demand redundancy against single-sensor failure modes in contested electromagnetic environments.
FAA Part 89 remote identification rules and the EU Green Deal's autonomous mobility targets are tightening interoperability standards across transatlantic drone corridors. The US Department of Defense's JADC2 framework further fragments procurement specifications, forcing suppliers to maintain multiple firmware branches. Stakeholders must decide whether to absorb certification costs for dual-use military-civil platforms or specialize in single-domain compliance.
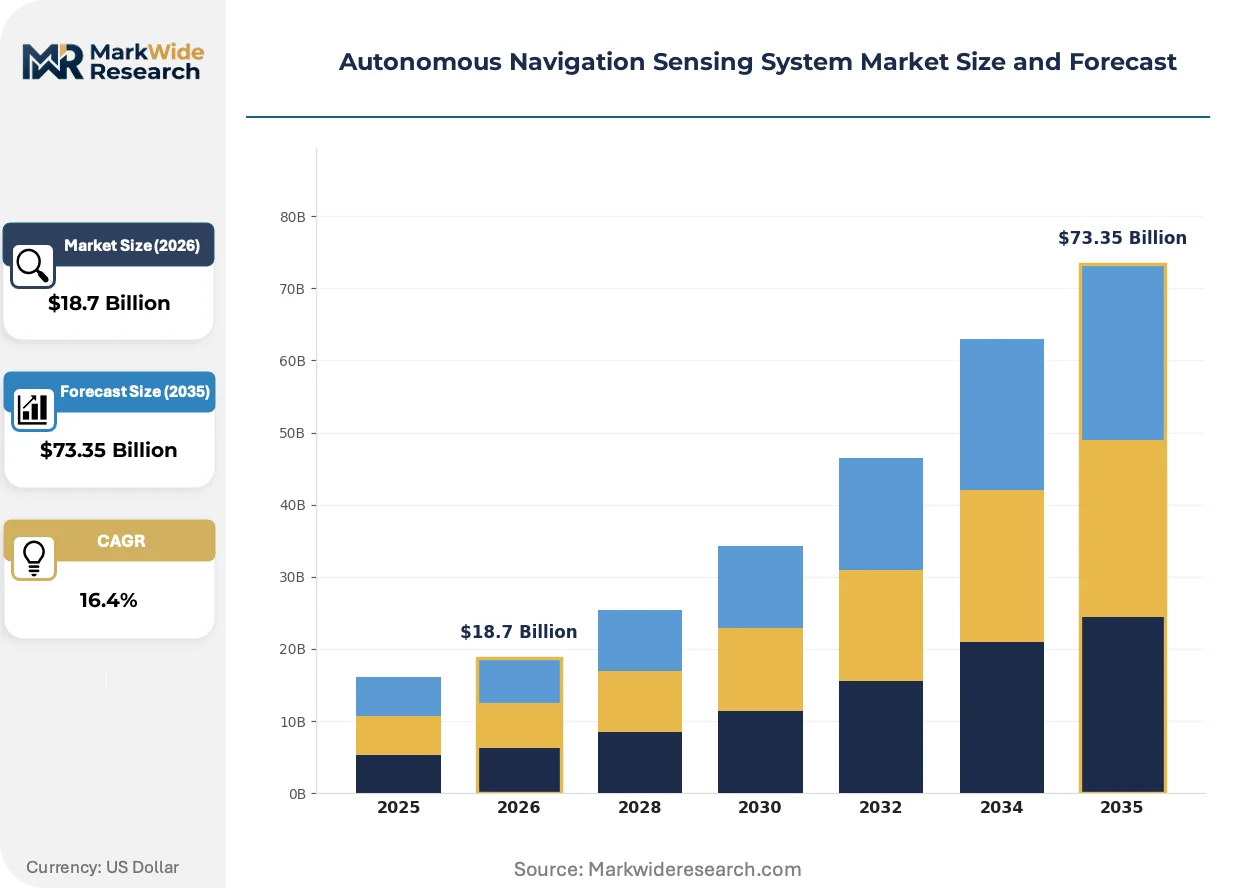
Market Dynamics
Defense procurement fragmentation under the US Department of Defense's JADC2 framework is forcing suppliers to maintain parallel firmware branches, compressing margins and extending development cycles for multi-sensor fusion platforms.
Growth Catalysts
- EU AI Act certification pathways:The regulation's risk-based classification for autonomous decision-making systems is creating predictable compliance roadmaps that reduce regulatory uncertainty for sensor fusion developers.
- Automotive OEM integration:German manufacturers and Tier-1 suppliers are embedding lidar-radar arrays into production vehicle lines, pulling demand from prototype testing into scaled manufacturing.
- GPS-denied navigation:Military end users in contested electromagnetic environments require redundant spatial mapping, accelerating procurement of multi-modal sensor suites.
Market Restraints
- Gallium nitride substrate shortages:Defense-grade radar component production concentrates among limited foundries, exposing lead time volatility for high-frequency arrays.
- Precision optics cost structure:Mechanical lidar assemblies require sub-micron alignment tolerances that resist automation, locking production labor costs at elevated levels.
- Dual-use export controls:ITAR and EU dual-use regulations fragment addressable markets, forcing product variants that dilute engineering resources.
Strategic Opportunities
- India defense modernization:The country's armed forces are soliciting indigenous unmanned platform capabilities, opening procurement channels for sensor integrators meeting BIS and DGFT localization requirements.
- Solid-state lidar convergence:MEMS and OPA architectures are narrowing cost-performance gaps with mechanical systems, enabling penetration of commercial drone and robotics segments.
- FAA-EU interoperability corridors:Remote identification rule harmonization between US and European regulators is standardizing transatlantic certification, reducing duplicate validation costs.
Industry Challenges
- Sensor fusion algorithm talent scarcity:Machine learning engineers with point-cloud processing and real-time SLAM expertise command premium compensation, constraining team scaling.
- Multi-branch firmware maintenance:JADC2 fragmentation forces suppliers to sustain divergent codebases for each defense customer, complicating version control and security patching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Navigation Sensing System Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lidar, Radar, Camera, Ultrasonic Sensors Application: Robotics, Automotive Safety, Drones, Smart Infrastructure Technology: Machine Learning, Computer Vision, Sensor Fusion, Signal Processing End User: Transport Companies, Logistics Providers, Defense, Urban Planners |
| Companies Covered | General Dynamics Corporation, Autonomous Solutions Inc, Safran, Northrop Grumman Corporation, L3Harris Technologies Inc, Honeywell International, Moog Inc, RTX Corporation, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Navigation Sensing System Market Emerging Trajectories
Hardware-software decoupling is reconfiguring competitive boundaries in autonomous navigation, as modular sensor architectures enable faster algorithm iteration independent of physical platform redesign.
Solid-state lidar based on optical phased arrays and MEMS mirrors is consolidating market structure by collapsing the cost differential with mechanical scanning systems. Automotive Tier-1 suppliers are adopting these architectures for highway-autonomy programs, displacing legacy sensor stacks within two development cycles. The technology is consolidating supplier tiers as semiconductor foundries capture value previously held by precision optics houses.
REACH and RoHS substance restrictions in Europe are forcing reformulation of laser diode packages and radar substrate materials. Manufacturers must qualify alternative solders and thermal interface compounds, extending new product introduction timelines by 8-12 months. Defense contractors with established aerospace environmental qualification labs are absorbing these costs faster than commercial entrants.
Defense procurement officers are compressing vendor evaluation cycles, shifting from multi-year pilot programs to accelerated field trials with live mission data. This pattern displaces traditional demonstration-to-production handoffs, favoring suppliers with existing military airworthiness certifications. The shift is most visible in NATO-aligned naval programs, where salt-hardened lidar arrays face limited qualified alternatives.
Autonomous Navigation Sensing System Market Segmentation
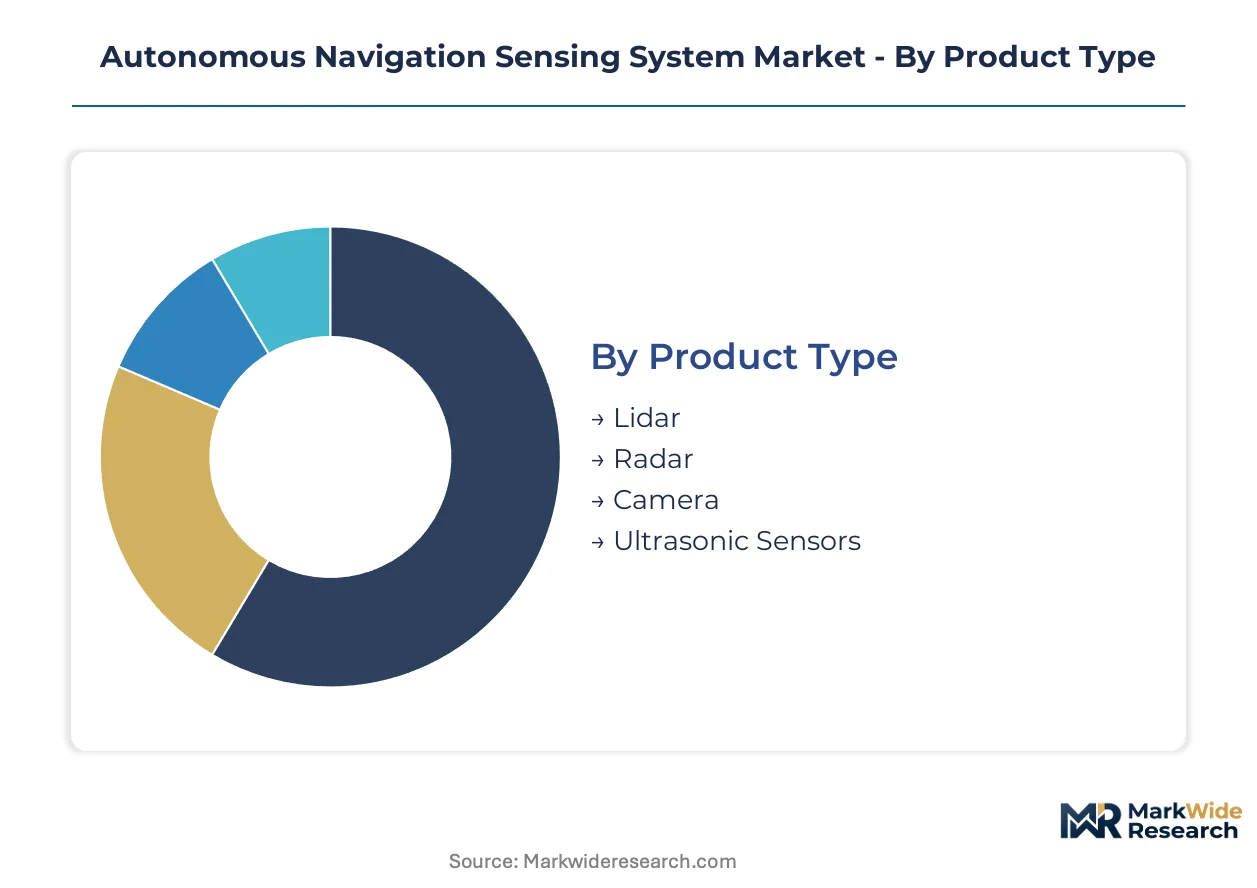
Autonomous navigation sensing systems fragment across hardware modalities, software architectures, and mission profiles. Each segmentation dimension carries distinct margin structures and certification burdens that reshape supplier positioning.
Product Type:
Mechanical lidar assemblies concentrate precision optics supply among Japanese and German component houses, while solid-state alternatives disperse manufacturing across semiconductor foundries.
- Lidar:Mechanical scanning systems generate point-cloud densities exceeding one million points per second through rotating mirror assemblies. German automotive OEMs and Tier-1 suppliers anchor procurement volumes for highway-autonomy programs, though sub-micron alignment tolerances resist automation and lock labor costs at elevated levels.
- Radar:Frequency-modulated continuous-wave arrays operate across 77-81 GHz bands for velocity resolution. Defense procurement from NATO-aligned naval programs dominates demand for salt-hardened gallium nitride variants, where limited qualified foundries expose lead time volatility.
- Camera:Stereo and monocular vision systems capture optical flow for lane-keeping and traffic sign recognition.
- Ultrasonic Sensors:Time-of-flight emitters provide sub-meter ranging for parking assistance and low-speed obstacle detection.
Today's leader: Lidar. Tomorrow's challenger: Radar.
Application:
Automotive safety programs absorb the highest unit volumes, while defense and smart infrastructure concentrate value per platform.
- Automotive Safety:Highway-autonomy and advanced driver-assistance systems integrate multi-sensor suites for lane-centering and emergency braking. German manufacturers pull demand from prototype testing into scaled manufacturing, embedding lidar-radar arrays into production vehicle lines.
- Defense:Unmanned ground vehicles and naval platforms require GPS-denied navigation with redundant spatial mapping. The US Department of Defense's JADC2 framework fragments procurement specifications, forcing suppliers to maintain multiple firmware branches.
- Drones:FAA Part 89 remote identification compliance shapes hardware requirements for commercial unmanned aerial systems.
- Robotics:Warehouse automation and last-mile delivery bots demand compact sensor payloads with sub-10-centimeter localization accuracy.
- Smart Infrastructure:Intersection monitoring and traffic flow optimization deploy edge-mounted sensor networks.
Automotive Safety commands current volume. Defense offers the steepest expansion trajectory.
Technology:
Software architecture decisions increasingly determine hardware procurement, as modular sensor interfaces enable faster algorithm iteration.
- Sensor Fusion:Multi-modal integration algorithms combine lidar point clouds, radar returns, and camera feeds into unified environmental models. Machine learning engineers with real-time SLAM expertise command premium compensation, constraining team scaling for developers.
- Machine Learning:Deep neural networks classify dynamic obstacles and predict trajectory probabilities from raw sensor inputs.
- Computer Vision:Convolutional architectures extract semantic segmentation from camera imagery for lane marking and pedestrian detection.
- Signal Processing:Digital beamforming and clutter suppression algorithms enhance radar detection in contested electromagnetic environments.
Sensor Fusion anchors platform differentiation. Machine Learning drives next-generation capability gaps.
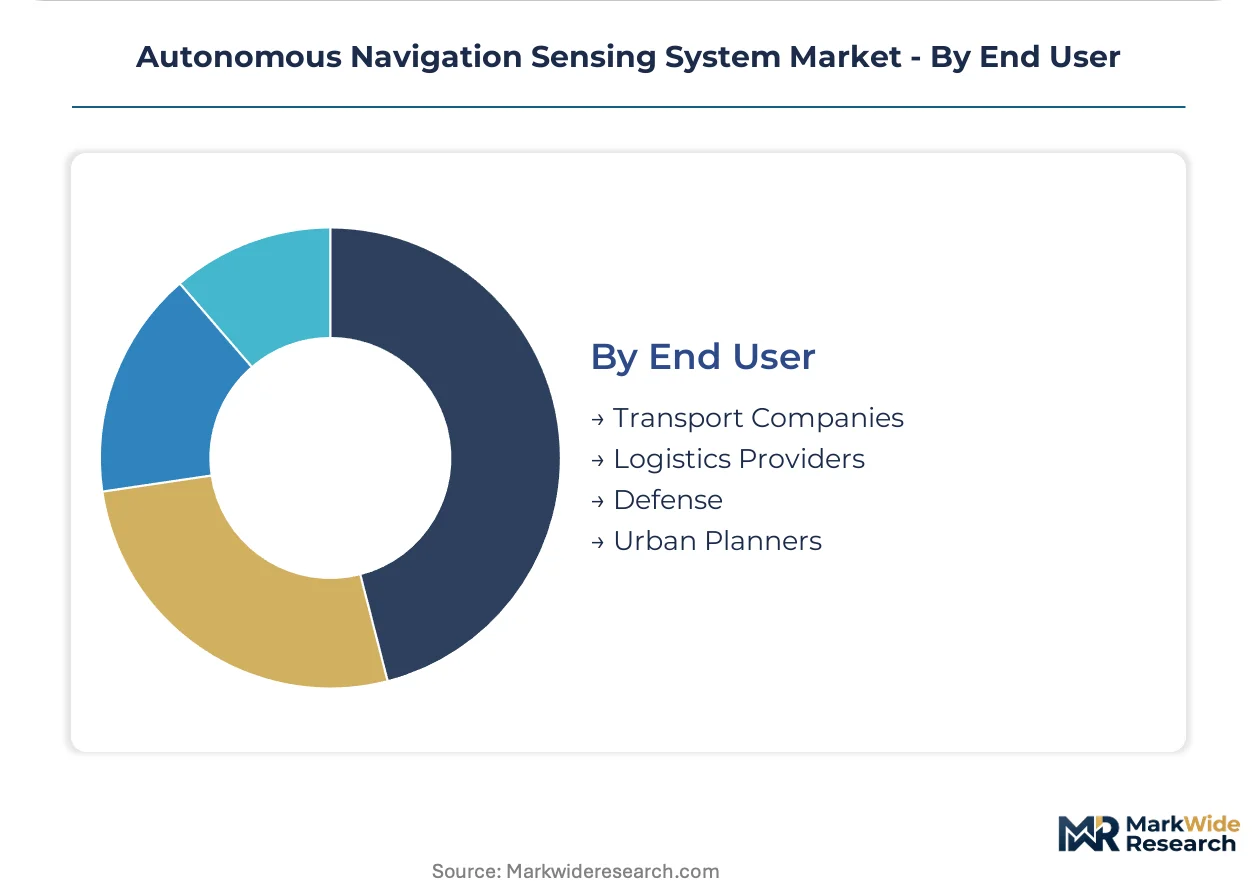
End User:
Defense and logistics providers concentrate procurement authority, while urban planners fragment demand across municipal procurement cycles.
- Defense:Military end users demand redundancy against single-sensor failure modes in GPS-denied and contested electromagnetic environments. Procurement officers compress vendor evaluation cycles from multi-year pilots to accelerated field trials with live mission data.
- Logistics Providers:Warehouse operators and freight carriers automate yard management and highway platooning. The EU AI Act's risk-based classification creates predictable compliance roadmaps that reduce regulatory uncertainty for fleet-wide deployments.
- Transport Companies:Ride-hail and public transit operators pilot autonomous shuttle services in geo-fenced zones.
- Urban Planners:Municipal authorities deploy sensor networks for congestion pricing and pedestrian safety analytics.
Defense sets technical specifications. Logistics Providers scale commercial adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machine learning engineers with point-cloud processing expertise cluster around Stuttgart, Detroit, and Shenzhen, anchoring development capacity for multi-sensor fusion platforms. These talent concentrations shape where automotive OEMs and defense contractors locate autonomous navigation R&D facilities.
United States
The US Department of Defense's JADC2 framework fragments procurement specifications across multiple service branches. FAA Part 89 remote identification rules standardize commercial drone hardware requirements. Salt-hardened lidar development concentrates in New England naval technology corridors where RTX Corporation maintains specialized testing facilities.
Germany
Automotive OEMs and Tier-1 suppliers embed lidar-radar arrays into production vehicle lines, pulling demand from prototype testing into scaled manufacturing. The EU AI Act's risk-based classification creates predictable compliance roadmaps for sensor fusion developers. Stuttgart and Munich anchor development clusters where Bosch and Continental integrate solid-state architectures.
China
Domestic unmanned platform manufacturers source MEMS lidar from local semiconductor foundries at collapsed cost structures. MIIT standards for autonomous vehicle testing mandate sub-10-centimeter localization accuracy in GPS-denied scenarios. Shenzhen and Shanghai house integrated development teams spanning hardware fabrication and SLAM algorithm optimization.
India
The country's armed forces solicit indigenous unmanned platform capabilities through defense procurement channels. BIS certification and DGFT localization requirements filter foreign sensor integrators. Bengaluru and Hyderabad concentrate startup activity around compact radar payloads for tactical drones and ground robots.
Japan
Precise optics houses in Osaka and Nagoya supply sub-micron alignment components for mechanical lidar assemblies. METI funding for autonomous mobility targets highway platooning and last-mile delivery standardization. Toyota and Honda anchor demand through integrated sensor suite programs with domestic Tier-1 suppliers.
Autonomous Navigation Sensing System Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered supplier structure. The market consolidates around three strategic archetypes: aerospace heritage conglomerates with defense airworthiness certifications, automotive Tier-1 suppliers with scaled manufacturing footprints, and semiconductor foundries capturing value from solid-state lidar convergence. Dominant competitive moves include M&A activity targeting sensor fusion software teams and capacity expansion into gallium nitride radar component fabrication.
Among defense-focused conglomerates, Honeywell International and BAE Systems exemplify archetypes leveraging aerospace environmental qualification labs to absorb REACH and RoHS compliance costs faster than commercial entrants. RTX Corporation occupies a specialized position in naval autonomous navigation where salt-hardened lidar arrays face limited qualified alternatives. These three companies represent distinct strategic postures: certification leverage, in-house component production, and mission-specific hardware dominance.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| Autonomous Solutions Inc |
| Safran |
| Northrop Grumman Corporation |
| L3Harris Technologies Inc |
| Honeywell International |
| Moog Inc |
| RTX Corporation |
| BAE Systems |
| Others |
Supply Flow & Price Mechanics
Gallium nitride substrate costs cascade through defense-grade radar production into three-tier pricing structure across premium, standard, and economy levels. Mechanical lidar assemblies lock labor expenses at elevated tiers due to sub-micron alignment tolerances that resist automation, while solid-state variants collapse cost differentials through semiconductor foundry economics.
Pricing Analysis
Bundled sensor fusion platforms with integrated software licensing command premium positioning against unbundled hardware-only transactions. Price differentiation separates ITAR-certified defense variants from commercial drone components, with volume scale and certification tier as primary drivers. Pricing pressure stems from gallium nitride substrate shortages that compress margins for high-frequency radar arrays. Logistics providers exhibit highest price sensitivity due to fleet-wide deployment economics, while defense procurement tolerates cost premiums for redundancy guarantees.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German automotive manufacturers, while defense contractors source through qualified vendor lists with airworthiness certification requirements. Manufacturing concentrates in Germany, Japan, and China for precision optics and semiconductor foundry capacity. The supply chain draws from gallium nitride wafers, MEMS mirror components, and laser diode packages as critical inputs. Single-source vulnerability in salt-hardened lidar qualification for naval programs exposes procurement delays. Distribution runs through Tier-1 supplier networks and direct military contracting offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autonomous navigation sensing system market functions as a stable compounder anchored by defense procurement fragmentation that perpetuates multi-year platform refresh cycles.
For Market Incumbents: Deepen in-house production of gallium nitride radar components to insulate margin control against commercial chip shortages. Expand certification laboratory capacity to absorb REACH and RoHS reformulation costs faster than commercial entrants facing 8-12 month qualification delays. JADC2 firmware fragmentation threatens engineering resource dilution; consolidate codebase architectures where security classification permits. For New Entrants and Emerging Players: Enter via India's indigenous unmanned platform procurement channels where BIS and DGFT localization requirements filter established foreign suppliers. Solid-state lidar architectures offer the most penetrable wedge for commercial drone and robotics segments with collapsed cost structures. Pursue sensor fusion software licensing models that decouple from hardware manufacturing capital intensity. For Investors and Strategic Acquirers: Consolidation pressure builds where sensor fusion algorithm talent scarcity constrains team scaling for point-cloud processing and real-time SLAM expertise. Long-term viability favors semiconductor foundries capturing value from solid-state lidar convergence and defense contractors with established aerospace environmental qualification labs. Watch FAA-EU interoperability corridor progress as inflection indicator for duplicate validation cost reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Software Acquisition | BAE Systems and Honeywell anchor defense contracts through machine learning team consolidation. |
| Gallium Nitride Capacity Expansion | In-house foundry investment insulates RTX Corporation against naval lidar supplier shortages. |
| Solid-State Lidar Platform Launch | MEMS and OPA architectures enable Bosch and Continental to penetrate commercial drone segments. |
| Defense Airworthiness Certification | Established labs accelerate REACH and RoHS compliance faster than commercial entrants. |
| India Localization Partnership | BIS certification pathways open procurement channels for unmanned ground vehicle sensor integrators. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged sensor fusion engineering directors, defense procurement officers at NATO-aligned agencies, Tier-1 supplier platform engineers, and semiconductor foundry operations managers. Secondary validation drew from FAA Part 89 regulatory filings, EU AI Act documentation, US Department of Defense JADC2 framework publications, and customs trade data for gallium nitride substrate flows. Bottom-up sensor unit economics triangulated against top-down defense budget allocation analysis.
Segment-weighting approaches distributed value across hardware modalities, software architectures, and mission profiles throughout the forecast period. Modeled dimensions included product type, application vertical, technology stack, and end-user procurement authority. CAGRs were derived from installed base growth curves and replacement cycle analysis. Industry-specific inputs incorporated defense procurement cycle timing and automotive OEM production ramp schedules.
Inputs from regulatory agency publications and defense budget documentation were available through the study window; gaps in real-time gallium nitride foundry capacity utilization introduce uncertainty bands around hardware cost assumptions. Forecasts reflect documented base conditions including JADC2 fragmentation persistence and EU AI Act compliance pathway stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Intelligent Vehicle Market
Autonomous Vehicles
China Autonomous Navigation Market
Autonomous Vehicles
Autonomous Ride-Sharing Services Market
Autonomous Vehicles
Automotive Lidar Market
Autonomous Vehicles
Automated Truck Technology Market
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Self-Balancing Mobility Market
Autonomous Vehicles
Germany Autonomous Navigation Market
Autonomous Vehicles
Autonomous Driving Component Market
Autonomous Vehicles
North America Autonomous Navigation Market
Autonomous Vehicles
North America Adaptive Steering Market
Autonomous Vehicles
Autonomous Emergency Braking (AEB) Market
Autonomous Vehicles
Autonomous Vehicle Simulation Software Market
Autonomous Vehicles
Semi-Autonomous and Autonomous Bus Market
Autonomous Vehicles
Self Driving Car Market