
 Platinum Automotive Catalyst Market | 2026-2036
Platinum Automotive Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Platinum Automotive Catalyst Market Insights
Euro 7 standards is hardening the cost-of-entry calculus for catalyst manufacturers serving European automotive programs. Johnson Matthey leverages its integrated precious metals refining and catalyst coating operations to sustain margin resilience under tighter platinum loading specifications. BASF SE anchors its competitive stance through dedicated R&D centers in Ludwigshafen that specialize in low-temperature catalyst activation. Umicore competes by controlling closed-loop recycling of platinum group metals from spent automotive catalysts.
Platinum automotive catalysts are heterogeneous catalytic systems typically composed of platinum, palladium, and rhodium deposited on ceramic honeycomb substrates with cell densities of 400-600 cells per square inch, designed to convert harmful exhaust pollutants into nitrogen, carbon dioxide, and water through redox reactions at operating temperatures between 200°C and 600°C. Three-way catalysts dominate value capture in passenger vehicle gasoline applications where stoichiometric air-fuel ratios enable simultaneous NOx, CO, and hydrocarbon reduction. Diesel oxidation catalysts represent the fastest-growing product category as commercial vehicle fleets in Europe and Asia retrofit older powertrains to meet evolving particulate matter limits. Heterogeneous catalysis leads technology deployment due to its proven durability and cost efficiency across high-volume automotive manufacturing lines.
The European Commission, ECHA under REACH, and national type-approval authorities in Germany and France collectively shape platinum catalyst demand through emission limit enforcement and material substance restrictions. EPA regulations in the United States and China's MEE standards exert parallel pressure on multinational suppliers to harmonize product platforms across regulatory jurisdictions. Stakeholders must monitor the pace of Euro 7 implementation and platinum-palladium substitution economics to calibrate capacity commitments and recycling infrastructure investments.
Market Dynamics
Euro 7 emission standards are compressing catalyst design cycles and forcing platinum loading optimization across European powertrain programs. OEMs now demand sub-10 milligram per kilometer NOx performance from gasoline three-way catalysts and diesel oxidation systems, rewriting supplier qualification protocols.
Growth Catalysts
- REACH substance restrictions:ECHA screening of candidate list chemicals is accelerating platinum-palladium substitution in catalyst formulations, expanding addressable demand for high-purity platinum coatings.
- Commercial vehicle retrofit mandates:Fleet operators in Germany and Poland face compulsory particulate matter compliance deadlines, driving diesel oxidation catalyst replacements across aging truck and bus powertrains.
- Closed-loop recycling infrastructure:Spent catalyst collection networks in Belgium and the United Kingdom are recovering platinum group metals at refining yields above 95 percent, securing secondary supply channels.
Market Restraints
- Platinum price volatility:London Bullion Market Association pricing swings above 15 percent annually compress catalyst manufacturer margins and complicate long-term OEM contract negotiations.
- Rare earth supply concentration:Cerium and lanthanum oxide requirements for oxygen storage components concentrate mining and processing in China, creating single-source vulnerability for European catalyst producers.
- Battery electric vehicle substitution:Zero-emission powertrain adoption in Norway and the Netherlands eliminates exhaust aftertreatment entirely from new vehicle registrations in premium segments.
Strategic Opportunities
- Hydrogen internal combustion engines:BMW and Toyota development programs for hydrogen-fueled spark ignition engines require novel platinum-ruthenium catalyst formulations to manage NOx from high-temperature combustion.
- Poland and Romania fleet modernization:EU Just Transition Fund disbursements are financing heavy-duty diesel retrofit programs in coal-dependent regions, opening catalyst demand outside Western European saturation.
- CSRD supply chain disclosure:Corporate Sustainability Reporting Directive mandates are forcing OEMs to document platinum provenance, rewarding catalyst suppliers with certified responsible mining partnerships.
Industry Challenges
- Catalyst engineering talent scarcity:European universities produce fewer than 200 specialized heterogeneous catalysis graduates annually, constraining R&D expansion at established coating facilities.
- Euro 7 type-approval timeline compression:KBA and UTAC certification cycles now demand 18-month validation protocols for new catalyst substrates, delaying program launches.
- Legacy coating line reconfiguration:Existing washcoat application equipment designed for 400 cells per square inch substrates requires capital-intensive retooling to handle 600-900 cell density honeycombs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platinum Automotive Catalyst Market |
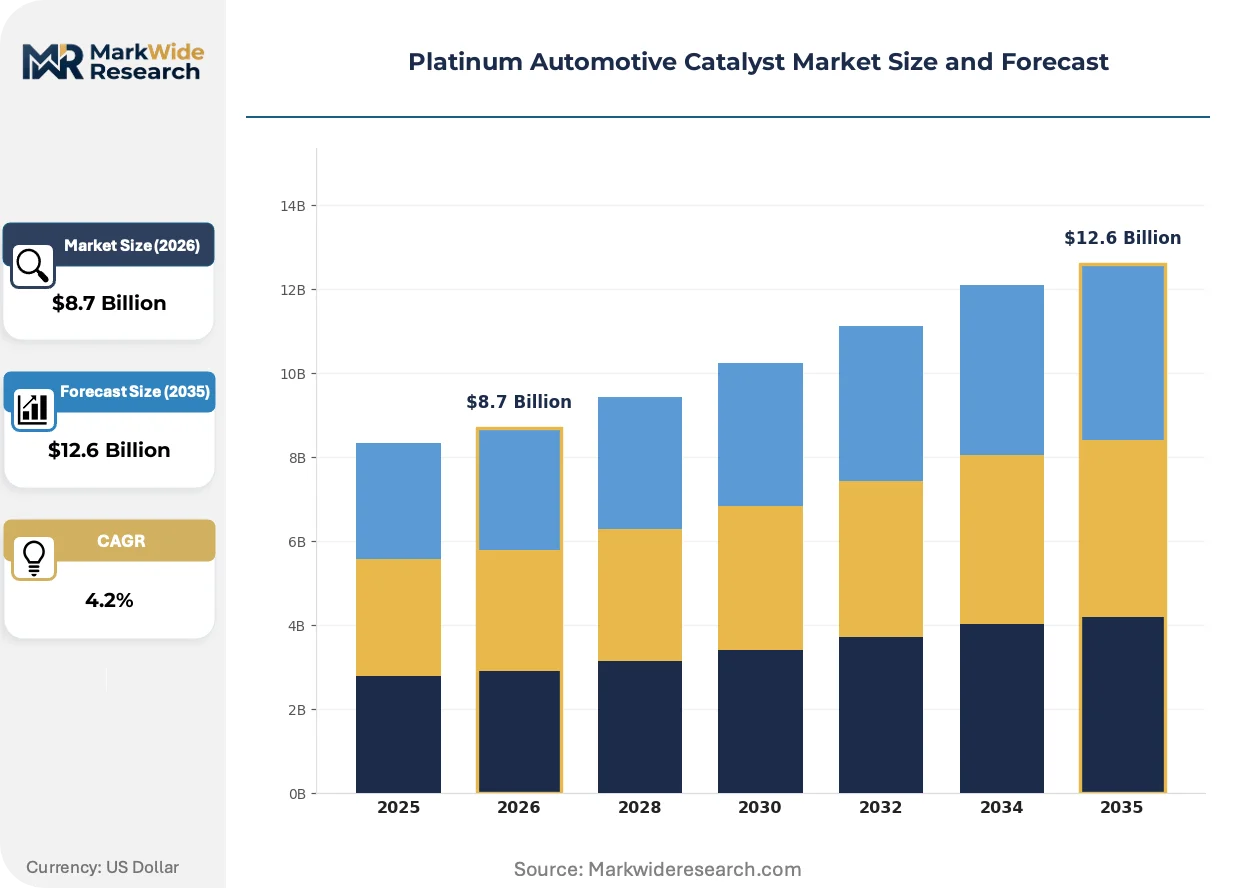
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Three-way Catalysts, Diesel Oxidation Catalysts, Selective Catalytic Reduction Systems, Lean NOx Traps End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: Gas-phase Catalysis, Homogeneous Catalysis, Heterogeneous Catalysis, Photocatalysis Application: Passenger Vehicles, Commercial Vehicles, Heavy-duty Trucks, Motorbikes |
| Companies Covered | Johnson Matthey, BASF SE, Umicore, Heraeus Holding, Tenneco, Clariant AG, Denso Corporation, Cataler, Sinopec Catalyst Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platinum Automotive Catalyst Market Trends and Innovations
Platinum automotive catalyst technology is bifurcating between incremental loading efficiency gains for conventional powertrains and radical formulation redesign for alternative fuels. Three interconnected developments are restructuring competitive advantage in coating and substrate supply.
Perovskite-oxide promoted platinum catalysts are electrifying low-temperature activity performance in gasoline three-way systems. BMW and Volkswagen powertrain divisions are qualifying these formulations for 2027 model year engines to meet cold-start emission windows under 90 seconds. The technology is electrifying supplier selection criteria by privileging coating houses with atomic layer deposition capabilities over conventional wet chemistry operations.
REACH authorization requirements for hexavalent chromium in stainless steel catalyst housings are forcing substrate manufacturers toward ferritic stainless alternatives. ECHA sunset date enforcement in 2026 is compressing qualification timelines for Swedish and Finnish steel suppliers serving catalyst canister producers. Diesel oxidation catalyst programs for commercial vehicles face the tightest substitution deadlines, with Scania and DAF accelerating ferritic grade validation.
Fleet procurement departments are consolidating catalyst sourcing through powertrain-as-a-service contracts rather than discrete component purchasing. Volvo Group and Daimler Truck are unbundling aftertreatment responsibility from vehicle ownership, transferring catalyst lifecycle management to leasing subsidiaries. This restructuring is most visible in German long-haul logistics corridors where total cost-per-kilometer contracts now dominate new fleet acquisitions.
Platinum Automotive Catalyst Market Segmentation
Platinum automotive catalyst procurement varies sharply across certification regimes. KBA type-approval in Germany, UTAC protocols in France, and EPA certification in the United States impose distinct loading specifications and durability testing cycles that reshape supplier economics by segment.
Product Type:
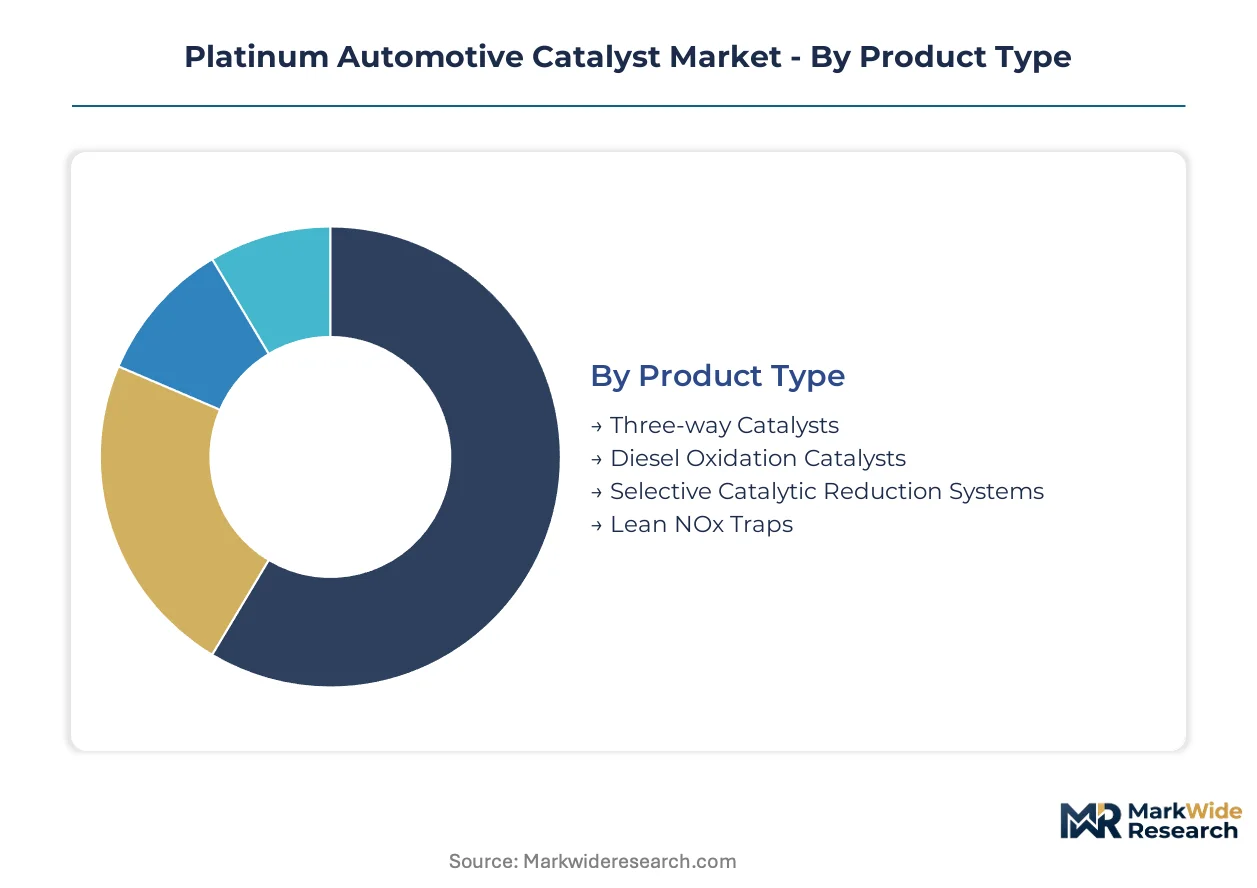
Certification burden falls heaviest on three-way catalysts and diesel oxidation systems facing Euro 7 NOx windows, while lean NOx traps navigate separate ammonia slip compliance thresholds.
- Three-way Catalysts:Simultaneous reduction of nitrogen oxides, carbon monoxide, and unburned hydrocarbons through platinum-palladium-rhodium coatings on ceramic substrates. Passenger vehicle gasoline programs in Germany and France concentrate procurement as OEMs chase sub-10 milligram per kilometer NOx performance under KBA and UTAC validation protocols.
- Diesel Oxidation Catalysts:Platinum-only or platinum-palladium formulations oxidizing particulate matter and hydrocarbons in diesel exhaust streams. Commercial vehicle retrofit mandates in Poland and Romania are accelerating demand as fleet operators face compulsory particulate matter compliance deadlines tied to EU Just Transition Fund disbursements.
- Selective Catalytic Reduction Systems:Platinum-free vanadium or zeolite-based alternatives dominating heavy-duty NOx reduction.
- Lean NOx Traps:Periodic regeneration systems capturing nitrogen oxides under lean-burn conditions.
Three-way catalysts sit at the top of the volume ranking, with diesel oxidation catalysts climbing the fastest.
End User:
Cost tier separation distinguishes captive production from merchant supply, with OEMs absorbing precious metal price volatility directly while aftermarket providers hedge through indexed contracts.
- OEMs:Volkswagen Group and Stellantis operate captive catalyst coating facilities in Germany and Italy, securing direct control over platinum group metal procurement and washcoat formulation IP.
- Aftermarket Providers:Independent distributors serving aging vehicle parc in Eastern Europe where Euro 4 and Euro 5 retrofit demand persists beyond original equipment lifecycles.
- Vehicle Assemblers:Contract manufacturers without in-house powertrain development relying on Tier-1 supply agreements for complete aftertreatment modules.
- Tier-1 Suppliers:Faurecia and Tenneco managing catalyst integration within broader exhaust system architectures.
OEMs capture the largest share of platinum loading volume, though aftermarket providers are expanding most quickly in Poland and Romania.
Technology:
Application maturity separates proven heterogeneous systems from emerging alternatives, with gas-phase and homogeneous approaches confined to laboratory validation or narrow specialty niches.
- Heterogeneous Catalysis:Solid platinum deposited on high-surface-area alumina or ceria-zirconia supports, dominating automotive volume through proven durability across 160,000-kilometer useful life requirements. BMW and Volkswagen powertrain divisions are qualifying perovskite-oxide promoted variants for cold-start emission windows.
- Gas-phase Catalysis:Homogeneous platinum complexes in vapor-phase reactions, limited to research-stage exhaust treatment concepts.
- Homogeneous Catalysis:Platinum dissolved in liquid reaction media, absent from automotive exhaust applications due to thermal instability.
- Photocatalysis:Titanium dioxide-based systems activated by ultraviolet light, experimental for auxiliary cabin air purification rather than powertrain emissions.
Heterogeneous catalysis commands the dominant technology position, with photocatalysis posting the steepest expansion trajectory from negligible base in cabin air applications.
Application:
Customer type differentiation splits procurement between high-unit passenger programs and low-volume, high-loading commercial segments where platinum intensity per vehicle multiplies.
- Passenger Vehicles:Three-way catalysts in gasoline powertrains carrying 2-5 grams platinum group metals per vehicle. Norwegian and Dutch zero-emission mandates are eliminating this category entirely from new registrations in premium battery electric segments.
- Commercial Vehicles:Diesel oxidation catalysts and selective catalytic reduction systems in light commercial fleets facing urban low-emission zone restrictions across German and French city centers.
- Heavy-duty Trucks:High-platinum-loading systems for long-haul corridors where Scania and DAF are accelerating ferritic stainless steel canister validation ahead of ECHA hexavalent chromium sunset dates.
- Motorbikes:Compact catalysts with reduced cell densities, concentrated in Italian and Indian two-wheeler production.
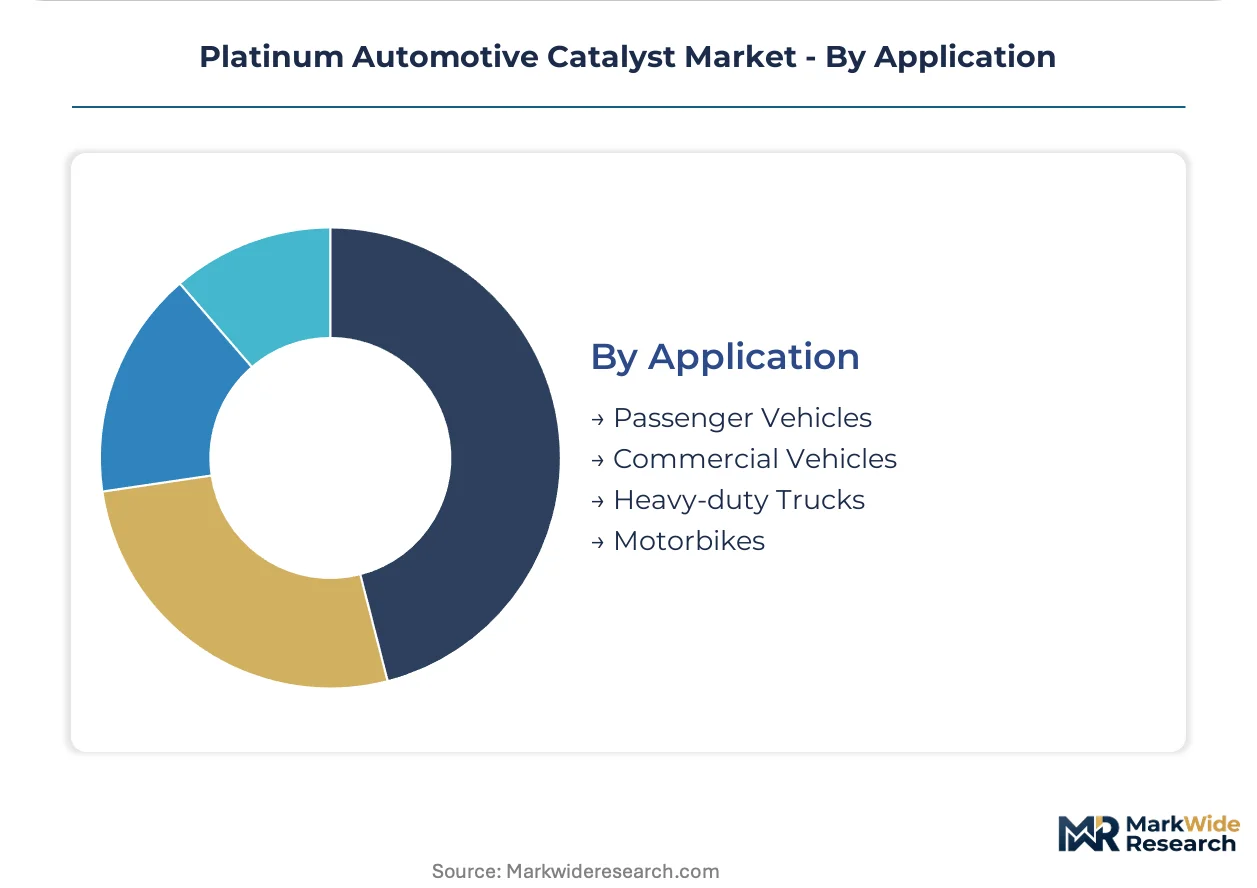
Passenger vehicles retain the highest unit volume, with heavy-duty trucks gaining share fastest on per-vehicle platinum intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European heterogeneous catalysis engineers and precious metals chemists cluster around the Rhine-Ruhr corridor and Belgian refining centers, anchoring the continent's catalyst design and platinum group metal processing capabilities.
Germany
KBA type-approval protocols for Euro 7 compliance are compressing validation cycles for three-way catalysts serving Volkswagen Group and BMW powertrain divisions. The country's Federal Motor Transport Authority mandates 160,000-kilometer durability testing that rewrites supplier qualification standards. Ludwigshafen and Hanau host BASF SE and Heraeus coating operations where low-temperature activation R&D concentrates.
China
MEE emission standards for heavy-duty diesel fleets are accelerating platinum-palladium substitution in oxidation catalyst formulations. The Ministry of Ecology and Environment enforces Stage VI-b particulate number limits that mirror Euro 7 stringency. Sinopec Catalyst Co. anchors production in the Yangtze River Delta, supplying domestic OEMs and export programs to Southeast Asian markets.
United States
EPA Tier 3 standards and California Air Resources Board LEV III regulations sustain platinum loading demand for light-duty gasoline and diesel applications. The Environmental Protection Agency's 150,000-mile useful life requirements exceed European durability benchmarks. Detroit's powertrain engineering corridor and Tennessee Valley catalyst coating facilities serve Ford, General Motors, and Stellantis North American programs.
Japan
METI carbon neutrality roadmaps are funding hydrogen internal combustion engine development that requires novel platinum-ruthenium catalyst formulations. The Ministry of Economy, Trade and Industry channels subsidies toward Toyota and Mazda hydrogen spark-ignition programs. Nagoya's automotive supplier belt and Yokkaichi precious metals refining centers concentrate catalyst substrate and coating expertise.
Belgium
Closed-loop platinum group metal recycling infrastructure recovers secondary supply from spent automotive catalysts at yields above 95 percent. ECHA REACH enforcement coordinates with national environmental authorities on substance restriction timelines. Hoboken's Umicore refining complex processes spent catalysts from across Western Europe, securing circular supply chains for OEM coating operations.
Platinum Automotive Catalyst Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across coating, substrate, and refining segments. The market structure consolidates around integrated precious metals processors and independent exhaust system integrators. Three archetypes dominate: backward-integrated chemical conglomerates controlling raw material supply, captive OEM coating operations protecting formulation IP, and merchant substrate specialists serving aftermarket retrofit demand. Capacity expansion and strategic partnerships represent the dominant competitive moves as Euro 7 timelines compress.
Among integrated chemical conglomerates, Johnson Matthey and BASF SE exemplify archetypes combining precious metals refining with catalyst coating capabilities. Umicore anchors the closed-loop recycling specialist tier, representing circular supply chain integration. These three occupy positions spanning the value chain from metal recovery through washcoat formulation, illustrating how European regulatory pressure rewards players with upstream control over platinum group metal flows.
| Leading Market Players |
|---|
| Johnson Matthey |
| BASF SE |
| Umicore |
| Heraeus Holding |
| Tenneco |
| Clariant AG |
| Denso Corporation |
| Cataler |
| Sinopec Catalyst Co. |
| Others |
Pricing and Supply Chain Analysis
European heterogeneous catalysis engineers concentrated in the Rhine-Ruhr corridor and Belgian refining centers command wage premiums that widen spreads between premium OEM contract tiers and economy aftermarket channels. Labor-cost differentials between Western European coating facilities and emerging Eastern European collection points reshape where platinum group metal recovery economics break even.
Pricing Analysis
Bundled powertrain-as-a-service contracts are displacing discrete component purchasing across German long-haul logistics corridors, compressing spot-market pricing visibility for standalone catalyst transactions. Three-tier pricing structure across premium OEM captive supply, standard Tier-1 merchant agreements, and economy aftermarket retrofit segments reflects certification-grade differentiation and volume-scale leverage. Pricing pressure stems from platinum London Bullion Market Association volatility above fifteen percent annually, which squeezes coating house margins on fixed-price OEM contracts. Aftermarket providers serving Poland and Romania exhibit highest price sensitivity due to fleet operator budget constraints under EU Just Transition Fund disbursement timelines, while BMW and Volkswagen powertrain divisions absorb precious metal swings through captive refining operations.
Supply Chain Analysis
Regional distribution centers in Belgium and the United Kingdom anchor hub-and-spoke patterns for spent catalyst collection, feeding Hoboken refining complexes at yields above ninety-five percent. Raw material flows concentrate in South Africa and Russia for primary platinum mining, with secondary supply from German and Belgian recycling infrastructure. Cerium and lanthanum oxide for oxygen storage components draws from Chinese processing concentration, creating single-source vulnerability for European washcoat producers. Distribution runs through OEM captive coating facilities in Ludwigshafen and Hanau for premium tier supply, while merchant substrate specialists serve fragmented aftermarket channels across Eastern Europe. Tariff exposure on Chinese rare earth imports represents the dominant structural risk to cost stability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Platinum Automotive Catalyst Market functions as a geographic-arbitrage play where Euro 7 compliance costs in Germany and France exceed Eastern European retrofit program economics by a factor that rewards dual-footprint suppliers. This cost differential between Western certification burden and Eastern fleet modernization creates repositioning opportunities across the value chain.
For Market Incumbents: Cement backward integration into spent catalyst recycling infrastructure to offset primary platinum price volatility threatening coating house margins. Lock in long-term offtake agreements with South African mining houses before REACH authorization timelines accelerate palladium substitution demand. Prioritize atomic layer deposition capability investments to capture BMW and Volkswagen perovskite-oxide qualification programs for cold-start emission windows. For New Entrants and Emerging Players: Digital catalyst lifecycle management platforms offer the lowest-friction entry vector for fleet operators seeking powertrain-as-a-service unbundling. Target Polish and Romanian heavy-duty retrofit segments where EU Just Transition Fund disbursements concentrate demand outside saturated Western European OEM supply relationships. Lead with certified responsible mining provenance documentation to satisfy CSRD supply chain disclosure mandates forcing OEM procurement transparency. For Investors and Strategic Acquirers: Chemical conglomerates with precious metals refining assets are the most active acquirers in this space, seeking coating technology to complete vertical integration. Five-to-ten year viability hinges on hydrogen internal combustion engine catalyst formulation IP as battery electric vehicle substitution eliminates exhaust aftertreatment in premium passenger segments. Watch METI funding trajectories for Toyota and Mazda hydrogen spark-ignition programs as the inflection signal for platinum-ruthenium demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Infrastructure Expansion | Umicore and Belgian competitors secure circular supply chains against primary mining volatility. |
| Perovskite-Oxide Coating Qualification | BMW and Volkswagen cold-start programs privilege atomic layer deposition capabilities over wet chemistry. |
| Powertrain-as-a-Service Contracting | Volvo Group and Daimler Truck unbundle aftertreatment responsibility from vehicle ownership. |
| Hydrogen ICE Catalyst Formulation R&D | Toyota and Mazda METI-funded programs require novel platinum-ruthenium compositions. |
| Ferritic Stainless Canister Validation | Scania and DAF accelerate substitution ahead of ECHA hexavalent chromium sunset dates. |
Research Methodology
Bottom-up passenger vehicle and commercial vehicle production modeling reconciled against top-down platinum group metal supply tracking forms the analytical core of this study. Primary interviews with coating facility technical directors, OEM platform engineers, Tier-1 supplier procurement leads, and aftermarket distribution channel heads combined with secondary validation from KBA type-approval databases, ECHA REACH substance restriction filings, and vehicle registration data. Trade flow analysis of platinum concentrates and refined metal movements through London Bullion Market Association clearing supplemented customs records for ceramic substrate imports.
Input-output matrices map platinum loading specifications by powertrain architecture against regional emission regulatory stringency tiers across the analysis window. Segmentation dimensions include catalyst product type, end-user category, technology maturity tier, and vehicle application class. CAGRs derive from regression of historical platinum demand intensity per vehicle against projected production volumes under stated Euro 7 and EPA Tier 3 implementation assumptions. Forecast inputs incorporate platinum-palladium substitution elasticity and hydrogen internal combustion engine commercialization trajectories.
The model assumes a particular technology adoption path; alternative pathways for battery electric vehicle penetration or hydrogen fuel cell acceleration would alter the outlook materially. Forecasts reflect documented assumptions regarding regulatory timeline adherence and rare earth supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
UAE Automotive Composites Market
Automotive Components
Global Automotive Thermal Management Market
Automotive Components
Automotive Plastic Components Market
Automotive Components
Automotive Braking Component Market
Automotive Components
US Automotive Glass Fiber Composites Market
Automotive Components
Automotive Pressure Plate Market
Automotive Components
Global Automotive Components Forging Market
Automotive Components
Japan Automotive Composites Market
Automotive Components
Automotive Active Grille Shutter Actuator Gear Market
Automotive Components
Automotive Spray Guns Market
Automotive Components
Automotive Radiator Fan Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Africa Automotive Lubricants Market
Automotive Components
Automotive Ignition Box Market
Automotive Components
North America Automotive Glass Market
Automotive Components
Automotive Seat Frame Market